
 United States Sales Tax Compliance Software Market | 2026-2036
United States Sales Tax Compliance Software Market Size, Share, and Industry Trends Forecast 2026-2036
United States Sales Tax Compliance Software Market Analytics
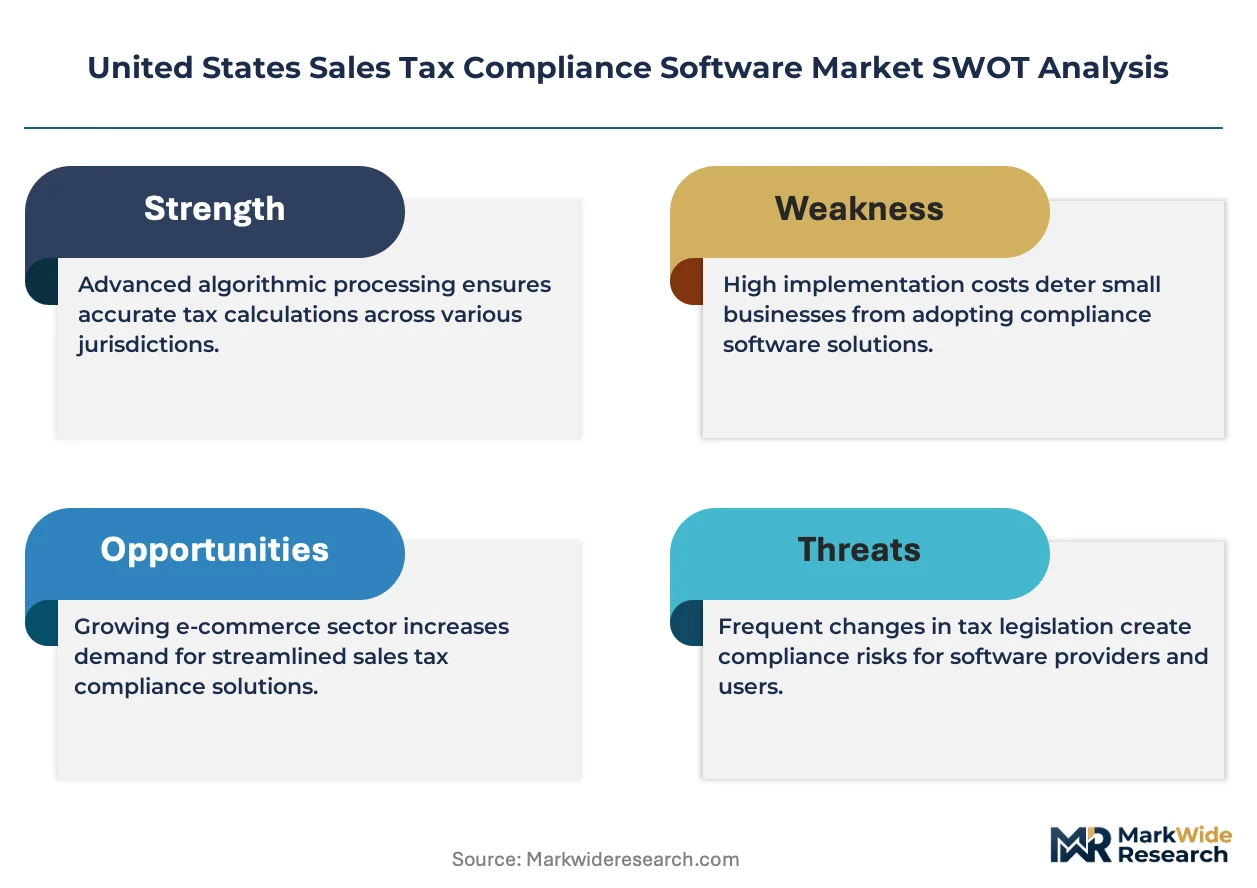
The Economic Nexus thresholds post-Wayfair is rebalancing compliance burdens for remote sellers across state lines. Avalara leverages cloud-native architecture to sustain multi-jurisdictional filing automation. Vertex anchors enterprise-grade tax determination engines for complex procurement networks. Sovos differentiates through embedded regulatory content updates that reduce audit exposure.
United States sales tax compliance software encompasses automated calculation engines, exemption certificate managers, and return preparation systems that synchronize transaction data with jurisdictional rate tables. These platforms integrate via APIs with ERP and e-commerce backends to enforce real-time tax decisions at point of sale. Cloud-based deployment leads segment adoption as mid-market firms abandon on-premises maintenance overhead. SaaS platforms capture expanding margin pools through usage-tiered subscription structures. API integrations represent the fastest-growing integration level as composable finance stacks displace monolithic ERP dependencies.
The IRS, state revenue departments, and the Streamlined Sales Tax Governing Board collectively shape product roadmap priorities through filing format changes and audit documentation standards. FERC and SEC disclosure requirements for public companies further tighten traceability demands on tax provision workflows. Stakeholders must monitor pending federal digital goods taxation proposals and state-level marketplace facilitator law expansions to anticipate compliance scope shifts.
Market Dynamics
The South Dakota v. Wayfair economic nexus framework continues forcing remote sellers into multi-jurisdictional compliance regimes, driving automation demand across state revenue department filing requirements.
Growth Catalysts
- Economic Nexus Thresholds:State-level revenue departments enforce transaction and revenue-based nexus rules that mandate automated rate determination for out-of-state vendors. California, Texas, and New York metropolitan corridors concentrate compliance software procurement.
- API-First Architecture:Cloud-native calculation engines integrate directly with ERP and e-commerce backends, enabling real-time tax decisions at point of sale without batch processing delays.
- Mid-Market Retail Expansion:Regional retailers scaling across state lines abandon manual spreadsheet-based compliance for subscription-based automation platforms.
Market Restraints
- Rate Table Volatility:Over 11,000 US sales tax jurisdictions update boundaries and rates unpredictably, forcing continuous data maintenance costs on platform providers.
- Exemption Certificate Complexity:Resale and manufacturing exemption documentation varies by state revenue department format, creating manual validation bottlenecks.
- Legacy ERP Lock-In:On-premises enterprise resource planning systems in industrial distribution lack modern API connectivity, delaying cloud migration timelines.
Strategic Opportunities
- Marketplace Facilitator Laws:State legislation shifting collection obligation to platforms like Amazon and eBay creates white-label compliance service demand.
- Vertical Tax Engines:Specialized modules for telecommunications, hospitality, and digital goods address sector-specific sourcing rules underserved by generic platforms.
- Audit Defense Automation:Embedded documentation workflows that satisfy IRS and state revenue department record retention standards reduce penalty exposure.
Industry Challenges
- Sales Tax Engineering Talent:Professionals combining jurisdictional rate knowledge with software architecture skills command premium compensation, constraining vendor scaling.
- Multi-State Filing Orchestration:Synchronizing return preparation across divergent state revenue department deadlines and payment portals requires complex workflow engineering.
- Exemption Certificate Lifecycle Management:Validating, storing, and renewing customer exemption documentation at scale demands specialized database infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Sales Tax Compliance Software Market |
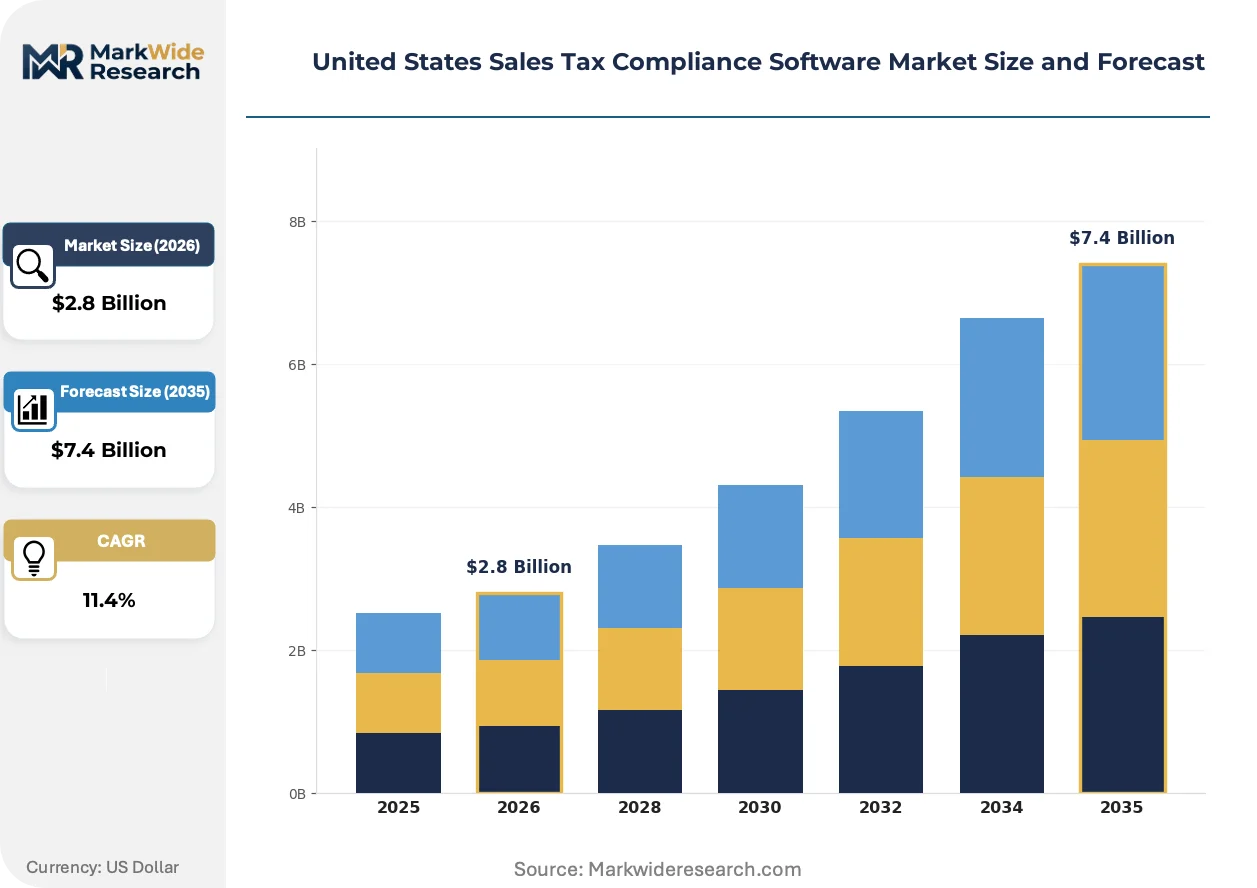
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
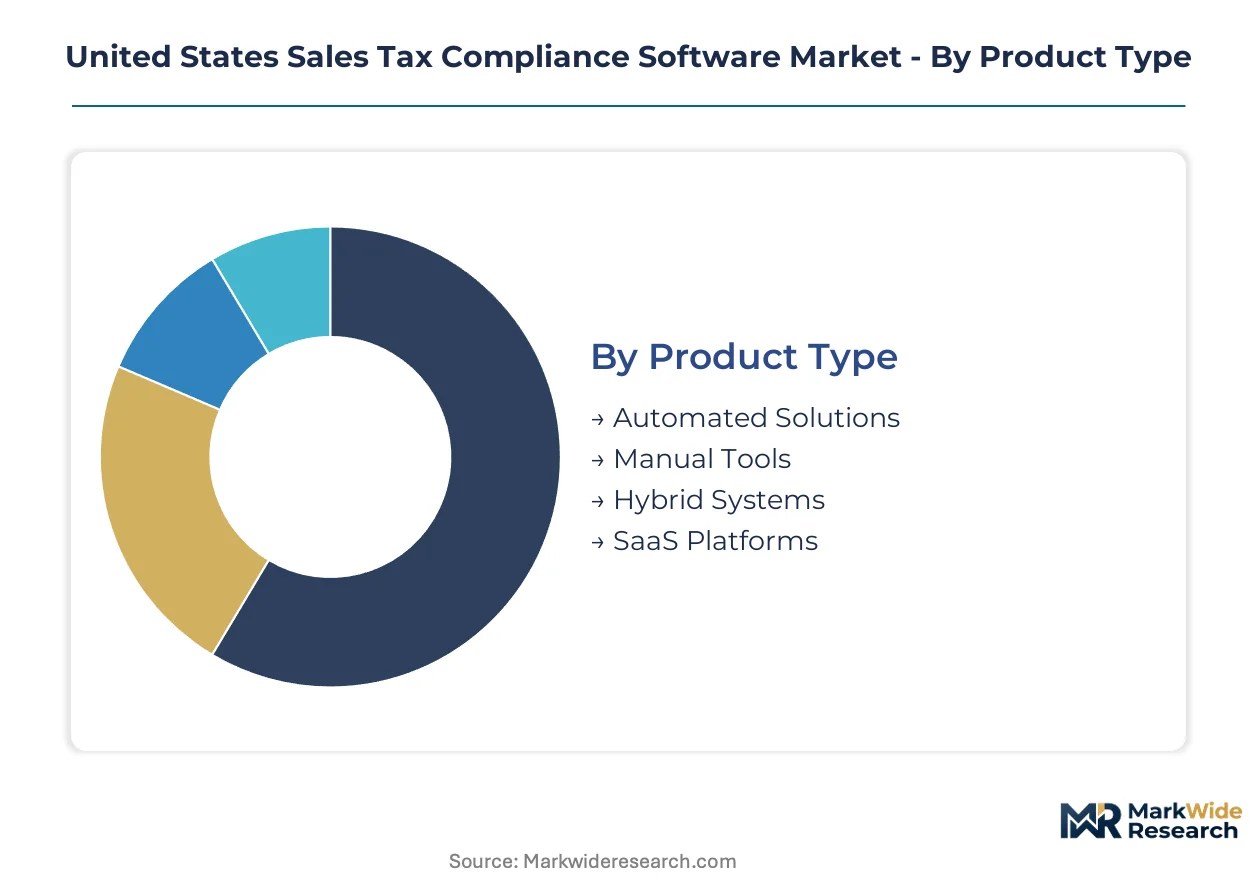
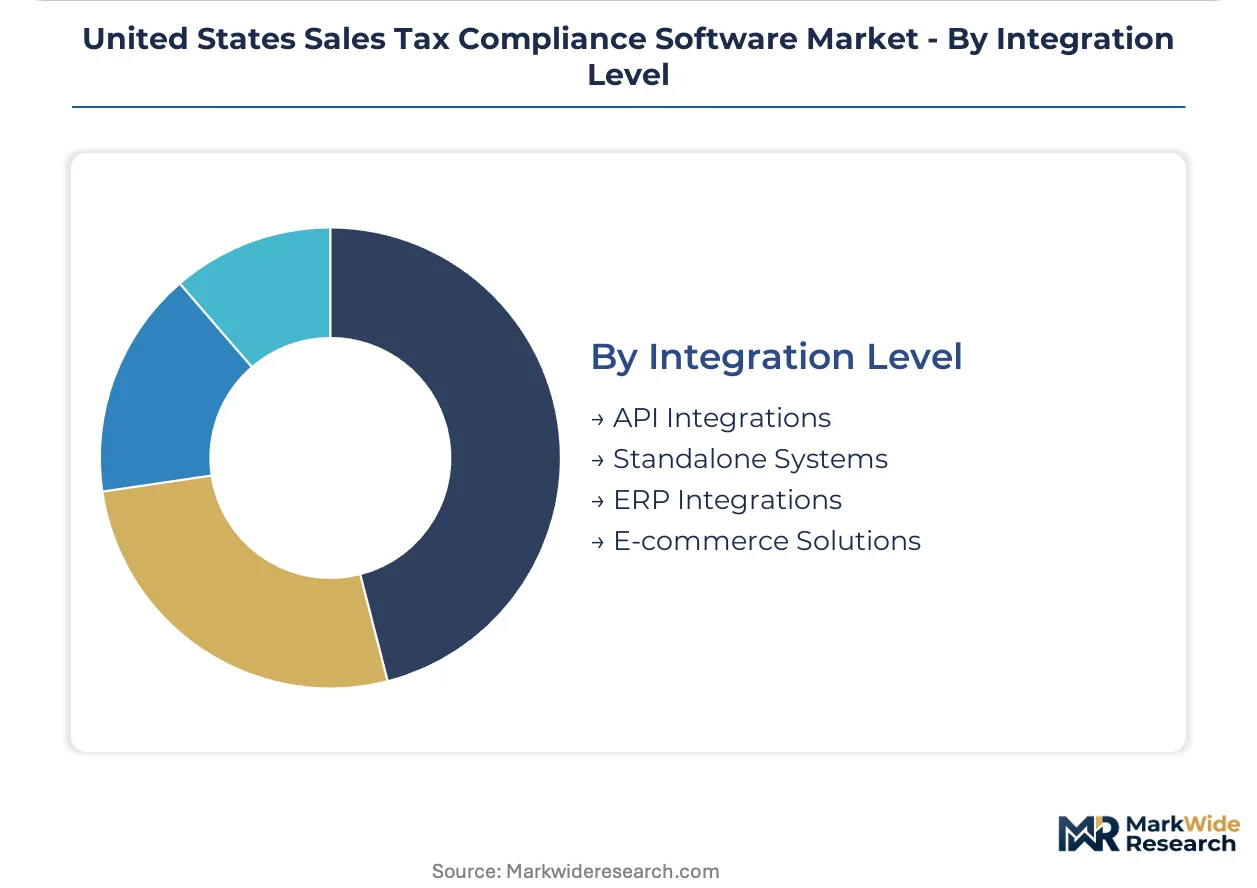
| Segmentation | Product Type: Automated Solutions, Manual Tools, Hybrid Systems, SaaS Platforms Deployment: On-premises, Cloud-based, Hybrid Deployment, Managed Services End User: Small Businesses, Medium Enterprises, Large Corporations, Accounting Firms Integration Level: API Integrations, Standalone Systems, ERP Integrations, E-commerce Solutions |
| Companies Covered | Avalara, Vertex, TaxJar, Sphere, TaxCloud, Anrok, Galvix, Sovos, Paddle, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Sales Tax Compliance Software Market Evolving Landscape
Composable finance architectures are fragmenting monolithic enterprise software stacks, enabling point-solution tax engines to displace bundled ERP modules through superior jurisdictional precision.
Microservices-based tax calculation engines is modularizing compliance infrastructure into discrete API endpoints. Mid-market retailers adopt these components incrementally rather than replacing entire ERP systems. This architecture compresses implementation timelines from quarters to weeks while preserving existing accounting workflows.
The Streamlined Sales Tax Governing Board's centralized registration and filing protocols reduce multi-state administrative burden for remote sellers. Twenty-four member states now accept uniform returns and tax base definitions. Sellers in these jurisdictions report reduced audit frequency compared to non-member states with idiosyncratic requirements.
Subscription billing platforms now embed native tax determination rather than routing to external services. SaaS vendors including subscription management and recurring revenue platforms integrate calculation engines directly. This pattern concentrates most visibly in California and New York metro software corridors where recurring revenue models dominate B2B pricing.
United States Sales Tax Compliance Software Market Segmentation
Tax compliance software procurement concentrates where nexus obligations intersect with transaction complexity. California, Texas, and New York metropolitan corridors drive disproportionate platform adoption as remote sellers navigate multi-jurisdictional filing requirements.
Product Type:
Supply concentration favors vendors with continuous rate table maintenance infrastructure across over 11,000 US jurisdictions.
- Automated Solutions:Real-time calculation engines synchronize transaction data with jurisdictional rate tables through API connections to ERP and e-commerce backends. Mid-market retailers in Texas and California metropolitan areas deploy these systems to replace spreadsheet-based compliance as economic nexus thresholds trigger filing obligations.
- SaaS Platforms:Cloud-native architectures deliver subscription-based access to tax determination engines without on-premises maintenance overhead. Usage-tiered pricing structures capture expanding margin pools as regional retailers scale across state lines.
- Manual Tools:Spreadsheet-based rate lookup systems serve micro-merchants with minimal interstate transaction volume.
- Hybrid Systems:Mixed deployments combine local data storage with cloud-based rate updates for firms with legacy infrastructure constraints.
Automated Solutions absorb the bulk of installed capacity; SaaS Platforms are expanding most quickly.
Deployment:
Cost tier stratification separates enterprise capital expenditure from mid-market operational expenditure preferences.
- Cloud-based:Fully managed infrastructure eliminates server maintenance and software patching burdens while enabling automatic rate table updates. Small and medium enterprises in New York and California software corridors favor this model for compressed implementation timelines.
- Managed Services:Outsourced compliance operations handle return preparation, filing, and remittance across divergent state revenue department deadlines. Accounting firms serving multi-state clients leverage these offerings to reduce penalty exposure.
- On-premises:Local server installations persist in industrial distribution sectors with stringent data residency requirements.
- Hybrid Deployment:Split architectures preserve sensitive transaction data on local systems while routing rate calculations to cloud engines.
Cloud-based deployment captures the majority of new installations; Managed Services is climbing the fastest.
End User:
Customer type determines feature depth requirements from basic rate calculation to multi-entity consolidation.
- Medium Enterprises:Regional retailers scaling across state lines require automated exemption certificate management and multi-jurisdictional filing orchestration. These firms abandon manual processes as South Dakota v. Wayfair economic nexus rules expand compliance scope.
- Large Corporations:Complex procurement networks demand enterprise-grade tax determination engines with audit defense documentation workflows. FERC and SEC disclosure requirements tighten traceability demands on tax provision systems.
- Small Businesses:Micro-merchants with limited interstate sales volume prioritize cost-minimized solutions for basic rate lookup.
- Accounting Firms:Client service platforms aggregate compliance data across multiple taxpayer entities for consolidated advisory delivery.
Medium Enterprises represent the dominant revenue pool; Large Corporations are gaining share fastest.
Integration Level:
Application architecture determines whether tax engines operate as embedded components or external services.
- API Integrations:Direct connectivity with ERP and e-commerce backends enables real-time tax decisions at point of sale without batch processing delays. Composable finance stacks in California and New York metro software corridors displace monolithic ERP dependencies through these modular endpoints.
- ERP Integrations:Native modules within enterprise resource planning systems provide consolidated workflow for firms with existing vendor relationships.
- E-commerce Solutions:Platform-specific plugins address marketplace facilitator law requirements for online sellers.
- Standalone Systems:Independent applications serve firms with minimal existing software infrastructure or specialized compliance needs.
API Integrations command the steepest expansion trajectory; ERP Integrations retain the largest installed base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Compliance software procurement concentrates where economic nexus obligations intersect with transaction volume complexity. California, Texas, and New York metropolitan corridors anchor demand as remote sellers navigate multi-jurisdictional filing requirements.
California
Silicon Valley SaaS vendors and Los Angeles e-commerce operators drive platform adoption as the state's $500,000 revenue nexus threshold captures out-of-state digital goods sellers. The California Department of Tax and Fee Administration enforces marketplace facilitator laws requiring platforms to collect and remit on behalf of third-party merchants. San Francisco and Los Angeles metro areas host the densest concentration of subscription billing platforms embedding native tax determination.
Texas
Dallas-Fort Worth and Houston retail corridors generate sustained demand as the state's $500,000 economic nexus threshold applies to both goods and taxable services. The Texas Comptroller of Public Accounts mandates detailed destination-based sourcing for remote sellers with complex local jurisdiction layering. Austin's technology sector accelerates API-first tax engine integration into composable finance stacks.
New York
The New York State Department of Taxation and Finance enforces $500,000 revenue and 100-transaction nexus thresholds that capture mid-market retailers scaling across state lines. New York City metropolitan area accounting firms aggregate compliance data across multiple taxpayer entities for consolidated advisory delivery. Buffalo and Rochester industrial distribution networks delay cloud migration due to legacy ERP constraints.
Florida
Miami and Orlando retail hubs face compliance complexity from the state's $100,000 economic nexus threshold and lack of state income tax shifting audit focus to sales tax enforcement. The Florida Department of Revenue administers destination-based sourcing rules with county-level discretionary surtaxes. Tampa-St. Petersburg logistics corridors drive demand for automated exemption certificate management.
Illinois
Chicago metropolitan procurement networks require enterprise-grade tax determination engines with audit defense documentation workflows. The Illinois Department of Revenue enforces $100,000 revenue nexus thresholds with home rule units creating additional local compliance layers. Peoria and Rockford industrial distributors maintain on-premises installations due to stringent data residency requirements.
United States Sales Tax Compliance Software Market Competitive Landscape
West Coast cloud-native providers anchor the high-velocity tier; East Coast enterprise specialists hold the complex-procurement segment. The vendor base organizes around three strategic archetypes: API-first calculation engines, full-service compliance platforms, and embedded subscription billing modules. M&A activity concentrates on vertical tax engine acquisitions, while geographic expansion targets state revenue department filing portal integrations.
Within the cloud-native tier, Avalara and TaxJar exemplify API-first architectures that compress implementation timelines for mid-market retailers. Vertex occupies a position among enterprise-grade determination engine providers serving complex procurement networks with audit defense workflows. Sovos anchors the regulatory content specialization archetype through embedded update mechanisms that reduce penalty exposure.
| Leading Market Players |
|---|
| Avalara |
| Vertex |
| TaxJar |
| Sphere |
| TaxCloud |
| Anrok |
| Galvix |
| Sovos |
| Paddle |
| Others |
Value Network & Pricing Analysis
Mid-market retailer procurement consolidation toward usage-tiered SaaS models forces platform providers to absorb continuous rate table maintenance costs across 11,000 jurisdictions while compressing implementation timelines. This demand-side shift toward API-first consumption patterns reshapes how vendors structure subscription tiers and where they anchor development resources.
Pricing Analysis
Volume-based SaaS tiers separate high-transaction enterprise accounts from mid-market operational expenditure budgets, with premium tiers bundling audit defense workflows and dedicated implementation support. Price differentiation rests on jurisdictional coverage breadth and real-time calculation latency guarantees, with California and Texas metro buyers showing lowest price sensitivity due to compliance penalty exposure. Cost compression in the standard tier intensifies as cloud-native entrants displace legacy on-premise providers through faster deployment cycles. Small businesses exhibit highest price sensitivity, driving demand for stripped-down rate lookup tools with minimal integration overhead.
Supply Chain Analysis
Domestic-content mandates in federal procurement software requirements reshape vendor sourcing toward US-based rate table maintenance operations and domestic cloud infrastructure. Development talent concentrates in California, Washington, and New York software corridors, with specialized sales tax engineering skills commanding premium compensation that feeds into platform pricing. Raw material dependencies include jurisdictional boundary databases, state revenue department filing format specifications, and regulatory content update feeds. Single-source vulnerability sits with concentrated state-level regulatory data providers. Distribution runs through direct SaaS sales teams, accounting firm channel partnerships, and ERP vendor marketplace integrations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where platform providers pursue backward control over regulatory content pipelines and forward integration into embedded subscription billing modules to capture margin pools.
For Market Incumbents: To counter API-first entrants compressing implementation timelines, anchor enterprise relationships through audit defense documentation workflows that satisfy SEC and FERC traceability requirements. Deepen upstream control over state revenue department filing portal integrations to create switching costs. Expand capacity in Texas and California metro corridors where mid-market retailer procurement concentrates. For New Entrants and Emerging Players: Regional retailers in Florida and Illinois secondary metros represent an underserved buyer archetype with $100,000 nexus thresholds triggering fresh compliance automation demand. White-label marketplace facilitator compliance services for platforms like Amazon and eBay offer the most penetrable entry vector. Pursue accounting firm channel partnerships as the primary go-to-market angle to bypass direct incumbent competition. For Investors and Strategic Acquirers: The window for entry favors vertical tax engine specialists with telecommunications, hospitality, or digital goods modules that address sector-specific sourcing rules. Long-term viability hinges on regulatory content update infrastructure that reduces customer audit exposure. Watch state-level marketplace facilitator law expansions as the inflection signal for compliance scope acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Native embedding into subscription billing systems captures recurring revenue platform demand in California and New York metros. |
| Acquisition of Specialist Firm | Vertical tax engine purchases address telecommunications and digital goods sourcing rules underserved by generic platforms. |
| Strategic Partnership | Accounting firm alliances aggregate compliance data across multiple taxpayer entities for consolidated advisory delivery. |
| Geographic Expansion | State revenue department filing portal integrations in Florida and Illinois secondary metros unlock mid-market procurement. |
| Product Launch | Microservices-based API endpoints compress implementation timelines from quarters to weeks for composable finance stacks. |
Research Methodology
SEC 10-K filings, Streamlined Sales Tax Governing Board protocol documentation, and state revenue department administrative rule changes formed the secondary backbone, cross-referenced against primary interviews with CTOs at mid-market retailers, integration specialists at ERP vendors, and channel partners at accounting firms. The approach combined bottom-up transaction volume estimates with top-down software spend allocation across the analysis window. Triangulation validated platform adoption rates against economic nexus threshold enforcement patterns.
Historical trendline analysis examined SaaS subscription growth trajectories and API integration penetration across deployment models, organization sizes, vertical specializations, and regional adoption patterns. The analytical framework modeled value expansion through the projection horizon without year-specific anchoring. CAGRs derived from segment-level growth rate synthesis across automated solutions, SaaS platforms, and managed services tiers. Forecast inputs incorporated state-level marketplace facilitator law expansion timelines and mid-market retailer cross-border scaling patterns.
Revisions become necessary when federal digital goods taxation proposals or state-level nexus threshold adjustments materialize beyond current administrative rule trajectories. Forecasts reflect documented assumptions about regulatory enforcement consistency and cloud infrastructure cost curves. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Regulatory Compliance Technology
Regulatory Reporting Solutions Market
Regulatory Compliance Technology
Nordic Regulatory Affairs Market
Regulatory Compliance Technology
Global Quality and Compliance Management Solution Market
Regulatory Compliance Technology
US Anti Money Laundering Solution Market
Regulatory Compliance Technology
Cross-Border Customs and Trade Compliance Orchestration Platforms Market
Regulatory Compliance Technology
Regulatory Change Management Software Market
Regulatory Compliance Technology
GDPR Assessment Tools Market
Regulatory Compliance Technology
Global GDPR Services Market
Regulatory Compliance Technology
Aviation Compliance Monitoring Software Market
Regulatory Compliance Technology
Management System Certification Market
Regulatory Compliance Technology
Global Regulatory Technology (Regtech) Market
Regulatory Compliance Technology
Global Anti- Money Laundering Solutions Market
Regulatory Compliance Technology
Anti-Money Laundering Systems Market
Regulatory Compliance Technology
Global AML Software Market
Regulatory Compliance Technology
Regulatory Information Management System Market
Regulatory Compliance Technology
Compliance and Traceability Solutions Market