
 Nordic Regulatory Affairs Market | 2026-2036
Nordic Regulatory Affairs Market Size, Share, and Industry Trends Forecast 2026-2036
Nordic Regulatory Affairs Market Intelligence
The service-provider channel between boutique Nordic consultancies and mid-cap pharmaceutical sponsors is narrowing as EMA procedure complexity rises. Parexel International Corporation leverages its pan-European clinical infrastructure to anchor multi-country submission mandates. Freyr specializes in regulatory technology platforms that streamline document compilation for MDR transitions. Pharma Assist Sweden AB competes through deep Swedish Medical Products Agency relationships and localized scientific advice capabilities.
Nordic regulatory affairs encompasses the strategic management of compliance documentation, scientific dossiers, and authority negotiations required for pharmaceutical, biologic, and medical product market authorization across Denmark, Finland, Iceland, Norway, and Sweden. The discipline demands precise CTD-format submissions, QMS integration, and pharmacovigilance reporting aligned with EMA and national agency standards. Consulting services capture the largest margin pool due to MDR and IVDR transition urgency, while document submission work grows fastest as electronic Common Technical Document formats become mandatory. Clinical trial application support concentrates among biotechnology firms seeking first-in-human approvals through Nordic competent authorities.
EMA centralized procedures, MDR compliance timelines, and national agency variations across Denmark's Danish Medicines Agency, Sweden's Medical Products Agency, and Finland's Fimea shape service demand and pricing structures. The EU AI Act introduces additional algorithm validation requirements for software-as-medical-device submissions, expanding advisory scopes. Stakeholders must monitor how Norway's EEA alignment evolves relative to EU regulatory automation initiatives and whether Iceland's small-market status sustains its role as a pilot jurisdiction for novel framework testing.
Market Dynamics
EMA centralized procedure complexity is compressing the service-provider channel between boutique Nordic consultancies and mid-cap pharmaceutical sponsors, forcing consolidation around pan-European clinical infrastructure and regulatory technology platforms.
Growth Catalysts
- MDR transition urgency:Medical device manufacturers across Sweden and Denmark accelerate consulting engagements to meet technical documentation and quality management system deadlines.
- Sweden:The Medical Products Agency's scientific advice capabilities attract early-stage biotechnology firms seeking first-in-human trial approvals.
- Electronic submission mandates:Electronic Common Technical Document formats create sustained demand for document compilation and validation services.
Market Restraints
- Talent scarcity:Qualified regulatory affairs professionals with EMA procedure experience command premium compensation, elevating service delivery costs.
- Norway EEA uncertainty:Evolving alignment with EU regulatory automation initiatives creates submission timeline unpredictability for sponsors.
- IVDR technical validation:In vitro diagnostic regulation compliance requires specialized clinical evidence generation capabilities that few Nordic consultancies possess.
Strategic Opportunities
- Finland:Fimea's emerging role in decentralized clinical trial oversight positions Helsinki as a hub for novel trial design regulatory consultation.
- EU AI Act algorithm validation:Software-as-medical-device submissions create advisory scope expansion for machine learning quality management system implementation.
- Pharmacovigilance outsourcing:Periodic safety update report automation and signal detection services attract mid-cap sponsors seeking cost-efficient Nordic operations.
Industry Challenges
- CTD-format expertise gap:Document compilation specialists with Module 1-5 integration experience remain scarce relative to submission volume growth.
- Legacy QMS integration:Medical device manufacturers struggle to align ISO 13485 procedures with MDR Article 10 general safety and performance requirements.
- Cross-border authority negotiation:Variations between Danish Medicines Agency and Swedish Medical Products Agency scientific advice timelines complicate multi-country development strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nordic Regulatory Affairs Market |
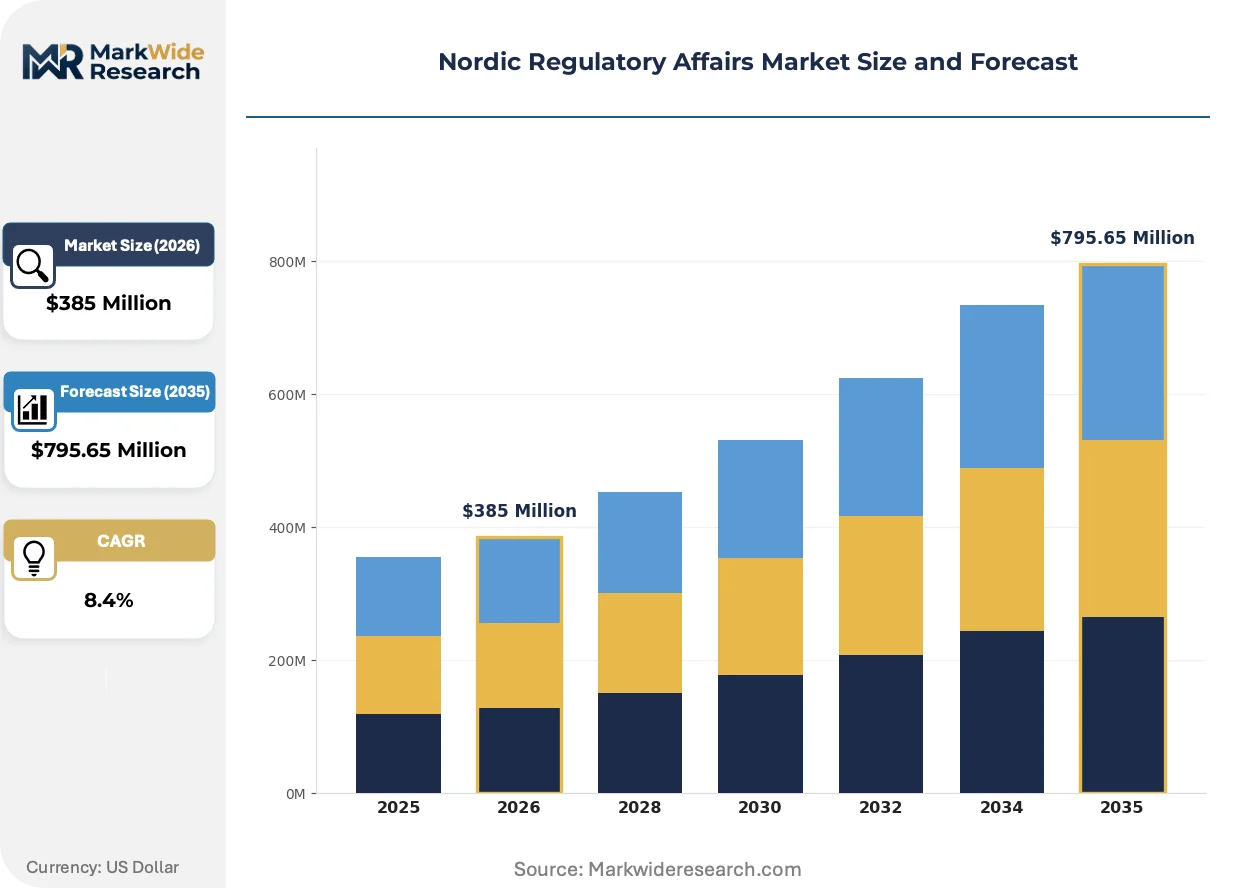
| Market Size in 2026 | $385 Million |
| Market Size in 2035 | $795.65 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Consulting, Compliance Management, Document Submission, Scientific Advice End User: Pharmaceutical Companies, Biotechnology Firms, Medical Device Manufacturers, Research Institutions Application: Product Development, Market Authorization, Clinical Trials, Post-Market Surveillance Therapy Area: Oncology, Cardiovascular, Neurology, Infectious Diseases |
| Companies Covered | Parexel International Corporation, Freyr, Pharma Assist Sweden AB, Global Pharma Consultancy AB, PRA Health Sciences, GenPact Ltd., Charles River Laboratories International, Inc., Syneos Health, ICON plc, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nordic Regulatory Affairs Market Strategic Shifts & Innovations
Regulatory technology platforms are compressing document compilation timelines while EMA procedure digitization and sponsor procurement model evolution reshape competitive positioning across the Nordic consulting landscape.
Artificial intelligence-powered document authoring tools automate Module 2 summary generation and cross-reference verification for eCTD submissions. Mid-cap pharmaceutical sponsors in Denmark and Sweden deploy these platforms to reduce regulatory writing cycle times by half. The technology is migrating from pilot implementation in large-cap sponsors to standard deployment across emerging biotechnology firms, compressing the cost advantage historically held by established consultancies.
The EU AI Act introduces mandatory algorithm validation documentation for machine learning-enabled diagnostic software. Nordic competent authorities in Finland and Sweden now require conformity assessment procedures that mirror medical device risk classification frameworks. Software-as-medical-device developers in Norway face expanded clinical evidence requirements that delay market authorization timelines by six to twelve months relative to traditional hardware submissions.
Fixed-fee milestone contracts are displacing hourly billing arrangements for clinical trial application support. Biotechnology sponsors in Copenhagen and Stockholm demand outcome-based pricing tied to regulatory authority acceptance rather than effort expended. This shift concentrates procurement power among sponsors with multiple active development programs, squeezing margin structures for boutique consultancies dependent on single-project engagements.
Nordic Regulatory Affairs Market Segmentation
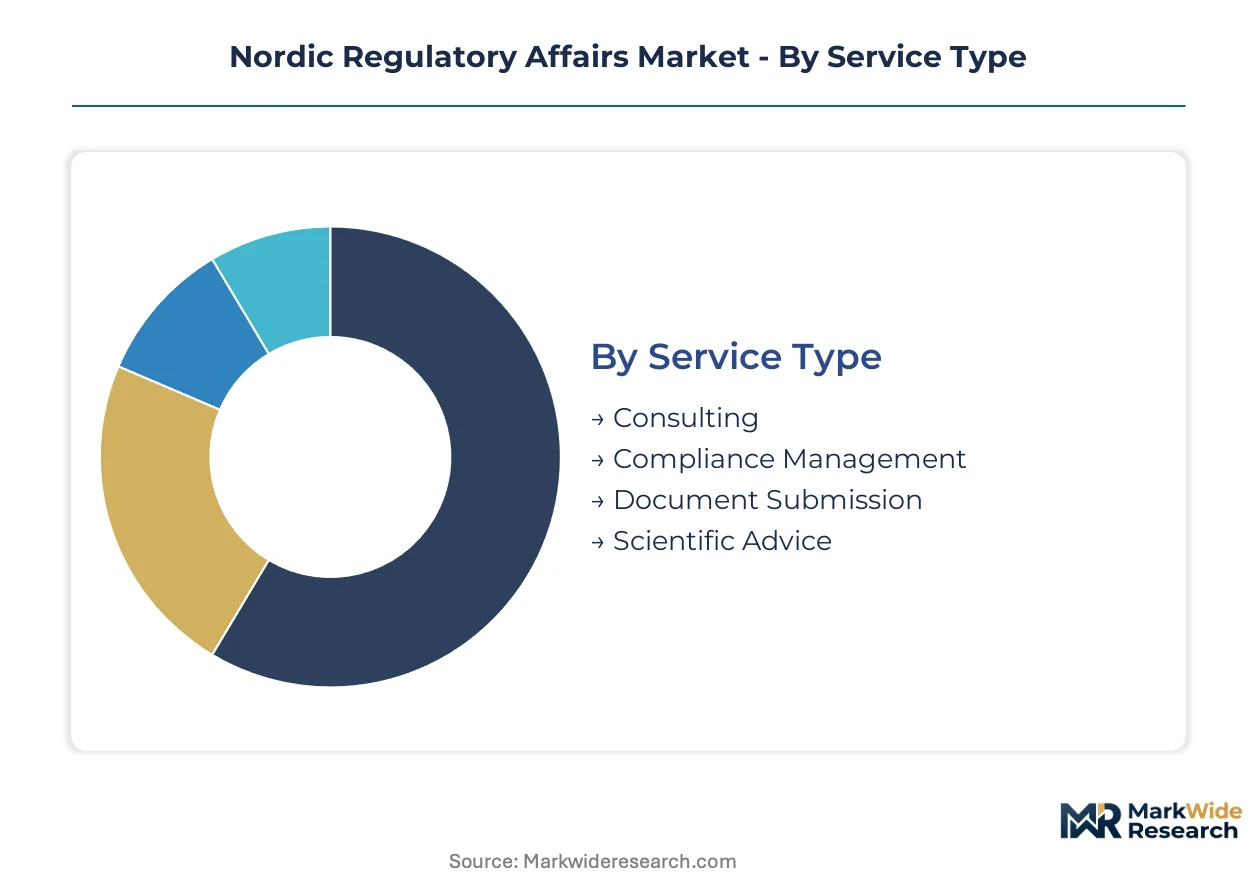
Service delivery models in Nordic regulatory affairs fragment across advisory depth, submission complexity, and therapeutic specialization. Cycle time variations between strategic consulting engagements and transactional document work create distinct margin profiles and talent requirements across each segment category.
Service Type:
Compliance Management and Document Submission turn over fastest with project cycles under 90 days, while Scientific Advice and strategic Consulting extend across 6-18 month retainer relationships.
- Consulting:Strategic advisory encompassing regulatory pathway design, authority negotiation preparation, and MDR transition planning. Demand concentrates among mid-cap pharmaceutical sponsors in Denmark and Sweden facing EMA centralized procedure complexity.
- Compliance Management:Ongoing quality management system maintenance, pharmacovigilance reporting, and periodic safety update automation. Medical device manufacturers across Norway and Finland drive adoption as MDR Article 10 technical documentation deadlines approach.
- Document Submission:Electronic Common Technical Document compilation, Module 1-5 integration, and eCTD validation services. Biotechnology firms in Stockholm and Copenhagen seek fixed-fee milestone contracts to compress regulatory writing timelines.
- Scientific Advice:Pre-submission meetings with Swedish Medical Products Agency, Danish Medicines Agency, and Fimea to align clinical development strategies. Early-stage oncology developers anchor demand in Gothenburg and Helsinki.
Consulting dominates installed base revenue. Document Submission is where expansion concentrates.
End User:
Cost tier stratification separates high-complexity biotechnology engagements from standardized medical device manufacturer contracts.
- Pharmaceutical Companies:Large-cap sponsors with established Nordic presence leverage pan-European clinical infrastructure for multi-country submission mandates. EMA centralized procedure expertise commands premium pricing.
- Biotechnology Firms:Emerging developers seeking first-in-human approvals through Nordic competent authorities. Sweden's Medical Products Agency scientific advice capabilities attract early-stage capital deployment.
- Medical Device Manufacturers:Swedish and Danish manufacturers accelerate MDR transition consulting to meet technical documentation and quality management system deadlines. ISO 13485 alignment with Article 10 requirements drives sustained advisory demand.
- Research Institutions:Academic medical centers and university hospitals navigating investigator-initiated trial regulations. Finland's decentralized clinical trial oversight expansion creates advisory scope in Helsinki.
Medical Device Manufacturers anchor current volume. Biotechnology Firms are climbing the fastest.
Application:
Geographic concentration varies by development phase, with clinical trial applications clustering in Sweden and Denmark while post-market surveillance distributes across all five Nordic markets.
- Product Development:Regulatory strategy formulation during preclinical and early clinical phases. Danish Medicines Agency engagement timelines influence Copenhagen sponsor advisory patterns.
- Market Authorization:Centralized and national procedure navigation for pharmaceutical, biologic, and medical product approvals. EMA procedure digitization reshapes document compilation requirements.
- Clinical Trials:First-in-human and pivotal trial regulatory support through Nordic competent authorities. Sweden anchors demand with established scientific advice infrastructure.
- Post-Market Surveillance:Pharmacovigilance system implementation, signal detection, and periodic safety update reporting. Norway's EEA alignment uncertainty creates timeline unpredictability for sponsors.
Clinical Trials capture the steepest expansion trajectory. Post-Market Surveillance holds the largest latent pool.
Therapy Area:
Maturity differentiation separates established cardiovascular pathways from emerging neurology frameworks.
- Oncology:Complex biomarker-driven development programs requiring adaptive trial design regulatory consultation. Fimea's emerging decentralized trial oversight role positions Finland for novel oncology protocol review.
- Cardiovascular:Well-established endpoints and historical precedent streamline Nordic competent authority engagement. Large-cap sponsors dominate with legacy program portfolios.
- Neurology:Expanding indication scope for rare disease and gene therapy submissions. Swedish Medical Products Agency scientific advice attracts early-stage developers.
- Infectious Diseases:Pandemic preparedness infrastructure and antimicrobial resistance frameworks drive regulatory advisory. Denmark's vaccine development cluster anchors demand.
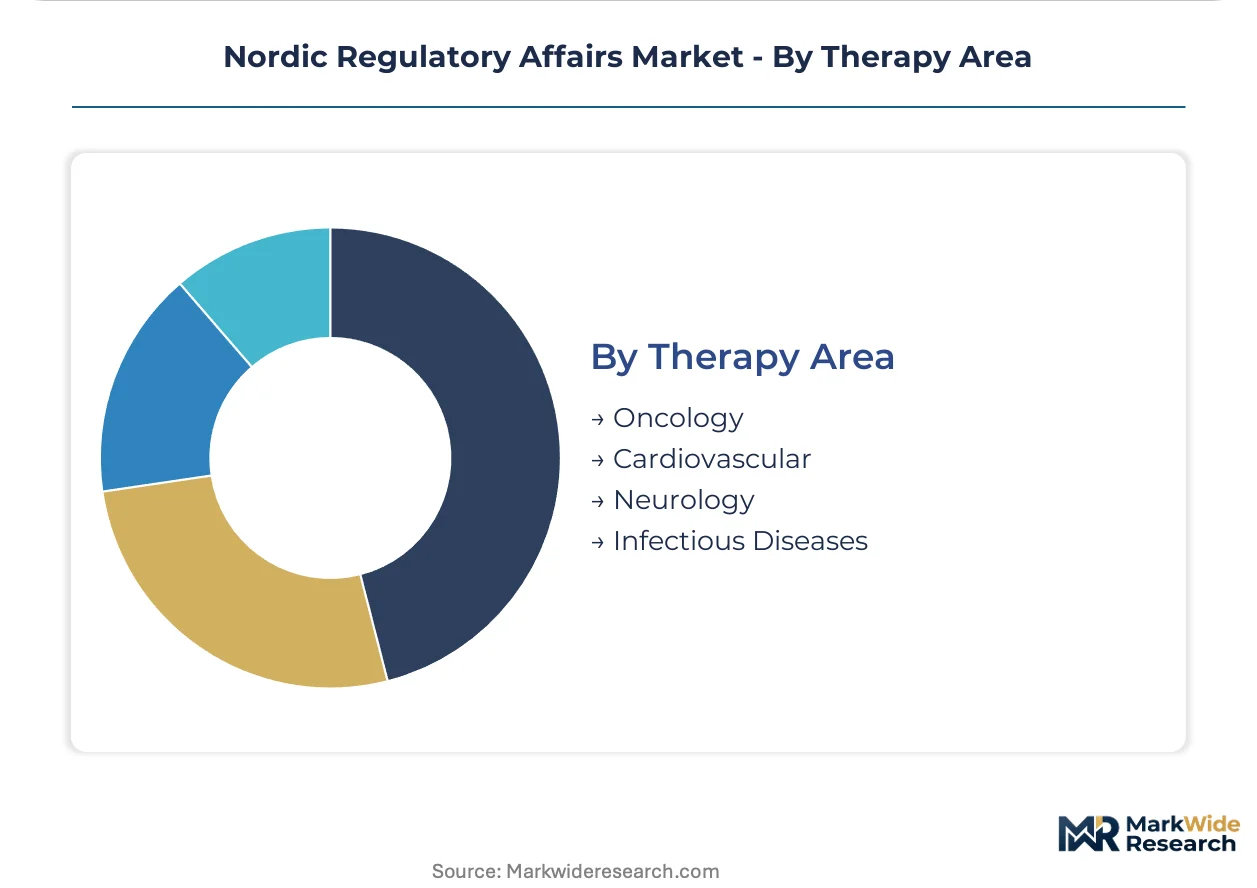
Cardiovascular dominates installed base. Oncology is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EMA centralized procedure digitization and MDR compliance deadlines are redistributing regulatory service demand across the Nordic region. National agency capabilities and scientific advice infrastructure determine where sponsors concentrate development programs.
Sweden
The Medical Products Agency's scientific advice capabilities attract early-stage biotechnology firms seeking first-in-human trial approvals. Stockholm anchors the region's clinical trial application volume with established regulatory writing clusters. Gothenburg's oncology developer concentration drives demand for adaptive trial design consultation.
Denmark
Copenhagen's pharmaceutical sponsor density creates sustained demand for EMA centralized procedure navigation. The Danish Medicines Agency engagement timelines influence multi-country development strategies for mid-cap sponsors. The city's vaccine development cluster generates specialized regulatory advisory requirements.
Finland
Fimea's emerging role in decentralized clinical trial oversight positions Helsinki for novel protocol review demand. The agency's pilot jurisdiction status attracts software-as-medical-device developers testing EU AI Act compliance pathways. Academic medical centers drive investigator-initiated trial regulatory support.
Norway
EEA alignment uncertainty with EU regulatory automation initiatives creates timeline unpredictability for sponsors. Oslo-based mid-cap pharmaceutical companies seek pharmacovigilance outsourcing to manage periodic safety update reporting costs. The country's small-market status limits standalone submission volume.
Iceland
The Icelandic Medicines Agency's pilot jurisdiction role sustains niche demand for novel framework testing. Reykjavik's minimal industrial base restricts local service provider development. Sponsors leverage the market for regulatory sandbox opportunities rather than core submission mandates.
Nordic Regulatory Affairs Market Key Industry Players
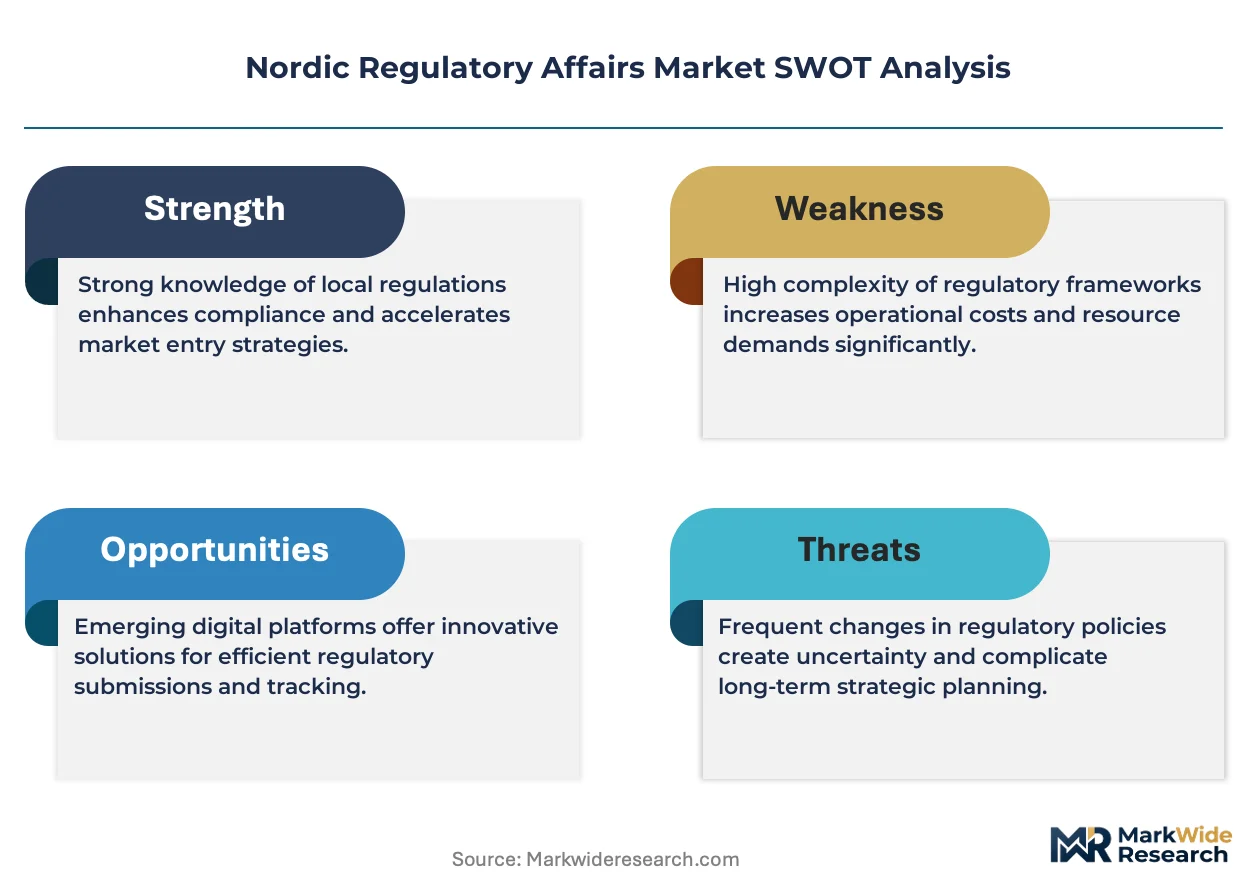
On the supply side, the industry is consolidating around pan-European clinical infrastructure and regulatory technology platforms as EMA procedure complexity compresses the service-provider channel. Boutique Nordic consultancies face margin pressure from mid-cap sponsors demanding fixed-fee milestone contracts. Three archetypes dominate: pan-European contract research organizations with centralized procedure expertise, specialized regulatory technology platform providers, and localized consultancies with deep national agency relationships. Competitive moves concentrate on M&A for clinical infrastructure scale and strategic partnerships for technology capability access.
Among pan-European service providers, Parexel International Corporation exemplifies the infrastructure-heavy archetype with multi-country submission mandates. Freyr occupies a position within the regulatory technology platform tier, streamlining document compilation for MDR transitions. Pharma Assist Sweden AB represents the localized consultancy model with deep Swedish Medical Products Agency relationships.
| Leading Market Players |
|---|
| Parexel International Corporation |
| Freyr |
| Pharma Assist Sweden AB |
| Global Pharma Consultancy AB |
| PRA Health Sciences |
| GenPact Ltd. |
| Charles River Laboratories International, Inc. |
| Syneos Health |
| ICON plc |
| Others |
Cost & Logistics Intelligence
Copenhagen's pharmaceutical sponsor density concentrates procurement power among mid-cap biotechnology firms seeking fixed-fee milestone contracts for EMA centralized procedure navigation. This geographic clustering compresses margins for boutique Nordic consultancies dependent on hourly billing arrangements while elevating pricing leverage for pan-European service providers with multi-country submission infrastructure.
Pricing Analysis
Certification level (ISO 13485/MDR CE-grade) creates the primary spread between premium advisory rates and standardized document compilation fees. Project-based pricing dominates clinical trial application support, with biotechnology sponsors in Stockholm and Copenhagen demanding outcome-based contracts tied to regulatory authority acceptance. Pricing pressure stems from regulatory technology platform adoption automating Module 2 summary generation and cross-reference verification. Mid-cap pharmaceutical sponsors exhibit highest price sensitivity due to capital constraints, while large-cap sponsors with established Nordic presence prioritize speed over cost.
Supply Chain Analysis
EU dual-use export controls and technology transfer restrictions limit algorithm validation documentation flows for machine learning-enabled diagnostic software developers. Regulatory talent concentrates in Sweden, Denmark, and Finland, with qualified EMA procedure specialists commanding premium compensation that elevates service delivery costs. Supply chain risk centers on single-source vulnerability for CTD-format document compilation specialists with Module 1-5 integration experience. Distribution runs through direct engagement models between sponsors and national competent authorities, with pan-European contract research organizations intermediating multi-country submission mandates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now govern competitive positioning as regulatory technology automation and sponsor procurement model evolution compress traditional advisory margins. Interoperability between eCTD submission systems and quality management software is redistributing value capture across the service provider landscape.
For Market Incumbents: Harden pan-European clinical infrastructure through M&A for multi-country submission scale. Acquire regulatory technology platforms to defend against document automation commoditizing Module 2-5 compilation work. EMA procedure digitization and fixed-fee contract migration threaten hourly billing margins; vertical integration into pharmacovigilance automation preserves recurring revenue streams.
For New Entrants and Emerging Players: Build out specialized algorithm validation capabilities for EU AI Act compliance as software-as-medical-device submissions expand advisory scopes. Finland's decentralized clinical trial oversight and Helsinki's pilot jurisdiction status offer the most penetrable geographic entry point. Target outcome-based pricing contracts with mid-cap oncology developers seeking adaptive trial design consultation through Fimea.
For Investors and Strategic Acquirers: Carve-out targets emerge from large-cap pharmaceutical sponsors divesting captive regulatory affairs functions to focus on core R&D. Long-term viability favors platform-enabled service providers with technology-augmented delivery models over pure-play consulting boutiques. Monitor Norway's EEA alignment negotiations as an inflection signal for regional service demand redistribution.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Technology Platform Acquisition | Automated eCTD compilation compresses document preparation timelines for MDR transitions. |
| Pan-European Clinical Infrastructure Expansion | Multi-country submission mandates require presence across EMA centralized procedure hubs. |
| Pharmacovigilance Outsourcing Capability Buildout | Periodic safety update report automation attracts cost-conscious mid-cap sponsors. |
| EU AI Act Algorithm Validation Service Launch | Machine learning quality management system implementation expands advisory scope. |
| Nordic National Agency Relationship Deepening | Swedish Medical Products Agency scientific advice access accelerates first-in-human approvals. |
Research Approach
Findings reconcile primary fieldwork against secondary review of EMA centralized procedure documentation, MDR transition guidance publications, and national competent authority submission databases. Interviews with regulatory affairs directors, clinical development executives, quality management officers, and medical device regulatory specialists informed demand pattern assessment. Secondary sources included Danish Medicines Agency procedural timelines, Swedish Medical Products Agency scientific advice records, Fimea decentralized trial oversight frameworks, and trade flow data for regulatory service procurement. Bottom-up service provider capacity modeling and top-down sponsor expenditure analysis were triangulated for market sizing.
Forecast inputs span service type segmentation by advisory depth and submission complexity, end-user stratification across pharmaceutical, biotechnology, and medical device manufacturer archetypes, and application dimensions covering clinical trial support versus post-market surveillance. Therapy area differentiation between established cardiovascular pathways and emerging oncology frameworks was modeled. CAGRs were derived from regression analysis of historical EMA procedure volume growth and MDR compliance deadline acceleration effects across the projection horizon. EMA digitization timelines and EU AI Act implementation phases served as regulatory scenario anchors.
Stress conditions across Norway EEA alignment evolution, IVDR technical validation capability scarcity, and regulatory technology platform adoption rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding EMA procedure complexity trajectories and sponsor procurement model migration speeds. Material shifts in EU regulatory automation initiatives or Nordic national agency scientific advice capacity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Regulatory Compliance Technology
Global Anti- Money Laundering Solutions Market
Regulatory Compliance Technology
Global Quality and Compliance Management Solution Market
Regulatory Compliance Technology
Compliance Testing Solutions Market
Regulatory Compliance Technology
Global AML Software Market
Regulatory Compliance Technology
Global Regulatory Technology (Regtech) Market
Regulatory Compliance Technology
GDPR Assessment Tools Market
Regulatory Compliance Technology
United States Sales Tax Compliance Software Market
Regulatory Compliance Technology
US Anti Money Laundering Solution Market
Regulatory Compliance Technology
Regulatory Reporting Solutions Market
Regulatory Compliance Technology
Regtech Software Market
Regulatory Compliance Technology
Global GDPR Services Market
Regulatory Compliance Technology
Regulatory Information Management System Market
Regulatory Compliance Technology
Regulatory Change Management Software Market
Regulatory Compliance Technology
Aviation Compliance Monitoring Software Market
Regulatory Compliance Technology
Cross-Border Customs and Trade Compliance Orchestration Platforms Market
Regulatory Compliance Technology
Anti-Money Laundering Systems Market