
 US Accounting Software Market | 2026-2036
US Accounting Software Market Size, Share, and Industry Trends Forecast 2026-2036
US Accounting Software Market Insights
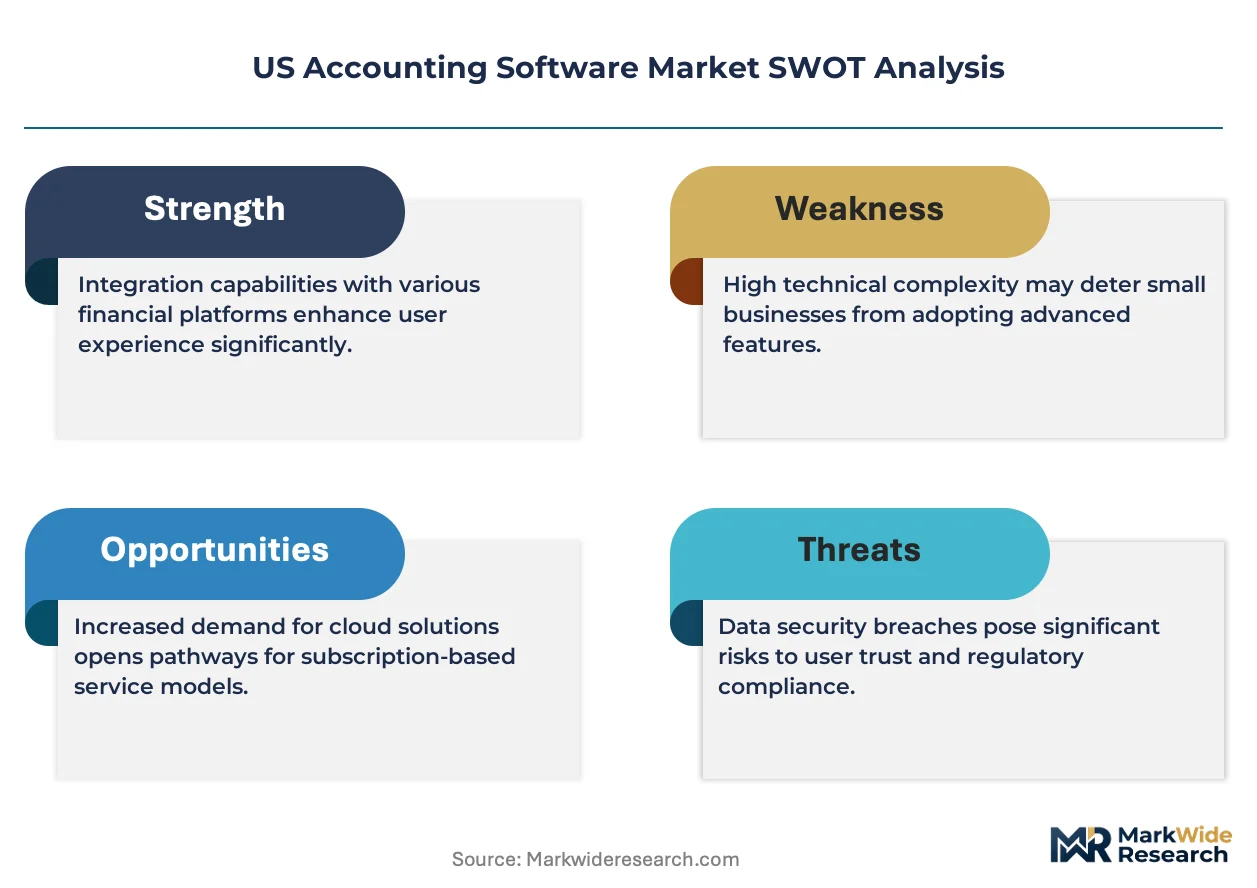
Sarbanes-Oxley compliance is shifting the cost-of-entry calculus for accounting software vendors serving publicly traded clients. Intuit QuickBooks dominates the small business segment with brand strength and channel control across retail and professional services. Oracle NetSuite anchors the mid-market ERP space with deep vertical functionality for manufacturing and healthcare. Sage Intacct differentiates through multi-entity consolidation capabilities that appeal to growing franchise operations and nonprofit networks.
US accounting software encompasses systems that automate financial record-keeping, general ledger management, accounts payable and receivable processing, and regulatory reporting through standardized data formats such as XBRL and API-driven bank feeds. Cloud-based deployment now leads the market as SaaS models replace on-premises installations, while tax software and payroll management capture concentrated margin pools from compliance-driven renewal cycles. ERP solutions serving large corporations remain mature with slower expansion, whereas expense management tools targeting mid-sized enterprises show the fastest uptake as distributed workforces demand real-time reimbursement workflows.
The IRS, SEC, and FASB collectively shape product standards through electronic filing mandates, revenue recognition rules under ASC 606, and audit trail requirements that force continuous platform updates. State-level CPA board regulations in California, New York, and Texas add licensing complexity for software providers offering advisory or bookkeeping services. Stakeholders must monitor how forthcoming IRS real-time reporting pilots and state sales tax nexus laws reshape integration priorities between accounting platforms and payment processors.
Market Dynamics
The IRS real-time reporting mandate is compressing upgrade cycles for legacy on-premise systems, forcing mid-sized enterprises toward cloud-native platforms with embedded compliance engines.
Growth Catalysts
- Electronic Filing Mandates:The IRS mandate for real-time tax data submission compels legacy system users toward compliant SaaS architectures. Professional services clusters in New York and Texas accelerate replacement timelines.
- API-Driven Bank Feeds:Open banking protocols enable automated reconciliation workflows that reduce manual data entry. Manufacturing and healthcare verticals adopt these integrations fastest.
- California CPA Board Licensing:Stricter state-level credentialing requirements for advisory services create captive demand for certified platform modules. Franchise operations expand multi-entity deployments to satisfy audit trail standards.
Market Restraints
- Data Migration Friction:Decades of historical ledger data trapped in proprietary formats inflate switching costs. Mid-market firms face six-to-twelve month transition timelines.
- Cybersecurity Insurance Requirements:SOC 2 Type II certification has become a de facto procurement gate. Non-certified vendors lose RFP eligibility across financial services and healthcare buyer segments.
- Talent Scarcity in XBRL Taxonomy:Specialized expertise for SEC-compliant financial reporting remains concentrated among legacy consultants. SaaS providers compete for this limited talent pool.
Strategic Opportunities
- Texas Franchise Tax Automation:The state's complex margin-based calculation creates white space for vertical-specific modules. Oilfield services and logistics clusters show unmet demand.
- AI-Assisted Audit Preparation:Machine learning convergence with natural language processing automates documentation review. Regional CPA firms adopt these tools to compete with national practices.
- Embedded Payments Integration:Native payment processing within accounting platforms captures interchange revenue. Illinois professional services networks pilot these unified workflows.
Industry Challenges
- ASC 606 Implementation Complexity:Revenue recognition rule changes require continuous platform reconfiguration. SaaS vendors absorb engineering costs without proportional pricing power.
- Interoperability with State Tax Systems:Florida's sales tax nexus laws demand real-time rate calculations across 67 counties. Integration maintenance consumes disproportionate development resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Accounting Software Market |
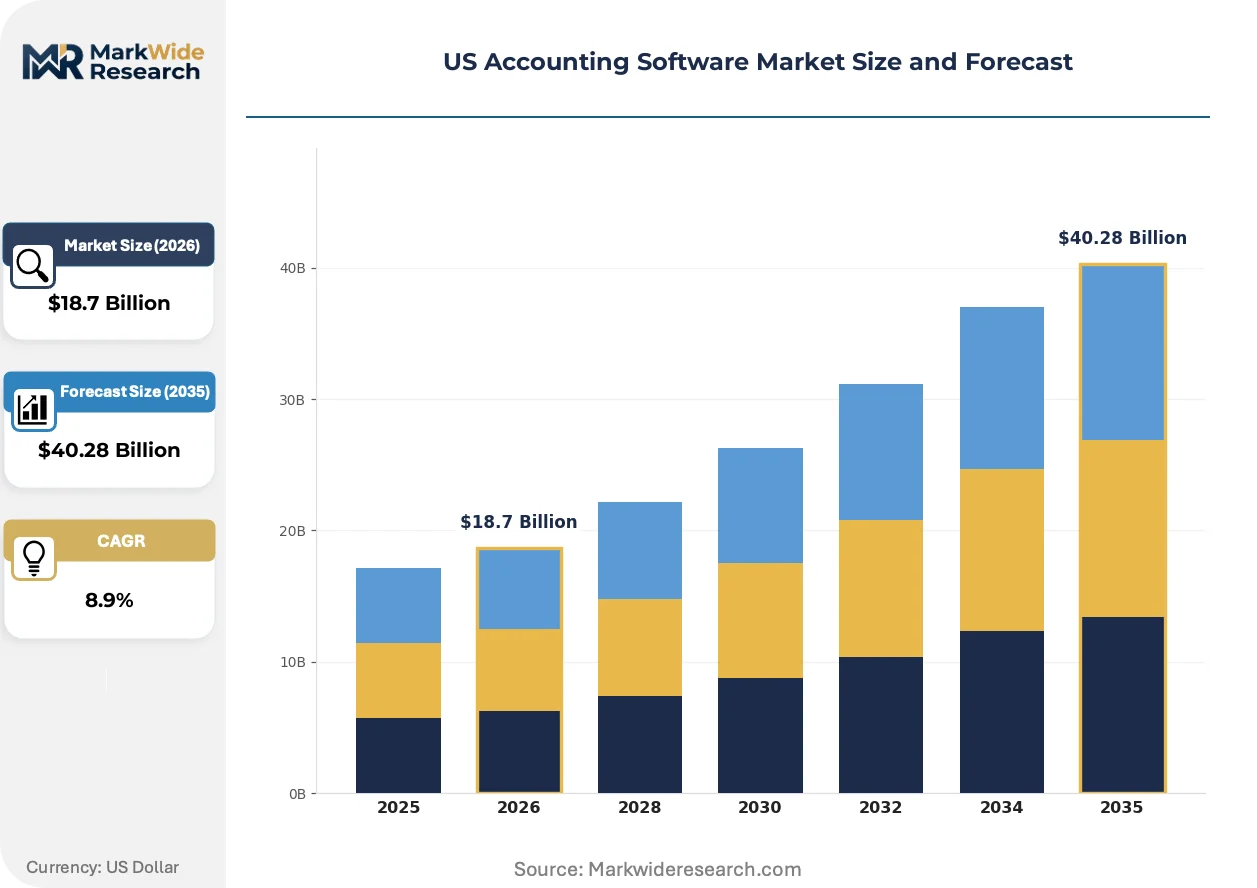
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $40.28 Billion |
| CAGR (2026 – 2036) | 8.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, SaaS Solution Type: ERP, Expense Management, Tax Software, Payroll Management End User: Small Businesses, Mid-Sized Enterprises, Large Corporations, Freelancers Industry Vertical: Retail, Manufacturing, Healthcare, Non-Profit |
| Companies Covered | Xero, Avalara, Intuit QuickBooks, Digits, Zoho Books, Oracle NetSuite, FreshBooks, Pilot, Sage Intacct, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Accounting Software Market Trends and Innovations
Automation architectures are converging with compliance engines to compress the traditional month-end close cycle from weeks to days.
Embedded machine learning for anomaly detection is consolidating transaction monitoring across accounts payable and receivable workflows. Mid-sized professional services firms in Illinois and Florida deploy these tools to replace manual sampling-based audits. The technology is consolidating risk management functions that previously required separate point solutions.
FASB revenue recognition guidance under ASC 606 forces continuous platform updates for contract modification tracking. SaaS vendors serving subscription-heavy verticals re-engineer core data models quarterly. Healthcare and software-as-a-service end-use segments face the steepest compliance engineering costs.
Subscription pricing for advisory modules displaces perpetual license models among regional CPA firms. Tiered access to automated compliance engines replaces traditional hourly billing for tax preparation. This shift concentrates most visibly in California and New York metropolitan clusters where labor costs pressure margin structures.
US Accounting Software Market Segmentation
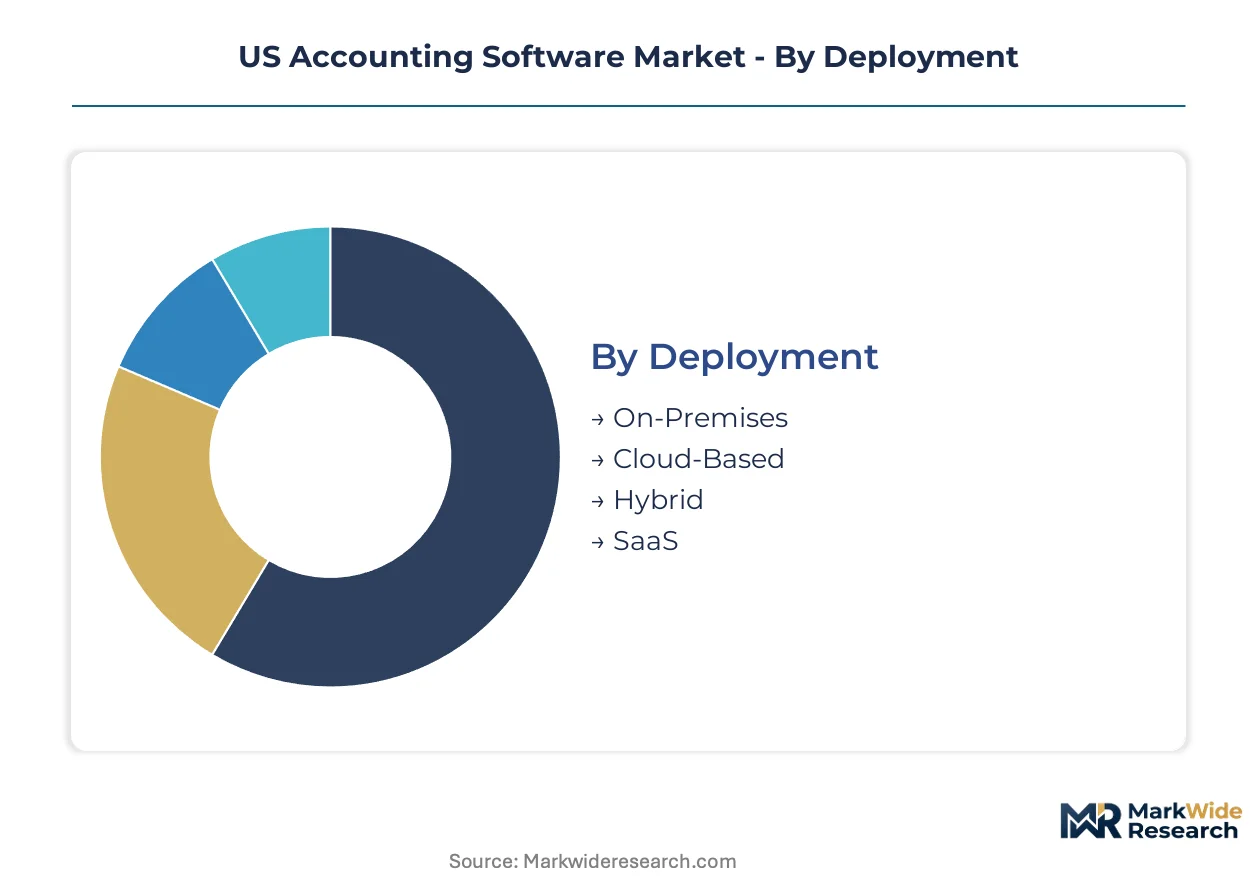
Deployment architecture determines compliance velocity for US accounting software buyers facing IRS electronic filing mandates. Solution specialization and end-user scale create divergent margin profiles across the market's $18.7 billion base.
Deployment:
Cloud-native architectures demand minimal upfront capital versus legacy on-premise infrastructure requiring dedicated server hardware and IT staffing.
- On-Premises:Perpetual license models with localized data storage appeal to defense contractors and rural healthcare systems with air-gapped security requirements. Texas oilfield services firms retain these installations for field-office autonomy despite higher total cost of ownership.
- Cloud-Based:Multi-tenant SaaS platforms with automatic compliance updates dominate new procurement across California and New York professional services clusters. Real-time bank feed integration eliminates reconciliation bottlenecks.
- Hybrid:Sensitive payroll data remains on local servers while general ledger functions migrate to cloud instances. Mid-sized manufacturers in Illinois adopt this architecture for phased transition.
- SaaS:Subscription pricing with embedded tax engine updates captures franchise operations seeking predictable operational expenditures. Quarterly feature releases replace multi-year upgrade cycles.
Most installed capacity flows through On-Premises systems in legacy manufacturing and government contracting. Expansion is steepest in Cloud-Based deployment among mid-market professional services.
Solution Type:
Payroll and tax modules command premium pricing due to compliance-driven renewal cycles and penalty avoidance value.
- ERP:Unified financial, supply chain, and human capital management through single data models. Manufacturing verticals in the Midwest deploy these systems for inventory-costing precision under ASC 606.
- Expense Management:Real-time receipt capture and policy enforcement via mobile applications. Distributed workforces in Illinois and Florida professional services drive fastest adoption.
- Tax Software:Automated form generation with embedded IRS rule updates. Small business clusters across Texas rely on these tools for quarterly estimated payment calculations.
- Payroll Management:Direct deposit orchestration with multi-state withholding compliance. California's complex disability insurance requirements create specialized demand.
Tax Software retains the largest installed base among small business filers. Expense Management is gaining share fastest as hybrid work policies persist.
End User:
Mid-sized enterprises face the steepest compliance engineering burden relative to internal IT resources.
- Small Businesses:Entry-level bookkeeping with invoicing and basic reporting. California sole proprietors prioritize mobile-first interfaces for on-the-go reconciliation.
- Mid-Sized Enterprises:Multi-entity consolidation with audit trail requirements. New York professional services firms seek SOC 2 certified platforms for client assurance.
- Large Corporations:Global financial consolidation with XBRL SEC filing capabilities. Healthcare systems require HIPAA-compliant audit logging.
- Freelancers:Simplified 1099 tracking and quarterly tax estimation. Creative economy workers in Florida metropolitan areas value automated mileage deduction.
Mid-Sized Enterprises absorb the majority of new platform implementations. Freelancer segment expansion is climbing fastest as gig economy participation rises.
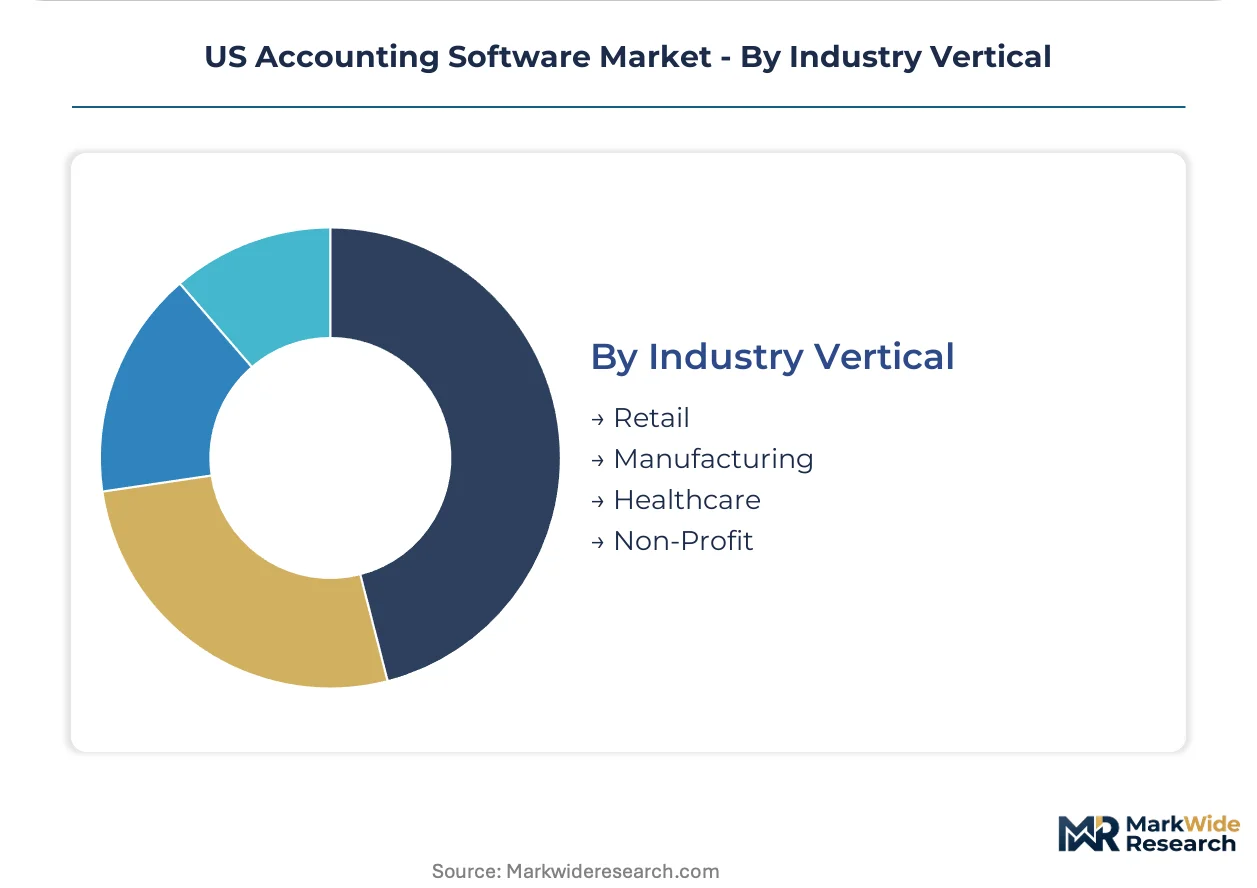
Industry Vertical:
Healthcare and non-profit sectors impose specialized fund-accounting and grant-compliance requirements.
- Retail:High-volume transaction processing with inventory valuation and sales tax nexus management. Florida's county-level rate variations demand real-time calculation engines.
- Manufacturing:Job costing and work-in-progress tracking with overhead allocation precision. Texas industrial clusters require oil and gas depletion schedule integration.
- Healthcare:Patient revenue cycle management with insurance eligibility verification and denial tracking. California providers face Medi-Cal reimbursement complexity.
- Non-Profit:Restricted fund accounting with grant compliance and Form 990 preparation. New York charitable networks need multi-entity consolidation for national operations.
Manufacturing carries the deepest legacy system penetration. Healthcare is expanding most quickly as value-based reimbursement models demand tighter financial control.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Certified public accountants and payroll specialists concentrate in Texas and California, anchoring regional demand for compliance-ready platforms. State-level credentialing requirements and industry-specific tax complexity shape procurement patterns across metropolitan clusters.
California
Medi-Cal reimbursement complexity and disability insurance mandates drive healthcare provider demand for specialized accounting modules. The California CPA Board enforces stricter licensing requirements for advisory services, compelling software vendors to embed certified workflows. Los Angeles and San Francisco metropolitan clusters lead SaaS adoption among creative economy freelancers and venture-backed startups.
Texas
Oilfield services and logistics operations require margin-based franchise tax automation unavailable in generic platforms. The Texas Comptroller's office administers complex calculations that favor vertical-specific software configurations. Houston and Dallas-Fort Worth energy corridors retain hybrid on-premise installations for field-office autonomy despite cloud migration pressure.
New York
Multi-entity professional services firms seek SOC 2 certified platforms to satisfy client assurance requirements. The New York State Department of Financial Services imposes cybersecurity standards that filter vendor eligibility. Manhattan and Brooklyn financial services clusters absorb the majority of mid-market ERP implementations serving hedge funds and private equity.
Illinois
Manufacturing job costing and work-in-progress tracking demand precision under ASC 606 revenue recognition rules. The Illinois Department of Revenue maintains complex sales tax nexus requirements across Cook County and collar counties. Chicago metropolitan manufacturers pilot hybrid deployments with sensitive payroll data remaining on local servers.
Florida
County-level sales tax rate variations across 67 jurisdictions necessitate real-time calculation engines. The Florida Department of Revenue enforces nexus laws that demand continuous integration maintenance from platform providers. Miami and Tampa professional services networks drive fastest adoption of expense management tools for distributed workforces.
US Accounting Software Market Competitive Landscape
The competitive structure tilts toward cloud-native specialists with embedded compliance engines rather than legacy ERP incumbents. Tiered player concentration separates mass-market small business offerings from vertical-specific mid-market solutions. Two strategic archetypes dominate: horizontal SaaS platforms with broad channel reach, and vertical specialists with deep industry functionality. M&A activity concentrates on tax automation capabilities, while portfolio diversification targets embedded payments integration.
Within the horizontal SaaS tier, Intuit QuickBooks and Xero occupy positions defined by mobile-first interfaces and self-service onboarding. Oracle NetSuite anchors the mid-market ERP segment with unified data models serving subscription-heavy verticals. Sage Intacct exemplifies the multi-entity consolidation specialist archetype, representing franchise operations and nonprofit networks with complex audit trail requirements.
| Leading Market Players |
|---|
| Xero |
| Avalara |
| Intuit QuickBooks |
| Digits |
| Zoho Books |
| Oracle NetSuite |
| FreshBooks |
| Pilot |
| Sage Intacct |
| Others |
Pricing and Supply Chain Analysis
Mid-sized enterprise procurement teams now mandate SOC 2 Type II certification as a non-negotiable gate, forcing supply reconfiguration toward audited cloud infrastructure providers and compressing margins for uncertified vendors unable to absorb compliance engineering costs.
Pricing Analysis
The bundled-versus-unbundled service split defines competitive positioning across the US accounting software landscape. Subscription SaaS tiers dominate, with price differentiation resting on certification grade and vertical customization depth. Cost compression in the entry-level tier intensifies as freemium models from horizontal platforms absorb price-sensitive small businesses, while least-sensitive buyers in healthcare and financial services absorb premium pricing for HIPAA-compliant audit logging and embedded tax engine modules.
Supply Chain Analysis
Warehouse-distribution layer consolidation concentrates cloud infrastructure supply across the United States, Ireland, and Singapore, with hyperscale data centers anchoring regional latency optimization. Raw material dependencies center on silicon for server hardware, lithium for backup power systems, and specialized cooling equipment. Single-source vulnerability in GPU allocation for AI-assisted audit preparation tools poses structural risk. Distribution runs through direct API-first provisioning to enterprise IT departments, bypassing traditional channel intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US accounting software market functions as a regulatory compounder, with the IRS real-time reporting mandate creating continuous demand for compliant platform refreshes and captive renewal cycles.
For Market Incumbents: Deploy embedded compliance engine investments as the primary defensive lever. Consolidate position through backward integration into payment processing infrastructure to capture interchange revenue streams. Counter emerging vertical-specific challengers by accelerating multi-entity consolidation capabilities for franchise operations. Absorb ASC 606 engineering costs through tiered advisory module pricing that displaces hourly billing. For New Entrants and Emerging Players: Texas oilfield services firms represent an underserved buyer archetype with unmet demand for margin-based franchise tax automation unavailable in generic platforms. Penetrable white space concentrates in vertical-specific modules for logistics clusters facing complex state tax calculations. Go-to-market execution should prioritize channel partnerships with regional CPA firms seeking differentiation tools against national practices. For Investors and Strategic Acquirers: Asymmetric upside sits with cloud-native specialists possessing embedded AI-assisted audit preparation capabilities and certified compliance engines. Long-term viability favors platforms demonstrating sustained R&D commitment to continuous regulatory adaptation rather than point-solution tax automation tools. Watch for IRS pilot program expansion signals as inflection indicators for real-time reporting infrastructure demand.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Native payment processing captures interchange revenue from Illinois professional services networks. |
| Acquisition of Specialist Firm | Tax automation capabilities consolidate through M&A targeting Texas franchise tax calculation engines. |
| Product Launch | AI-assisted audit preparation tools displace manual sampling for regional CPA firms in Florida. |
| Strategic Partnership | Open banking API alliances accelerate automated reconciliation adoption in manufacturing verticals. |
| Geographic Expansion | California CPA Board certified modules penetrate Los Angeles creative economy freelancer clusters. |
Research Methodology
Direct dialogue with CTOs at mid-sized professional services firms, IT procurement officers at healthcare systems, platform engineers at cloud-native vendors, and integration specialists at regional CPA practices grounded qualitative insights. Secondary validation drew from SEC filings, IRS procedural updates, state CPA board regulatory notices, and hyperscaler capex disclosures. Bottom-up deployment model sizing and top-down macroeconomic trend analysis triangulated market estimates.
Segmentation outputs across deployment architecture, solution type, end-user scale, and industry vertical dimensioned the analytical framework. CAGRs derived from historical adoption curve analysis and regulatory mandate timing assumptions across the projection horizon. Forecast inputs incorporated IRS electronic filing mandate compliance deadlines and state-level credentialing requirement phase-ins without year-specific anchoring.
Underlying measurement precision varies by segment; cloud-based deployment and mid-sized enterprise end-user categories carry tighter precision than legacy on-premise installations and freelancer segments where data fragmentation persists. Forecasts reflect documented assumptions regarding regulatory implementation timelines and technology substitution rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Accounting and Taxation Services
US Auditing Services Market
Accounting and Taxation Services
Japan Accounting Software Market
Accounting and Taxation Services
Europe Auditing Services Market
Accounting and Taxation Services
Forensic Accounting Market
Accounting and Taxation Services
China Accounting & Budgeting Software Market
Accounting and Taxation Services
Cloud Accounting Software Market
Accounting and Taxation Services
Australia Accounting Software Market
Accounting and Taxation Services
China Forensic Accounting Market
Accounting and Taxation Services
Italy Forensic Accounting Market
Accounting and Taxation Services
Bookkeeper Software Market
Accounting and Taxation Services
Tax Automation Software Market
Accounting and Taxation Services
Italy Accounting Software Market
Accounting and Taxation Services
United Kingdom Accounting Software Market
Accounting and Taxation Services
Global Business Accounting Software Market
Accounting and Taxation Services
India Accounting Software Market
Accounting and Taxation Services
China Accounting Software Market