
 Cloud Accounting Software Market | 2026-2036
Cloud Accounting Software Market Size, Share, and Industry Trends Forecast 2026-2036
Cloud Accounting Software Market Intelligence
Certified accountant shortages across mid-market firms is redrawing how software vendors design automated reconciliation and AI-assisted bookkeeping workflows. QuickBooks Online leverages its vast ProAdvisor network to sustain channel dominance among small enterprises in North America. Xero anchors its position through deep API ecosystems that connect banking, payroll, and tax preparation into unified ledgers. Sage Intacct specializes in multi-entity consolidation tools that dominate the nonprofit and franchise verticals with complex intercompany reporting needs.
Cloud accounting software delivers general ledger, accounts payable, and financial close management through browser-based interfaces with automatic data backup, role-based access controls, and real-time bank feed synchronization. Its primary commercial purpose is to replace on-premise ERP finance modules with scalable, subscription-accessible platforms that reduce IT overhead. Public cloud deployment leads volume due to lower entry costs, though hybrid cloud architectures are capturing margin pools from large corporations with segmented data sovereignty requirements. Subscription-based service models sustain predictable revenue for vendors, while expense tracking and tax management features are expanding fastest as regulatory complexity deepens client willingness to pay for automated compliance.
The EU AI Act, GDPR, and SEC cybersecurity disclosure rules are tightening how vendors process automated financial recommendations and store cross-border transaction records. HIPAA and SOX requirements in the United States further segment product roadmaps, as healthcare and publicly traded clients demand audit-trail granularity that consumer-grade tools cannot satisfy. Stakeholders must monitor whether emerging EU DORA standards for operational resilience will force additional infrastructure investments or create compliance barriers for smaller SaaS entrants.
Market Dynamics
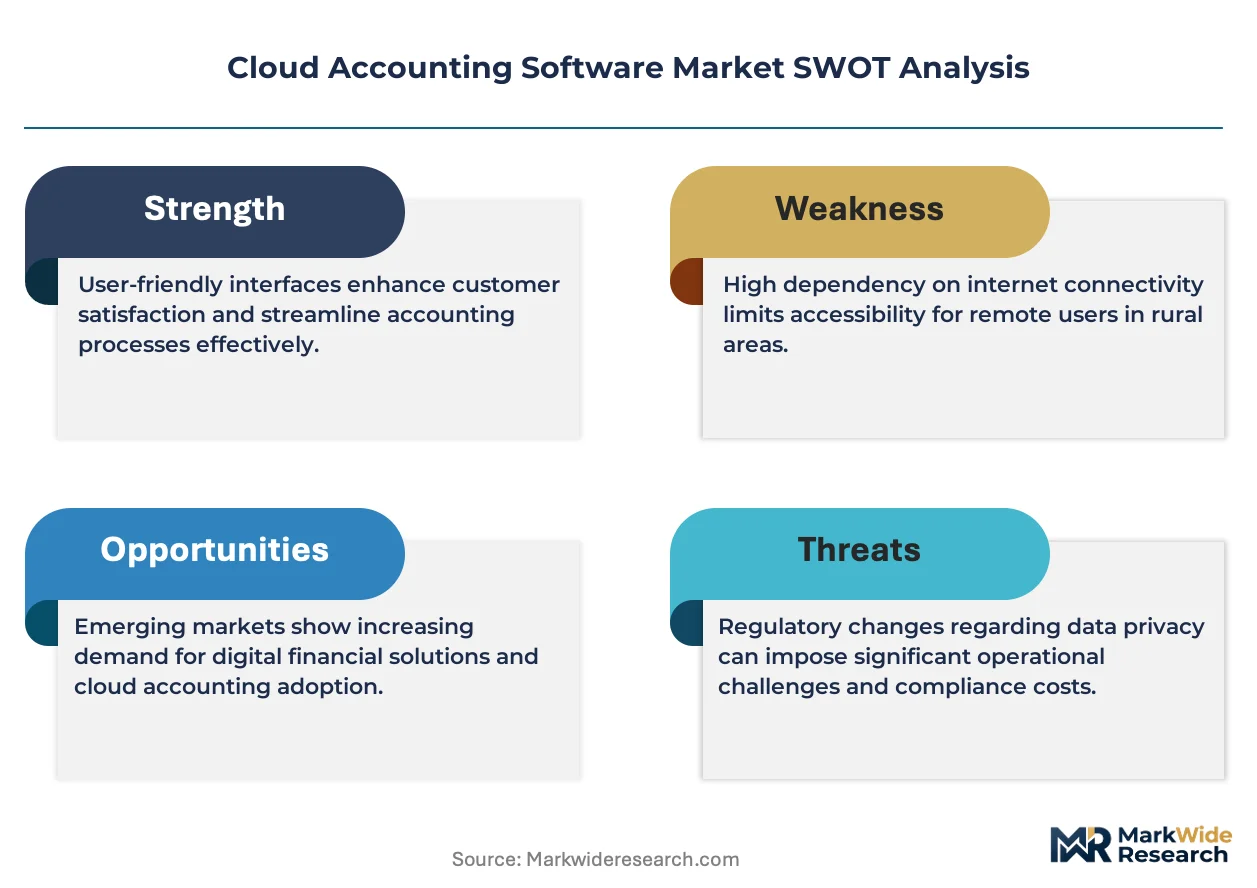
Certified accountant shortages across mid-market firms are compressing implementation timelines and forcing vendors to embed AI-assisted reconciliation directly into core workflows, eliminating the traditional services layer that once separated software from professional expertise.
Growth Catalysts
- EU AI Act compliance mandates:Automated financial recommendation engines now require algorithmic transparency documentation, creating upgrade cycles among existing subscribers seeking audit-ready systems.
- API-first banking integrations:Real-time payment rails from Plaid, Stripe Treasury, and embedded finance providers are collapsing reconciliation latency from days to minutes for small enterprises.
- Remote-work normalization:Distributed finance teams across the United States, United Kingdom, and Australia are demanding browser-native access controls that legacy on-premise ERP modules cannot provide.
Market Restraints
- Data residency fragmentation:GDPR's cross-border transfer restrictions and emerging national data localization laws in India, China, and Saudi Arabia are forcing vendors to maintain redundant infrastructure stacks.
- Certified Professional Accountant scarcity:The pipeline of credentialed bookkeepers in North America and Western Europe cannot match deployment velocity, choking implementation capacity.
- Legacy ERP switching costs:Mid-market firms with decade-old SAP or Oracle Financials deployments face six-to-eighteen month migration timelines that freeze replacement decisions.
Strategic Opportunities
- India's GST automation gap:The country's complex multi-rate tax structure and monthly compliance filing requirements create white space for cloud-native vendors with automated return preparation.
- Healthcare HIPAA-aligned modules:Specialized audit-trail granularity for clinics and hospital networks commands premium pricing unavailable to generalist platforms.
- Carbon accounting convergence:CSRD-mandated Scope 3 emissions reporting is driving demand for ledger systems that integrate financial and environmental data in unified workflows.
Industry Challenges
- Multi-jurisdiction tax engine maintenance:Vendors must continuously update calculation logic across thousands of municipal, state, and national rate tables with zero tolerance for arithmetic error.
- AI hallucination risk in automated categorization:Misclassified transactions in expense workflows create downstream audit exposure that professional liability insurers are still pricing.
- Interoperability with legacy payroll systems:Bi-directional sync with ADP, Paychex, and country-specific providers requires brittle custom connectors that break on vendor API updates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cloud Accounting Software Market |
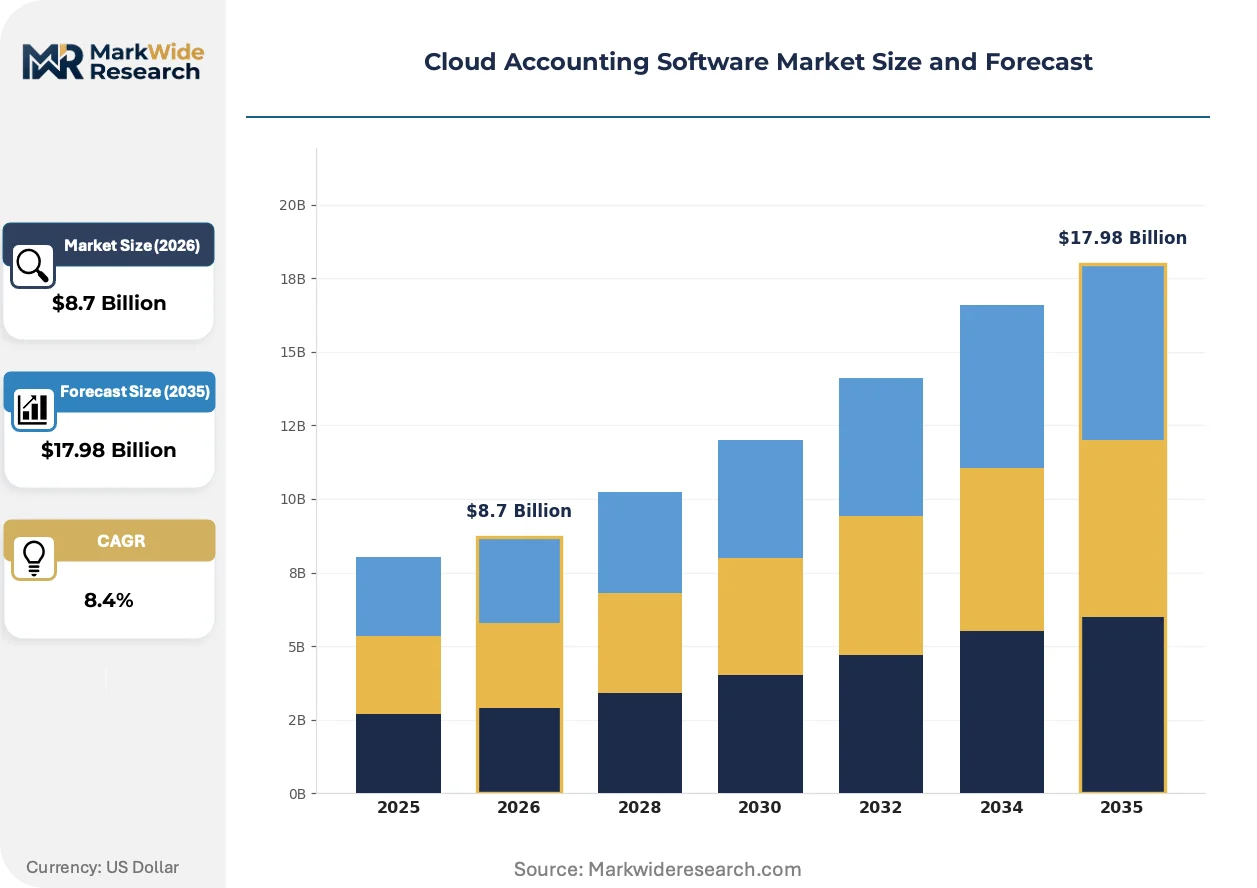
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $17.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Tenant End User: Small Enterprises, Medium Enterprises, Large Corporations, Freelancers Service Type: Subscription-Based, Pay-Per-Use, One-Time Purchase, Managed Services Feature: Invoicing, Expense Tracking, Financial Reporting, Tax Management |
| Companies Covered | Sage Intacct, FreshBooks, QuickBooks Online, Maxio, Wave, Xero, Zoho Books, Pilot, NetSuite, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cloud Accounting Software Market Strategic Shifts & Innovations
Embedded finance architectures and generative AI capabilities are collapsing the traditional boundaries between accounting software, banking infrastructure, and advisory services, creating new competitive arenas where data network effects matter more than feature depth.
Natural language processing for transaction coding is miniaturizing the cognitive load on bookkeepers by converting unstructured invoice descriptions into structured general ledger entries without manual mapping tables. Mid-market firms with lean finance teams are adopting these tools fastest, compressing month-end close cycles from ten days to three. The technology is miniaturizing the distinction between software and human judgment in routine categorization decisions.
The EU AI Act's risk-based classification system is forcing vendors to document training data provenance and algorithmic decision logic for any automated financial recommendation feature. Systems classified as high-risk must maintain human-in-the-loop controls and external audit capabilities. European mid-market deployments are experiencing six-to-nine month compliance retrofit timelines that delay feature rollouts.
Subscription unbundling is fragmenting how buyers procure accounting capabilities, with core ledger access separating from tax preparation, payroll, and CFO advisory services. Channel partners and independent bookkeepers are assembling custom technology stacks rather than reselling monolithic suites. This pattern is most visible in the United States, where the ProAdvisor network model competes with direct API-first purchasing by tech-savvy small enterprises.
Cloud Accounting Software Market Segmentation
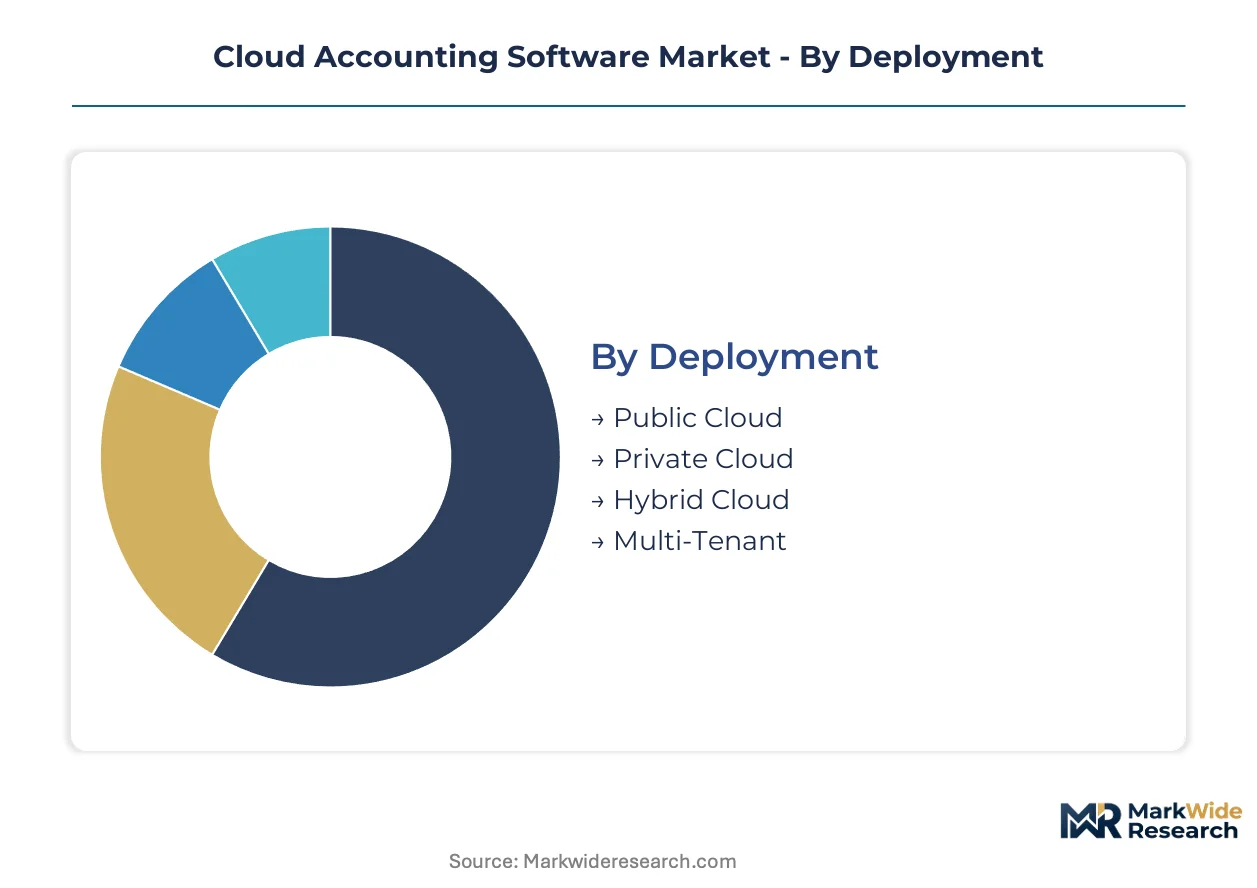
Cloud accounting software vendors architect product portfolios around deployment flexibility, organizational scale, and consumption economics. Segmentation discipline determines pricing architecture, sales motion design, and R&D resource allocation across competing platform strategies.
Deployment:
Substitution pressure concentrates most intensely among public cloud deployments, where horizontal infrastructure providers commoditize baseline compute and storage layers.
- Public Cloud:Browser-delivered platforms run on shared infrastructure with automatic scaling, backup redundancy, and zero client-side hardware investment. Small enterprises across the United States and United Kingdom dominate adoption, driven by API-first banking integrations that collapse reconciliation latency.
- Private Cloud:Single-tenant architectures isolate compute resources within dedicated virtual environments with custom security policies. Healthcare networks and financial services firms in Germany and Switzerland anchor demand, compelled by HIPAA and national banking secrecy requirements.
- Hybrid Cloud:Segmented workloads split sensitive ledger data on-premises while pushing analytics and reporting to public nodes. Large corporations with multi-entity structures in India and Australia favor this model for GST and tax residency compliance.
- Multi-Tenant:Shared application layers with logical data separation enable vendor economies of scale and rapid feature propagation. Franchise operators and nonprofit networks with standardized workflows represent the core customer base.
Public Cloud retains volume leadership; Hybrid Cloud holds the steepest expansion curve.
End User:
Cost tier stratification separates self-serve digital acquisition from enterprise sales cycles with professional services attachments.
- Small Enterprises:Firms with under 50 employees consume standardized subscription tiers with minimal configuration, prioritizing mobile invoice capture and automated bank feeds. The United States small business density sustains the largest addressable pool.
- Medium Enterprises:Organizations with 50-500 employees demand multi-entity consolidation, role-based permissions, and custom workflow automation. Sage Intacct and similar platforms target this segment with vertical-specific templates.
- Large Corporations:Complex intercompany reporting, audit-trail granularity, and SOX compliance requirements necessitate dedicated implementation teams and API ecosystem depth.
- Freelancers:Sole practitioners prioritize mileage tracking, quarterly tax estimation, and simplified 1099 preparation over full general ledger functionality.
Small Enterprises retain volume leadership; Medium Enterprises hold the steepest expansion curve.
Service Type:
Application maturity varies sharply, with consumption-based models displacing perpetual licenses only in specific workload patterns.
- Subscription-Based:Predictable monthly or annual fees bundle software access, automatic updates, and baseline support. This model dominates North American and Western European markets with established SaaS procurement cultures.
- Pay-Per-Use:Metered billing tied to transaction volume, active users, or API calls aligns costs with actual consumption. Seasonal businesses and project-based professional services firms in Australia and Canada favor this structure.
- One-Time Purchase:Perpetual licenses with optional maintenance contracts persist in regions with conservative capital expenditure approval processes and limited cloud infrastructure reliability.
- Managed Services:Fully outsourced bookkeeping, reconciliation, and compliance execution bundled with platform access. Certified accountant scarcity in the United Kingdom and United States expands this category fastest.
Subscription-Based retains volume leadership; Managed Services holds the steepest expansion curve.
Feature:
Customer type and geographic regulatory complexity determine which capability modules command premium pricing and development priority.
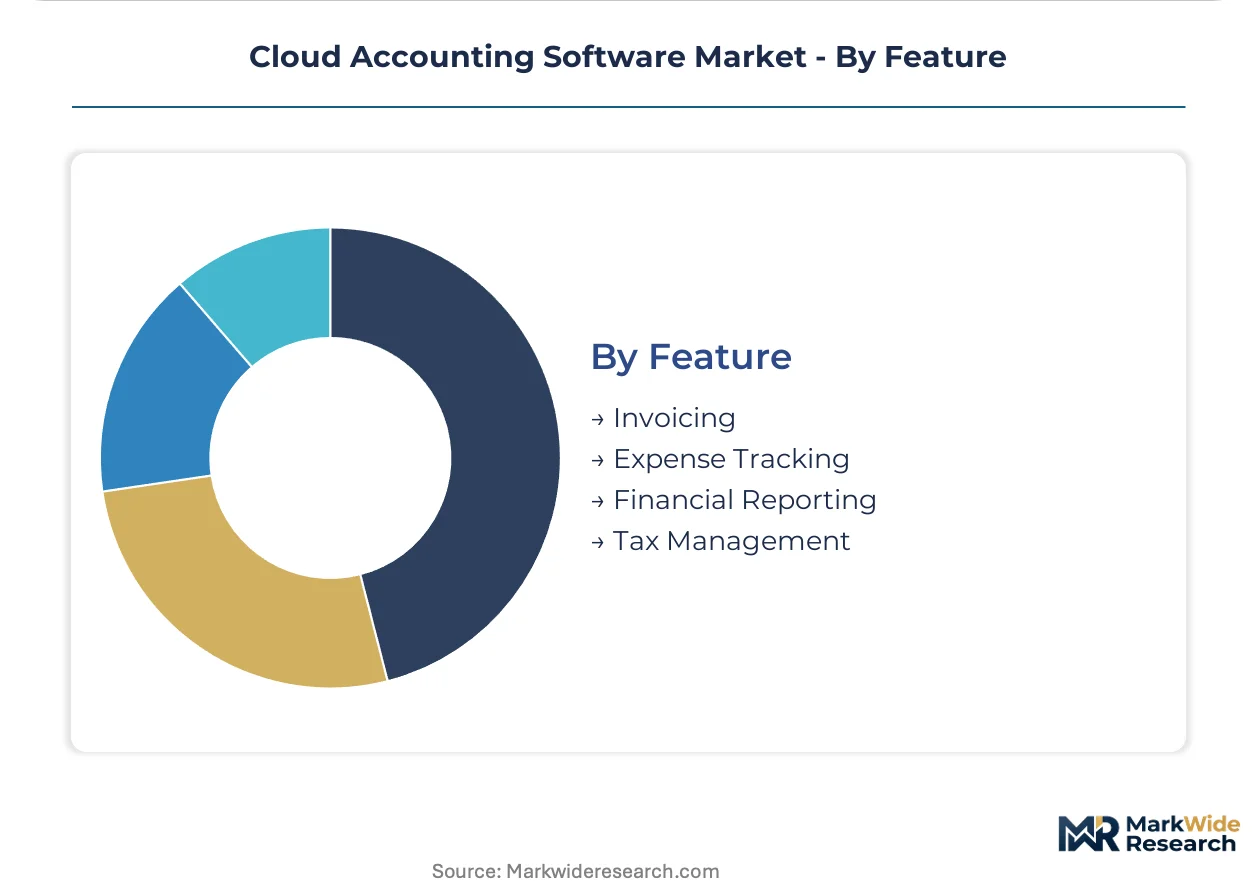
- Invoicing:Automated receivables workflows with multi-currency support, payment gateway integration, and dunning management. Freelancers and small enterprises across the United States and Australia adopt this as entry-point functionality.
- Expense Tracking:Receipt capture, mileage logging, and corporate card reconciliation with policy enforcement. Remote-work normalization drives replacement of manual spreadsheet processes in medium enterprises.
- Financial Reporting:Custom dashboard construction, consolidated P&L across entities, and board-ready presentation exports. Nonprofit and franchise verticals with complex fund accounting requirements anchor demand.
- Tax Management:Automated return preparation, jurisdiction-specific rate tables, and audit documentation aligned with GDPR, EU AI Act, and SEC disclosure rules. India's GST complexity creates specialized demand for automated multi-rate calculation engines.
Invoicing retains volume leadership; Tax Management holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SEC cybersecurity disclosure rules and the EU AI Act are reshaping vendor infrastructure investments across the United States and Europe. Remote-work normalization and API-first banking integrations are accelerating replacement cycles in English-speaking markets.
United States
Small and medium enterprises in Texas and California are driving demand for automated reconciliation and AI-assisted bookkeeping workflows. SEC disclosure requirements and HIPAA mandates for healthcare networks force audit-trail granularity that consumer-grade tools cannot satisfy. The ProAdvisor network model competes with direct API-first purchasing in New York and Chicago metro clusters.
United Kingdom
Certified accountant shortages across London and Manchester are compressing implementation timelines for mid-market firms. GDPR cross-border transfer restrictions and emerging FCA operational resilience guidance reshape data residency architectures. The Bristol and Edinburgh fintech corridors anchor demand for browser-native access controls among distributed finance teams.
Germany
Multi-entity consolidation tools dominate nonprofit and franchise verticals in Bavaria and North Rhine-Westphalia with complex intercompany reporting needs. National banking secrecy requirements and GDPR compliance compel single-tenant private cloud deployments. The Frankfurt financial services cluster demands granular audit trails unavailable to generalist platforms.
India
GST automation gaps in Maharashtra and Karnataka create white space for cloud-native vendors with automated multi-rate tax calculation engines. Monthly compliance filing requirements and RBI data localization norms force redundant infrastructure stacks. The Bangalore and Hyderabad SaaS corridors concentrate development talent for ledger-integrated environmental reporting.
Australia
Remote-work normalization across Sydney and Melbourne drives replacement of manual spreadsheet processes with expense tracking and corporate card reconciliation. Seasonal businesses in Queensland favor pay-per-use billing tied to transaction volume. The Australian Taxation Office's digital reporting mandates accelerate subscription unbundling among tech-savvy small enterprises.
Cloud Accounting Software Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes, creating a tiered market structure where feature depth competes with channel reach. The vendor base spans global SaaS incumbents, regional specialists, and vertical-focused platforms. Three archetypes dominate: API-first ecosystem builders, ProAdvisor-network channel players, and multi-entity consolidation specialists. M&A activity concentrates on embedded finance capabilities, while strategic partnerships with banking infrastructure providers reshape competitive positioning.
Within the ecosystem-builder tier, Xero and Zoho Books exemplify API-first architectures that unify banking, payroll, and tax preparation workflows. Sage Intacct occupies a position among multi-entity consolidation specialists serving complex nonprofit and franchise structures. These three anchors represent divergent bets on whether data network effects, channel density, or vertical depth will capture margin pools from mid-market replacement cycles.
| Leading Market Players |
|---|
| Sage Intacct |
| FreshBooks |
| QuickBooks Online |
| Maxio |
| Wave |
| Xero |
| Zoho Books |
| Pilot |
| NetSuite |
| Others |
Cost & Logistics Intelligence
GDPR certification tiers and EU AI Act compliance documentation now gate vendor qualification while simultaneously enabling price stratification across deployment architectures. Healthcare networks and financial services firms in Germany and Switzerland pay substantial premiums for single-tenant private cloud configurations that satisfy HIPAA and banking secrecy mandates, whereas small enterprises in the United States and United Kingdom absorb standardized public cloud rates with minimal configuration overhead.
Pricing Analysis
Geographic price spreads of forty to sixty percent separate North American SaaS tiers from European compliance-heavy deployments. Subscription-based service models dominate, with three-tier pricing structure across premium, standard, and economy levels differentiated by audit-trail granularity and data residency controls. Price differentiation hinges on certification grade and vertical integration depth. Pricing pressure stems from hyperscaler infrastructure commoditization at the compute layer. Freelancers and sole practitioners exhibit highest price sensitivity; healthcare networks and publicly traded corporations demonstrate lowest elasticity.
Supply Chain Analysis
Container availability constraints across Asia-Pacific trade lanes elevate inbound logistics costs for server hardware destined to European and Indian data centers. Cloud accounting software supply concentrates in the United States, Ireland, and Singapore, where hyperscaler regions anchor primary infrastructure. Raw material dependencies span semiconductor chips for server capacity, lithium-ion battery systems for backup power, and optical fiber for inter-region connectivity. Single-source vulnerability in GPU allocation for AI-assisted bookkeeping features poses structural risk. Distribution runs through direct vendor sales, channel partner networks, and embedded finance platform integrations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards defensive moats built on regulatory entrenchment rather than feature velocity alone. Switching costs compound as clients embed API connections across banking, payroll, and tax preparation workflows, creating exit friction that sustains incumbent pricing power.
For Market Incumbents: Consolidate API ecosystem depth by acquiring specialized tax engine providers in India and Brazil where GST complexity creates technical barriers. Deepen vertical integration into embedded finance infrastructure through strategic partnerships with Plaid and Stripe Treasury. Channel control represents the critical lever against API-first challengers targeting direct procurement. For New Entrants and Emerging Players: SOC 2 Type II fast-track certification unlocks mid-market healthcare and financial services segments where audit-ready systems command premium positioning. India's GST automation gap and Australia's carbon accounting convergence represent the most penetrable white spaces. Direct-to-accountant go-to-market motions bypass incumbent channel saturation. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across public cloud deployment sub-segments as hyperscaler economies of scale compress infrastructure costs. Long-term viability favors platforms with multi-entity consolidation capabilities and vertical-specific templates. Acquisition targets should demonstrate API ecosystem density and regional tax engine coverage. Watch for EU DORA implementation timelines as inflection indicator for compliance-related infrastructure spending.| Strategic Initiative | Industry Significance |
|---|---|
| API Ecosystem Expansion | Deep Plaid and Stripe Treasury integrations collapse reconciliation latency for small enterprises. |
| Vertical Tax Engine Acquisition | India GST specialists and Brazil Nota Fiscal engines address multi-jurisdiction complexity gaps. |
| HIPAA-Aligned Module Development | Healthcare audit-trail granularity commands pricing premiums unavailable to generalist platforms. |
| Carbon Accounting Convergence | CSRD-mandated Scope 3 reporting integrates environmental and financial data workflows. |
| Managed Services Bundling | Certified accountant scarcity in the United Kingdom expands outsourced bookkeeping attachment rates. |
Research Approach
Desk research of SEC filings, hyperscaler capex disclosures, and EU regulatory guidance documents preceded structured interviews with CTOs, finance transformation directors, channel partners, and integration specialists. Primary fieldwork captured deployment decision criteria and switching cost quantification across mid-market firms. Secondary validation drew from App Annie platform data, GPO procurement databases, and customs records of server hardware imports. Bottom-up subscription revenue modeling triangulated against top-down TAM estimates across deployment and end-user segments.
Variance decomposition across the analysis window isolates pricing, volume, and mix effects within segment-level CAGRs. The analytical framework models deployment architecture, organization size, vertical industry, integration complexity, and regional regulatory cluster as core segmentation dimensions. Growth trajectories derive from cohort retention analysis and API connection density metrics. Forecast inputs incorporate certified accountant pipeline constraints and EU AI Act compliance retrofit timelines.
Underlying assumptions cover remote-work normalization persistence, API-first banking integration adoption curves, and regulatory enforcement intensity, with deviation risk concentrated in data localization law proliferation and AI hallucination liability frameworks. Practitioners should keep alternative scenarios live as GDPR cross-border transfer rulings and SEC cybersecurity disclosure refinements evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Accounting and Taxation Services
Global Business Accounting Software Market
Accounting and Taxation Services
Accounting Software Market
Accounting and Taxation Services
Spain Forensic Accounting Market
Accounting and Taxation Services
Global Sales Tax Compliance Software Market
Accounting and Taxation Services
India Accounting Professional Services Market
Accounting and Taxation Services
Tax Software Market
Accounting and Taxation Services
Sales Tax Software Market
Accounting and Taxation Services
Integrated Accounting Software Market
Accounting and Taxation Services
Europe Auditing Services Market
Accounting and Taxation Services
Crypto Tax Software Market
Accounting and Taxation Services
United Kingdom Accounting Software Market
Accounting and Taxation Services
Bookkeeping Services Market
Accounting and Taxation Services
Global Artificial Intelligence for Accounting Market
Accounting and Taxation Services
India Forensic Accounting Market
Accounting and Taxation Services
Accounting and Budgeting Software Market
Accounting and Taxation Services
Hydrocarbons Accounting Solution Market