
 Europe Auditing Services Market | 2026-2036
Europe Auditing Services Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Auditing Services Market Foresight
Partnership networks between mid-tier firms and technology vendors is reconfiguring how audit capabilities reach national markets. BDO leverages its integrated European platform to deliver cross-border assurance to mid-cap manufacturers. Grant Thornton competes through sector-specialized teams in financial services and healthcare. Mazars anchors its growth in founder-led family enterprises across France and Italy.
Auditing services encompass independent examination and verification of financial statements, internal controls, and regulatory compliance, performed under International Standards on Auditing with risk-based sampling and substantive testing protocols. External audit engagements generate the largest fee pools due to statutory mandate density across EU member states, while forensic audit represents the fastest-expanding segment driven by anti-money laundering enforcement and fraud investigation demand from banking regulators. Hybrid delivery models now capture growing share as firms blend on-site inventory verification with remote data analytics and continuous monitoring tools.
The European Securities and Markets Authority coordinates audit oversight with national competent authorities in Germany, France, and Spain, while the EU Corporate Sustainability Reporting Directive mandates expanded assurance scope for listed entities. ECHA chemical reporting obligations and GDPR data governance requirements create parallel compliance audit demand from industrial clients. Stakeholders must weigh technology investment intensity against regulatory deadline density when allocating capital across service lines and geographies.
Market Dynamics
The EU Corporate Sustainability Reporting Directive is compressing audit timelines while expanding assurance scope, forcing firms to reconfigure staffing models and technology stacks simultaneously.
Growth Catalysts
- CSRD Mandate Expansion:The directive requires listed entities and large private companies to obtain limited assurance on sustainability disclosures, creating mandatory demand for integrated audit services across Germany, France, and the Netherlands.
- Anti-Money Laundering Enforcement:Banking regulators in Spain and Italy are intensifying forensic audit requirements for financial institutions, accelerating specialized investigation service growth.
- Cloud Analytics Platforms:Remote data analytics tools enable mid-market corporates to access continuous monitoring capabilities previously reserved for large-cap clients, democratizing assurance coverage.
Market Restraints
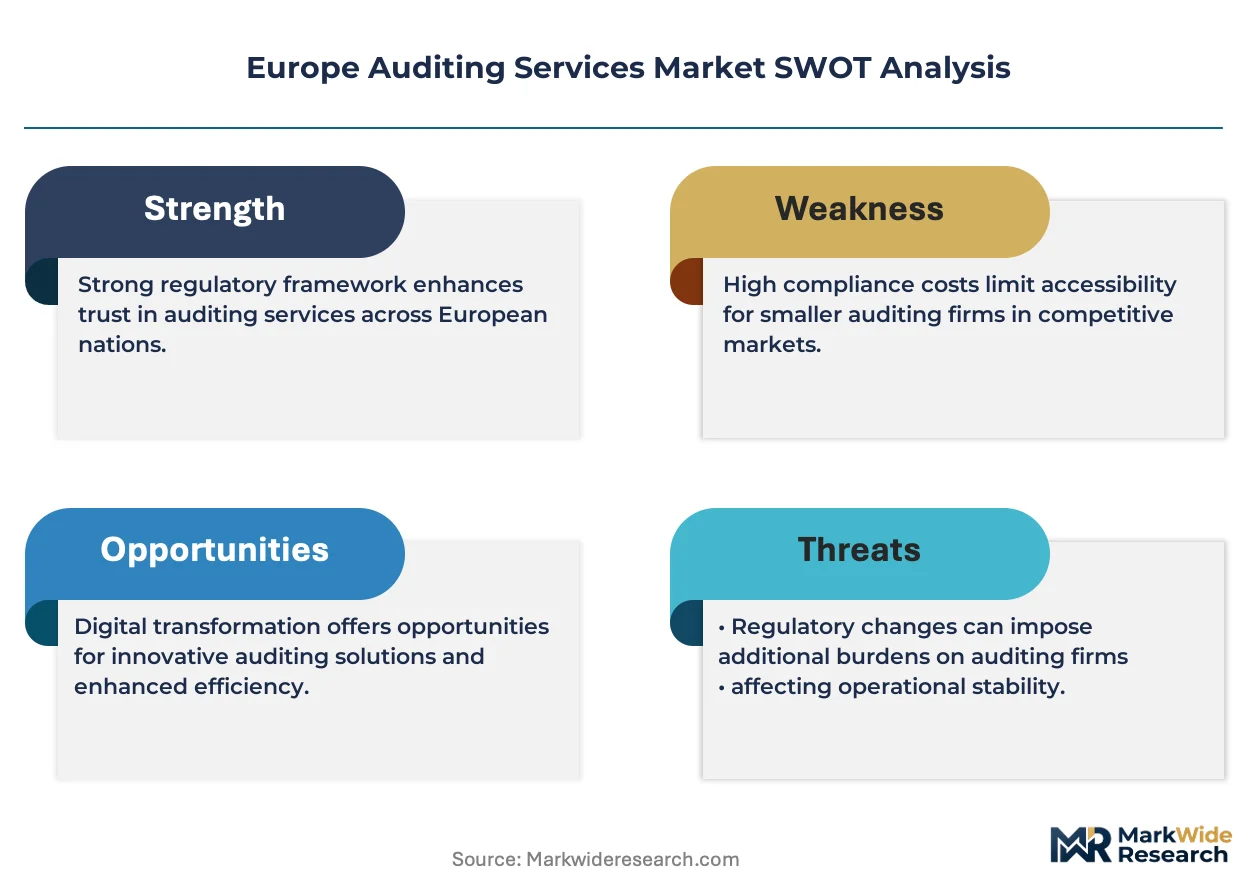
- Qualified Auditor Scarcity:The pipeline of professionals holding both statutory audit qualifications and sustainability expertise remains constrained across Southern Europe, inflating labor costs.
- Regulatory Fragmentation:National competent authorities in Germany, France, and Spain maintain divergent interpretations of International Standards on Auditing, complicating cross-border engagement execution.
- Technology Investment Burden:Continuous monitoring infrastructure requires substantial capital deployment before fee realization, straining mid-tier firm balance sheets.
Strategic Opportunities
- Eastern European Expansion:Poland and Romania exhibit underpenetrated mid-market segments where founder-led enterprises are approaching statutory audit thresholds.
- Cybersecurity Assurance Convergence:The EU AI Act and GDPR create overlapping compliance requirements that audit firms can bundle into unified service offerings.
- Remote Delivery Standardization:Hybrid models combining on-site inventory verification with cloud-based analytics enable geographic arbitrage in talent deployment.
Industry Challenges
- Data Engineering Talent Gap:Firms struggle to recruit professionals capable of configuring continuous monitoring algorithms and interpreting unstructured regulatory data.
- Legacy System Integration:Client enterprise resource planning platforms often lack API connectivity with modern audit analytics tools, requiring manual data extraction protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Auditing Services Market |
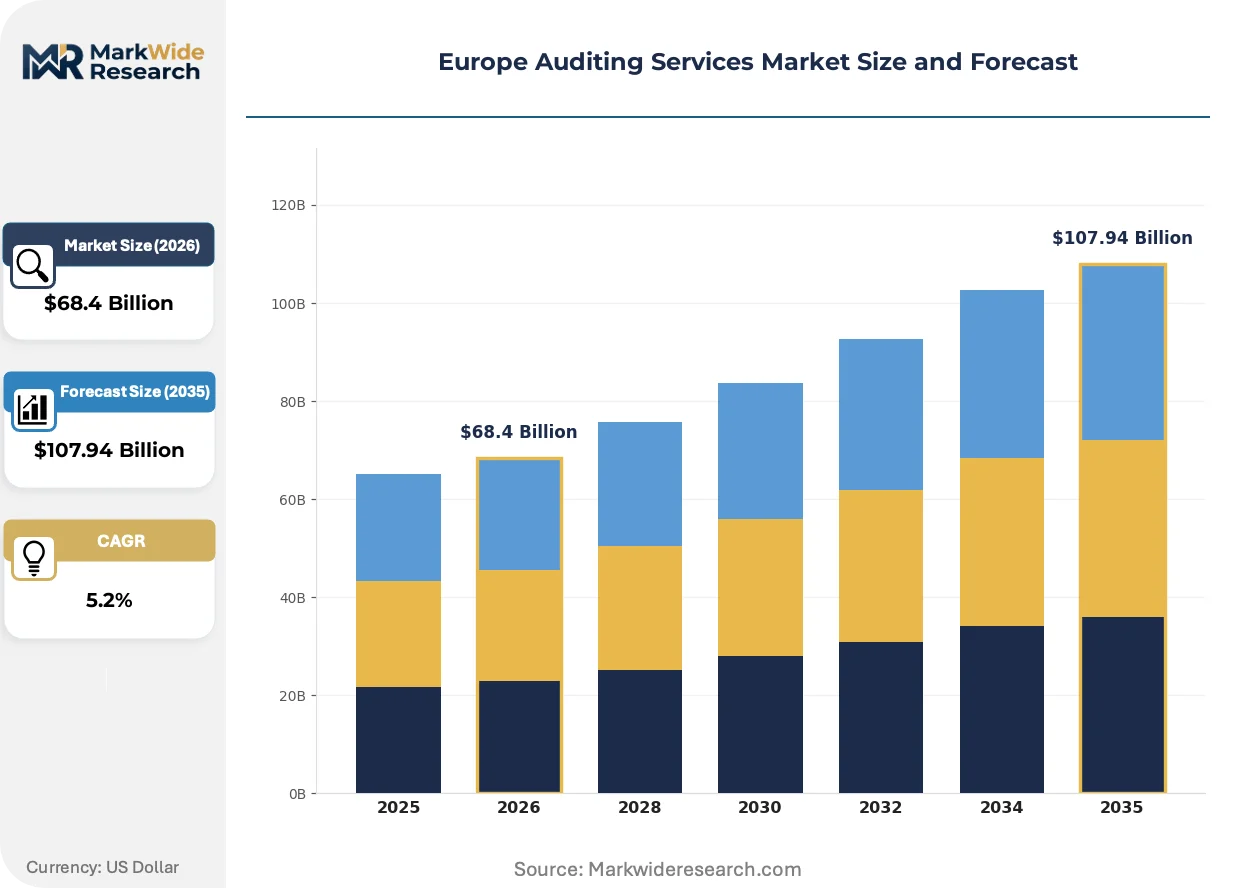
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $107.94 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Internal Audit, External Audit, Forensic Audit, Tax Audit Industry Vertical: Financial Services, Healthcare, Manufacturing, Retail Delivery Model: On-site, Remote, Hybrid, Outsourced Client Type: Corporates, SMEs, Public Sector, Non-profit |
| Companies Covered | KPMG, BDO, Deloitte, Mazars, RSM International, PwC, Grant Thornton, Baker Tilly International, EY, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Auditing Services Market Shifts & Advancements
Audit delivery models are fragmenting across technology-enabled specialization, with firms competing through differentiated data infrastructure rather than traditional relationship networks alone.
Continuous monitoring platforms are migrating from periodic sampling to full-population transaction analysis. Mid-cap manufacturers in the Netherlands and Belgium are adopting these tools for inventory and revenue verification. This compression of testing scope is enabling smaller engagement teams to cover larger client portfolios without quality degradation.
The EU Green Deal and CSRD are mandating double materiality assessments that extend audit scope beyond financial statements to environmental impact verification. Industrial clients in chemicals and energy face the steepest compliance burden. German and French firms are responding by recruiting environmental scientists into assurance teams.
Subscription-based assurance contracts are displacing traditional annual engagement structures for internal audit functions. Financial services institutions in London and Zurich are piloting these arrangements. This shift is most visible among banking and insurance verticals seeking integrated risk coverage across financial, operational, and regulatory domains.
Europe Auditing Services Market Segmentation
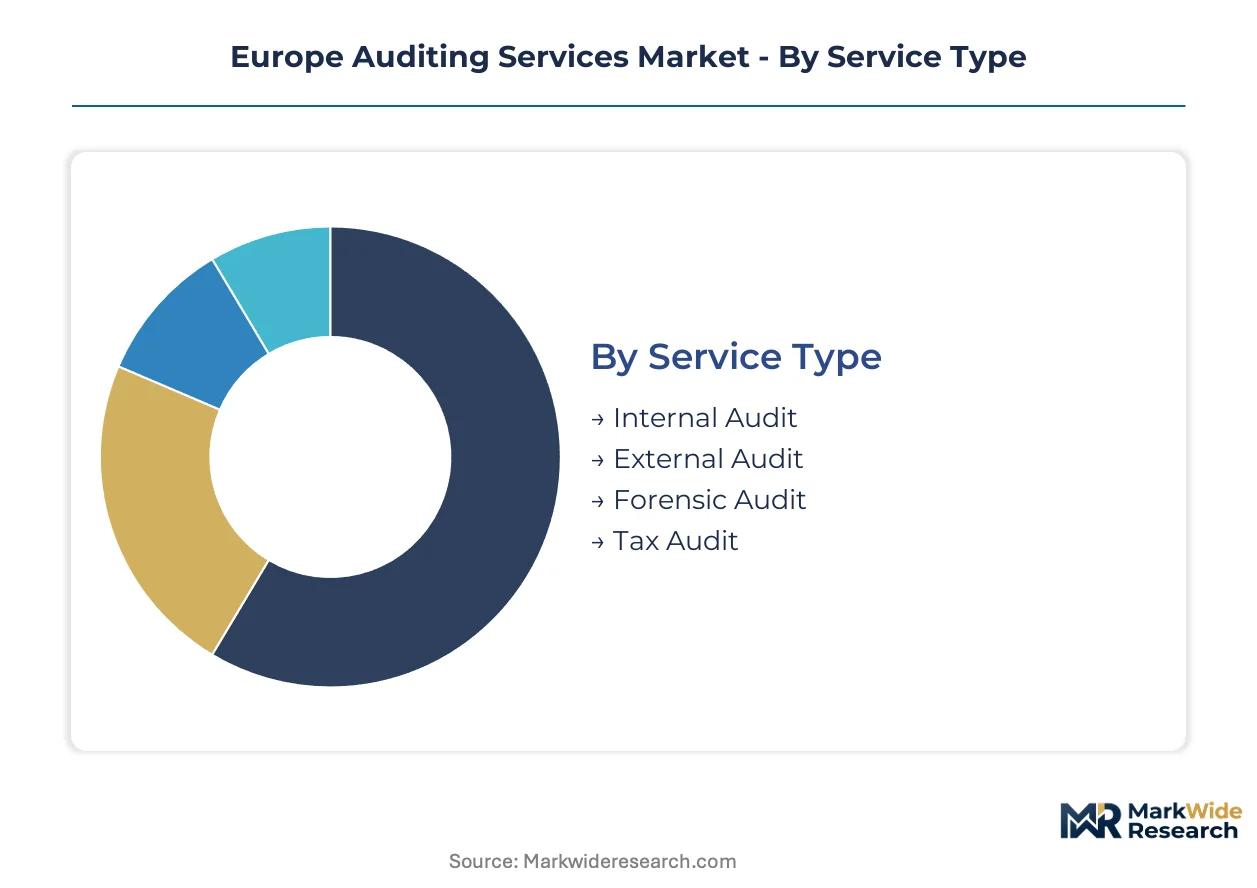
Service configuration in the European auditing market determines fee realization cycles and technology deployment intensity. Segmentation reveals where statutory mandates create recurring revenue pools versus where discretionary spending drives competitive differentiation.
Service Type:
External audit engagements operate on fixed annual cycles tied to fiscal year-ends, while forensic investigations compress delivery windows to weeks under regulatory enforcement pressure.
- Internal Audit:Continuous monitoring capabilities embedded within client risk management frameworks. Demand concentrates among Dutch and Belgian mid-cap manufacturers seeking operational assurance beyond financial compliance.
- External Audit:Statutory examination of financial statements under International Standards on Auditing with risk-based sampling protocols. German and French listed entities drive the largest fee pools through mandatory rotation requirements and expanded CSRD assurance scope.
- Forensic Audit:Fraud investigation and anti-money laundering compliance verification. Spanish and Italian banking regulators are accelerating specialized investigation demand following enforcement actions.
- Tax Audit:Revenue authority compliance verification and transfer pricing documentation. Cross-border engagements between Germany and the Netherlands dominate complexity-adjusted pricing tiers.
External audit dominates installed base. Forensic audit is where expansion concentrates.
Industry Vertical:
Financial services clients absorb the highest per-engagement technology costs while manufacturing verticals prioritize standardized, repeatable protocols.
- Financial Services:Integrated assurance across prudential regulation, AML compliance, and sustainability disclosure. German universal banks and French asset managers are consolidating vendor relationships to reduce fragmentation.
- Healthcare:Clinical trial documentation verification and pharmaceutical serialization compliance. EMA regulatory deadlines in Belgium and the Netherlands drive seasonal capacity constraints.
- Manufacturing:Inventory verification and supply chain sustainability attestation. Founder-led enterprises in France and Italy anchor mid-tier firm growth strategies.
- Retail:Revenue recognition testing and omnichannel inventory reconciliation. Seasonal peak demands compress delivery timelines for pre-holiday assurance.
Financial services commands premium pricing tiers. Manufacturing offers volume scalability through standardized methodologies.
Delivery Model:
Capital intensity varies threefold between on-site inventory verification requiring travel logistics versus remote analytics platforms with fixed infrastructure costs.
- On-site:Physical presence for inventory counts, asset verification, and management interviews. German industrial clients maintain requirements for warehouse verification despite remote tool availability.
- Remote:Cloud-based data analytics and continuous monitoring without physical presence. Mid-market corporates in the Netherlands are adopting these tools fastest for cost efficiency.
- Hybrid:Blended execution combining targeted site visits with remote analytics coverage. This configuration is gaining share as the default for mid-cap engagements across Belgium and Switzerland.
- Outsourced:Fully managed internal audit functions under subscription contracts. London and Zurich financial institutions are piloting these arrangements for integrated risk coverage.
Hybrid delivery captures emerging demand. Outsourced models are climbing the fastest among banking and insurance verticals.
Client Type:
Procurement sophistication diverges sharply between listed corporates with dedicated audit committees and founder-led SMEs purchasing assurance reactively.
- Corporates:Listed entities with mandatory rotation requirements and CSRD sustainability assurance obligations. German and French large-caps are consolidating multi-country engagements with integrated European platforms.
- SMEs:Founder-led enterprises approaching statutory thresholds or seeking bank financing support. Poland and Romania exhibit underpenetrated segments where mid-tier firms are building presence.
- Public Sector:Government agency and state-owned enterprise audits under national public procurement rules. Spanish and Italian regional governments maintain fragmented vendor bases.
- Non-profit:Charitable organization compliance and donor accountability verification. GDPR data governance requirements create parallel compliance demand from institutional funders.
Corporates anchor fee concentration. SMEs represent the steepest expansion trajectory as statutory thresholds expand across Eastern Europe.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German and French statutory audit markets where mandatory rotation and CSRD assurance scope inflate fee tiers, while Southern European markets trade at structural discounts amid fragmented vendor competition and slower regulatory enforcement timelines.
Germany
Universal banks and industrial conglomerates drive integrated assurance demand across prudential regulation, AML compliance, and sustainability disclosure. BaFin enforcement actions on anti-money laundering controls intensify forensic audit procurement from Frankfurt and Munich financial centers. The KBA automotive regulator's supply chain due diligence requirements extend audit scope into tier-n supplier networks across Baden-Württemberg and Bavaria.
France
Asset managers and listed luxury houses anchor premium-tier external audit fees through consolidated multi-country engagements. The AMF securities regulator coordinates with ESMA on audit quality inspections for Paris-based systemic institutions. Founder-led family enterprises in Lyon and Marseille manufacturing clusters generate mid-tier firm volume as statutory thresholds expand to private companies under CSRD phase-in schedules.
Netherlands
Mid-cap manufacturers adopt cloud-based remote delivery models fastest for inventory verification and revenue assurance. The AFM competent authority enforces strict auditor independence rules for Amsterdam-listed entities with complex cross-border structures. Eindhoven's high-tech systems sector concentrates demand for continuous monitoring tools embedded within operational risk frameworks.
Spain
Banking regulators accelerate specialized forensic investigation demand following enforcement actions on AML compliance failures. The CNMV securities supervisor mandates expanded sustainability assurance for IBEX-35 constituents ahead of full CSRD implementation. Barcelona and Madrid financial services clusters consolidate vendor relationships to reduce assurance fragmentation across prudential and regulatory domains.
Poland
Founder-led enterprises approaching statutory audit thresholds create underpenetrated expansion opportunities for mid-tier networks. The KNF financial supervision authority aligns Polish audit standards with EU directives ahead of full CSRD adoption. Warsaw and Krakow manufacturing hubs exhibit procurement sophistication gaps that favor standardized, repeatable assurance methodologies over bespoke advisory bundles.
Europe Auditing Services Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in niche assurance segments. The European auditing market structures around three concentration layers: global networks capturing listed corporate mandates, mid-tier firms competing on sector specialization, and national boutiques serving founder-led SMEs. Strategic differentiation runs through integrated European delivery platforms, sustainability credential stacking, and hybrid remote-on-site capability deployment. Consolidation pressure intensifies as CSRD timelines compress and technology investment thresholds exclude sub-scale operators.
Among the integrated global networks, Deloitte, PwC, and EY occupy positions defined by statutory rotation mandates and cross-border coordination infrastructure. These firms anchor the premium tier through multi-country engagement consolidation and CSRD assurance scope expansion. BDO and Grant Thornton exemplify mid-tier competitive positioning, leveraging sector-specialized teams and technology vendor partnerships to capture founder-led enterprise demand across national markets without global network overhead.
| Leading Market Players |
|---|
| KPMG |
| BDO |
| Deloitte |
| Mazars |
| RSM International |
| PwC |
| Grant Thornton |
| Baker Tilly International |
| EY |
| Others |
Supply & Pricing Matrix
The Rhine-Alpine freight corridor's cost dynamics amplify pricing power concentration among integrated audit platforms while compressing margins for national boutiques dependent on fragmented logistics networks. German and French statutory mandates inflate fee tiers at corridor termini, whereas Polish and Romanian practitioners absorb higher input costs without corresponding price realization.
Pricing Analysis
The customization-premium spread separates configured assurance bundles from standardized compliance packages. External audit engagements for listed German corporates command premium tiers driven by mandatory rotation requirements and CSRD sustainability scope expansion, while founder-led SMEs in Eastern Europe purchase reactive, price-sensitive assurance. Price differentiation hinges on auditor qualification density and cross-border coordination infrastructure. Cost compression in mid-market forensic services is intensifying because banking regulators in Spain and Italy are accelerating specialized investigation mandates without proportional fee adjustment mechanisms.
Supply Chain Analysis
Export-control regimes limiting flows of continuous monitoring algorithms and data analytics platforms constrain technology transfer to mid-tier networks. Supply concentration rests on Germany, the Netherlands, and Poland as primary capability hubs, with founder-led enterprises in Romania and Bulgaria sourcing assurance through subcontracted arrangements. Raw material dependencies include qualified auditor pipelines, cloud infrastructure subscriptions, and regulatory data feeds. Single-source vulnerability concentrates in sustainability credential stacking where environmental scientists are recruited into assurance teams. Distribution runs through partnership networks between mid-tier firms and technology vendors rather than direct client relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where interoperability between audit analytics tools and client ERP systems determines competitive viability. The CSRD mandate expansion is forcing ecosystem consolidation around integrated European delivery platforms.
For Market Incumbents: Entrench cross-border coordination infrastructure through sector-specialized team investments in financial services and healthcare verticals. Deepen sustainability credential stacking by recruiting environmental scientists into assurance teams before qualified talent scarcity inflates labor costs further. Defend against mid-tier firm technology partnerships by accelerating proprietary continuous monitoring platform deployment. For New Entrants and Emerging Players: Build out standardized, repeatable methodologies for founder-led SMEs approaching statutory thresholds in Poland and Romania. White-space concentration sits in cybersecurity assurance convergence where EU AI Act and GDPR compliance requirements overlap. Target subscription-based internal audit contracts among banking and insurance verticals in Zurich and London piloting integrated risk coverage arrangements. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors mid-tier networks with hybrid remote-on-site capabilities and sector-specialized teams over global network overhead structures. Acquisition archetypes should prioritize firms with embedded continuous monitoring infrastructure and cross-border European platform integration. The signal to watch is CSRD implementation velocity across German and French phase-in schedules as inflection indicator for integrated assurance demand scaling.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | CSRD mandate expansion forces interoperability between audit analytics and client ERP systems. |
| Acquisition of Specialist Firm | Environmental science recruitment into assurance teams addresses sustainability credential gaps. |
| Geographic Expansion | Founder-led SME penetration in Poland and Romania captures statutory threshold expansion. |
| Strategic Partnership | Technology vendor alliances enable mid-tier firms to deploy continuous monitoring without capital burden. |
| Product Launch | Subscription-based internal audit contracts displace annual engagement structures in financial services. |
Research Methodology
Cross-validation between primary fieldwork with audit firm partners and secondary validation through regulatory filings anchors the qualitative findings. Conversations with statutory audit partners, technology vendor account executives, banking regulator enforcement leads, and CFOs at mid-cap manufacturers informed demand-side dynamics. Secondary sources include AFM and BaFin enforcement disclosures, ESMA audit quality inspection reports, EU Corporate Sustainability Reporting Directive implementation guidance, and customs data on cross-border service flows. Bottom-up engagement fee analysis and top-down regulatory mandate sizing were triangulated.
Calibration against historical CSRD adoption curves and AML enforcement intensity patterns shaped the projection framework. Segmentation dimensions modeled include service type, delivery model, client size tier, and industry vertical across the analysis window. CAGRs were derived from mandate expansion velocity and technology adoption diffusion rates. Forecast inputs incorporated qualified auditor pipeline constraints and cloud infrastructure cost trajectories.
Stress conditions across regulatory deadline density, technology investment thresholds, and labor cost inflation were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on CSRD phase-in schedules and banking regulator enforcement continuity. Material shifts in EU sustainability assurance scope interpretation or qualified auditor supply would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Accounting and Taxation Services
Global Sales Tax Compliance Software Market
Accounting and Taxation Services
Corporate Tax Service Market
Accounting and Taxation Services
Accounting Software Market
Accounting and Taxation Services
Global Artificial Intelligence for Accounting Market
Accounting and Taxation Services
US Auditing Services Market
Accounting and Taxation Services
Hydrocarbons Accounting Solution Market
Accounting and Taxation Services
Germany Accounting Software Market
Accounting and Taxation Services
Small Business Accounting Software Market
Accounting and Taxation Services
Cloud Accounting Software Market
Accounting and Taxation Services
Bookkeeper Software Market
Accounting and Taxation Services
France Accounting Software Market
Accounting and Taxation Services
South Africa Forensic Accounting Market
Accounting and Taxation Services
Japan Accounting Software Market
Accounting and Taxation Services
China Accounting Software Market
Accounting and Taxation Services
India Accounting Software Market
Accounting and Taxation Services
US Accounting Software Market