
 Australia Accounting Software Market | 2026-2036
Australia Accounting Software Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Accounting Software Market Insights
Professional services adoption is decoupling from traditional desktop licensing as compliance automation becomes non-negotiable. Xero leverages cloud-native architecture to anchor subscription retention among Australian SMEs. MYOB sustains hybrid deployment flexibility for firms navigating legacy transitions. Intuit QuickBooks differentiates through freelancer-centric workflow tools that reduce onboarding friction.
Australia accounting software comprises digital platforms that automate ledger management, payroll calculation, tax compliance, and financial reporting through configurable rule engines and API-connected banking feeds. Cloud-based deployment leads segment growth as multi-tenant architectures reduce per-seat infrastructure costs for Australian providers. Subscription-based service models now dominate revenue capture, while tax management solutions attract premium pricing due to ATO reporting complexity. On-premise installations persist in sectors with stringent data residency requirements, though hybrid configurations are displacing pure local deployments.
The Australian Taxation Office mandates Single Touch Payroll compliance, while the Australian Securities and Investments Commission governs financial record retention standards, and the Australian Prudential Regulation Authority shapes audit-readiness expectations for regulated entities. These frameworks compel vendors to embed real-time reporting capabilities directly into core product architecture. Stakeholders must evaluate whether modular API ecosystems or vertically integrated suites better address evolving interoperability demands from Australian regulators and enterprise buyers.
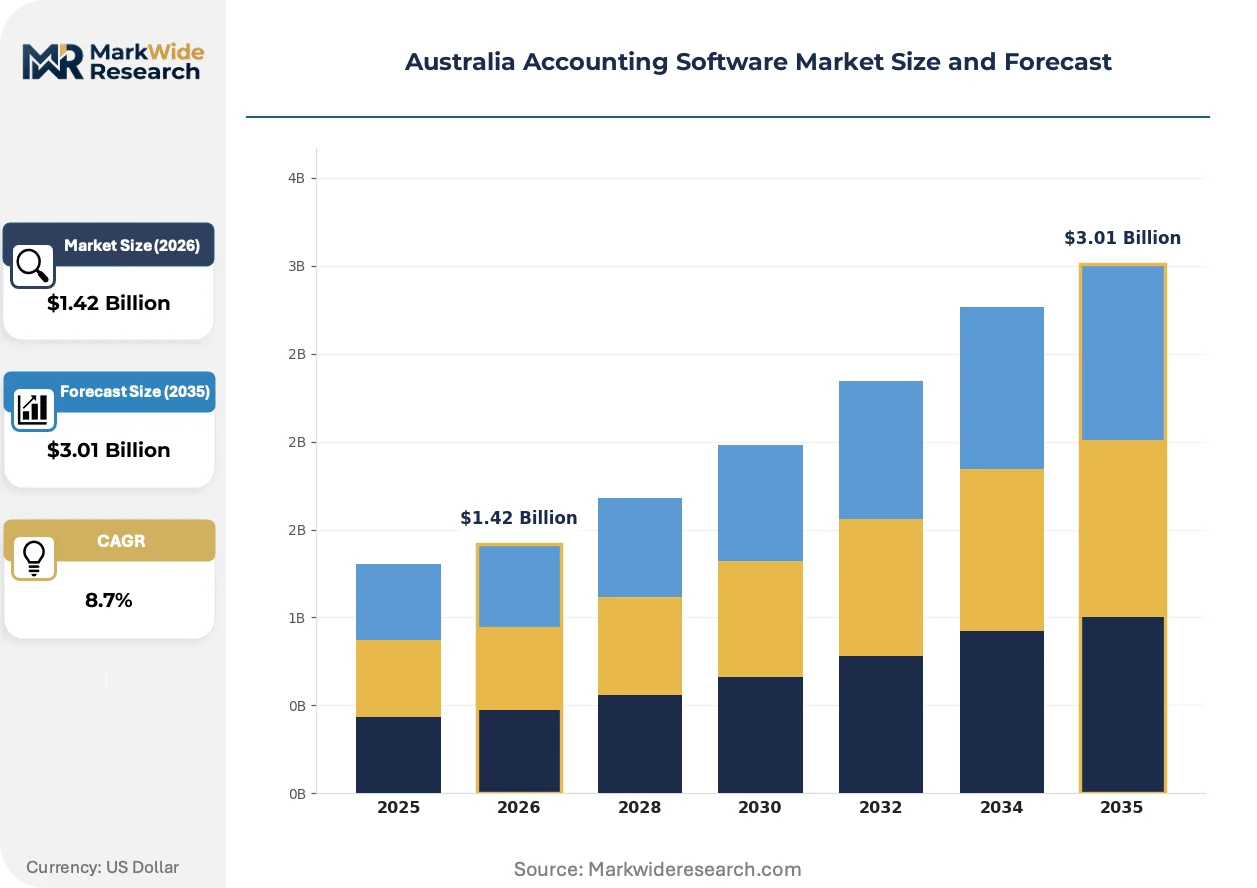
Market Dynamics
The Australian Taxation Office's Single Touch Payroll Phase 2 mandate is compressing software upgrade cycles across professional services firms, forcing vendors to embed real-time compliance engines directly into cloud-native architectures.
Growth Catalysts
- ATO Reporting Mandates:Single Touch Payroll Phase 2 requires automated real-time wage and superannuation reporting, compelling mid-sized firms to abandon manual processes.
- API-Connected Banking Feeds:Open banking protocols enable direct transaction ingestion, reducing reconciliation labor for New South Wales accounting practices.
- Professional Services Density:Victoria's concentration of financial services firms creates concentrated demand for scalable multi-tenant deployment models.
Market Restraints
- Data Residency Requirements:Defense contractors and government suppliers in Canberra maintain on-premise installations despite higher total cost of ownership.
- Legacy System Entrenchment:Established practices in Queensland retain desktop licenses due to sunk costs in customized chart-of-accounts configurations.
- Skills Fragmentation:Regional Tasmania faces acute shortages of cloud migration specialists capable of managing hybrid transition architectures.
Strategic Opportunities
- Western Australia Expansion:Perth's mining sector professional services remain underpenetrated by automated compliance tools relative to eastern states.
- Freelancer Workflow Integration:Gig economy tax complexity creates demand for simplified BAS lodgment tools targeting sole traders in South Australia.
- ASIC Audit-Readiness Modules:Enhanced financial record retention capabilities address Australian Securities and Investments Commission expectations for regulated entities.
Industry Challenges
- Interoperability Complexity:Hybrid deployments require seamless data synchronization between legacy on-premise servers and cloud instances.
- Compliance Velocity:Australian Prudential Regulation Authority audit standards evolve faster than vendor release cycles can accommodate.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Accounting Software Market |
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $3.01 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-based, On-premise, Hybrid, Multi-tenant End User: Small Businesses, Large Enterprises, Freelancers, Non-profits Solution: Invoicing, Payroll, Expense Tracking, Tax Management Service Type: Software Licensing, Subscription-based, Custom Solutions, Consulting |
| Companies Covered | Xero, MYOB, Intuit QuickBooks, Microsoft Dynamics 365 Business Central, Oracle NetSuite, SAP, Sage Intacct, Tencia, Odoo, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Accounting Software Market Trends and Innovations
Cloud-native architectures are converging with embedded compliance automation to reshape how Australian professional services firms manage financial workflows. This convergence is eliminating the traditional separation between transactional accounting and regulatory reporting functions.
Machine learning-powered anomaly detection is converging with natural language processing to automate expense categorization from unstructured receipts. Mid-tier firms in Sydney and Melbourne are adopting these tools at accelerated rates to reduce manual data entry. The technology is converging with mobile capture interfaces to compress monthly close cycles from weeks to days.
The Australian Taxation Office's real-time reporting protocols are mandating continuous disclosure rather than periodic submission. This regulatory architecture forces vendors to rebuild core ledgers around event-stream processing rather than batch updates. Small and mid-sized enterprises in Victoria face the steepest adaptation curve as they transition from quarterly to pay-cycle reporting.
Subscription unbundling is fragmenting the traditional suite model into modular API-accessible components. Freelancers and micro-practices in Brisbane and Adelaide are selecting point solutions for specific functions rather than purchasing comprehensive platforms. Western Australia's dispersed geography amplifies this pattern as remote practitioners prioritize lightweight, mobile-first tools over feature-heavy enterprise editions.
Australia Accounting Software Market Segmentation
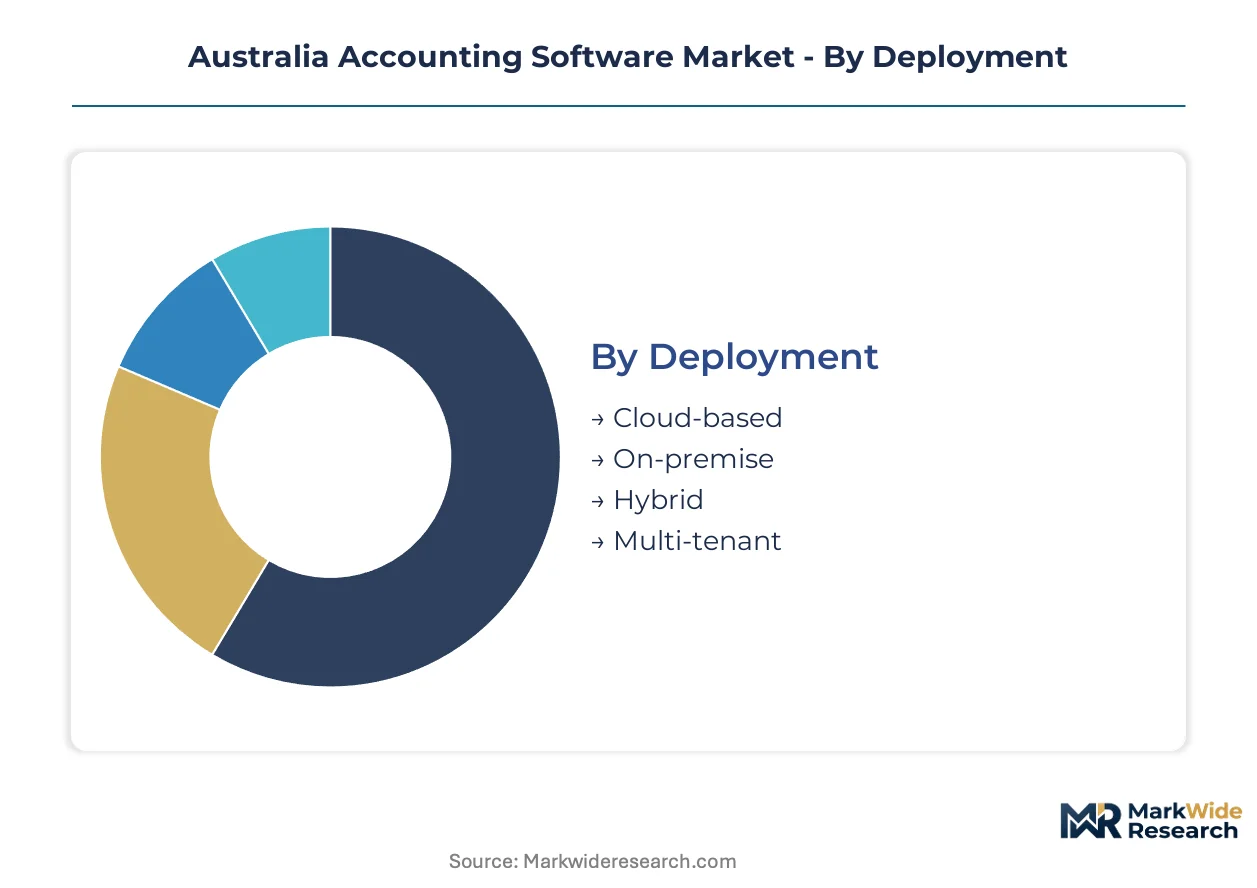
Australian accounting software segmentation reflects divergent compliance burdens across deployment modes and user profiles. ATO Single Touch Payroll Phase 2 mandates reshape which segments command premium positioning versus commoditized alternatives.
Deployment:
ATO compliance certification requirements vary sharply across deployment architectures, with real-time reporting mandates favoring cloud-native validation pathways over legacy on-premise audit trails.
- Cloud-based:Multi-tenant SaaS architectures enable automatic ATO protocol updates without client-side intervention. New South Wales professional services firms concentrate demand here due to STP Phase 2 deadline pressure and API-connected banking feed integration.
- On-premise:Local server installations persist where data residency requirements override cloud migration economics. Canberra defense contractors and government suppliers maintain these deployments despite higher total cost of ownership and manual compliance update cycles.
- Hybrid:Split configurations synchronize legacy ledger data with cloud compliance modules. Queensland accounting practices with sunk costs in customized chart-of-accounts use this architecture to phase migration.
- Multi-tenant:Shared infrastructure models reduce per-seat costs for mid-tier Victorian firms managing multiple client entities under single administrative dashboards.
Leading the category by volume: Cloud-based. Expanding most quickly: Hybrid configurations bridging legacy transition gaps.
End User:
User type determines feature complexity requirements and pricing tolerance, with compliance automation needs scaling inversely with organizational accounting sophistication.
- Small Businesses:SME operators require streamlined BAS lodgment workflows and automated superannuation calculations. Victoria and New South Wales show concentrated uptake as ATO penalties for non-compliance stiffen.
- Large Enterprises:ASIC audit-readiness modules and multi-entity consolidation capabilities dominate procurement criteria. Financial services density in Sydney drives sophisticated deployment.
- Freelancers:Sole traders prioritize mobile-first invoice generation and simplified expense capture. South Australia's gig economy participants generate disproportionate demand for lightweight tools.
- Non-profits:Grant reporting compliance and restricted fund tracking shape specialized requirements distinct from commercial accounting workflows.
Highest revenue per seat: Large Enterprises. Steepest expansion trajectory: Freelancers as independent contractor classification spreads.
Solution:
Functional module selection correlates with regulatory touchpoint frequency, where payroll and tax management face the most intensive ATO oversight.
- Invoicing:Automated accounts receivable with ATO-compliant GST calculation and e-invoice PEPPOL integration. Freelancers and micro-practices in Brisbane select standalone modules over comprehensive suites.
- Payroll:STP Phase 2 real-time wage and superannuation reporting represents the most compliance-critical function. Victorian mid-sized firms face steepest adaptation curves migrating from quarterly to pay-cycle disclosure.
- Expense Tracking:Machine learning-powered receipt categorization compresses monthly close cycles. Sydney and Melbourne mid-tier practices adopt these tools at accelerated rates.
- Tax Management:Embedded ATO lodgment gateways and audit trail preservation command premium pricing due to regulatory complexity and penalty exposure.
Widest penetration: Invoicing. Gaining share fastest: Tax Management as real-time reporting protocols harden.
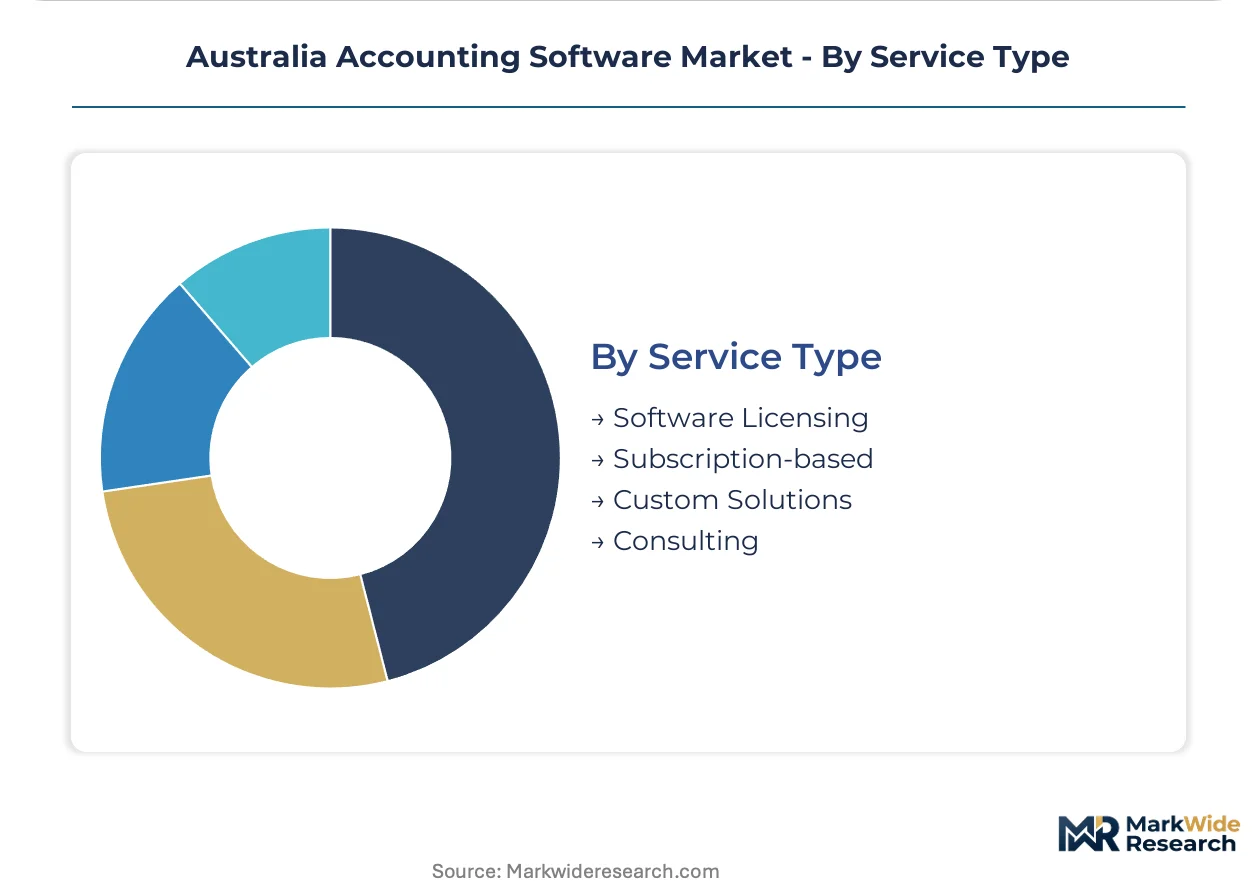
Service Type:
Commercial model selection reflects customer technical maturity and customization requirements, with subscription architectures displacing perpetual licenses across all user tiers.
- Software Licensing:Perpetual desktop licenses persist in Queensland and Tasmania where legacy system entrenchment and skills fragmentation delay cloud migration.
- Subscription-based:Recurring revenue models dominate new customer acquisition, with automatic feature updates ensuring continuous ATO compliance. Cloud-native vendors anchor retention through this architecture.
- Custom Solutions:Bespoke configurations serve specialized industry verticals with non-standard chart-of-accounts or multi-currency consolidation requirements.
- Consulting:Migration advisory and compliance setup services address acute cloud specialist shortages in regional Tasmania and Western Australia.
Dominant revenue capture: Subscription-based. Climbing the fastest: Consulting as hybrid transition complexity intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Software production concentrates in Sydney and Melbourne, while consumption spreads across state capitals and regional professional services clusters. New South Wales and Victoria generate disproportionate demand relative to their population share.
New South Wales
Financial services density in Sydney drives concentrated demand for multi-tenant cloud architectures. The Australian Taxation Office's Single Touch Payroll Phase 2 mandate compresses upgrade cycles for mid-sized practices. Parramatta and North Sydney host dense clusters of accounting firms migrating from desktop licenses to API-connected banking feed solutions.
Victoria
Melbourne's professional services corridor generates the steepest adoption curves for real-time reporting compliance tools. The Australian Securities and Investments Commission's audit-readiness expectations shape procurement criteria for large enterprises. Geelong and regional Victorian practices face acute skills shortages in hybrid cloud migration.
Queensland
Brisbane's mid-tier firms retain legacy desktop installations due to sunk costs in customized chart-of-accounts configurations. The Australian Prudential Regulation Authority shapes compliance expectations for regulated financial entities. Gold Coast sole traders disproportionately select lightweight mobile-first invoicing modules over comprehensive suites.
Western Australia
Perth's mining sector professional services remain underpenetrated by automated compliance tools relative to eastern states. Data residency requirements for defense contractors in Canberra-influenced supply chains sustain on-premise installations. Regional Western Australia faces consulting service gaps for cloud transition advisory.
South Australia
Adelaide's gig economy participants generate disproportionate demand for simplified BAS lodgment tools targeting freelancers. The Australian Taxation Office's real-time reporting protocols force sole traders toward subscription-based service models. South Australia's dispersed geography amplifies preference for mobile-first expense capture interfaces.
Australia Accounting Software Market Competitive Landscape
Top-tier vendors anchor the cloud-native segment, while hybrid deployment specialists and legacy desktop incumbents occupy distinct competitive tiers. The market structure reflects a consolidation pattern around three strategic archetypes: cloud-first SaaS platforms, hybrid flexibility providers, and enterprise suite vendors. Dominant competitive moves include vertical integration into adjacent payroll and tax management modules, plus geographic expansion into underpenetrated Western Australian mining professional services.
Within the cloud-native tier, Xero and MYOB exemplify divergent strategic positioning—Xero representing pure multi-tenant SaaS architecture while MYOB occupies the hybrid transition space. Intuit QuickBooks anchors the freelancer-centric workflow specialization. These three vendors collectively represent the competitive tension between compliance automation depth and user experience simplicity that defines Australian accounting software procurement.
| Leading Market Players |
|---|
| Xero |
| MYOB |
| Intuit QuickBooks |
| Microsoft Dynamics 365 Business Central |
| Oracle NetSuite |
| SAP |
| Sage Intacct |
| Tencia |
| Odoo |
| Others |
Pricing and Supply Chain Analysis
Cloud infrastructure costs cascade through Australian accounting software pricing tiers, with Sydney-based data center capacity feeding subscription rates for New South Wales professional services firms while API licensing fees from banking feed providers compress margins at the freelancer tier.
Pricing Analysis
Margin tightening in the freelancer segment reflects API-connected banking feed licensing costs passed through from upstream financial data aggregators. Three-tier pricing structure across premium, standard, and economy levels segments by compliance automation depth, with ATO-certified STP Phase 2 modules commanding premium positioning. Cost-down pressure on mid-tier subscriptions accelerates because Victorian firms demand real-time reporting without proportional price tolerance. Freelancers show highest price sensitivity, while ASIC-regulated enterprises accept premium tiers for audit-readiness modules.
Supply Chain Analysis
Dual-sourcing requirements from Australian financial institutions mandate multi-cloud qualification, forcing vendors to maintain parallel infrastructure relationships with domestic and hyperscale providers. Software development concentrates in Australia, India, and New Zealand, with cloud infrastructure drawing from Singapore and Sydney data center clusters. Raw material dependencies center on compute capacity, API licensing, and specialized compliance engineering talent. Single-source vulnerability sits with ATO protocol update timing, where regulatory release cycles precede vendor implementation windows. Distribution runs through direct SaaS subscription channels and accounting practice reseller networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
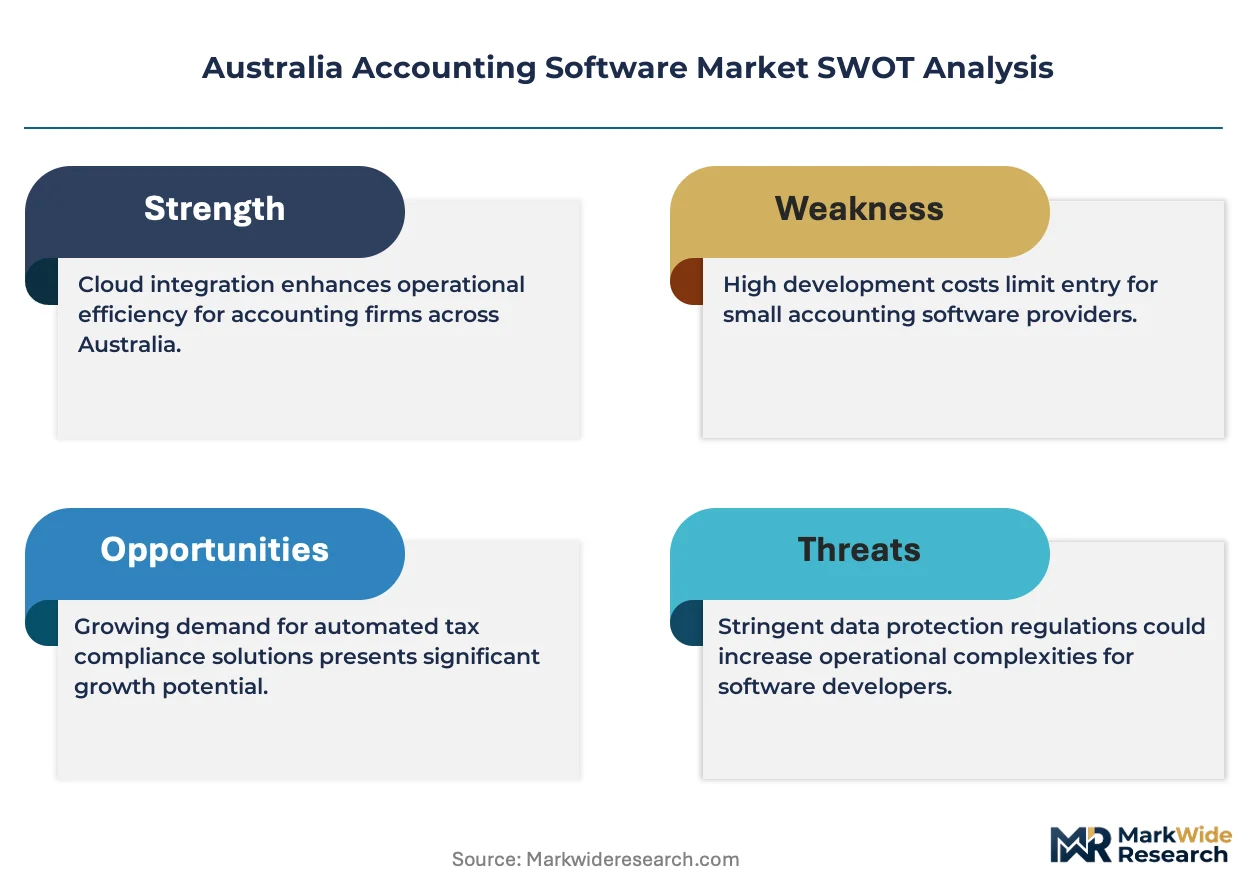
This market represents a consolidation play as ATO compliance certification costs force subscale vendors toward exit or acquisition by platform specialists with captive compliance engineering capacity.
For Market Incumbents: Extend hybrid deployment capabilities to capture Queensland practices navigating legacy transitions, anchoring retention through STP Phase 2 automation depth. Build backward integration into API banking feed infrastructure to reduce third-party licensing exposure and defend margin position against pure-play cloud entrants. For New Entrants and Emerging Players: The gap between premium ASIC-compliant suites and economy freelancer tools offers white-space entry for mid-market professional services in Western Australia and regional South Australia. Target Perth mining sector practices with simplified compliance bundles. Pursue mobile-first positioning with embedded BAS lodgment to bypass incumbent channel control. For Investors and Strategic Acquirers: Accelerated M&A activity among hybrid-deployment specialists is the leading indicator that compliance engineering scarcity is concentrating value capture with vertically integrated platforms. Five-to-ten year viability favors vendors with captive ATO relationship management and multi-tenant infrastructure scale. Monitor STP Phase 2 certification failure rates as the inflection signal for distressed acquisition opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Embedded ATO compliance modules reduce customer churn in Victoria's professional services corridor. |
| Geographic Expansion | Western Australia mining sector professional services remain underpenetrated by automated STP tools. |
| Acquisition of Specialist Firm | Hybrid migration consultants address acute skills gaps in regional Tasmania and Queensland. |
| Strategic Partnership | Open banking API alliances with major Australian banks compress reconciliation labor for practices. |
| Product Launch | Freelancer-centric BAS lodgment tools capture South Australia's gig economy tax complexity demand. |
Research Methodology
Independent corroboration across software vendor product managers, accounting practice technology officers, and ATO compliance specialists underwrites the qualitative findings in this study. Primary interviews with CTOs at mid-tier professional services firms, integration specialists at banking feed providers, and channel partners at accounting software resolvers combined with secondary validation from ASIC regulatory filings, ATO compliance bulletins, and hyperscaler infrastructure disclosures. Bottom-up deployment model sizing and top-down subscription revenue triangulation anchored the market scope.
Rate-of-change decomposition across the analysis window segmented by deployment architecture, organization size, and state-level regulatory adoption pattern. CAGRs derived from trend extrapolation of cloud migration velocity and STP Phase 2 compliance deadline impacts. Forecast inputs incorporated API banking feed penetration curves and hybrid transition consulting demand elasticity.
Inputs from vendor product roadmaps and ATO protocol release schedules were available through the study window; gaps in real-time compliance adoption timing introduce uncertainty bands around migration velocity assumptions. Deviation in ATO enforcement intensity or STP Phase 2 deadline extensions would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Accounting and Taxation Services
Bookkeeper Software Market
Accounting and Taxation Services
Italy Forensic Accounting Market
Accounting and Taxation Services
Global Accounting Finance Market
Accounting and Taxation Services
Crypto Tax Software Market
Accounting and Taxation Services
Global Sales Tax Compliance Software Market
Accounting and Taxation Services
Trust Accounting Software Market
Accounting and Taxation Services
Integrated Accounting Software Market
Accounting and Taxation Services
Tax Compliance Services Market
Accounting and Taxation Services
Accounting and Budgeting Software Market
Accounting and Taxation Services
Canada Accounting Software Market
Accounting and Taxation Services
AI in Accounting Market
Accounting and Taxation Services
Tax Software Market
Accounting and Taxation Services
Global Fund Accounting Software Market
Accounting and Taxation Services
Germany Forensic Accounting Market
Accounting and Taxation Services
US Accounting Software Market
Accounting and Taxation Services
UAE Forensic Accounting Market