
 India Accounting Software Market | 2026-2036
India Accounting Software Market Size, Share, and Industry Trends Forecast 2026-2036
India Accounting Software Market Insights
Subscription-based financing and pay-as-you-scale leasing is reconfiguring competitive dynamics in India's accounting software sector, allowing smaller vendors to challenge incumbents without heavy upfront infrastructure. TallyPrime leverages its three-decade channel density across tier-2 and tier-3 cities to sustain dominant offline-to-cloud migration flows. Zoho Books anchors its position through tight integration with the broader Zoho ecosystem, while myBillBook competes aggressively on vernacular-language interfaces tailored to non-English-speaking traders.
India accounting software encompasses platforms that automate bookkeeping, tax computation, invoicing, and statutory reporting through configurable ledgers, GST-return auto-population, and multi-entity consolidation engines designed for Indian accounting standards and direct tax codes. These systems serve primarily to reduce compliance latency for businesses navigating India's complex indirect tax architecture and mandatory digital filing protocols. Cloud-based deployment leads in new customer acquisition among micro-enterprises seeking zero-maintenance infrastructure, while on-premises solutions retain stickiness among large corporations with legacy ERP integrations and data residency requirements. The freelancer customer segment represents the fastest-growing subscription pool as gig-economy professionals formalize tax filings, though large corporations still command the deepest per-account revenue and customization margin pools.
The Central Board of Direct Taxes mandates quarterly advance tax e-filing, while the Goods and Services Tax Council requires invoice-level data upload through the GST Network, both forcing software vendors to maintain real-time compliance modules. BIS guidelines on data localization and the RBI's recurring payment tokenization rules further constrain architecture choices for cloud-hosted accounting platforms serving Indian enterprises. Stakeholders must monitor how the proposed Digital Personal Data Protection Act enforcement reshapes cross-border data routing permissions for multinational SaaS providers operating in India.
Market Dynamics
GST Network mandates for invoice-level data upload are compressing compliance timelines and forcing micro-enterprises across Gujarat and Maharashtra to abandon manual ledger systems for automated platforms. This regulatory pressure is restructuring competitive dynamics as vendors race to embed real-time tax computation engines.
Growth Catalysts
- Digital Personal Data Protection Act:Proposed enforcement is accelerating vendor investment in localized data centers and encryption protocols to preempt compliance requirements.
- Chartered accountant firms:Deep SaaS penetration among Mumbai, Bangalore, and Delhi-NCR practices is creating referral networks that pull family-owned businesses onto cloud platforms.
- Recurring payment tokenization:RBI rules on subscription billing are standardizing auto-renewal infrastructure, reducing churn friction for SaaS providers serving micro-enterprises.
Market Restraints
- Data localization costs:BIS guidelines mandate domestic server infrastructure, elevating capital requirements for multinational SaaS entrants without existing Indian facilities.
- Legacy ERP integration complexity:Large corporations with captive on-premises systems face switching costs that retard cloud migration despite compliance pressures.
- Vernacular interface development:Non-English-speaking traders require localized UX investment that fragments R&D budgets across regional language variants.
Strategic Opportunities
- Tier-2 and tier-3 cities:Channel density gaps outside Mumbai-Bangalore-Delhi axis present white-space for vernacular-first platforms targeting Gujarat and Maharashtra traders.
- Gig-economy formalization:Freelancer tax filing automation represents an emerging application segment with subscription pooling potential.
- PLI scheme alignment:Domestic software product incentives under India's production-linked initiative could subsidize indigenous ledger engine development.
Industry Challenges
- GST return auto-population engineering:Real-time API synchronization with government portals requires specialized talent scarce outside Bangalore and Hyderabad tech clusters.
- Multi-entity consolidation:Family-owned business groups with cross-state operations demand complex inter-company transaction mapping that stretches implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Accounting Software Market |
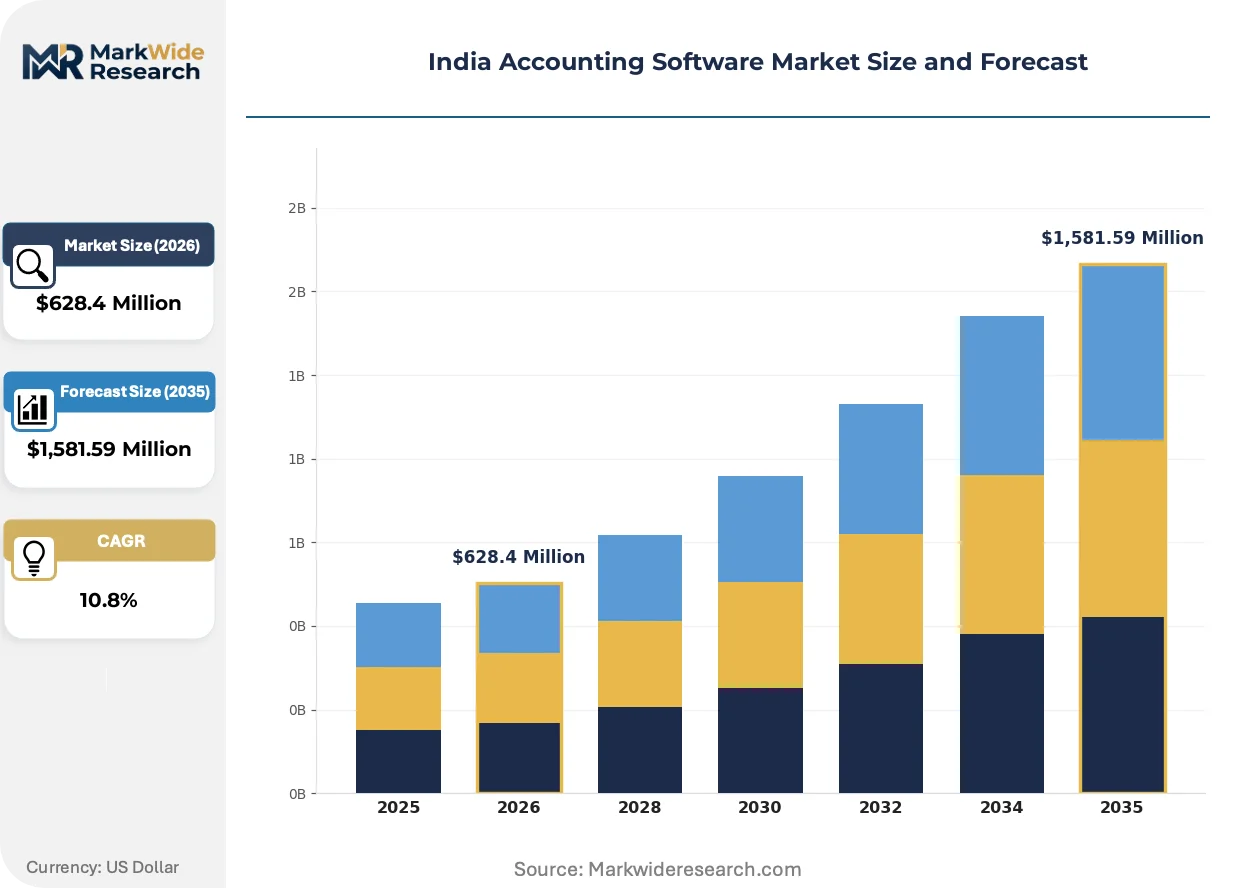
| Market Size in 2026 | $628.4 Million |
| Market Size in 2035 | $1,581.59 Million |
| CAGR (2026 – 2036) | 10.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-Based, On-Premises, Hybrid, Mobile Accounting Customer Type: Small Businesses, Medium Enterprises, Large Corporations, Freelancers Deployment: Single-User, Multi-User, Enterprise, Subscription-Based End User: Retail, Manufacturing, Healthcare, Non-Profit |
| Companies Covered | QuickBooks Online, myBillBook, TallyPrime, ProfitBooks, Munim ERP, Zoho Books, FreshBooks, AlignBooks, Xero Accounting, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Accounting Software Market Trends and Innovations
Artificial intelligence is embedding into compliance workflows, compressing the gap between transaction recording and statutory filing. Vendors are racing to differentiate through predictive tax liability modeling and automated anomaly detection.
Optical character recognition paired with machine learning is rendering obsolete manual data entry for invoice processing. Mid-sized trading houses in Ahmedabad and Surat are adopting these tools at accelerating pace. The technology is compressing book-closing cycles from weeks to hours, forcing traditional service providers to reposition as implementation consultants.
The Digital Personal Data Protection Act is mandating explicit consent frameworks and cross-border data routing restrictions for cloud-hosted platforms. Vendors must architect granular user permission layers and domestic data residency guarantees. SaaS providers serving multinational clients face the steepest reconfiguration burden as they segment Indian subscriber data from global instances.
Subscription unbundling is fragmenting buyer relationships as micro-enterprises purchase point solutions for invoicing, GST filing, and payroll separately rather than integrated suites. Regional resellers in tier-2 cities are capturing margin by assembling vendor-agnostic stacks for price-sensitive traders. This pattern is most pronounced in Maharashtra's industrial corridors where family-owned manufacturers prioritize cost transparency over ecosystem loyalty.
India Accounting Software Market Segmentation
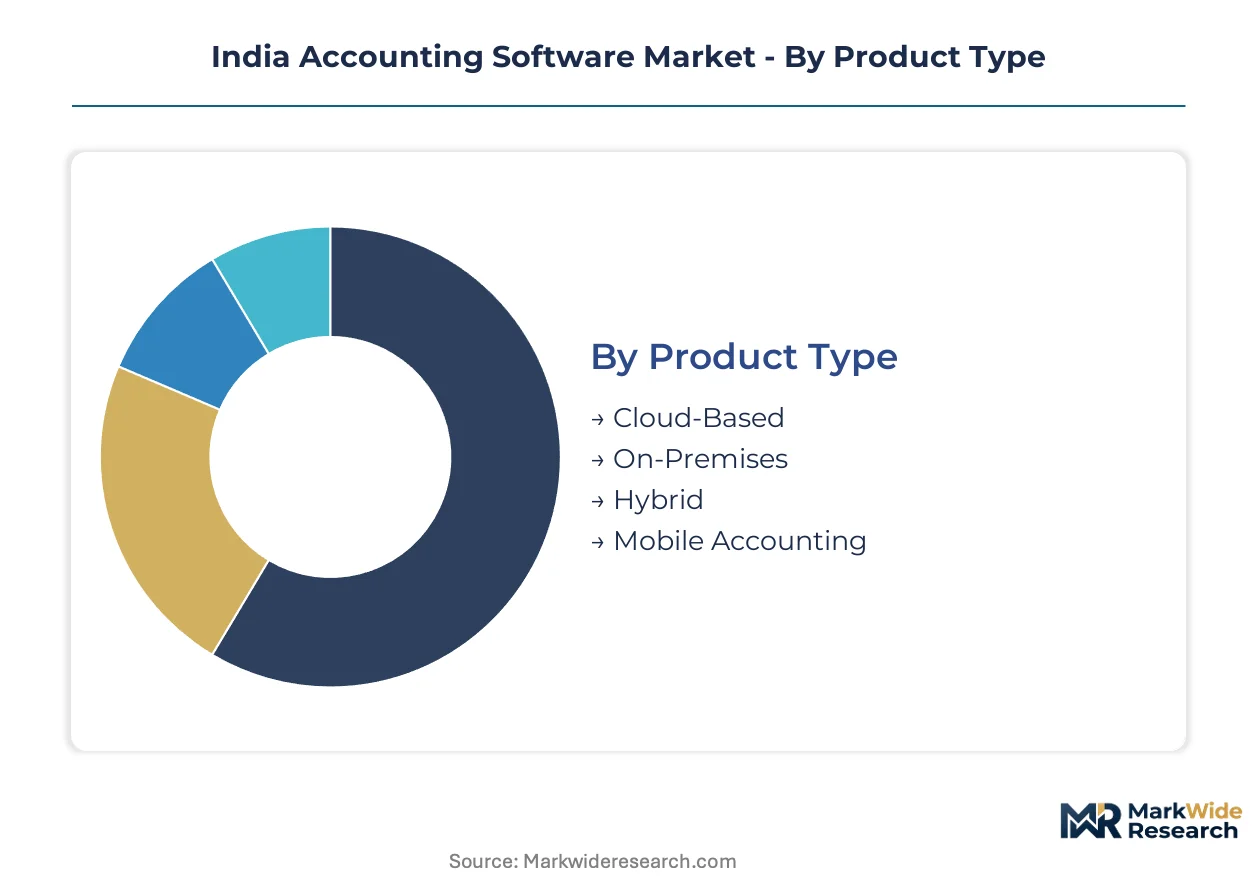
Segmentation in India's accounting software market reveals how regulatory pressure and infrastructure constraints split demand across technical architectures and organizational scale. Vendors must align product roadmaps with the compliance maturity and capital intensity of distinct buyer clusters.
Product Type:
Mature cloud platforms now dominate new customer acquisition, while hybrid and on-premises systems retain entrenched positions among legacy-dependent buyers.
- Cloud-Based:SaaS architectures deliver zero-maintenance infrastructure with automatic GST-return synchronization. Mumbai and Bangalore micro-enterprises are migrating fastest as RBI tokenization rules standardize subscription billing.
- On-Premises:Perpetual-license software running on local servers satisfies data residency mandates for large manufacturers with captive IT infrastructure. Gujarat textile houses favor these systems for audit trail control.
- Hybrid:Split architectures keep sensitive ledger data local while pushing statutory filings to cloud gateways.
- Mobile Accounting:Smartphone-native apps target traveling traders needing invoice generation without desktop dependency.
Cloud-based platforms handle the majority of throughput; mobile accounting is expanding most quickly among non-English-speaking traders in tier-3 cities.
Customer Type:
Revenue concentration and implementation complexity diverge sharply across organizational scale, with family-owned businesses presenting the stickiest long-term contracts.
- Small Businesses:Single-location traders with basic GST compliance needs drive volume for vernacular-interface platforms. Maharashtra industrial corridor demand concentrates here due to mandatory e-invoice thresholds.
- Medium Enterprises:Multi-branch operations require inter-company consolidation engines and multi-state tax jurisdiction handling. These buyers generate the deepest customization revenue pools.
- Large Corporations:Complex ERP integrations and legacy data migration requirements extend sales cycles but yield enterprise-grade annual contracts.
- Freelancers:Gig-economy professionals formalizing tax filings represent an emerging subscription segment with pooled pricing potential.
Small businesses generate the highest absolute transaction volume; freelancers are climbing the fastest on share as platform formalization spreads.
Deployment:
User concurrency models and payment structures segment buyers by technical sophistication and cash-flow preferences.
- Single-User:Solo proprietors and individual chartered accountants operate standalone installations with localized data storage.
- Multi-User:Concurrent-access licensing serves partnership firms and departmental accounting teams with role-based permission hierarchies.
- Enterprise:Unlimited-user deployments with API access for ERP integration dominate manufacturing conglomerates with centralized finance functions.
- Subscription-Based:Monthly or annual recurring payments reduce capital barriers for micro-enterprises in tier-2 Gujarat cities.
Subscription-based deployment captures the majority of new logo acquisition; enterprise licensing retains the steepest expansion trajectory among legacy system replacements.
End User:
Industry-specific compliance workflows and invoice complexity create divergent functional requirements across verticals.
- Retail:High-frequency, low-value transactions demand rapid invoice generation and inventory-linked accounting. Delhi-NCR kirana stores and modern trade outlets drive adoption.
- Manufacturing:Multi-stage production costing and input tax credit tracking require sophisticated job-work modules. Ahmedabad and Surat industrial clusters concentrate demand here.
- Healthcare:Patient billing integration and pharmaceutical supply chain compliance necessitate specialized ledger configurations.
- Non-Profit:Donation tracking and 80G certificate management create unique reporting requirements distinct from commercial accounting.
Retail verticals process the highest invoice throughput; manufacturing is gaining share fastest as GST e-way bill compliance tightens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Maharashtra commands premium pricing power through Mumbai's chartered accountant density, while Gujarat's tier-2 industrial corridors operate on thinner margins despite higher absolute transaction volumes. This asymmetry shapes vendor go-to-market strategies across western India.
Maharashtra
Mumbai's concentration of CA firms and family-owned business headquarters drives demand for multi-entity consolidation engines. The RBI's recurring payment tokenization rules standardize subscription billing infrastructure across SaaS providers. Pune and Nagpur industrial belts are absorbing cloud migration fastest among mid-sized manufacturers.
Gujarat
Ahmedabad and Surat textile houses favor on-premises systems for audit trail control despite GST Network pressure. BIS data localization guidelines elevate domestic server requirements for cloud entrants. Verdant industrial corridors in Vadodara and Rajkot present white-space for vernacular-first platforms targeting non-English-speaking traders.
Karnataka
Bangalore's tech ecosystem supplies scarce engineering talent for GST return auto-population APIs. The state's startup policy incentives subsidize indigenous ledger engine development. Whitefield and Electronic City host the deepest SaaS penetration among micro-enterprises seeking zero-maintenance infrastructure.
Delhi-NCR
The National Capital Region concentrates demand for retail-focused rapid invoice generation tools. Central Board of Direct Taxes quarterly advance tax mandates compress compliance timelines for kirana stores. Gurugram and Noida corridors attract multinational SaaS providers establishing Indian data centers.
Telangana
Hyderabad's tech clusters rival Bangalore for GST API synchronization engineering talent. The state's IT policy framework accelerates domestic cloud infrastructure investment. Secunderabad trading communities are emerging as early adopters of mobile-native accounting apps for traveling merchants.
India Accounting Software Market Competitive Landscape
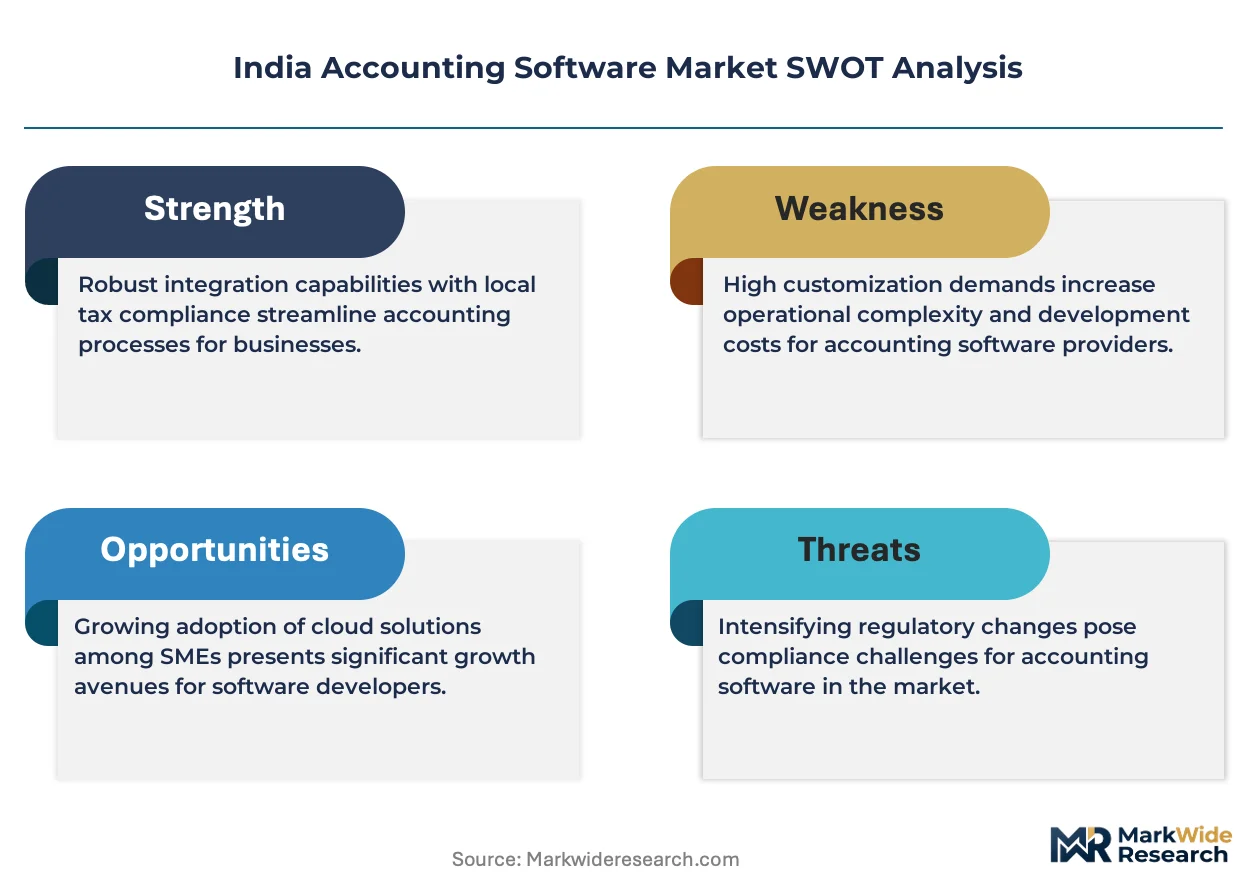
Platform integrators command the system tier; component specialists sit upstream capturing margin on discrete compliance modules. The vendor base organizes around three-decade incumbents with channel density, ecosystem-anchored suites with cross-sell leverage, and vernacular-first challengers with regional UX depth. Two strategic moves dominate: subscription unbundling to capture price-sensitive micro-enterprises, and localized data center buildout to satisfy BIS residency mandates.
Among domestic platform specialists, TallyPrime anchors the offline-to-cloud migration flow through tier-2 and tier-3 penetration. Zoho Books occupies a position within the ecosystem-anchored tier, leveraging cross-product integration. myBillBook represents the vernacular-first challenger archetype, competing on regional language interfaces for non-English-speaking traders across Gujarat and Maharashtra industrial belts.
| Leading Market Players |
|---|
| QuickBooks Online |
| myBillBook |
| TallyPrime |
| ProfitBooks |
| Munim ERP |
| Zoho Books |
| FreshBooks |
| AlignBooks |
| Xero Accounting |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in cloud infrastructure across Bangalore and Hyderabad data centers is compressing hosting costs for SaaS vendors while simultaneously elevating price competition for subscription tiers, forcing providers to absorb margin pressure or differentiate through customization premiums rather than raw infrastructure savings.
Pricing Analysis
The customization-premium spread between configured-to-order enterprise deployments and standard SaaS tiers defines competitive positioning. Subscription-based recurring revenue dominates new customer acquisition, while perpetual licensing retains stickiness among legacy-dependent manufacturers. Price differentiation rests on vertical integration depth and GST compliance certification levels. Pricing pressure stems from vernacular-first challengers undercutting standard tiers in Gujarat and Maharashtra industrial belts. Micro-enterprises in tier-2 cities exhibit acute price sensitivity, whereas large corporations with multi-entity consolidation needs tolerate premium positioning.
Supply Chain Analysis
Tariff exposure between India and China for server hardware components elevates capital costs for domestic data center expansion. Engineering talent concentrates in Bangalore, Hyderabad, and Pune, creating geographic dependency for GST API synchronization development. Raw material inputs draw from Taiwanese semiconductor foundries, Korean memory suppliers, and domestic assembly facilities. Single-source vulnerability in specialized compliance engineering talent stretches implementation timelines for real-time tax computation modules. Distribution runs through channel partners in tier-2 and tier-3 cities, with regional resellers capturing margin by assembling vendor-agnostic stacks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where ecosystem interoperability determines customer lifetime value, as evidenced by cross-product integration within productivity suites pulling family-owned businesses onto unified cloud platforms.
For Market Incumbents: Insulate dominant position by deepening channel control in tier-2 Gujarat and Maharashtra corridors where vernacular-first challengers threaten share. Prioritize R&D investment in predictive tax liability modeling to differentiate against commodity GST filing tools. Vertical integration into localized data center infrastructure addresses BIS residency mandates while raising rival cost structures. For New Entrants and Emerging Players: Mid-market manufacturing clusters in Vadodara and Rajkot represent the most penetrable entry point, where on-premises legacy dependence creates switching-cost friction for incumbents but compliance pressure demands cloud migration. Freelancer tax automation in tier-3 cities offers pooled subscription potential with lower customer acquisition costs. Go-to-market execution through chartered accountant referral networks in Mumbai and Delhi-NCR accelerates trust formation. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vertical-specific platforms with embedded compliance workflows rather than horizontal accounting tools. Long-term viability favors vendors with indigenous ledger engines eligible for PLI scheme subsidies. Acquisition target archetype: vernacular-interface specialists with deep tier-3 penetration. Watch GST Council e-invoice threshold reductions as inflection signal for compliance-driven upgrade cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Cross-product bundling within productivity suites captures family-owned business migration flows. |
| Vernacular Localization | Regional language UX unlocks tier-3 trader segments in Gujarat and Maharashtra industrial belts. |
| Domestic Data Center Buildout | BIS-compliant infrastructure satisfies residency mandates for multinational SaaS entrants. |
| API Ecosystem Partnership | Real-time GST Network synchronization differentiates compliance automation from basic bookkeeping. |
| Freelancer Segment Launch | Gig-economy formalization creates pooled pricing models with subscription expansion potential. |
Research Methodology
A spread of perspectives from SaaS product managers, chartered accountant practitioners, GST Network implementation specialists, and channel distribution partners converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through RBI circulars, GST Council notifications, BIS data localization guidelines, and SEC filings of listed software providers. Bottom-up triangulation across deployment models and customer segments was cross-checked against top-down market sizing from trade association disclosures.
Demand-supply balance framing anchored the analytical approach across the analysis window. Segmentation dimensions modeled include deployment architecture, organizational scale, vertical industry, integration complexity, and regional adoption maturity. CAGRs were derived from installed base growth rates and average revenue per account expansion. Forecast inputs incorporated GST e-invoice threshold trajectories and PLI scheme incentive structures.
Macroeconomic conditions sit as an overlay; deviation in SME credit availability or rupee volatility would shift the trajectory. Forecasts reflect documented assumptions about regulatory enforcement timelines and cloud infrastructure investment cycles. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Accounting and Taxation Services
Europe Accounting Software Market
Accounting and Taxation Services
South Korea Accounting & Budgeting Software Market
Accounting and Taxation Services
China Accounting Software Market
Accounting and Taxation Services
US Auditing Services Market
Accounting and Taxation Services
UK Forensic Accounting Market
Accounting and Taxation Services
Crypto Tax Software Market
Accounting and Taxation Services
Global Financial Accounting Advisory Services Market
Accounting and Taxation Services
Accounting and Budgeting Software Market
Accounting and Taxation Services
Tax Preparation Services Market
Accounting and Taxation Services
Bookkeeper Software Market
Accounting and Taxation Services
Spain Forensic Accounting Market
Accounting and Taxation Services
Trust Accounting Software Market
Accounting and Taxation Services
Global Fund Accounting Software Market
Accounting and Taxation Services
Bookkeeping Services Market
Accounting and Taxation Services
India Forensic Accounting Market
Accounting and Taxation Services
US Accounting Software Market