
 Electric Water Bottle Market | 2026-2036
Electric Water Bottle Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Water Bottle Market Foresight
Chinese OEM capacity is hardening as Shenzhen and Dongguan electronics corridors expand temperature-control assembly lines for portable appliances. PHILIPS leverages its healthcare brand equity to command premium positioning in European retail channels. Midea anchors mass-market volume through its appliance distribution network across Asia. Zojirushi differentiates via precision thermal engineering heritage and Japanese manufacturing standards.
An electric water bottle integrates battery-powered heating or cooling elements with vacuum insulation to maintain liquid temperature for extended periods, typically operating via USB-rechargeable lithium cells with digital thermostat interfaces. The device serves commuters, athletes, and office workers requiring on-demand temperature control without external power sources. Smart Bottle and Heated Bottle categories capture the dominant margin pools as consumers prioritize app-connected hydration tracking and rapid heating functions. Stainless Steel construction leads material demand due to durability perceptions, while BPA-Free Materials segments attract parental and health-conscious buyers. USB Charging technology dominates power interfaces, though Bluetooth Connectivity integration is accelerating as wellness app ecosystems expand.
FDA food-contact material standards and EU REACH chemical safety frameworks govern plastic and coating components in bottles sold across North America and Europe. China's GB standards for small appliance electrical safety and Japan's PSE certification requirements shape export compliance costs for manufacturers targeting those markets. Battery transport regulations from IATA and national aviation authorities increasingly constrain lithium-cell logistics for cross-border e-commerce shipments. Stakeholders must monitor evolving right-to-repair mandates and extended producer responsibility laws that could reshape product design and end-of-life collection obligations.
Market Dynamics
The electric water bottle market pivots on lithium-ion cell miniaturization and vacuum insulation co-manufacturing capabilities concentrated in China's Pearl River Delta electronics corridors. This supply concentration creates asymmetric pricing power and accelerates feature integration cycles.
Growth Catalysts
- Fitness tracking integration:Athletes and wellness consumers demand app-connected hydration monitoring. Bluetooth-enabled bottles capture this segment through seamless data synchronization with health platforms.
- EU REACH chemical safety frameworks:Stricter material certification requirements elevate entry barriers for low-cost competitors. Premium manufacturers leverage compliance as competitive differentiation.
- Shenzhen-Dongguan manufacturing clusters:Dense supplier networks for temperature-control components compress prototyping timelines. Domestic Chinese brands exploit this proximity for rapid product iteration.
Market Restraints
- Lithium carbonate price volatility:Battery cell costs fluctuate with mining output from Chile and Australia. Manufacturers face margin compression during supply tightness.
- IATA lithium transport regulations:Aviation authorities restrict air freight of rechargeable cells. Cross-border e-commerce fulfillment incurs routing delays and compliance surcharges.
- Thermal efficiency ceilings:Current vacuum insulation technology approaches theoretical heat transfer limits. Further performance gains require material science breakthroughs with extended R&D timelines.
Strategic Opportunities
- India's PLI scheme for electronics manufacturing:Production-linked incentives attract contract manufacturers away from sole China dependency. Brands can diversify assembly footprints while accessing domestic tariff advantages.
- Workplace wellness programs:Corporate procurement of connected hydration devices expands B2B revenue streams. Employers subsidize employee health monitoring through bulk subscription models.
- Right-to-repair mandates in France and EU member states:Modular battery and heating element designs align with emerging regulatory requirements. Early compliance builds brand reputation and reduces future redesign costs.
Industry Challenges
- Thermal engineering talent scarcity:Cross-disciplinary expertise combining electrochemistry, insulation physics, and firmware development commands premium compensation. Startups struggle to recruit against established appliance manufacturers.
- Multi-market certification complexity:Simultaneous FDA food-contact, PSE electrical safety, and GB standard compliance extends product launch timelines. Testing backlog at accredited laboratories creates bottlenecks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Water Bottle Market |
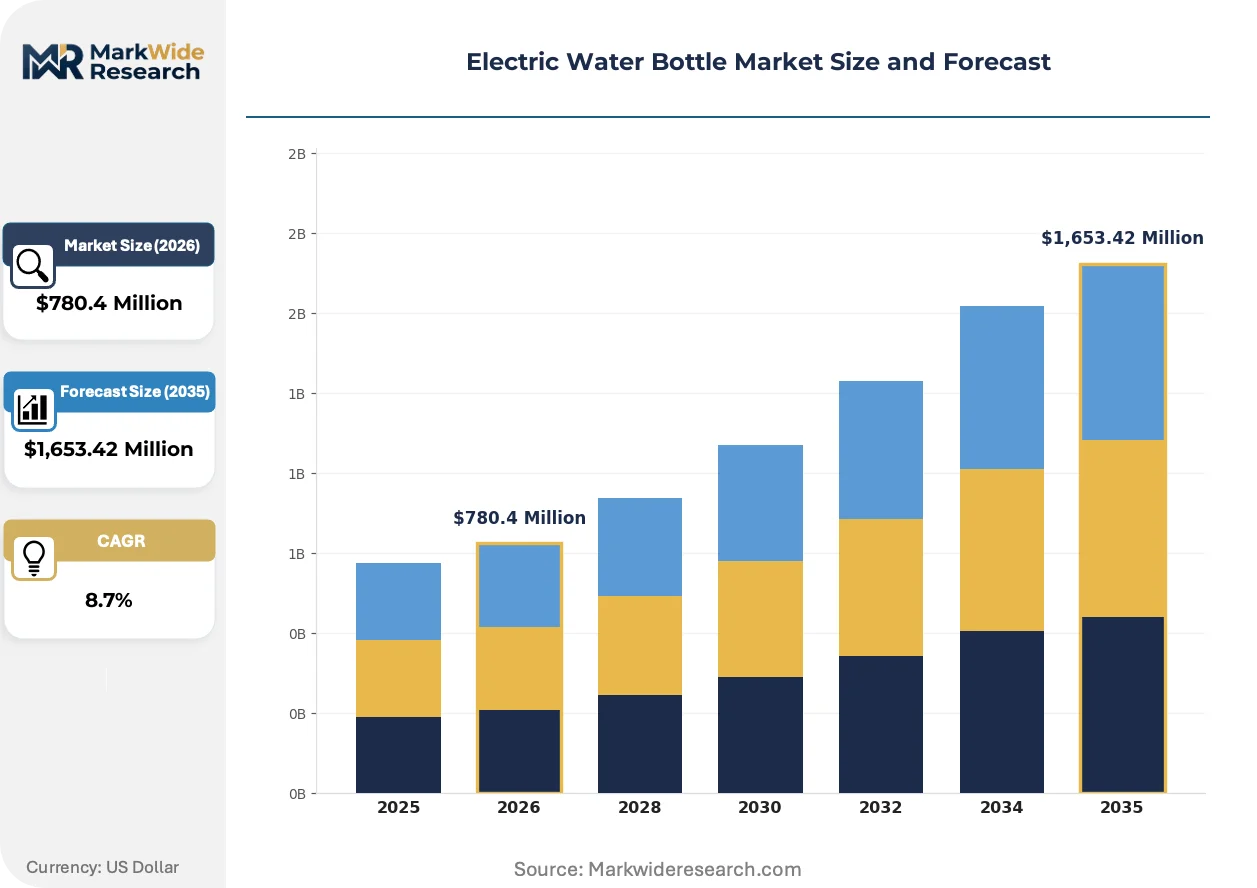
| Market Size in 2026 | $780.4 Million |
| Market Size in 2035 | $1,653.42 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Bottle, Heated Bottle, Insulated Bottle, Portable Bottle End User: Fitness Enthusiasts, Travelers, Office Workers, Students Material: Stainless Steel, Plastic, Glass, BPA-Free Materials Technology: Bluetooth Connectivity, Solar Power, USB Charging, Temperature Control |
| Companies Covered | PHILIPS, Thermos, Midea, Bear, Zojirushi, SUPOR, Tiger, SKG, Joyoung, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Water Bottle Market Shifts & Advancements
Product architecture is converging around smart connectivity and sustainable materials as baseline expectations rather than premium differentiators. This shift compresses feature commoditization cycles and raises minimum viable product specifications.
USB-C power delivery is overtaking proprietary charging interfaces across the electric water bottle category. The universal standard eliminates adapter clutter for commuters and travelers. Office workers and frequent flyers adopt USB-C models at three times the rate of legacy micro-USB alternatives. This convergence is overtaking regional charging fragmentation and forcing manufacturers to abandon custom connector designs.
EU extended producer responsibility laws for small appliance recycling are tightening material disclosure requirements. Manufacturers must document plastic polymer grades and battery chemistries for end-of-life processing. The Smart Bottle segment faces the steepest compliance burden due to embedded electronics density. European retailers now demand take-back program commitments before listing new products.
Direct-to-consumer subscription models are displacing traditional retail stocking for replacement parts and accessories. Fitness enthusiasts purchase filter cartridges and charging bases through brand apps rather than third-party marketplaces. This channel shift concentrates customer data ownership with manufacturers. The United States and United Kingdom show the highest subscription attachment rates among health-conscious demographics.
Electric Water Bottle Market Segmentation
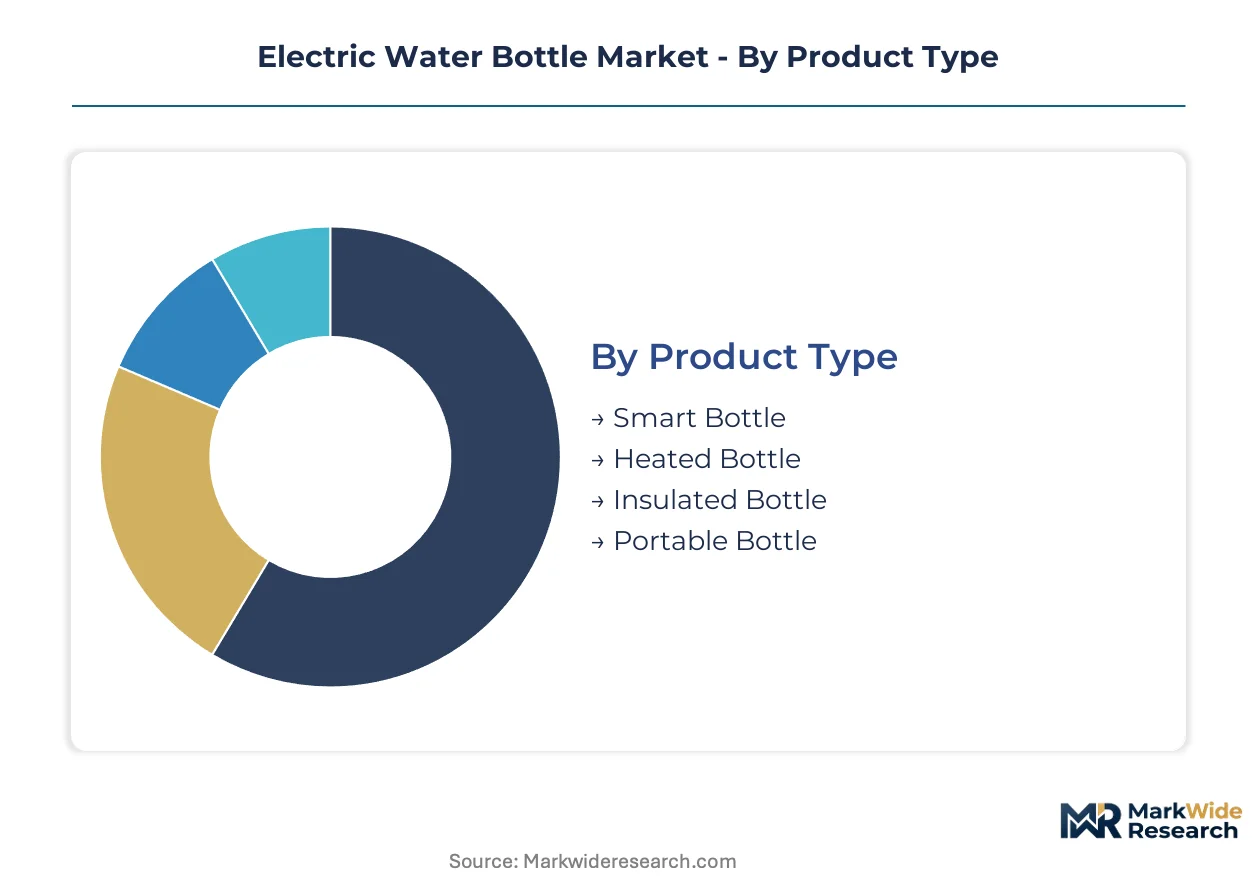
Electric water bottle purchasing decisions hinge on upgrade cycles driven by battery degradation, connectivity protocol obsolescence, and wellness app ecosystem shifts. Segmentation reveals how replacement timing varies dramatically across use cases and technology tiers.
Product Type:
Replacement cycles compress where digital interfaces and lithium cells require periodic refresh, extending where passive insulation dominates.
- Smart Bottle:Embedded sensors and Bluetooth modules demand firmware updates and battery swaps every 18-24 months. Fitness enthusiasts in the United States and United Kingdom drive replacement through health platform integration requirements.
- Heated Bottle:Heating element durability and thermostat calibration drift create 3-4 year replacement windows. Office workers across Germany and Japan prioritize rapid heating functions for workplace consumption.
- Insulated Bottle:Vacuum seal integrity determines multi-year lifespans with minimal technology obsolescence. Travelers value reliability over feature churn.
- Portable Bottle:Compact form factors trade thermal capacity for mobility, appealing to students with constrained carrying capacity.
Volume placements concentrate in Heated Bottle; the faster expansion belongs to Smart Bottle.
End User:
Customer lifetime value diverges sharply between subscription-oriented fitness segments and price-sensitive student cohorts.
- Fitness Enthusiasts:Hydration tracking accuracy and app synchronization command premium pricing tolerance. China's domestic brands exploit manufacturing proximity to iterate sensor hardware rapidly.
- Travelers:TSA compliance and universal voltage compatibility filter product selection. Frequent flyers prioritize USB-C charging standardization across multiple device categories.
- Office Workers:Desktop footprint and noise suppression during heating cycles influence purchasing. European workplace wellness subsidies expand addressable demand.
- Students:Entry price points and dormitory electrical safety certifications constrain options. BPA-free material requirements dominate parental purchasing criteria.
Margin concentration sits with Fitness Enthusiasts; steepest volume expansion tracks Students.
Material:
Surface finish durability and thermal conductivity properties govern material selection trade-offs between performance and cost.
- Stainless Steel:304 and 316 grade alloys deliver impact resistance and neutral taste profiles. Japanese manufacturing standards from Zojirushi anchor premium positioning through electropolished interiors.
- BPA-Free Materials:Tritan copolyester and food-grade polypropylene address parental health concerns. FDA food-contact certification requirements elevate testing costs for new entrants.
- Plastic:Lower unit weights appeal to cycling and hiking applications where gram reduction matters.
- Glass:Chemical inertness attracts tea and coffee purists despite fragility constraints.
Stainless Steel commands production volume; BPA-Free Materials climb the fastest on regulatory tailwinds.
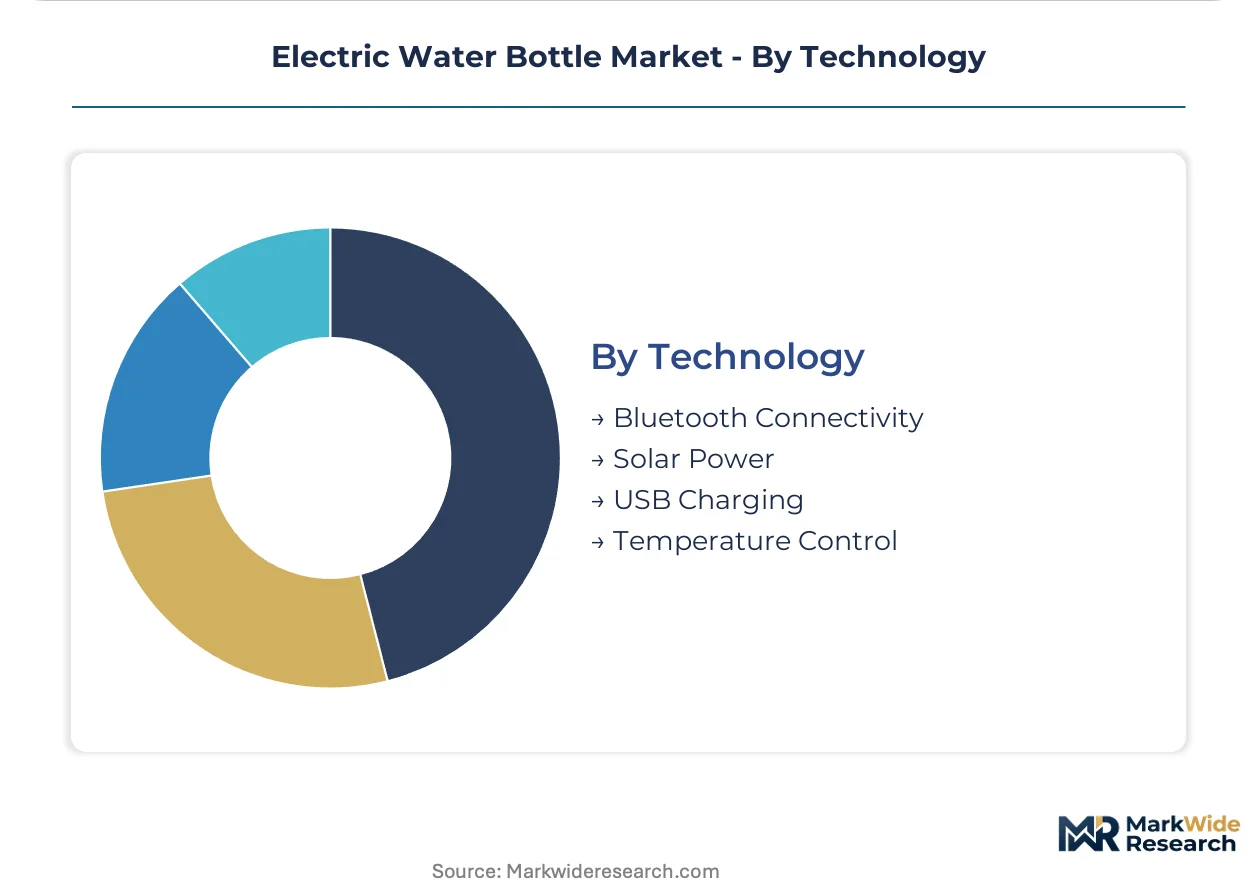
Technology:
Power interface standardization and wireless protocol adoption reshape component sourcing and firmware development priorities.
- USB Charging:USB-C Power Delivery 3.0 eliminates proprietary adapter fragmentation. Shenzhen component suppliers drive cost compression through scale economies.
- Bluetooth Connectivity:BLE 5.2 integration enables continuous hydration monitoring without excessive battery drain. EU GDPR compliance for health data processing adds firmware complexity.
- Temperature Control:PID algorithm precision differentiates heating speed and energy efficiency. Thermal engineering talent scarcity constrains startup R&D velocity.
- Solar Power:Amorphous silicon cell efficiency limits practical deployment to extended outdoor use cases.
USB Charging dominates unit placements; Bluetooth Connectivity gains share fastest on wellness app proliferation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lithium carbonate deposits in Chile's Atacama Desert and Australia's Greenbushes mine anchor battery cost structures for electric water bottle manufacturers worldwide. Shenzhen's electronics corridor converts these raw materials into temperature-control assemblies at scale.
United States
Fitness enthusiasts and corporate wellness programs drive premium Smart Bottle demand across metropolitan markets. FDA food-contact material standards govern plastic and coating components for bottles sold domestically. California's Bay Area hosts connected-device startups iterating hydration-tracking firmware.
China
Domestic e-commerce penetration and manufacturing cluster density accelerate both production and consumption simultaneously. GB standards for small appliance electrical safety shape export compliance costs for Pearl River Delta assemblers. Dongguan's temperature-control component suppliers compress prototyping timelines for domestic brands.
Germany
Office workers prioritize rapid heating functions and desktop footprint efficiency in workplace consumption settings. EU REACH chemical safety frameworks elevate material certification barriers for imported products. Bavaria's industrial design studios specialize in thermal engineering interfaces for premium appliance brands.
Japan
Precision thermal engineering heritage sustains demand for electropolished stainless steel construction and multi-year durability. METI and PSE certification requirements constrain product launch timelines for foreign entrants. Osaka-Kansai manufacturing bases anchor Zojirushi's vacuum insulation production standards.
India
Student demographics and entry-price sensitivity expand volume potential in urban and tier-two cities. PLI scheme incentives for electronics manufacturing attract contract assemblers exploring alternatives to sole China dependency. Maharashtra's Pune corridor incubates domestic brands targeting BPA-free material preferences.
Electric Water Bottle Market Competitive Landscape
Global majors compete with regional champions across brand equity and distribution reach. The market structure tiers between premium healthcare-positioned multinationals, mass-market appliance conglomerates, and precision-engineering specialists. Appliance conglomerates exploit existing retail networks. Precision specialists leverage thermal engineering heritage. Dominant competitive moves include geographic expansion through e-commerce platforms and portfolio diversification into connected hydration ecosystems.
Among diversified appliance conglomerates, Midea Group Co., Ltd. and Joyoung Co., Ltd. occupy positions exemplifying mass-market volume strategies through established distribution networks. PHILIPS anchors the premium tier through healthcare brand equity transfer. Zojirushi Corporation represents precision thermal engineering heritage with Japanese manufacturing standards.
| Leading Market Players |
|---|
| PHILIPS |
| Thermos |
| Midea |
| Bear |
| Zojirushi |
| SUPOR |
| Tiger |
| SKG |
| Joyoung |
| Others |
Supply & Pricing Matrix
Lithium carbonate extraction from Chile's Atacama Desert and Australia's Greenbushes mine feeds through Shenzhen component assemblers into three distinct pricing tiers for end consumers. Battery cell cost volatility compresses margins at the economy tier while premium manufacturers absorb fluctuations through healthcare brand equity.
Pricing Analysis
Warranty bundling separates premium positioning from mass-market alternatives, with PHILIPS and Zojirushi including multi-year heating element coverage against Midea's standard limited protection. Three-tier pricing structure across premium, standard, and economy levels reflects certification tier differentiation, with PSE and FDA food-contact compliance commanding markups. Pricing pressure stems from lithium carbonate spot market volatility pressuring battery-dependent Smart Bottle margins. Students exhibit highest price sensitivity, filtering selections through dormitory electrical safety certification requirements, while fitness enthusiasts tolerate premium positioning for app synchronization accuracy.
Supply Chain Analysis
Dual-sourcing mandates from European retailers now require battery qualification from both Chinese and South Korean cell suppliers before product listing approval. Manufacturing gravity centers on China's Pearl River Delta, South Korea's battery corridor, and Japan's precision thermal engineering bases. Component dependencies span lithium-ion cells, vacuum insulation materials, and PID thermostat controllers. Single-source vulnerability concentrates in Shenzhen temperature-control assembly capacity. Distribution runs through domestic e-commerce platforms in China, specialized appliance retail in Germany and Japan, and direct-to-consumer subscription channels in the United States and United Kingdom.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
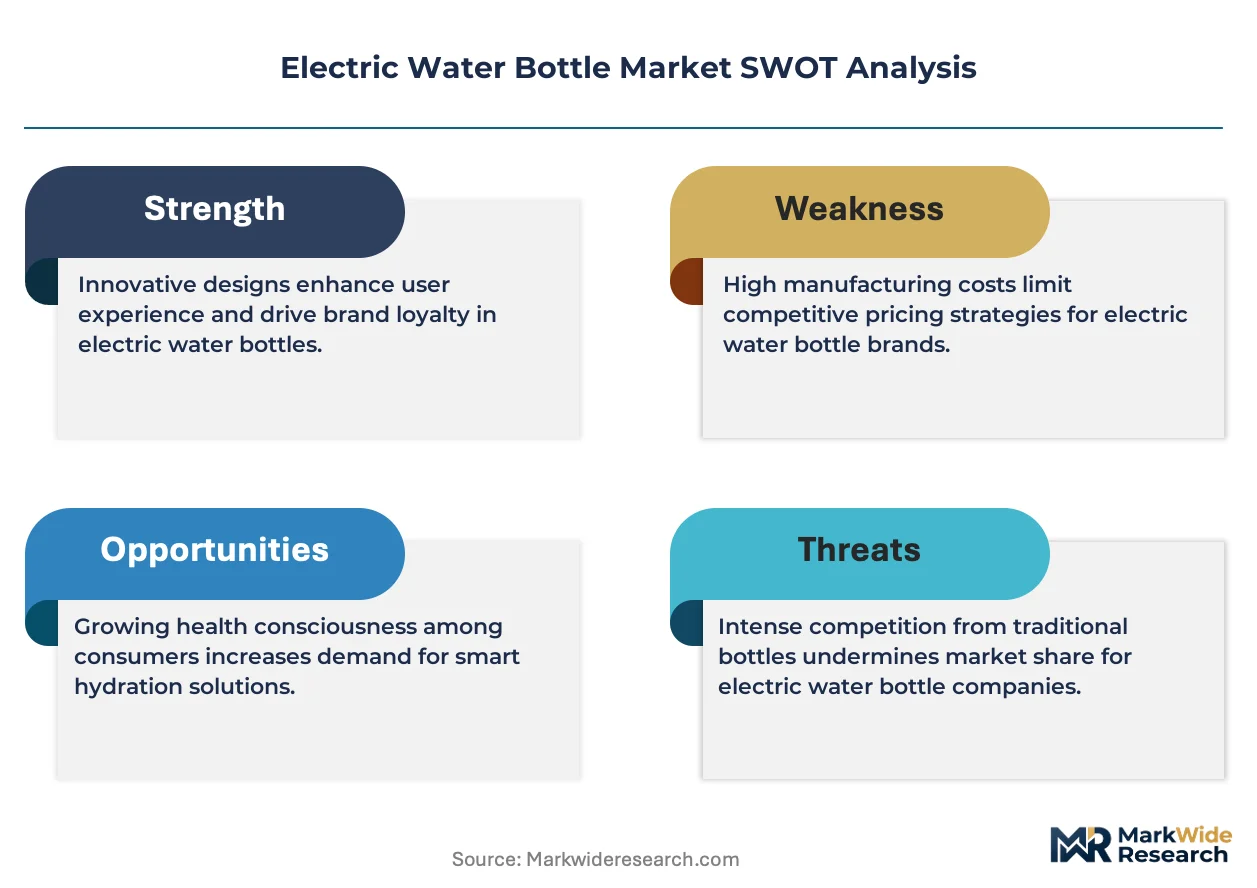
The electric water bottle market is becoming a vertical-integration race as manufacturers pursue captive lithium-cell supply to insulate margins from mining output volatility.
For Market Incumbents: Extend firmware development capabilities in-house to reduce dependency on Shenzhen Bluetooth module suppliers facing GDPR compliance complexity. Acquire thermal engineering talent through Bavaria and Osaka-Kansai design studio partnerships before startup competitors exhaust local pools. Consolidate position against emerging direct-to-consumer subscription entrants by locking corporate wellness procurement contracts with multi-year hydration monitoring service bundles.
For New Entrants and Emerging Players: Fitness app developers represent the most penetrable channel partner type for white-label Smart Bottle deployment without manufacturing infrastructure investment. Target India's student demographic through Maharashtra Pune corridor assembly partnerships exploiting PLI scheme tariff advantages. Pursue workplace wellness program procurement channels in Germany where EU REACH compliance barriers filter out unqualified competitors.
For Investors and Strategic Acquirers: India's PLI scheme attracting contract manufacturers away from sole China dependency is the leading indicator that geographic diversification will reshape competitive economics. Five-to-ten year viability favors precision thermal engineering specialists with modular battery designs aligned to emerging right-to-repair mandates. Acquisition target archetype: mid-cap brands with established PSE or FDA certification pathways and dormant distribution in underpenetrated European markets. Signal to watch: IATA lithium transport regulation tightening forcing air freight routing restructuring.
| Strategic Initiative | Industry Significance |
|---|---|
| USB-C Power Delivery Standardization | Eliminates proprietary adapter fragmentation for frequent flyers across multiple device categories. |
| Modular Battery Design Transition | Aligns product architecture with France and EU right-to-repair mandate compliance requirements. |
| Corporate Wellness Program Partnership | Expands B2B revenue streams through employer-subsidized employee health monitoring subscriptions. |
| Thermal Engineering Talent Acquisition | Addresses cross-disciplinary expertise scarcity combining electrochemistry, insulation physics, and firmware development. |
| Direct-to-Consumer Subscription Launch | Concentrates customer data ownership with manufacturers displacing third-party marketplace dependency. |
Research Methodology
Trade databases, customs records, and appliance industry association filings formed the secondary backbone for volume and value estimation. Primary interviews with thermal engineering directors, e-commerce platform category managers, lithium-cell procurement leads, and corporate wellness program administrators validated demand assumptions. Bottom-up and top-down triangulation cross-referenced Shenzhen component supplier output data against end-market retail audit figures.
Bottom-up modeling anchored forecasts on product-level bill-of-materials analysis across Smart Bottle, Heated Bottle, Insulated Bottle, and Portable Bottle categories. Segmentation dimensions included technology tier, material grade, end-user archetype, and regional certification cluster. CAGRs derived from fitted growth curves incorporating battery degradation replacement cycles, connectivity protocol obsolescence patterns, and wellness app ecosystem expansion rates. Lithium carbonate price trajectory assumptions and IATA transport regulation evolution shaped cost-side projections.
Caveats apply where lithium mining output volatility, IATA lithium transport restriction tightening, or EU extended producer responsibility law acceleration could materially shift the outlook. Deviation in China's GB standards enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
Global Laptop Market
Consumer Electronics
China Massage Equipment Market
Consumer Electronics
Europe Refurbished and Used Mobile Phones Market
Consumer Electronics
Gaming PC Market
Consumer Electronics
Pet Cameras Market
Consumer Electronics
Mannequin Head Market
Consumer Electronics
Armenia Consumer Goods Market
Consumer Electronics
Apple Accessories Market
Consumer Electronics
Pool Speakers Market
Consumer Electronics
Global Office and Contact Center Headset Market
Consumer Electronics
Shoe Shining Machine Market
Consumer Electronics
Air Tube Headset Market
Consumer Electronics
Europe Mobile Phone Accessories Market
Consumer Electronics
Vape Cartridge Market
Consumer Electronics
Gaming Computer Market
Consumer Electronics
Smart TV Market