
 Vape Market | 2026-2036
Vape Market Size, Share, and Industry Trends Forecast 2026-2036
Vape Market Analysis
The EU Tobacco Products Directive is repositioning vape formulation standards across member states, compelling manufacturers to reformulate nicotine concentrations and packaging disclosures. British American Tobacco leverages its heated-tobacco R&D infrastructure to sustain dual-portfolio competitiveness. Philip Morris International anchors its growth trajectory on smoke-free product transitions in regulated European markets. RELX Technology dominates pod-system distribution across Asia-Pacific retail channels.
A vape comprises a battery-powered inhalation device that aerosolizes e-liquid—typically propylene glycol, vegetable glycerin, flavorings, and optional nicotine—through resistive heating at 100–250°C for pulmonary nicotine delivery or recreational use. Disposable products lead volume sales through convenience-store penetration, while pod systems capture premium margin pools via closed-system cartridge economics. E-liquid flavor profiles stratify demand, with fruit and dessert variants outpacing tobacco-menthol growth in non-switcher demographics.
The FDA's PMTA pathway in the United States, the EU TPD notification system, and the UK's MHRA compliance framework collectively determine market access, product legality, and nicotine concentration ceilings. These regulatory architectures favor firms with dedicated regulatory-affairs capabilities and substantial submission funding. Stakeholders must monitor pending flavor restrictions and taxation proposals that could restructure profitability across pod and disposable formats.
Market Dynamics
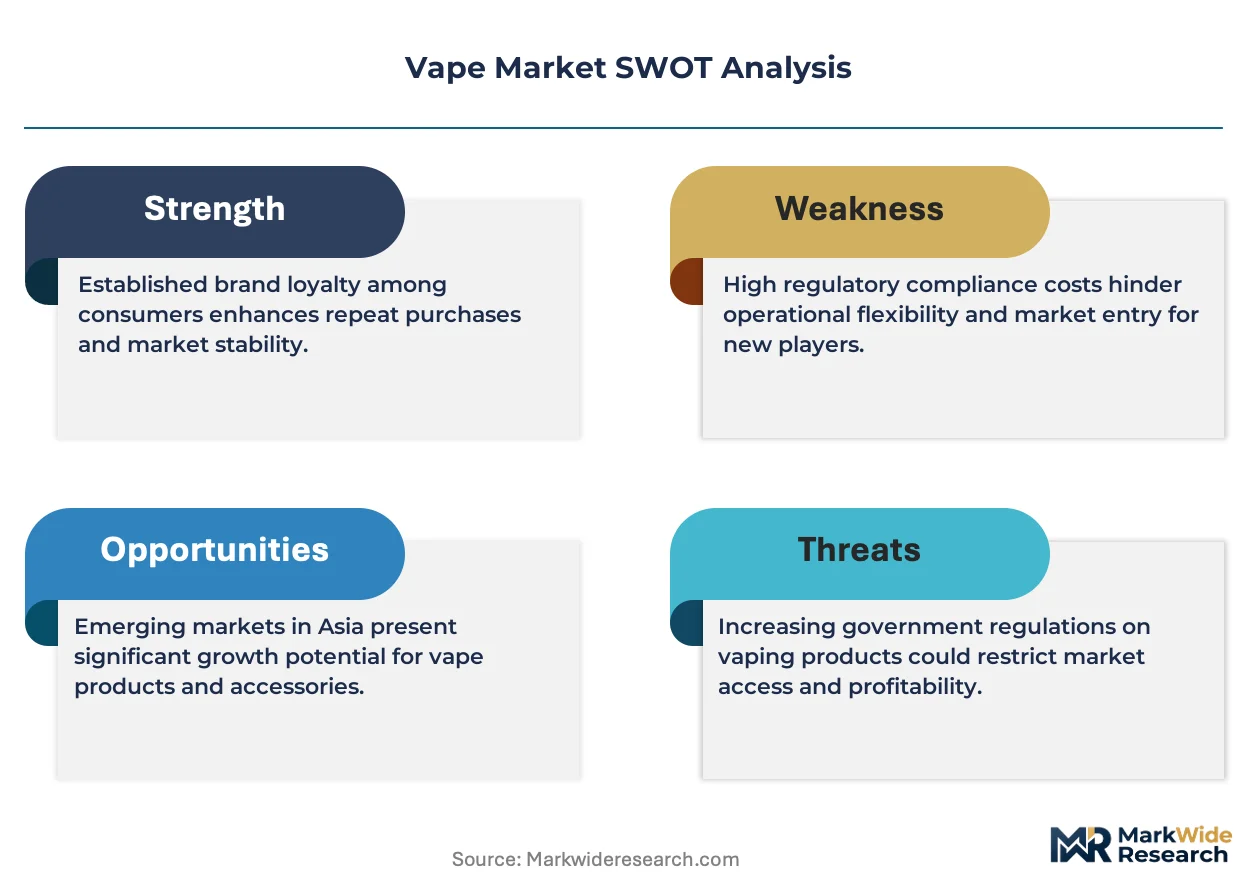
The FDA's PMTA pathway and the EU Tobacco Products Directive are compressing product lifecycles while elevating compliance costs, forcing manufacturers to choose between portfolio consolidation and regulatory abandonment.
Growth Catalysts
- Flavor Innovation:Fruit and dessert e-liquid profiles capture non-switcher demographics in the United States and United Kingdom, expanding addressable demand beyond traditional tobacco-menthol users.
- EU TPD Notification System:Clearer compliance frameworks across Germany, France, and Italy reduce market-entry uncertainty for compliant manufacturers, concentrating volume in regulated jurisdictions.
- Pod-System Economics:Closed-system cartridge models generate recurring revenue streams through proprietary coil and pod architectures, locking in user retention.
Market Restraints
- Input Cost Volatility:Vegetable glycerin and propylene glycol prices fluctuate with biodiesel feedstock markets, squeezing e-liquid formulation margins.
- Regulatory Friction:Pending flavor restrictions in multiple US states threaten disposable and pod-system profitability, forcing inventory write-downs and SKU rationalization.
- Substitution Threat:Heated-tobacco products and nicotine pouches divert switching smokers away from liquid-based vapor systems, particularly in Japan and South Korea.
Strategic Opportunities
- Underpenetrated Channels:Pharmacy and healthcare retail networks in Germany and the United Kingdom remain underdeveloped for reduced-risk nicotine distribution, offering white-space expansion.
- Regulatory Tailwind:The UK's MHRA compliance framework for medically licensed vaping products creates a pathway to prescription reimbursement, opening institutional procurement channels.
- Technology Convergence:Integration of Bluetooth-enabled dose-tracking and smartphone connectivity differentiates premium pod systems, capturing data-monetization potential.
Industry Challenges
- Compliance Timeline Compression:FDA PMTA resubmission requirements and EU TPD renewal cycles strain regulatory-affairs staffing, particularly for mid-tier manufacturers.
- Supply Chain Reconfiguration:Relocation of battery and chipset sourcing away from concentrated Asian suppliers requires qualification of alternative vendors, delaying product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vape Market |
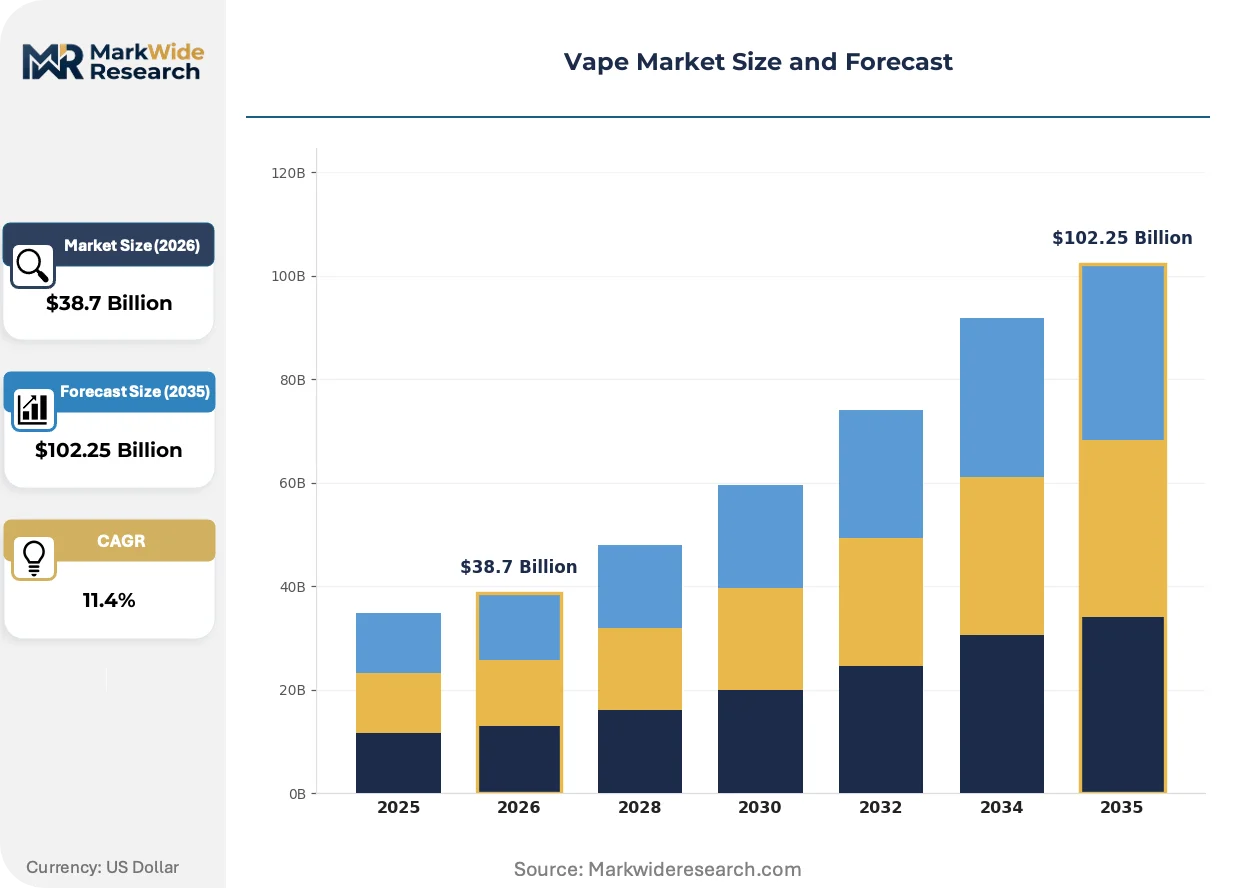
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $102.25 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disposable, Pod System, Box Mod, E-liquid Customer Type: Beginner, Intermediate, Advanced, Casual User Flavor Profile: Tobacco, Menthol, Fruit, Dessert Distribution Channel: Online Retail, Specialty Store, Convenience Store, Supermarket |
| Companies Covered | Altria Group, British American Tobacco, Philip Morris International, Juul Labs, Imperial Brands, Japan Tobacco, RELX Technology, SMOK Technology, NJOY Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vape Market Emerging Trajectories
Ceramic coil architectures, synthetic nicotine formulations, and closed-loop recycling mandates are converging to redefine product performance standards and environmental accountability across the value chain.
Ceramic heating elements are absorbing thermal stress from high-viscosity e-liquids while extending coil longevity beyond traditional cotton-wick systems. Premium pod-system manufacturers in the United States and Germany are adopting these substrates to reduce dry-hit complaints and warranty claims. The shift is absorbing margin pressure from flavor-ban uncertainty by anchoring differentiation on hardware reliability rather than liquid variety alone.
The EU Tobacco Products Directive is tightening nicotine concentration ceilings and mandating refill-container size limits, forcing manufacturers to reformulate for efficiency rather than potency. Disposable product lines face particular pressure as member states implement additional national restrictions beyond baseline harmonization. Germany and France are responding with accelerated transitions to rechargeable pod systems that circumvent single-use prohibitions.
Convenience-store buyers are consolidating SKU counts and demanding slotting-fee concessions from vape brands, compressing shelf-space competition. This consolidation favors suppliers with direct-store-delivery infrastructure and promotional funding depth. The United States exhibits the most visible channel contraction, with independent vape shops closing at accelerated rates as tobacco-convenience hybrids capture traffic.
Vape Market Segmentation
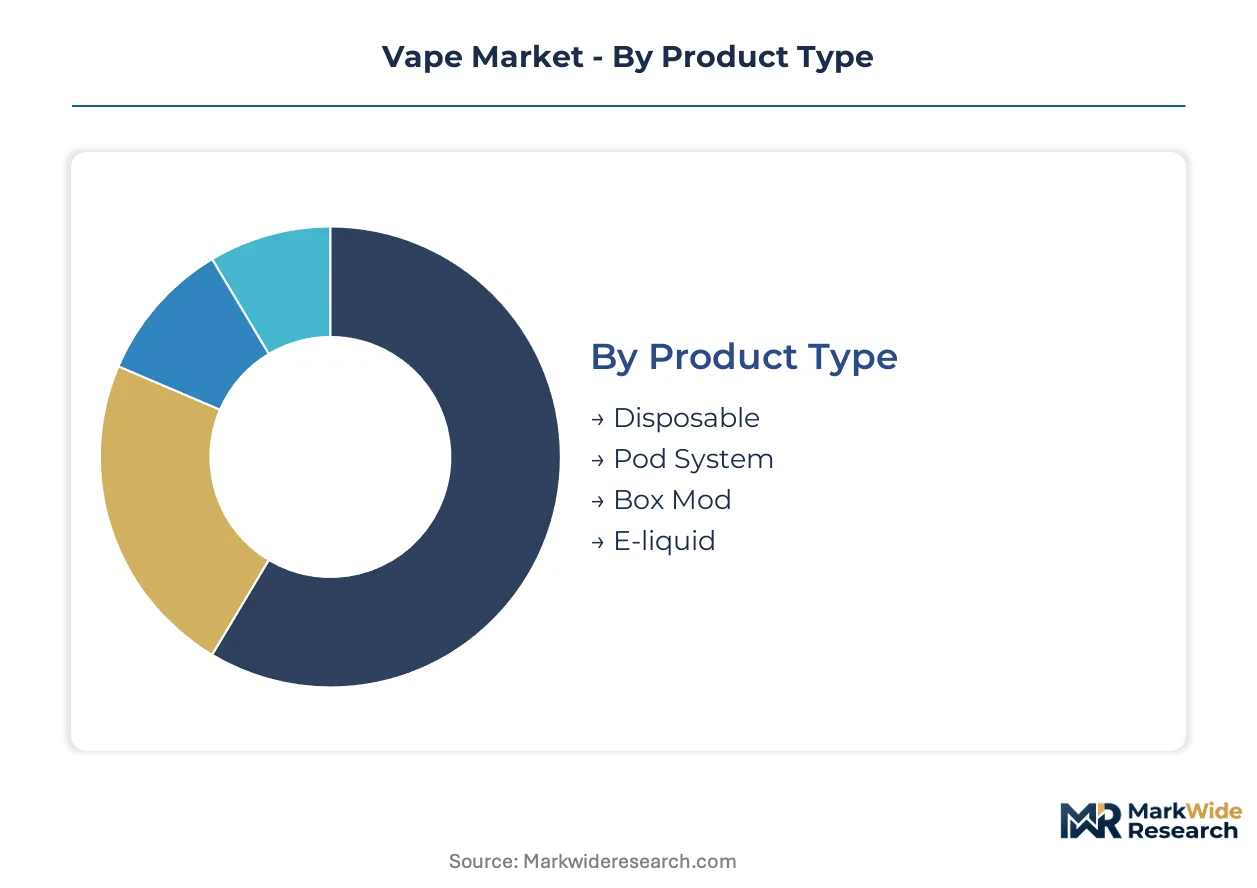
Product architecture and user sophistication stratify the vape market into distinct commercial battlegrounds. Each segmentation dimension carries unique margin profiles, regulatory exposure, and channel requirements that determine manufacturer positioning strategy.
Product Type:
Volume leadership sits with convenience-oriented formats, while premium economics concentrate in closed-system architectures with recurring consumables.
- Disposable:Single-use devices with integrated battery and pre-filled e-liquid reservoir, typically 300-800 puff capacity. Demand concentrates in United States convenience stores and United Kingdom petrol retail, driven by trial-seeking casual users and flavor-ban evasion tactics. Today's leader: Disposable. Tomorrow's challenger: Pod System.
- Pod System:Closed-system rechargeable devices with proprietary replaceable cartridges. Germany and France exhibit accelerating adoption as EU TPD refill-container limits push consumers toward compliant rechargeable formats. Recurring pod purchases generate 3-4x lifetime value versus disposables.
- Box Mod:Open-system devices with user-replaceable batteries, variable wattage control, and refillable tanks. Advanced hobbyists in United States vape shops and German specialty retailers sustain this segment despite regulatory compression on tank capacity.
- E-liquid:Standalone bottled formulations for open-system refilling, spanning 10ml to 120ml containers. United Kingdom independent retailers and German online channels dominate distribution, with shortfill formats circumventing TPD nicotine concentration ceilings.
Volume concentrates in disposables. Value extraction shifts toward pod systems.
Customer Type:
Experience level determines hardware complexity tolerance, nicotine concentration preference, and price elasticity across the purchase journey.
- Beginner:First-time users prioritizing simplicity and low initial outlay. United States gas station retail and United Kingdom pharmacy pilot programs capture this cohort, with prefilled pod systems dominating conversion from combustible tobacco.
- Intermediate:Established vapers seeking flavor variety without rebuildable complexity. German and French consumers in this tier drive rechargeable pod system growth, balancing customization against regulatory compliance burden.
- Advanced:Hobbyists building custom coils, mixing DIY e-liquid, and chasing vapor density. United States enthusiast forums and specialized retailers serve this niche, though FDA PMTA requirements constrain hardware innovation velocity.
- Casual User:Social or situational vapers without daily dependence patterns. United Kingdom nightlife venues and seasonal tourism corridors in Spain and Italy exhibit this demand, favoring discreet disposable formats.
Beginners deliver volume scale. Advanced users anchor premium pricing.
Flavor Profile:
Palate preference divides between switching-motivated tobacco fidelity and recreational flavor exploration, with regulatory targeting reshaping portfolio priorities.
- Tobacco:Flavor profiles mimicking combustible cigarette taste, historically dominant among smoking-cessation seekers. United States PMTA authorizations favor this category, though youth-appeal restrictions limit marketing latitude.
- Menthol:Cooling sensation variants with or without tobacco base, particularly prevalent among former menthol cigarette smokers. FDA flavor enforcement actions and state-level prohibitions compress this segment's addressable market.
- Fruit:Berry, citrus, and tropical flavor formulations capturing non-switcher recreational demand. United Kingdom and Germany lead European consumption, though pending restrictions in multiple US states threaten inventory exposure.
- Dessert:Custard, pastry, and confectionery-inspired profiles with high sweetness intensity. Adult recreational users in United States online channels and United Kingdom specialty retail sustain this category's premium positioning.
Fruit dominates current volume. Tobacco secures regulatory endurance.
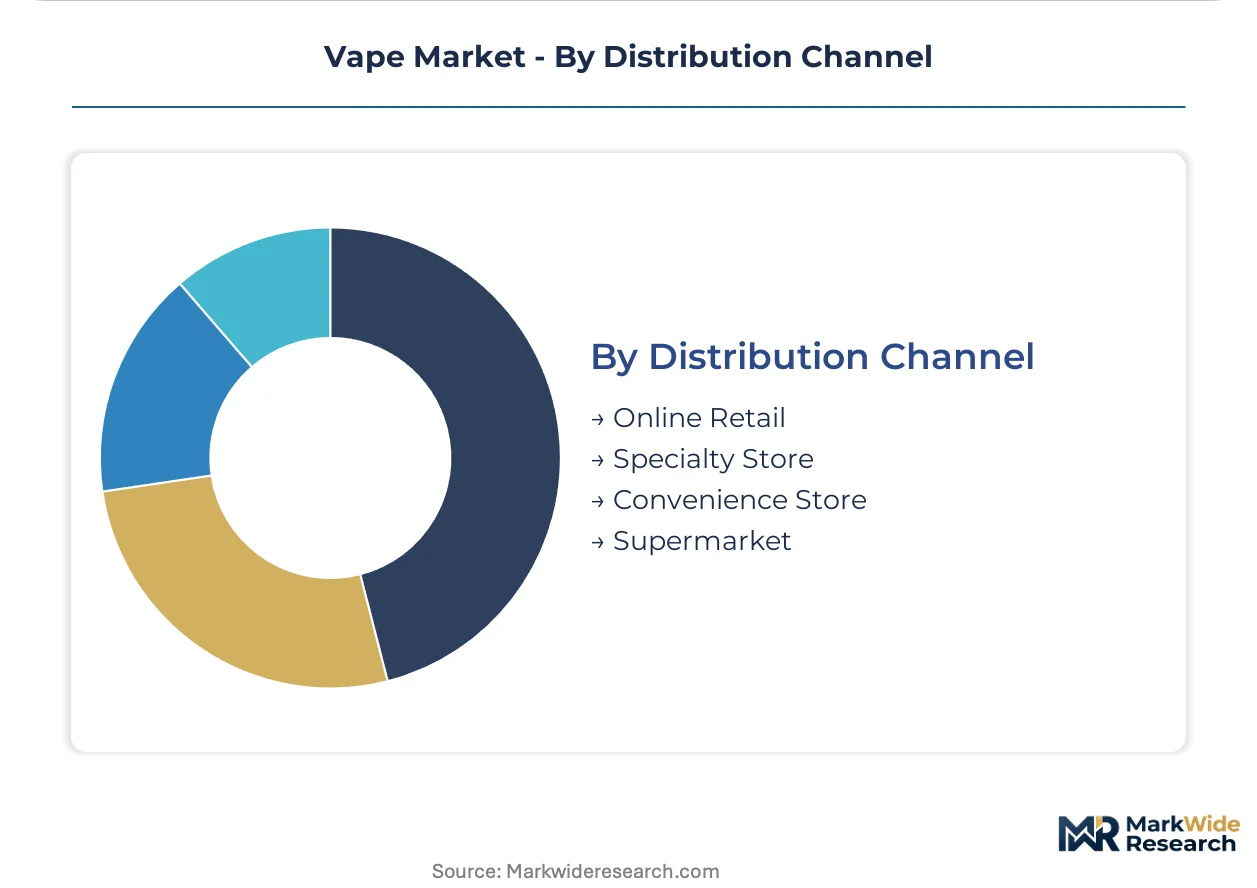
Distribution Channel:
Channel selection determines customer acquisition cost, age-verification compliance burden, and competitive density for shelf space.
- Online Retail:Direct-to-consumer and marketplace platforms offering broadest flavor and device selection. United Kingdom and Germany maintain robust e-commerce penetration, though age-verification technology requirements elevate operational complexity.
- Specialty Store:Dedicated vape shops providing hands-on device consultation and coil-building services. United States independent operators face consolidation pressure as tobacco-convenience hybrids capture traffic.
- Convenience Store:Petrol stations and tobacco-forward retailers emphasizing disposable and prefilled pod accessibility. United States c-store chains rationalize SKU counts, demanding slotting fees and direct-store-delivery infrastructure.
- Supermarket:Mass-market retail with limited assortment focused on closed-system pod brands. United Kingdom pharmacy and grocery pilots for medically licensed products signal potential channel expansion.
Convenience stores drive unit velocity. Specialty retail preserves margin.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The vape industry traces its commercial origins to China, where Shenzhen's electronics manufacturing ecosystem first scaled battery-powered inhalation devices for export markets in the late 2000s. This foundation established the supply chain architecture that now feeds demand centers across North America and Western Europe. Distribution today concentrates in jurisdictions with clarified reduced-risk nicotine frameworks.
United States
Gas station chains and convenience-store networks drive unit velocity for disposable formats, particularly in Florida, Texas, and California metropolitan corridors. The FDA's PMTA pathway determines market access, with authorization decisions reshaping permissible flavor portfolios and nicotine concentrations. Los Angeles and Miami retail clusters exhibit the highest per-capita consumption of fruit and dessert flavor profiles among adult recreational users.
Germany
Pharmacy retail pilots and specialized vape shops in Berlin, Hamburg, and Munich sustain rechargeable pod-system growth as consumers migrate from disposable formats. The EU Tobacco Products Directive mandates refill-container size limits and nicotine concentration ceilings, forcing manufacturers to optimize formulation efficiency. Bavaria's industrial base hosts several e-liquid production facilities serving Central European distribution networks.
United Kingdom
Independent vape shops and online channels dominate distribution, with London, Manchester, and Birmingham retail clusters supporting the highest density of specialty operators. The MHRA compliance framework for medically licensed vaping products creates a pathway toward prescription reimbursement and institutional procurement. Liverpool and Glasgow municipalities have pioneered age-verification technology deployment in convenience-store channels.
Japan
Heated-tobacco products divert demand from liquid-based vapor systems in Tokyo, Osaka, and Nagoya metropolitan areas, compressing addressable market share for conventional vapes. The Ministry of Health, Labour and Welfare maintains stringent pharmaceutical classification requirements for nicotine-containing e-liquids. Fukuoka and Sapporo retail corridors exhibit residual demand for zero-nicotine recreational devices among younger adult demographics.
France
Tobacco shop networks and specialized retailers in Paris, Lyon, and Marseille distribute pod systems as EU TPD harmonization reduces cross-border regulatory friction. ANSM oversight of nicotine product safety standards elevates compliance documentation requirements for market entry. Toulouse and Nice industrial zones host contract manufacturing operations serving Southern European export markets.
Vape Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the vape value chain, creating a bifurcated structure where integrated tobacco conglomerates face specialized device manufacturers. The market exhibits tiered consolidation, with a handful of multinational firms controlling premium pod-system segments while mid-tier specialists populate disposable and open-system categories. Three archetypes dominate: diversified tobacco incumbents pivoting toward smoke-free portfolios, dedicated vape-native hardware specialists, and contract manufacturers serving white-label demand. Competitive dynamics center on regulatory submission capacity and direct-store-delivery infrastructure rather than manufacturing scale alone.
Within the tobacco incumbent tier, Altria Group, British American Tobacco, and Philip Morris International exemplify the smoke-free transition archetype, leveraging existing regulatory affairs capabilities and distribution relationships to navigate PMTA and TPD compliance pathways. These firms occupy positions that emphasize portfolio diversification across heated-tobacco, vapor, and oral nicotine formats. Among vape-native specialists, RELX Technology and Juul Labs represent the closed-system pod architecture model, anchoring recurring revenue strategies through proprietary cartridge economics. NJOY Holdings sits within the independent challenger segment, competing on regulatory authorization velocity and flavor portfolio differentiation.
| Leading Market Players |
|---|
| Altria Group |
| British American Tobacco |
| Philip Morris International |
| Juul Labs |
| Imperial Brands |
| Japan Tobacco |
| RELX Technology |
| SMOK Technology |
| NJOY Holdings |
| Others |
Supply Flow & Price Mechanics
The EU's WEEE directive on electronic waste recovery gates qualified supply access and premium-tier pricing power for vape manufacturers seeking pharmacy and healthcare retail placement in Germany and the United Kingdom. Compliance with extended producer responsibility frameworks separates certified suppliers commanding slotting-fee leverage from gray-market operators facing inventory seizures.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies the vape market by hardware sophistication and consumables bundling. Premium pod systems anchored by ceramic coil architectures and Bluetooth connectivity extract 3-4x lifetime value against disposables, while price erosion runs through convenience-store disposable tiers as SKU rationalization intensifies slotting-fee negotiations. Beginners and casual users exhibit highest price sensitivity, driving volume through gas station chains, whereas advanced hobbyists sustain premium positioning in specialty retail.
Supply Chain Analysis
Single-source vulnerability sits with lithium-ion battery cell production concentrated in China, South Korea, and Japan, where cathode chemistry suppliers feed Shenzhen assembly operations. Vegetable glycerin and propylene glycol feedstock costs hinge on biodiesel market volatility, while ceramic heating element substrates draw from specialized Japanese and German ceramics manufacturers. Tariff exposure on Chinese electronics imports threatens margin stability for US-bound finished goods. Distribution runs through direct-store-delivery networks to convenience chains and tobacco-forward hybrids, with independent vape shops consolidating toward fewer, larger distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The vape market functions as a stable compounder, with regulatory clarity in reduced-risk nicotine frameworks driving steady replacement demand and consumables attachment across pod-system formats.
For Market Incumbents: Hedge against heated-tobacco and nicotine pouch substitution by accelerating medically licensed product pathways under MHRA frameworks, while securing backward integration into e-liquid formulation capacity in Bavaria and North Carolina to defend margin compression from flavor-ban volatility. For New Entrants and Emerging Players: Launch via pharmacy retail pilots in German metropolitan corridors, exploiting underpenetrated healthcare distribution channels where prescription reimbursement pathways create institutional procurement moats against convenience-store congestion. For Investors and Strategic Acquirers: Roll-up economics work for mid-tier pod-system specialists with MHRA notification compliance and direct-store-delivery infrastructure because FDA PMTA submission costs have stranded non-compliant competitors, creating distressed acquisition targets. Watch FDA authorization velocity for synthetic nicotine formulations as the inflection signal for portfolio rebalancing toward regulatory-durable assets.| Strategic Initiative | Industry Significance |
|---|---|
| Medically Licensed Product Development | MHRA compliance opens prescription reimbursement channels in United Kingdom pharmacy networks. |
| Ceramic Coil Architecture Adoption | Japanese substrate suppliers extend hardware longevity beyond cotton-wick warranty exposure. |
| Direct-Store-Delivery Expansion | Tobacco-convenience hybrid chains demand slotting-fee depth that DSD infrastructure satisfies. |
| Synthetic Nicotine Formulation Pivot | FDA PMTA scrutiny of tobacco-derived nicotine creates regulatory arbitrage for laboratory-synthesized alternatives. |
| Closed-Loop Recycling Program | WEEE directive compliance secures pharmacy retail placement against non-certified competitors in Germany. |
Methodological Framework
Coverage spans North America, Western Europe, and Asia-Pacific, with primary inputs from each region combining structured interviews with regulatory affairs directors at multinational tobacco incumbents, vape-native hardware specialists, e-liquid formulation chemists, convenience-store category buyers, and pharmacy procurement officers. Secondary validation draws from FDA PMTA submission databases, EU TPD notification registries, MHRA product licensing records, and customs trade data on vaping device imports. Bottom-up volume modeling triangulates against top-down category spend estimates from retail audit panels.
Granularity-level modeling disaggregates volume and value across product architecture, user sophistication tier, flavor profile, and distribution channel, with additional segmentation by regional regulatory cluster reflecting FDA, EU TPD, and MHRA compliance frameworks. CAGRs derive from trend extrapolation moderated by regulatory event probability weighting, with inputs including PMTA authorization timelines, TPD refill-container limit enforcement patterns, and heated-tobacco substitution elasticity estimates across the projection horizon.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated flavor-ban adoption or synthetic nicotine reclassification by FDA. The analysis reflects assumptions on regulatory enforcement intensity, consumer substitution elasticities, and supply chain reconfiguration timelines. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
Europe Smart TV Market
Consumer Electronics
In-Ear-Monitors (Iems) Market
Consumer Electronics
Smartphone Screen Protector Market
Consumer Electronics
Vape Cartridge Market
Consumer Electronics
Portable Stick Market
Consumer Electronics
Dual Screen Laptops Market
Consumer Electronics
Action Camera Market
Consumer Electronics
Stress Ball Market
Consumer Electronics
True Wireless Stereo Market
Consumer Electronics
Global Tablet Keyboards Market
Consumer Electronics
Portable Media Player Market
Consumer Electronics
Gaming PC Market
Consumer Electronics
Consumer Electronics Retail Market
Consumer Electronics
Mannequin Head Market
Consumer Electronics
Smart TV Sticks Market
Consumer Electronics
Global Smart Outdoor TV Market