
 Consumer Electronics Electric Motor Market | 2026-2036
Consumer Electronics Electric Motor Market Size, Share, and Industry Trends Forecast 2026-2036
Consumer Electronics Electric Motor Market Outlook
Asset-light contract manufacturing and equipment leasing is fragmenting competitive dynamics across the consumer electronics electric motor landscape. Nidec Corporation leverages its vertical integration in hard disk drive spindle motors to sustain pricing power in precision micro-motor segments. Johnson Electric Holdings Limited anchors its position through specialized manufacturing of automotive-grade motors that cross-sell into consumer applications. Siemens AG competes by extending industrial automation expertise into compact, high-efficiency motor designs for premium home appliances.
Consumer electronics electric motors are compact electromechanical devices typically operating below 500 watts, converting electrical energy into mechanical motion through electromagnetic induction in wound stators and permanent magnet or induction rotors, primarily enabling motion control in portable and stationary consumer products. DC motors, particularly brushless variants, occupy the fastest-expanding margin pool as efficiency mandates and battery-powered portability requirements intensify across personal devices and home appliances. Stepper motors dominate precision positioning applications in cameras, printers, and optical drives where discrete angular control remains essential. Servo motors command premium positioning in high-end automotive systems and professional audio equipment where closed-loop feedback ensures exacting performance.
China's MIIT enforces GB motor efficiency standards that compel manufacturers to redesign electromagnetic architectures and material selections. Japan's METI and JIS certification frameworks shape product reliability benchmarks that govern access to premium consumer electronics supply chains. The EU F-Gas Regulation and REACH compliance requirements constrain insulation material choices and thermal management designs for motors entering European consumer markets. Stakeholders must monitor how regional efficiency mandates diverge and decide whether to platform standardized designs or fragment production across compliance jurisdictions.
Market Dynamics
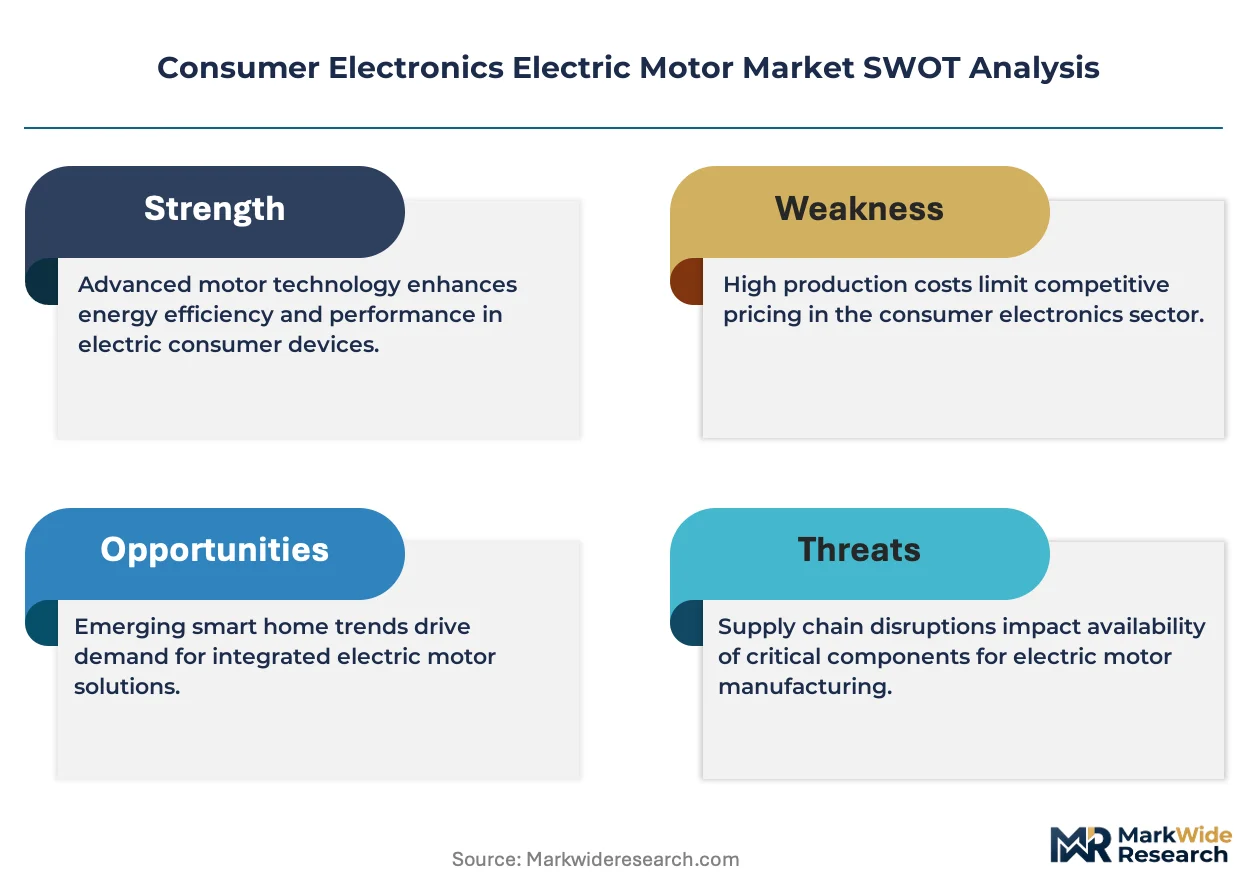
Brushless DC motor architectures are displacing brushed designs across portable electronics as China's GB efficiency standards and battery density imperatives force electromagnetic redesigns. This technology transition concentrates procurement leverage among East Asian winding equipment suppliers while fragmenting legacy motor assembly capacity.
Growth Catalysts
- China's dual carbon goals:Beijing's MIIT mandates compel motor manufacturers to redesign stator laminations and magnet configurations, accelerating premium brushless DC adoption in personal devices and home appliances.
- Portable audio equipment:TWS earbuds and smart speakers require micro-motors below 2 watts with extreme power density, pulling precision winding capabilities from hard disk drive supply chains into consumer electronics.
- Permanent magnet material advances:Neodymium-iron-boron formulations with reduced dysprosium content enable cost-efficient high-torque densities for smartphone haptic feedback and camera autofocus modules.
Market Restraints
- Rare earth supply concentration:Over 80 percent of processed neodymium and dysprosium originates from Chinese refining operations, exposing motor manufacturers to export quota volatility and geopolitical supply interruptions.
- Copper price volatility:Winding wire constitutes 15-25 percent of micro-motor bill-of-materials, with LME copper fluctuations compressing margins for fixed-price consumer electronics contracts.
- Technical miniaturization limits:Thermal dissipation constraints in sub-10mm motor diameters prevent power scaling for next-generation AR glasses and hearables, capping performance envelopes.
Strategic Opportunities
- India's PLI scheme for electronics manufacturing:New Delhi's production-linked incentives attract motor winding and magnet assembly investments, creating alternative supply nodes to China-dominant rare earth processing.
- Wearable health monitoring:Smart rings and continuous glucose monitors require silent vibration motors below 50 milliwatts, opening premium positioning for specialized Japanese and South Korean suppliers.
- EU F-Gas Regulation phase-down:Refrigerant constraints in heat pump compressors create demand for high-efficiency variable-speed motors in premium home appliances, favoring European appliance OEMs with captive motor design.
Industry Challenges
- Electromagnetic simulation talent scarcity:Finite element analysis expertise for thermal-magnetic co-design concentrates among aging specialists in Japanese trading houses and German industrial software consultancies, constraining new product development timelines.
- Multi-jurisdiction certification complexity:Simultaneous compliance with China's GB standards, Japan's JIS frameworks, and EU CE marking requirements extends validation cycles by 8-14 months for platform motor designs.
- Legacy brushed motor inventory stranding:Contract manufacturers in Vietnam and Indonesia face write-downs on winding equipment optimized for commutator architectures as buyers pivot to brushless platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Consumer Electronics Electric Motor Market |
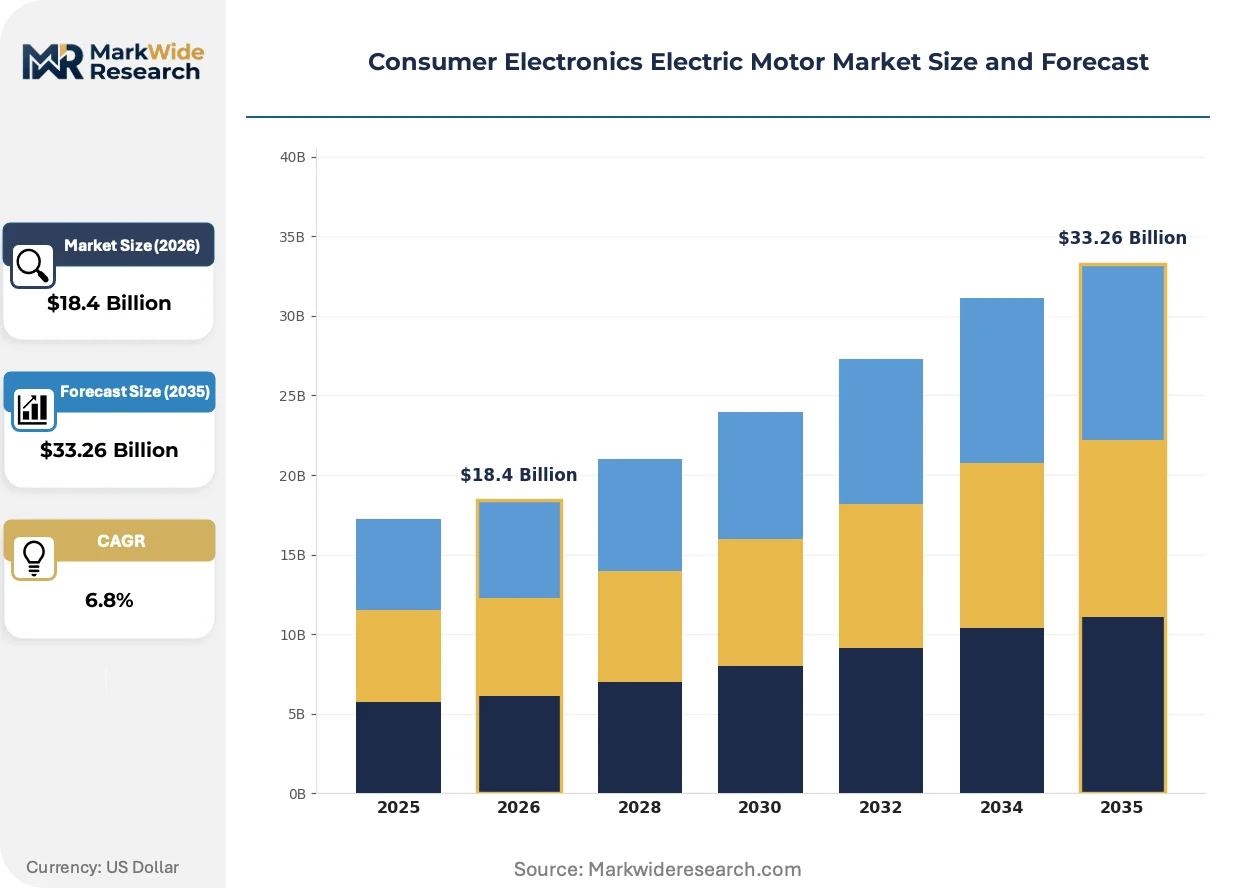
| Market Size in 2026 | $18.4 Billion |
| Market Size in 2035 | $33.26 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: AC Motors, DC Motors, Stepper Motors, Servo Motors End User: Home Appliances, Automotive Systems, Industrial Equipment, Personal Devices Power Rating: Low Power, Medium Power, High Power, Ultra High Power Installation: Integrated, Standalone, Modular, Customizable |
| Companies Covered | Nidec Corporation, Panasonic Corporation, Siemens AG, Johnson Electric Holdings Limited, Emerson Electric, Toshiba Corporation, ABB Ltd, WEG, AMETEK Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Consumer Electronics Electric Motor Market Strategic Shifts
Motor electromagnetic architectures are converging with power electronics and thermal management systems, eroding traditional component boundaries. This integration is compressing supplier tiers and relocating value capture toward system-level designers.
Amorphous metal stator laminations are hybridizing conventional silicon steel motor cores with glassy alloy ribbons that reduce core losses by 60-70 percent. Premium robot vacuum and cordless appliance manufacturers in Japan and Germany are adopting these materials despite 3-4x material cost premiums. The technology is hybridizing motor efficiency benchmarks and supplier qualification requirements, forcing winding houses to retool lamination handling equipment.
The EU F-Gas Regulation and accompanying Ecodesign requirements are mandating minimum efficiency indexes for motor-driven appliances entering European markets. Brussels' enforcement is eliminating single-speed induction motors from washing machines and dishwashers by 2027. Compressor and pump OEMs are responding with variable-frequency drive integration, shifting procurement toward integrated motor-drive subsystems rather than discrete components.
Contract manufacturers are consolidating purchasing of precision bearings and magnet assemblies into multi-year framework agreements with Japanese and Chinese tier-one suppliers. This behavior concentrates supply risk among three dominant bearing houses while squeezing second-tier winding shops on component access. The shift is most visible in Shenzhen and Dongguan electronics corridors, where smartphone motor procurement has shifted from spot-market purchasing to captive supplier development programs.
Consumer Electronics Electric Motor Market Segmentation
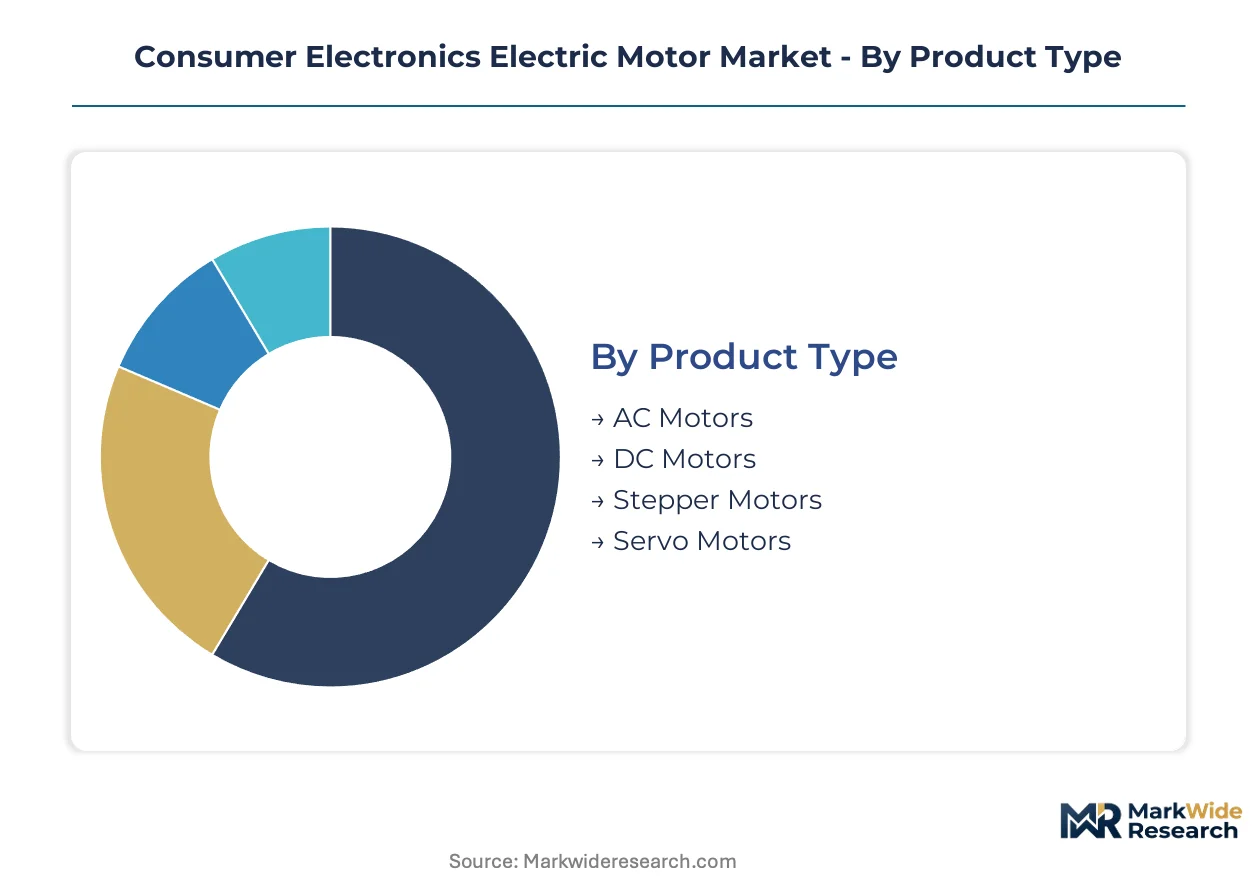
Segmentation in consumer electronics electric motors reveals how procurement leverage concentrates around specific electromagnetic architectures and end-use requirements. Motor specifications diverge sharply between portable personal devices demanding sub-watt precision and stationary home appliances requiring thermal durability.
Product Type:
After-sales-service intensity varies dramatically across motor architectures, with brushed DC designs requiring periodic commutator maintenance while brushless platforms demand specialized drive electronics replacement.
- DC Motors:Brushless variants dominate portable electronics through permanent magnet rotors and electronic commutation eliminating mechanical wear. China's GB efficiency mandates and TWS earbud proliferation concentrate demand in Shenzhen and Dongguan manufacturing corridors. By volume, DC Motors lead. By growth pace, brushless architectures are expanding most quickly.
- Stepper Motors:Hybrid stepper designs with toothed rotors enable discrete angular positioning without closed-loop feedback. Smartphone camera autofocus and optical image stabilization modules in Japanese and South Korean supply chains drive procurement concentration. Thermal management limitations in sub-10mm diameters constrain power scaling for AR glasses applications.
- AC Motors:Single-phase induction designs persist in cost-optimized home appliances with direct mains connection eliminating drive electronics.
- Servo Motors:Closed-loop feedback systems with encoder integration command premium positioning in professional audio equipment and high-end automotive interfaces.
Margin pools concentrate in brushless DC and servo architectures where electromagnetic design expertise creates supplier differentiation.
End User:
Application-specific reliability requirements fragment motor procurement, with automotive-grade validation cycles extending 18-24 months versus 6-9 months for personal devices.
- Personal Devices:Smartphones, wearables, and TWS earbuds require micro-motors below 2 watts with extreme power density. Haptic feedback modules and camera autofocus mechanisms in East Asian manufacturing clusters pull precision winding capabilities from hard disk drive supply chains. By volume, Home Appliances lead. By growth pace, Personal Devices are gaining share fastest.
- Home Appliances:Robot vacuums, cordless stick vacuums, and kitchen equipment demand variable-speed motors with integrated power electronics. EU F-Gas Regulation phase-downs and Ecodesign requirements are eliminating single-speed induction motors from washing machines and dishwashers.
- Automotive Systems:Seat adjustment, mirror positioning, and HVAC flap actuation require automotive-grade reliability certification under AEC-Q100 standards.
- Industrial Equipment:Test and measurement instruments, semiconductor handling systems, and laboratory automation deploy precision motors with extended operational lifespans.
Procurement leverage shifts toward personal device OEMs as volume concentration accelerates supplier consolidation.
Power Rating:
Cost structures scale non-linearly with power output, with ultra-high-power designs requiring rare-earth magnet formulations that concentrate supply risk.
- Low Power:Motors below 10 watts dominate smartphone haptic feedback and wearable vibration alerts. Neodymium-iron-boron formulations with reduced dysprosium content enable cost-efficient torque density for sub-50 milliwatt smart ring applications.
- Medium Power:10-100 watt range serves cordless appliances and portable audio equipment where battery voltage constraints shape electromagnetic design.
- High Power:100-500 watt motors in robot vacuums and premium kitchen equipment require thermal management integration with appliance housings.
- Ultra High Power:Specialized industrial and professional audio applications exceed 500 watts with liquid cooling and advanced lamination materials.
Technology transition concentrates in low and medium power tiers as efficiency mandates and battery portability reshape electromagnetic architectures.
Installation:
System integration depth determines supplier tier positioning, with integrated motor-drive subsystems capturing value from discrete component vendors.
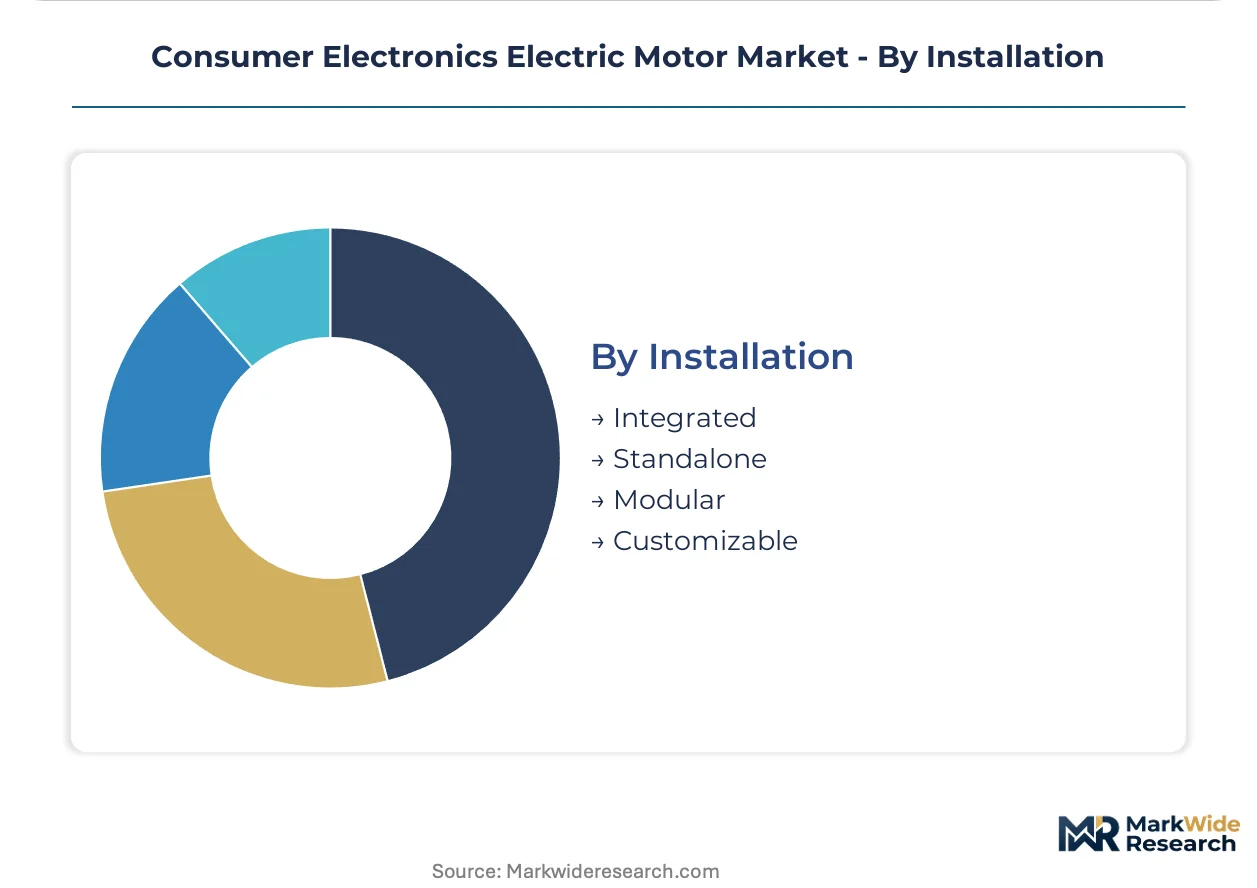
- Integrated:Motor, driver electronics, and thermal management co-packaged into sealed subsystems. EU appliance OEMs favor integrated designs for variable-speed compressor and pump applications under F-Gas Regulation compliance timelines.
- Standalone:Discrete motor units with external drive electronics persist in cost-optimized consumer products and repair-serviceable equipment.
- Modular:Standardized mechanical interfaces enable platform motor designs across multiple product lines, reducing certification burden for multi-jurisdiction compliance.
- Customizable:Application-specific winding configurations, shaft geometries, and connector placements for specialized industrial and medical device integration.
Procurement patterns favor integrated and modular architectures as appliance OEMs consolidate supplier tiers and internalize motor-drive system design.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
East Asian manufacturing corridors generate surplus precision motor capacity that exports to North American and European appliance assembly plants, while importing rare-earth magnet feedstock from Chinese refining operations. This trade configuration concentrates value capture in winding equipment and drive electronics, with raw material dependency creating persistent current-account exposure for Japanese and South Korean motor fabricators.
China
Smartphone haptic modules and TWS earbud micro-motors pull demand through Shenzhen and Dongguan electronics corridors. MIIT enforces GB motor efficiency standards that compel stator lamination redesigns and accelerate brushless DC adoption across personal device manufacturing. Dongguan's precision winding clusters now supply 70 percent of global smartphone vibration motor demand.
Japan
Camera autofocus mechanisms and optical image stabilization modules in hybrid stepper designs drive procurement from Nagoya and Osaka precision manufacturing bases. METI and JIS certification frameworks govern reliability benchmarks that filter access to premium consumer electronics supply chains. Tokyo-Yokohama corridor specialists retain finite element analysis talent for thermal-magnetic co-design in sub-10mm motor diameters.
South Korea
Wearable health monitoring devices requiring silent vibration motors below 50 milliwatts expand addressable demand for Seoul-Incheon manufacturing complexes. The country's national industrial regulator enforces efficiency benchmarks aligned with export market requirements. Busan-Ulsan bearing and magnet assembly suppliers consolidate multi-year framework agreements with smartphone OEMs.
Germany
Premium home appliance OEMs integrate variable-speed motor-drive subsystems for EU F-Gas Regulation compliance in washing machines and heat pump compressors. Ecodesign requirements eliminate single-speed induction motors from dishwashers by 2027. Bavarian and Baden-Württemberg industrial automation specialists extend expertise into compact high-efficiency designs.
United States
Professional audio equipment and high-end automotive interfaces command closed-loop servo motor procurement with extended validation cycles. EPA efficiency guidelines and FCC electromagnetic compatibility requirements shape thermal management and insulation material selections. Midwest appliance assembly plants import precision wound stators from East Asian contract manufacturers.
Consumer Electronics Electric Motor Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in winding and magnet assembly. The vendor base concentrates around three bearing houses and five dominant winding equipment suppliers, with second-tier shops facing component access compression. Two strategic archetypes prevail: vertically integrated precision motor specialists capturing margin in micro-actuator segments, and diversified industrial conglomerates cross-selling automation expertise into consumer applications. Competitive moves center on captive supplier development programs and multi-year magnet assembly framework agreements.
Among Japanese precision motor specialists, Nidec Corporation and Panasonic Corporation exemplify vertical integration strategies that sustain pricing power in hard disk drive spindle motor segments now repurposed for smartphone haptic applications. Johnson Electric Holdings Limited anchors the Hong Kong-listed tier through automotive-grade motor manufacturing that cross-sells validation capabilities into consumer electronics procurement. These three entities represent distinct geographic and structural positioning within a market where electromagnetic design expertise creates supplier differentiation.
| Leading Market Players |
|---|
| Nidec Corporation |
| Panasonic Corporation |
| Siemens AG |
| Johnson Electric Holdings Limited |
| Emerson Electric |
| Toshiba Corporation |
| ABB Ltd |
| WEG |
| AMETEK Inc. |
| Others |
Value Chain & Pricing Dynamics
Shenzhen-Dongguan freight corridors carry precision-wound stator assemblies from contract manufacturers to appliance OEMs in Germany and the United States, with container rate volatility feeding directly into three-tier pricing stratification across premium brushless DC, standard induction, and economy brushed motor tiers.
Pricing Analysis
Industrial OEM buyers anchor a contract-based pricing structure where volume scale and GB efficiency certification tier determine unit economics. Price differentiation rests on magnet grade specification and thermal management integration depth. Cost compression in economy brushed tiers is intensifying because Vietnamese contract manufacturers compete on depreciated winding equipment. Personal device OEMs exhibit highest price sensitivity; professional audio equipment buyers accept premiums for closed-loop servo architectures.
Supply Chain Analysis
Foxconn, BYD Electronics, and Luxshare Precision hold concentrated capacity for micro-motor winding and magnet assembly across Shenzhen, Dongguan, and Vietnam border zones. Raw material flows draw from Chinese neodymium refining, Japanese bearing fabrication, and South Korean ferrite processing. Single-source vulnerability concentrates in dysprosium supply from Chinese state-owned refiners. Distribution runs through captive supplier development programs rather than spot-market procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brushless DC motor adoption sits at early-cycle expansion as China's GB efficiency mandates and TWS earbud proliferation force electromagnetic redesigns across personal device portfolios.
For Market Incumbents: Pre-empt commoditization in brushed motor segments by migrating capacity to integrated motor-drive subsystems for EU appliance OEMs facing F-Gas Regulation deadlines. Lock multi-year magnet assembly agreements with Japanese tier-one suppliers before rare earth export quotas tighten. Defend margin position through backward integration into amorphous metal lamination handling equipment. For New Entrants and Emerging Players: Build out precision winding capabilities for sub-50 milliwatt vibration motors serving wearable health monitoring in Seoul-Incheon and Tokyo-Yokohama corridors. India's PLI scheme for electronics manufacturing offers the most penetrable geography for greenfield magnet assembly investments. Pursue direct supplier qualification with smartphone OEMs bypassing established contract manufacturer tiers. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with captive consumer electronics motor divisions lacking scale focus. Long-term viability favors specialists with in-house finite element analysis talent for thermal-magnetic co-design. Watch for MIIT enforcement actions on GB standard compliance as inflection signal for brushless DC acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Magnet Assembly Framework Agreements | Multi-year contracts with Japanese tier-one suppliers lock rare earth access against Chinese export quota volatility. |
| Amorphous Metal Lamination Adoption | Glassy alloy ribbon integration reduces core losses for premium robot vacuum and cordless appliance OEMs in Japan and Germany. |
| Integrated Motor-Drive Subsystem Development | Co-packaged electronics capture value from discrete component vendors under EU F-Gas Regulation compliance timelines. |
| India PLI Scheme Manufacturing Investment | Production-linked incentives attract winding and magnet assembly capacity as alternative nodes to China-dominant processing. |
| Finite Element Analysis Talent Acquisition | Thermal-magnetic co-design expertise concentrates among aging specialists in Japanese trading houses and German consultancies. |
Study Parameters
Desk research of customs trade databases, MIIT regulatory filings, and SEC 10-K disclosures preceded structured interviews with motor procurement managers at smartphone OEMs, winding equipment specialists in Shenzhen-Dongguan corridors, and rare earth trading desk analysts. Primary fieldwork with appliance OEM platform engineers and contract manufacturing operations heads validated secondary findings. Bottom-up unit shipment estimates triangulated against top-down value projections.
Base-case assumptions held China's dual carbon enforcement trajectory and EU F-Gas Regulation phase-down schedules fixed while varying copper price bands and rare earth export quota stringency across the projection horizon. Segmentation modeling spanned motor architecture, power rating tier, installation type, and regional manufacturing cluster. CAGRs derived from regression analysis against historical efficiency mandate adoption curves and battery energy density improvement trajectories.
Stress conditions across neodymium price spikes, LME copper volatility, and MIIT enforcement intensity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions and risk factors including geopolitical supply interruption and electromagnetic simulation talent scarcity. Quarterly review of GB standard certification timelines and Indian PLI scheme disbursement rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
Consumer Electronics Market
Consumer Electronics
Digital Accessories Market
Consumer Electronics
United States Smart TV Market
Consumer Electronics
True Wireless Stereo Market
Consumer Electronics
Middle East and Africa Smartphones Market
Consumer Electronics
Used and Refurbished Smartphone Market
Consumer Electronics
TV Mirror Market
Consumer Electronics
Action Camera Market
Consumer Electronics
Headset Market
Consumer Electronics
Smart Audio Devices Market
Consumer Electronics
Portable Smart Speaker Market
Consumer Electronics
Silicone Sex Doll Market
Consumer Electronics
North America Refurbished and Used Mobile Phones Market
Consumer Electronics
Closed Back Studio Headphone Market
Consumer Electronics
Refurbished Electronics Market
Consumer Electronics
US Refurbished and Used Mobile Phones Market