
 North America Strategic Consulting Market | 2026-2036
North America Strategic Consulting Market Size, Share, and Industry Trends Forecast 2026-2036
North America Strategic Consulting Market Analytics
Talent scarcity among data scientists and AI implementation specialists is rotating consulting firms toward premium pricing for technical capabilities. McKinsey & Company leverages its advanced analytics division to capture complex transformation mandates. Boston Consulting Group anchors its competitive position through proprietary digital tools and specialized industry pods. Deloitte Touche Tohmatsu Limited extends its advisory footprint by integrating consulting with audit and tax compliance services.
Strategic consulting encompasses advisory services that diagnose organizational performance gaps, design operational restructuring plans, and guide capital deployment decisions using proprietary frameworks and primary research methodologies. Firms typically deliver recommendations through phased engagements spanning diagnostic assessment, solution design, and implementation support. Management Consulting and Strategy Consulting command the deepest margin pools due to C-suite access and recurring enterprise relationships. IT Consulting represents the fastest-expanding service category as cloud migration and cybersecurity imperatives intensify. Corporate Clients generate the most stable revenue base, while Government Agencies present accelerating opportunity under infrastructure and industrial policy programs.
The Securities and Exchange Commission shapes disclosure requirements that drive financial advisory demand, while the Federal Trade Commission's merger review standards compel pre-deal strategy work. State-level procurement regulations in California and New York add compliance complexity to public-sector consulting engagements. Stakeholders must monitor how artificial intelligence governance frameworks reshape the value proposition of human-delivered strategic advice.
Market Dynamics
The Inflation Reduction Act's domestic content provisions and clean energy incentives are redirecting capital allocation across United States healthcare and energy sectors, forcing advisory firms to rebuild sector expertise around subsidy compliance and supply chain restructuring.
Growth Catalysts
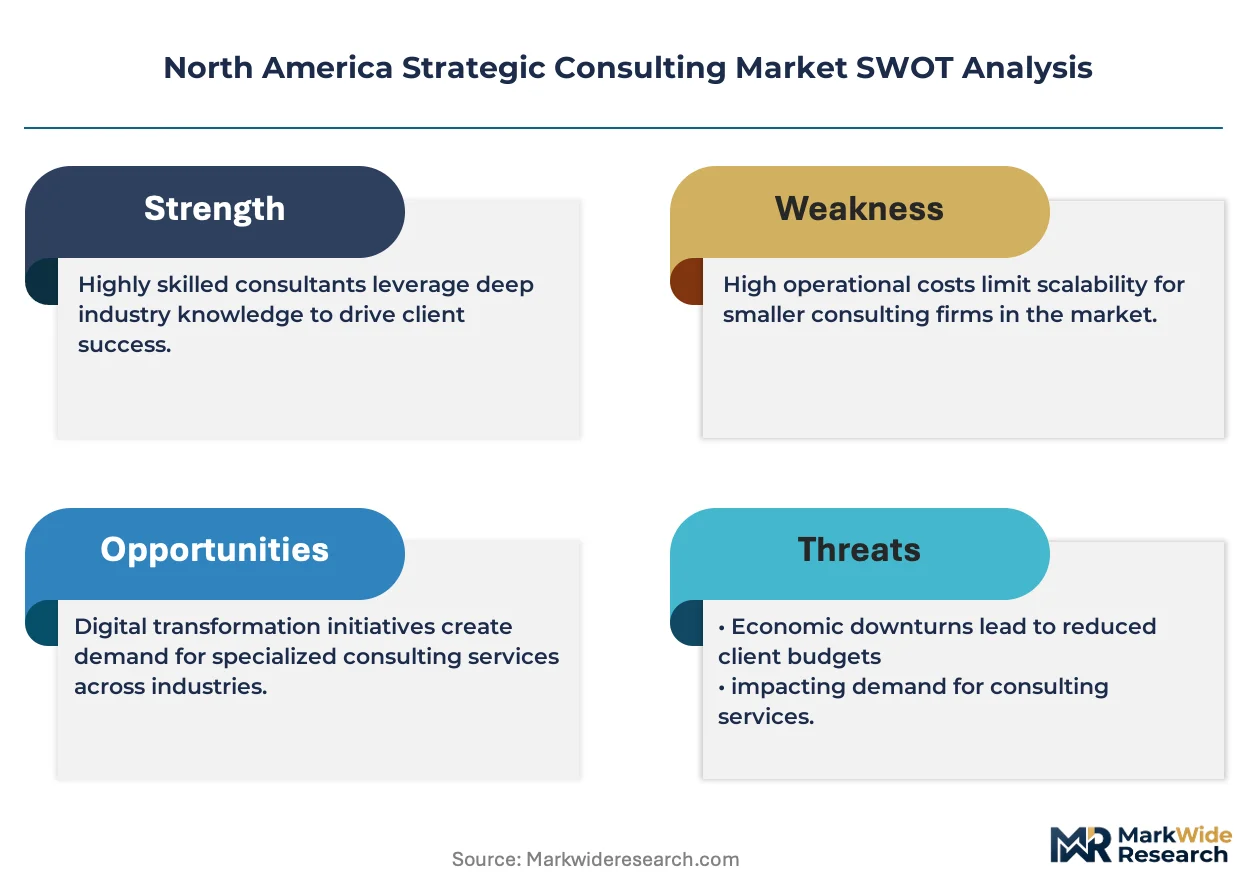
- IRA Clean Energy Incentives:Tax credits under the Inflation Reduction Act are triggering capital deployment reviews across renewable energy portfolios, requiring specialized advisory support for qualification documentation and supply chain verification.
- Healthcare Reimbursement Complexity:Medicare Advantage expansion and value-based care mandates are compelling United States hospital systems to retain external advisors for contract negotiation and clinical pathway redesign.
- Texas Corporate Headquarters Concentration:Energy sector consolidation around Houston and Dallas-Fort Worth is generating sustained demand for M&A advisory and post-merger integration support.
Market Restraints
- Data Scientist Talent Scarcity:Specialized AI implementation expertise commands compensation premiums that compress project margins and extend hiring timelines for technical engagements.
- California Procurement Regulations:State-level public-sector contracting rules impose compliance overhead that limits advisory firm participation in municipal and state agency RFPs.
- SEC Disclosure Requirements:Evolving climate risk and cybersecurity disclosure mandates create liability exposure for advisory firms certifying client compliance positions.
Strategic Opportunities
- Canadian Healthcare Digitalization:Provincial health authority modernization programs present underpenetrated demand for electronic health record transition and interoperability advisory.
- AI Governance Framework Development:Emerging Federal Trade Commission guidance on algorithmic accountability creates advisory white space for risk assessment and compliance architecture design.
- Cybersecurity-Strategy Convergence:Board-level cyber risk oversight requirements are merging IT security mandates with enterprise strategy planning, opening integrated engagement models.
Industry Challenges
- Cloud Migration Skill Gaps:Advisory firms face execution risk as legacy infrastructure specialists struggle to deliver against compressed hyperscaler transition timelines.
- Multi-Jurisdiction Compliance Stacking:Clients operating across United States state lines and Canadian provinces require harmonized advisory frameworks that increase delivery complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Strategic Consulting Market |
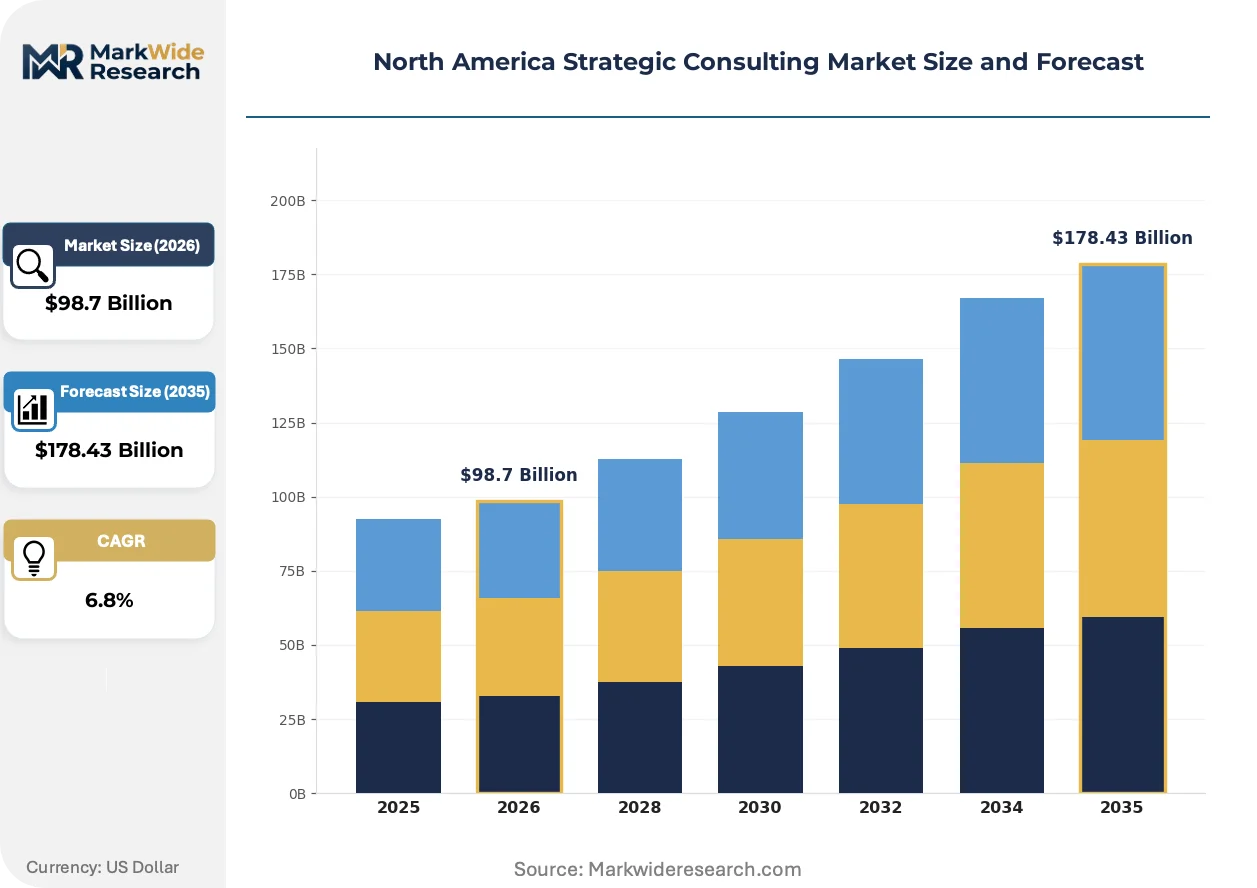
| Market Size in 2026 | $98.7 Billion |
| Market Size in 2035 | $178.43 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Management Consulting, IT Consulting, Financial Advisory, Strategy Consulting Client Type: Corporate Clients, Government Agencies, Non-Profit Organizations, Startups Industry Vertical: Finance, Healthcare, Technology, Retail Engagement Type: Project-Based, Retainer Agreements, Hourly Consulting, Workshops |
| Companies Covered | McKinsey & Company, Boston Consulting Group, Bain & Company, Accenture, Deloitte Touche Tohmatsu Limited, A.T. Kearney, PricewaterhouseCoopers, Ernst & Young, Oliver Wyman, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Strategic Consulting Market Evolving Landscape
Advisory delivery models are fragmenting between high-touch C-suite engagements and technology-enabled diagnostic platforms, with competitive position increasingly tied to proprietary data assets rather than relationship networks alone.
Generative AI diagnostic tools are bifurcating the market between premium strategy engagements requiring human judgment and commoditized analytics deliverables. Fortune 500 clients are piloting automated scenario modeling for capital allocation decisions, compressing timelines for traditional primary research phases. The technology is bifurcating service tiers, forcing established firms to defend margin pools through exclusive data partnerships and customized implementation support.
The Securities and Exchange Commission's climate risk disclosure rules are mandating scenario analysis capabilities that most internal corporate strategy teams lack. Industrial and energy sector clients must now quantify transition exposure across multi-decade horizons, driving advisory demand for specialized modeling infrastructure. United States publicly traded companies are responding by embedding external advisors into quarterly disclosure preparation workflows.
Corporate procurement functions are consolidating advisory spend under fewer preferred provider relationships with outcome-linked fee structures. Healthcare and financial services verticals are replacing time-and-materials contracts with fixed-fee transformation guarantees that transfer implementation risk to advisory firms. This compression is most visible in California and New York, where procurement centralization has reduced the number of active consulting relationships per enterprise by roughly half.
North America Strategic Consulting Market Segmentation
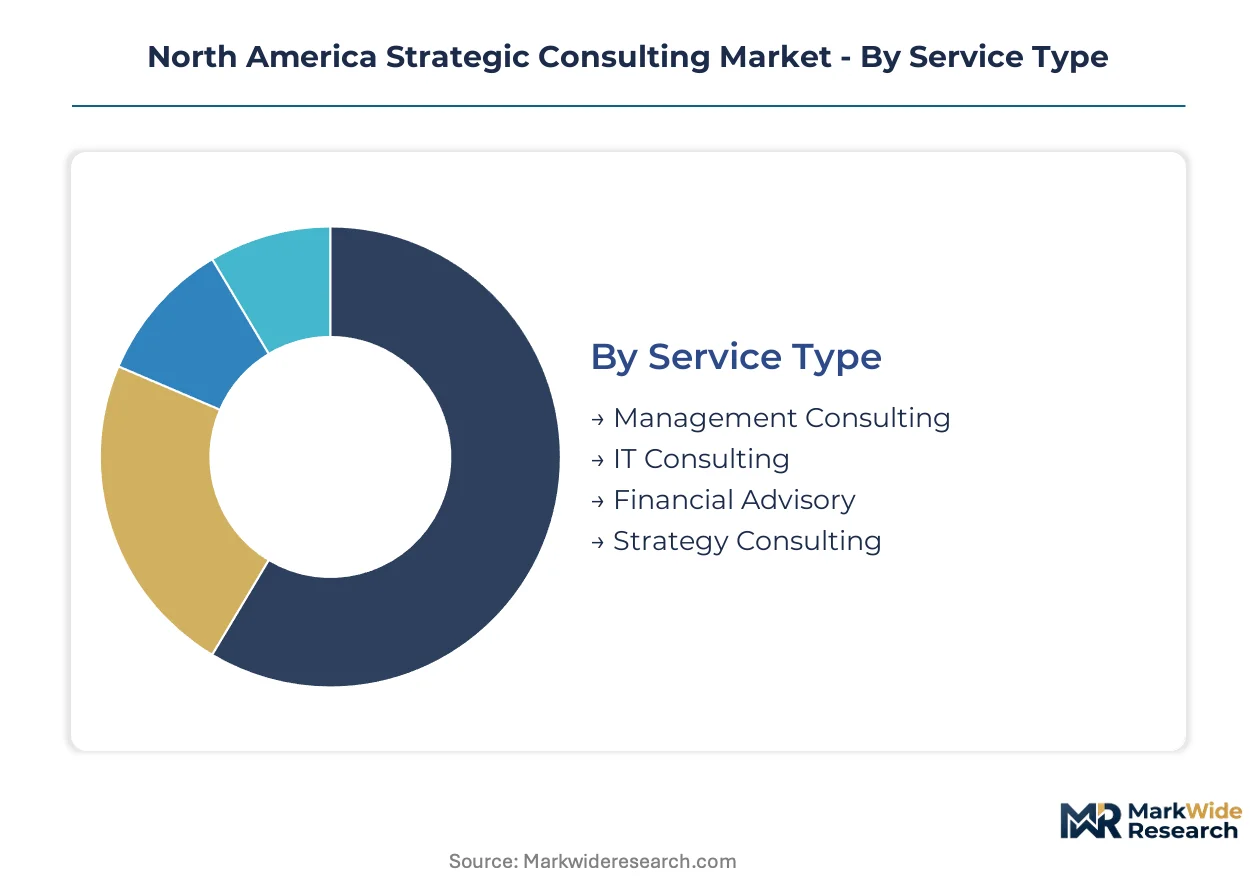
Strategic consulting engagements in North America fragment across service delivery models, client procurement patterns, and industry specialization requirements. Understanding these segmentation layers clarifies where advisory firms concentrate capability investments and how procurement functions structure vendor relationships.
Service Type:
Management Consulting and Strategy Consulting engagements flow through partner-led C-suite channels with multi-year relationship frameworks, while IT Consulting and Financial Advisory increasingly route through procurement-led RFP processes with outcome-linked fee structures.
- Management Consulting:Encompasses operational restructuring, organizational design, and performance improvement mandates. United States healthcare systems and Texas energy conglomerates drive sustained demand for post-merger integration and cost transformation programs under compressed timelines.
- Strategy Consulting:Focuses on market entry, competitive positioning, and capital allocation decisions using proprietary frameworks. California technology headquarters and Canadian pension funds generate the deepest engagements requiring board-level presentation cycles and primary research methodologies.
- IT Consulting:Cloud migration, cybersecurity architecture, and enterprise system implementation support. Procurement centralization in New York financial services is compressing vendor panels and shifting fee structures toward fixed-price transformation guarantees.
- Financial Advisory:M&A due diligence, valuation, and transaction structuring services. SEC disclosure requirements and FTC merger review standards are embedding external advisors into quarterly compliance workflows and pre-deal strategy phases.
By volume, Management Consulting leads. By growth pace, IT Consulting is expanding most quickly.
Client Type:
Corporate procurement functions are consolidating advisory spend under fewer relationships with risk-transfer fee models, while Government Agencies present accelerating opportunity under infrastructure and industrial policy programs with compliance-heavy contracting rules.
- Corporate Clients:Fortune 500 enterprises and mid-cap companies seeking operational transformation or transaction support. United States-based conglomerates in Texas and California are reducing active consulting relationships per enterprise by roughly half through procurement centralization initiatives.
- Government Agencies:Federal, state, and municipal entities navigating infrastructure deployment and regulatory compliance. California and New York state-level procurement regulations impose overhead that limits advisory firm participation in public-sector RFPs.
- Non-Profit Organizations:Healthcare systems, educational institutions, and charitable foundations requiring mission-aligned advisory support. Canadian provincial health authority modernization programs present underpenetrated demand for electronic health record transition consulting.
- Startups:Venture-backed companies seeking market entry strategy and scaling support. Technology sector concentration in Silicon Valley and Austin generates episodic demand for rapid commercialization and fundraising advisory.
Corporate Clients anchor revenue stability. Government Agencies are climbing the fastest as IRA and infrastructure programs expand.
Industry Vertical:
Healthcare and Finance verticals command premium pricing due to regulatory complexity, while Technology and Retail segments are rotating toward technology-enabled diagnostic platforms and automated scenario modeling tools.
- Finance:Banking, insurance, and asset management advisory encompassing risk transformation and regulatory compliance. SEC climate risk disclosure rules are mandating scenario analysis capabilities that internal strategy teams lack, embedding external advisors into quarterly preparation workflows.
- Healthcare:Hospital systems, payers, and pharmaceutical clients navigating reimbursement complexity and digital transformation. Medicare Advantage expansion and value-based care mandates in the United States are compelling contract negotiation and clinical pathway redesign advisory.
- Technology:Software, hardware, and platform companies requiring commercialization and scaling support. Generative AI diagnostic tools are bifurcating engagements between premium strategy work and commoditized analytics deliverables.
- Retail:Consumer goods and omnichannel operators seeking supply chain and customer analytics advisory. E-commerce platform transitions and last-mile optimization generate project-based demand with compressed timelines.
Finance captures the deepest margins. Healthcare is gaining share fastest on reimbursement complexity and IRA implementation.
Engagement Type:
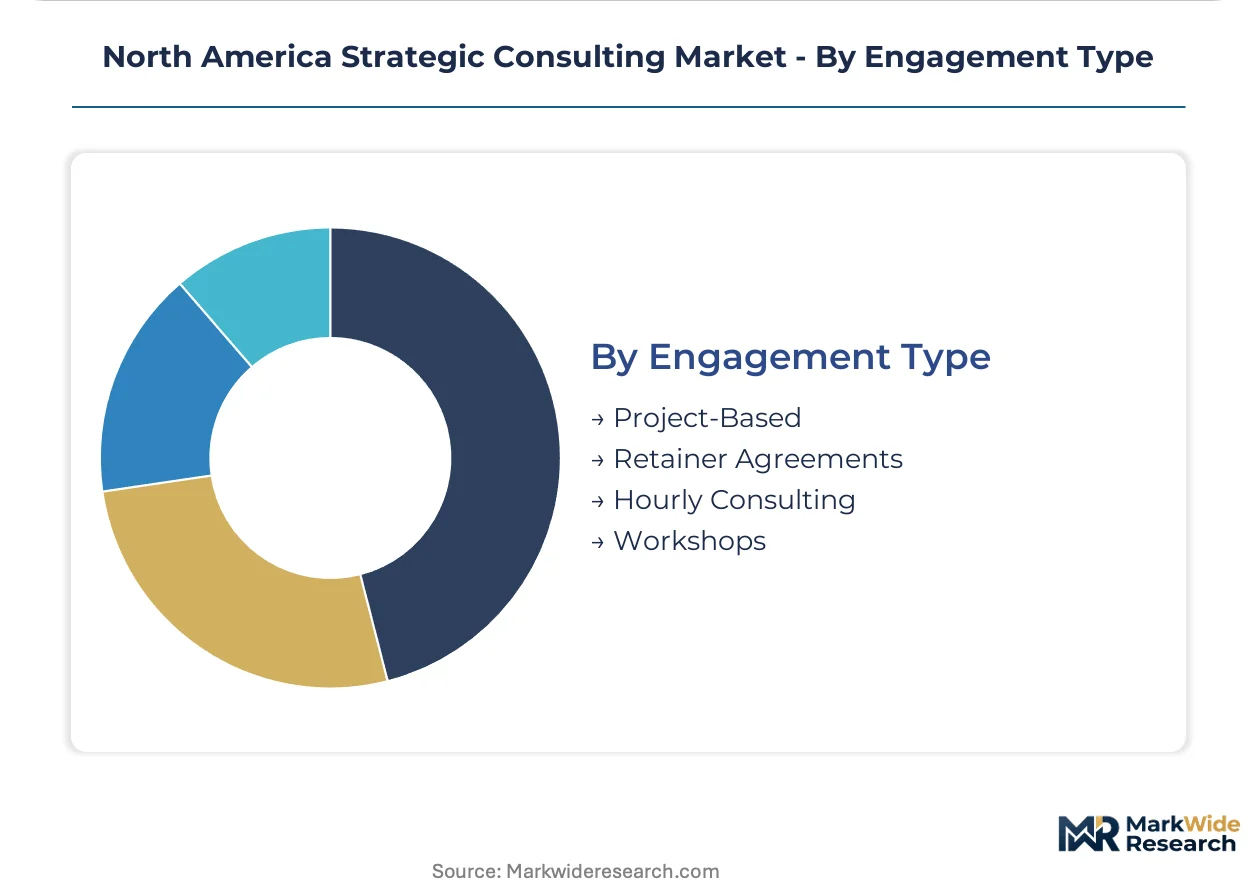
Project-Based and Retainer Agreements concentrate among established advisory relationships, while Hourly Consulting and Workshops serve episodic demand and capability-building mandates with lower switching costs.
- Project-Based:Defined-scope engagements with discrete deliverables and timeline milestones. Post-merger integration in Texas energy sector consolidation and IRA clean energy qualification documentation drive sustained demand for fixed-scope advisory.
- Retainer Agreements:Ongoing advisory relationships with dedicated partner access and priority staffing. C-suite access and recurring enterprise relationships in United States healthcare and financial services command the deepest margin pools.
- Hourly Consulting:Time-based billing for discrete expertise or interim executive support. Procurement centralization is displacing this model in favor of outcome-linked structures with implementation risk transfer.
- Workshops:Facilitated sessions for strategy alignment, capability building, or decision acceleration. Board-level cyber risk oversight requirements are merging IT security mandates with enterprise strategy planning in condensed workshop formats.
Project-Based engagements dominate contract volume. Retainer Agreements show the steepest expansion trajectory as procurement consolidates vendor relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Advisory consumption patterns diverge sharply across North America, with United States enterprises favoring long-term retainer relationships while Canadian clients emphasize project-based digital transformation mandates and Mexican operations concentrate on cross-border supply chain compliance.
United States
Healthcare systems and energy conglomerates drive the deepest contract volumes, with Medicare Advantage expansion and IRA clean energy incentives triggering sustained advisory demand. SEC climate risk disclosure rules embed external advisors into quarterly compliance workflows for publicly traded companies. Texas corporate headquarters in Houston and Dallas-Fort Worth generate concentrated M&A and post-merger integration mandates.
Canada
Provincial health authority modernization programs present underpenetrated demand for electronic health record transition and interoperability advisory. Health Canada procurement regulations impose compliance overhead that limits advisory firm participation in federal RFPs. Toronto and Calgary financial centers anchor wealth management and pension fund advisory relationships requiring board-level presentation cycles.
Mexico
Nearshoring manufacturing expansion and USMCA compliance requirements are accelerating demand for supply chain restructuring and cross-border tax advisory. The country's federal economic competition regulator shapes pre-deal strategy work for transactions involving United States buyers. Monterrey and Mexico City industrial corridors concentrate advisory engagements around automotive and aerospace supplier integration.
California
Technology headquarters and venture capital concentration generate episodic demand for rapid commercialization and fundraising advisory. State-level procurement regulations impose compliance complexity that limits advisory firm participation in municipal and state agency RFPs. Silicon Valley and Los Angeles metro areas drive premium pricing for AI implementation and digital transformation mandates.
New York Metro
Financial services procurement centralization is compressing vendor panels and shifting fee structures toward fixed-price transformation guarantees. FTC merger review standards compel pre-deal strategy work for transactions requiring regulatory clearance. Manhattan and Connecticut financial corridors anchor recurring enterprise relationships with outcome-linked fee structures.
North America Strategic Consulting Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the market consolidating around advisory firms that combine strategy consulting with implementation capabilities. The premium tier captures C-suite access through multi-year relationship frameworks, while mid-tier players compete on sector specialization and technology-enabled delivery models. Two dominant competitive moves are reshaping positioning: vertical integration into adjacent professional services and proprietary AI diagnostic platform development.
Within the integrated advisory tier, McKinsey & Company and Boston Consulting Group exemplify firms leveraging advanced analytics capabilities to capture complex transformation mandates. Deloitte Touche Tohmatsu Limited occupies a position bridging consulting with audit and tax compliance services, representing the multi-service archetype that extends advisory footprint through cross-selling integration. These three entities anchor the competitive structure, with their positioning reflecting broader industry segmentation between pure-play strategy boutiques and diversified professional services networks.
| Leading Market Players |
|---|
| McKinsey & Company |
| Boston Consulting Group |
| Bain & Company |
| Accenture |
| Deloitte Touche Tohmatsu Limited |
| A.T. Kearney |
| PricewaterhouseCoopers |
| Ernst & Young |
| Oliver Wyman |
| Others |
Value Network & Pricing Analysis
SEC climate risk disclosure mandates and FTC merger review standards simultaneously gate advisory firm qualification and stratify fee structures across the North America strategic consulting landscape. These regulatory frameworks compress margins for compliance-heavy engagements while amplifying pricing power for firms with specialized implementation capabilities.
Pricing Analysis
Long-term retainer agreements anchor the highest-value relationships in United States healthcare and financial services, while project-based structures dominate Canadian digital transformation mandates and Mexican cross-border advisory. Three-tier pricing structure across premium, standard, and economy levels separates partner-led C-suite engagements from staff-augmented implementation support and commoditized analytics deliverables. Pricing pressure stems from procurement centralization initiatives in California and New York that consolidate vendor panels and shift fee structures toward fixed-price transformation guarantees with risk transfer. Corporate clients exhibit the greatest price sensitivity for IT Consulting and cloud migration advisory, while Government Agencies demonstrate lower elasticity due to compliance-heavy contracting rules and limited qualified supplier pools.
Supply Chain Analysis
Port congestion along the Los Angeles-Long Beach corridor and container availability fluctuations on trans-Pacific trade lanes intermittently disrupt the inbound talent pipeline for specialized AI implementation and data science expertise. Advisory capability concentrates in the United States, Canada, and the United Kingdom, with talent sourcing drawing from elite business schools and technical universities in these jurisdictions. Project delivery rests on human capital inputs including partner-level relationship managers, engagement managers, and specialized subject matter experts in healthcare reimbursement and clean energy incentives. Single-source vulnerability emerges from concentrated dependence on top-tier MBA programs and technical institutes for pipeline talent. Distribution runs through direct partner networks, preferred provider relationships, and procurement-led RFP processes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized expertise scarcity in AI implementation and IRA subsidy compliance architecture constrains market expansion and concentrates margin capture among firms with proven delivery track records. This capability gap shapes competitive positioning across all stakeholder archetypes.
For Market Incumbents: Secure exclusive data partnerships with healthcare systems and energy conglomerates to defend margin pools against technology-enabled diagnostic platforms. Anchor implementation risk transfer capabilities through fixed-fee transformation guarantees that match procurement centralization demands in New York financial services. Build captive supply of data science talent through university pipeline investments and acquisition of boutique AI specialists.
For New Entrants and Emerging Players: Anchor in Canadian provincial health authority modernization programs where electronic health record transition advisory remains underpenetrated relative to United States markets. Target municipal and state agency RFPs in Texas where energy sector consolidation generates sustained post-merger integration demand. Pursue outcome-linked fee structures with mid-cap corporate clients seeking to bypass procurement centralization barriers at Fortune 500 enterprises.
For Investors and Strategic Acquirers: FTC algorithmic accountability guidance reshapes the acquisition landscape by elevating firms with AI governance framework capabilities above pure-play strategy boutiques. Long-term viability favors advisory platforms combining strategy consulting with implementation execution across healthcare and clean energy verticals. Monitor SEC climate risk disclosure enforcement intensity as the signal indicating expansion or contraction of specialized scenario analysis advisory demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary AI Diagnostic Platform Development | Generative AI tools bifurcate engagements between premium strategy and commoditized analytics deliverables. |
| Healthcare Reimbursement Specialization Buildout | Medicare Advantage expansion and value-based care mandates embed advisors into contract negotiation workflows. |
| IRA Clean Energy Advisory Capability | Tax credit qualification documentation and supply chain verification trigger specialized advisory demand. |
| Outcome-Linked Fee Structure Migration | Procurement centralization in California and New York compels risk transfer from clients to advisory firms. |
| Canadian Healthcare Digitalization Entry | Provincial health authority modernization programs present underpenetrated demand for interoperability advisory. |
Research Methodology
Cross-validation between primary interviews with consulting firm partners, healthcare system strategy officers, and energy sector corporate development leads and secondary validation through SEC filings, FTC regulatory dockets, and state procurement databases anchors the qualitative findings. Conversations with procurement executives at Fortune 500 enterprises, GPO contracts managers, and municipal RFP administrators informed vendor relationship structuring and fee model evolution. Bottom-up engagement-level data triangulates against top-down market sizing derived from disclosed advisory revenues and contract award announcements.
Sensitivity analysis around talent scarcity intensity and regulatory enforcement pace shapes the forecast confidence intervals across the projection horizon. Segmentation dimensions modeled include service type, client type, industry vertical, and engagement type alongside geographic adoption patterns and procurement centralization maturity. CAGRs derive from trend extrapolation adjusted for structural breakpoints including IRA implementation timelines and AI governance framework emergence. Forecast inputs incorporate partner hiring velocity, RFP volume indices, and disclosed transformation guarantee adoption rates.
Material uncertainties — regulatory enforcement intensity shifts, talent pipeline disruption, and procurement centralization acceleration — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding IRA program continuity and SEC disclosure rule stability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Risk Management and Compliance
Treasury and Risk Management Application Market
Risk Management and Compliance
Governance, Risk and Compliance Platform Market
Risk Management and Compliance
Global Backstop Netting Systems Market
Risk Management and Compliance
Loan Compliance Management Software Market
Risk Management and Compliance
Asia-Pacific BFSI Biometrics Market
Risk Management and Compliance
Fraud Detection and Prevention (FDP) Market
Risk Management and Compliance
Treasury and Risk Management Market
Risk Management and Compliance
Artificial Intelligence and Regtech Market
Risk Management and Compliance
Asia-Pacific Operational Risk Management Consulting Services in Manufacturing Market
Risk Management and Compliance
Anti-Money Laundering (AML) Market
Risk Management and Compliance
Global Financial Crime and Fraud Management Solutions Market
Risk Management and Compliance
United States Strategic Consulting Services Market
Risk Management and Compliance
Trade Surveillance Market
Risk Management and Compliance
Global Credit Risk Rating Software Market
Risk Management and Compliance
Stress Testing Solutions Market
Risk Management and Compliance
Employee Benefits Strategy and Consulting Market