
 Asia-Pacific BFSI Biometrics Market | 2026-2036
Asia-Pacific BFSI Biometrics Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific BFSI Biometrics Market Insights
ISO/IEC 30107-3 Presentation Attack Detection (PAD) certification is reorganizing vendor eligibility across the Asia-Pacific BFSI Biometrics Market, filtering out suppliers lacking liveness detection rigor. NEC Corporation leverages its longstanding government biometric contracts to sustain enterprise-grade channel control across Japanese megabanks. Thales Group anchors its position through embedded security chip integration with fingerprint modules, while Fujitsu dominates palm-vein authentication deployments where contactless hygiene protocols govern procurement decisions.
Asia-Pacific BFSI biometrics encompasses physiological and behavioral identification systems—fingerprint minutiae extraction, iris pattern encoding, voiceprint frequency analysis—engineered to authenticate individuals against enrolled templates with false acceptance rates below 0.001%. These systems secure high-velocity financial transactions, remote account provisioning, and regulatory-compliant customer due diligence across distributed banking networks. Fingerprint recognition leads transaction authentication volumes due to sensor cost compression and mature algorithm libraries, though facial recognition captures the fastest expansion as liveness detection accuracy converges with mobile camera ubiquity. Cloud-based deployment architectures concentrate margin pools among hyperscale platform operators, while on-premises installations persist where India's RBI mandates data localization for Aadhaar-seeded biometric vaults.
India's RBI, Australia's ACCC with Consumer Data Right enforcement, and Singapore's MAS Technology Risk Management Guidelines collectively shape product standards, mandating multi-factor biometric binding for high-risk transactions and audit-trail retention. Compliance with these frameworks determines market access velocity, as vendors without localized infrastructure certification face 12-18 month qualification delays. Stakeholders must monitor whether India's forthcoming Digital Personal Data Protection Act amendments will extend biometric consent requirements beyond Aadhaar-linked services to private-sector insurance and wealth management workflows.
Market Dynamics
ISO/IEC 30107-3 Presentation Attack Detection certification is filtering vendor eligibility across Asia-Pacific BFSI procurement, compressing qualification timelines for suppliers lacking liveness detection rigor while elevating enterprise-grade authentication contracts toward certified incumbents.
Growth Catalysts
- India's Aadhaar-linked eKYC mandate:RBI directives compel urban cooperative banks and payment banks to deploy biometric vaults with data localization, accelerating fingerprint and iris module procurement cycles.
- Contactless hygiene protocols:Post-pandemic procurement criteria in Australia's neobank sector favor palm-vein and facial recognition over fingerprint sensors, reshaping authentication technology selection.
- Consumer Data Right framework:Australia's ACCC enforcement mandates strong customer authentication for open banking data sharing, forcing legacy institutions to bypass infrastructure replacement timelines with modular biometric overlays.
Market Restraints
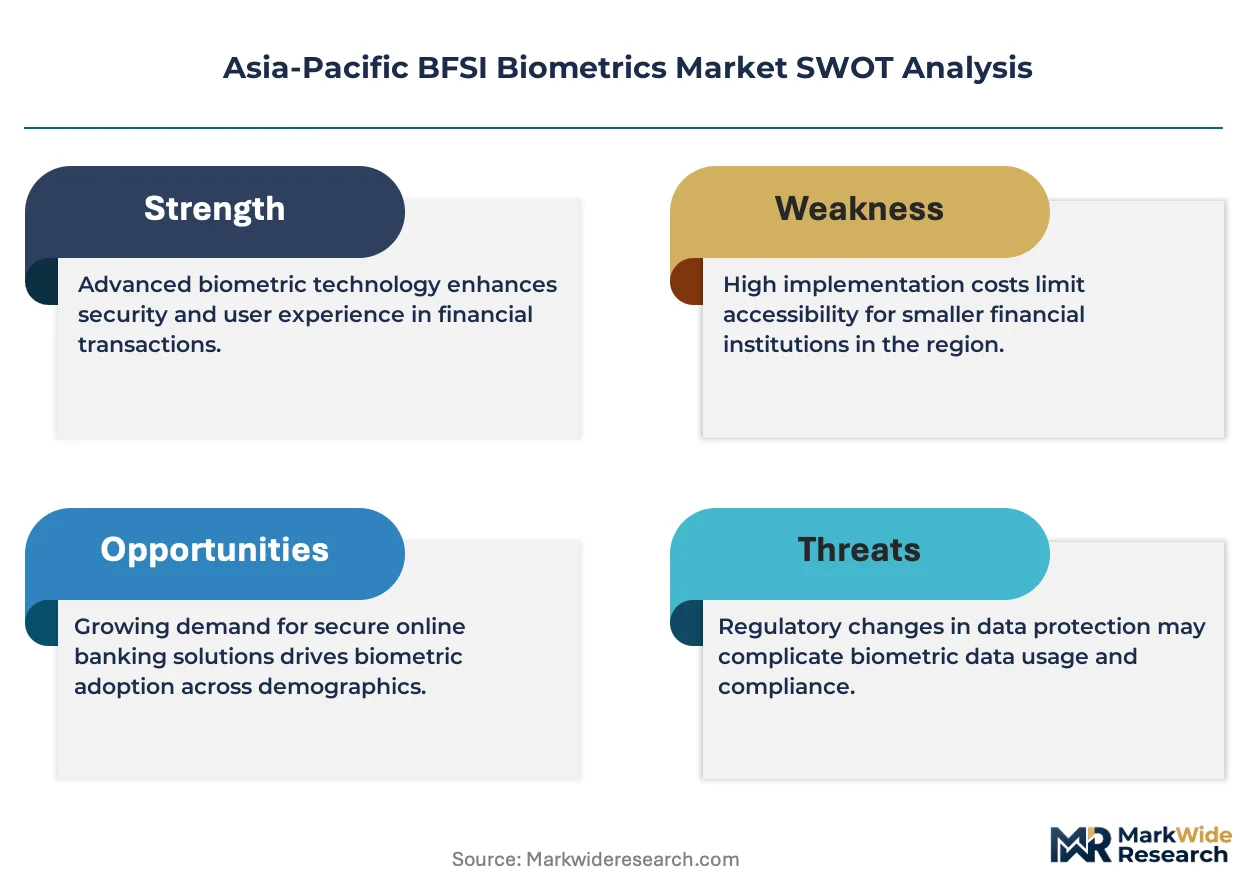
- Sensor cost volatility:Fingerprint module pricing fluctuates with CMOS image sensor wafer allocations, squeezing margin pools for mid-tier authentication system integrators.
- Data localization infrastructure:India's RBI mandates Aadhaar-seeded biometric data residency, forcing foreign platform operators to build captive data centers or forfeit public-sector contracts.
- Template interoperability gaps:Proprietary minutiae extraction algorithms lock enrolled biometric records into vendor-specific formats, raising switching costs for multi-branch banking networks.
Strategic Opportunities
- Branchless account opening:Southeast Asian mobile-first banks seek video-based facial recognition with passive liveness detection, opening white space for cloud-native authentication platforms.
- Behavioral biometrics convergence:Keystroke dynamics and gait analysis layered atop physiological templates enable continuous authentication for high-velocity digital payments.
- MAS Technology Risk Management Guidelines:Singapore's financial regulator mandates multi-factor biometric binding for high-risk transactions, creating procurement pull for integrated authentication stacks.
Industry Challenges
- ISO/IEC 30107-3 certification timelines:Independent testing laboratory queues extend vendor qualification to 12-18 months, delaying product launches and contract awards.
- Legacy core banking integration:Mainframe authentication protocols from the 1990s lack API-native interfaces, forcing expensive middleware development for biometric module connectivity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific BFSI Biometrics Market |
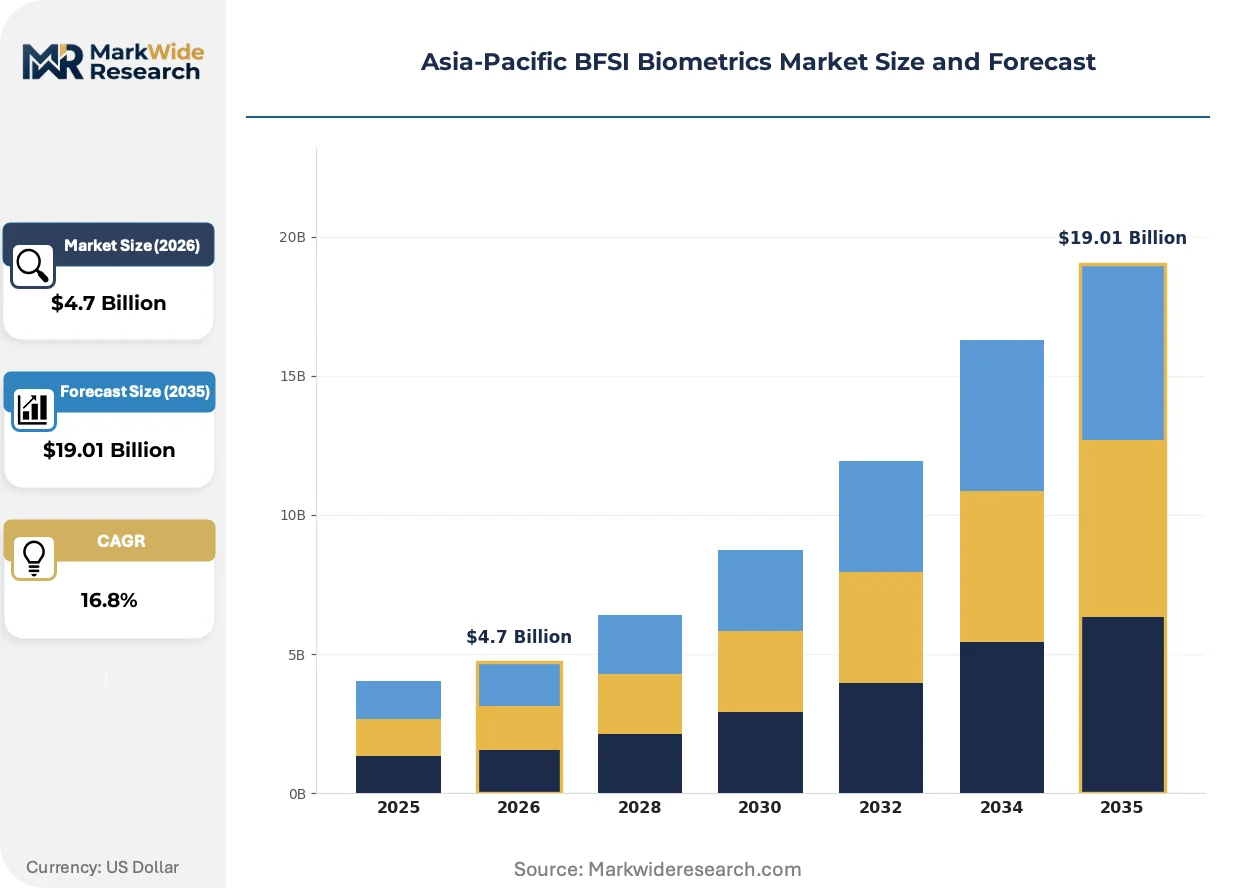
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $19.01 Billion |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Fingerprint Recognition, Facial Recognition, Iris Recognition, Voice Recognition Application: Access Control, Identity Verification, Transaction Authentication, Customer Engagement End User: Banking Institutions, Insurance Companies, Financial Services, Investment Firms Deployment: Cloud-Based, On-Premises, Hybrid, Mobile Solutions |
| Companies Covered | Veridium, Thales Group, NEC Corporation, Precise Biometrics AB, M2SYS Technologies, Fujitsu, Innovatrics, Aware Inc, HID Global Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific BFSI Biometrics Market Trends and Innovations
Cloud-native deployment architectures are capturing margin pools from on-premises installations as regulatory data localization requirements fragment across Asia-Pacific jurisdictions, while liveness detection accuracy improvements compress false acceptance rates below legacy thresholds.
Passive facial liveness detection using single-frame analysis is displacing active challenge-response methods in mobile banking applications. Australian neobanks deploy this technology for remote account provisioning without specialized hardware. The compression of customer onboarding friction is displacing branch-based identity verification toward fully digital channels.
Singapore's MAS Technology Risk Management Guidelines mandate multi-factor biometric binding for high-risk transactions above specified thresholds. Financial institutions must demonstrate independent audit trails for authentication events. Private banks and wealth management platforms face the steepest compliance curve as they retrofit legacy customer due diligence workflows.
Outcome-based authentication service contracts are emerging as the dominant procurement model among Asia-Pacific digital banks. Vendors guarantee false acceptance and false rejection rates rather than selling perpetual hardware licenses. Australia's Consumer Data Right enforcement creates the strongest pressure for this shift, as open banking liability frameworks allocate fraud losses to authentication providers.
Asia-Pacific BFSI Biometrics Market Segmentation
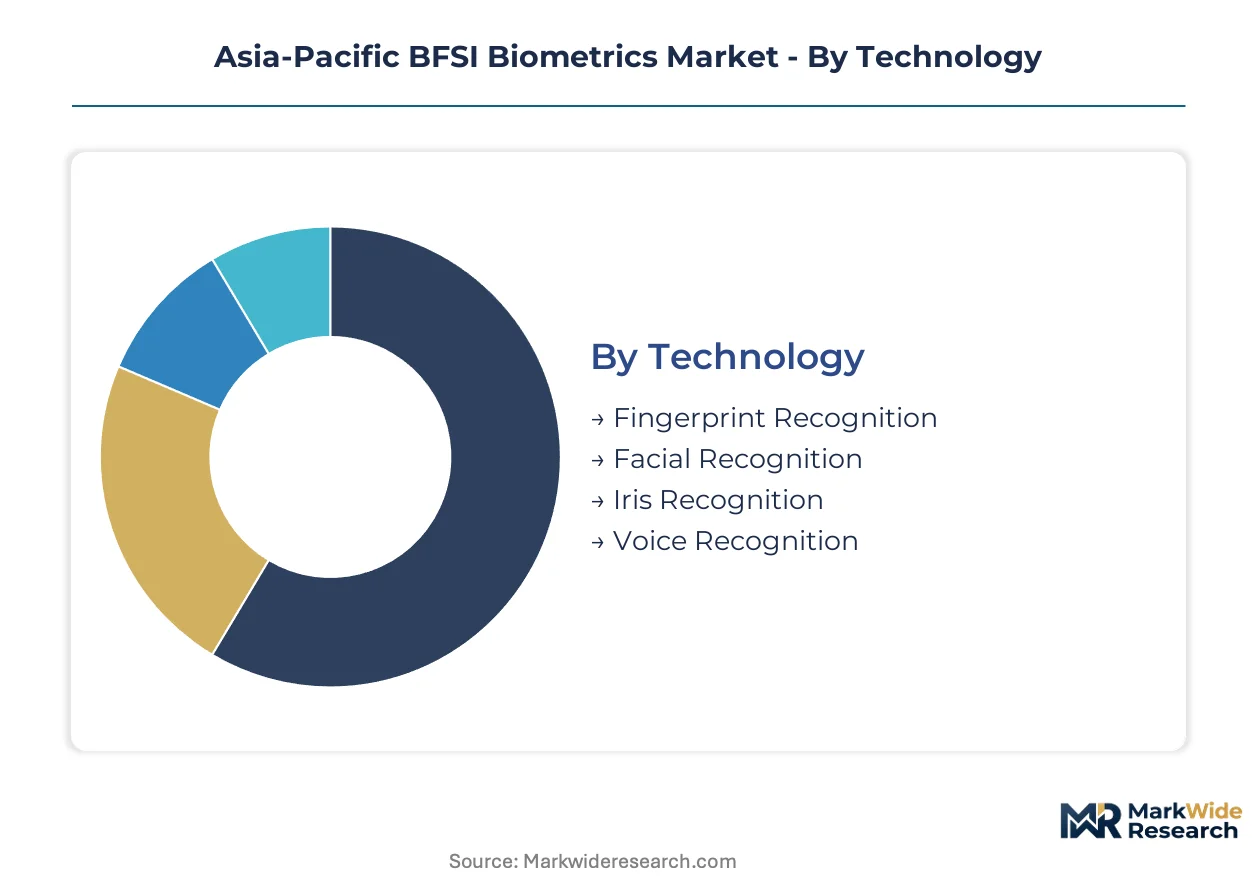
Biometric technology selection in Asia-Pacific banking hinges on balancing regulatory compliance against infrastructure replacement economics. Deployment architecture decisions increasingly fragment procurement patterns as data localization mandates multiply across national jurisdictions.
Technology:
Facial recognition modules face intensifying substitution pressure from palm-vein systems where contactless hygiene protocols govern procurement, while fingerprint sensors confront CMOS wafer allocation volatility that squeezes mid-tier integrator margins.
- Fingerprint Recognition:Minutiae extraction algorithms leverage mature sensor libraries with false acceptance rates below 0.001%. India's urban cooperative banks concentrate demand as RBI directives compel biometric vault deployment with localized data residency.
- Facial Recognition:Passive liveness detection using single-frame analysis displaces active challenge-response methods. Australian neobanks drive procurement for remote account provisioning without specialized hardware, compressing customer onboarding friction toward fully digital channels.
- Iris Recognition:Pattern encoding systems serve high-security vault authentication with template stability advantages over facial aging effects.
- Voice Recognition:Frequency analysis for telephone banking authentication retains niche deployment where legacy IVR infrastructure persists.
Fingerprint recognition retains volume leadership; facial recognition holds the steepest expansion curve.
Application:
Cost tier stratification separates enterprise authentication stacks from modular overlay solutions, with open banking liability frameworks forcing outcome-based procurement models among Australian institutions.
- Identity Verification:eKYC workflows for branchless account opening bind biometric templates against national identity databases. India's Aadhaar-linked mandate accelerates deployment across payment banks and urban cooperatives facing compressed vendor qualification timelines.
- Transaction Authentication:High-velocity payment authorization requires sub-second template matching with audit-trail retention for regulatory examination. Singapore's MAS Technology Risk Management Guidelines mandate multi-factor biometric binding above specified transaction thresholds.
- Access Control:Physical perimeter security for data centers and treasury operations employs multi-modal fusion.
- Customer Engagement:Behavioral biometrics layering keystroke dynamics atop physiological templates enable continuous authentication.
Identity verification commands the largest procurement budgets; transaction authentication is climbing the fastest as real-time payment volumes surge.
End User:
Customer type divergence separates regulated deposit-taking institutions from investment advisory platforms, with insurance intermediaries facing the steepest retrofit burden for legacy policy administration systems.
- Banking Institutions:Universal banks and neobanks deploy integrated authentication stacks spanning branch, mobile, and ATM channels. Australia's Consumer Data Right enforcement allocates fraud liability to authentication providers, forcing modular biometric overlays where core banking replacement timelines extend.
- Insurance Companies:Life and general insurers retrofit customer due diligence workflows for regulatory-compliant policy issuance. India's forthcoming Digital Personal Data Protection Act amendments may extend biometric consent requirements beyond Aadhaar-linked services to private-sector insurance workflows.
- Financial Services:Payment system operators and remittance platforms require high-throughput template matching.
- Investment Firms:Wealth management platforms face MAS audit-trail mandates for high-value transaction authentication.
Banking institutions dominate installed base; insurance companies are expanding most quickly as regulatory scope broadens.
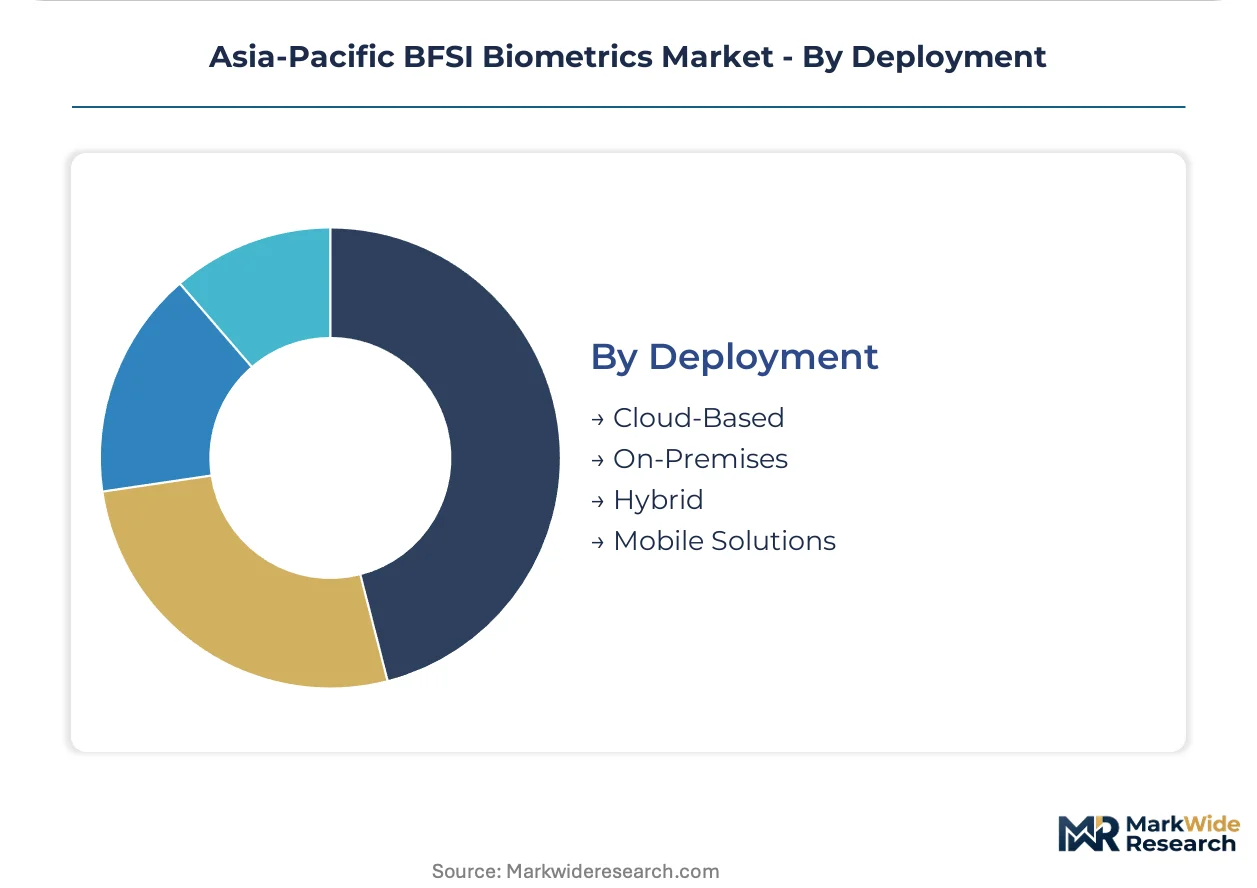
Deployment:
Margin pool concentration favors hyperscale platform operators as cloud-native architectures displace on-premises installations, though data fragmentation across national localization requirements sustains hybrid demand.
- Cloud-Based:API-native authentication services enable rapid deployment without capital infrastructure commitment. Southeast Asian mobile-first banks seek video-based facial recognition with passive liveness detection, opening white space for platform operators.
- On-Premises:Captive biometric vaults satisfy India's RBI data localization mandates for Aadhaar-seeded templates. Foreign platform operators must build captive data centers or forfeit public-sector contracts.
- Hybrid:Edge processing with cloud analytics balances latency against scalability for distributed branch networks.
- Mobile Solutions:Native SDK integration with device-secure enclaves leverages smartphone biometric sensors without dedicated hardware.
Cloud-based deployment captures the fastest share gains; on-premises retains structural demand where regulatory data residency is non-negotiable.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
RBI directives on Aadhaar-linked eKYC, Australia's Consumer Data Right enforcement, and Singapore's MAS Technology Risk Management Guidelines are compressing vendor qualification timelines and reshaping procurement patterns across the region.
India
Urban cooperative banks and payment banks drive fingerprint and iris module procurement as RBI mandates biometric vaults with data localization. The Digital Personal Data Protection Act amendments may extend biometric consent requirements to private-sector insurance workflows. Mumbai and Bangalore concentrate vendor certification activity as foreign platform operators build captive data centers.
Australia
Neobanks favor palm-vein and facial recognition over fingerprint sensors under post-pandemic contactless hygiene protocols. ACCC enforcement of the Consumer Data Right allocates fraud liability to authentication providers, forcing modular biometric overlays. Sydney and Melbourne anchor outcome-based service contract negotiations as open banking liability frameworks mature.
Singapore
Private banks and wealth management platforms retrofit legacy customer due diligence workflows to comply with MAS Technology Risk Management Guidelines mandating multi-factor biometric binding. The city-state's financial hub status attracts cloud-native authentication platform operators seeking regional headquarters. Enterprise-grade procurement concentrates among full-license banks.
Japan
Megabanks sustain demand for enterprise-grade authentication stacks spanning branch, mobile, and ATM channels. Government biometric contracts create channel control advantages for established vendors. Tokyo anchors palm-vein authentication deployments where contactless hygiene protocols govern procurement decisions in high-traffic financial districts.
South Korea
Financial institutions deploy integrated authentication systems for high-velocity digital payments and real-time settlement networks. The country's technology regulator shapes product standards for multi-factor biometric binding. Seoul concentrates demand for behavioral biometrics layering keystroke dynamics atop physiological templates.
Asia-Pacific BFSI Biometrics Market Competitive Landscape
Listed leaders compete with private specialists across certification timelines and data localization capabilities. The vendor base stratifies between hyperscale platform operators capturing cloud-native margins and on-premises specialists serving RBI-mandated biometric vaults. Three archetypes dominate: government contract holders leveraging longstanding institutional relationships, embedded security chip integrators, and cloud-native authentication platforms. Competitive moves concentrate on ISO/IEC 30107-3 certification acceleration and captive data center construction for data residency compliance.
Within the government contract holder archetype, NEC Corporation and Fujitsu exemplify how longstanding public-sector relationships translate into enterprise banking channel control. Thales Group anchors the embedded security tier through hardware-software integration capabilities. These three entities represent distinct competitive positions: Tokyo-based conglomerates with defense and government heritage, and Paris-headquartered aerospace-defense conglomerates with digital identity divisions.
| Leading Market Players |
|---|
| Veridium |
| Thales Group |
| NEC Corporation |
| Precise Biometrics AB |
| M2SYS Technologies |
| Fujitsu |
| Innovatrics |
| Aware Inc |
| HID Global Corporation |
| Others |
Pricing and Supply Chain Analysis
Eighteen-month ISO/IEC 30107-3 certification queues compress vendor cash conversion cycles and concentrate pricing power among incumbent laboratories with accredited testing capacity, while CMOS wafer allocation volatility feeds cost uncertainty through fingerprint module supply chains.
Pricing Analysis
Certification level creates the primary spread between premium-tier PAD-validated systems and uncertified alternatives. Three-tier pricing structure across PAD-certified enterprise stacks, standard biometric modules, and economy sensor components governs procurement. Pricing pressure stems from hyperscale cloud operators bundling authentication APIs below standalone hardware economics. Neobanks and payment banks exhibit highest price sensitivity; Japanese megabanks and Singapore private banks demonstrate lowest sensitivity due to compliance-driven specification rigidity.
Supply Chain Analysis
Eighteen-month certification queues strain working capital across mid-tier vendors awaiting laboratory slots. CMOS image sensor fabrication concentrates in Taiwan and South Korea, while algorithm development clusters in Japan and India. Supply chains draw from semiconductor wafers, optical lens arrays, and specialized biometric ASICs. Single-source vulnerability runs through TSMC-adjacent foundry capacity for advanced sensor nodes. Distribution runs through systems integrators with RBI localization certification and direct enterprise sales teams for hyperscale platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory entrenchment moat where ISO/IEC 30107-3 certification timelines and RBI data localization mandates erect structural barriers against rapid competitive displacement.
For Market Incumbents: Secure PAD certification acceleration through captive laboratory partnerships or strategic acquisitions of accredited testing facilities. Deepen channel control across Japanese megabank procurement committees before cloud-native platforms achieve MAS compliance. Threat vector: hyperscale operators achieving ISO/IEC 30107-3 validation and bundling authentication below hardware economics. For New Entrants and Emerging Players: ISO/IEC 30107-3 fast-track partnerships with Singapore-based testing laboratories open qualification pathways compressed versus standard queues. Target Australia's neobank sector where outcome-based service contracts displace hardware procurement and regulatory frameworks allocate fraud liability to authentication providers. Go-to-market angle: passive liveness detection SDKs with native cloud deployment. For Investors and Strategic Acquirers: Carve-out targets emerge from defense-aerospace conglomerates with dormant biometric divisions lacking banking sector focus. Five-to-ten-year viability hinges on regulatory entrenchment deepening rather than technology disruption. Signal to monitor: India's Digital Personal Data Protection Act enforcement scope expansion beyond Aadhaar-linked services into private-sector insurance and wealth management workflows.| Strategic Initiative | Industry Significance |
|---|---|
| ISO/IEC 30107-3 Certification Acceleration | Compressed qualification timelines capture enterprise contracts ahead of competitor laboratory queue clearance. |
| Captive Data Center Construction | RBI-mandated Aadhaar biometric data residency requires localized infrastructure for public-sector contract eligibility. |
| Passive Liveness Detection SDK Launch | Single-frame facial analysis displaces active challenge-response methods in Australian neobank remote onboarding. |
| Outcome-Based Service Contract Transition | ACCC Consumer Data Right liability frameworks allocate fraud losses to authentication providers, reshaping procurement models. |
| Behavioral Biometrics Platform Integration | Keystroke dynamics and gait analysis layered atop physiological templates enable continuous authentication for high-velocity payments. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, vendor certification databases, and national biometric procurement records. Primary interviews spanned chief technology officers at neobanks, RBI compliance officers at urban cooperative banks, biometric systems procurement leads at Japanese megabanks, and laboratory directors at ISO-accredited testing facilities. Secondary sources included SEBI circulars, MAS Technology Risk Management Guidelines, ACCC Consumer Data Right enforcement documents, and RBI data localization directives. Bottom-up unit economics triangulated against top-down market sizing across technology, application, and deployment segments.
Segmentation dimensions modeled encompass biometric modality, application workflow, end-user institution type, and deployment architecture across the projection horizon. CAGRs derive from installed base growth rates, replacement cycle compression, and regulatory mandate enforcement timelines. Industry-specific inputs include Aadhaar-seeded transaction volumes, open banking API authentication event growth, and PAD certification pipeline throughput assumptions.
Decision-makers should treat outputs as directional under sustained regulatory enforcement of data localization and multi-factor biometric binding; material deviation in certification timeline compression or cloud-native platform compliance achievement would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Risk Management and Compliance
Global Energy Trading and Risk Management (ETRM) Market
Risk Management and Compliance
Asia-Pacific Sustainable Finance Market
Risk Management and Compliance
Global Regulatory Reporting and Compliance Market
Risk Management and Compliance
Operational Risk Management Consulting Services in Manufacturing Market
Risk Management and Compliance
Artificial Intelligence and Regtech Market
Risk Management and Compliance
Asset Liability Management (ALM) Solution Market
Risk Management and Compliance
Anti-Money Laundering (AML) Market
Risk Management and Compliance
Healthcare Fraud Detection Market
Risk Management and Compliance
Corporate Investigation Services Market
Risk Management and Compliance
Compliance As a Service Market
Risk Management and Compliance
Global Patient Safety and Risk Management Softwares Market
Risk Management and Compliance
Operations Advisory Service Market
Risk Management and Compliance
Legal Advisory Service Market
Risk Management and Compliance
Risk Assessment Software Market
Risk Management and Compliance
Risk Management Market
Risk Management and Compliance
Employee Benefits Strategy and Consulting Market