
 South Africa Pet Food Market | 2026-2036
South Africa Pet Food Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Pet Food Market Insights
Subscription-based pet nutrition services is rebalancing how manufacturers engage repeat purchasers in South Africa. Mars Petcare South Africa leverages its veterinary clinic partnerships to anchor recurring dry food deliveries. Nestlé Purina PetCare South Africa sustains brand loyalty through breed-specific formulations. Montego Pet Nutrition competes via locally sourced protein inputs and price-tier flexibility.
South Africa pet food comprises formulated nutritional products manufactured to AAFCO or equivalent nutrient profiles, with extruded kibble representing the dominant dry food process and retort-cooked cans constituting wet food production. Dry food occupies the largest volume share due to shelf stability and cost efficiency in township and suburban distribution alike. Wet food and treats represent faster-growing margin pools as pet humanization trends elevate palatability expectations among Gauteng and Western Cape consumers. The veterinary clinic channel commands premium price tier placement, while supermarkets and online platforms drive mid-range and economy volume.
The Department of Agriculture, Land Reform and Rural Development enforces pet food safety under the Fertilizers, Farm Feeds, Seeds and Remedies Act, mandating label disclosures that shape manufacturer formulation transparency. SANS standards and municipal health bylaws in Cape Town and eThekwini further regulate manufacturing facility hygiene and import inspection protocols. Stakeholders must monitor pending amendments to farm feed classifications that could reclassify certain pet food ingredients and alter import duty structures.
Market Dynamics
Subscription-based pet nutrition services is rebalancing how manufacturers engage repeat purchasers in South Africa. Mars Petcare South Africa leverages its veterinary clinic partnerships to anchor recurring dry food deliveries. Nestlé Purina PetCare South Africa sustains brand loyalty through breed-specific formulations. Montego Pet Nutrition competes via locally sourced protein inputs and price-tier flexibility.
Growth Catalysts
- The Fertilizers, Farm Feeds, Seeds and Remedies Act:Label disclosure mandates under the Department of Agriculture, Land Reform and Rural Development force formulation transparency, elevating consumer trust in premium tiers.
- Urban middle-class households:Gauteng province's dense pet-owning populations in Johannesburg and Pretoria concentrate demand for AAFCO-equivalent nutritional profiles.
- Extruded kibble technology:Shelf stability and cost efficiency in township and suburban distribution channels expand dry food volume penetration.
Market Restraints
- Protein input cost volatility:Locally sourced meat and poultry prices fluctuate with agricultural supply shocks, compressing margin pools for mid-range manufacturers.
- Veterinary clinic channel concentration:Premium price tier placement depends on Gauteng and Western Cape clinic networks, creating geographic supply risk.
- Pending farm feed reclassification:Amendments to ingredient classifications under the Fertilizers, Farm Feeds, Seeds and Remedies Act could alter import duty structures and disrupt formulation economics.
Strategic Opportunities
- Western Cape expansion:Cape Town's municipal health bylaws and elevated palatability expectations create white space for wet food and treat margin pools.
- E-commerce channel innovation:Online platforms currently drive mid-range and economy volume, with subscription mechanics offering recurring revenue capture.
- SANS standards alignment:Manufacturing facility hygiene certifications open export pathways into regulated African markets.
Industry Challenges
- Retort-cooked can production capex:Wet food manufacturing requires specialized thermal processing equipment, creating barrier to entry for local entrants.
- Import inspection protocol delays:eThekwini municipal health inspections create inventory holding costs for imported specialty ingredients.
- Veterinary nutritionist talent scarcity:Breed-specific formulation development depends on scarce qualified professionals concentrated in Gauteng academic institutions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Pet Food Market |
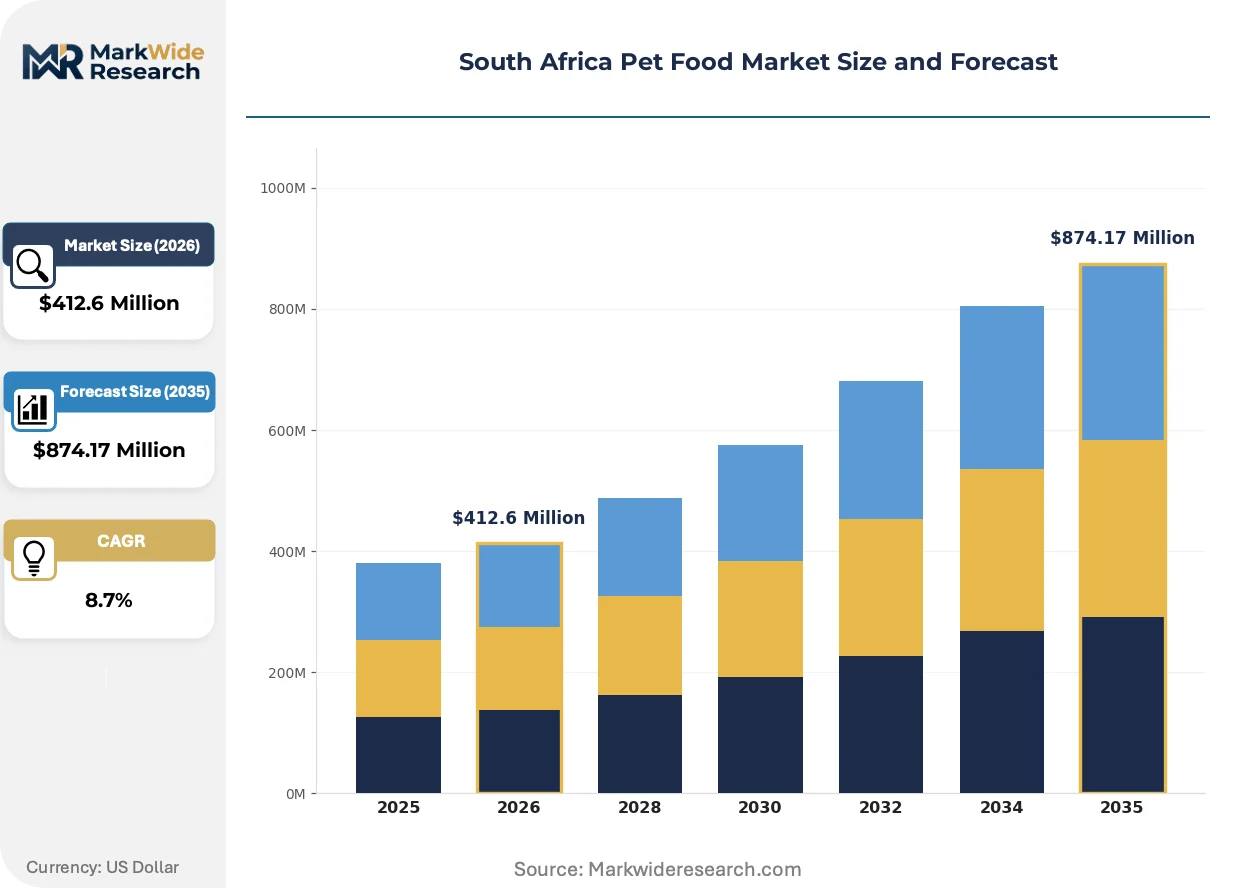
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $874.17 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dry Food, Wet Food, Snacks, Treats Animal Type: Dog, Cat, Bird, Fish Distribution Channel: Online, Supermarkets, Pet Shops, Veterinary Clinics Price Tier: Premium, Mid-Range, Economy, Budget |
| Companies Covered | Nestlé Purina PetCare South Africa, Mars Petcare South Africa, Hill's Pet Nutrition South Africa, Montego Pet Nutrition, RCL Foods, AVI Limited, Promeal, Premier FMCG, Martin & Martin, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Pet Food Market Trends and Innovations
Pet humanization trends are elevating palatability expectations and compressing product development cycles across South Africa's pet food landscape. Manufacturers now balance AAFCO nutritional compliance with sensory appeal targeting Gauteng and Western Cape consumer preferences.
Cold-pressed extrusion technology is modularizing dry food production workflows in South African manufacturing facilities. Mid-tier producers in Gauteng province adopt this lower-temperature process to preserve nutrient density in premium kibble lines. The technology is modularizing plant configurations, enabling smaller batch runs for breed-specific formulations without retooling entire production lines.
The Department of Agriculture's pending amendments to farm feed classifications under the Fertilizers, Farm Feeds, Seeds and Remedies Act are tightening ingredient traceability requirements. Manufacturers must reconfigure supplier qualification systems to maintain label compliance. Wet food producers importing specialty proteins face the steepest documentation burden, accelerating backward integration into local protein sourcing.
Subscription mechanics are displacing traditional supermarket replenishment among urban middle-class households. Veterinary clinic channels now bundle recurring dry food deliveries with wellness check-ups, capturing higher lifetime value per pet. Gauteng province's Johannesburg and Pretoria metros exhibit the densest adoption of automated reorder platforms, with Western Cape consumers following at a twelve-month lag.
South Africa Pet Food Market Segmentation
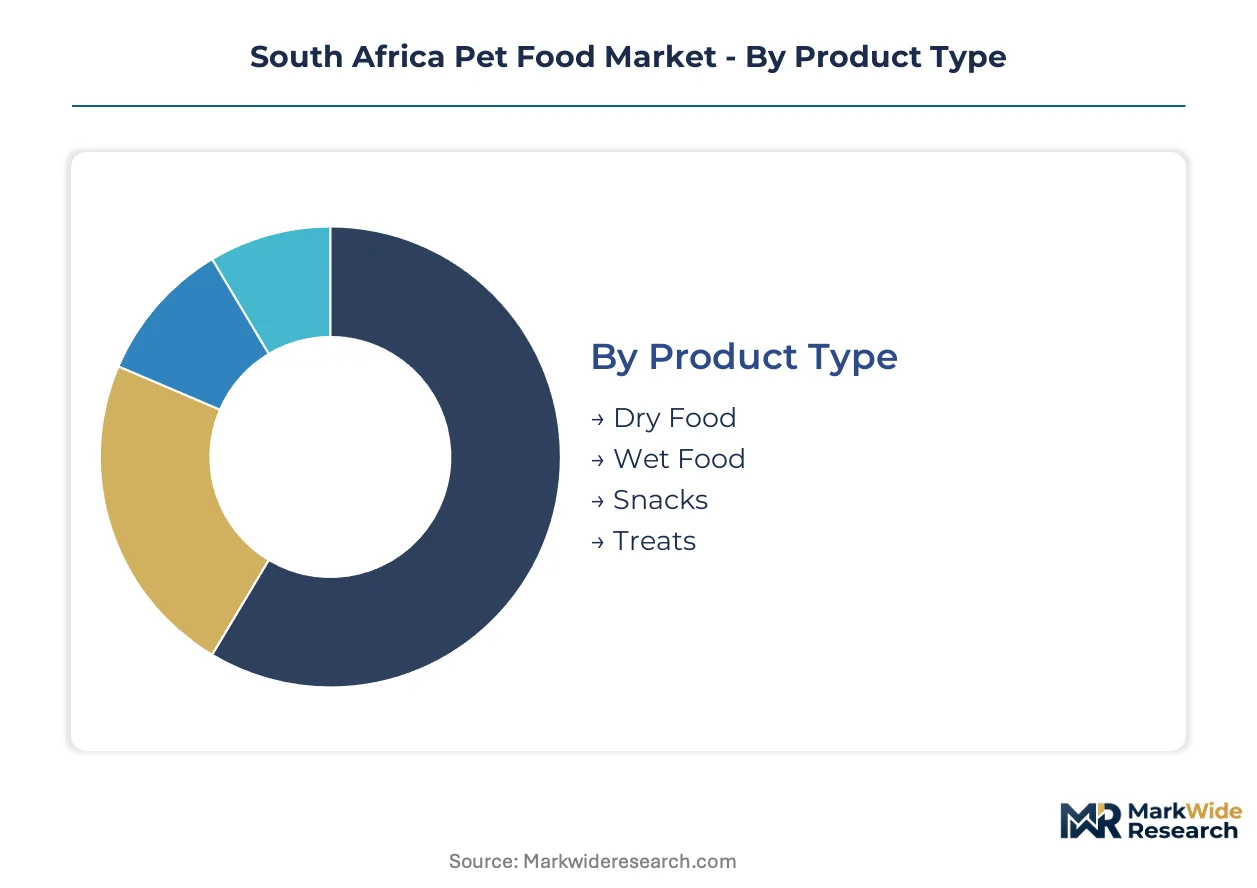
Segmentation in South Africa's pet food market reveals how manufacturers align product architecture with Gauteng's urban middle-class density and Western Cape's premium palatability expectations. Each dimension exposes distinct margin pools and channel access requirements.
Product Type:
Dry food functions as the standalone volume anchor, while wet food and treats operate as embedded margin enhancers within subscription and veterinary bundles.
- Dry Food:Extruded kibble manufactured to AAFCO-equivalent nutrient profiles dominates township and suburban distribution through shelf stability. Gauteng province's Johannesburg and Pretoria corridors absorb the densest dry food volumes due to cost efficiency in mid-range household budgets.
- Wet Food:Retort-cooked cans deliver elevated palatability for humanization-driven consumers. Western Cape demand clusters in Cape Town's municipal health jurisdiction, where municipal bylaws intersect with premium sensory expectations.
- Snacks:Functional dental and training formats bridge daily feeding rituals with intermittent reward behaviors.
- Treats:Occasion-based indulgence products targeting breed-specific formulation trends in veterinary clinic channels.
Volume placements concentrate in Dry Food; the faster expansion belongs to Wet Food.
Animal Type:
Cost tier alignment separates companion mammals from ornamental species, with protein input economics driving formulation divergence.
- Dog:Largest addressable base across all price tiers, with breed-specific formulations commanding veterinary channel premiums. Gauteng's dense pet-owning populations sustain mid-range and economy kibble throughput.
- Cat:Obligate carnivore physiology mandates higher protein inclusion rates, elevating wet food attachment. Western Cape consumers exhibit elevated palatability sensitivity for feline formulations.
- Bird:Seed and pellet blends serving avian hobbyist segments with specialized nutritional requirements.
- Fish:Aquatic ornamental species sustaining niche flake and pellet demand through pet shop channels.
Volume placements concentrate in Dog; the steepest expansion trajectory belongs to Cat.
Distribution Channel:
Channel selection determines price tier access, with veterinary clinics gating premium placement and online platforms democratizing mid-range reach.
- Online:Subscription mechanics now anchor recurring dry food deliveries for urban middle-class households. Automated reorder platforms in Johannesburg and Pretoria metros capture highest lifetime value per pet.
- Supermarkets:Mid-range and economy volume driver with standardized shelf configurations across Gauteng and Western Cape retail footprints.
- Pet Shops:Specialty access point for breed-specific and exotic animal nutrition with trained staff consultation.
- Veterinary Clinics:Premium tier gatekeeper bundling wellness check-ups with therapeutic and prescription formulations. Geographic concentration in Gauteng and Western Cape creates supply risk.
Volume placements concentrate in Supermarkets; the fastest share gains belong to Online.
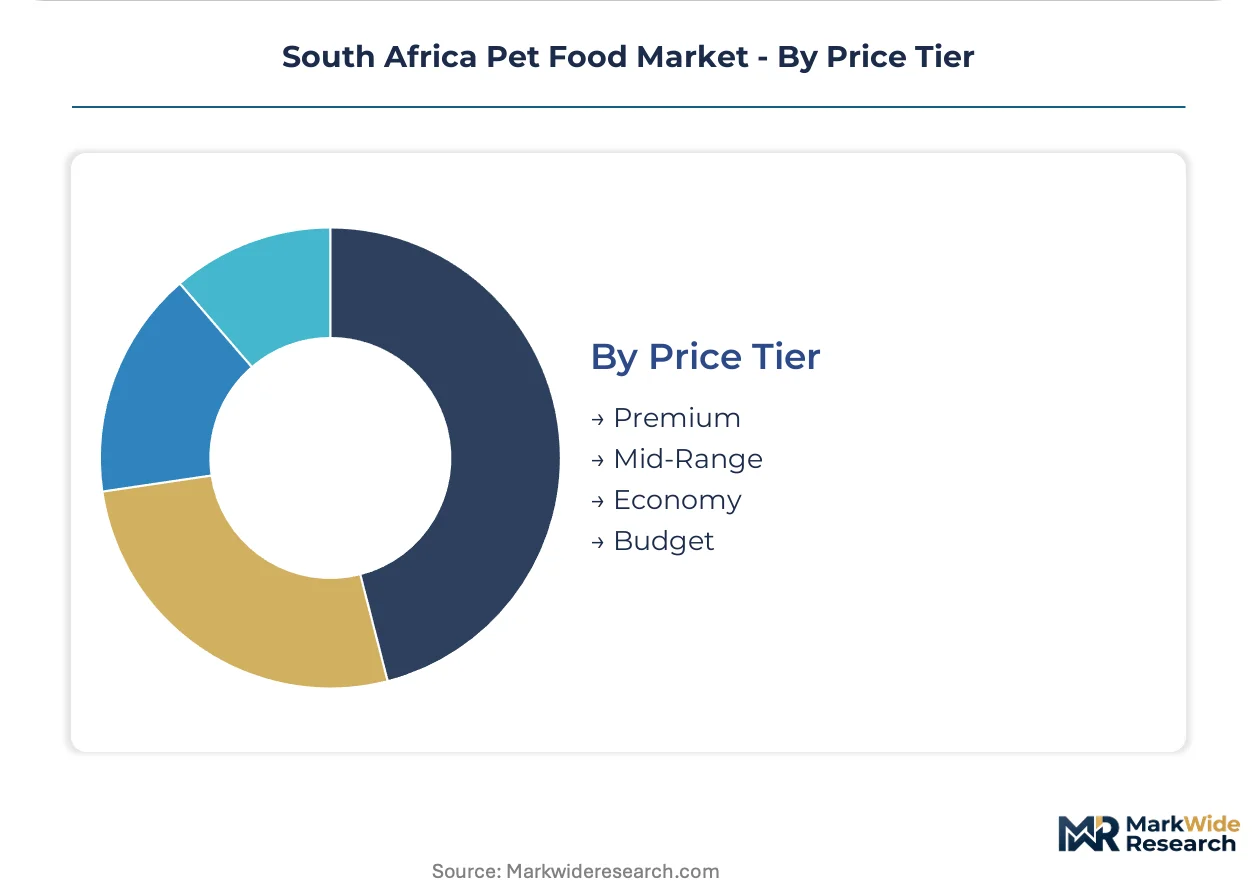
Price Tier:
Raw material provenance and certification grade stratify the market into four distinct procurement thresholds.
- Premium:AAFCO-compliant formulations with locally sourced protein traceability and cold-pressed extrusion processing. Veterinary clinic placement and subscription bundling sustain margin integrity.
- Mid-Range:Standard extrusion technology serving Gauteng's urban middle-class density through supermarket and online channels. Protein input cost volatility compresses margins most acutely here.
- Economy:Shelf-stable kibble prioritizing caloric density over sensory appeal for price-sensitive township distribution.
- Budget:Entry-level formulations meeting minimum regulatory thresholds under the Fertilizers, Farm Feeds, Seeds and Remedies Act.
Volume placements concentrate in Mid-Range; the margin expansion belongs to Premium.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Johannesburg-Pretoria corridor concentrates South African pet food demand through Gauteng province's dense urban middle-class households and veterinary clinic networks.
Gauteng
Johannesburg and Pretoria metros absorb the densest dry food volumes through cost-efficient extruded kibble distribution. The Department of Agriculture's labeling standards under the Fertilizers, Farm Feeds, Seeds and Remedies Act mandate formulation transparency for products entering this corridor. Automated subscription reorder platforms capture highest lifetime value per pet in Sandton and Centurion suburbs.
Western Cape
Cape Town's elevated palatability expectations drive wet food and treat margin expansion among humanization-focused consumers. Municipal health bylaws in eThekwini and Cape Town regulate manufacturing facility hygiene and import inspection protocols. Somerset West and Stellenbosch industrial zones host cold-pressed extrusion facilities serving premium tier production.
KwaZulu-Natal
eThekwini metropolitan area processes imported specialty ingredients through port infrastructure, though inspection protocol delays create inventory holding costs. SANS standards alignment opens export pathways into regulated African markets from Durban-based facilities. Pinetown manufacturing clusters concentrate mid-range kibble production for township distribution.
Eastern Cape
Gqeberha and East London corridors sustain economy-tier shelf-stable kibble penetration through price-sensitive distribution networks. Provincial agricultural supply chains feed locally sourced protein inputs to regional manufacturers. Nelson Mandela Bay logistics hubs connect Eastern Cape production to national supermarket channels.
South Africa Pet Food Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across South Africa's pet food manufacturing base. The market structure consolidates around multinational nutrition conglomerates with captive veterinary channels, mid-tier local manufacturers with protein sourcing advantages, and economy-focused distributors prioritizing township reach. Strategic archetypes separate subscription-anchored premium players, backward-integrated local protein processors, and supermarket-dependent volume suppliers. Competitive moves concentrate on veterinary clinic partnership lock-ups and e-commerce subscription mechanics.
Within the multinational tier, Nestlé Purina PetCare South Africa and Mars Petcare South Africa occupy positions exemplifying breed-specific formulation development and clinic-channel bundling. Montego Pet Nutrition represents the locally integrated archetype, anchoring competitive positioning through captive protein sourcing and price-tier flexibility across Gauteng and Western Cape distribution corridors.
| Leading Market Players |
|---|
| Nestlé Purina PetCare South Africa |
| Mars Petcare South Africa |
| Hill's Pet Nutrition South Africa |
| Montego Pet Nutrition |
| RCL Foods |
| AVI Limited |
| Promeal |
| Premier FMCG |
| Martin & Martin |
| Others |
Pricing and Supply Chain Analysis
Veterinary clinic channel concentration in Gauteng and Western Cape provinces anchors value-based pricing through bundled wellness subscriptions. The Department of Agriculture's labeling mandates under the Fertilizers, Farm Feeds, Seeds and Remedies Act elevate transparency premiums that manufacturers capture via AAFCO-equivalent certification tiers.
Pricing Analysis
Breed-specific formulation outcomes command the highest value-based premiums in South African pet nutrition. Three-tier pricing structure across premium, standard, and economy levels stratifies raw material provenance against certification grade and cold-pressed processing investment. Cost compression in mid-range tiers intensifies because protein input volatility erodes standard extrusion margins. Township distributors exhibit acute price sensitivity, while veterinary clinic subscribers demonstrate lowest elasticity due to embedded wellness service bundling.
Supply Chain Analysis
Regional distribution centers in Johannesburg-Pretoria and Cape Town-Somerset West operate hub-and-spoke patterns feeding township and suburban retail nodes. Local poultry and red meat processors in Eastern Cape and KwaZulu-Natal supply protein inputs, while specialty vitamin premixes draw from established European and North American feed additive suppliers. Single-source vulnerability concentrates in cold-pressed extrusion equipment, where limited Gauteng-based technical service capacity creates maintenance bottlenecks. Distribution runs through supermarket chains for economy volume, with subscription platforms capturing premium tier direct-to-consumer flows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Retort-cooked can production capacity scarcity props premium wet food pricing, constraining supply response to Western Cape palatability demand surges.
For Market Incumbents: Acquire cold-pressed extrusion technical service capacity in Gauteng province to lock out mid-tier competitors. Nestlé Purina PetCare South Africa and Mars Petcare South Africa should deepen backward integration into Eastern Cape poultry processing to defend margin position against protein cost volatility. Veterinary clinic partnership exclusivity remains the critical defensive lever against subscription-platform disintermediation. For New Entrants and Emerging Players: The Fertilizers, Farm Feeds, Seeds and Remedies Act in South Africa opens a window for transparency-first brands to capture mid-range share from legacy manufacturers slow to adapt label disclosure requirements. White space concentrates in Western Cape wet food and treat segments, where Cape Town's municipal health bylaws create compliance barriers for national players lacking localized production. E-commerce subscription mechanics offer the most penetrable go-to-market angle for asset-light entrants targeting Sandton and Centurion household clusters. For Investors and Strategic Acquirers: The window for entry favors backward-integrated protein processors with existing SANS hygiene certifications. Long-term viability hinges on captive supply chain control spanning raw material through veterinary channel placement. Monitor pending farm feed reclassification amendments as the signal for import duty disruption and formulation economics inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Pressed Extrusion Capacity Expansion | Modular plant configurations in Gauteng enable smaller batch runs for breed-specific formulations. |
| Backward Integration into Local Protein Sourcing | Eastern Cape poultry supply chains reduce exposure to agricultural price volatility under the Fertilizers Act. |
| Veterinary Clinic Partnership Lock-ups | Bundled wellness subscriptions in Johannesburg-Pretoria corridors capture highest lifetime value per pet. |
| E-commerce Subscription Platform Launch | Automated reorder mechanics displace traditional supermarket replenishment among urban middle-class households. |
| SANS Standards Alignment Investment | Manufacturing hygiene certifications open export pathways into regulated African markets from Durban-based facilities. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this South Africa pet food market assessment. Primary interviews with veterinary nutritionists, pet food manufacturing plant managers, supermarket category buyers, and Department of Agriculture regulatory affairs officers combined with bottom-up and top-down triangulation. Secondary validation drew from Fertilizers, Farm Feeds, Seeds and Remedies Act documentation, SANS standards publications, municipal health bylaws in Cape Town and eThekwini, and AAFCO nutrient profile guidelines.
Data-stream reconciliation across production volume surveys, channel shipment data, and retail audit information established the analytical framework. Segmentation dimensions modeled include product type, animal species, distribution channel, price tier, and provincial demand cluster across the analysis window. CAGRs were derived from trend extrapolation of historical volume trajectories adjusted for regulatory and technology adoption assumptions. Industry-specific forecast inputs incorporated cold-pressed extrusion technology diffusion rates and subscription platform penetration curves.
The model assumes a particular technology adoption path for cold-pressed extrusion; alternative pathways for retort-cooked can production automation would alter the outlook for wet food margin expansion. Forecasts reflect documented assumptions regarding protein input cost stabilization and veterinary channel consolidation trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
UAE Dog Food Market
Pet Care Products
Dog Vest Market
Pet Care Products
Cat Harness Market
Pet Care Products
Cannabidiol CBD Pet Market
Pet Care Products
US Pet Daycare Market
Pet Care Products
UTI Cat Food Market
Pet Care Products
Dog Supplement Market
Pet Care Products
Dog Brush Market
Pet Care Products
Japan Dog Food Market
Pet Care Products
Dog Food Market
Pet Care Products
UK Pet Boarding Market
Pet Care Products
Asia-Pacific Pet Travel Services Market
Pet Care Products
Pet Grooming Services Market
Pet Care Products
Pet Oral Care Market
Pet Care Products
Pet Clothing Market
Pet Care Products
Mobile Pet Care Market