
 Pet Food Market | 2026-2036
Pet Food Market Size, Share, and Industry Trends Forecast 2026-2036
Pet Food Market Intelligence
Millennial and Gen Z pet owners is reorganizing demand toward subscription-based fresh food programs and veterinary-recommended diets. Mars Petcare leverages its global manufacturing footprint to supply both mass-market and prescription nutrition lines across six continents. Nestlé Purina anchors its position through in-house veterinary research centers that validate therapeutic formulations. Champion Petfoods differentiates via biologically appropriate recipes built on regional ingredient sourcing protocols.
Pet food denotes commercially manufactured nutritional products formulated from proteins, fats, carbohydrates, vitamins, and minerals to meet species-specific dietary requirements, typically processed through extrusion, canning, or freeze-drying to achieve shelf stability and digestibility. Dry food dominates volume due to logistics efficiency and extended shelf life, though raw food captures margin expansion as cold-chain infrastructure matures. Wet food maintains stable demand among feline owners seeking hydration support, while grain-free formulations face reformulation pressure as veterinary cardiologists link certain legume-heavy diets to dilated cardiomyopathy in dogs.
The FDA Center for Veterinary Medicine enforces contaminant thresholds and ingredient disclosure rules that shape domestic formulation standards, while AAFCO model regulations guide state-level nutrient profiles and labeling requirements across the United States. The European Food Safety Authority and EU feed hygiene regulations mandate HACCP-based controls and detailed additive authorization that condition market access for imported products. Stakeholders must monitor evolving veterinary science on grain-free formulations and emerging state legislation on cultivated protein acceptance to anticipate next-generation ingredient pipelines.
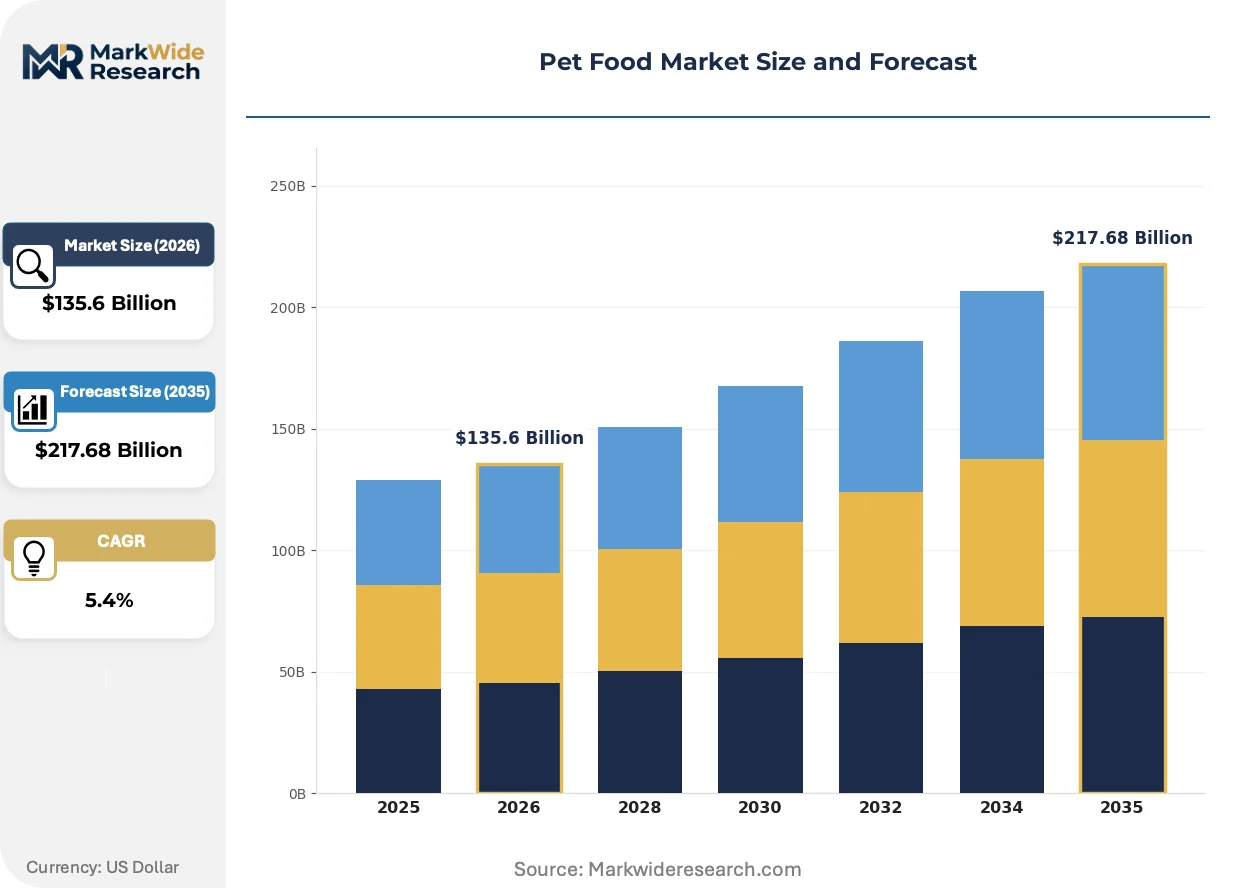
Market Dynamics
Pet humanization among millennial households is compressing purchase cycles toward subscription-based fresh nutrition programs while simultaneously elevating veterinary-grade formulation standards across all retail tiers.
Growth Catalysts
- EU Feed Hygiene Regulations:HACCP-based control mandates are forcing consolidation among compliant manufacturers, creating shelf space advantages for certified exporters entering European distribution networks.
- Freeze-drying technology:Cold-chain infrastructure maturation in Brazil and China is enabling raw food segment expansion without spoilage losses that previously constrained geographic reach.
- Pet insurance penetration:Veterinary-recommended diet coverage in the United States is shifting owner willingness-to-pay toward therapeutic formulations previously restricted to prescription channels.
Market Restraints
- Animal protein input volatility:Chicken and fish meal prices fluctuate with agricultural commodity cycles, compressing gross margins for mid-tier brands lacking long-term supply contracts.
- Grain-free reformulation costs:FDA veterinary cardiologist guidance linking legume-heavy diets to dilated cardiomyopathy is forcing R&D expenditure on alternative carbohydrate sources.
- Concentrated retail gatekeeping:Mass-market shelf access in the United States and Brazil is controlled by chains demanding slotting fees that exclude emerging regional players.
Strategic Opportunities
- Cultivated protein regulatory acceptance:Emerging state legislation in the United States is creating first-mover advantage for brands securing FDA Center for Veterinary Medicine approval for lab-grown meat formulations.
- Direct-to-veterinary distribution:Bypassing retail entirely through clinic-exclusive prescription lines captures higher margins and builds clinical evidence databases.
- Senior pet nutrition:Underdeveloped therapeutic segments for geriatric dogs and cats in China offer white space as veterinary infrastructure matures in tier-one cities.
Industry Challenges
- Veterinary nutritionist talent scarcity:Formulating therapeutic diets requires board-certified specialists whose training pipeline operates on multi-year cycles, constraining R&D velocity.
- Legacy ERP integration:Subscription-based fresh food programs require real-time inventory and cold-chain tracking that conflicts with batch-oriented systems at established manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pet Food Market |
| Market Size in 2026 | $135.6 Billion |
| Market Size in 2035 | $217.68 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dry Food, Wet Food, Treats, Raw Food Ingredient Type: Meat-Based, Grain-Free, Organic, Vegetarian Animal Type: Dogs, Cats, Birds, Small Mammals Packaging Type: Bags, Cans, Pouches, Boxes |
| Companies Covered | J.M. Smucker, Diamond Pet Foods, Mars Petcare, Virbac, Champion Petfoods, Nestlé Purina, Blue Buffalo, Bosch Tiernahrung, Hill's Pet Nutrition, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pet Food Market Strategic Shifts & Innovations
Formulation science and distribution infrastructure are converging to enable veterinary-grade nutrition at consumer price points, while regulatory scrutiny on ingredient sourcing is accelerating transparency investments.
High-pressure processing is displacing traditional extrusion for raw and fresh food categories. Premium pet owners in the United States and United Kingdom are adopting HPP-treated products at double-digit rates annually. This technology is displacing conventional pasteurization's market share in the refrigerated pet food aisle by preserving nutrient bioavailability without thermal degradation.
The FDA Center for Veterinary Medicine's evolving position on grain-free formulations is tightening ingredient disclosure requirements. Manufacturers must now substantiate nutritional adequacy claims with expanded feeding trial documentation. Therapeutic diet producers are most affected, responding by funding longitudinal cardiovascular studies to preempt regulatory action against legume-based recipes.
Subscription auto-replenishment is consolidating purchase decisions into algorithm-driven recommendation engines. Direct-to-consumer platforms are replacing periodic retail stock-ups with customized portioning based on pet health data inputs. This shift is most visible among urban millennial owners in the United States, where churn rates remain low due to embedded veterinary telehealth integrations.
Pet Food Market Segmentation
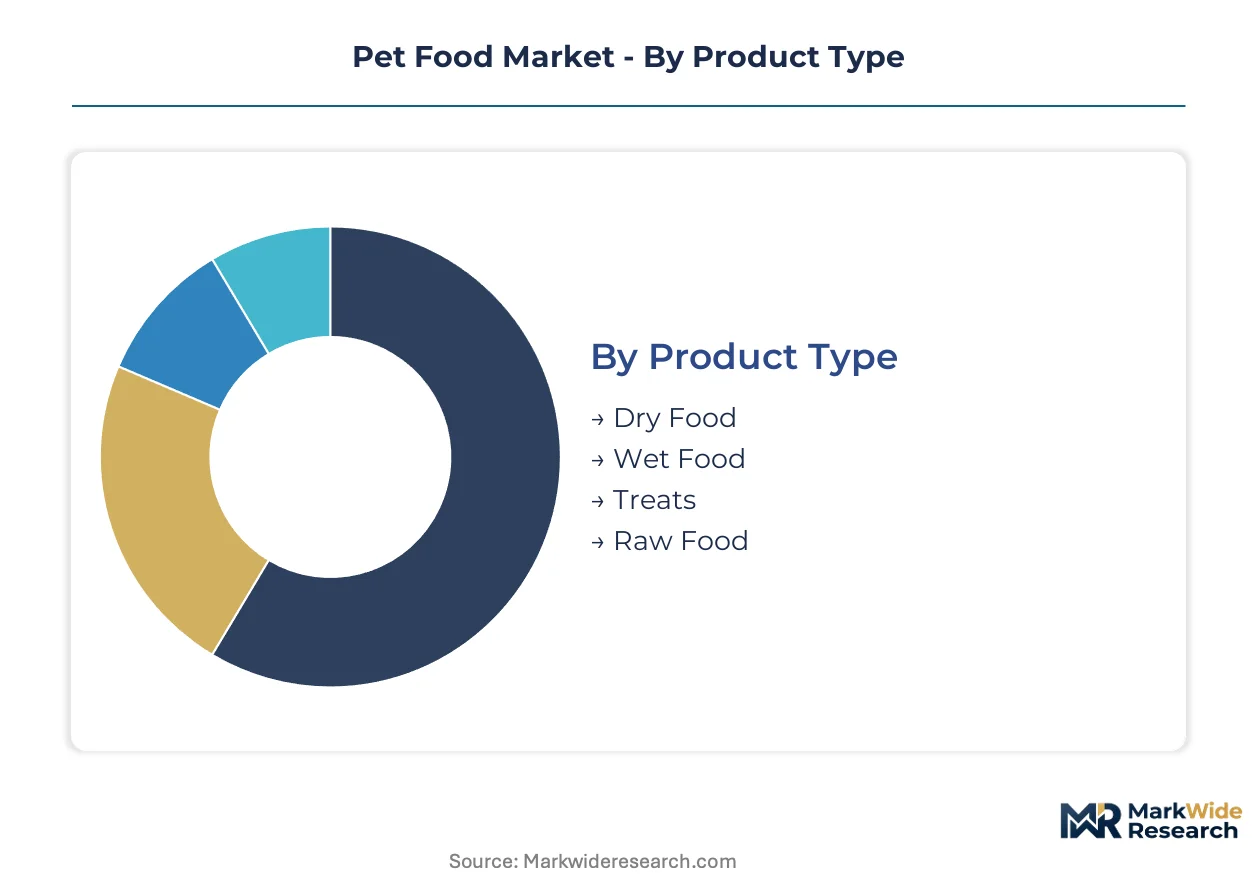
Pet food segmentation reveals divergent growth trajectories across product formats and ingredient philosophies. Manufacturers must calibrate production assets to serve both mass-market volume segments and premium niches demanding specialized supply chains.
Product Type:
Domestic consumption in the United States and Brazil concentrates on shelf-stable formats, while raw food exports from North American freeze-drying facilities target European and Asian premium channels.
- Dry Food:Extruded kibble formulations achieve 12-18 month shelf stability through moisture reduction below 10%. United States mass-market retailers move the highest volumes, though Brazilian logistics networks favor dry formats due to tropical humidity challenges. Dry food holds the largest share; momentum sits with raw alternatives.
- Wet Food:Canned and pouched products contain 75-85% moisture content, supporting feline hydration requirements. Demand clusters among urban cat owners in tier-one Chinese cities where veterinary guidance emphasizes urinary tract health. Wet food maintains stable premium positioning despite higher shipping costs.
- Treats:Functional dental chews and training rewards command per-gram premiums exceeding complete diets. United States pet specialty retailers allocate disproportionate shelf space to treat innovation.
- Raw Food:Minimally processed frozen and freeze-dried recipes bypass thermal degradation. Cold-chain infrastructure maturation in São Paulo and Shanghai is expanding geographic reach beyond North American origins.
Dry food dominates volume metrics; raw formats capture the steepest expansion trajectory as infrastructure investments mature.
Ingredient Type:
Cost tier differentiation separates commodity formulations from certified organic lines requiring multi-year conversion protocols and audit trails.
- Meat-Based:Poultry, beef, and fish meals supply amino acid profiles matching carnivore metabolic requirements. Brazilian chicken meal exports compete with United States rendered protein supplies on global markets. Meat-based formulations anchor mainstream pricing tiers.
- Grain-Free:Legume and tuber carbohydrate substitutes replaced corn and wheat until FDA veterinary cardiologist guidance triggered reformulation waves. Premium United States brands now diversify starch sources to mitigate dilated cardiomyopathy associations.
- Organic:USDA Organic and EU Organic certifications mandate synthetic additive prohibitions and livestock feed restrictions. Supply scarcity limits organic protein availability to premium price points.
- Vegetarian:Plant-protein concentrates and synthetic amino acid supplementation target ethical-consumption segments. European markets show higher acceptance than carnivore-traditional United States or Brazilian markets.
Meat-based formulations retain volume leadership; grain-free lines face structural pressure from veterinary science developments.
Animal Type:
Application-specific nutrition drives formulation divergence between species with distinct metabolic pathways and feeding behaviors.
- Dogs:Omnivore-adapted formulations incorporate broader carbohydrate tolerance than feline diets. United States households maintain the highest per-dog spending on therapeutic and fresh food subscriptions.
- Cats:Obligate carnivore requirements mandate higher protein percentages and taurine supplementation. Wet food penetration exceeds dog markets due to hydration-sensitive urinary physiology.
- Birds:Seed blends and extruded pellets target psittacine nutrition with vitamin A and calcium balancing. Specialty avian veterinarians drive prescription diet recommendations.
- Small Mammals:Rabbit, guinea pig, and hamster formulations emphasize fiber content and dental wear properties. European markets show deeper category development than emerging economies.
Canine nutrition generates absolute revenue scale; feline segments sustain premium pricing power.
Packaging Type:
Customer type and channel format dictate packaging selection, with e-commerce suitability increasingly influencing structural design.
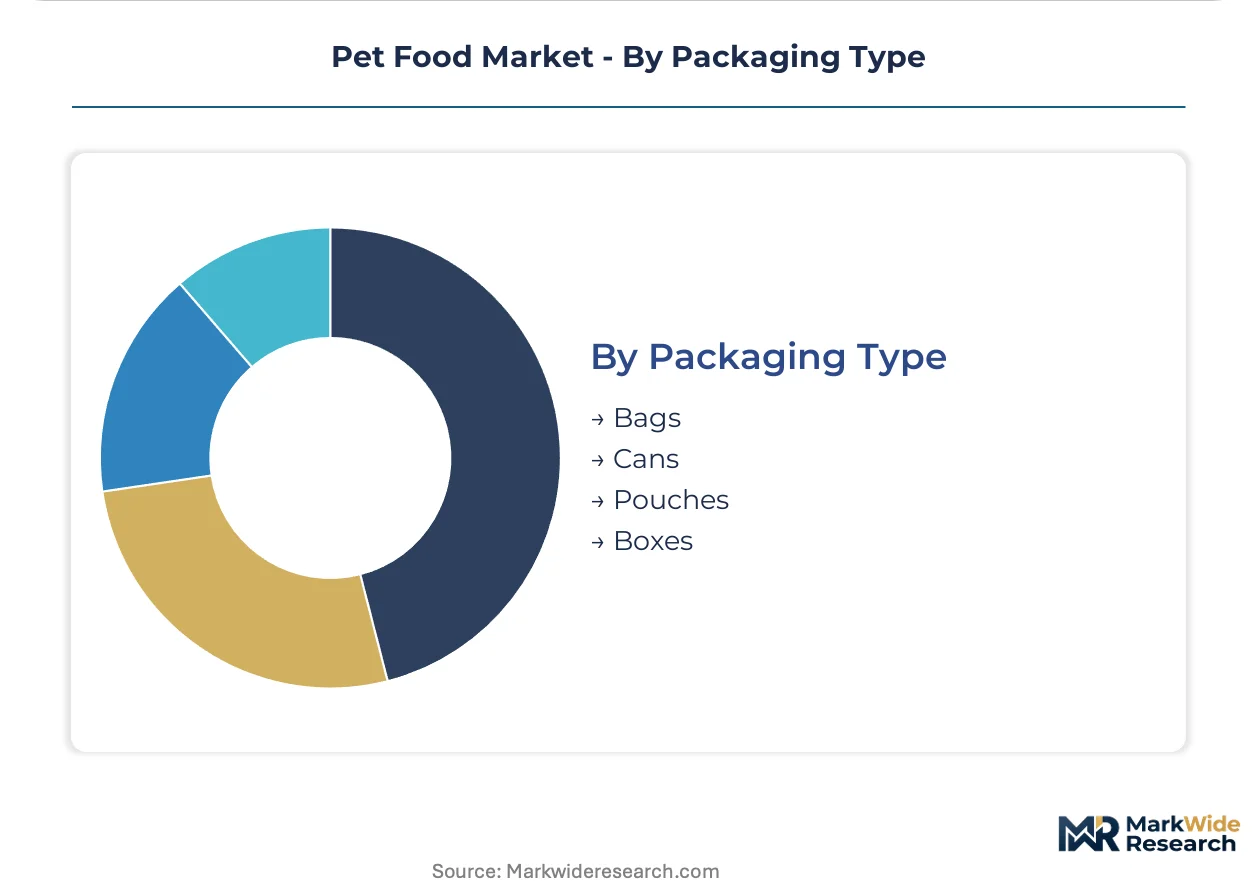
- Bags:Multi-wall paper and plastic laminates protect dry food from oxidation and moisture intrusion. Subscription services in the United States favor resealable bag formats for home delivery efficiency.
- Cans:Steel and aluminum containers enable retort sterilization for wet food shelf stability. Recycling infrastructure variations between the United States and European Union affect material selection.
- Pouches:Flexible retort pouches reduce shipping weight versus cans while enabling single-serve portions. Asian markets adopted pouch formats earlier than North American retail.
- Boxes:Corrugated and rigid packaging supports treat assortments and fresh food insulation. Direct-to-consumer cold-chain programs utilize insulated box configurations with gel packs.
Bags handle the highest product volume; pouches gain share fastest in wet food channel transitions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ingredient sourcing and cold-chain infrastructure concentrate manufacturing capacity in the United States, China, and Brazil, while regulatory compliance costs reshape competitive access across European and Asian distribution networks.
United States
Millennial pet owners drive subscription fresh-food adoption and veterinary-recommended diet expenditure. FDA Center for Veterinary Medicine enforces contaminant thresholds and expanded feeding trial documentation for nutritional adequacy claims. Kansas and Iowa host rendering and extrusion clusters supplying poultry and fish meal proteins to national brands.
China
Tier-one cities generate premium wet food demand among feline owners prioritizing urinary tract health through hydration-focused formulations. SAMR and GB standards mandate additive authorization and import inspection protocols that condition market access for foreign suppliers. Shanghai cold-chain infrastructure expansion enables raw food segment growth previously constrained by spoilage logistics.
Brazil
Tropical humidity challenges favor dry food logistics efficiency across mass-market retail channels. ANVISA feed hygiene regulations align with Mercosur trade bloc standards for cross-border distribution. São Paulo freeze-drying facilities export minimally processed products to European premium channels as cold-chain maturation extends geographic reach.
Germany
Ethical-consumption segments sustain higher vegetarian formulation acceptance than carnivore-traditional markets. EFSA and EU feed hygiene regulations enforce HACCP-based controls and detailed additive authorization for imported products. Bavaria hosts specialized manufacturers serving organic certification tiers requiring multi-year conversion protocols.
Japan
Aging pet demographics elevate geriatric nutrition demand as veterinary infrastructure matures in metropolitan centers. METI and PMDA frameworks govern functional claim substantiation for therapeutic diet categories. Tokyo-Osaka distribution corridors concentrate premium import channels for freeze-dried and high-pressure processed products.
Pet Food Market Key Industry Players
Concentration sits with diversified multinationals possessing veterinary research capabilities and global manufacturing footprints. The vendor base spans three structural tiers: mass-market volume producers, premium specialists with regional ingredient sourcing protocols, and prescription-channel operators building clinical evidence databases. Dominant competitive moves include strategic acquisitions of fresh-food subscription platforms and backward integration into captive protein rendering operations.
Within the multinational tier, Mars Petcare and Nestlé Purina occupy positions defined by in-house veterinary research centers and six-continent supply networks. Champion Petfoods exemplifies the premium specialist archetype through biologically appropriate formulation positioning. Among European operators, Bosch Tiernahrung GmbH represents mid-scale fabrication anchored in German quality-tier segmentation.
| Leading Market Players |
|---|
| J.M. Smucker |
| Diamond Pet Foods |
| Mars Petcare |
| Virbac |
| Champion Petfoods |
| Nestlé Purina |
| Blue Buffalo |
| Bosch Tiernahrung |
| Hill's Pet Nutrition |
| Others |
Cost & Logistics Intelligence
Long-term offtake contracts for poultry and fish meal lock in both supply access and price visibility for United States manufacturers facing volatile agricultural commodity cycles, while subscription-based fresh food programs demand real-time inventory systems that reshape procurement cost structures.
Pricing Analysis
FDA Center for Veterinary Medicine dictates the pricing tier structure through contaminant thresholds and feeding trial documentation requirements that elevate compliance costs. Pricing stratifies across premium therapeutic formulations, standard mass-market extruded kibble, and economy private-label tiers. Cost compression in the mid-market segment is intensifying because animal protein input volatility squeezes brands lacking long-term supply contracts. Mass-market retailers exhibit highest price sensitivity, while veterinary-recommended diet buyers demonstrate lowest elasticity due to insurance coverage expansion.
Supply Chain Analysis
The United States and Brazil anchor global rendering and extrusion capacity, with Kansas and Iowa clusters supplying poultry meal and São Paulo freeze-drying facilities exporting minimally processed products. Supply chains draw from chicken meal, fish meal, and legume carbohydrate substitutes as primary inputs. Single-source vulnerability concentrates in Brazilian chicken meal exports competing with domestic rendered protein supplies. Distribution runs through mass-market retail chains demanding slotting fees, direct-to-consumer subscription platforms, and veterinary clinic-exclusive prescription channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is recovering from grain-free reformulation disruption as veterinary cardiologist guidance forces R&D reinvestment, creating cyclical consolidation pressure on mid-tier brands lacking clinical research capabilities.
For Market Incumbents: Secure backward integration into captive protein rendering operations to defend margins against commodity volatility. Champion Petfoods and Mars Petcare demonstrate how in-house veterinary research centers create formulation moats that emerging players cannot replicate. Consolidate shelf space advantages through HACCP certification investments that satisfy EU feed hygiene regulations for European distribution access. For New Entrants and Emerging Players: Lead with direct-to-veterinary distribution models bypassing retail gatekeeping entirely. Senior pet nutrition in Chinese tier-one cities offers the most penetrable white space as veterinary infrastructure matures. Cultivated protein regulatory acceptance presents a go-to-market angle through FDA Center for Veterinary Medicine approval pathways for lab-grown meat formulations. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among subscription-based fresh food platforms with embedded veterinary telehealth integrations. Long-term viability favors acquisitions of freeze-drying technology operators with cold-chain logistics capabilities across São Paulo and Shanghai corridors. Watch for state-level cultivated protein legislation as the inflection signal triggering first-mover valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rendering | Captive poultry meal supply secures margin stability against commodity cycles. |
| Veterinary Research Center Investment | In-house formulation validation builds therapeutic diet credibility with clinicians. |
| Freeze-Drying Capacity Expansion | Cold-chain infrastructure in São Paulo and Shanghai extends raw food geographic reach. |
| Direct-to-Veterinary Channel Development | Clinic-exclusive prescription lines capture higher margins and clinical evidence databases. |
| Cultivated Protein Regulatory Approval | FDA Center for Veterinary Medicine clearance creates first-mover advantage in lab-grown formulations. |
Research Approach
Two parallel data streams informed the analysis: primary interviews with veterinary nutritionists, pet food manufacturing executives, retail category buyers, and cold-chain logistics specialists; and secondary validation through FDA Center for Veterinary Medicine filings, AAFCO model regulations, EU feed hygiene documentation, and customs trade records for poultry meal and fish meal flows. Bottom-up segmentation modeling triangulated against top-down market sizing across product format, ingredient philosophy, and animal type dimensions.
Across the analysis window, volume and value outputs reflect econometric modeling of pet ownership demographics, veterinary infrastructure development, and cold-chain capital expenditure cycles. Segmentation dimensions include product format, ingredient type, animal species, packaging configuration, and regional regulatory cluster. CAGRs were derived from trend extrapolation of premiumization rates and subscription adoption curves, with specific inputs from pet insurance penetration trajectories and freeze-drying technology diffusion patterns.
Forecasts assume regulatory continuity in FDA, AAFCO, and EU feed hygiene regimes; material policy shifts on grain-free formulations or cultivated protein acceptance would require re-modeling. Model boundaries exclude non-commercial pet nutrition and veterinary pharmaceutical adjacencies. Recalibration cycles align with material shifts in veterinary cardiologist guidance and state-level cultivated protein legislation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Vegan Dog Food Market
Pet Care Products
Modern Cat Furniture Market
Pet Care Products
Cat Mat Market
Pet Care Products
Dog Food Market
Pet Care Products
UK Pet Boarding Market
Pet Care Products
Pet Car Seat Market
Pet Care Products
Natural Cat Litter Products Market
Pet Care Products
Smart Pet Leash Market
Pet Care Products
Pet Meal Kit Delivery Services Market
Pet Care Products
Pet Oral Care Market
Pet Care Products
Dog Clothing and Accessories Market
Pet Care Products
Europe Dog Food Market
Pet Care Products
Pet Smart Tracker Market
Pet Care Products
Smart Pet Collar Market
Pet Care Products
Pet Pee Pads Market
Pet Care Products
Italy Pet Food Market