
 United Kingdom Pet Food Market | 2026-2036
United Kingdom Pet Food Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Pet Food Market Analytics
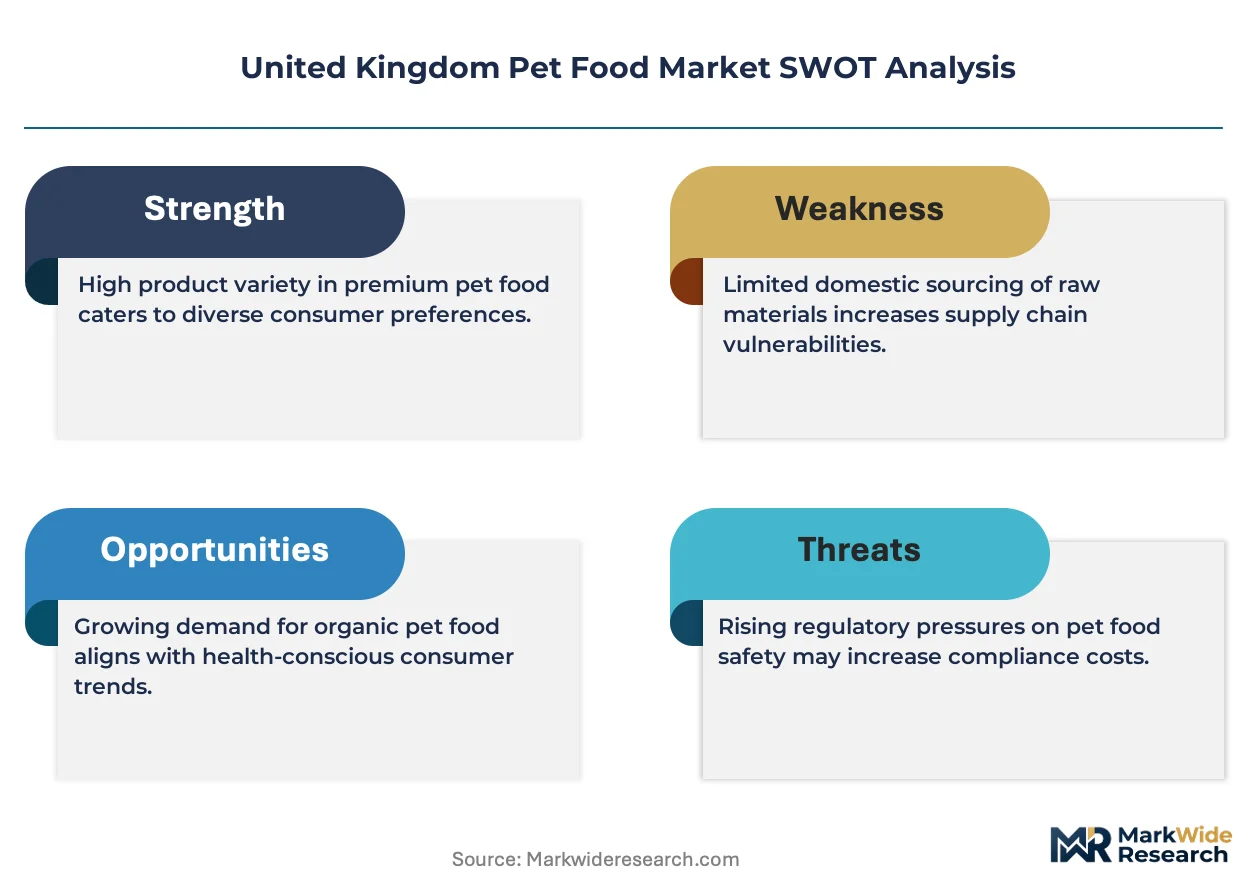
Scotland's emerging pet food manufacturing corridor is reconfiguring supply dynamics for northern UK distribution. Mars Petcare UK leverages its Grimsby production complex to sustain national dry food output. Nestlé Purina Ltd anchors premium wet food development through its Wisbech R&D facility. GA Pet Food Partners competes in private-label manufacturing with specialized cold-pressed capabilities.
United Kingdom pet food encompasses nutritionally complete and complementary feeds formulated for domesticated companion animals, typically meeting FEDIAF nutritional guidelines through controlled protein, fat, and micronutrient profiles manufactured via extrusion, canning, or raw processing methods. Dry food occupies the largest volume share due to shelf stability and cost efficiency, while raw food represents the fastest-expanding category driven by humanization trends. Wet food commands concentrated margin pools in the premium tier, particularly within veterinary-recommended therapeutic segments.
The Food Standards Agency enforces feed hygiene regulations that shape manufacturing facility standards across England, Wales, and Northern Ireland. DEFRA's animal by-product rules constrain raw material sourcing, while FEDIAF codes influence nutritional claim permissibility on UK labeling. Trading standards officers at local authority level conduct market surveillance that determines product access for imported and artisan brands. Stakeholders must monitor evolving post-Brexit import certification requirements and anticipate whether extended producer responsibility frameworks will mandate packaging redesign.
Market Dynamics
Cold-pressed manufacturing is compressing production timelines while elevating nutritional density benchmarks across British wet food and treat formulations. This thermal-minimization approach is forcing incumbent extrusion-based facilities to retool or cede premium positioning.
Growth Catalysts
- FSA Labeling Modernization:The Food Standards Agency's updated pet food declaration requirements are compelling manufacturers to reformulate with cleaner ingredient decks, which urban retailers now feature as shelf differentiators.
- Veterinary Channel Expansion:Prescription therapeutic diets distributed through UK veterinary practices are capturing margin pools that conventional retail cannot access, with clinics in Greater London serving as launch corridors.
- Aging Pet Demographics:Joint-support and cognitive-function formulations for senior dogs are commanding repeat purchase loyalty among owners in the South East, where disposable income concentration sustains premium pricing.
Market Restraints
- Protein Input Volatility:DEFRA's animal by-product sourcing constraints limit domestic poultry and fish meal availability, forcing manufacturers to absorb import cost fluctuations or reformulate protein profiles.
- Grimsby Supply Concentration:National dry food output depends heavily on Lincolnshire production clusters, creating geographic vulnerability to logistics disruptions or regional labor shortages.
- Raw Food Safety Friction:Trading standards surveillance at local authority level imposes batch-testing burdens on artisan raw brands that industrial extrusion facilities bypass through kill-step validation.
Strategic Opportunities
- Scotland Manufacturing Corridor:Emerging production capacity in Scottish central belt regions offers northern distribution reach with lower real estate and labor costs than southern England alternatives.
- Subscription Direct-to-Consumer:Cold-pressed and fresh-frozen formats are bypassing traditional retail markups through recurring delivery models targeting urban apartment dwellers without vehicle access.
- Post-Brexit Export Certification:FEDIAF-compliant UK manufacturers can leverage mutual recognition agreements to access Irish Republic and select Commonwealth markets with reduced technical barriers.
Industry Challenges
- Refrigerated Last-Mile Infrastructure:Raw and fresh-frozen distribution requires temperature-controlled logistics networks that remain underdeveloped outside London and major metropolitan zones.
- Extended Producer Responsibility Uncertainty:Pending packaging redesign mandates create formulation and sourcing hesitancy as manufacturers await definitive recycling-content thresholds and compliance timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Pet Food Market |
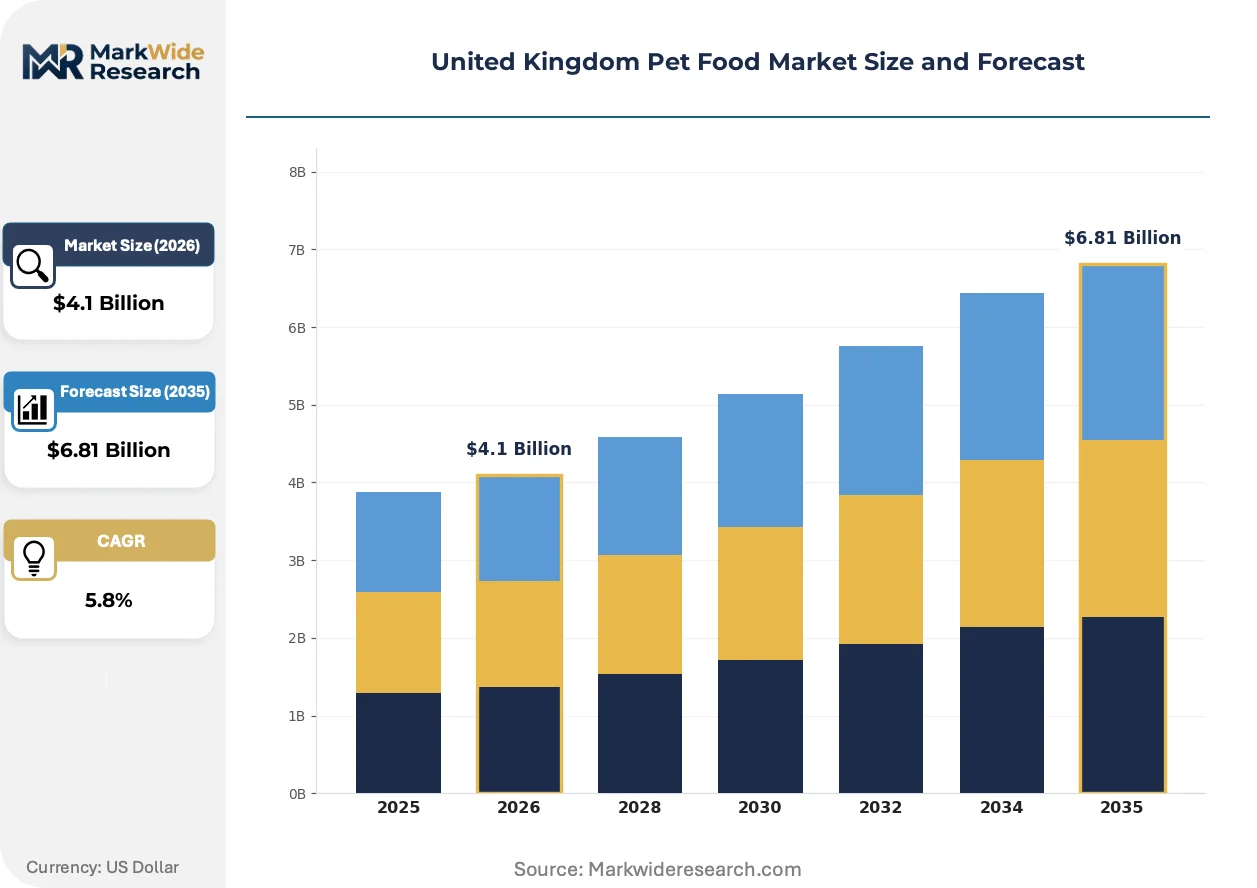
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dry Food, Wet Food, Treats, Raw Food Animal Type: Cats, Dogs, Birds, Small Mammals Distribution Channel: Supermarkets, Pet Stores, Online Retail, Veterinary Clinics Price Tier: Premium, Mid-Range, Economy, Budget |
| Companies Covered | Hill's Pet Nutrition Ltd, Nestlé Purina Ltd, Mars Petcare UK, Pets Choice, GA Pet Food Partners, Nestle UK Ltd, Butcher's Pet Care Ltd, Crown Pet Foods Ltd, Inspired Pet Nutrition Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Pet Food Market Evolving Landscape
Humanization pressures are collapsing the boundary between pet nutrition and human food production standards, with British manufacturers adopting pharmaceutical-grade quality systems and clean-label ingredient sourcing previously reserved for premium human consumption categories.
Cold-pressed manufacturing is migrating from niche artisan production to mid-scale commercial deployment across the United Kingdom. This low-temperature process preserves heat-sensitive vitamins and enzymes that extrusion destroys. Specialist manufacturers in Lancashire and Yorkshire are scaling output to serve national retail chains. The technology is migrating from premium positioning toward mass-market accessibility, compressing the price gap between conventional dry food and nutritionally dense alternatives.
DEFRA's evolving animal by-product regulations are tightening traceability requirements for protein sourcing across England, Wales, and Northern Ireland. These rules now mandate documented chain-of-custody from slaughterhouse to finished product. Wet food and raw categories face disproportionate compliance burden due to higher fresh meat content. Manufacturers are responding by consolidating supplier relationships and investing in in-house microbiological testing capacity.
Urban pet owners are consolidating purchasing decisions around subscription platforms that combine veterinary telehealth with customized nutrition delivery. This bundling displaces the traditional retail discovery process where impulse treat purchases drove basket value. Digital-native brands capture lifetime value through data-driven portion recommendations. The shift concentrates most visibly in Greater London, where apartment living and transit dependency already favor home delivery over warehouse club stocking.
United Kingdom Pet Food Market Segmentation
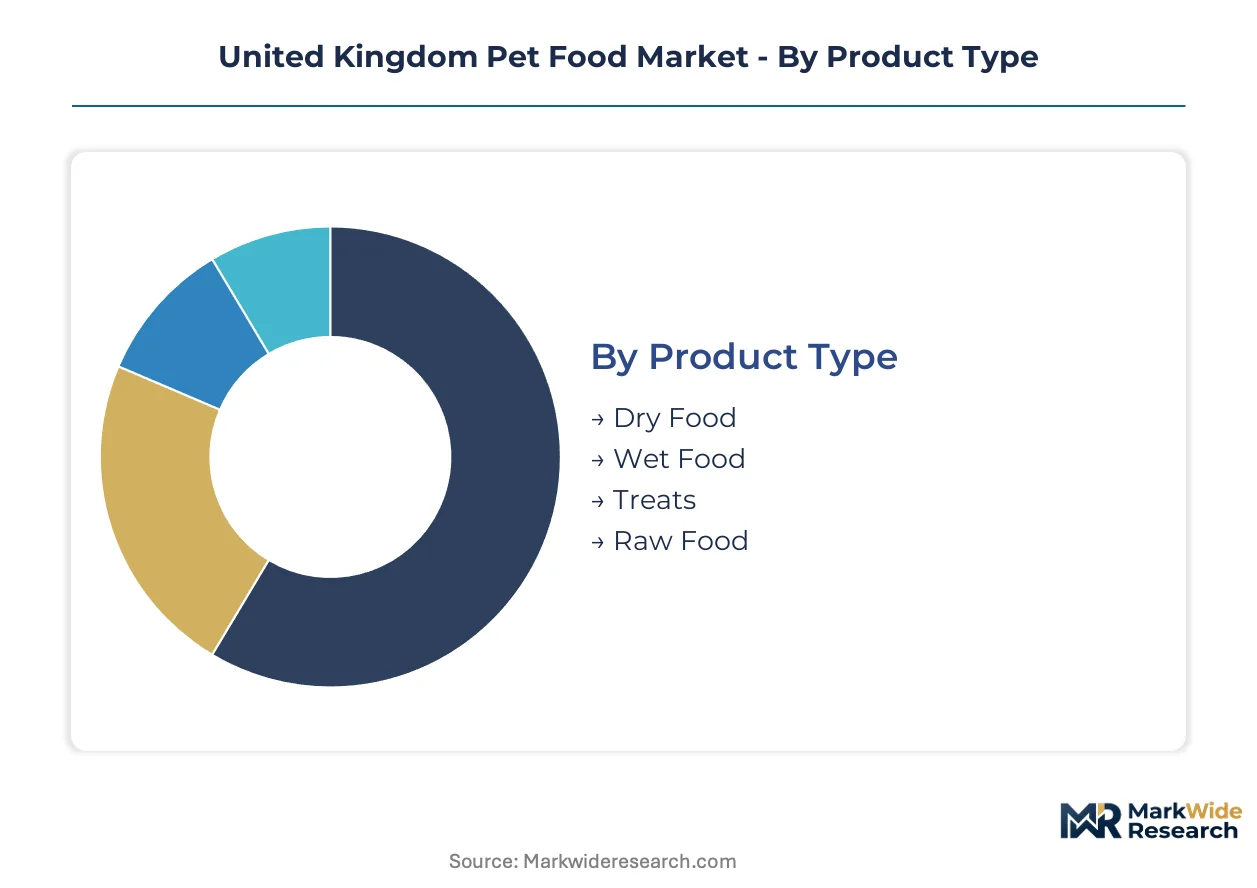
Segmentation in United Kingdom pet food reveals how purchasing patterns fragment across feeding philosophies, species-specific nutrition needs, and channel loyalty. Manufacturers must align formulation investments with distinct margin profiles rather than treating the market as monolithic.
Product Type:
After-sales service intensity varies sharply across product types, with raw and wet formats demanding refrigeration support, nutritional consultation, and complaint resolution that dry food manufacturers rarely provide.
- Dry Food:Extruded kibble formulations achieve shelf stability through moisture reduction below 10%, enabling bulk retail distribution without cold-chain dependency. Demand concentrates in suburban households across the South East, where Mars Petcare's Grimsby complex supplies national supermarket chains with consistent volume pricing.
- Wet Food:Canned and pouch formats retain higher moisture content and palatability, requiring precision thermal processing to achieve commercial sterility. Greater London veterinary clinics drive premium wet food adoption through prescription therapeutic positioning that commands recurring subscription purchases.
- Treats:Functional and indulgent reward products carry elevated margin structures with minimal nutritional completeness requirements.
- Raw Food:Minimally processed fresh and frozen formats face DEFRA animal by-product traceability mandates that industrial extrusion bypasses through validated kill steps.
Dry food holds the largest share; momentum sits with raw food.
Animal Type:
Species-specific formulation requirements drive divergent R&D investment patterns, with canine nutrition commanding the deepest clinical trial infrastructure and feline formulations demanding precise taurine and arachidonic acid supplementation.
- Dogs:Omnivorous nutritional profiles accommodate grain-inclusive and grain-free formulations across all price tiers, with senior joint-support and cognitive-function variants capturing premium pricing in affluent South East postcodes.
- Cats:Obligate carnivore metabolism mandates higher protein inclusion and specific amino acid fortification that elevates manufacturing complexity above canine equivalents. Urban apartment dwellers in Greater London sustain demand for portion-controlled wet food formats that address feline urinary health concerns.
- Birds:Seed, pellet, and nectar formulations serve avian species with highly specialized digestive requirements and limited volume scale.
- Small Mammals:Rabbit, guinea pig, and hamster feeds occupy niche positioning with hay-based and extruded pellet options.
Dogs dominate volume; cats deliver the steepest expansion trajectory in premium wet segments.
Distribution Channel:
Channel selection determines margin capture and customer data access, with veterinary and online routes displacing traditional retail discovery for health-conscious owners.
- Supermarkets:High-volume, low-margin distribution of mainstream dry and wet formats depends on shelf-space negotiations with Tesco, Sainsbury's, and Asda that favor established manufacturers with promotional funding capacity.
- Pet Stores:Specialist retailers including Pets at Home provide assisted selling environments where staff training drives premium conversion and private-label penetration.
- Online Retail:Direct-to-consumer platforms and Amazon marketplace listings enable subscription models and cold-pressed niche brands to bypass traditional retail markups.
- Veterinary Clinics:Prescription therapeutic diets distributed through CVS Group and independent practices capture margin pools inaccessible to conventional retail, with Greater London clinics serving as launch corridors for new formulations.
Supermarkets retain volume leadership; online channels are gaining share fastest through subscription retention models.
Price Tier:
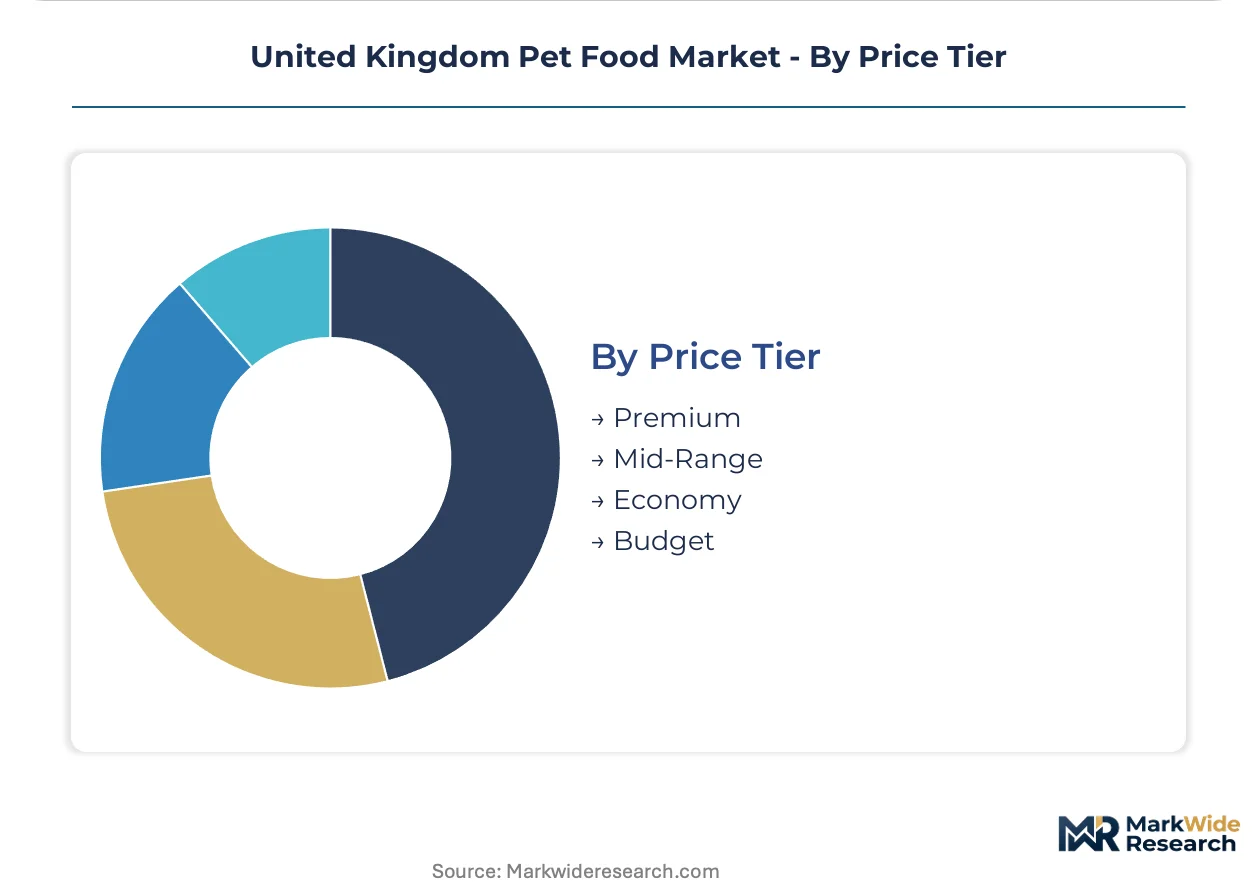
Price stratification reflects ingredient sourcing transparency, manufacturing method, and nutritional claim substantiation rather than simple formulation cost.
- Premium:Cold-pressed, human-grade ingredient, and veterinary-recommended formulations command pricing multiples through FEDIAF nutritional adequacy verification and clean-label positioning that urban professionals in Greater London prioritize.
- Mid-Range:Established branded products with balanced nutritional profiles and moderate ingredient quality serve cost-conscious owners seeking reliability without therapeutic positioning.
- Economy:Private-label and value-branded dry foods compete on price per kilogram with standard extrusion processing and commodity protein sourcing.
- Budget:Lowest-tier products prioritize caloric density over nutritional optimization, facing regulatory scrutiny under FSA labeling modernization requirements.
Premium tier captures margin concentration; economy and budget segments face compression from private-label expansion and ingredient cost volatility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dry food manufacturing clusters heavily in Lincolnshire, while wet food and cold-pressed capacity disperses across southern England and Scotland. Regional consumption patterns split between premium subscription models in affluent metros and value-oriented bulk purchasing in suburban and rural zones.
Greater London
Veterinary clinic density and apartment-dwelling pet ownership drive premium wet food and subscription fresh-frozen demand. Trading standards officers at local authority level enforce batch-testing protocols that artisan raw brands navigate through specialized compliance infrastructure. Fulfillment centers in Croydon and Enfield anchor cold-chain distribution networks serving the capital's subscription economy.
South East England
Disposable income concentration in Surrey, Kent, and Sussex postcodes sustains pricing multiples for senior dog formulations and functional treats. Nestlé Purina's Wisbech R&D facility anchors premium wet food development within this catchment area. Independent pet retailers in Brighton and Guildford serve as launch corridors for clean-label positioning.
Scotland
Central belt manufacturing capacity offers northern distribution reach with lower real estate and labor costs than southern alternatives. Cold-pressed specialists in Lanarkshire and Fife scale output to serve national retail chains. Scottish Enterprise incentive programs support food manufacturing investment that pet food producers leverage for facility expansion.
Midlands
Logistics connectivity through the M1 corridor positions Birmingham and Leicester as dry food distribution hubs serving northern England and Wales. GA Pet Food Partners operates private-label manufacturing from Lancashire-adjacent facilities with specialized thermal-minimization capabilities. Regional supermarket distribution centers consolidate volume pricing for economy-tier extruded products.
Wales and Northern Ireland
Rural pet ownership patterns favor bulk dry food purchasing through agricultural merchants and cooperative retail structures. DEFRA animal by-product regulations apply with equivalent force, though local authority trading standards capacity varies. Manufacturing presence remains limited, with distribution dependence on English supply corridors.
United Kingdom Pet Food Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with formulation and manufacturing technology. The United Kingdom market consolidates around three multinational parents controlling volume production, while mid-scale private-label manufacturers and artisan cold-pressed specialists fragment the premium tier. Strategic archetypes include vertically integrated nutrition platforms, contract manufacturing specialists, and direct-to-consumer digital natives. Competitive moves concentrate on cold-pressed capacity expansion and veterinary channel partnerships that capture prescription diet margins.
Among the integrated nutrition platforms, Mars Petcare UK and Nestlé Purina Ltd represent multinational manufacturing presence with national distribution infrastructure. GA Pet Food Partners occupies a position within the contract manufacturing tier, exemplifying private-label production specialization. These three anchors demonstrate how scale-driven parents coexist with manufacturing-service specialists in a market where thermal-processing technology defines competitive differentiation.
| Leading Market Players |
|---|
| Hill's Pet Nutrition Ltd |
| Nestlé Purina Ltd |
| Mars Petcare UK |
| Pets Choice |
| GA Pet Food Partners |
| Nestle UK Ltd |
| Butcher's Pet Care Ltd |
| Crown Pet Foods Ltd |
| Inspired Pet Nutrition Ltd |
| Others |
Value Network & Pricing Analysis
DEFRA's animal by-product sourcing constraints determine both the spread between premium and economy tiers and the geographic clustering of manufacturing capacity. Protein input volatility compresses margins at the budget end while justifying pricing multiples for traceability-certified alternatives.
Pricing Analysis
The Food Standards Agency's updated pet food labeling requirements dictate the pricing tier structure across the United Kingdom market. Premium-mid-economy pricing differentiation rests on FEDIAF nutritional adequacy verification and clean-label positioning that urban professionals prioritize. Cost compression in the budget segment is intensifying because commodity protein sourcing faces DEFRA traceability mandates. Veterinary clinics demonstrate the least price sensitivity, while suburban bulk purchasers of dry food exhibit the highest.
Supply Chain Analysis
GA Pet Food Partners and Mars Petcare UK's Grimsby complex hold dominant contract-manufacturing capacity for extruded and cold-pressed production. Domestic supply draws from Lincolnshire poultry meal, Scottish fish processing by-products, and imported South American soya derivatives. Single-source vulnerability concentrates in the Grimsby corridor, where national dry food output rests on one geographic cluster. Distribution runs through supermarket regional distribution centers, veterinary clinic networks, and direct-to-consumer fulfillment hubs in Greater London.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United Kingdom pet food market functions as a service-attach opportunity where subscription nutrition platforms and veterinary telehealth bundles expand faster than conventional retail product sales.
For Market Incumbents: Entrench cold-pressed manufacturing capabilities before mid-scale competitors achieve national retail distribution. Mars Petcare UK and Nestlé Purina Ltd should consolidate supplier relationships to secure protein traceability documentation under tightening DEFRA rules. Channel control through veterinary clinic partnerships represents the critical defensive lever against digital-native subscription entrants.
For New Entrants and Emerging Players: Scotland's central belt manufacturing corridor represents the most penetrable entry point for northern distribution reach without southern England real estate premiums. Artisan raw food producers in Lancashire and Yorkshire can bypass supermarket slotting fees through direct-to-consumer subscription models targeting apartment-dwelling pet owners in Greater London. A go-to-market angle combining cold-pressed nutrition with veterinary telehealth bundling captures lifetime value through data-driven portion recommendations.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors private-label manufacturing specialists with thermal-minimization capabilities. Long-term viability across the projection horizon rests on regulatory compliance infrastructure rather than brand equity alone. Acquisition targets should demonstrate FEDIAF certification, in-house microbiological testing capacity, and established veterinary channel relationships. The signal to watch is post-Brexit export certification reciprocity with Irish Republic and Commonwealth markets.
| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Pressed Capacity Expansion | Thermal-minimization technology preserves heat-sensitive enzymes that extrusion destroys, commanding premium positioning. |
| Veterinary Channel Partnership | Prescription therapeutic distribution through CVS Group clinics captures margin pools inaccessible to conventional retail. |
| Subscription Platform Launch | Recurring delivery models bypass traditional retail markups while capturing customer lifetime value through data. |
| Scotland Manufacturing Footprint | Central belt production capacity offers northern distribution reach with lower labor costs than southern alternatives. |
| Traceability Certification Investment | DEFRA-compliant chain-of-custody documentation enables premium pricing through clean-label positioning. |
Research Methodology
A standing panel of pet food manufacturing executives, veterinary practice managers, supermarket category buyers, and trading standards officers provided ongoing calibration throughout the study. Primary interviews with these stakeholders combined with secondary validation from FEDIAF nutritional guidelines, DEFRA animal by-product regulations, Food Standards Agency labeling requirements, and Nielsen retail audit data. Bottom-up volume modeling and top-down value triangulation anchored the analytical framework.
Scenario-bracketing around protein input volatility, regulatory enforcement intensity, and subscription adoption curves shaped the projection methodology. Segmentation dimensions modeled include product type, animal species, distribution channel, price tier, and regional consumption cluster. CAGRs were derived through trend extrapolation of historical volume patterns adjusted for structural shifts in cold-pressed manufacturing adoption and veterinary channel expansion.
Macroeconomic conditions sit as an overlay; deviation in disposable income concentration across Greater London and the South East, or shifts in post-Brexit import certification requirements, would shift the trajectory. Forecasts reflect documented assumptions about manufacturing capacity expansion timelines and regulatory enforcement consistency. Quarterly review of veterinary clinic prescription volumes, cold-pressed SKU proliferation, and Scotland manufacturing investment announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
North America Functional Pet Treat Market
Pet Care Products
Automatic Dog Feeder Market
Pet Care Products
South Africa Pet Boarding Market
Pet Care Products
Bird Toy Market
Pet Care Products
Asia-Pacific Pet Treats Market
Pet Care Products
Dog Box Market
Pet Care Products
Dog Brush Market
Pet Care Products
Dehydrated Pet Food Market
Pet Care Products
South America Pet Treats Market
Pet Care Products
Pet Oral Care Products Market
Pet Care Products
Pet Apparel Market
Pet Care Products
Europe Pet Clothing Market
Pet Care Products
Fish Based Pet Food Market
Pet Care Products
South Korea Dog Food Market
Pet Care Products
Dog Hats Market
Pet Care Products
Pet Hair Care Market