
 Pet Tag Market | 2026-2036
Pet Tag Market Size, Share, and Industry Trends Forecast 2026-2036
Pet Tag Market Analytics
Veterinary clinic procurement is reconfiguring how pet tag manufacturers reach end users. GoTags leverages direct-to-consumer engraving platforms to sustain margin control across digital channels. LuckyPet anchors wholesale supply relationships with independent pet retailers, while Providence Engraving competes through specialized bulk-order services for animal shelters.
Pet tags are identification accessories manufactured from stainless steel, aluminum, plastic, or brass, typically incorporating engraved text, QR codes, or embedded NFC chips to link lost animals with owner contact data. Engraved tags retain the largest volume share due to low unit cost and universal compatibility with collar hardware, though smart tags represent the fastest-expanding margin pool as connectivity features command premium pricing. Silicone tags occupy a niche position among price-sensitive buyers seeking lightweight, noise-reduced alternatives for indoor pets.
FDA guidelines on animal device labeling intersect with FCC regulations governing RFID and GPS transmission frequencies in smart tag variants. The EU Green Deal's material sourcing requirements and REACH chemical restrictions shape aluminum and brass supply decisions for exporters serving European veterinary clinics. Stakeholders must monitor evolving interoperability standards between proprietary pet tracking platforms and universal microchip databases.
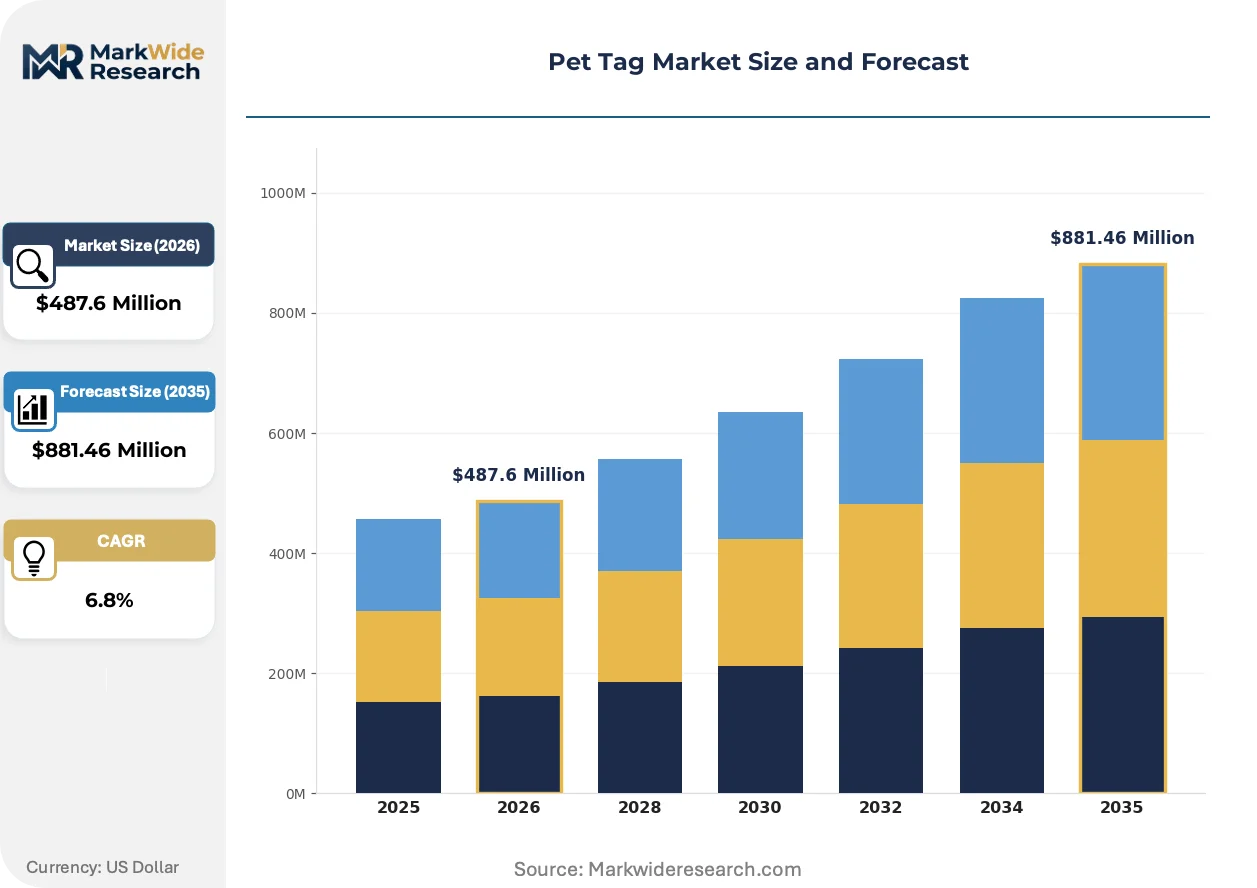
Market Dynamics
Smart tag integration with NFC and GPS tracking technology is compressing traditional engraved tag margins while creating parallel premium price tiers. Veterinary clinic procurement programs are consolidating purchase volumes and demanding interoperability guarantees that fragment manufacturer R&D priorities.
Growth Catalysts
- FCC frequency allocation for pet tracking devices:Standardized transmission bands enable cross-platform GPS tag compatibility, reducing consumer switching costs and expanding addressable demand for connected accessories.
- Veterinary clinic bulk procurement:North American clinic networks are centralizing tag supply through exclusive distributor agreements, creating predictable volume pipelines for compliant manufacturers.
- QR code resurgence in shelter intake systems:Municipal animal control facilities are mandating scannable identification to accelerate reunification workflows, driving aluminum tag upgrades from basic engraved plates.
Market Restraints
- Aluminum price volatility:Raw material cost swings compress margin buffers for mid-tier stamped tag producers dependent on commodity metal sourcing.
- REACH chemical restrictions on brass alloys:European import compliance requires lead-free formulations that increase unit production costs and extend certification timelines.
- Smartphone-dependent NFC functionality:Tag utility collapses where cellular coverage fails or owner device compatibility gaps persist, limiting rural deployment viability.
Strategic Opportunities
- Subscription-based location services:GPS tag vendors can attach recurring revenue streams to hardware sales through geofencing alerts and activity monitoring dashboards.
- EU Green Deal material sourcing incentives:Recycled aluminum certification unlocks preferential procurement status with sustainability-mandated veterinary chains.
- Silicone tag noise reduction niche:Lightweight alternatives for indoor-only pets address urban owner preferences suppressed by traditional metal tag clatter.
Industry Challenges
- Microchip database interoperability:Proprietary smart tag platforms resist integration with universal veterinary registries, creating data silos that frustrate clinic adoption.
- Engraving equipment capex cycles:Laser systems for permanent QR marking require capital outlays that strain smaller manufacturer balance sheets.
- ISO 11784/11785 compliance testing:RFID tag frequency certification demands third-party validation that extends product launch timelines by quarters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pet Tag Market |
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engraved Tags, QR Code Tags, Smart Tags, Silicone Tags Material: Stainless Steel, Aluminum, Plastic, Brass Customization: Custom Engraving, Color Options, Shape Variations, Pattern Designs End User: Pet Owners, Veterinary Clinics, Pet Adoption Centers, Pet Retailers |
| Companies Covered | LuckyPet, K9king, GoTags, Pet-tastic, Io Tags, Dr. Fremont's, Providence Engraving, LogoTags, Road ID, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pet Tag Market Evolving Landscape
Digital identification protocols are fragmenting legacy engraved tag demand while elevating connectivity features to primary purchase criteria. Manufacturers are recalibrating R&D budgets toward sensor integration and cloud platform development.
Passive NFC chips embedded in stainless steel tags enable tap-to-contact functionality without battery dependency. Veterinary clinics in Germany and France are piloting these units for instant owner notification during emergency intake. Basic engraved plates without electronic functionality are rendering obsolete in metropolitan markets where smartphone penetration exceeds ninety percent.
EU Green Deal material sourcing requirements are forcing aluminum and brass suppliers to document recycled content percentages and carbon footprint data. Exporters serving European veterinary clinics must reconfigure supply chains to capture recycled metal certifications or face exclusion from tender processes. REACH chemical restrictions on nickel release rates particularly affect polished brass tag finishes.
Direct-to-consumer engraving platforms are compressing traditional wholesale distributor margins. Pet owners in the United States increasingly design and order customized tags through manufacturer websites, bypassing retail markup. Independent pet stores are responding by unbundling tag sales from collar attachments and emphasizing same-day engraving services as differentiation.
Pet Tag Market Segmentation
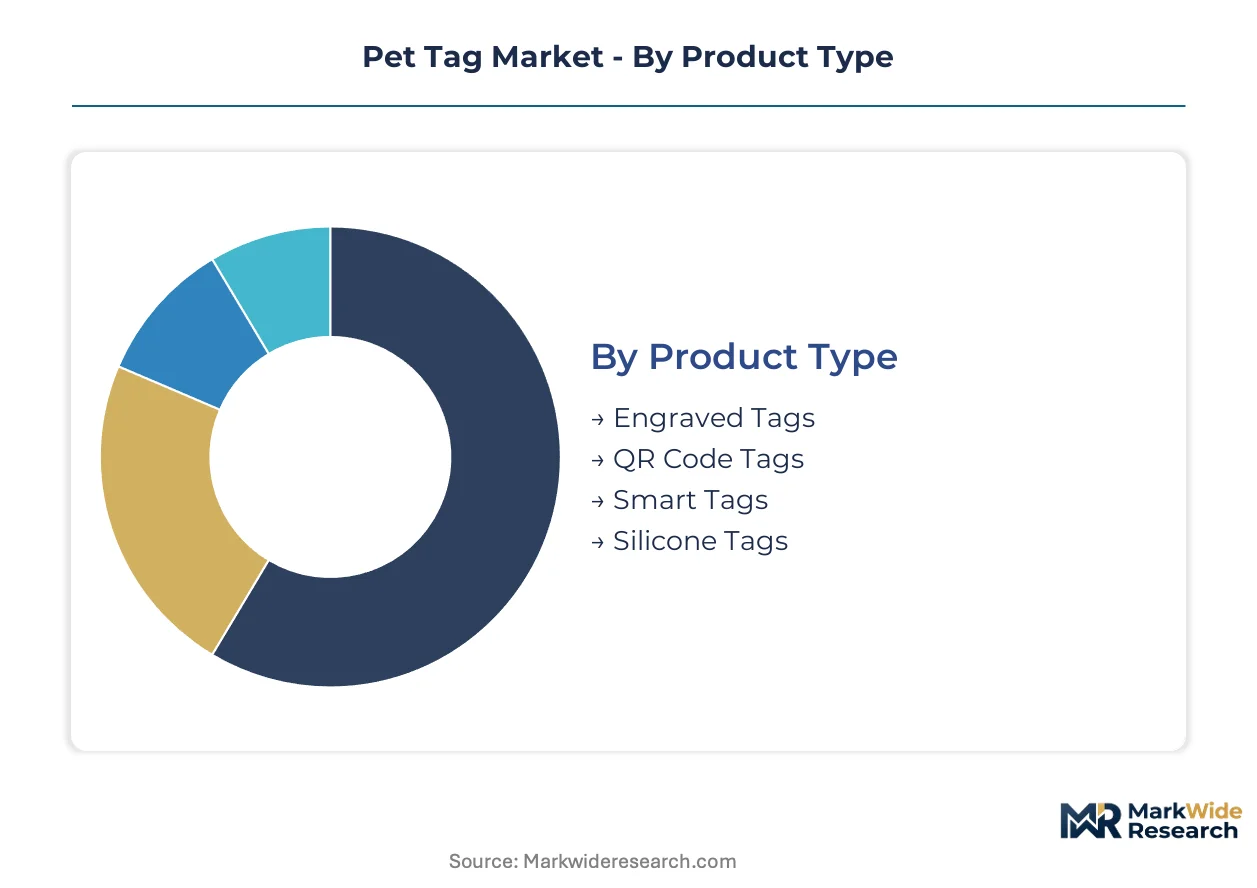
Pet tag manufacturers configure production lines around four distinct axes that determine margin structure and channel access. Product type and material selection drive unit economics, while customization depth and end-user concentration shape pricing power and inventory requirements.
Product Type:
Cost tier stratification separates commoditized identification plates from premium-connected accessories with recurring revenue potential.
- Engraved Tags:Laser-etched stainless steel or aluminum plates carry owner contact data through permanent physical marking. United States pet retailers move the highest volumes of these units through impulse-purchase displays near checkout counters, though margin compression from direct-to-consumer engraving platforms is eroding wholesale profitability.
- Smart Tags:Battery-powered or passive NFC devices embed GPS receivers and cellular transmitters for real-time location tracking. Veterinary clinics in Germany and France are piloting these for emergency intake workflows, but smartphone dependency and subscription fatigue limit rural United States penetration.
- QR Code Tags:Scannable matrix codes printed on anodized aluminum link to dynamic online profiles updatable by owners. Municipal animal control facilities in the United States are mandating these for accelerated shelter reunification.
- Silicone Tags:Flexible polymer construction eliminates metal-on-metal noise for indoor-only pets. Urban apartment dwellers in dense United States metros favor these lightweight alternatives.
Engraved tags command the established base. The steepest expansion runs through smart tags.
Material:
Raw material selection determines corrosion resistance, engraving fidelity, and regulatory compliance burden across export markets.
- Stainless Steel:Grade 304 or 316 alloys provide maximum durability for active outdoor dogs exposed to salt water and abrasion. United States coastal markets sustain premium pricing for marine-grade finishes.
- Aluminum:Anodized 6061-T6 sheet enables vibrant color finishes through electrolytic oxidation. EU Green Deal recycled content requirements are forcing suppliers to document carbon footprint data for European veterinary clinic tenders.
- Brass:Copper-zinc alloys accept deep rotary engraving with distinctive gold appearance. REACH chemical restrictions on nickel release rates and lead-free formulations extend certification timelines for European exports.
- Plastic:Injection-molded ABS or polycarbonate serves price-sensitive shelter bulk orders where unit cost dominates durability concerns.
Stainless steel anchors premium positioning. Aluminum is climbing the fastest on sustainability-linked procurement.
Customization:
Application-specific personalization depth separates mass-produced commodity tags from higher-margin bespoke orders.
- Custom Engraving:Laser systems cut owner names, phone numbers, and medical alerts into metal substrates with permanent resolution. Direct-to-consumer platforms in the United States now capture this value previously retained by retail intermediaries.
- Color Options:Anodized aluminum and powder-coated finishes match collar aesthetics or visibility requirements. Hunting dog owners in rural United States states prioritize blaze orange for field safety.
- Shape Variations:Bone, heart, and circular blanks accommodate breed-owner aesthetic preferences. Pet retailers in the United States rotate seasonal shapes to drive repeat traffic.
- Pattern Designs:Printed or embossed textures including camouflage, floral, and geometric motifs target gift-market purchasers. United States e-commerce channels enable micro-batch pattern experimentation without inventory risk.
Custom engraving captures the value pool. Pattern designs are expanding most quickly through digital printing flexibility.
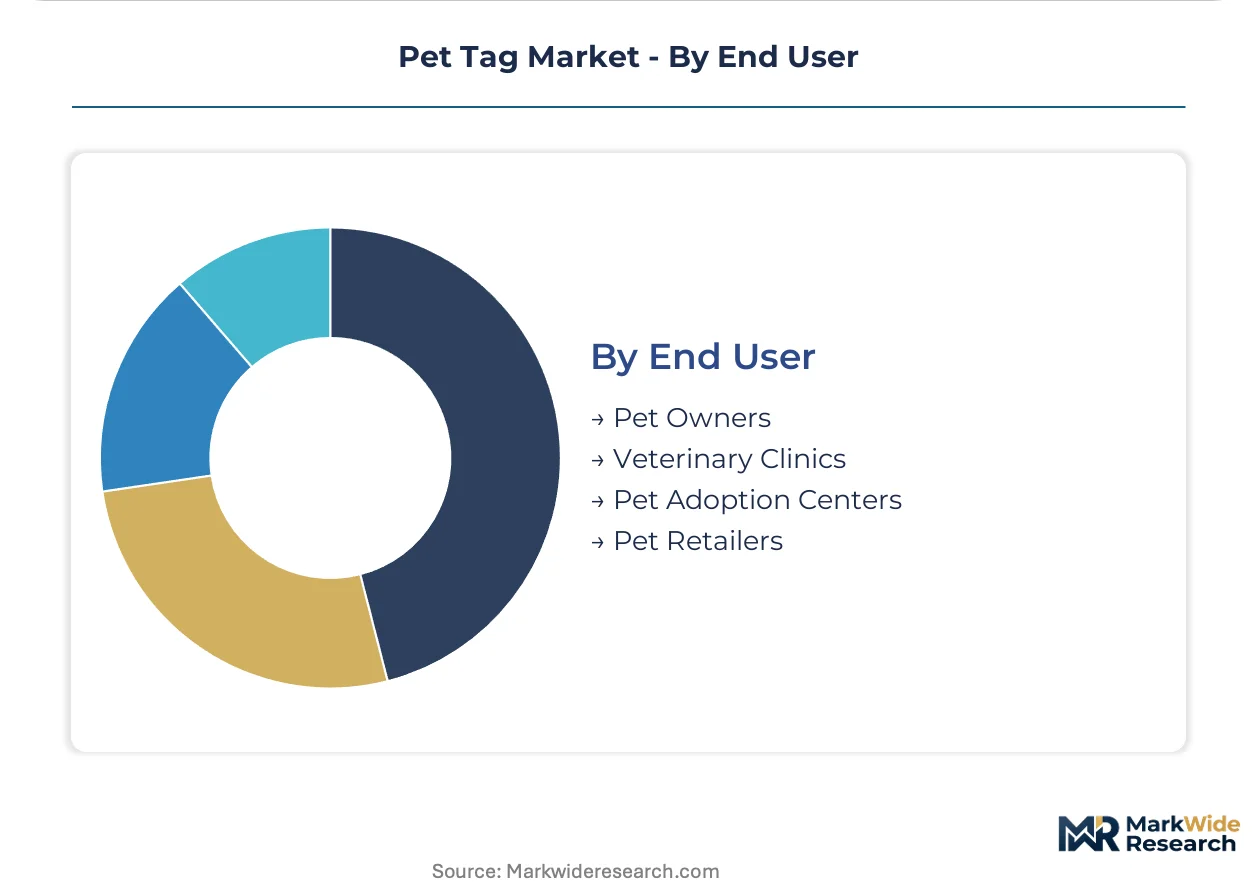
End User:
Customer type concentration dictates sales cycle length, order fragmentation, and service attachment opportunities.
- Pet Owners:Individual purchasers through e-commerce or retail channels drive the highest customization rates and lowest price elasticity for emotional purchases. United States direct-to-consumer engraving platforms have captured significant share from traditional pet stores.
- Veterinary Clinics:Professional purchasers centralize volume through distributor agreements and demand interoperability guarantees for smart tag platforms. North American clinic networks are consolidating procurement through exclusive supplier relationships.
- Pet Adoption Centers:Municipal and nonprofit facilities prioritize low-unit-cost identification for intake processing. QR code mandates in United States animal control jurisdictions are upgrading these facilities from basic engraved plates.
- Pet Retailers:Independent and chain stores stock impulse-purchase inventory with same-day engraving differentiation. United States independents are unbundling tag sales from collar attachments to defend margin against manufacturer direct channels.
Pet owners command the established base. Veterinary clinics are gaining share fastest through procurement consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FCC frequency allocation for pet tracking devices anchors United States market leadership, while EU Green Deal material sourcing requirements and REACH chemical restrictions reshape European supply chain configurations across veterinary clinic procurement networks.
United States
Veterinary clinic bulk procurement programs concentrate demand through exclusive distributor agreements in Texas and California metropolitan corridors. FDA guidelines on animal device labeling intersect with FCC regulations governing RFID transmission frequencies for smart tag variants. Austin and San Diego host specialized engraving equipment clusters serving direct-to-consumer digital platforms.
Germany
Passive NFC chip pilot programs in Frankfurt and Munich veterinary clinics drive premium tag adoption for emergency intake workflows. EU Green Deal recycled aluminum certification requirements force suppliers to document carbon footprint data for tender participation. Bavarian metal fabrication clusters reconfigure brass alloy formulations to meet REACH nickel release restrictions.
France
Municipal animal control facilities in Paris and Lyon mandate QR code identification to accelerate shelter reunification processes. ECHA chemical restrictions on lead-free brass alloys extend product certification timelines for exporters. The Auvergne-Rhône-Alpes region concentrates anodized aluminum finishing capacity serving veterinary procurement networks.
United Kingdom
Independent pet retailers in London and Manchester emphasize same-day engraving services to defend margin against manufacturer direct channels. CE marking requirements for electronic pet identification devices shape smart tag import compliance. Midlands-based stamping operations supply shelter bulk orders across England and Wales.
Canada
Health Canada oversight of animal health product labeling influences cross-border tag distribution from Ontario manufacturing clusters. Toronto and Vancouver veterinary networks centralize procurement through exclusive supplier relationships. Prairie province agricultural communities sustain demand for durable stainless steel tags in working dog applications.
Pet Tag Market Competitive Landscape
Direct-to-consumer specialists and wholesale-anchored fabricators split the market into competing channel strategies. The vendor base organizes around three archetypes: digital-native engraving platforms, distributor-dependent volume suppliers, and shelter-focused bulk order specialists. Consolidation pressure intensifies as veterinary clinic procurement centralization favors scale-compliant manufacturers. Competitive moves concentrate on exclusive distributor agreements and laser equipment capacity expansion.
Within the digital-native tier, GoTags exemplifies direct-to-consumer platform architecture, while LuckyPet occupies a wholesale-anchored position serving independent pet retailers. Providence Engraving represents the shelter-specialist archetype through bulk-order service configuration. These three entities illustrate divergent responses to veterinary clinic procurement consolidation and FCC frequency standardization pressures.
| Leading Market Players |
|---|
| LuckyPet |
| K9king |
| GoTags |
| Pet-tastic |
| Io Tags |
| Dr. Fremont's |
| Providence Engraving |
| LogoTags |
| Road ID |
| Others |
Value Network & Pricing Analysis
Overcapacity in Chinese aluminum rolling mills is compressing input costs for mid-tier stamped tag producers while simultaneously eroding pricing power across European export markets. This utilization dynamic rewards manufacturers with long-term offtake agreements and punishes spot-market buyers facing margin volatility.
Pricing Analysis
United States direct-to-consumer engraving platforms command unit prices triple those of wholesale bulk orders in Germany. Three-tier pricing structure across premium smart tags, standard QR-code aluminum plates, and economy plastic shelter tags separates subscription-enabled GPS devices from commodity identification. Cost compression in engraved stainless steel is intensifying because laser equipment depreciation spreads across shrinking batch sizes. Pet adoption centers exhibit highest price sensitivity; veterinary clinic networks show lowest elasticity due to interoperability mandates.
Supply Chain Analysis
Tariff exposure between China and the United States dominates raw material cost planning for aluminum and brass alloy suppliers. Manufacturing gravity centers on China for anodized aluminum sheet, Germany for precision laser engraving systems, and Vietnam for injection-molded plastic components. Brass feedstock draws from Chilean copper concentrate and Australian zinc smelters. Single-source vulnerability concentrates in NFC chip fabrication. Distribution runs through exclusive veterinary distributor networks in North America and independent pet retail channels in Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are inflecting as proprietary smart tag ecosystems resist integration with universal microchip databases, creating winner-take-most dynamics for interoperability-compliant vendors.
For Market Incumbents: Entrench clinic network relationships through exclusive distributor agreements that lock in volume commitments ahead of FCC frequency standardization completion. Secure backward integration into laser engraving equipment to control capacity expansion timing against direct-to-consumer platform erosion. Prioritize ISO 11784/11785 certification investment to maintain tender eligibility as European procurement consolidates. For New Entrants and Emerging Players: Rural United States veterinary corridors present underpenetrated white space where smartphone-dependent NFC functionality limits incumbent smart tag deployment. Target silicone tag niches in dense urban apartment markets where noise reduction commands premium positioning. Pursue shelter bulk order specialization with QR-code mandate compliance as the go-to-market wedge. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across GPS-enabled smart tag sub-segments as cloud platform development and cellular connectivity subscriptions require sustained R&D commitment. Five-to-ten year viability favors manufacturers with demonstrated veterinary clinic procurement traction over pure-play direct-to-consumer engravers. Monitor FCC frequency allocation finalization as the signal to watch for platform consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Smart Tag Platform Integration | Interoperability with universal microchip databases unlocks veterinary clinic procurement centralization. |
| Recycled Aluminum Certification | EU Green Deal compliance secures preferential tender status with sustainability-mandated European chains. |
| Direct-to-Consumer Engraving Launch | Digital platforms capture margin previously retained by retail intermediaries in United States markets. |
| Exclusive Distributor Agreement | Clinic network lock-in creates predictable volume pipelines ahead of frequency standardization. |
| Silicone Tag Product Line Expansion | Noise-reduced alternatives address urban owner preferences suppressed by traditional metal tag clatter. |
Research Methodology
Operator-level perspectives from veterinary clinic procurement managers, pet retailer category buyers, laser engraving equipment manufacturers, and animal shelter operations directors anchored the qualitative base. Secondary validation drew from FCC frequency allocation dockets, EU Green Deal implementation guidance, REACH chemical restriction updates, and aluminum trade flow customs data. Bottom-up demand modeling triangulated against top-down market sizing across product type, material grade, customization depth, and end-user concentration dimensions.
Scenario-bracketing framed low, base, and high cases across the projection horizon without specifying discrete year markers. Segmentation dimensions modeled included product type tier, material certification status, engraving customization level, and regional regulatory cluster. CAGRs were derived from installed base growth rates and replacement cycle assumptions. Industry-specific forecast inputs incorporated veterinary clinic procurement consolidation timelines and smart tag subscription attach rate trajectories.
The forecast holds incumbent behavior within observed patterns; aggressive ecosystem integration moves by GPS platform vendors or rapid direct-to-consumer platform scaling would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
North America Pet Food Nutraceuticals Market
Pet Care Products
Dry Dog Food Market
Pet Care Products
Taiwan Pet Food Market
Pet Care Products
Cat Shampoo Market
Pet Care Products
Pet Tick and Flea Prevention Market
Pet Care Products
Thunder Jacket for Dogs Market
Pet Care Products
Pet Collar Market
Pet Care Products
China Pet Food Market
Pet Care Products
Vegan Cat Food Market
Pet Care Products
Pet Toys Market
Pet Care Products
Asia Pacific Dog Food Market
Pet Care Products
Cat Accessories Market
Pet Care Products
UAE Pet Boarding Market
Pet Care Products
UK Pet Treats Market
Pet Care Products
Modern Cat Furniture Market
Pet Care Products
Pet Dental Health Market