
 UK Pet Training Services Market | 2026-2036
UK Pet Training Services Market Size, Share, and Industry Trends Forecast 2026-2036
UK Pet Training Services Market Insights
Aftermarket service revenue from subscription-based training programs is tilting toward digital platforms that extend client engagement beyond initial instruction. DogBuddy leverages proprietary app-based scheduling to sustain recurring bookings across Greater London. Battersea Dogs & Cats Home anchors its market position through integrated behavioral rehabilitation that transitions rescue animals into adoptable placements. Butternut Box extends its pet wellness ecosystem into training content, competing for share of wallet among health-conscious owners.
UK pet training services encompass structured behavioral modification programs delivered by certified professionals using evidence-based protocols, typically involving one-to-sixteen session curricula with defined outcome metrics for obedience, socialization, or task-specific competency. The primary commercial purpose centers on reducing owner surrender rates, mitigating liability exposure from aggressive behavior, and enabling veterinary compliance during clinical examinations. Obedience training and behavioral therapy command the deepest margin pools as repeat engagement rates exceed single-session puppy socialization formats. Positive reinforcement dominates method selection as veterinary behaviorists and the RSPCA align professional standards around reward-based protocols, displacing electronic device reliance among accredited providers.
The Department for Environment, Food and Rural Affairs enforces the Animal Welfare (Licensing of Activities Involving Animals) Regulations 2018, which mandates trainer certification and facility inspection across England. The Scottish Government's Animal Health and Welfare (Scotland) Act 2006 and Wales's corresponding legislation impose parallel compliance obligations that shape market access for multi-region operators. The Kennel Club's Good Citizen Dog Scheme and Association of Pet Dog Trainers accreditation further segment provider credibility, directing owner selection toward credentialed practitioners. Stakeholders must monitor evolving welfare legislation and certification harmonization between devolved administrations to anticipate compliance cost trajectories and competitive positioning requirements.
Market Dynamics
The Animal Welfare (Licensing of Activities Involving Animals) Regulations 2018 has compressed market access around certified practitioners, creating a two-tier structure where accredited providers capture premium pricing while uncredentialed operators face enforcement risk across England, Wales, and Scotland.
Growth Catalysts
- Regulatory harmonization pressure:The Kennel Club's Good Citizen Dog Scheme and Association of Pet Dog Trainers accreditation are consolidating owner trust around credentialed professionals, filtering demand toward compliant providers.
- Household pet density expansion:London and the Southeast exhibit concentrated ownership growth, generating localized demand clusters that reward scalable service models.
- Veterinary behaviorist alignment:Positive reinforcement protocols endorsed by the RSPCA are displacing electronic device methods, standardizing service delivery and reducing liability exposure for accredited trainers.
Market Restraints
- Certification cost barriers:Facility inspection mandates and trainer qualification requirements impose fixed compliance costs that disadvantage sole practitioners and rural operators.
- Geographic demand fragmentation:Service consumption clusters in Greater London and the Southeast, leaving Northern England and Wales with thinner revenue pools and lower session frequency.
- Substitution from digital content:Subscription-based training platforms and app-based instruction are capturing price-sensitive owners seeking self-directed behavioral modification.
Strategic Opportunities
- Underpenetrated regional expansion:Northern England and Scotland exhibit lower trainer density per capita, creating whitespace for certified providers to establish first-mover positioning.
- Integrated wellness ecosystems:Pet food and veterinary services are converging with training content, enabling cross-sell opportunities for providers with captive client relationships.
- Rescue-to-placement pipelines:Battersea Dogs & Cats Home demonstrates demand for behavioral rehabilitation services that transition animals into adoptable status, creating institutional contract channels.
Industry Challenges
- Practitioner certification bottlenecks:The Association of Pet Dog Trainers and Kennel Club accreditation pathways face capacity constraints, limiting supply expansion relative to demand growth.
- Service standardization complexity:Outcome metrics for obedience and behavioral therapy vary across providers, complicating quality assurance and client retention.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Pet Training Services Market |
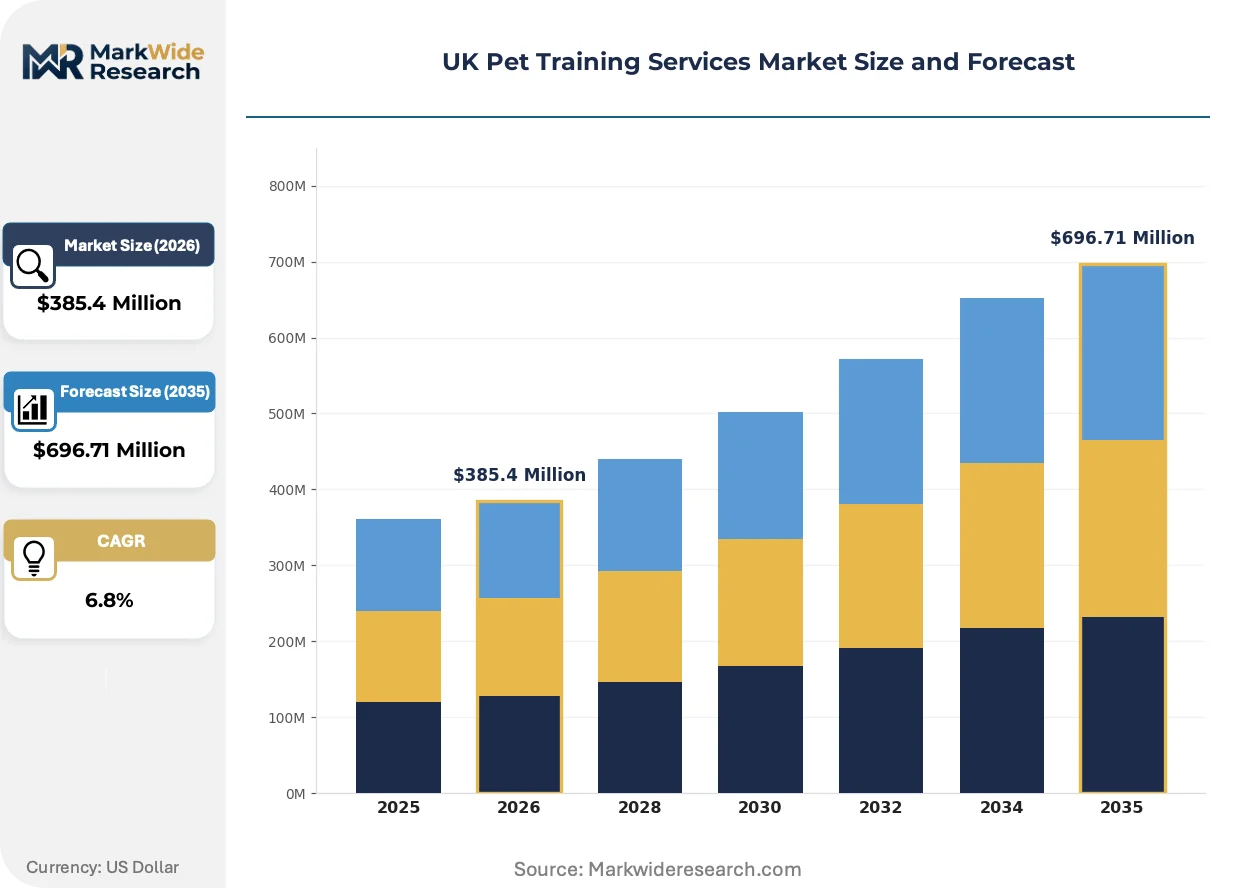
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $696.71 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Obedience Training, Agility Coaching, Behavioral Therapy, Puppy Socialization, Advanced Skills, Service Animal Preparation Pet Type: Dogs, Cats, Birds, Small Mammals, Reptiles, Exotic Pets Training Method: Positive Reinforcement, Clicker Training, Electronic Training Devices, Model-Rival Technique, Relationship-Based Training, Target Training Customer Type: Pet Owners, Animal Shelters, Professional Trainers, Rescue Organizations, Veterinary Clinics, Pet Daycare Centers |
| Companies Covered | DogBuddy, Napo, Zigzag Puppy Coach, Ruggable, Pickles, Battersea Dogs & Cats Home, Butternut Box, Pawmatix, Tails.com, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Pet Training Services Market Trends and Innovations
Digital platforms are restructuring how pet owners engage with training services, compressing the traditional instructor-client relationship into app-mediated interactions that extend beyond initial instruction periods.
Proprietary scheduling applications are digitizing client relationship management for training providers, enabling automated booking, progress tracking, and recurring revenue capture. Urban pet owners in Greater London are adopting these tools at accelerating rates, drawn by convenience and session continuity. The technology is digitizing the aftermarket service layer, shifting value capture from discrete sessions toward sustained subscription relationships.
The Animal Welfare (Licensing of Activities Involving Animals) Regulations 2018 tightened enforcement protocols across England, mandating facility inspection and trainer certification as conditions of market access. Multi-region operators face parallel compliance obligations under Scotland's Animal Health and Welfare Act 2006 and Welsh corresponding legislation, elevating administrative burden. Professional obedience and behavioral therapy segments are responding by consolidating around accredited practitioners, displacing informal providers from premium service tiers.
Subscription-based training programs are displacing single-session puppy socialization formats as the dominant commercial model, reflecting owner preference for sustained engagement over discrete interventions. Digital platforms and app-based scheduling tools are capturing this shift, intermediating between trainers and clients through recurring payment structures. Greater London exhibits the most pronounced behavioral transition, where household density and technology adoption converge to reward platform-mediated service delivery.
UK Pet Training Services Market Segmentation
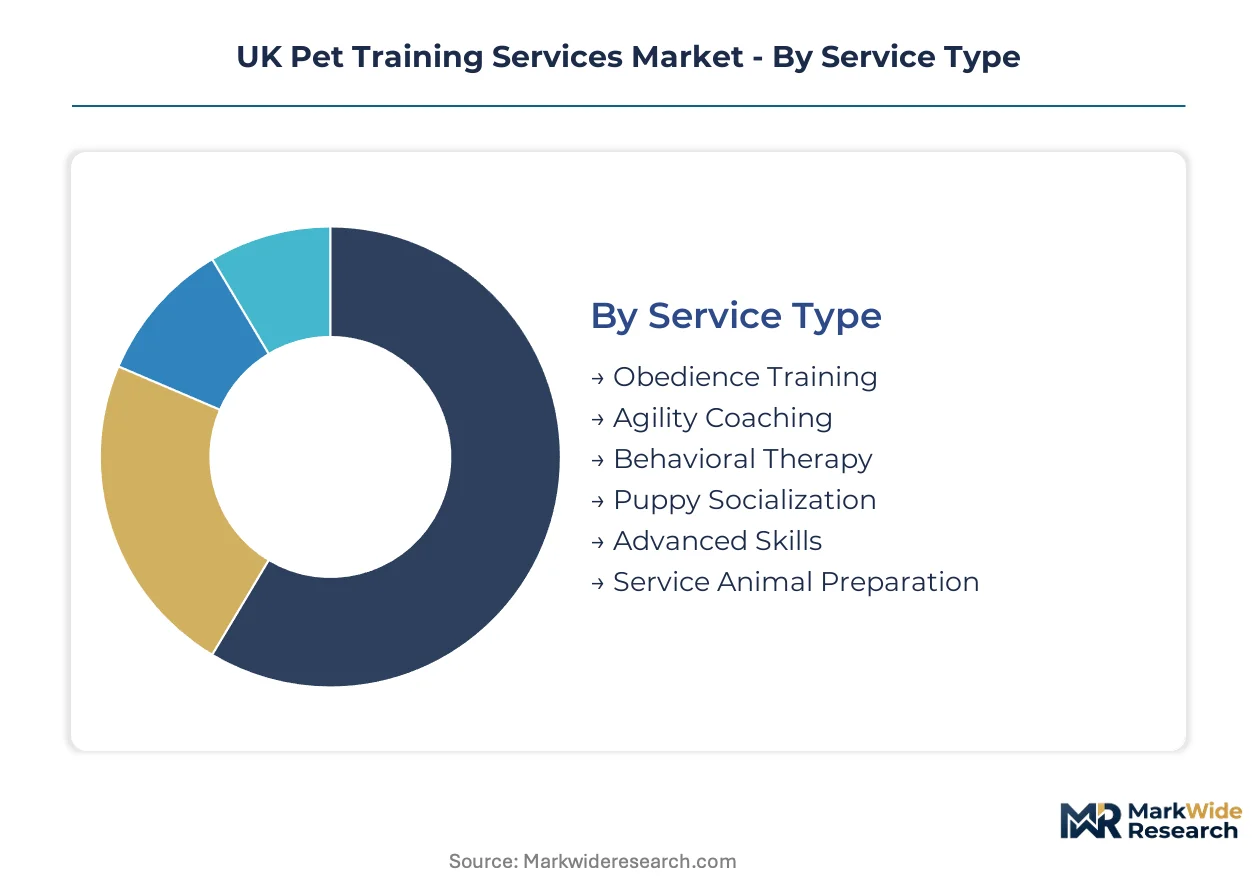
Service differentiation across the UK pet training market reflects divergent owner expectations, regulatory compliance thresholds, and margin structures. Segmentation reveals where accredited providers capture premium pricing and how digital platforms reshape traditional delivery models.
Service Type:
Cost tier stratification separates single-session formats from recurring revenue programs with defined outcome metrics.
- Obedience Training:Structured curricula spanning basic commands through advanced compliance, typically delivered in six-to-twelve session packages. Demand concentrates in Greater London and the Southeast, where household pet density and owner willingness to pay for credentialled instruction intersect.
- Behavioral Therapy:Evidence-based modification protocols for aggression, anxiety, and compulsive disorders, requiring veterinary behaviorist collaboration or referral networks. The Kennel Club's Good Citizen Dog Scheme accreditation filters owner selection toward practitioners with documented case resolution rates.
- Agility Coaching:Competitive sport preparation with specialized equipment requirements.
- Puppy Socialization:Group-based early exposure sessions, often price-pressured by digital substitutes.
- Advanced Skills:Task-specific competency development including scent detection and retrieval.
- Service Animal Preparation:Disability assistance training governed by Disability Discrimination Act compliance standards.
Obedience Training commands the established base. The steepest expansion runs through Behavioral Therapy.
Pet Type:
Application focus determines service complexity, certification requirements, and addressable owner populations.
- Dogs:Dominant species for formal training investment, encompassing obedience, behavioral modification, and working dog preparation. The Animal Welfare (Licensing of Activities Involving Animals) Regulations 2018 mandates trainer certification specifically for canine instruction across England, Wales, and Scotland.
- Cats:Litter box issues and aggression management drive demand, though session frequency remains below canine benchmarks.
- Birds:Behavioral feather-plucking and vocalization modification for parrot species.
- Small Mammals:Limited structured service availability outside exotic veterinary referral networks.
- Reptiles:Husbandry compliance rather than behavioral modification dominates owner education needs.
- Exotic Pets:Niche demand concentrated among specialist veterinary practices in urban centers.
Canine services absorb the majority of professional training expenditure. Feline applications are gaining share fastest among urban households.
Training Method:
Volume concentration around positive reinforcement reflects RSPCA and veterinary behaviorist alignment on welfare standards.
- Positive Reinforcement:Reward-based protocols using food, toys, and verbal markers to shape behavior, now standard for Kennel Club Good Citizen assessments. Battersea Dogs & Cats Home and RSPCA-affiliated trainers have standardized delivery around this methodology.
- Clicker Training:Conditioned reinforcer precision for timing-sensitive behavior capture, prevalent in agility and competitive obedience circles.
- Electronic Training Devices:Collar-based aversive methods facing displacement from accredited provider protocols.
- Model-Rival Technique:Observational learning applications primarily for avian and exotic species.
- Relationship-Based Training:Bond-centered approaches emphasizing handler-dog communication quality.
- Target Training:Contact-based shaping for specific physical positioning tasks.
Positive Reinforcement anchors mainstream service delivery. Clicker Training is climbing the fastest among competitive sport participants.
Customer Type:
Geography and institutional purchasing power segment demand between individual owners and organizational contracts.
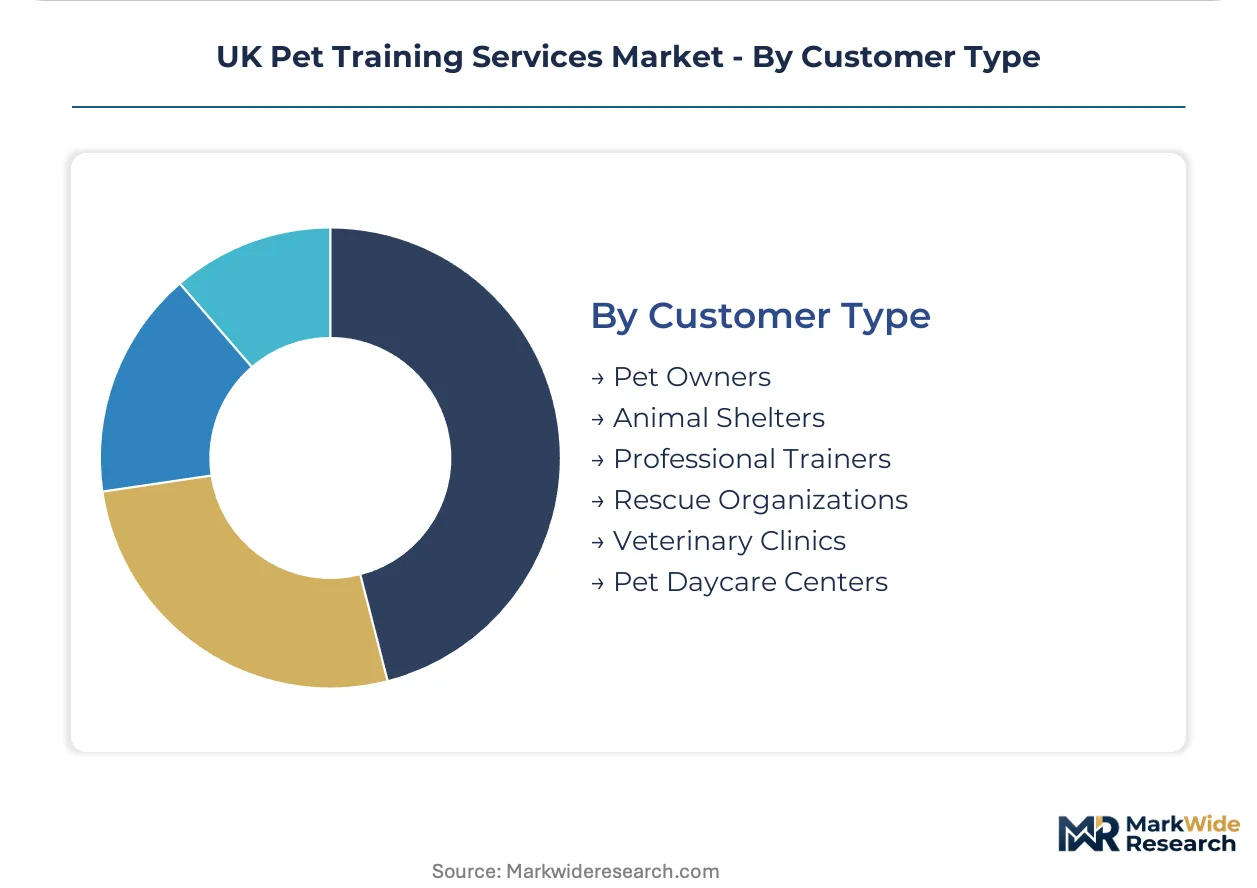
- Pet Owners:Individual purchasers in Greater London and the Southeast exhibit highest session frequency and subscription adoption rates. Battersea Dogs & Cats Home demonstrates rescue-to-placement pipeline potential for behavioral rehabilitation contracts.
- Animal Shelters:Institutional volume concentrated in behavioral rehabilitation for adoptability outcomes.
- Professional Trainers:Continuing education and certification maintenance demand.
- Rescue Organizations:Grant-funded rehabilitation services with outcome-based contracting.
- Veterinary Clinics:Referral network nodes for behavioral cases exceeding general practice scope.
- Pet Daycare Centers:Staff training and client education add-on services.
Individual Pet Owners generate the revenue foundation. Rescue Organizations are expanding their training procurement most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across UK regions. London and Southeast owners absorb premium pricing for certified instruction, while Northern England and Wales markets exhibit pronounced price sensitivity that favors digital substitutes over face-to-face sessions.
London and the Southeast
Household pet density in Greater London exceeds national averages by a significant margin, generating concentrated demand clusters for obedience and behavioral therapy. The Animal Welfare (Licensing of Activities Involving Animals) Regulations 2018 enforcement is strictest here, with DEFRA conducting frequent facility inspections. Battersea Dogs & Cats Home anchors the rescue-to-placement pipeline, demonstrating institutional contract potential for behavioral rehabilitation services.
Midlands
Urban centers like Birmingham and Leicester exhibit growing middle-class pet ownership with rising willingness to pay for credentialled training. The Kennel Club's Good Citizen Dog Scheme accreditation filters owner selection toward verified practitioners. Coventry and Nottingham host emerging trainer collectives that leverage lower facility costs than London to offer competitive session pricing.
North England
Trainer density per capita remains below Southern benchmarks, creating whitespace for certified providers to establish first-mover positioning. Manchester and Leeds show accelerating demand for subscription-based digital platforms as owners seek alternatives to limited local practitioner availability. The RSPCA's regional branches increasingly refer complex behavioral cases to accredited specialists rather than handling in-house.
Scotland
The Scottish Government's Animal Health and Welfare (Scotland) Act 2006 imposes parallel certification requirements that shape market access for cross-border operators. Edinburgh and Glasgow concentrate demand for professional obedience services, though rural Highland areas face severe practitioner scarcity. Scottish SPCA affiliates are expanding behavioral rehabilitation capacity to reduce rescue animal euthanasia rates.
Wales
Corresponding Welsh legislation mirrors English and Scottish compliance frameworks, elevating administrative burden for multi-region operators. Cardiff and Swansea generate localized demand clusters, while rural Welsh markets remain underpenetrated by accredited providers. The Dogs Trust Cardiff facility exemplifies institutional procurement of behavioral services for rescue animal adoptability outcomes.
UK Pet Training Services Market Competitive Landscape
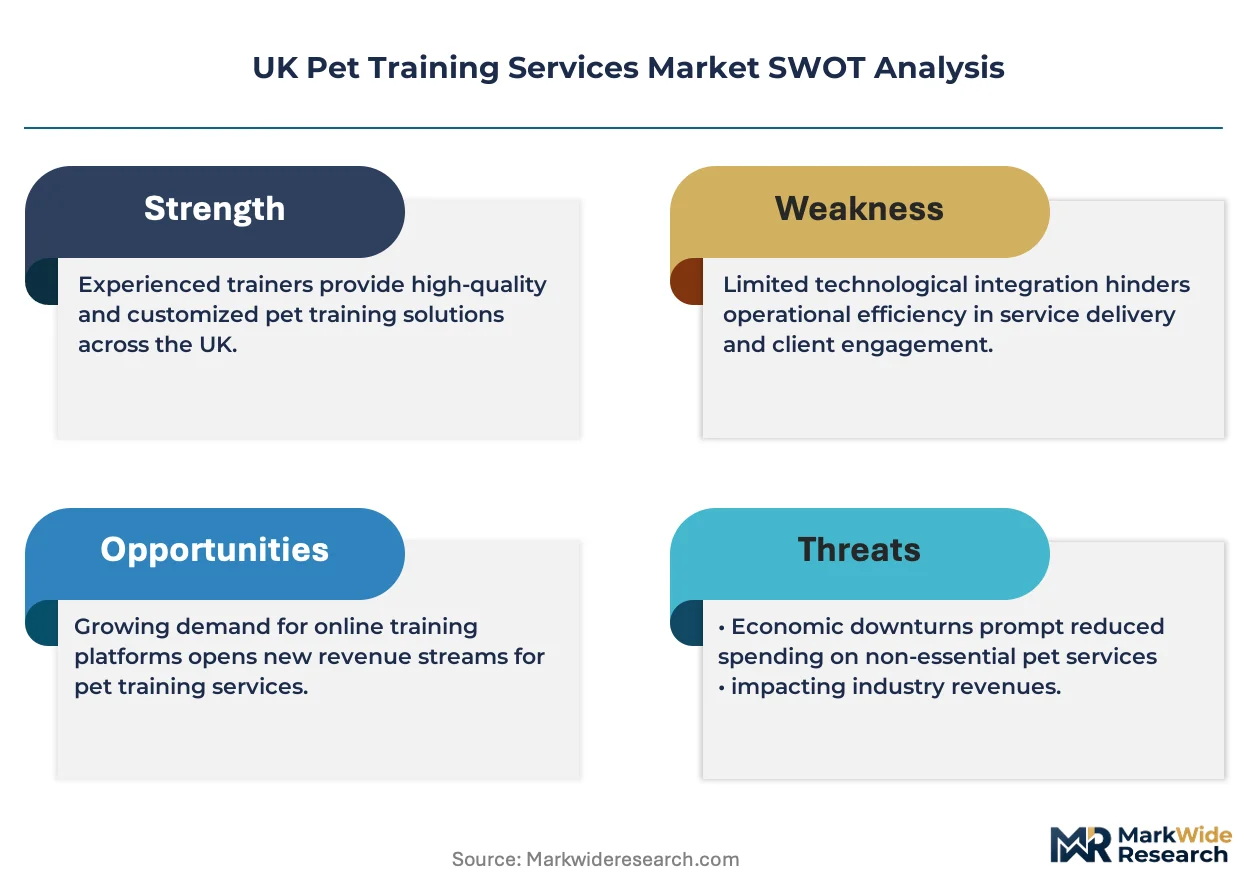
Capability concentration sits with accredited specialists holding Kennel Club and APDT credentials; scale advantage sits with platform-mediated networks that digitize client acquisition and session scheduling. The market exhibits a two-tier structure where certified practitioners capture premium pricing while app-based intermediaries aggregate price-sensitive demand. Three archetypes dominate: rescue-affiliated rehabilitation providers, subscription-based digital platforms, and wellness ecosystem extenders from adjacent pet care verticals. Competitive moves center on geographic expansion into underpenetrated Northern markets and backward integration into captive content production.
Among platform-mediated intermediaries, DogBuddy exemplifies the scheduling-technology archetype that sustains recurring bookings across Greater London. Battersea Dogs & Cats Home occupies a distinctive position as a rescue-affiliated rehabilitation specialist, leveraging institutional contracts and outcome-based funding for behavioral intervention. Butternut Box represents the wellness ecosystem extender, competing for share of wallet among health-conscious owners by bundling training content with nutrition subscriptions.
| Leading Market Players |
|---|
| DogBuddy |
| Napo |
| Zigzag Puppy Coach |
| Ruggable |
| Pickles |
| Battersea Dogs & Cats Home |
| Butternut Box |
| Pawmatix |
| Tails.com |
| Others |
Pricing and Supply Chain Analysis
Greater London's concentrated trainer capacity generates asymmetric pricing power for certified practitioners, while sparse supply in Northern England and Wales forces owners toward digital substitutes or uncredentialed providers. The Animal Welfare (Licensing of Activities Involving Animals) Regulations 2018 enforcement gradient reinforces this geographic rent extraction, with DEFRA inspection intensity correlating directly to session rate premiums.
Pricing Analysis
Aftermarket subscription revenue from recurring training programs drives lifetime value capture, displacing single-session transactional formats. Three-tier pricing structure across Kennel Club-accredited premium, APDT-certified standard, and informal economy levels segments owner willingness to pay. Pricing pressure stems from app-based platforms aggregating price-sensitive demand in underpenetrated regions. Individual pet owners in Greater London exhibit lowest price sensitivity, while Northern England owners demonstrate highest substitution elasticity toward digital content.
Supply Chain Analysis
Upstream feedstock of certified trainer talent draws from Kennel Club and APDT accreditation pathways with capacity-constrained throughput. Geographic supply concentration centers on England, with Wales and Scotland exhibiting parallel but thinner certification pipelines. Raw material dependencies include veterinary behaviorist collaboration networks, training facility real estate, and proprietary curriculum content. Single-source vulnerability sits with the Association of Pet Dog Trainers accreditation bottleneck limiting supply expansion. Distribution runs through platform-mediated scheduling applications in urban centers, direct practitioner relationships in suburban markets, and rescue organization institutional contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UK pet training services market represents a high-growth disruption as the Animal Welfare (Licensing of Activities Involving Animals) Regulations 2018 compresses market access around credentialed practitioners, accelerating consolidation toward platform-scale operators and accredited specialists.
For Market Incumbents: Entrench certification moats through Kennel Club Good Citizen Scheme and APDT accreditation investment, while backward integration into captive curriculum production reduces content licensing exposure. Platform-mediated competitors threaten client acquisition economics; defend through exclusive veterinary referral network lockups in Greater London and the Southeast.
For New Entrants and Emerging Players: Northern England's trainer density gap per capita offers whitespace for first-mover positioning with subscription-based digital platforms. Rescue organization institutional contracts provide revenue foundation with outcome-based funding structures. Target Manchester and Leeds with app-mediated service delivery bridging local practitioner scarcity.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors platform-enabled networks with recurring revenue capture over discrete-session sole practitioners. Long-term viability hinges on regulatory compliance automation and cross-border scalability across England, Wales, and Scotland. Acquisition target archetype: accredited trainer collectives with proprietary scheduling infrastructure. Signal to watch: Kennel Club-APDT certification harmonization accelerating supply expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | DogBuddy's proprietary scheduling application sustains recurring bookings across Greater London. |
| Certification Investment | Kennel Club Good Citizen Scheme accreditation filters owner selection toward verified practitioners. |
| Geographic Expansion | Northern England whitespace rewards first-mover positioning by certified providers. |
| Backward Integration | Captive curriculum production reduces content licensing exposure for scaling operators. |
| Institutional Contracting | Battersea Dogs & Cats Home demonstrates rescue-to-placement pipeline revenue potential. |
Research Methodology
A standing panel of certified dog trainers, veterinary behaviorists, rescue organization operations directors, and pet owner focus group participants provided ongoing calibration across the research process. Primary interviews with Kennel Club assessors, APDT-accredited practitioners, and DEFRA licensing officers combined with secondary validation from the Animal Welfare (Licensing of Activities Involving Animals) Regulations 2018 statutory instruments, Kennel Club Good Citizen Scheme documentation, RSPCA training protocol publications, and regional veterinary referral network directories. Bottom-up session volume estimates triangulated against top-down household pet density projections.
Scenario-bracketing framed demand elasticity across regulatory enforcement intensity gradients and digital platform penetration rates. Segmentation dimensions modeled encompass service type, training method, pet species, customer archetype, and geographic density cluster. CAGRs derived from cohort-based trainer capacity expansion curves and owner willingness-to-pay elasticities by accreditation tier. Forecast inputs incorporated DEFRA inspection frequency data and Kennel Club examination throughput statistics.
The forecast holds incumbent behavior within observed patterns; aggressive certification capacity expansion by the Association of Pet Dog Trainers or Kennel Club would shift supply-side constraints and revise growth trajectories. Cross-checking against Dogs Trust and RSPCA annual rehoming statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
UK Pet Treats Market
Pet Care Products
Dog Food Market
Pet Care Products
Pet Oral Care Products Market
Pet Care Products
Dog Food and Snacks Market
Pet Care Products
Japan Organic and Natural Pet Food Market
Pet Care Products
Paw Plunger Market
Pet Care Products
Freeze Dried Dog Food Market
Pet Care Products
UAE Pet Food Market
Pet Care Products
Dog Pen Market
Pet Care Products
Dog Brush Market
Pet Care Products
Fresh and Frozen Dog Food Market
Pet Care Products
Pet Water Dispenser Market
Pet Care Products
Canned Wet Cat Food Market
Pet Care Products
Saudi Arabia Dog Food Market
Pet Care Products
Fish Based Pet Food Market
Pet Care Products
Cat Window Perches and Wall Shelves Market