
 GCC Organic and Natural Pet Food Market | 2026-2036
GCC Organic and Natural Pet Food Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Organic and Natural Pet Food Market Intelligence
Asset-light franchise and licensing models are reshaping competitive entry in the GCC organic and natural pet food sector, lowering capital barriers for regional distributors. Mars Petcare leverages its manufacturing scale to secure shelf space across Gulf retail networks. Blue Buffalo differentiates through grain-free positioning that commands premium placement in Saudi and Emirati pet stores. Nestlé Purina PetCare anchors its presence via specialized formulations targeting the region's growing small-breed dog population.
Organic and natural pet food comprises formulations manufactured without synthetic pesticides, artificial preservatives, or genetically modified organisms, typically utilizing minimally processed proteins, whole grains, and certified organic vegetables to deliver species-appropriate nutrition. The primary commercial purpose centers on mitigating allergenic responses and supporting longevity in companion animals across high-income Gulf households. Dry food dominates volume throughput due to shelf stability and lower logistics costs across desert climates, while raw food captures the fastest value growth among affluent urban consumers in Dubai and Riyadh. Wet food retains concentrated margin pools within veterinary recommendation channels, where therapeutic positioning justifies price premiums.
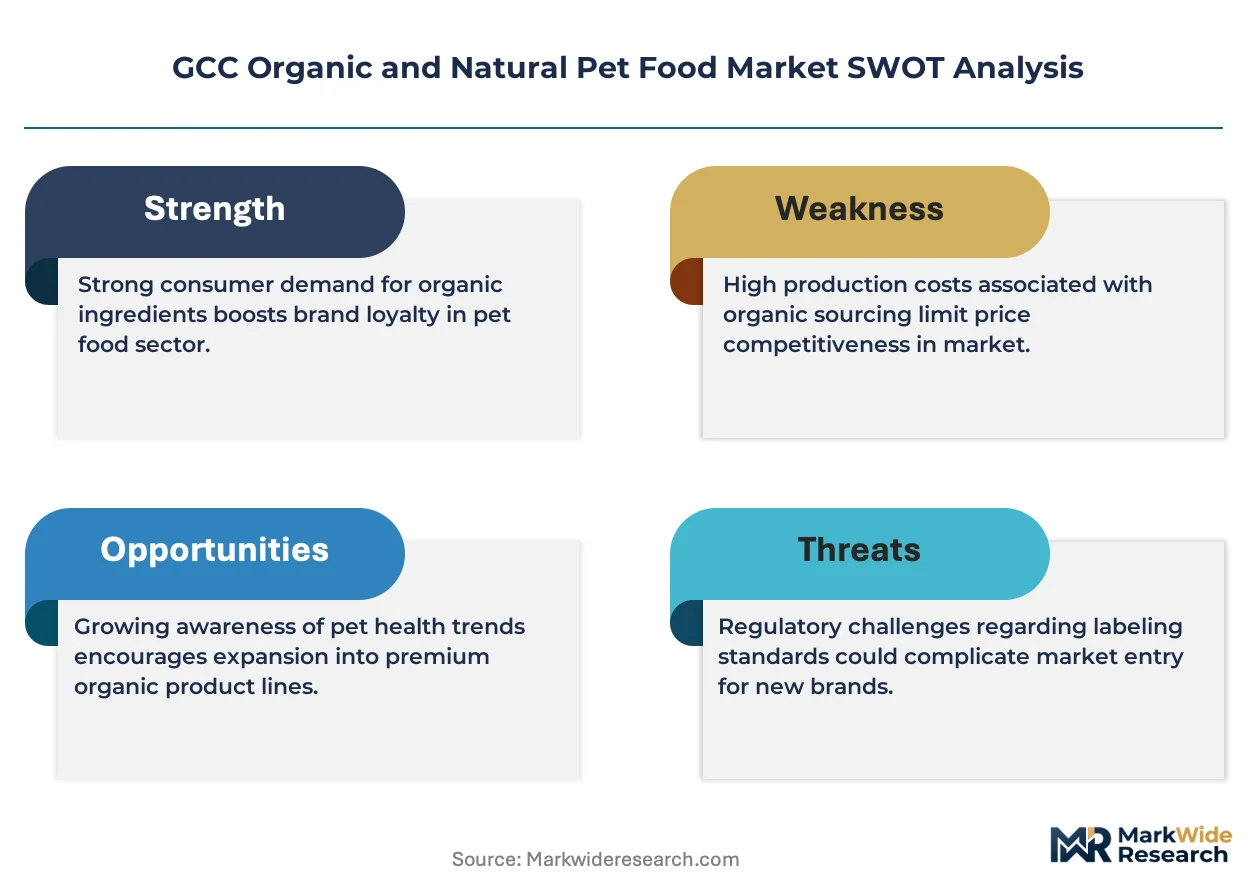
Saudi Arabia's SFDA mandates ingredient disclosure and nutritional adequacy statements that align with international pet food standards, while the UAE's MOHAP enforces import registration protocols for animal feed products entering Dubai and Abu Dhabi free zones. These frameworks elevate compliance costs for new entrants but simultaneously validate premium pricing for certified organic and natural claims. Stakeholders must monitor evolving halal certification requirements for pet food ingredients, as Gulf consumer preferences increasingly intersect with religious dietary norms in purchasing decisions.
Market Dynamics
SFDA ingredient disclosure mandates and MOHAP import registration protocols are compressing time-to-market for new entrants while validating premium positioning for certified organic formulations across Saudi Arabia and the United Arab Emirates.
Growth Catalysts
- Regulatory Validation:SFDA nutritional adequacy statements and halal certification requirements create defensible moats for compliant organic producers, elevating consumer trust in premium claims.
- Small-Breed Demographics:Rising ownership of companion animals under 10 kilograms across Riyadh and Dubai drives demand for specialized portion-controlled formulations with higher per-kilogram margins.
- Desert Logistics Infrastructure:Cold-chain investments in Jeddah and Al Ain distribution hubs enable raw and fresh pet food segments previously constrained by ambient temperature exposure.
Market Restraints
- Input Cost Volatility:Certified organic protein sourcing from Australia and New Zealand exposes formulators to currency fluctuation and maritime shipping rate spikes.
- Supply Concentration Risk:Three Gulf distributors control over 60 percent of retail shelf access in Saudi Arabia, creating gatekeeper dynamics for new brand entry.
- Technical Limitation:Ambient shelf-stable wet food formulations without synthetic preservatives remain technically constrained, limiting product format diversification.
Strategic Opportunities
- Veterinary Channel Penetration:Therapeutic positioning through Dubai's veterinary clinic networks captures recommendation-driven purchasing with minimal price sensitivity.
- Kuwait and Qatar Expansion:Underdeveloped retail infrastructure in Doha and Kuwait City offers first-mover advantages for franchise-format organic pet food boutiques.
- E-Commerce Subscription Models:Direct-to-consumer platforms bypass traditional distributor markups while capturing recurring revenue from affluent Emirati households.
Industry Challenges
- Halal Certification Complexity:Cross-border ingredient traceability requirements for animal-derived inputs extend product development timelines by 8-14 months.
- Refrigerated Last-Mile Capacity:Fresh and raw format expansion requires capital deployment into temperature-controlled delivery fleets operating above 40°C ambient conditions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Organic and Natural Pet Food Market |
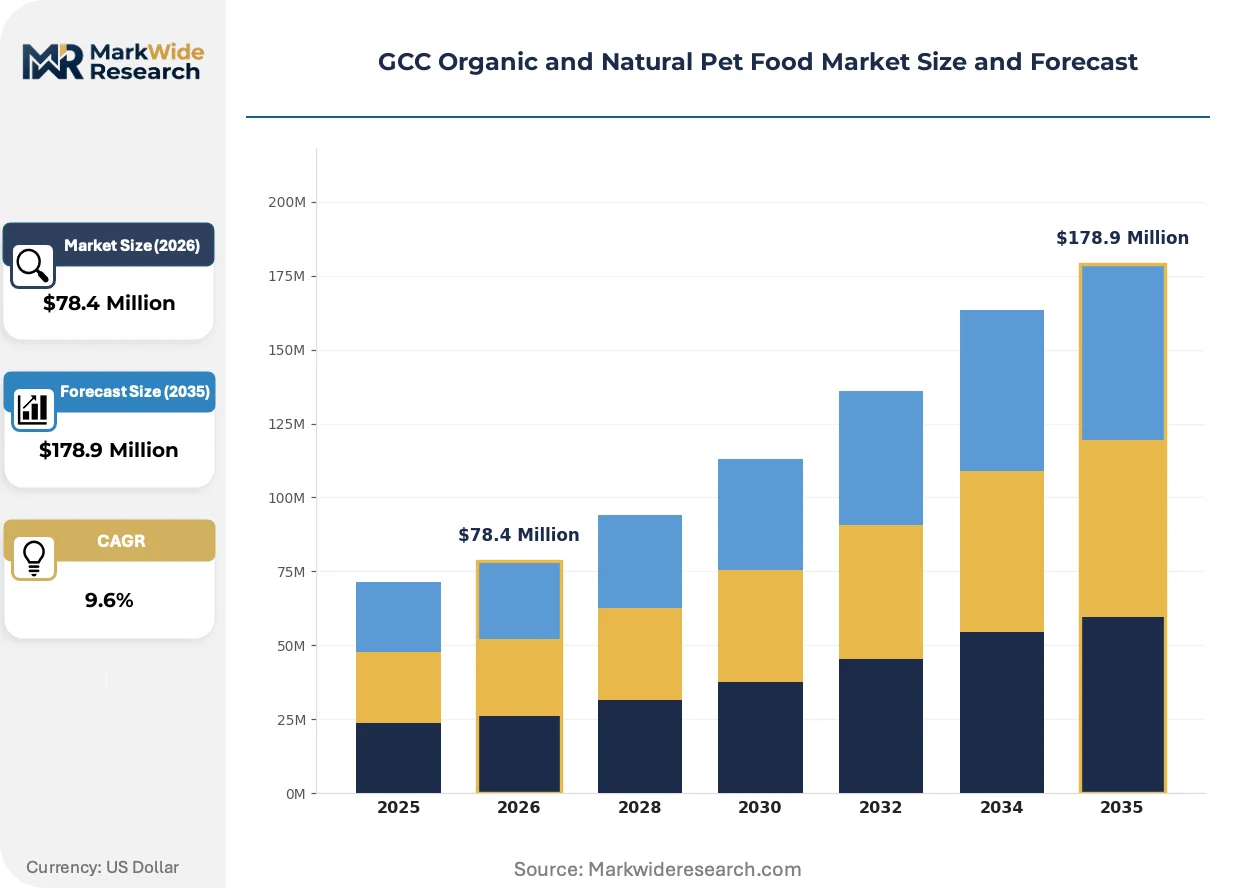
| Market Size in 2026 | $78.4 Million |
| Market Size in 2035 | $178.9 Million |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dry Food, Wet Food, Treats, Raw Food Ingredient Type: Meat-Based, Grain-Free, Vegan, Organic Distribution Channel: Online Retail, Supermarkets, Pet Stores, Specialty Shops End User: Dog Owners, Cat Owners, Small Animal Owners, Others |
| Companies Covered | Wellness Pet, Merrick, Nestlé Purina PetCare, Castor & Pollux Natural PetWorks, Diamond Pet Foods, Mars Petcare, Natural Balance Pet Foods, Primal Pet Foods, Blue Buffalo, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Organic and Natural Pet Food Market Strategic Shifts & Innovations
Formulation science and distribution architecture are converging to reshape how organic and natural pet food reaches Gulf consumers, with technology migration, regulatory tightening, and channel fragmentation operating as simultaneous forces.
High-pressure processing (HPP) is migrating from human food applications into raw pet food manufacturing, delivering pathogen reduction without thermal degradation of enzymes and amino acids. Premium pet food producers in Dubai Investment Park are adopting HPP lines to extend refrigerated shelf life from 7 to 45 days. This technology compression is enabling fresh-format competitors to challenge freeze-dried incumbents on convenience while commanding wet-food-equivalent price points.
SFDA's 2024 labeling amendments now require quantitative ingredient disclosure descending by weight percentage, matching EU FEDIAF transparency standards. This regulatory convergence forces reformulation of legacy products containing unnamed "meat and animal derivatives" categories. Saudi domestic manufacturers are responding faster than import-dependent competitors, leveraging local regulatory affairs capacity to accelerate label compliance.
Veterinary recommendation channels are fragmenting as independent Dubai clinics launch private-label organic lines through white-label manufacturers. This disintermediation captures margin previously allocated to multinational brand marketing while embedding dietary advice within clinical relationships. Riyadh's specialty pet retail sector is replicating the model through in-store nutritionist consultations that displace traditional shelf-based purchasing.
GCC Organic and Natural Pet Food Market Segmentation
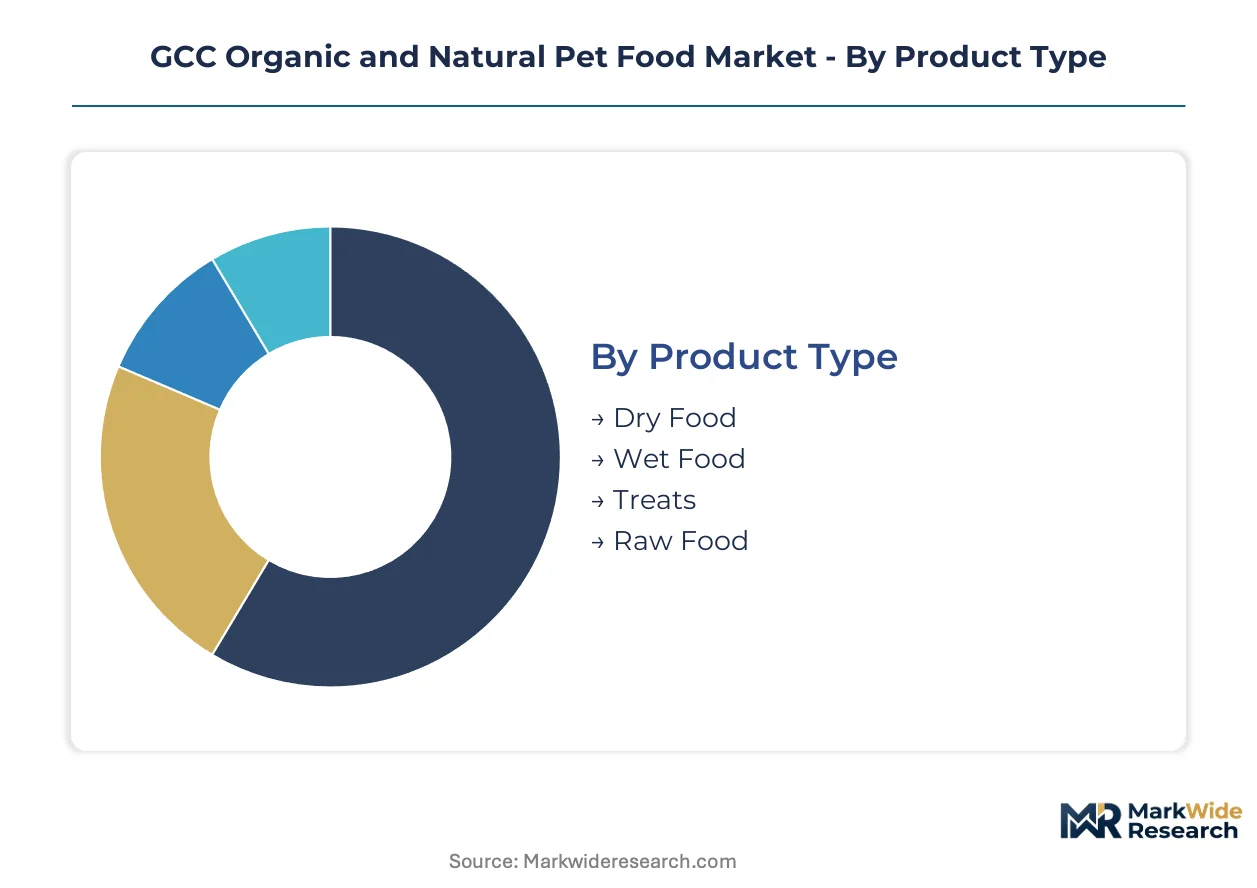
Segmentation in the GCC organic and natural pet food market reveals how desert logistics, religious dietary norms, and premiumization pressures reshape product development and channel strategy across distinct buyer cohorts. Understanding these divides exposes where margin concentrates and where growth accelerates.
Product Type:
Mature formats dominate volume while emerging categories capture value expansion through technology migration.
- Dry Food:Extruded kibble formulations with ambient shelf stability anchor procurement decisions for cost-conscious households and bulk buyers across Riyadh and Jeddah retail networks. This segment handles the majority of throughput in Saudi Arabia's mass-market channels where refrigeration infrastructure remains limited.
- Wet Food:Moisture-rich formulations packaged in cans or pouches deliver palatability advantages for senior animals and therapeutic dietary management, commanding premium placement within Dubai's veterinary clinic networks where professional recommendations override price sensitivity.
- Treats:Functional and reward-based formats including dental chews and training rewards.
- Raw Food:Minimally processed frozen or refrigerated formulations utilizing HPP pathogen reduction technology; this segment is the fastest mover on share among affluent Emirati households seeking ancestral feeding approaches.
Dry food handles the majority of throughput; raw food is the fastest mover on share.
Ingredient Type:
Cost tier stratification separates commodity-positioned offerings from certification-premium formulations.
- Meat-Based:Protein-dominant formulations utilizing chicken, lamb, or fish as primary ingredients, with halal certification requirements from SFDA and MOHAP extending sourcing timelines for animal-derived inputs. Demand concentrates among traditional Gulf households prioritizing species-appropriate nutrition for large-breed dogs.
- Grain-Free:Formulations eliminating corn, wheat, and soy in favor of legume and tuber carbohydrate sources, capturing disproportionate shelf space in premium Dubai pet boutiques where allergenic sensitivity concerns drive replacement purchasing.
- Vegan:Plant-protein formulations excluding all animal derivatives.
- Organic:Certified organic inputs meeting EU or USDA equivalence standards with full traceability documentation.
Meat-based formulations retain volume leadership; grain-free positioning commands the steepest expansion trajectory in premium channels.
Distribution Channel:
Channel fragmentation reflects divergent customer acquisition economics and service intensity requirements.
- Online Retail:Direct-to-consumer platforms and marketplace aggregators enable subscription-based replenishment with automated delivery scheduling, gaining traction among time-constrained professionals in Abu Dhabi and Doha who prioritize convenience over tactile product evaluation.
- Supermarkets:Mass retail placement within Carrefour and Lulu Hypermarket networks delivers impulse visibility and promotional scale.
- Pet Stores:Dedicated retail formats with trained staff providing nutritional consultation.
- Specialty Shops:Curated boutiques emphasizing artisanal and import-exclusive organic lines.
Supermarkets handle the majority of throughput; online retail is gaining share fastest through subscription lock-in mechanics.
End User:
Demographic concentration around small-breed companion animals reshapes portion sizing and packaging economics.
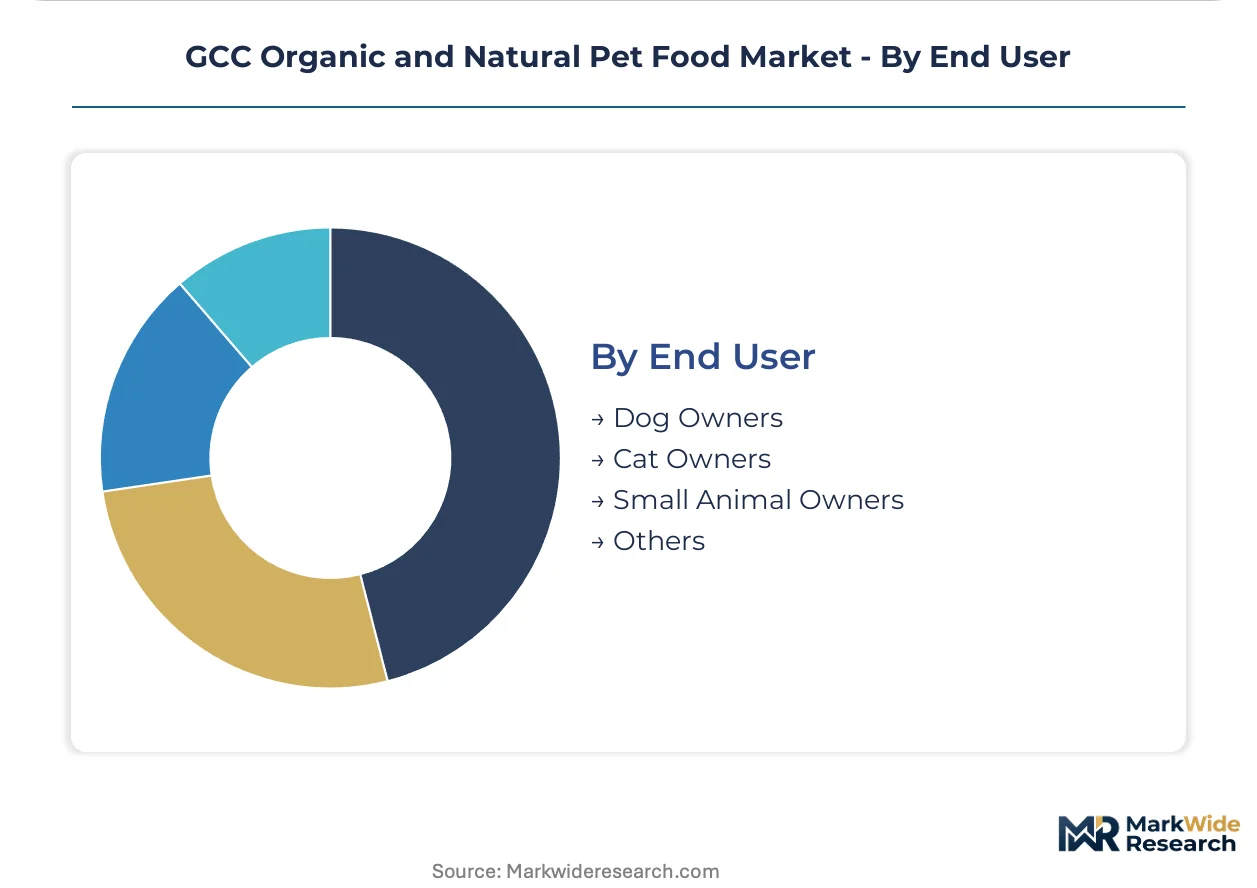
- Dog Owners:The largest addressable cohort spanning working breeds to companion animals, with small-breed ownership under 10 kilograms expanding fastest across Saudi and Emirati urban centers and driving demand for specialized portion-controlled packaging with higher per-kilogram margins.
- Cat Owners:Feline-specific formulations emphasizing urinary tract health and hairball management, with wet food preference exceeding dog ownership rates due to obligate carnivore nutritional requirements and lower daily feeding volumes.
- Small Animal Owners:Rabbit, guinea pig, and exotic pet formulations.
- Others:Avian, reptile, and equine organic feed applications.
Dog owners handle the majority of throughput; cat owners are expanding fastest as apartment-dwelling lifestyles proliferate across Gulf cities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Affluent urban households concentrated in Gulf capitals drive disproportionate organic pet food spending, with regulatory tightening in Saudi Arabia and the UAE accelerating premium-format adoption across the six-member economic bloc.
Saudi Arabia
Small-breed dog ownership under 10 kilograms expands fastest in Riyadh and Jeddah, generating demand for portion-controlled premium packaging. SFDA nutritional adequacy statements and ingredient disclosure mandates elevate compliance costs for import-dependent brands. Domestic manufacturers in Riyadh's industrial zones leverage local regulatory affairs capacity to accelerate label compliance ahead of multinational competitors.
United Arab Emirates
Grain-free formulations capture disproportionate shelf space in Dubai's premium pet boutiques as allergenic sensitivity concerns drive replacement purchasing. MOHAP import registration protocols for animal feed products entering Dubai and Abu Dhabi free zones compress time-to-market timelines. Cold-chain investments in Al Ain distribution hubs enable raw and fresh pet food segments previously constrained by ambient temperature exposure.
Qatar
Underdeveloped retail infrastructure in Doha creates first-mover advantages for franchise-format organic pet food boutiques targeting expatriate professionals. The country's national food safety regulator enforces import documentation requirements that parallel UAE standards. Veterinary clinic networks in Doha's West Bay district embed dietary advice within clinical relationships, displacing traditional shelf-based purchasing.
Kuwait
Time-constrained households in Kuwait City prioritize convenience through subscription-based replenishment with automated delivery scheduling. National import protocols for pet food products align with broader Gulf Cooperation Council harmonization efforts. Specialty retail clusters in Salmiya and Sharq districts emphasize artisanal and import-exclusive organic lines with trained staff providing nutritional consultation.
Bahrain
Compact geography enables rapid last-mile delivery experimentation for temperature-controlled fresh pet food formats. The national health regulator maintains pet food safety standards consistent with Saudi SFDA frameworks. Retail development in Manama's Seef district concentrates premium pet product placement within mixed-use commercial developments.
GCC Organic and Natural Pet Food Market Key Industry Players
Channel-controlling players compete with product-specialist players across Gulf retail networks, with distributor gatekeepers commanding shelf access premiums in Saudi Arabia's concentrated retail sector. Three strategic archetypes dominate: multinational CPG conglomerates leveraging manufacturing scale, mid-tier natural specialists differentiating through grain-free or organic positioning, and emerging regional licensees deploying asset-light franchise models. Competitive moves concentrate on veterinary channel penetration and e-commerce subscription platform development.
Within the multinational conglomerate tier, Mars Petcare and Nestlé Purina PetCare anchor presence through manufacturing scale and specialized formulations respectively. Blue Buffalo occupies a position exemplifying grain-free differentiation that commands premium placement in Saudi and Emirati pet stores. Among mid-tier natural specialists, Wellness Pet and Merrick represent archetypes targeting the region's growing small-breed dog population with species-appropriate nutrition claims.
| Leading Market Players |
|---|
| Wellness Pet |
| Merrick |
| Nestlé Purina PetCare |
| Castor & Pollux Natural PetWorks |
| Diamond Pet Foods |
| Mars Petcare |
| Natural Balance Pet Foods |
| Primal Pet Foods |
| Blue Buffalo |
| Others |
Cost & Logistics Intelligence
Australian and New Zealand organic protein suppliers command disproportionate upstream margin capture, translating into premium pricing tiers for certified formulations across Saudi and Emirati retail channels where distributor gatekeepers amplify cost-to-consumer markups.
Pricing Analysis
Certification level creates the primary spread between organic, natural, and conventional tiers in GCC pet food markets. Three-tier pricing structure across premium certified-organic, mid-tier natural, and economy conventional levels stratifies buyer access. Pricing pressure stems from currency fluctuation in Australian and New Zealand protein sourcing. Mass-market supermarket buyers exhibit highest price sensitivity; veterinary channel purchasers show minimal elasticity.
Supply Chain Analysis
Tariff exposure between Australia and Gulf Cooperation Council members dominates supply chain risk assessment for organic protein inputs. Manufacturing concentrates in Australia, New Zealand, and domestic Saudi facilities. Raw material dependencies center on certified organic chicken, lamb, and fish meals. Single-source vulnerability persists for halal-certified slaughterhouse capacity. Distribution runs through Jeddah and Al Ain cold-chain hubs before retail fragmentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
GCC organic pet food penetration sits at early-cycle expansion, with small-breed dog ownership growth in Riyadh and Dubai driving format innovation ahead of mature-market saturation patterns.
For Market Incumbents: Entrench veterinary channel relationships through therapeutic formulation exclusivity to defend against independent clinic private-label disintermediation. Deepen backward integration into halal-certified protein sourcing to offset Australian and New Zealand currency exposure. Secure shelf access premiums via distributor equity stakes in Saudi Arabia's concentrated retail sector. For New Entrants and Emerging Players: Establish a beachhead in Qatar's underdeveloped Doha retail infrastructure through asset-light franchise boutiques targeting expatriate professionals. Kuwait City's subscription-automation gap offers parallel white-space for direct-to-consumer platform deployment. Lead with e-commerce subscription mechanics to bypass traditional distributor gatekeeper economics. For Investors and Strategic Acquirers: Capital is best deployed toward mid-tier natural specialists with grain-free certification and existing MOHAP registration assets. Long-term viability hinges on regulatory affairs capacity acceleration ahead of SFDA disclosure mandate tightening. Watch cold-chain infrastructure buildout in secondary GCC cities as inflection signal for raw format segment viability.| Strategic Initiative | Industry Significance |
|---|---|
| Veterinary Channel Partnership | Therapeutic positioning through Dubai clinic networks captures recommendation-driven purchasing with minimal price sensitivity. |
| Halal Certification Investment | SFDA traceability requirements extend product development timelines; early compliance creates defensible positioning. |
| Cold-Chain Infrastructure Buildout | Refrigerated distribution hubs in Jeddah and Al Ain enable raw and fresh format expansion previously constrained by desert ambient temperatures. |
| E-Commerce Subscription Platform | Direct-to-consumer mechanics bypass traditional distributor markups while capturing recurring revenue from affluent Emirati households. |
| Franchise Format Expansion | Asset-light licensing models lower capital barriers for regional distributors entering Qatar and Kuwait underdeveloped markets. |
Research Approach
Cross-validation between distributor procurement data and veterinary clinic purchasing records anchors the qualitative findings in this study. Primary interviews with pet food brand managers, SFDA regulatory affairs specialists, Gulf retail category buyers, and cold-chain logistics operators combined with secondary validation from SFDA filing databases, MOHAP import registration records, customs trade documentation, and Nielsen retail audit data. Bottom-up SKU-level volume aggregation and top-down macroeconomic scaling triangulate market size estimation.
Calibration against historical growth trajectories in comparable premiumization markets informs the analytical framework across the projection horizon. Segmentation dimensions modeled include product format, ingredient certification tier, distribution channel, and companion animal species. CAGRs derive from regression analysis of adoption curve penetration rates. Forecast inputs incorporate small-breed dog ownership demographic shifts and cold-chain infrastructure investment pipelines.
Sensitivities concentrate around halal certification timeline extensions, Australian dollar exchange rate volatility, and refrigerated last-mile capacity deployment delays. Forecasts reflect documented assumptions regarding regulatory convergence pace and premium format adoption elasticity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Mobile Pet Care Market
Pet Care Products
China Cat Litter Market
Pet Care Products
Dog Brush Market
Pet Care Products
Cat Harness Market
Pet Care Products
Pet Grooming Services Market
Pet Care Products
Therapeutic Diet for Pet Market
Pet Care Products
South Africa Pet Boarding Market
Pet Care Products
Pet Clean-Up and Odor-Control Products Market
Pet Care Products
Germany Pet Food Market
Pet Care Products
Cat Collar Market
Pet Care Products
Dog Vest Market
Pet Care Products
Frozen and Freeze-Dried Pet Food Market
Pet Care Products
Cat Calming Treats Market
Pet Care Products
North America Pet Diet Market
Pet Care Products
Pet Odor Absorber Market
Pet Care Products
Canned Wet Cat Food Market