
 United States Luxury Hotel Market | 2026-2036
United States Luxury Hotel Market Size, Share, and Industry Trends Forecast 2026-2036
United States Luxury Hotel Market Analytics
The United States luxury hotel segment is decoupling from mid-scale and economy tiers in both rate architecture and guest experience investment. Marriott International leverages its Bonvoy ecosystem to sustain direct booking share against online travel agency commissions. Hyatt Hotels Corporation anchors its portfolio around wellness-centric property designs that differentiate select urban and resort locations. Four Seasons Hotels and Resorts competes on service labor ratios and residential-style suite configurations that dominate ultra-premium positioning.
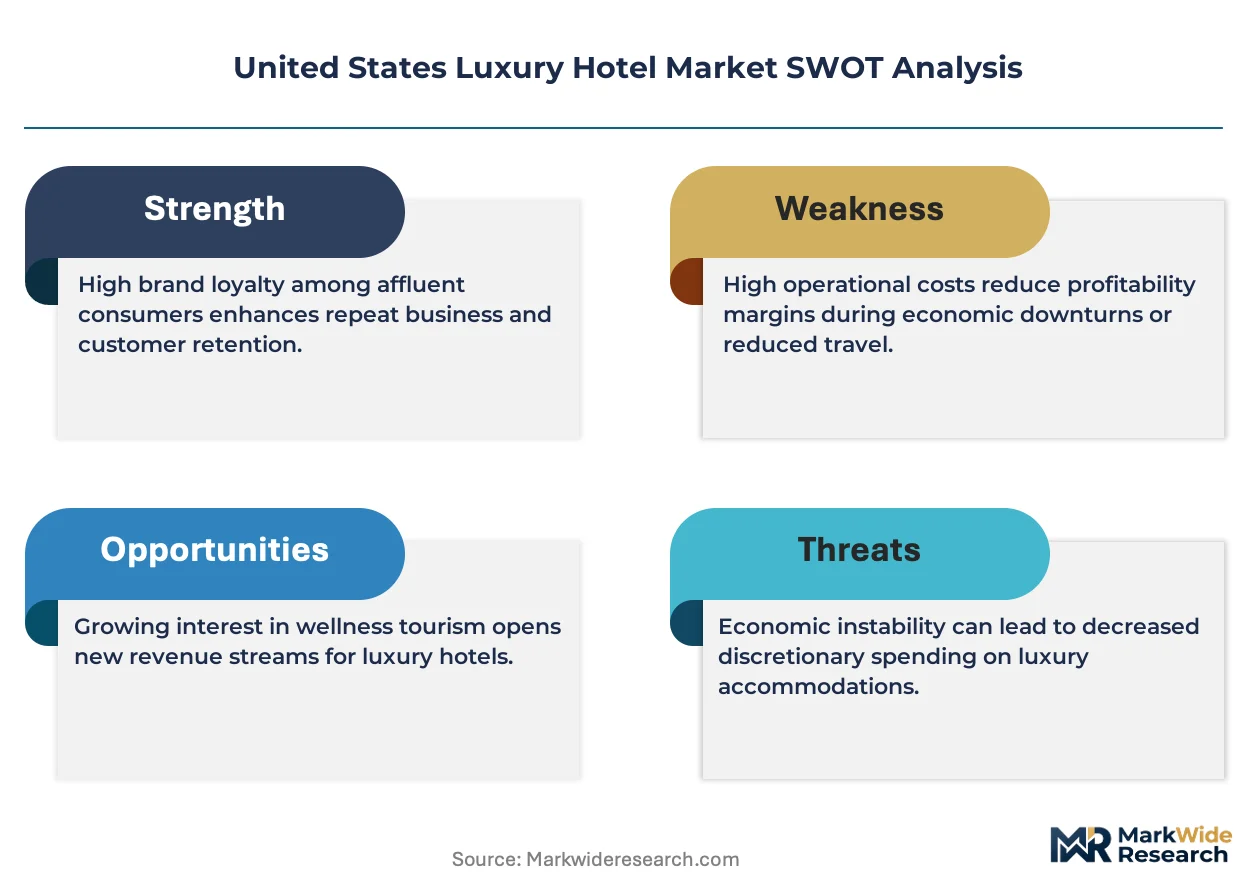
Luxury hotels in the United States constitute full-service lodging properties typically offering minimum four-diamond ratings, personalized concierge operations, fine dining outlets, and spa or wellness facilities across average daily rates exceeding three hundred dollars. These properties serve high-net-worth leisure travelers, corporate executives, and event-driven groups requiring premium accommodations with bespoke service protocols. Resort and boutique property types command the deepest margin pools due to experiential differentiation and lower direct chain-competition density. Business travelers represent a recovering but structurally smaller segment as hybrid work patterns reshape corporate travel budgets. Direct booking channels now capture growing share as loyalty program investments reduce reliance on online travel agency intermediaries.
The Department of Justice and Federal Trade Commission scrutinize merger activity among major hotel operators, affecting consolidation strategies. The Americans with Disabilities Act and state-level building codes enforce accessibility standards that shape renovation timelines and capital allocation. OSHA workplace safety requirements influence labor cost structures in housekeeping and food service operations. Stakeholders must monitor how interest rate movements affect development financing and whether branded residential components offset pure lodging volatility.
Market Dynamics
Leisure traveler preference for experiential over transactional lodging is restructuring capital allocation across the United States luxury hotel sector. Developers now prioritize wellness infrastructure and residential-style suite configurations over conventional business-center amenities.
Growth Catalysts
- Americans with Disabilities Act Renovation Cycles:Federal accessibility mandates trigger property-wide upgrades that simultaneously modernize aging infrastructure and expand addressable guest segments.
- Florida Resort Corridor Demand Density:Concentrated high-net-worth leisure migration to Miami-Dade and Orlando-Kissimmee sub-markets sustains premium rate floors through seasonal peaks.
- Direct Booking Channel Migration:Loyalty program investments reduce online travel agency commission burdens and capture richer guest data for personalized service delivery.
Market Restraints
- Interest Rate Sensitivity:Federal Reserve policy movements compress development financing availability and extend project timelines for ground-up luxury construction.
- Specialized Labor Scarcity:OSHA workplace safety requirements elevate housekeeping and food service wage structures while reducing available candidate pools in select metropolitan markets.
- Supply Concentration in Manhattan:Overbuilt luxury inventory in New York City's core cluster creates localized rate pressure that ripples through Northeast pricing benchmarks.
Strategic Opportunities
- State-Level Sustainability Mandates:California and New York building efficiency standards create first-mover advantages for properties achieving net-zero operational certification ahead of compliance deadlines.
- Hybrid Work Adjacent Stays:Extended-stay suite configurations targeting remote executives blend leisure and productivity amenities in resort and secondary urban locations.
- Branded Residential Component Integration:Fractional ownership and condominium structures offset pure lodging revenue volatility while locking in long-term management contracts.
Industry Challenges
- Historic Property HVAC Retrofitting:Pre-war building stock in Boston, Philadelphia, and Chicago requires capital-intensive mechanical system replacement to meet contemporary efficiency and comfort standards.
- Concierge Talent Development:Bespoke service protocols demand specialized training pipelines that compete with broader hospitality and luxury retail sectors for skilled candidates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Luxury Hotel Market |
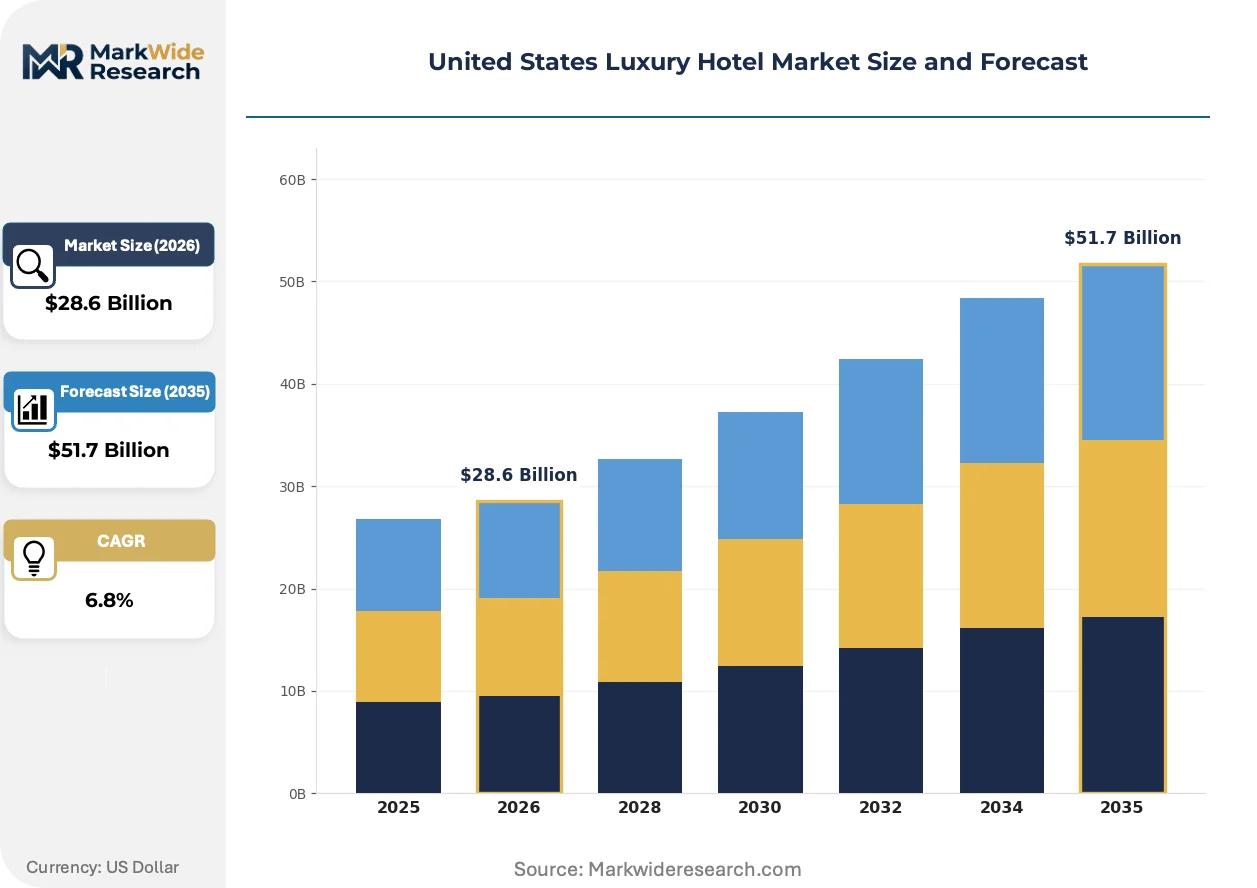
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Property Type: Resort, Boutique Hotel, Chain Hotel, All-Suite Hotel Customer Type: Leisure Travelers, Business Travelers, Group Travelers, Event Planners Amenities Offered: Spa Services, Fine Dining, Concierge, Room Service Booking Channel: Direct Booking, Online Travel Agencies, Travel Agents, Corporate Bookings |
| Companies Covered | Marriott International, Hilton Worldwide, Hyatt Hotels Corporation, InterContinental Hotels Group, Accor, Four Seasons Hotels and Resorts, Rosewood Hotels and Resorts, Ritz-Carlton Hotel Company, Aman Resorts, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Luxury Hotel Market Evolving Landscape
Digital infrastructure and sustainability certification are converging to redefine guest experience architecture across the United States luxury hotel landscape. Properties now compete on operational transparency and personalized environmental control rather than standardized amenity checklists.
Smart room technology is integrating IoT-enabled climate, lighting, and entertainment systems into unified guest-controlled environments. Urban and resort properties alike deploy these platforms to reduce energy waste while capturing preference data for return-visit personalization. The technology is integrating operational silos that previously required separate staff interventions, compressing service response times.
The Department of Justice and Federal Trade Commission maintain active merger review protocols that constrain consolidation strategies among major operators. This regulatory posture preserves independent and boutique property competitiveness while complicating scale-driven loyalty program expansion. Smaller regional portfolios face elevated legal costs when pursuing strategic combinations.
Leisure travelers now initiate booking journeys through property-direct digital channels rather than traditional travel advisor intermediaries. High-net-worth segments research sustainability certifications and wellness program specifics before committing to premium rate categories. This behavior shift concentrates marketing investment on owned-platform content and transparent operational disclosure, particularly visible in Florida and California resort markets.
United States Luxury Hotel Market Segmentation
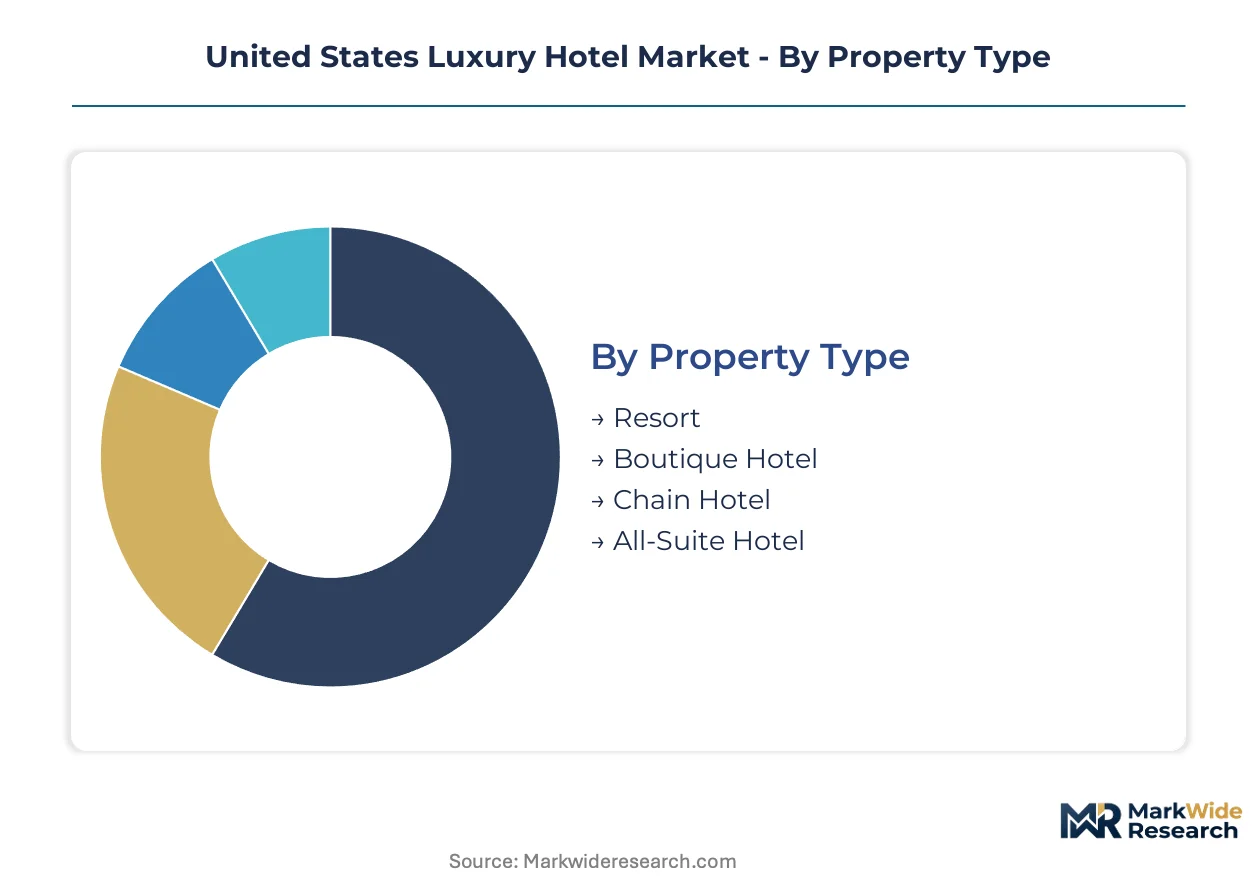
Segmentation in the United States luxury hotel market reveals how capital allocation, guest acquisition costs, and operational complexity vary across property configurations. Developers and operators use these categories to match investment intensity with revenue stability and margin profiles.
Property Type:
Resort properties demand the heaviest upfront capital commitment due to land assembly, extensive amenity infrastructure, and environmental permitting timelines.
- Resort:Sprawling footprints integrate golf courses, wellness pavilions, and multiple dining venues across coastal or mountain locations. Florida's resort corridors absorb concentrated leisure migration, sustaining premium rate floors through seasonal peaks despite hurricane exposure and insurance cost volatility.
- Boutique Hotel:Intimate scale properties emphasize design-forward interiors and localized programming over standardized brand consistency. Manhattan's luxury cluster hosts the densest concentration, though overbuilt inventory creates localized rate pressure that ripples through Northeast pricing benchmarks.
- Chain Hotel:Flagged properties leverage centralized reservation systems and loyalty program infrastructure to reduce customer acquisition costs. These assets trade some experiential differentiation for revenue management sophistication and repeat guest capture.
- All-Suite Hotel:Residential-style configurations target extended-stay demand with separate living spaces and kitchenettes. Hybrid work patterns have expanded addressable demand beyond traditional corporate relocation segments.
Resort properties absorb the bulk of installed capacity; boutique hotels are expanding most quickly.
Customer Type:
Customer mix determines staffing ratios, food and beverage investment, and the optimal balance between transient and group business.
- Leisure Travelers:High-net-worth individuals and families now drive the majority of premium room-night demand across United States luxury properties. These guests prioritize experiential programming and sustainability credentials over transactional efficiency.
- Business Travelers:Corporate executives represent a recovering but structurally smaller segment as hybrid work patterns reshape travel budgets. Properties serving this segment emphasize location efficiency and meeting infrastructure over resort amenities.
- Group Travelers:Multi-room blocks for weddings, reunions, and affinity gatherings require dedicated event coordination and flexible catering capacity. Peak season compression creates yield management complexity.
- Event Planners:Third-party coordinators negotiate aggressively on commission structures and attrition clauses, compressing net revenue per occupied room for group business.
Leisure travelers command the deepest margin contribution; group volume is climbing the fastest as postponed celebrations reschedule.
Amenities Offered:
Amenity programming separates rate tiers and extends guest dwell time, directly influencing food and beverage capture and ancillary spend per stay.
- Spa Services:Wellness infrastructure requires specialized build-out, certified therapist recruitment, and ongoing product supply relationships. California properties lead operational certification ahead of state-level sustainability mandate deadlines.
- Fine Dining:Chef-driven restaurants anchor destination positioning but demand kitchen capital and inventory management discipline. These outlets compete with independent restaurants for talent and guest occasion.
- Concierge:Bespoke service protocols require specialized training pipelines that compete with luxury retail for skilled candidates. Labor ratios in this function distinguish ultra-premium positioning.
- Room Service:24-hour in-room dining has contracted as a standard offering, with many properties substituting grab-and-go alternatives or third-party delivery partnerships.
Fine dining absorbs the heaviest operational investment; spa services are gaining share fastest as wellness prioritization accelerates.
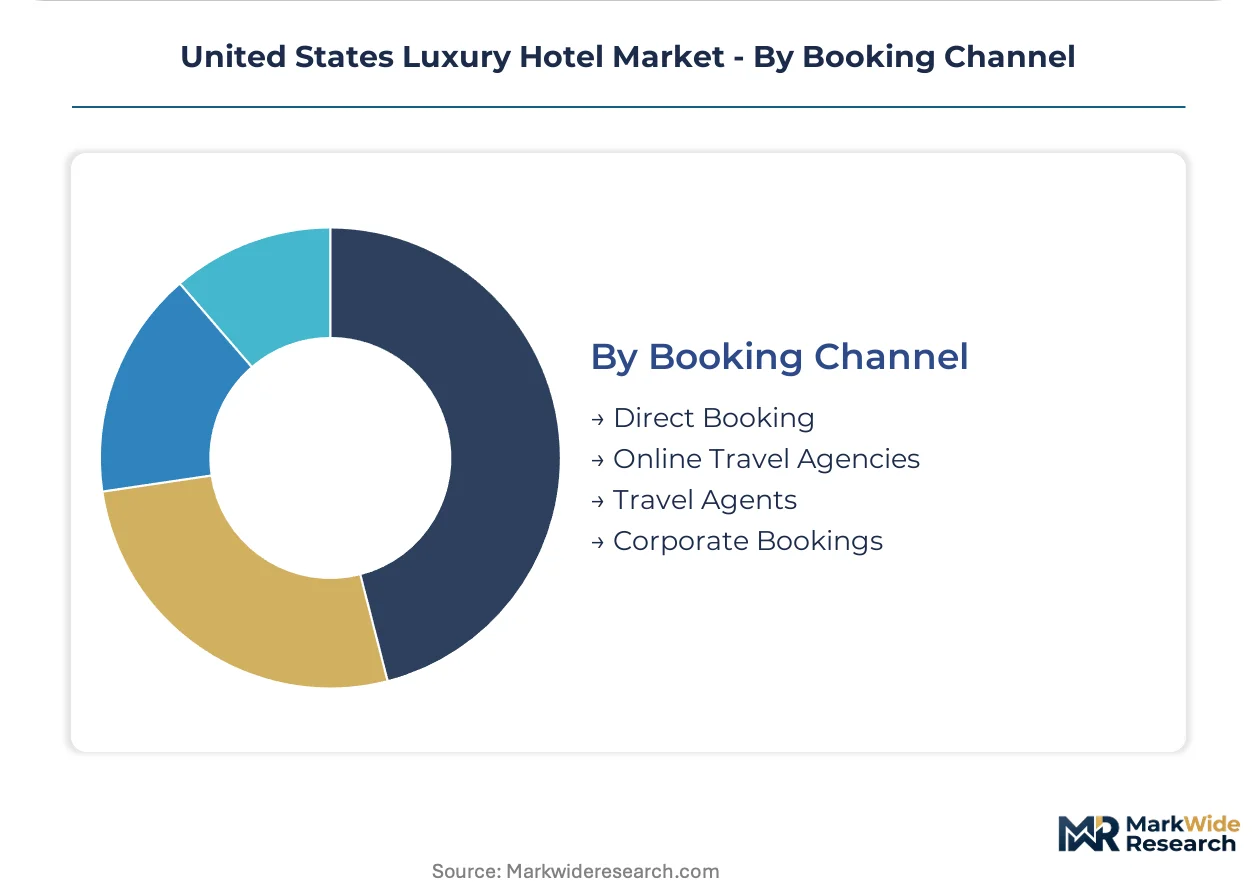
Booking Channel:
Channel mix shapes customer acquisition economics, guest data ownership, and the degree of rate parity enforcement required.
- Direct Booking:Property-owned digital platforms and loyalty program redemption capture the richest guest preference data while eliminating intermediary commissions. Marriott International's Bonvoy ecosystem exemplifies this strategy.
- Online Travel Agencies:Expedia and Booking Holdings aggregates deliver volume visibility but compress net revenue through commission structures and rate parity constraints. Properties balance OTA presence against direct channel investment.
- Travel Agents:Traditional advisor intermediaries retain influence in ultra-high-net-worth segments and complex multi-destination itineraries. Commission structures here exceed OTA economics but deliver qualified demand.
- Corporate Bookings:Negotiated rate contracts with Fortune 500 travel managers provide base-load occupancy but limit dynamic pricing flexibility during peak compression periods.
Direct booking channels command the fastest expansion trajectory; corporate agreements provide the steadiest base-load foundation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manhattan's luxury cluster anchors United States premium lodging demand, with concentrated development in Midtown and Hudson Yards corridors driving national rate benchmarks. State-level sustainability mandates and federal accessibility requirements reshape capital allocation across metropolitan sub-markets.
Florida
Miami-Dade and Orlando-Kissimmee corridors absorb concentrated high-net-worth leisure migration, sustaining premium rate floors through seasonal peaks. The state's building code enforcement and hurricane resilience standards elevate insurance and construction costs for coastal resort developments. Palm Beach and Naples sub-markets command the deepest margin pools due to experiential differentiation and limited competing supply.
California
Los Angeles and San Francisco metropolitan areas blend entertainment industry demand with technology executive travel, creating hybrid leisure-business guest profiles. California Title 24 building efficiency standards and Cal/OSHA workplace requirements accelerate property renovation cycles and elevate operational compliance costs. Napa Valley and coastal Orange County resort concentrations lead wellness infrastructure investment ahead of net-zero certification deadlines.
New York
Manhattan's luxury inventory concentration generates localized rate pressure that ripples through Northeast pricing benchmarks, particularly in Midtown and SoHo districts. New York State energy efficiency mandates and NYC Department of Buildings accessibility enforcement trigger pre-war property HVAC retrofitting requirements. Brooklyn and Hudson Valley secondary markets capture overflow demand as primary Manhattan supply saturates.
Texas
Dallas-Fort Worth and Houston energy sector executives sustain corporate luxury demand despite hybrid work compression in other markets. Texas Commission on Environmental Quality air quality standards and municipal building codes shape new development specifications in Austin and San Antonio growth corridors. Hill Country resort sub-markets outside Austin attract wellness-focused leisure investment with lower land assembly costs than coastal alternatives.
United States Luxury Hotel Market Competitive Landscape
Capital-heavy property owners compete with asset-light management contract operators for fee-based revenue streams without balance-sheet real estate exposure. The United States luxury hotel sector presents a tiered structure with global flagged portfolios, independent boutique collections, and ultra-premium residential-style operators occupying distinct competitive positions. Three strategic archetypes dominate: scale-driven loyalty program ecosystems, design-forward experiential specialists, and service-labor-intensive ultra-premium operators. Consolidation activity concentrates on management contract acquisitions and brand portfolio diversification rather than property-level real estate aggregation.
Among global flagged operators, Marriott International and Hilton Worldwide occupy positions as scale-driven loyalty ecosystem anchors, while Hyatt Hotels Corporation exemplifies the wellness-centric design specialist archetype. Four Seasons Hotels and Resorts represents the service-labor-intensive ultra-premium tier with residential-style suite configurations. These three entities collectively illustrate how competitive positioning stratifies across direct booking channel investment, experiential amenity programming, and bespoke service protocol depth.
| Leading Market Players |
|---|
| Marriott International |
| Hilton Worldwide |
| Hyatt Hotels Corporation |
| InterContinental Hotels Group |
| Accor |
| Four Seasons Hotels and Resorts |
| Rosewood Hotels and Resorts |
| Ritz-Carlton Hotel Company |
| Aman Resorts |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up luxury hotel portfolios anchor pricing discipline through yield management centralization while compressing procurement leverage across fragmented FF&E suppliers. These ownership structures concentrate renovation capital in flagship assets while extracting operational efficiencies through shared service platforms.
Pricing Analysis
Value-based pricing anchored to experiential outcomes and guest satisfaction scores dominates rate-setting architecture across United States luxury properties. Three-tier pricing structure across ultra-premium suites, standard luxury accommodations, and entry-luxury rooms reflects amenity depth and service labor ratios. Pricing pressure stems from overbuilt Manhattan inventory rippling through Northeast benchmarks. Corporate booking segments exhibit highest price sensitivity; leisure travelers in Florida resort corridors demonstrate lowest elasticity.
Supply Chain Analysis
ADA compliance certification and LEED operational standards gate supplier qualification across United States luxury hotel procurement. Domestic manufacturers supply custom millwork and soft goods while Italy and Turkey anchor luxury textile sourcing. Construction materials draw from regional distributors with tariff exposure on imported stone and fixture components. Distribution runs through consolidated procurement consortia serving branded flag portfolios.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States luxury hotel sector is transitioning from transactional booking systems to integrated digital guest experience platforms. Smart room IoT infrastructure is displacing legacy building management systems as the primary capital allocation priority.
For Market Incumbents: Acquire boutique management contracts in secondary urban markets to capture experiential differentiation without balance-sheet real estate exposure. Consolidate loyalty program data infrastructure to defend direct booking share against online travel agency commission compression. Prioritize wellness certification investment ahead of California and New York sustainability mandate deadlines.
For New Entrants and Emerging Players: ADA renovation cycle requirements in legacy urban properties open a window for accessibility-focused design-build specialists to capture renovation spend. Target historic hotel HVAC retrofitting demand in Boston, Philadelphia, and Chicago where capital-intensive mechanical replacement exceeds incumbent operator appetite. Pursue white-label spa management contracts as the most penetrable service vertical.
For Investors and Strategic Acquirers: Distressed-cycle entries favor all-suite extended-stay assets in Texas Hill Country and Florida resort corridors where hybrid work patterns sustain occupancy premiums. Long-term viability hinges on branded residential component integration locking in management fee streams. Monitor Federal Reserve interest rate trajectory as inflection indicator for development financing availability.
| Strategic Initiative | Industry Significance |
|---|---|
| Direct Booking Platform Investment | Marriott Bonvoy demonstrates loyalty ecosystem capture reducing OTA commission burdens. |
| Wellness Infrastructure Buildout | Hyatt's wellness-centric designs differentiate select urban and resort locations. |
| Branded Residential Integration | Four Seasons residential-style suites lock in long-term management contracts. |
| Smart Room Technology Deployment | IoT-enabled climate and lighting systems compress service response times. |
| Sustainability Certification Advancement | California Title 24 compliance creates first-mover positioning ahead of deadlines. |
Research Methodology
Document review covered SEC hospitality sector filings, Smith Travel Research demand data, and municipal building permit records, complemented by interviews with hotel development executives, revenue management directors, procurement leads at FF&E suppliers, and franchise operations officers. Secondary sources included OSHA workplace safety reports, DOJ-FTC merger review dockets, and state-level energy efficiency mandate documentation. Bottom-up property-level revenue modeling triangulated against top-down macroeconomic demand projections.
Cross-reference of historical occupancy and rate trajectories against executive panel input shaped the analytical framework across the projection horizon. Segmentation dimensions modeled encompass property type, customer segment, amenity configuration, and booking channel. CAGRs derived from regression analysis of demand drivers including high-net-worth leisure migration patterns and corporate travel budget recovery. Forecast inputs incorporated interest rate sensitivity scenarios and hurricane insurance cost volatility for Florida resort assets.
The model assumes a particular technology adoption path; alternative pathways for smart room IoT deployment would alter the outlook for operational efficiency gains and capital allocation priorities. Forecasts reflect assumptions regarding sustained leisure traveler preference for experiential lodging and regulatory enforcement continuity. A model refresh is warranted upon material change in Federal Reserve policy or ADA enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hotels and Resorts
Cuba Tourism and Hotel Market
Hotels and Resorts
Philippines Tourism and Hotel Market
Hotels and Resorts
Five Star Hotel Market
Hotels and Resorts
Global Beach Hotels Market
Hotels and Resorts
Spain HRI Market
Hotels and Resorts
Morocco Tourism and Hotel Market
Hotels and Resorts
Morocco Tourism Market
Hotels and Resorts
Europe Luxury Hotel Market
Hotels and Resorts
Germany HRI Market
Hotels and Resorts
India Luxury Hotel Market
Hotels and Resorts
Hotels, Resorts, and Cruise Lines Market
Hotels and Resorts
Asia-Pacific Luxury Hotel Market
Hotels and Resorts
Boutique Hotels Market
Hotels and Resorts
Spa Resorts Market
Hotels and Resorts
Mountain and Ski Resorts Market
Hotels and Resorts
United Kingdom HRI Market