
 Germany HRI Market | 2026-2036
Germany HRI Market Size, Share, and Industry Trends Forecast 2026-2036
Germany HRI Market Foresight
The EU F-Gas Regulation is repositioning refrigerant-dependent kitchen infrastructure toward lower-GWP alternatives. McDonald's leverages its scale to pre-empt compliance across German franchise networks. Burger King anchors its refurbishment schedule to the phasedown timeline. KFC competes through targeted equipment upgrades in high-traffic locations.
Hotels, Restaurants, and Institutions (HRI) denotes commercial foodservice operations encompassing preparation, cooking, and service infrastructure for away-from-home consumption. Electric induction systems dominate new installations due to thermal efficiency exceeding 90% and elimination of open-flame ventilation requirements. Product type segmentation shows gas burners retaining share in legacy institutional kitchens while ceramic hob configurations capture premium hotel fit-outs. Touch control technology leads distribution channel engagement through specialty stores serving independent operators.
Germany's Federal Ministry for Economic Affairs and Climate Action (BMWK) enforces efficiency labeling under the Energieverbrauchskennzeichnungsgesetz, compelling manufacturers to disclose consumption metrics. The KBA-relevant commercial vehicle standards indirectly shape mobile catering equipment specifications. Stakeholders must monitor pending amendments to the EU Ecodesign Directive that will tighten standby power limits for connected kitchen appliances.
Market Dynamics
Germany's Building Energy Act (GEG) compresses the replacement cycle for commercial kitchen infrastructure, forcing operators to retire gas-dependent equipment ahead of natural obsolescence. Bavarian full-service restaurants and North Rhine-Westphalia hotel groups accelerate electric induction procurement to preempt enforcement windows.
Growth Catalysts
- GEG efficiency mandates:The Building Energy Act establishes hard thresholds for commercial kitchen equipment, compelling operators to source electric alternatives. Berlin's hotel renovation pipeline absorbs premium induction systems at elevated volumes.
- Munich catering cluster concentration:Bavaria's institutional foodservice hub generates concentrated procurement demand for high-capacity electric cooking infrastructure. Regional suppliers align distribution capacity to this geography.
- F-Gas refrigerant phaseout:The EU F-Gas Regulation redirects capital toward lower-GWP kitchen infrastructure across German franchise networks. Equipment financing now incorporates compliance timeline risk.
Market Restraints
- Copper and semiconductor input volatility:Induction coil manufacturing depends on copper pricing and power electronics availability. German fabricators face margin compression from commodity swings.
- Legacy gas infrastructure lock-in:Existing ventilation and fuel line investments in institutional kitchens create switching cost barriers. Operators delay full electrification where gas lines remain functional.
- Grid capacity constraints in eastern states:Saxony and Thuringia commercial zones face distribution network limitations for high-amperage electric cooking loads. Utility upgrade timelines extend project completion.
Strategic Opportunities
- Baden-Württemberg precision manufacturing corridor:Stuttgart's industrial equipment base supports domestic induction component fabrication. Local sourcing reduces import dependency for control systems.
- Connected appliance convergence:IoT-enabled cooking platforms integrate with building energy management systems. Operators gain demand-response revenue streams through utility programs.
- BMWK efficiency labeling differentiation:The Energieverbrauchskennzeichnungsgesetz creates tiered product positioning. Premium-rated equipment commands specification priority in public procurement.
Industry Challenges
- Certified electrician scarcity:Commercial induction installation requires specialized high-voltage credentials. Training pipeline gaps extend project timelines in secondary cities.
- Legacy ventilation retrofit complexity:Existing hood systems designed for combustion byproducts require reengineering for electric cooking effluent. Operators face unbudgeted mechanical scope.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany HRI Market |
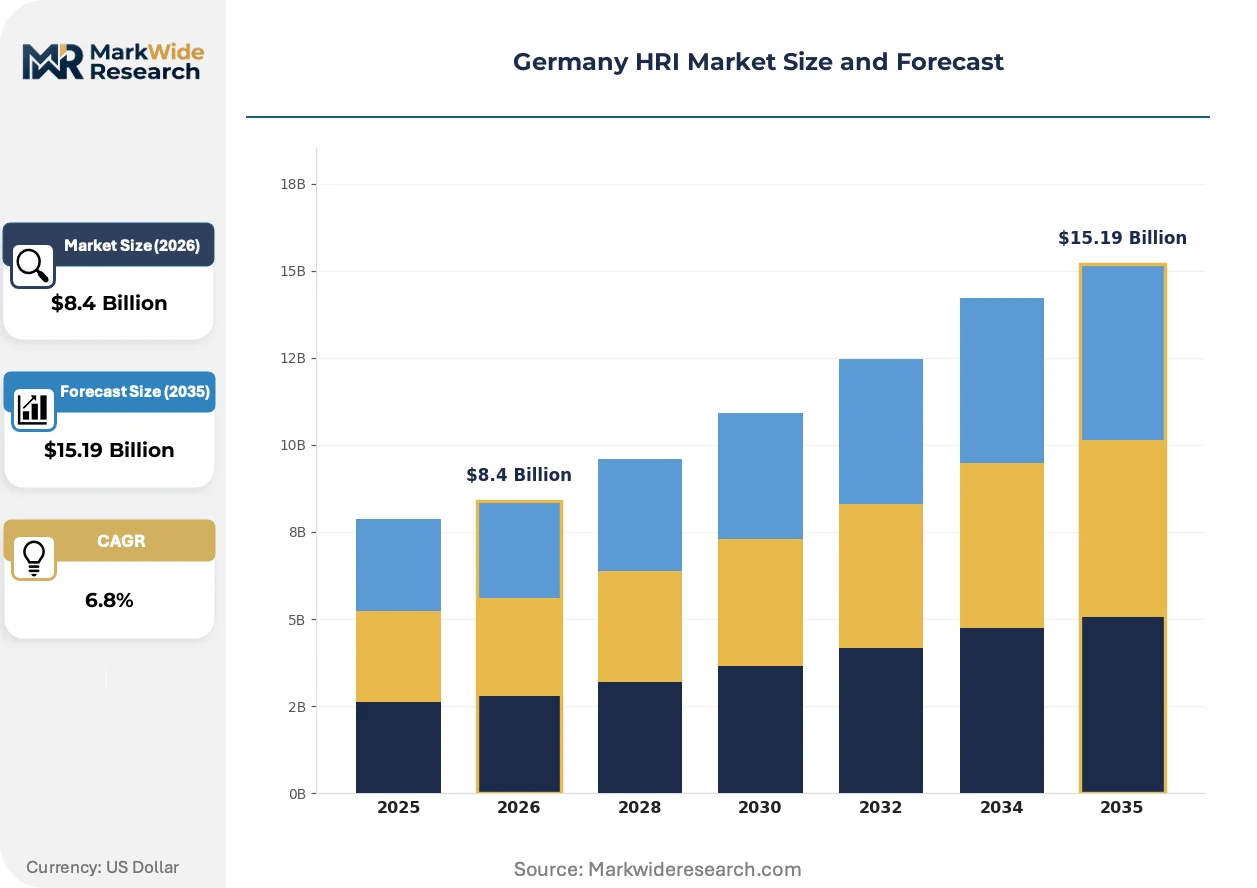
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.19 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Induction, Gas Burners, Radiant Plate, Halogen, Ceramic Hob End Use Industry: Commercial Kitchens, Catering Services, Hotels, Food Processing Units, Institutions Technology: Touch Control, Manual Control, Auto Shut-off, Temperature Sensors, Timer Function Distribution Channel: Specialty Stores, Online Retailers, Wholesale Distributors, Direct Sales, Appliance Dealers |
| Companies Covered | Caffè Nero, Rosebottel, Papa Joe's, Nordsee, Popeyes Louisiana Kitchen, McDonald's, KFC, Burger King, Yum! Brands, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany HRI Market Shifts & Advancements
Electrification mandates and digital integration are compressing equipment replacement cycles while reshaping supplier-operator relationships. German commercial kitchens face simultaneous pressure to decarbonize operations and integrate connected infrastructure.
Induction cooking technology is integrating advanced power electronics and precision temperature control into modular platform architectures. Munich's high-volume catering operators adopt these systems to eliminate open-flame ventilation requirements and reduce kitchen footprint. The technology is integrating building management protocols, enabling load balancing across multiple cooking stations during peak demand periods.
The EU Ecodesign Directive tightens standby power limits for connected kitchen appliances, forcing firmware and hardware redesigns across German equipment portfolios. Manufacturers must recertify product lines to maintain market access. Full-service restaurants in Hamburg and Frankfurt face compressed procurement timelines as compliance deadlines approach.
Equipment-as-a-service models displace traditional capital purchase arrangements among mid-scale independent operators. Leasing providers bundle maintenance, energy monitoring, and upgrade rights into single contracts. This shift concentrates most visibly in Berlin's hotel renovation pipeline, where ownership seeks operational expenditure predictability over asset ownership.
Germany HRI Market Segmentation
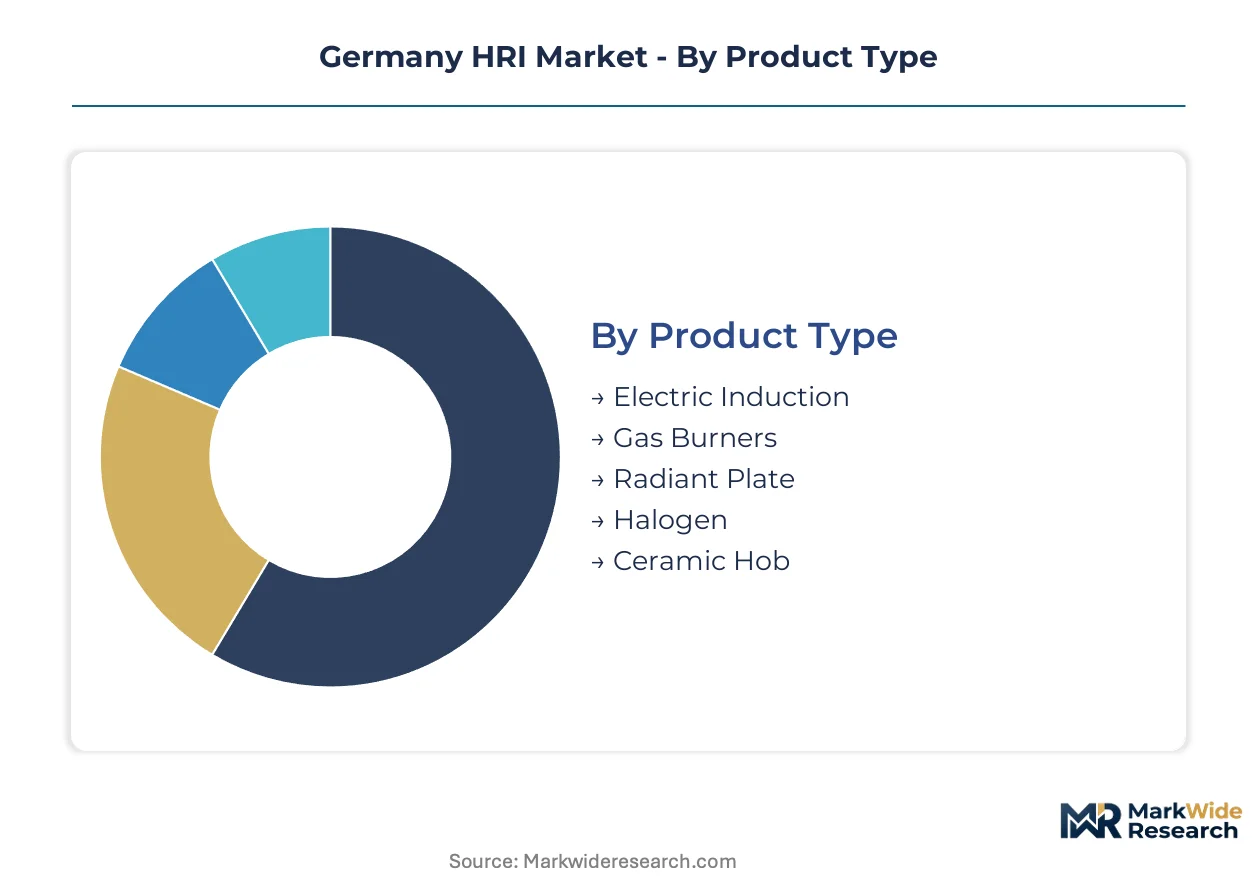
Equipment specification in Germany's HRI market diverges sharply between regulatory-driven replacements and discretionary upgrades. Procurement patterns cluster around electrification mandates in Bavaria and North Rhine-Westphalia versus legacy retention in eastern states with grid constraints.
Product Type:
The customization-to-standardization spectrum spans from bespoke induction platforms engineered for specific kitchen footprints to mass-configured gas burners with interchangeable components.
- Electric Induction:Electromagnetic coil systems generate heat directly in ferrous cookware with thermal efficiency exceeding 90%. Bavarian full-service restaurants and North Rhine-Westphalia hotel groups absorb premium units to comply with GEG efficiency thresholds ahead of enforcement windows.
- Gas Burners:Open-flame combustion systems retain installed base in institutional kitchens with functional ventilation infrastructure. Operators in Saxony and Thuringia delay replacement where grid capacity cannot support high-amperage electric alternatives.
- Radiant Plate:Electric resistance heating elements suit mid-scale catering operations seeking thermal consistency without induction's cookware constraints.
- Halogen:Tungsten-halogen lamp systems deliver rapid response times for front-of-house cooking demonstrations in Munich's high-traffic hotel properties.
- Ceramic Hob:Smooth-surface electric cooktops capture premium hotel fit-outs in Berlin's renovation pipeline where aesthetics drive specification alongside performance.
Leading the category by volume: Electric Induction. Growing fastest: Ceramic Hob.
End Use Industry:
Application intensity ranges from continuous-duty institutional food production to intermittent event-based catering with highly variable load profiles.
- Commercial Kitchens:High-throughput preparation facilities in independent restaurants and chain operations. Munich's catering hub generates concentrated procurement for modular induction platforms with building management integration.
- Catering Services:Mobile and event-based foodservice requiring equipment portability and rapid deployment. Operators face KBA-relevant commercial vehicle standards shaping mobile kitchen specifications.
- Hotels:Full-service properties with integrated banquet and room service operations. Berlin's renovation pipeline absorbs connected appliance systems with utility demand-response capability.
- Food Processing Units:Industrial-scale preparation facilities with standardized batch requirements and continuous production schedules.
- Institutions:Schools, hospitals, and corporate cafeterias with legacy gas infrastructure and extended equipment replacement cycles driven by public procurement timelines.
Commercial Kitchens dominate procurement volume. Hotels exhibit the steepest expansion trajectory amid renovation-driven replacement cycles.
Technology:
Control sophistication determines price positioning from basic mechanical interfaces to networked systems with predictive maintenance algorithms.
- Touch Control:Capacitive interface panels with programmable recipe storage and HACCP logging. Specialty stores serving independent operators report strongest engagement for these configurations.
- Manual Control:Rotary dial or lever-actuated systems with minimal electronic content. Budget-constrained institutional buyers prioritize repairability over feature depth.
- Auto Shut-off:Safety interlocks responding to pan removal or overheating conditions. Required for EU Ecodesign Directive compliance on connected appliances.
- Temperature Sensors:Probe-based feedback systems enabling precision cooking protocols in premium hotel properties.
- Timer Function:Integrated countdown controls for batch consistency in high-volume catering environments.
Touch Control leads technology category volume. Auto Shut-off is climbing fastest as regulatory deadlines approach.
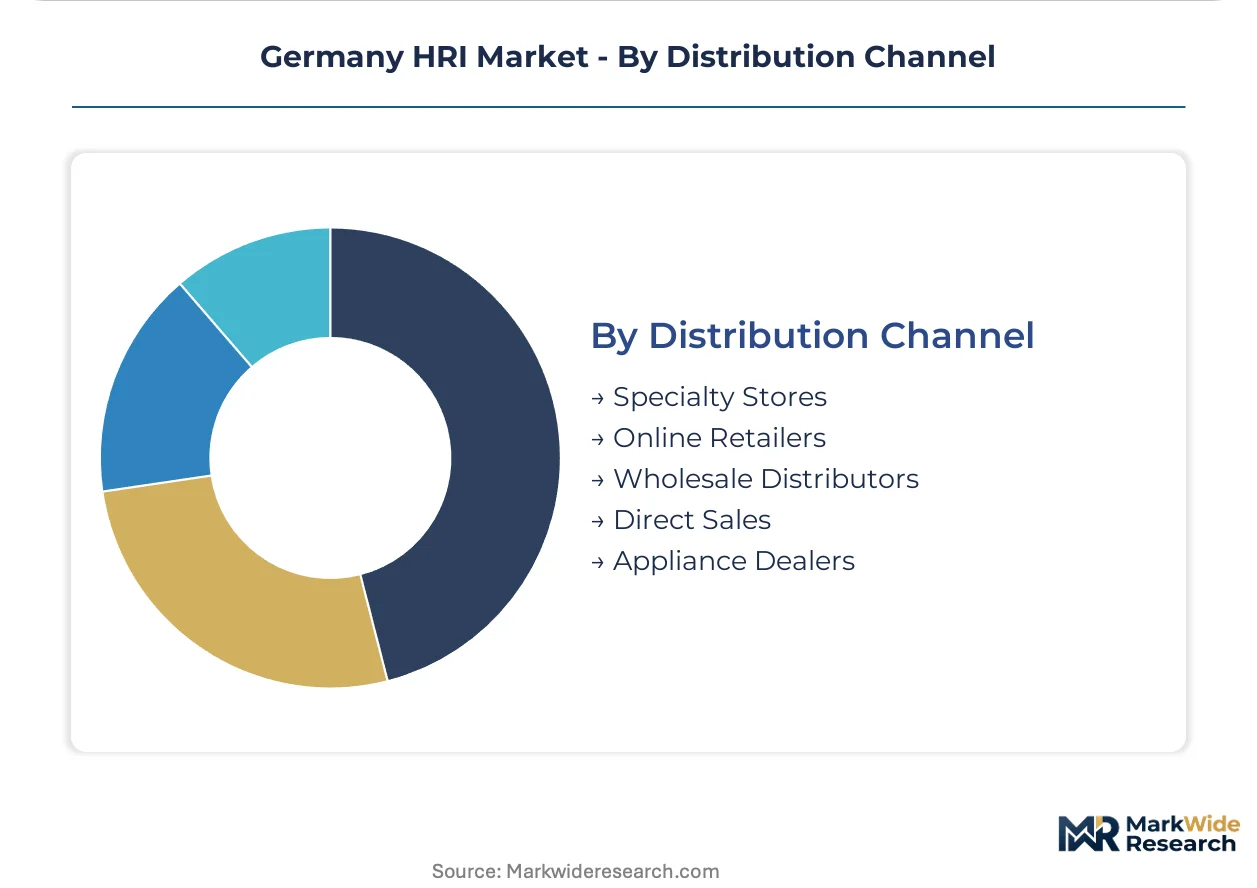
Distribution Channel:
Channel selection reflects operator scale and technical support requirements from self-service procurement to engineered system integration.
- Specialty Stores:Dedicated commercial kitchen equipment retailers with demonstration facilities and installation coordination. Independent operators in Hamburg and Frankfurt rely on these channels for specification guidance.
- Online Retailers:Digital platforms serving price-sensitive buyers with standardized product configurations and limited technical support.
- Wholesale Distributors:Volume aggregators supplying multi-unit operators with consolidated logistics and contract pricing.
- Direct Sales:Manufacturer-led engagement for large-scale hotel and institutional projects requiring custom engineering.
- Appliance Dealers:Generalist retailers capturing replacement demand from smaller operators with immediate equipment needs.
Specialty Stores lead channel volume. Direct Sales is gaining share fastest among large hotel renovation projects.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German commercial kitchen equipment procurement concentrates in three distinct state-level clusters, each responding to different regulatory pressures and infrastructure constraints. Bavaria and North Rhine-Westphalia drive premium induction adoption, while eastern states lag due to grid limitations.
Bavaria
Munich's catering hub generates concentrated demand for high-capacity modular induction platforms with building management integration. The state's implementation of federal GEG efficiency mandates proceeds ahead of national deadlines. Full-service restaurants across Greater Munich accelerate procurement to secure compliance credits.
North Rhine-Westphalia
Düsseldorf and Cologne hotel groups absorb connected appliance systems with utility demand-response capability. Regional utilities offer load-balancing incentives that reduce effective equipment costs. The Ruhr industrial corridor supplies specialized high-voltage installation contractors for commercial kitchen projects.
Baden-Württemberg
Stuttgart's precision manufacturing base supports domestic induction component fabrication, reducing import dependency for control systems. Local fabricators source power electronics from regional semiconductor suppliers. The state's technical universities feed engineering talent into equipment design firms.
Berlin-Brandenburg
The capital's hotel renovation pipeline prioritizes operational expenditure predictability through equipment-as-a-service leasing arrangements. Property owners specify ceramic hob configurations for aesthetic-driven premium fit-outs. Brandenburg's grid infrastructure supports high-amperage loads without utility upgrade delays.
Saxony
Commercial zones in Leipzig and Dresden face distribution network limitations for electric cooking loads, extending project completion timelines. Institutional kitchens retain legacy gas infrastructure where switching costs outweigh regulatory pressure. Utility upgrade schedules lag western state counterparts by 18-24 months.
Germany HRI Market Competitive Landscape
German producers anchor the premium equipment tier; Asian fabricators hold volume positions through standardized component supply. The market exhibits moderate consolidation around five to seven dominant equipment brands with established service networks. Two strategic archetypes predominate: full-system integrators bundling installation and maintenance, and component specialists supplying induction coils and power electronics to third-party assemblers. Capacity expansion and geographic service network extension represent the dominant competitive moves.
Among quick-service restaurant operators, McDonald's, KFC, and Burger King occupy distinct archetype positions within franchise-led equipment procurement. McDonald's leverages scale to pre-empt compliance across German networks. KFC competes through targeted equipment upgrades in high-traffic locations. Burger King anchors refurbishment schedules to phasedown timelines.
| Leading Market Players |
|---|
| Caffè Nero |
| Rosebottel |
| Papa Joe's |
| Nordsee |
| Popeyes Louisiana Kitchen |
| McDonald's |
| KFC |
| Burger King |
| Yum! Brands |
| Others |
Supply & Pricing Matrix
Electric induction coil manufacturing simultaneously compresses unit economics and concentrates supplier power around copper and semiconductor inputs. German fabricators face margin pressure from commodity volatility while procurement officers negotiate multi-year contracts to lock in power electronics availability.
Pricing Analysis
Volume procurement absorbs margin compression while premium configurations retain pricing power. Equipment-as-a-service leasing models spread capital costs across operational expenditure budgets, reducing upfront price sensitivity among Berlin hotel operators. Price differentiation rests on GEG efficiency certification tiers and after-sales service bundling. Cost compression in standard induction platforms intensifies as Asian component suppliers expand capacity.
Supply Chain Analysis
Dual-sourcing requirements from major German hotel groups and QSR chains mandate qualified suppliers in both China and South Korea for power electronics. Copper coil fabrication draws from domestic Baden-Württemberg suppliers alongside Polish and Czech metal processors. Semiconductor availability from Taiwanese foundries creates single-source vulnerability for IGBT modules. Distribution runs through specialty store networks with direct sales gaining share for large hotel renovation contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Germany's HRI equipment market is consolidating around compliance-capable full-system integrators. The EU F-Gas Regulation and GEG enforcement windows are forcing smaller fabricators without certification resources toward exit.
For Market Incumbents: Deploy service network extension as the primary lever. Expand certified technician training pipelines in Saxony and Thuringia to capture delayed electrification demand. Acquire regional induction coil specialists in Baden-Württemberg to secure upstream control over power electronics integration. Preempt emerging Asian entrants by front-loading GEG compliance documentation for entire product portfolios.
For New Entrants and Emerging Players: The EU Ecodesign Directive in Germany opens a window for firmware-native equipment suppliers. Target Berlin's hotel renovation pipeline with connected appliance platforms featuring built-in demand-response capability. Enter through equipment-as-a-service leasing partnerships with property management groups seeking operational expenditure predictability.
For Investors and Strategic Acquirers: Re-rating potential sits with full-system integrators given BMWK efficiency labeling differentiation. Long-term viability favors domestic fabricators with captive control system engineering and established KBA-relevant commercial vehicle certification for mobile catering. Monitor utility grid upgrade timelines in eastern states as the inflection signal for pent-up demand release.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Power Electronics | Domestic IGBT sourcing from Stuttgart semiconductor suppliers reduces tariff exposure and lead times. |
| GEG Compliance Certification Program | BMWK efficiency labeling tiering creates specification priority in public procurement channels. |
| Equipment-as-a-Service Platform Launch | Berlin hotel operators shift capital expenditure to predictable operational budgets through leasing. |
| Connected Appliance Integration | IoT-enabled induction systems capture utility demand-response revenue streams in North Rhine-Westphalia. |
| Regional Service Network Expansion | Certified electrician training in Leipzig and Dresden accelerates project completion in grid-constrained zones. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with commercial kitchen equipment procurement managers, hotel facility directors, QSR franchise operations leads, certified installation contractors, and BMWK policy officers combined with DEHOGA industry statistics, KBA commercial vehicle registration databases, and Federal Network Agency grid infrastructure reports. Bottom-up equipment shipment tracking and top-down HRI sector expenditure modeling provided triangulation validation.
Granularity-level modeling captured product type splits at the technology configuration level, end-use industry demand at the facility-type tier, and regional procurement patterns at the state level across the analysis window. CAGRs derived from equipment replacement cycle compression under GEG mandates and F-Gas phasedown timelines. Forecast inputs incorporated copper price futures curves and utility grid upgrade schedules from transmission system operators.
The model assumes a particular technology adoption path; alternative pathways for gas-to-induction conversion in institutional kitchens would alter the outlook. Forecasts reflect documented assumptions about enforcement timing and commodity input stability. Deviation in BMWK efficiency labeling implementation or eastern state grid investment acceleration would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hotels and Resorts
Boutique Hotels Market
Hotels and Resorts
Morocco Tourism Market
Hotels and Resorts
United Kingdom HRI Market
Hotels and Resorts
Five Star Hotel Market
Hotels and Resorts
Europe Luxury Hotel Market
Hotels and Resorts
Global Floating Hotels Market
Hotels and Resorts
Spa Resorts Market
Hotels and Resorts
Hotels, Resorts, and Cruise Lines Market
Hotels and Resorts
Morocco Hospitality Market
Hotels and Resorts
India Luxury Hotel Market
Hotels and Resorts
Mountain and Ski Resorts Market
Hotels and Resorts
United States Luxury Hotel Market
Hotels and Resorts
Philippines Tourism and Hotel Market
Hotels and Resorts
Spain HRI Market
Hotels and Resorts
Morocco Tourism and Hotel Market
Hotels and Resorts
North America Luxury Hotel Market