
 Mountain and Ski Resorts Market | 2026-2036
Mountain and Ski Resorts Market Size, Share, and Industry Trends Forecast 2026-2036
Mountain and Ski Resorts Market Foresight
ISO 14001 environmental management certification is unwinding competitive access for smaller mountain operators across the European Alpine belt. Vail Resorts Inc. leverages its multi-pass network to sustain year-round visitation across North American properties. Alterra Mountain Company anchors its portfolio through destination resorts with integrated lodging and terrain diversity. Aspen Skiing Company differentiates via aggressive renewable energy commitments and on-mountain conservation programming.
Mountain and ski resorts comprise commercial recreational facilities situated at elevation, utilizing lift infrastructure with cable capacities typically ranging from 2,000 to 6,000 passengers per hour to transport visitors across groomed terrain, backcountry access points, and supporting hospitality amenities. Lift Services generate the highest-margin recurring revenue during peak winter operations, while Accommodations capture extended-stay spending from destination travelers. Families represent the most stable demand base, though Adventure Seekers command premium pricing for heli-skiing and guided backcountry experiences.
EPA stormwater discharge permits constrain expansion near sensitive watersheds in the United States, while EU F-Gas Regulation phases out hydrofluorocarbon use in snowmaking systems across European properties. Health Canada guidelines for alpine workplace safety influence operational protocols at Canadian resorts. Stakeholders must weigh capital allocation between snow reliability infrastructure and summer activity diversification as climate variability intensifies operational planning complexity.
Market Dynamics
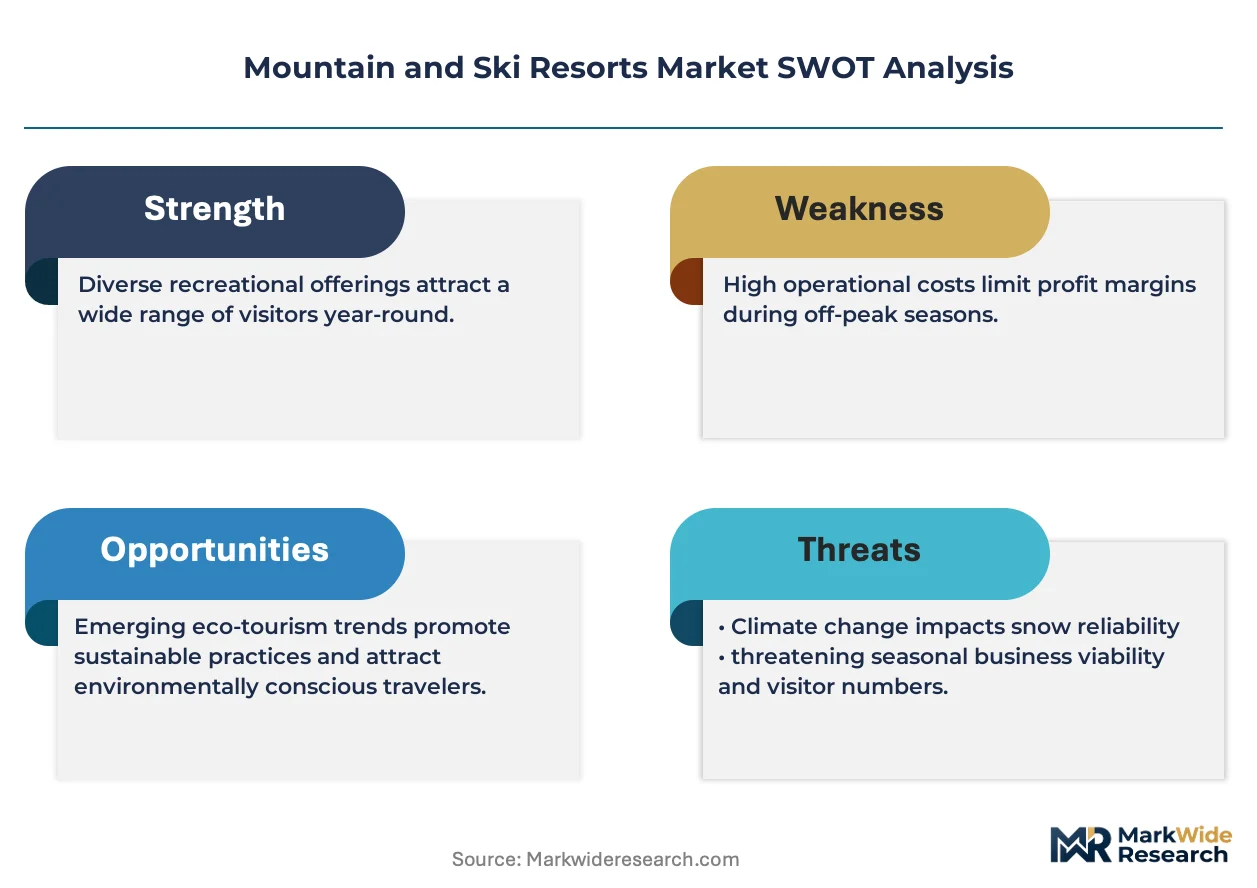
Climate volatility is forcing capital allocation trade-offs between snow reliability infrastructure and summer diversification, while EU Green Deal mandates accelerate infrastructure replacement cycles across Alpine properties.
Growth Catalysts
- EU F-Gas Regulation:Phased hydrofluorocarbon restrictions are driving replacement demand for low-emission snowmaking systems at European resorts.
- Heli-skiing and backcountry guiding:Adventure tourism operators are expanding premium booking volumes at alpine destination properties.
- France's Alpine corridor:Concentrated international visitor flows sustain extended-stay accommodation demand across Savoie and Haute-Savoie departments.
Market Restraints
- Energy input volatility:Electricity and diesel price swings compress operating margins for lift services and snowmaking operations.
- ISO 14001 certification concentration:Smaller mountain operators face competitive access barriers as environmental management standards tighten across the European Alpine belt.
- Watershed proximity limits:EPA stormwater discharge permits constrain terrain expansion near sensitive hydrological zones in US mountain regions.
Strategic Opportunities
- Summer activity diversification:Mountain biking infrastructure and alpine coaster installations capture off-season visitation at underutilized lift assets.
- EU Green Deal infrastructure financing:Sustainability-linked capital pools support renewable energy retrofits and low-carbon transport upgrades.
- Multi-pass network convergence:Integrated booking platforms spanning dispersed properties are consolidating fragmented regional demand.
Industry Challenges
- Alpine workplace safety compliance:Health Canada guidelines require specialized training protocols and equipment standards for high-elevation operations.
- Capex intensity for snow reliability:Reservoir expansion, pump stations, and automated gun networks demand substantial upfront investment with extended payback periods.
- Legacy lift system integration:New cable capacity installations must interface with decades-old control architectures and terrain access patterns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mountain and Ski Resorts Market |
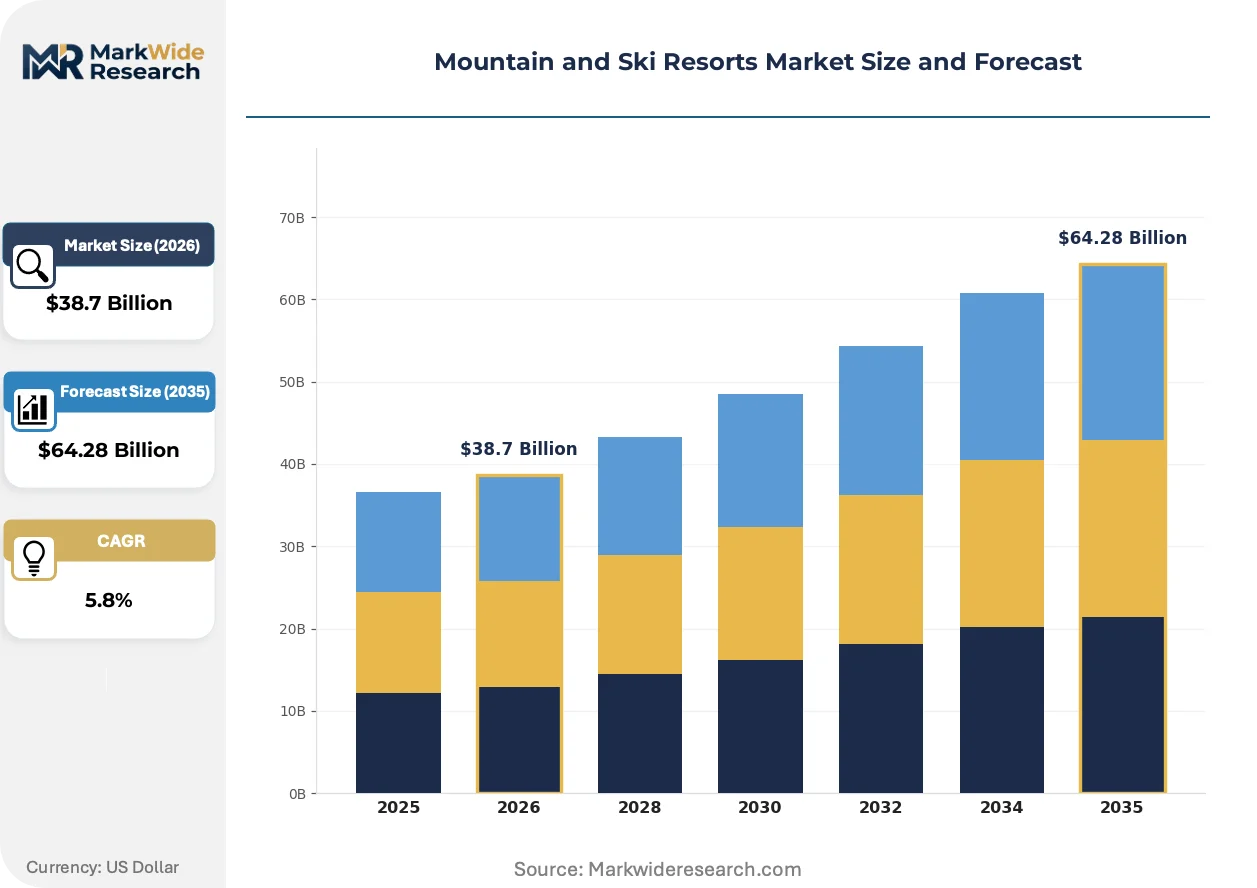
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $64.28 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Lift Services, Ski Rentals, Snowboard Rentals, Ski Lessons Product Type: Accommodations, Dining, Retail, Equipment Sales End User: Families, Adventure Seekers, Couples, Beginners Season: Winter, Summer, Off-Season, Holiday |
| Companies Covered | Powdr Corp., Mountain Capital Partners, Vail Resorts Inc., Midwest Family Ski Resorts, Pacific Group Resorts Inc., Alterra Mountain Company, Aspen Skiing Company, Mont Saint-Sauveur International Inc., Boyne USA Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mountain and Ski Resorts Market Shifts & Advancements
Digitalization of terrain access and automated snowmaking are reshaping operational cost structures, while regulatory pressure on refrigerants and energy use accelerates equipment replacement cycles across mountain properties.
Automated snowmaking systems with real-time weather integration and remote gun control are fragmenting traditional operational models. Mid-sized resorts in Austria and Switzerland are deploying these systems fastest, reducing manual labor dependency during marginal temperature windows. The technology is fragmenting capital deployment patterns as properties prioritize sensor networks over incremental lift capacity.
EU F-Gas Regulation phase-out schedules are compressing snowmaking equipment replacement timelines. Hydrofluorocarbon-based refrigeration systems face mandatory decommissioning, forcing capital draws toward CO2 and ammonia alternatives. Nordic and Alpine properties are responding fastest, with Norwegian and Swedish resorts already completing majority fleet transitions.
Destination travelers are consolidating booking decisions around integrated lodging-terrain packages rather than lift-ticket-first planning. Online travel aggregators and resort-direct platforms are displacing traditional travel agent channels for international visitors. This pattern is most pronounced among Australian and British skiers targeting French and Austrian Alpine corridors.
Mountain and Ski Resorts Market Segmentation
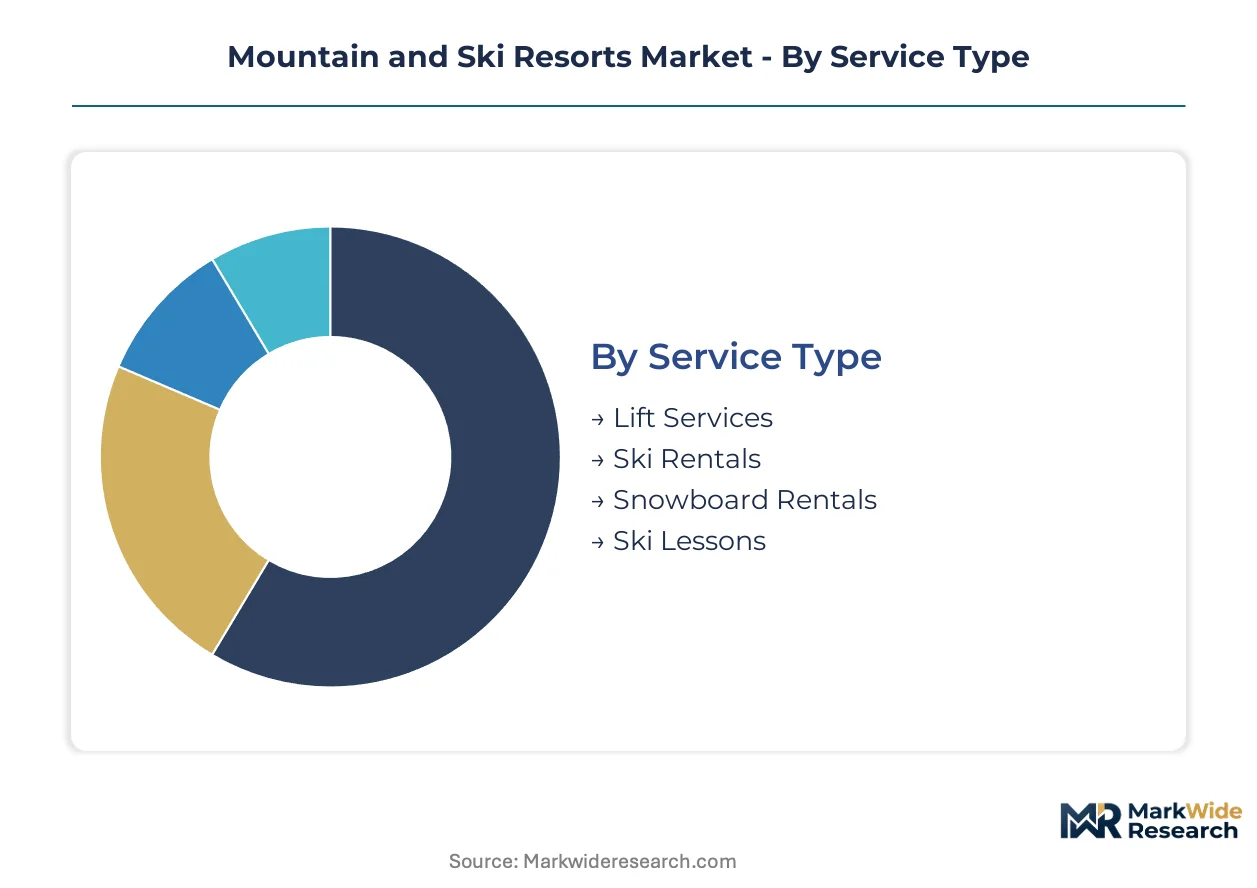
Segmentation reveals where capital efficiency diverges across mountain resort operations. Lift infrastructure and accommodation yield curves differ materially from rental and lesson businesses. Understanding these margin architectures directs capex allocation between snow reliability systems and hospitality upgrades.
Service Type:
Lift Services commands the dominant margin pool within this category, with automated cable systems generating recurring revenue through fixed-capacity hourly throughput.
- Lift Services:Cable transport infrastructure with 2,000-6,000 passenger-per-hour capacity ratings. French Alpine corridor properties concentrate demand here, where Savoie and Haute-Savoie departments sustain extended-stay visitation requiring repeated daily lift access. EU Green Deal infrastructure financing is accelerating low-carbon transport upgrades at these high-traffic installations.
- Ski Rentals:Equipment provisioning services with inventory turnover tied to visitor volume and lesson package attachment. Austrian and Swiss mid-sized resorts are rotating fastest toward automated fitting systems, reducing labor dependency during peak arrival windows. Sensor-enabled boot and ski matching is fragmenting traditional rental counter operations.
- Snowboard Rentals:Specialized equipment lines with shorter average rental duration and higher damage rates. Health Canada guidelines influence alpine workplace safety protocols for binding adjustment and terrain park equipment.
- Ski Lessons:Instruction services with instructor-to-guest ratios constrained by certification requirements and terrain capacity. Demand concentrates at destination properties where multi-day packages extend guest spend per visit.
Lift Services holds installed capacity. Ski Lessons is rotating up the share rankings.
Product Type:
Cost tier stratification runs deepest in this category, with Accommodations separating premium destination lodges from limited-service slope-side inventory.
- Accommodations:Lodging inventory spanning full-service destination resorts to limited-service slope-side properties. Vail Resorts Inc. leverages its multi-pass network to sustain year-round occupancy across North American properties with integrated terrain access. Summer activity diversification into mountain biking infrastructure is capturing off-season utilization at underutilized lift-adjacent lodging.
- Dining:Food and beverage operations with per-capita spend varying by visit duration and accommodation tier. French Alpine corridor properties concentrate premium dining demand among international visitors seeking extended-stay experiences.
- Retail:Apparel and accessory sales with margin profiles tied to brand exclusivity and impulse purchase patterns. Aspen Skiing Company differentiates via on-mountain conservation programming that drives branded merchandise attachment.
- Equipment Sales:Hard goods retail with inventory risk concentrated in seasonal demand windows and technology cycle obsolescence. Nordic properties are completing majority fleet transitions fastest under EU F-Gas Regulation phase-out schedules.
Accommodations anchors revenue concentration. Equipment Sales is expanding most quickly as climate volatility accelerates gear replacement cycles.
End User:
Volume distribution across this category tracks directly with pricing power, where Adventure Seekers accept premium positioning for specialized experiences.
- Families:Multi-generational visitor units with stable demand patterns and package-oriented booking behavior. Australian and British skiers targeting French Alpine corridors show pronounced consolidation around integrated lodging-terrain packages. This segment generates predictable midweek occupancy during school holiday windows.
- Adventure Seekers:Experience-focused visitors commanding premium pricing for heli-skiing and guided backcountry access. Alterra Mountain Company anchors its portfolio through destination resorts with terrain diversity that captures this high-yield demand. Heli-skiing operators are expanding premium booking volumes across alpine destination properties.
- Couples:Dual-adult visitor units with higher per-capita dining and spa attachment than family segments. Demand concentrates at properties with integrated wellness programming and premium accommodation tiers.
- Beginners:First-time visitors with high lesson attachment and rental dependency, converting to equipment purchase at variable rates. Lesson package design and terrain progression infrastructure determine retention into repeat visitation.
Families holds installed capacity. Adventure Seekers is climbing the fastest as experience premiumization accelerates.
Season:
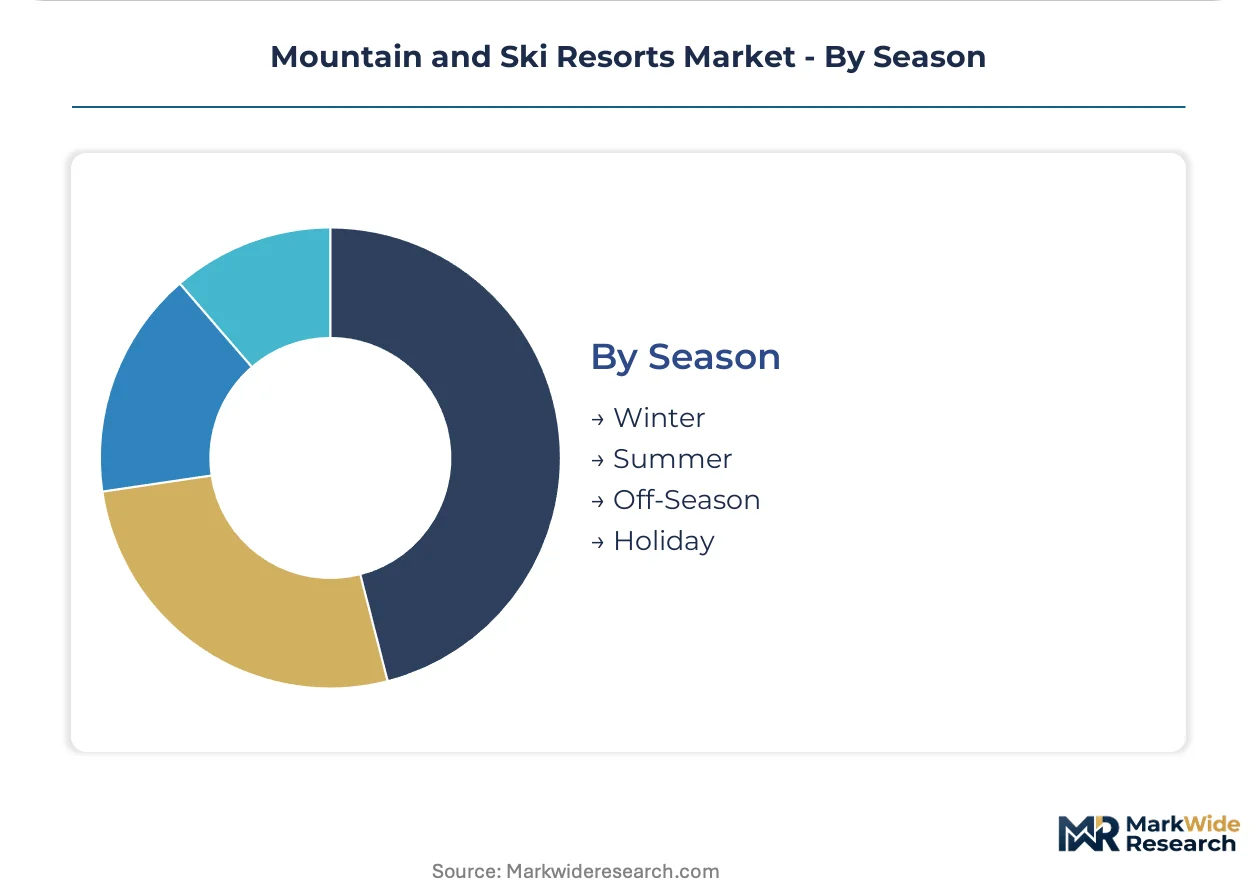
Customer type rotation across this category determines fixed-cost coverage, with Winter carrying infrastructure depreciation and Summer capturing incremental return on lift assets.
- Winter:Core operating period with snowmaking energy inputs and lift maintenance cycles concentrated in these months. EPA stormwater discharge permits constrain expansion near sensitive watersheds in US mountain regions during peak construction windows.
- Summer:Off-peak diversification period with mountain biking infrastructure and alpine coaster installations capturing underutilized lift asset returns. Mid-sized resorts in Austria and Switzerland are deploying automated summer operations fastest.
- Off-Season:Shoulder periods with minimal programmed activity and maintenance-focused staffing. Properties with conference and event infrastructure capture corporate retreat demand during these windows.
- Holiday:Compressed high-demand windows with pricing power maximization and capacity constraints. ISO 14001 certification concentration creates competitive access barriers for smaller operators during these peak revenue periods.
Winter holds installed capacity. Summer is gaining share fastest as climate variability intensifies operational planning complexity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal infrastructure financing is redirecting capital toward low-carbon lift retrofits across Alpine properties. French and Austrian departments concentrate destination demand through integrated lodging-terrain packages. EPA stormwater constraints and Health Canada alpine safety protocols shape operational parameters in North American mountain regions.
France
International visitor flows from Australia and Britain sustain extended-stay demand across Savoie and Haute-Savoie. The EU F-Gas Regulation accelerates snowmaking equipment replacement timelines at properties throughout the Alpine corridor. Chamonix and Val d'Isère anchor premium destination positioning through terrain diversity and integrated hospitality infrastructure.
Austria
Mid-sized resorts deploy automated snowmaking systems fastest, reducing labor dependency during marginal temperature windows. EU Green Deal sustainability-linked capital pools support renewable energy retrofits across Tyrol and Salzburg provinces. Kitzbühel and Lech-Zürs exemplify the shift toward sensor-network prioritization over incremental lift capacity expansion.
United States
Multi-pass network convergence consolidates fragmented regional demand across dispersed mountain properties. EPA stormwater discharge permits constrain terrain expansion near sensitive watersheds in Colorado and Utah. Vail Resorts anchors year-round visitation through integrated lodging assets across its North American portfolio.
Switzerland
ISO 14001 certification concentration creates competitive access barriers for smaller operators during peak revenue windows. The EU F-Gas Regulation drives fleet transitions toward CO2 and ammonia refrigeration alternatives ahead of mandatory decommissioning schedules. Zermatt and St. Moritz maintain premium positioning through aggressive renewable energy commitments and conservation programming.
Canada
Heli-skiing operators expand premium booking volumes across British Columbia alpine destinations. Health Canada guidelines for alpine workplace safety mandate specialized training protocols and equipment standards at high-elevation operations. Whistler and Banff anchor destination demand through backcountry access infrastructure and guided experience packages.
Mountain and Ski Resorts Market Competitive Landscape
Player mix skews toward integrated destination resort operators with multi-property networks and specialized regional hospitality groups. Consolidation pressure concentrates around pass-network convergence and summer diversification capabilities. Three archetypes dominate: scale-driven portfolio operators with year-round revenue streams, terrain-differentiated destination specialists, and regional hospitality-integrated properties. Competitive moves center on multi-pass platform expansion and automated infrastructure deployment.
Among North American portfolio operators, Vail Resorts Inc., Alterra Mountain Company, and Aspen Skiing Company occupy distinct positioning vectors. Vail Resorts exemplifies the scale-driven network archetype through its multi-pass infrastructure spanning dispersed geographic assets. Alterra Mountain Company anchors the destination-specialist tier through integrated lodging and terrain diversity concentration. Aspen Skiing Company represents the sustainability-differentiated position through renewable energy commitments and conservation programming integration. Regional specialists including Powdr Corp., Mountain Capital Partners, and Boyne USA Inc. sit within the hospitality-integrated tier, leveraging localized market knowledge and community anchoring against network-scale competitors.
| Leading Market Players |
|---|
| Powdr Corp. |
| Mountain Capital Partners |
| Vail Resorts Inc. |
| Midwest Family Ski Resorts |
| Pacific Group Resorts Inc. |
| Alterra Mountain Company |
| Aspen Skiing Company |
| Mont Saint-Sauveur International Inc. |
| Boyne USA Inc. |
| Others |
Supply & Pricing Matrix
Take-or-pay lift-access contracts lock in multi-season revenue visibility for destination resort operators while insulating against energy input volatility. These structures bind families and international visitors to prepaid terrain packages across French Alpine corridor properties, embedding price certainty into capital planning for snow reliability infrastructure.
Pricing Analysis
Certification level creates the primary spread between ISO 14001-compliant destination resorts and limited-service slope-side properties. Three-tier pricing structure across premium, standard, and economy levels segments visitors by accommodation integration and lesson package attachment. Cost compression in mid-tier inventory intensifies as automated snowmaking systems reduce labor differentiation. Adventure Seekers show least price sensitivity for heli-skiing and backcountry guiding, while Beginners concentrate price elasticity around rental and lesson bundles.
Supply Chain Analysis
France and Austria anchor lift infrastructure manufacturing and automated snowmaking system assembly. Supply draws from specialized steel cable production in Germany and sensor network components from Switzerland. Single-source vulnerability concentrates in high-capacity cable transport systems where EU Green Deal compliance timelines compress replacement windows. Distribution runs through resort-direct procurement channels and integrated hospitality-terrain package aggregators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Multi-pass network convergence is shifting this market toward platform-economics dynamics where interoperability between dispersed properties determines visitor capture. Ecosystem integration now governs pricing power more than standalone terrain quality.
For Market Incumbents: Consolidate pass-network scale through summer activity diversification into mountain biking infrastructure and alpine coaster installations. Defensive positioning requires backward integration into lodging assets to capture extended-stay spend. The threat of climate volatility demands accelerated reservoir and pump station deployment to defend snow reliability margins against marginal temperature windows. For New Entrants and Emerging Players: ISO 14001 fast-track certification unlocks competitive access to EU Green Deal infrastructure financing pools. White-space concentrates in mid-sized Austrian and Swiss resorts where automated operations reduce incumbent labor advantages. A terrain-differentiated positioning through guided backcountry access captures premium Adventure Seeker demand outside established destination corridors. For Investors and Strategic Acquirers: Capital is best deployed toward hospitality-integrated regional specialists with untapped summer utilization and community anchoring. Long-term viability hinges on properties with dual-season revenue coverage and renewable energy retrofit completion. The signal to watch is automated snowmaking penetration rates as inflection indicator for operational cost structure divergence.| Strategic Initiative | Industry Significance |
|---|---|
| Summer Activity Diversification | Mountain biking infrastructure captures off-season returns at underutilized French Alpine lift assets. |
| EU Green Deal Infrastructure Financing | Sustainability-linked capital pools accelerate low-carbon transport upgrades across Savoie properties. |
| Automated Snowmaking Deployment | Sensor networks reduce labor dependency during marginal temperature windows at Austrian mid-sized resorts. |
| Multi-Pass Network Integration | Platform convergence consolidates fragmented regional demand across dispersed North American mountain properties. |
| Heli-Skiing Capacity Expansion | Premium backcountry access captures high-yield Adventure Seeker bookings at British Columbia destinations. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with resort operations directors, lift infrastructure procurement managers, alpine hospitality executives, and backcountry guiding specialists. Secondary validation drew from EU F-Gas Regulation filings, EPA stormwater permit databases, Health Canada alpine safety guidelines, and customs data on snowmaking equipment imports. Bottom-up property-level capacity assessments and top-down regional visitation estimates were triangulated to anchor projections.
Across the analysis window, forecasts model service type segmentation by lift capacity tier, accommodation integration level, and end-user visitor archetype. CAGRs were derived from slope of fitted trend lines across historical visitation and capital expenditure patterns. Climate volatility indices and EU Green Deal compliance timelines fed directly into snow reliability infrastructure investment assumptions.
Decision-makers should treat outputs as directional under sustained international destination travel and regulatory compliance trajectories; material deviation would warrant model refresh. Forecasts embed assumptions around energy input cost stabilization and automated technology adoption curves. Recalibration cycles align with material shifts in EU F-Gas phase-out schedules and multi-pass network membership penetration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hotels and Resorts
Hotel Furniture and Furnishing Market
Hotels and Resorts
Global Floating Hotels Market
Hotels and Resorts
Spa Resorts Market
Hotels and Resorts
Hotels, Resorts, and Cruise Lines Market
Hotels and Resorts
Philippines Tourism and Hotel Market
Hotels and Resorts
Morocco Hospitality Market
Hotels and Resorts
United States Luxury Hotel Market
Hotels and Resorts
Boutique Hotels Market
Hotels and Resorts
Asia-Pacific Luxury Hotel Market
Hotels and Resorts
Global Beach Hotels Market
Hotels and Resorts
Five Star Hotel Market
Hotels and Resorts
Morocco Tourism and Hotel Market
Hotels and Resorts
Germany HRI Market
Hotels and Resorts
North America Luxury Hotel Market
Hotels and Resorts
India Luxury Hotel Market
Hotels and Resorts
Europe Luxury Hotel Market