
 Boutique Hotels Market | 2026-2036
Boutique Hotels Market Size, Share, and Industry Trends Forecast 2026-2036
Boutique Hotels Market Analysis
Specialized hospitality design talent is redrawing competitive boundaries in boutique lodging as architects and interior curators with adaptive reuse expertise become scarce. Marriott International leverages its Autograph Collection platform to sustain property-level autonomy while maintaining loyalty network benefits. Hilton Worldwide anchors its Tapestry Collection in urban cultural districts where independent competitors struggle with distribution costs. Kimpton Hotels & Restaurants differentiates through food-and-beverage programming that occupies a distinct position between full-service dining and incidental hotel restaurants.
Boutique hotels are independently styled lodging properties typically comprising 10 to 100 rooms, distinguished by personalized service, localized design narratives, and operational integration with surrounding cultural or commercial ecosystems rather than standardized brand formulas. The lifestyle segment within hotel type classification leads development pipelines as developers prioritize properties with authentic neighborhood narratives over heritage conversions with higher restoration complexity. Business travelers within target customer segmentation represent the fastest-growing booking segment as corporate travel policies relax restrictions on non-chain properties with reliable connectivity and meeting infrastructure.
FDA oversight of spa and wellness amenities intersects with state-level hospitality health codes to shape operational compliance costs, while OSHA workplace safety standards govern boutique properties' staffing models where lean teams handle multiple functional roles. The EU Green Deal's building performance standards are forcing renovation timelines for older boutique inventory across European markets. Stakeholders must monitor how direct booking channel investments reshape intermediary dependency as online travel agency commission structures evolve.
Market Dynamics
The boutique hotel sector faces a structural compression between experiential authenticity demands and the capital efficiency required by institutional investors backing portfolio expansion. EU Green Deal building performance mandates are accelerating renovation cycles for older inventory, while adaptive reuse expertise scarcity constrains pipeline velocity.
Growth Catalysts
- Experiential hospitality adoption:Leisure travelers prioritize localized design narratives and neighborhood integration over standardized amenities, pulling development toward lifestyle-oriented properties with authentic cultural programming.
- Corporate travel policy relaxation:Business travelers now represent the fastest-growing booking segment as firms permit non-chain properties with verified connectivity infrastructure and meeting facilities.
- EU Green Deal efficiency mandates:Building performance standards are forcing renovation timelines that upgrade energy systems in older European boutique inventory, creating compliant supply for ESG-focused institutional capital.
Market Restraints
- Adaptive reuse talent scarcity:Architects and interior curators with heritage conversion expertise command premium compensation, inflating pre-opening costs for properties in historic districts.
- Online travel agency commission structures:Platform dependency extracts 15-25% of revenue per booking, compressing net operating income for independent operators lacking direct booking scale.
- Regulatory fragmentation:FDA spa oversight intersects with state-level hospitality health codes, creating multi-layer compliance costs for wellness-programmed properties.
Strategic Opportunities
- Portugal's Lisbon-Porto corridor:Demand concentration in this cluster offers first-mover positioning for experiential properties targeting cultural tourism and remote-work extended stays.
- Food-and-beverage programming differentiation:Properties occupying the space between full-service dining and incidental hotel restaurants capture local patronage beyond guest rooms.
- Direct booking channel investment:Loyalty network benefits from soft-brand collections enable reduced intermediary dependency while preserving operational autonomy.
Industry Challenges
- Lean-team staffing models:OSHA workplace safety standards govern boutique properties where multi-functional roles increase training complexity and compliance exposure.
- Distribution cost management:Independent competitors struggle to match the marketing scale of soft-brand collections anchored in urban cultural districts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Boutique Hotels Market |
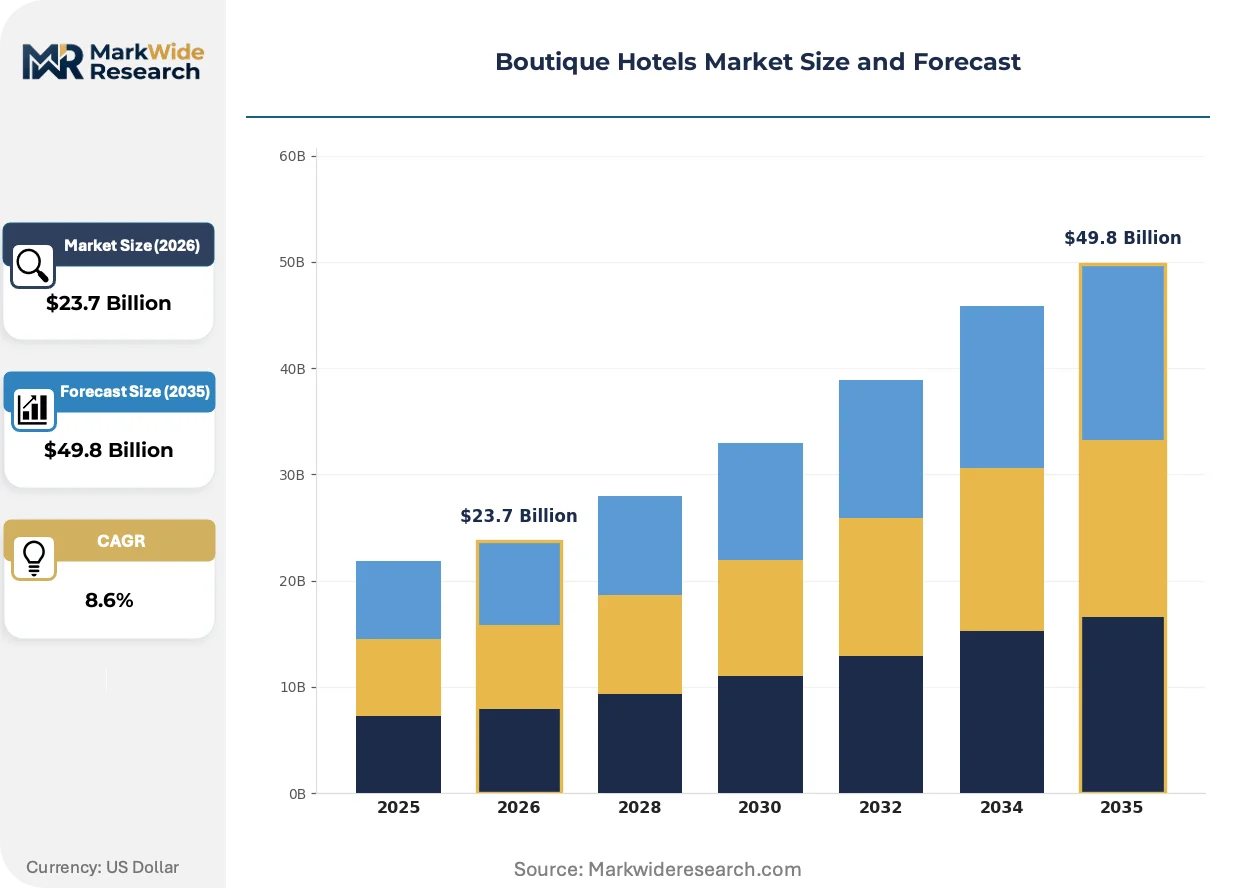
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $49.8 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Hotel Type: Lifestyle, Boutique, Luxury, Heritage Target Customer: Leisure Travelers, Business Travelers, Couples, Families Amenities Offered: Spas, Rooftop Bars, Concierge Services, Swimming Pools Booking Channel: Direct, Online Travel Agencies, Travel Agents, Corporate Bookings |
| Companies Covered | Hyatt Hotels Corporation, Wyndham Hotels & Resorts, Marriott International, Autograph Collection Hotels, Design Hotels, Hilton Worldwide, IHG Hotels and Resorts, Kimpton Hotels & Restaurants, Accor, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Boutique Hotels Market Emerging Trajectories
Property-level technology and regulatory compliance frameworks are actively restructuring how boutique hotels design guest experiences and manage operational infrastructure. Three forces dominate current investment priorities.
Modular guest room technology is decomposing the traditional fixed-amenity model. Smart room systems now enable on-demand service activation rather than permanent fixture installation. Urban cultural district properties are adopting these systems fastest, compressing capital deployment timelines while preserving design flexibility for frequent refreshes.
EU Green Deal building performance standards are mandating energy efficiency upgrades across European boutique inventory. Properties face accelerated renovation cycles to meet carbon intensity thresholds. Portugal's heritage building stock encounters particular friction as thermal envelope improvements conflict with preservation requirements, forcing creative engineering solutions.
Extended-stay booking patterns are disrupting traditional length-of-stay assumptions. Remote-work-enabled travelers now occupy boutique properties for 7-14 day durations, replacing the legacy weekend-leisure or conference-transient model. Lisbon's central district properties report the highest incidence of this behavior, requiring recalibrated housekeeping and F&B service structures.
Boutique Hotels Market Segmentation
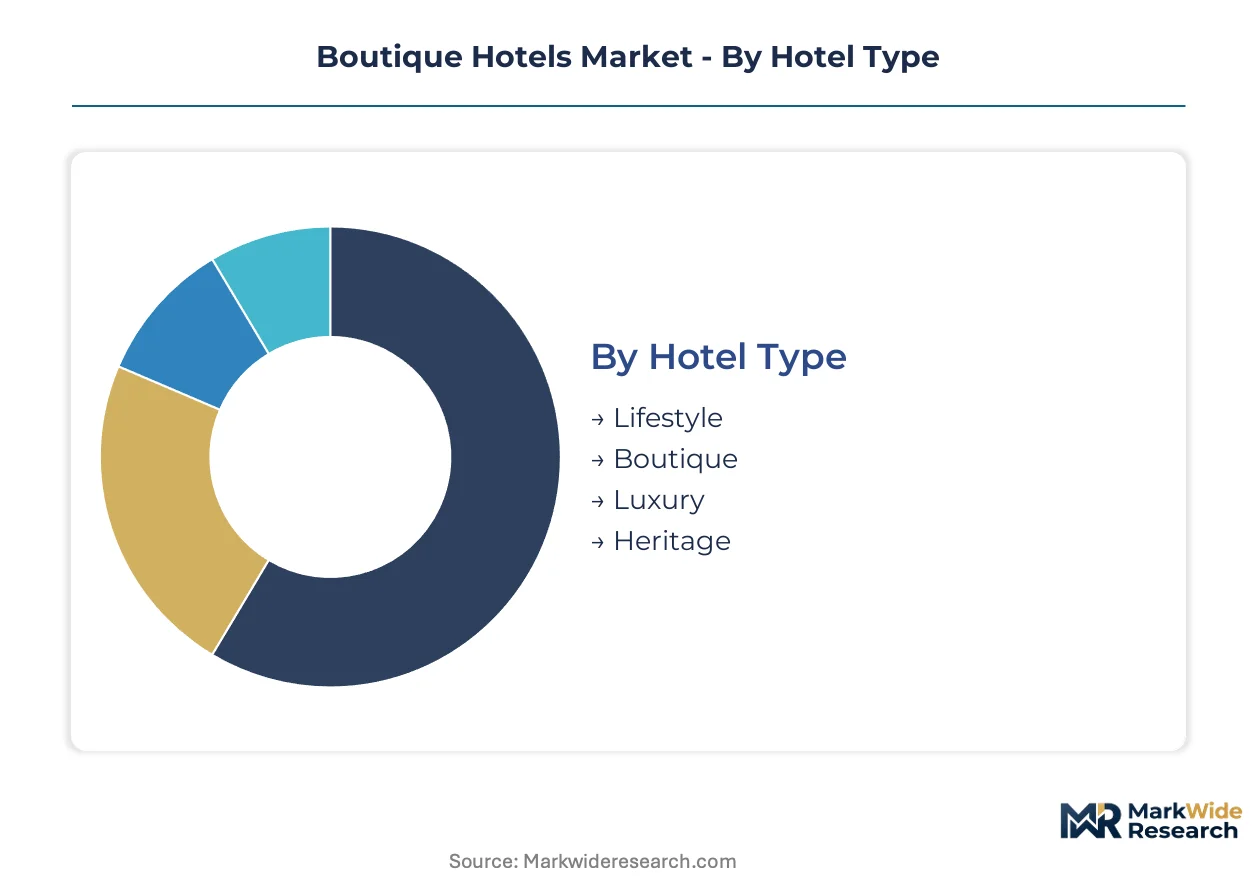
Boutique hotel operators configure property portfolios across four distinct dimensions to capture differentiated demand pools. Each segmentation axis carries unique margin profiles and capital requirements that shape investment decisions.
Hotel Type:
Lifestyle properties concentrate in urban cultural districts across Portugal, France, and Italy where neighborhood authenticity commands premium positioning. Heritage conversions cluster in historic European centers subject to EU Green Deal renovation mandates.
- Lifestyle:Properties emphasize localized design narratives and operational integration with surrounding commercial ecosystems rather than standardized brand formulas. Lisbon's central district hosts the densest concentration of new lifestyle openings, driven by remote-work extended-stay demand and cultural tourism positioning.
- Boutique:Independently styled lodging typically comprising 10 to 100 rooms distinguished by personalized service. Porto has emerged as a key development corridor where adaptive reuse projects convert nineteenth-century merchant houses into intimate properties with neighborhood-specific programming.
- Luxury:Ultra-premium positioning with elevated service ratios and bespoke amenity configurations.
- Heritage:Historic building conversions requiring specialized architectural expertise and preservation compliance.
Lifestyle holds the largest share; momentum sits with Heritage as EU efficiency mandates accelerate renovation pipelines.
Target Customer:
Corporate travel policy relaxation has reordered customer mix priorities, while leisure segments retain higher per-stay ancillary spend.
- Leisure Travelers:Experience-seeking guests prioritizing localized programming and neighborhood immersion over standardized amenities. Portugal's Alentejo and Douro Valley regions attract this segment for wine tourism and rural experiential positioning.
- Business Travelers:Corporate guests now represent the fastest-expanding booking segment as firms permit non-chain properties with verified connectivity infrastructure. Properties in Lisbon's Parque das Nações district specifically target this cohort with dedicated meeting facilities and reliable broadband.
- Couples:Romantic getaway segment seeking intimate scale and design-forward environments.
- Families:Multi-generational travelers requiring flexible room configurations and child-appropriate programming.
Leisure Travelers hold the largest share; momentum sits with Business Travelers.
Amenities Offered:
Food-and-beverage programming now functions as a primary revenue center rather than incidental guest service, with regulatory compliance costs varying by amenity type.
- Spas:Wellness facilities subject to FDA oversight intersecting with state-level hospitality health codes in US markets, and national health ministry regulations across European jurisdictions. Properties in Germany's Baden-Württemberg region leverage existing thermal spring infrastructure to offset compliance burdens.
- Rooftop Bars:Elevated F&B venues capturing local patronage beyond registered guests, with liquor licensing and fire safety codes creating operational complexity. Barcelona's Eixample district properties report highest ancillary revenue contribution from this amenity type.
- Concierge Services:Personalized local access and experience coordination.
- Swimming Pools:Capital-intensive amenities with seasonal utilization challenges in temperate climates.
Rooftop Bars hold the largest share; momentum sits with Spas as wellness programming deepens rate premiums.
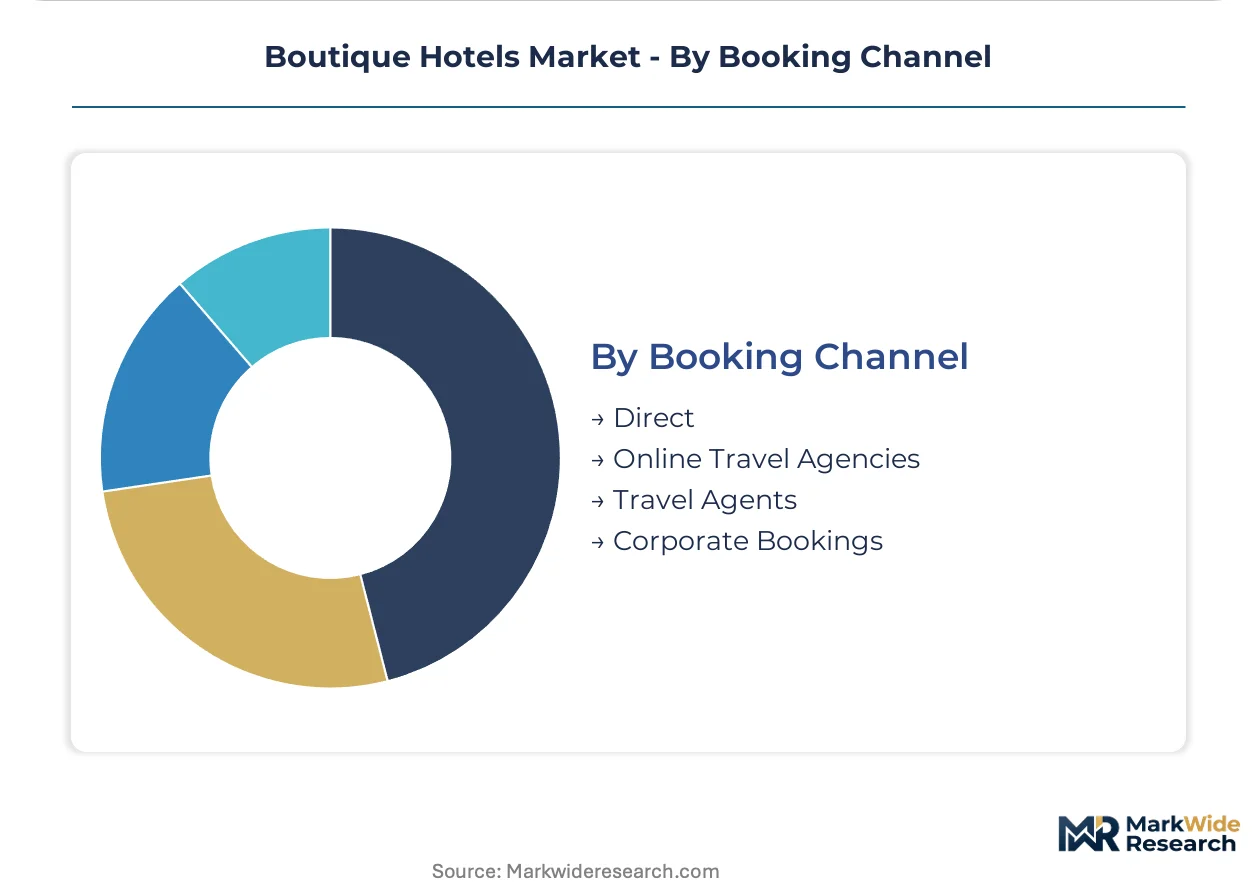
Booking Channel:
Channel mix directly determines net operating income through commission extraction versus direct acquisition costs.
- Direct:Proprietary website and loyalty program bookings eliminating intermediary commissions. Soft-brand collections like Marriott's Autograph Collection enable this channel through inherited loyalty network benefits while preserving operational autonomy.
- Online Travel Agencies:Platform-dependent distribution extracting 15-25% revenue per booking, compressing margins for independent operators lacking scale. Parisian boutique properties report highest OTA dependency due to international visitor concentration.
- Travel Agents:Traditional intermediary channel retaining relevance for complex multi-city itineraries.
- Corporate Bookings:Negotiated rate structures with enterprise clients requiring consistent connectivity and meeting infrastructure verification.
Online Travel Agencies hold the largest share; momentum sits with Direct as property-level technology investments reduce intermediary dependency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Portugal's boutique hotel segment serves extended-stay remote workers and cultural tourists, while Germany's market centers on wellness-programmed heritage conversions. France emphasizes gastronomy-anchored properties, Spain targets urban rooftop-bar social venues, and Italy concentrates on rural wine-tourism estates.
Portugal
Lisbon's central district properties report the highest incidence of 7-14 day remote-work stays, replacing legacy weekend-leisure patterns. The country's national tourism board administers heritage preservation incentives that offset EU Green Deal thermal envelope compliance costs. Porto's nineteenth-century merchant house conversions concentrate adaptive reuse expertise in the Lisbon-Porto corridor.
Germany
Baden-Württemberg properties leverage existing thermal spring infrastructure to offset spa regulatory compliance burdens from the EU Green Deal. The country's federal building energy efficiency regulations accelerate renovation timelines for older boutique inventory. Berlin's Mitte district hosts dense clusters of lifestyle properties targeting business travelers with verified connectivity infrastructure.
France
Parisian boutique properties report the highest online travel agency dependency due to international visitor concentration, compressing net operating income. The country's national hospitality health codes intersect with EU-level building performance standards for wellness-programmed properties. Lyon and Bordeaux have emerged as secondary development corridors where food-and-beverage programming captures local patronage beyond registered guests.
Spain
Barcelona's Eixample district properties report highest ancillary revenue contribution from rooftop bar amenities, with liquor licensing and fire safety codes creating operational complexity. The country's regional heritage preservation authorities negotiate thermal efficiency upgrades with EU Green Deal carbon intensity thresholds. Madrid's Salamanca district concentrates soft-brand collection properties anchored in urban cultural districts.
Italy
Tuscany's rural estates and Piedmont's wine regions attract leisure travelers prioritizing localized programming over standardized amenities. The country's superintendence for architectural heritage governs adaptive reuse projects where thermal envelope improvements conflict with preservation requirements. Milan's Brera district exemplifies the lifestyle segment's emphasis on neighborhood-specific programming and commercial ecosystem integration.
Boutique Hotels Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in boutique hospitality, with soft-brand collections and independent curators occupying distinct competitive positions. Marriott International and Hilton Worldwide anchor the integrated tier through Autograph Collection and Tapestry Collection platforms that preserve property-level autonomy while distributing loyalty network benefits. Independent operators compete on design authenticity but struggle with distribution cost management against scaled marketing infrastructure. Dominant competitive moves include portfolio diversification into food-and-beverage programming and strategic partnerships with heritage preservation architects.
Among North American hospitality conglomerates, Marriott International, Hilton Worldwide, and Hyatt Hotels Corporation exemplify the integrated-leader archetype through soft-brand collection structures. Kimpton Hotels & Restaurants occupies a specialist position between full-service dining and incidental hotel restaurants. European operators including Accor and Design Hotels represent the independent-curator tier competing on localized authenticity. These groupings illustrate how competitive positioning stratifies across network scale, operational autonomy, and programming differentiation.
| Leading Market Players |
|---|
| Hyatt Hotels Corporation |
| Wyndham Hotels & Resorts |
| Marriott International |
| Autograph Collection Hotels |
| Design Hotels |
| Hilton Worldwide |
| IHG Hotels and Resorts |
| Kimpton Hotels & Restaurants |
| Accor |
| Others |
Supply Flow & Price Mechanics
Adaptive reuse expertise substitution for conventional hospitality construction simultaneously redistributes supply geography toward Portugal's Lisbon-Porto corridor and compresses pre-opening cost structures for heritage conversions. EU Green Deal building performance mandates accelerate this shift by penalizing new-build energy profiles while incentivizing thermal envelope upgrades in existing inventory.
Pricing Analysis
Contract-based long-term offtake agreements with institutional investors dominate capital deployment, though independent operators rely on project-based spot pricing for renovation services. Price differentiation hinges on heritage certification tier and localized design narrative authenticity, with EU Green Deal compliance status commanding premium positioning. Cost compression in mid-market lifestyle properties is intensifying because adaptive reuse talent scarcity inflates architect fees. Corporate booking segments demonstrate lowest price sensitivity due to policy-mandated connectivity requirements, while leisure direct-booking guests exhibit highest elasticity to OTA commission passthrough.
Supply Chain Analysis
Inbound logistics costs from Mediterranean port congestion and container availability constraints on Asia-Europe trade lanes elevate lead times for modular guest room technology components. Supply concentration rests on Italy for heritage preservation materials, Germany for energy systems engineering, and Portugal for localized artisan furnishings. Raw material dependencies include thermal insulation composites, smart room IoT hardware, and reclaimed structural timber. Single-source vulnerability permeates adaptive reuse architect pools. Distribution runs through soft-brand collection procurement networks that aggregate specification standards across portfolio properties.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation creates multiple viable positioning niches as remote-work extended-stay demand splinters traditional weekend-leisure assumptions. Experiential hospitality adoption enables specialist operators to capture premium rate positioning against standardized competitors.
For Market Incumbents: Shield portfolio yield by securing exclusive adaptive reuse architect relationships before EU Green Deal renovation deadlines accelerate talent competition. Prioritize direct booking channel technology investment to reduce OTA commission extraction from 15-25% revenue share. Consolidate food-and-beverage programming capabilities in-house to capture local patronage revenue beyond registered guests.
For New Entrants and Emerging Players: Anchor in Porto's nineteenth-century merchant house conversion pipeline where heritage preservation incentives offset thermal envelope compliance costs. Target Lisbon's Parque das Nações district for business traveler positioning with verified connectivity infrastructure. Deploy modular guest room technology to compress capital deployment timelines while preserving design refresh flexibility.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors soft-brand collection platforms with inherited loyalty network benefits. Long-term viability over a 5-10 year window rests on properties achieving direct booking scale sufficient to decouple from OTA dependency. Target acquisition archetypes include lifestyle properties in the Lisbon-Porto corridor with established remote-work guest relationships. Monitor EU Green Deal renovation completion rates as inflection indicator for compliant supply availability to ESG-focused institutional capital.
| Strategic Initiative | Industry Significance |
|---|---|
| Direct Booking Channel Investment | Reduces OTA commission extraction while preserving operational autonomy for independent operators. |
| Adaptive Reuse Architect Partnership | Secures scarce heritage conversion expertise ahead of EU Green Deal renovation deadlines. |
| Food-and-Beverage Programming Expansion | Captures local patronage revenue between full-service dining and incidental hotel restaurants. |
| Modular Guest Room Technology Deployment | Compresses capital timelines while enabling frequent design refreshes in urban cultural districts. |
| Soft-Brand Collection Affiliation | Distributes loyalty network benefits without sacrificing property-level operational autonomy. |
Methodological Framework
Initial hypotheses were tested against primary input from boutique hotel development executives, heritage preservation architects, institutional hospitality investors, and corporate travel procurement managers and refined through secondary validation. Bottom-up property-level financial modeling triangulated against top-down sector expenditure estimates. Secondary sources included EU Green Deal regulatory filings, national tourism board heritage incentive documentation, hospitality OTA commission structure disclosures, and soft-brand collection performance reports.
Variance decomposition across hotel type, target customer segment, amenities configuration, and booking channel dimensions shaped analytical framework construction across the analysis window. CAGRs were derived from segment-level booking volume trajectories and average daily rate progression assumptions. Forecast inputs incorporated EU Green Deal renovation pipeline velocity and remote-work extended-stay incidence patterns reported by Lisbon central district properties.
Material uncertainties — regulatory enforcement timing for building performance standards, adaptive reuse talent availability, and OTA commission structure evolution — sit outside the modeled envelope. Forecasts reflect assumptions about sustained experiential hospitality preference and corporate travel policy relaxation. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hotels and Resorts
Cuba Tourism and Hotel Market
Hotels and Resorts
Mountain and Ski Resorts Market
Hotels and Resorts
Morocco Tourism and Hotel Market
Hotels and Resorts
Europe Luxury Hotel Market
Hotels and Resorts
Spain HRI Market
Hotels and Resorts
Five Star Hotel Market
Hotels and Resorts
India Luxury Hotel Market
Hotels and Resorts
Spa Resorts Market
Hotels and Resorts
United States Luxury Hotel Market
Hotels and Resorts
Germany HRI Market
Hotels and Resorts
Morocco Hospitality Market
Hotels and Resorts
Global Floating Hotels Market
Hotels and Resorts
Morocco Tourism Market
Hotels and Resorts
Global Beach Hotels Market
Hotels and Resorts
Hotel Armchair Market
Hotels and Resorts
North America Luxury Hotel Market