
 India Luxury Hotel Market | 2026-2036
India Luxury Hotel Market Size, Share, and Industry Trends Forecast 2026-2036
India Luxury Hotel Market Foresight
Corporate MICE travel is repositioning toward extended-stay formats with integrated workspace amenities. EIH Ltd anchors its portfolio around palace conversions and heritage restorations in Rajasthan and Kerala. The Indian Hotels Company Ltd leverages the Taj brand to dominate gateway city markets with mixed-use developments. Marriott International competes through its Ritz-Carlton and St. Regis flagships targeting ultra-high-net-worth international arrivals.
India luxury hotels constitute premium lodging properties delivering personalized service, bespoke design, and curated experiences at average daily rates exceeding three-star benchmarks by substantial multiples; these assets integrate fine dining, wellness facilities, and concierge operations as core revenue generators rather than ancillary offerings. Full-service hotels sustain the largest revenue pool through their integrated F&B and banquet infrastructure, while boutique properties capture outsized margin per room through design differentiation and lower staffing ratios. Resort hotels in Goa and Kerala lead occupancy recovery patterns, with spa facilities and golf courses functioning as decisive booking factors for leisure segments.
BIS fire safety standards and state-level excise regulations shape operational compliance costs across Maharashtra, Karnataka, and Rajasthan properties. The Ministry of Tourism's classification criteria mandate minimum room specifications and service benchmarks for five-star deluxe certification. Stakeholders must monitor evolving FSSAI hospitality norms and state municipal corporation licensing timelines as these determine property opening schedules and capital deployment cycles.
Market Dynamics
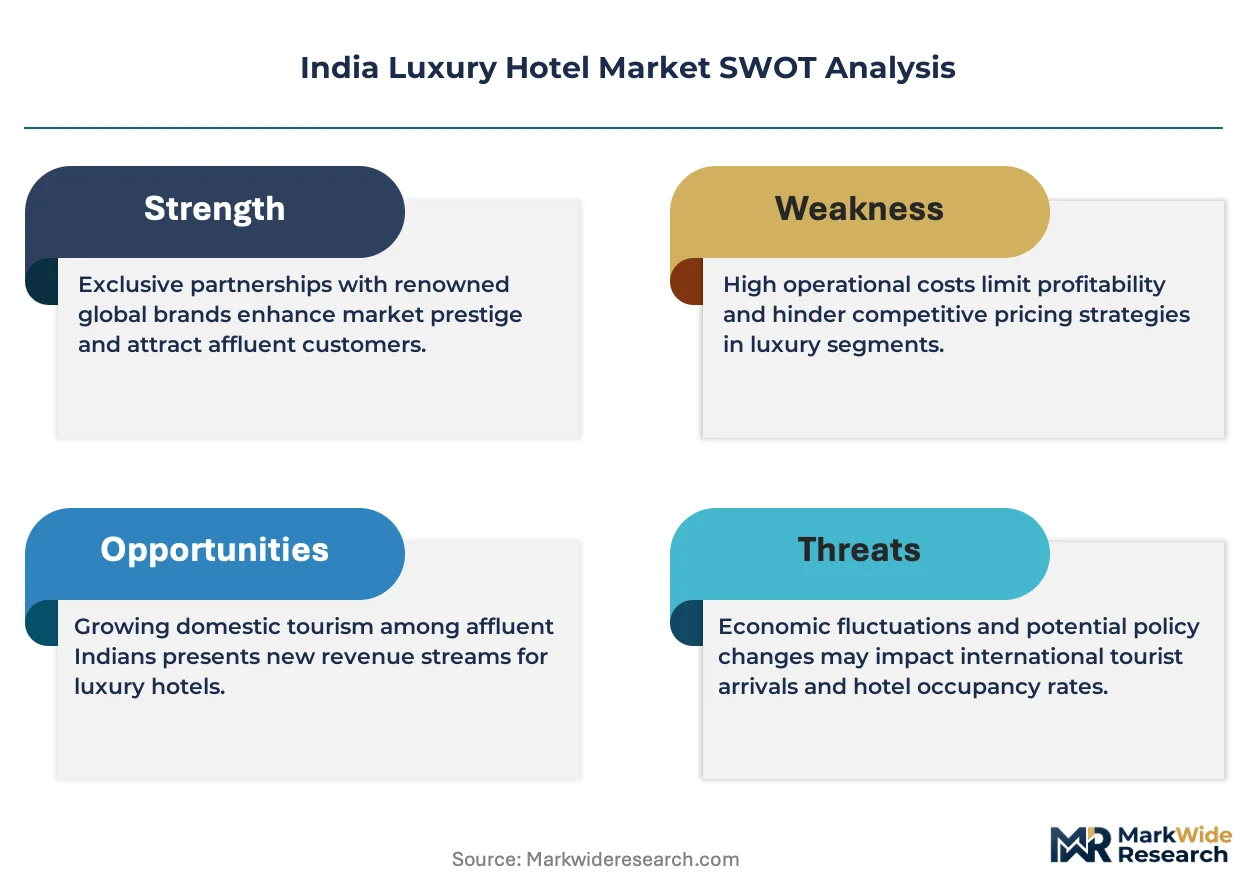
The Ministry of Tourism's Swadesh Darshan scheme is converting heritage circuits into luxury corridors, redirecting capital toward palace conversions and heritage restorations across Rajasthan and Kerala while reshaping competitive positioning around cultural authenticity rather than standardized amenities.
Growth Catalysts
- Destination wedding demand:Wedding planners are expanding their share of bookings across Rajasthan and Goa properties, creating dedicated banquet infrastructure investments.
- BIS fire safety standards:Upgraded compliance mandates are accelerating property renovations that simultaneously modernize safety systems and guest room specifications.
- Corporate long-stay suites:Mumbai's financial district and Bangalore's tech corridor now command premium rates for extended-stay formats with integrated workspace amenities.
Market Restraints
- State-level excise regulations:Maharashtra, Karnataka, and Rajasthan impose divergent licensing costs that fragment operational economics across multi-state portfolios.
- FSSAI hospitality norms:Evolving food safety mandates require recurring kitchen infrastructure upgrades that compress margin recovery timelines.
- Heritage property supply concentration:Rajasthan palace conversions face finite inventory constraints as protected monument status limits eligible assets.
Strategic Opportunities
- Kerala backwater resort expansion:Underpenetrated waterfront segments beyond Kochi offer white space for boutique wellness-focused developments.
- Integrated mixed-use developments:Gateway city land scarcity is pushing Taj and competitors toward hospitality-retail-office hybrids in Mumbai and Delhi.
- PLI scheme tourism infrastructure:Central government production-linked incentives for allied sectors are lowering capital costs for technology-integrated properties.
Industry Challenges
- Five-star deluxe certification timelines:Ministry of Tourism classification criteria mandate minimum room specifications that extend pre-opening schedules by 8-14 months.
- Specialized heritage restoration skills:Craftsmen capable of authentic palace renovation are aging out of the workforce faster than training pipelines replenish.
- Municipal corporation licensing:State-level permitting fragmentation creates unpredictable capital deployment cycles across Maharashtra, Karnataka, and Rajasthan.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Luxury Hotel Market |
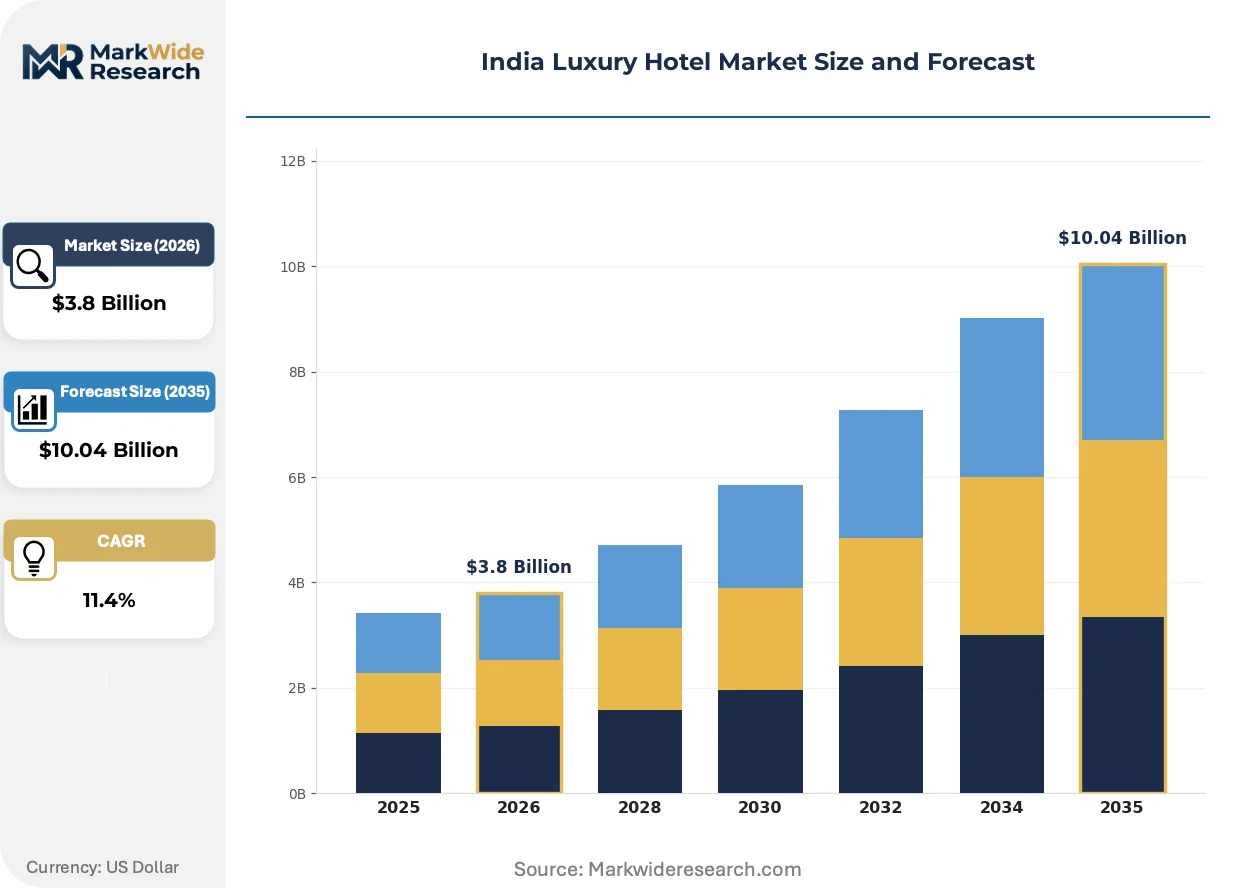
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Full-Service Hotels, Boutique Hotels, Resort Hotels, Luxury Apartments Client Type: Business Travelers, Vacationers, Event Organizers, Tourists Amenities: Spa Facilities, Fine Dining, Concierge Services, Golf Courses Room Type: Suites, Executive Rooms, Standard Rooms, Villas |
| Companies Covered | EIH Ltd (Oberoi Group), Hyatt Hotels Corp, The Indian Hotels Company Ltd (Taj), Accor S.A., Hilton Worldwide, Marriott International, The Leela Palaces Hotels & Resorts, Radisson Hotel Group, ITC Hotels, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Luxury Hotel Market Shifts & Advancements
Technology-enabled personalization is compressing the gap between standardized luxury and bespoke service delivery, while regulatory pressure on heritage preservation is forcing architectural innovation around adaptive reuse rather than greenfield construction.
Smart room automation systems integrating biometric entry, climate personalization, and in-room wellness monitoring are overtaking traditional concierge-dependent service models. Ultra-high-net-worth international arrivals at Ritz-Carlton and St. Regis flagships now expect seamless digital control interfaces. This technology compression is enabling smaller staffing ratios while maintaining service perception metrics.
FSSAI hospitality norms are tightening traceability requirements for imported ingredients and specialty F&B sourcing. Fine dining operations must now maintain digital audit trails from supplier to plate. Heritage properties in Rajasthan face particular compliance pressure as traditional Rajasthani cuisine preparations intersect with modern food safety documentation mandates.
Corporate MICE travel procurement is consolidating around extended-stay formats with guaranteed workspace amenities and residential-style floor plans. Bangalore tech corridor buyers now negotiate annual block contracts rather than transient booking patterns. This contract compression is most visible in Mumbai's Bandra-Kurla Complex and Hyderabad's HITEC City sub-markets.
India Luxury Hotel Market Segmentation
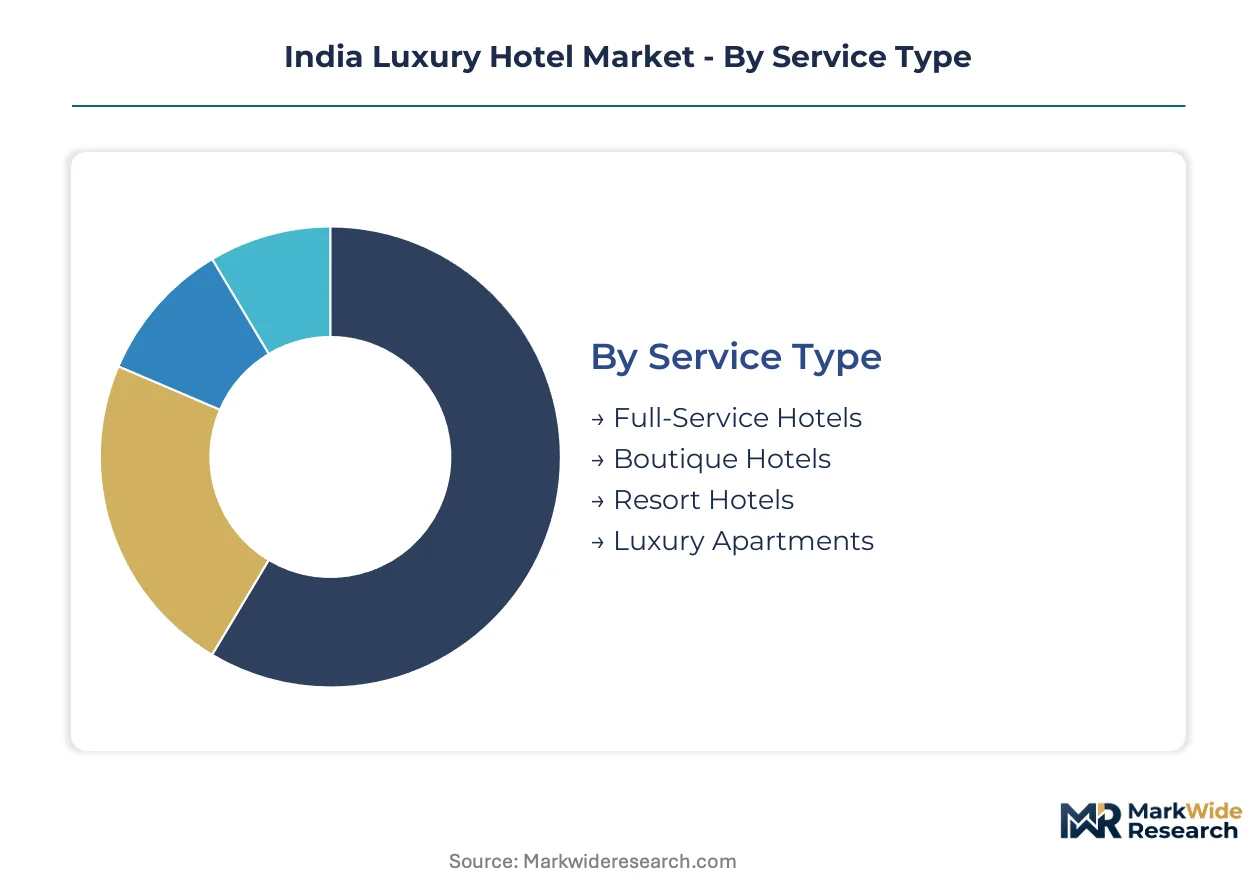
Segmentation in India's luxury hospitality sector determines capital allocation, staffing models, and regulatory compliance pathways. Each category carries distinct certification burdens from BIS fire safety standards and Ministry of Tourism classification criteria that shape property development timelines.
Service Type:
BIS fire safety standards and Ministry of Tourism five-star deluxe certification apply differentially across service formats, with full-service properties facing the most extensive pre-opening compliance audits.
- Full-Service Hotels:Integrated F&B and banquet infrastructure defines these assets, with fine dining operations generating substantial ancillary revenue beyond room sales. Demand concentrates in Mumbai's financial district and Bangalore's tech corridor, where corporate long-stay contracts command premium rates and extended booking windows.
- Boutique Hotels:Design differentiation drives margin capture through lower staffing ratios and curated experiential programming. Rajasthan palace conversions and Kerala heritage restorations anchor this segment, with EIH Ltd deploying authentic craftsmanship to maintain cultural authenticity against standardized competitors.
- Resort Hotels:Goa and Kerala properties lead occupancy recovery through spa facilities and golf courses as decisive booking factors.
- Luxury Apartments:Extended-stay formats with residential-style floor plans target corporate MICE procurement consolidation.
Leading the category by volume: Full-Service Hotels. Growing fastest: Boutique Hotels.
Client Type:
Customer mix determines revenue seasonality and cancellation risk profiles, with business travelers providing counter-cyclical stability against leisure segment volatility.
- Business Travelers:Annual block contracts in Mumbai's Bandra-Kurla Complex and Hyderabad's HITEC City replace transient booking patterns. Bangalore tech corridor buyers now negotiate guaranteed workspace amenities as standard procurement terms.
- Vacationers:Goa and Kerala resort properties depend on this segment for peak-season rate realization.
- Event Organizers:Destination wedding planners are expanding their share of bookings across Rajasthan and Goa properties, driving dedicated banquet infrastructure investments.
- Tourists:Heritage circuit traffic flows through Ministry of Tourism Swadesh Darshan scheme corridors.
Dominant revenue contributor: Business Travelers. Steepest expansion trajectory: Event Organizers.
Amenities:
FSSAI hospitality norms and state-level excise regulations fragment operational economics across amenity categories, particularly for fine dining and spa facilities.
- Spa Facilities:Wellness monitoring technology integration enables compressed staffing while maintaining service perception metrics. Kerala backwater properties leverage Ayurvedic positioning to differentiate from standardized urban spa offerings.
- Fine Dining:FSSAI traceability mandates require digital audit trails from supplier to plate, with heritage properties facing particular compliance pressure as traditional Rajasthani preparations intersect modern documentation requirements.
- Concierge Services:Smart room automation systems with biometric entry are displacing traditional concierge-dependent service models.
- Golf Courses:Decisive booking factor for leisure segments in Goa and Kerala resort markets.
Highest capital intensity: Fine Dining. Gaining share fastest: Spa Facilities.
Room Type:
Room specifications determine Ministry of Tourism classification tier and corresponding five-star deluxe certification eligibility, extending pre-opening schedules by 8-14 months for non-compliant inventory.
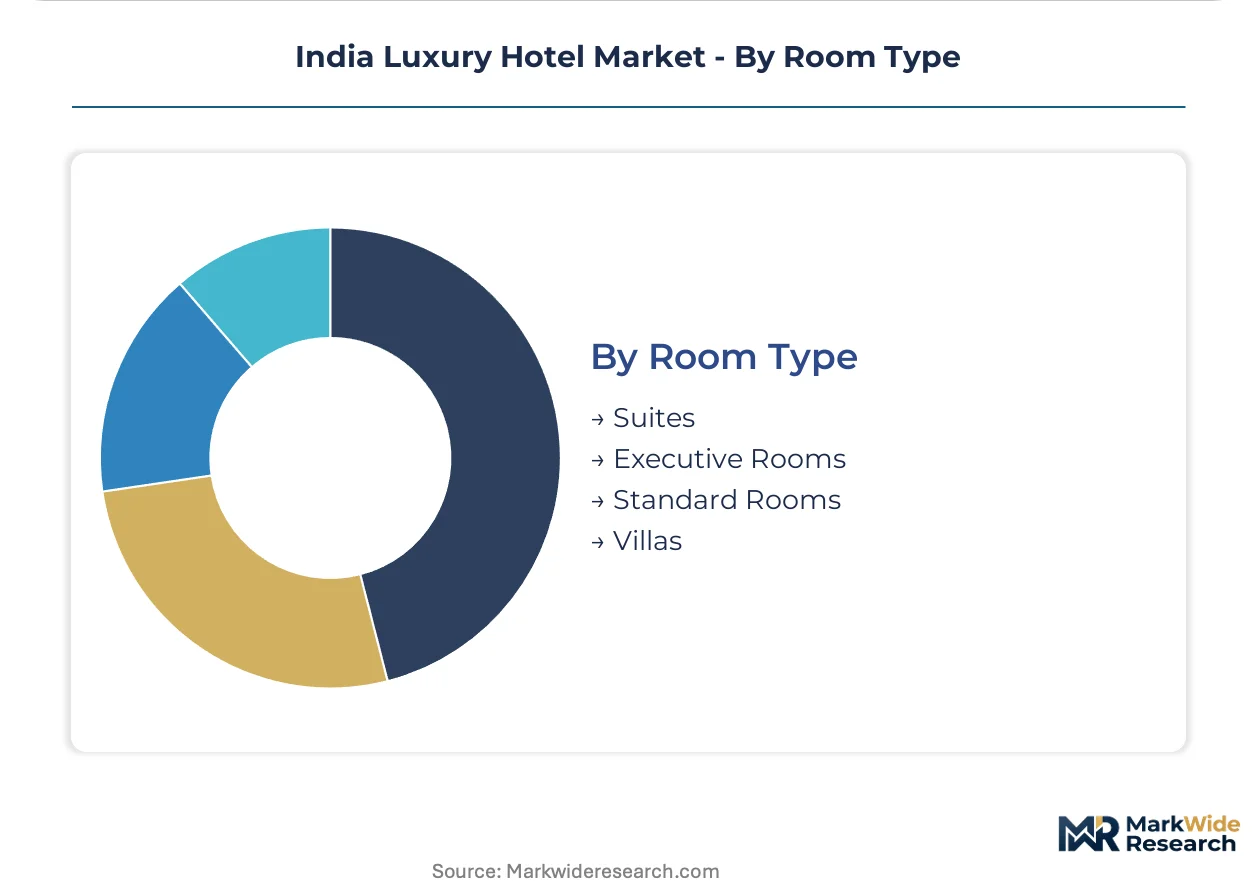
- Suites:Corporate long-stay formats with integrated workspace amenities command premium rates in Mumbai's financial district. Residential-style floor plans now dominate Bangalore tech corridor procurement negotiations.
- Executive Rooms:Mid-tier positioning within luxury properties targets extended-stay business travelers.
- Standard Rooms:Volume base for full-service properties in gateway city markets.
- Villas:Boutique wellness-focused developments in underpenetrated Kerala backwater segments beyond Kochi.
Leading the category by volume: Standard Rooms. Expanding most quickly: Suites.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's luxury hospitality production concentrates in heritage-rich states and gateway metros, while consumption spreads across business corridors and leisure destinations. The Ministry of Tourism's Swadesh Darshan scheme redirects capital toward palace conversions and heritage restorations. State-level regulatory fragmentation shapes operational economics across multi-state portfolios.
Maharashtra
Mumbai's financial district drives corporate long-stay suite demand with premium rate realization. BIS fire safety standards accelerate property renovations that modernize safety systems and guest specifications simultaneously. Bandra-Kurla Complex anchors annual block contract negotiations for extended-stay formats with integrated workspace amenities.
Karnataka
Bangalore's tech corridor commands premium rates for residential-style floor plans and guaranteed workspace amenities. State-level excise regulations impose licensing costs that fragment operational economics against neighboring jurisdictions. HITEC City sub-markets in Hyderabad compete directly for the same corporate procurement consolidation.
Rajasthan
Destination wedding planners expand booking share across palace properties, driving dedicated banquet infrastructure investments. Heritage property supply faces finite inventory constraints as protected monument status limits eligible assets. Jaipur and Udaipur clusters anchor EIH Ltd's palace conversion portfolio around authentic craftsmanship positioning.
Goa
Resort hotels lead occupancy recovery through spa facilities and golf courses as decisive leisure booking factors. FSSAI hospitality norms tighten traceability requirements for imported ingredients in fine dining operations. North Goa beachfront concentrates boutique wellness-focused developments targeting ultra-high-net-worth international arrivals.
Kerala
Backwater resort expansion offers white space for boutique wellness developments beyond Kochi's established inventory. The Ministry of Tourism's heritage circuit upgrades redirect capital toward Ayurvedic-differentiated spa positioning. Kochi and Kumarakom clusters compete for waterfront segments with lower staffing ratios than urban full-service properties.
India Luxury Hotel Market Competitive Landscape
Top-tier vendors anchor heritage palace conversions and gateway city mixed-use developments, while mid-scale operators compete through extended-stay formats and regional banquet specialization. The competitive structure stratifies across three archetypes: heritage restorers leveraging cultural authenticity, global flagships targeting ultra-high-net-worth international arrivals, and domestic conglomerates optimizing corporate procurement relationships. Dominant competitive moves include portfolio diversification into adjacent wellness and F&B verticals, plus strategic partnerships with destination wedding planners for guaranteed occupancy blocks.
Within the heritage restoration tier, EIH Ltd and The Indian Hotels Company Ltd represent contrasting approaches to cultural authenticity—EIH through Rajasthan palace craftsmanship, Taj through gateway city land scarcity responses. Marriott International occupies a position exemplifying global flagship competition through Ritz-Carlton and St. Regis positioning. These three anchors illustrate how competitive strategy diverges between domestic cultural depth and international scale economics.
| Leading Market Players |
|---|
| EIH Ltd (Oberoi Group) |
| Hyatt Hotels Corp |
| The Indian Hotels Company Ltd (Taj) |
| Accor S.A. |
| Hilton Worldwide |
| Marriott International |
| The Leela Palaces Hotels & Resorts |
| Radisson Hotel Group |
| ITC Hotels |
| Others |
Supply & Pricing Matrix
Five-star deluxe certification tiers bifurcate the India luxury hotel market into heritage-authenticated palace properties and standardized gateway city assets, with this divergence manifesting in both rate premiums and supply chain configurations. Rajasthan palace conversions command substantial booking premiums through finite inventory scarcity, while Mumbai and Bangalore corporate long-stay formats compete on workspace amenity density rather than cultural differentiation.
Pricing Analysis
Short lead-time premiums dominate wedding planner procurement, with Rajasthan palace properties extracting rate surges for bookings secured under 90-day windows while spot inventory in Goa resort markets trades at discounts. Three-tier pricing structure across heritage-authenticated, business-optimized, and leisure-standard levels segments buyer archetypes. Cost compression in gateway city corporate segments is intensifying because annual block contract negotiations now mandate guaranteed workspace amenities as baseline terms. Event organizers demonstrate highest price sensitivity through competitive bidding across multiple palace properties, whereas ultra-high-net-worth international arrivals at global flagships show minimal elasticity.
Supply Chain Analysis
Freight costs for imported marble, specialty F&B ingredients, and wellness equipment from Italy, Turkey, and Southeast Asia inflate construction and operating budgets for heritage restoration projects. Rajasthan and Kerala properties draw from localized artisan networks for authentic craftsmanship, while Goa and Mumbai developments rest on global supplier relationships for standardized luxury fixtures. Single-source vulnerability concentrates in specialized heritage restoration skills as aging craftsmen exit faster than training pipelines replenish. Distribution runs through destination wedding planners, corporate procurement offices, and direct digital channels with divergent commission structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The India luxury hotel market is becoming a vertical-integration race as players pursue captive control over heritage restoration craftsmanship pipelines and in-house wedding planning operations to lock in occupancy blocks.
For Market Incumbents: Deepen backward integration into artisan training academies and captive wedding planning subsidiaries to defend rate premiums against standardized competitors. EIH Ltd's palace conversion portfolio faces margin pressure from Taj's mixed-use gateway city scale, requiring accelerated Kerala backwater expansion to diversify beyond Rajasthan inventory constraints. Certification investment in BIS fire safety compliance ahead of mandate timelines preserves operational continuity. For New Entrants and Emerging Players: Launch via boutique wellness-focused developments in underpenetrated Kerala backwater segments beyond Kochi's established inventory. White space concentrates in Ayurvedic-differentiated spa positioning with lower staffing ratios than urban full-service properties. Corporate MICE procurement consolidation in Bangalore's tech corridor offers the most penetrable entry vector through guaranteed workspace amenity contracts. For Investors and Strategic Acquirers: Re-rating potential sits with heritage-authenticated boutique operators given Ministry of Tourism Swadesh Darshan scheme capital redirection into palace conversion corridors. Long-term viability over the next decade hinges on finite Rajasthan inventory scarcity and authentic craftsmanship differentiation against global flagships. Monitor municipal corporation licensing timeline compression across Maharashtra, Karnataka, and Rajasthan as inflection indicator for capital deployment cycle predictability.| Strategic Initiative | Industry Significance |
|---|---|
| Heritage Restoration Academy Development | Captive artisan training pipelines address workforce aging and preserve authenticity premiums. |
| Destination Wedding Planner Vertical Integration | In-house planning operations lock occupancy blocks and capture commission margins. |
| Corporate Long-Stay Format Expansion | Residential-style floor plans with guaranteed workspace amenities secure annual contracts. |
| Ayurvedic Spa Certification Investment | Kerala backwater differentiation leverages FSSAI compliance for wellness positioning. |
| Mixed-Use Development Partnerships | Gateway city land scarcity pushes Taj and competitors toward hospitality-retail-office hybrids. |
Research Methodology
Ministry of Tourism classification databases, BIS fire safety compliance filings, and state-level excise regulatory records formed the secondary backbone for market sizing and competitive positioning analysis. Primary interviews with heritage property general managers, corporate procurement officers at Bangalore tech corridor firms, destination wedding planners, and FSSAI compliance consultants validated demand patterns and operational cost structures. Bottom-up property-level revenue modeling and top-down tourism sector expenditure analysis provided triangulation across the analysis window.
Bottom-up segmentation modeling across service type, client type, amenities, and room type dimensions generated volume and value outputs throughout the forecast period. CAGRs were derived from property pipeline analysis, heritage inventory constraints, and corporate contract growth trajectories. Forecast inputs incorporated Swadesh Darshan scheme capital allocation patterns, municipal corporation licensing timeline distributions, and wedding planner booking share expansion rates.
Regulatory enforcement variance, artisan workforce attrition, and corporate travel policy shifts are the dominant revision risks to projection assumptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hotels and Resorts
Global Beach Hotels Market
Hotels and Resorts
Europe Luxury Hotel Market
Hotels and Resorts
Five Star Hotel Market
Hotels and Resorts
Spain HRI Market
Hotels and Resorts
Hotels, Resorts, and Cruise Lines Market
Hotels and Resorts
Hotel Furniture and Furnishing Market
Hotels and Resorts
Mountain and Ski Resorts Market
Hotels and Resorts
Boutique Hotels Market
Hotels and Resorts
Asia-Pacific Luxury Hotel Market
Hotels and Resorts
Philippines Tourism and Hotel Market
Hotels and Resorts
Morocco Tourism Market
Hotels and Resorts
Cuba Tourism and Hotel Market
Hotels and Resorts
Hotel Armchair Market
Hotels and Resorts
North America Luxury Hotel Market
Hotels and Resorts
United States Luxury Hotel Market
Hotels and Resorts
United Kingdom HRI Market