
 Philippines Tourism and Hotel Market | 2026-2036
Philippines Tourism and Hotel Market Size, Share, and Industry Trends Forecast 2026-2036
Philippines Tourism and Hotel Market Analytics
The capital-intensity divergence between full-service resort developers and limited-service operators is unwinding competitive dynamics across the Philippine hospitality sector. Marriott International (PH) leverages its global loyalty infrastructure to anchor premium positioning in Metro Manila and Cebu. SM Hotels and Conventions Corp. sustains venue-integrated development through its mall-and-convention center ecosystem. Discovery Hospitality Corp. differentiates via boutique island resort specialization in Palawan and Boracay.
The Philippines tourism and hotel sector encompasses accommodation provisioning, travel intermediation, guided experience curation, and tourist transportation coordination across the archipelago's 7,600-plus islands, with room inventory spanning from 15-square-meter pod hostels to 200-key integrated beachfront resorts designed for MICE and leisure dual-use. Accommodation type segmentation shows hotels and resorts capturing the dominant margin pool due to nightly rate premiums in Boracay, Cebu, and Palawan, while vacation rentals are expanding fastest through platform-enabled supply growth in secondary municipalities. Customer type dynamics reveal international tourists contributing higher per-trip expenditure but domestic travelers providing volume stability during external demand shocks.
The Department of Tourism's accreditation framework and the Department of Trade and Industry's consumer protection standards jointly shape market access requirements for accommodation operators, with fire safety, sanitation, and sustainability criteria escalating compliance costs for independent properties. The Department of Environment and Natural Resources enforces carrying-capacity limits on ecologically sensitive destinations including El Nido and Siargao, constraining room supply expansion in high-yield locations. Stakeholders must monitor accreditation tier migration and environmental compliance timelines to calibrate development pipelines against regulatory bottlenecks.
Market Dynamics
The Department of Tourism's tightening accreditation standards are compressing independent property margins while concentrating market share among capitalized operators capable of absorbing fire safety, sanitation, and sustainability compliance costs across the archipelago.
Growth Catalysts
- Domestic leisure corridor expansion:Cebu and Davao are maturing as secondary destination hubs beyond Metro Manila, drawing developer investment and route capacity from Philippine carriers.
- Department of Environment and Natural Resources carrying-capacity frameworks:These limits on El Nido and Siargao create artificial scarcity that protects rate premiums for compliant existing inventory.
- MICE-integrated resort development:Dual-use properties combining beachfront leisure with convention infrastructure are capturing corporate retreat demand from ASEAN regional headquarters.
Market Restraints
- Construction input cost volatility:Cement and steel price fluctuations in Philippine supply chains are squeezing development IRRs for greenfield resort projects.
- Environmental permit bottlenecks:Coastal construction moratoriums and ecological clearance timelines extend pre-revenue phases by 18-36 months in Palawan and Siargao.
- Labor pool fragmentation:Hospitality service skills concentrate in Metro Manila and Cebu, creating wage inflation and turnover costs for provincial properties.
Strategic Opportunities
- Mindanao underpenetration:Davao Region and Soccsksargen offer first-mover positioning before infrastructure completion closes competitive windows.
- Digital nomad visa alignment:Bureau of Immigration long-stay permit frameworks can anchor month-long booking patterns distinct from traditional 3-4 night leisure stays.
- Renewable energy integration:Solar-plus-storage microgrids are enabling off-grid island properties to bypass diesel dependency and command sustainability premiums.
Industry Challenges
- Accreditation tier migration complexity:Properties upgrading from one-star to three-star Department of Tourism ratings face capital deployment decisions against uncertain demand elasticity.
- Platform dependency risk:OTA commission structures and review algorithm volatility concentrate customer acquisition power outside operator control.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Philippines Tourism and Hotel Market |
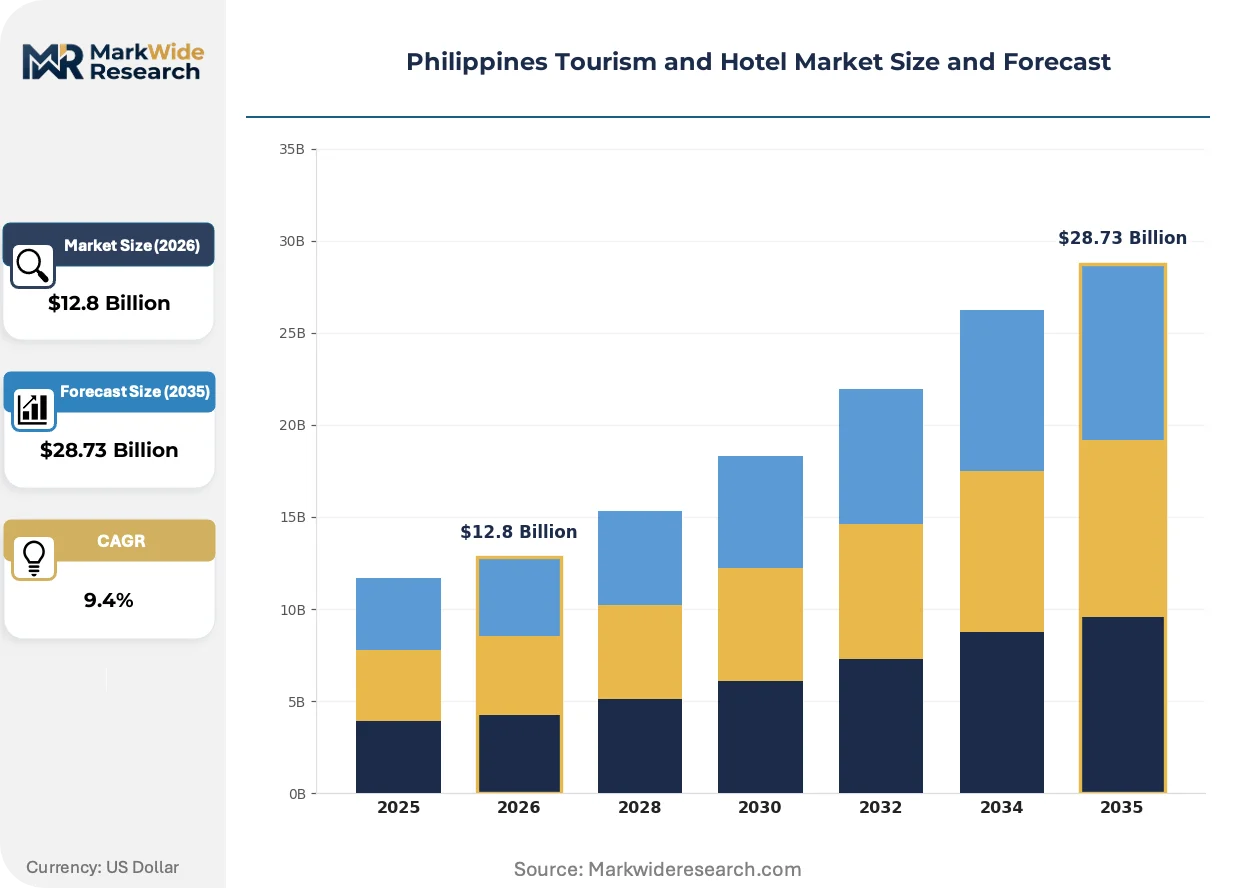
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $28.73 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Accommodation, Travel Agency, Guided Tours, Transportation Customer Type: Domestic Travelers, International Tourists, Business Travelers, Adventure Seekers Accommodation Type: Hotels, Resorts, Hostels, Vacation Rentals Booking Channel: Online Travel Agents, Direct Booking, Travel Agencies, Mobile Apps |
| Companies Covered | Marriott International (PH), IHG Hotels & Resorts (PH), SM Hotels and Conventions Corp., Discovery Hospitality Corp., Red Planet Hotels (PH), Robinsons Hotels & Resorts, Travellers International Hotel Group, Berjaya Hotels (PH), AyalaLand Hotels & Resorts Corp., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Philippines Tourism and Hotel Market Evolving Landscape
Property management systems and guest-facing digital infrastructure are compressing operational cost structures while enabling personalization at scale across dispersed island locations.
Cloud-native property management platforms are displacing on-premise legacy systems in mid-scale Philippine hotels. Independent operators in Boracay and Palawan are adopting these tools fastest to reduce front-desk staffing ratios. The shift is displacing traditional franchise-dependent technology access, allowing non-branded properties to match chain-level operational sophistication.
The Department of Tourism's sustainability certification tiers are tightening eligibility for marketing support and international promotion placement. Properties must document waste management, renewable energy share, and local employment ratios to qualify. Boutique resorts in El Nido and Coron are responding by embedding circular economy practices into guest experience design.
Domestic travelers are consolidating booking windows and extending length-of-stay patterns beyond traditional weekend excursion norms. Multi-night island-hopping itineraries are replacing single-destination trips, particularly among remote-working professionals. This behavioral shift is most visible in Cebu and Iloilo gateway markets where ferry and air connectivity enables flexible routing.
Philippines Tourism and Hotel Market Segmentation
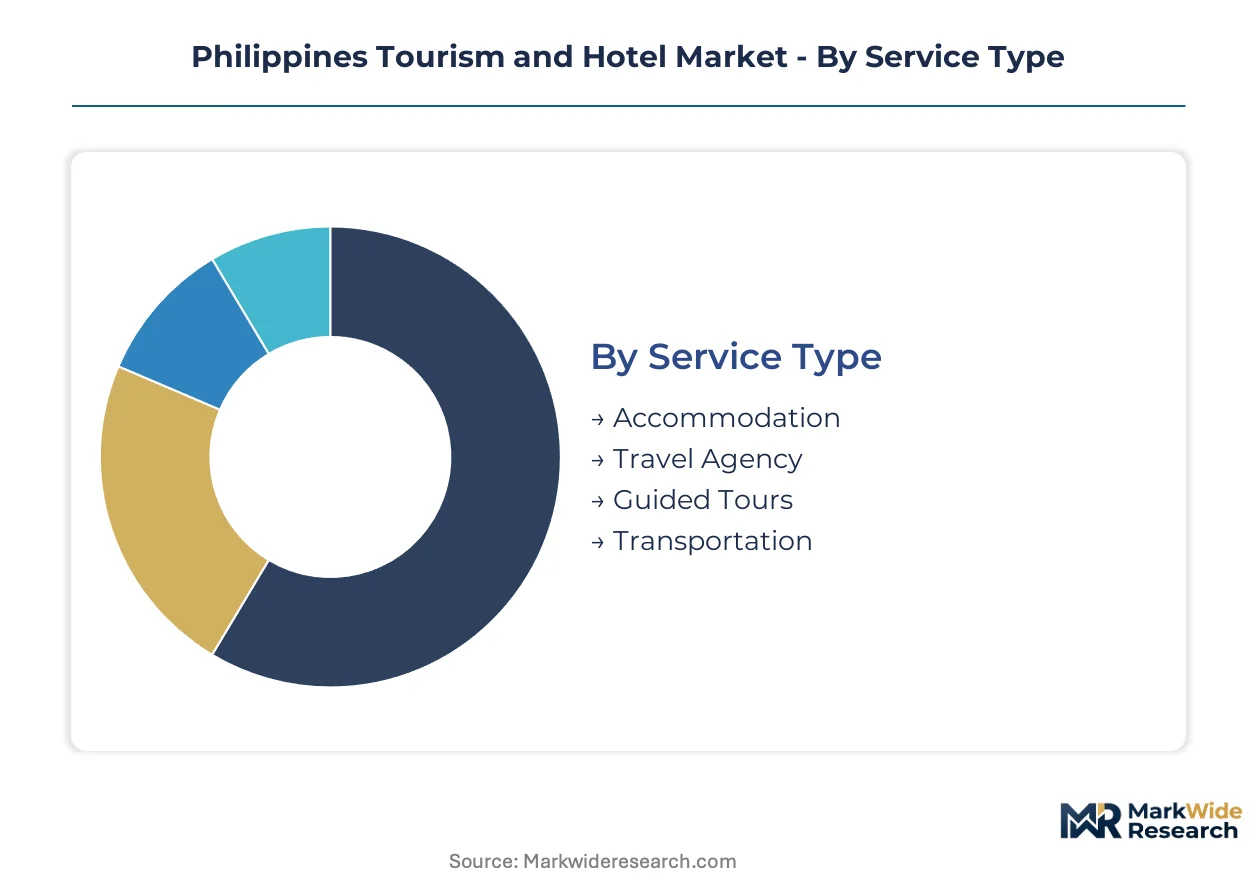
Segmentation in the Philippine hospitality market reveals how substitution pressures reshape competitive boundaries. Platform-enabled alternatives now challenge traditional service models across every category, forcing operators to defend their value proposition through differentiation or integration.
Service Type:
Accommodation faces the strongest substitution threat as vacation rentals and home-sharing platforms capture price-sensitive demand, while travel intermediation confronts direct-booking technology disintermediation.
- Accommodation:Physical lodging inventory spanning 15-square-meter pod hostels to 200-key integrated beachfront resorts. Demand concentrates in Boracay, Cebu, and Palawan where nightly rate premiums justify capital deployment despite Department of Environment and Natural Resources carrying-capacity limits.
- Travel Agency:Intermediation services connecting travelers with packaged inventory and fragmented island-hopping logistics. Cebu and Davao corridor expansion is driving corporate account consolidation as secondary destination infrastructure matures.
- Guided Tours:Curated experiential programming across the archipelago's 7,600-plus islands. El Nido and Siargao operators embed sustainability certification requirements into excursion design to qualify for Department of Tourism marketing support.
- Transportation:Coordination of ferry, domestic air, and ground transfer networks. Philippine carrier route capacity allocation to Cebu and Davao is reshaping gateway economics away from Metro Manila dominance.
Accommodation retains volume leadership; Travel Agency holds the steepest expansion curve as platform consolidation accelerates.
Customer Type:
Cost tier stratification determines margin capture, with international visitors commanding rate premiums while domestic travelers provide occupancy floor stability during external demand shocks.
- Domestic Travelers:Filipino nationals undertaking leisure, VFR, and corporate travel across the archipelago. Multi-night island-hopping itineraries are replacing single-destination weekend excursions, particularly among remote-working professionals in Cebu and Iloilo gateway markets.
- International Tourists:Foreign nationals generating higher per-trip expenditure but exposed to currency volatility and geopolitical demand disruption. Korean, Chinese, and Japanese source markets dominate volume.
- Business Travelers:Corporate account demand spanning MICE events, regional headquarters retreats, and individual executive travel. Dual-use properties combining beachfront leisure with convention infrastructure capture ASEAN regional headquarters demand.
- Adventure Seekers:Experience-focused travelers prioritizing diving, surfing, and trekking activities. Siargao and Coron operators target this segment with specialized equipment and guide certification requirements.
Domestic Travelers anchor occupancy baselines; Adventure Seekers are climbing the fastest as experience premiumization accelerates.
Accommodation Type:
Supply concentration varies by development capital intensity, with full-service resort projects requiring 18-36 month pre-revenue phases against limited-service operators' faster deployment timelines.
- Hotels:Urban and secondary city properties offering standardized service tiers. Metro Manila and Cebu concentrate branded inventory where Marriott International leverages global loyalty infrastructure.
- Resorts:Beachfront and island properties designed for leisure and MICE dual-use. Palawan and Boracay rate premiums justify extended environmental clearance timelines under Department of Environment and Natural Resources frameworks.
- Hostels:Budget-oriented shared accommodation targeting price-sensitive segments. Platform-enabled supply growth in secondary municipalities is expanding this category fastest.
- Vacation Rentals:Privately-owned inventory distributed through online platforms. Independent operators bypass Department of Tourism accreditation costs but face fire safety and sanitation compliance pressure.
Hotels dominate revenue concentration; Vacation Rentals are gaining share fastest through platform-enabled supply expansion.
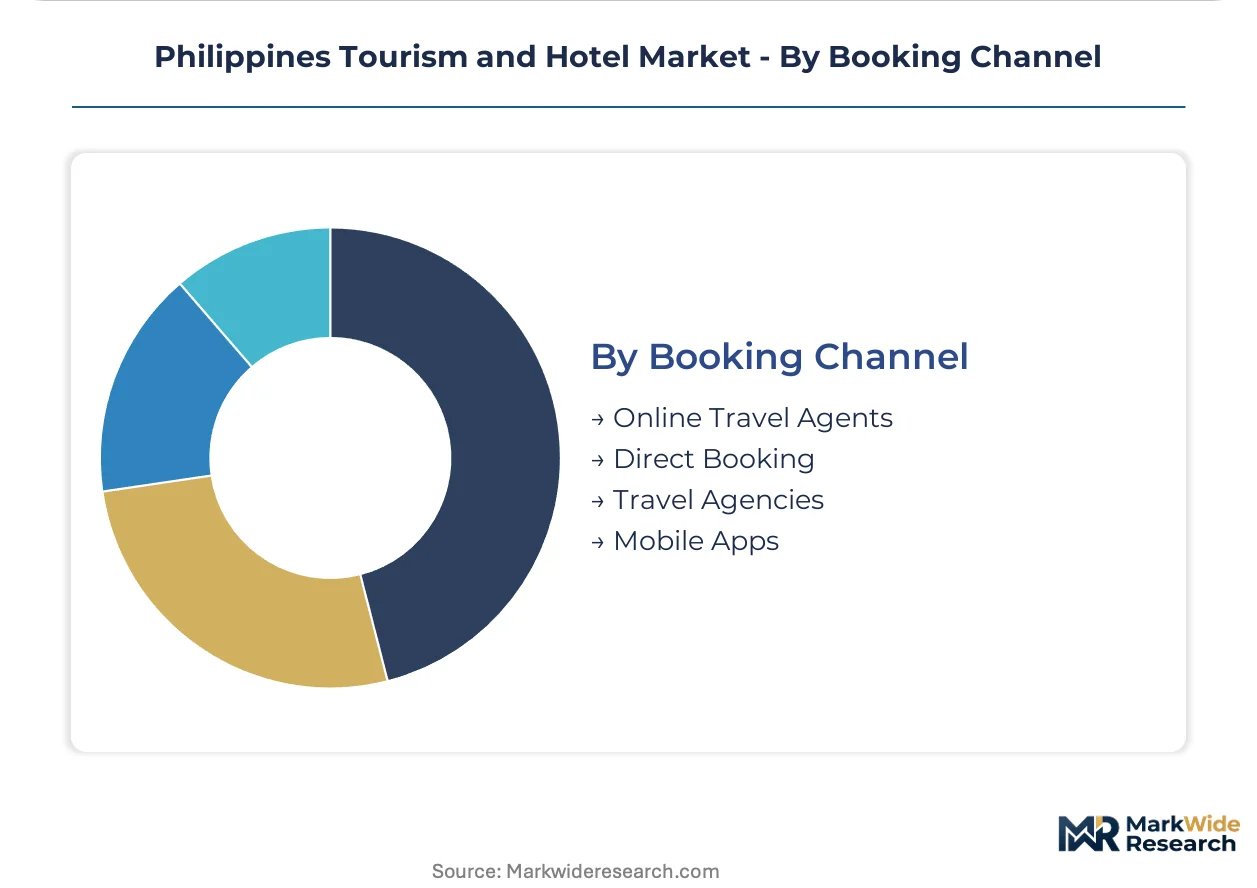
Booking Channel:
Customer acquisition power concentration outside operator control creates platform dependency risk, with algorithm volatility and commission structures compressing net revenue per booking.
- Online Travel Agents:Third-party platforms aggregating inventory and capturing customer relationships. Commission structures concentrate pricing power with intermediaries.
- Direct Booking:Property-controlled reservation channels bypassing platform fees. Cloud-native property management systems enable independent operators to match chain-level operational sophistication.
- Travel Agencies:Traditional intermediaries serving corporate accounts and package tour segments. Corporate retreat demand from ASEAN regional headquarters sustains this channel in MICE-integrated resort development.
- Mobile Apps:Smartphone-native booking interfaces capturing last-minute and impulse demand. Domestic travelers consolidating booking windows favor this channel for flexible island-hopping itinerary adjustments.
Online Travel Agents command transaction volume; Mobile Apps show the steepest expansion trajectory as smartphone penetration deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Metro Manila commands rate premiums that provincial corridors cannot match, yet Cebu and Davao are narrowing this gap through infrastructure completion and carrier route expansion. The Department of Tourism's accreditation tier system reinforces this hierarchy by concentrating marketing support on properties in designated priority zones.
Metro Manila
Corporate MICE demand and international gateway traffic sustain occupancy floors in Makati and Pasay integrated complexes. The Department of Tourism's three-star minimum accreditation for international marketing eligibility filters independent properties from premium channel access. Marriott International anchors global loyalty program penetration in the Bonifacio Global City cluster.
Cebu
Secondary destination maturation draws Philippine Airlines and Cebu Pacific capacity allocation away from Manila dominance. The Department of Environment and Natural Resources coastal construction permits face 18-month clearance timelines that constrain beachfront supply expansion. Mactan Island resort developers capture ASEAN regional headquarters retreat demand through dual-use convention infrastructure.
Davao Region
Mindanao underpenetration offers first-mover positioning before road and air connectivity completion closes competitive windows. The Department of Trade and Industry's investment priority status accelerates fiscal incentive access for tourism-focused capital deployment. Samal Island operators test renewable energy microgrid integration to bypass diesel dependency.
Palawan
El Nido and Coron carrying-capacity limits create artificial scarcity protecting rate premiums for compliant existing inventory. The Department of Environment and Natural Resources ecological clearance requirements extend pre-revenue phases by 24-36 months for greenfield projects. Boutique resort specialists embed circular economy practices to qualify for sustainability certification tiers.
Western Visayas
Boracay rehabilitation protocols permanently reduced room supply below peak levels, concentrating revenue among remaining accredited operators. The Department of Tourism's fire safety and sanitation compliance costs displaced independent properties during the 2018-2021 restructuring window. Station 1 beachfront commands the archipelago's highest nightly rate realizations.
Philippines Tourism and Hotel Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the Philippine hospitality sector. Global chain operators leverage cloud-native property management systems and loyalty infrastructure to compress customer acquisition costs, while limited-service specialists minimize staffing ratios through automated check-in platforms. The market structure tiers into three strategic archetypes: international brand licensors, domestic integrated developers, and boutique island specialists. Competitive moves concentrate on accreditation tier migration and renewable energy integration as regulatory compliance becomes a differentiator.
Within the international brand licensor tier, Marriott International (PH) and IHG Hotels & Resorts (PH) occupy positions defined by global loyalty program anchoring. Domestic integrated developers include SM Hotels and Conventions Corp. and AyalaLand Hotels & Resorts Corp., which exemplify venue-integrated development through mall-and-convention center ecosystem control. Discovery Hospitality Corp. represents the boutique island specialist archetype, differentiating through Palawan and Boracay resort concentration rather than scale.
| Leading Market Players |
|---|
| Marriott International (PH) |
| IHG Hotels & Resorts (PH) |
| SM Hotels and Conventions Corp. |
| Discovery Hospitality Corp. |
| Red Planet Hotels (PH) |
| Robinsons Hotels & Resorts |
| Travellers International Hotel Group |
| Berjaya Hotels (PH) |
| AyalaLand Hotels & Resorts Corp. |
| Others |
Value Network & Pricing Analysis
Vacation rental platform substitution for traditional hotel inventory simultaneously redistributes pricing power toward algorithm-mediated intermediaries and fragments supply geography across thousands of uncoordinated host properties. This displacement compresses rate transparency in secondary municipalities while concentrating margin capture with online travel agents controlling customer access.
Pricing Analysis
The customization-premium spread between configured island-hopping packages and standardized room nights defines Philippine hospitality pricing. Three-tier pricing structure across luxury eco-resorts, mid-scale business hotels, and budget hostels stratifies by Department of Tourism accreditation grade and sustainability certification status. Pricing pressure stems from online travel agent commission structures that extract 15-25 percent of gross booking value. Domestic leisure travelers exhibit highest price sensitivity during off-peak months, while MICE corporate accounts absorb premium rates for exclusive venue access.
Supply Chain Analysis
Manila-Cebu ferry lane congestion and Mactan Island port capacity constraints throttle construction material flows to resort developments. Cement and steel sourcing draws from China, South Korea, and domestic Philippine manufacturers, with rebar and finishing fixtures resting on imported supply. Single-source vulnerability concentrates in diesel generator sets powering off-grid island properties before renewable microgrid completion. Distribution runs through provincial construction material depots in Davao and Iloilo that feed last-mile barge networks.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform-mediated accommodation substitution threatens incumbent hotel operators with disintermediation of customer relationships and rate-setting autonomy. Defending against this erosion requires structural repositioning around regulatory moats and experience differentiation.
For Market Incumbents: Compound Department of Tourism accreditation tier advantages by accelerating three-star and above property upgrades before compliance cost escalations filter smaller competitors. Secure direct booking channel share through cloud-native property management investments that reduce platform dependency. Anchor renewable energy microgrid development in Palawan and Siargao to command sustainability premiums before diesel price volatility erodes margin.
For New Entrants and Emerging Players: Digital nomad long-stay accommodation gaps in Cebu and Davao corridors offer first-mover positioning before incumbent brands adapt extended-stay product formats. Target Mindanao underpenetration in Soccsksargen and Caraga regions where infrastructure completion timelines create temporary competitive windows. Deploy co-living and workspace-integrated hostel formats to capture remote worker demand distinct from traditional leisure segmentation.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with domestic integrated developers holding mall-and-convention center venue control that generates captive hotel demand. Five-to-ten year viability hinges on regulatory compliance capability rather than scale alone. Monitor Bureau of Immigration digital nomad visa policy implementation as demand inflection signal for extended-stay inventory repositioning.
| Strategic Initiative | Industry Significance |
|---|---|
| Accreditation Tier Migration | Department of Tourism three-star minimum unlocks international marketing channel access and rate premiums. |
| Renewable Energy Microgrid Integration | Solar-plus-storage deployment in El Nido and Siargao bypasses diesel dependency and commands sustainability premiums. |
| Direct Booking Channel Investment | Cloud-native property management systems reduce online travel agent commission extraction and recover customer data ownership. |
| Mindanao Geographic Expansion | Davao Region and Soccsksargen infrastructure completion creates first-mover windows before competitive saturation. |
| Digital Nomad Visa Alignment | Bureau of Immigration long-stay permit frameworks anchor month-long booking patterns distinct from traditional leisure stays. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with hotel development executives, Department of Tourism accreditation officers, resort operations directors, online travel agent partnership managers, and renewable energy EPC contractors. Secondary validation drew from Department of Environment and Natural Resources permitting databases, Department of Trade and Industry investment priority listings, Philippine carrier route capacity disclosures, and Bureau of Immigration visa policy circulars. Bottom-up property inventory counts and top-down tourism receipts triangulation anchored market sizing.
Across the analysis window, forecasts segment by accommodation type, customer archetype, booking channel, and regional corridor to capture substitution dynamics between hotels and vacation rentals. CAGRs derive from historical elasticity modeling against infrastructure completion timelines and regulatory compliance phase-ins. Inputs include Philippine Airlines and Cebu Pacific capacity allocation patterns, coastal construction permit approval velocities, and sustainability certification adoption curves.
Forecasts assume regulatory continuity in Department of Tourism accreditation frameworks and Department of Environment and Natural Resources carrying-capacity regimes; material policy shifts would require re-modeling. Scenario risks encompass environmental permit moratorium extensions, platform commission structure changes, and Mindanao security condition volatility. Practitioners should keep alternative scenarios live as renewable energy cost curves and digital nomad visa uptake evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hotels and Resorts
Cuba Tourism and Hotel Market
Hotels and Resorts
Five Star Hotel Market
Hotels and Resorts
Asia-Pacific Luxury Hotel Market
Hotels and Resorts
Morocco Tourism and Hotel Market
Hotels and Resorts
Global Floating Hotels Market
Hotels and Resorts
Boutique Hotels Market
Hotels and Resorts
Germany HRI Market
Hotels and Resorts
Europe Luxury Hotel Market
Hotels and Resorts
Hotels, Resorts, and Cruise Lines Market
Hotels and Resorts
Hotel Armchair Market
Hotels and Resorts
Morocco Tourism Market
Hotels and Resorts
United States Luxury Hotel Market
Hotels and Resorts
Spain HRI Market
Hotels and Resorts
North America Luxury Hotel Market
Hotels and Resorts
Global Beach Hotels Market
Hotels and Resorts
India Luxury Hotel Market