
 Asia-Pacific Luxury Hotel Market | 2026-2036
Asia-Pacific Luxury Hotel Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Luxury Hotel Market Outlook
A severe shortage of multilingual hospitality management graduates is unwinding development timelines across Southeast Asia. Marriott International leverages its Bonvoy loyalty ecosystem to sustain repeat visitation in Maldives and Phuket. Aman Group S.a.r.l. anchors ultra-luxury rate integrity through deliberately limited room counts and exclusive site control. Mandarin Oriental International Ltd differentiates on food and beverage programming, occupying premium positioning in Bangkok and Singapore.
Asia-Pacific luxury hotels constitute high-service lodging properties typically delivering minimum 50 square meter guest rooms, personalized concierge functions, and signature dining venues with chef-led concepts. These assets serve wealth concentration, corporate travel recovery, and destination event demand across the region's major metropolitan and resort corridors. Resort properties within the Hotel Type segment command the deepest rate pools, particularly in Indian Ocean and South Pacific island destinations where land scarcity limits competitive supply. The Ultra-Luxury size tier captures disproportionate margin contribution per available room, while Full-Service properties under Service Type face pressure to rationalize labor-intensive operating models against rising wage floors.
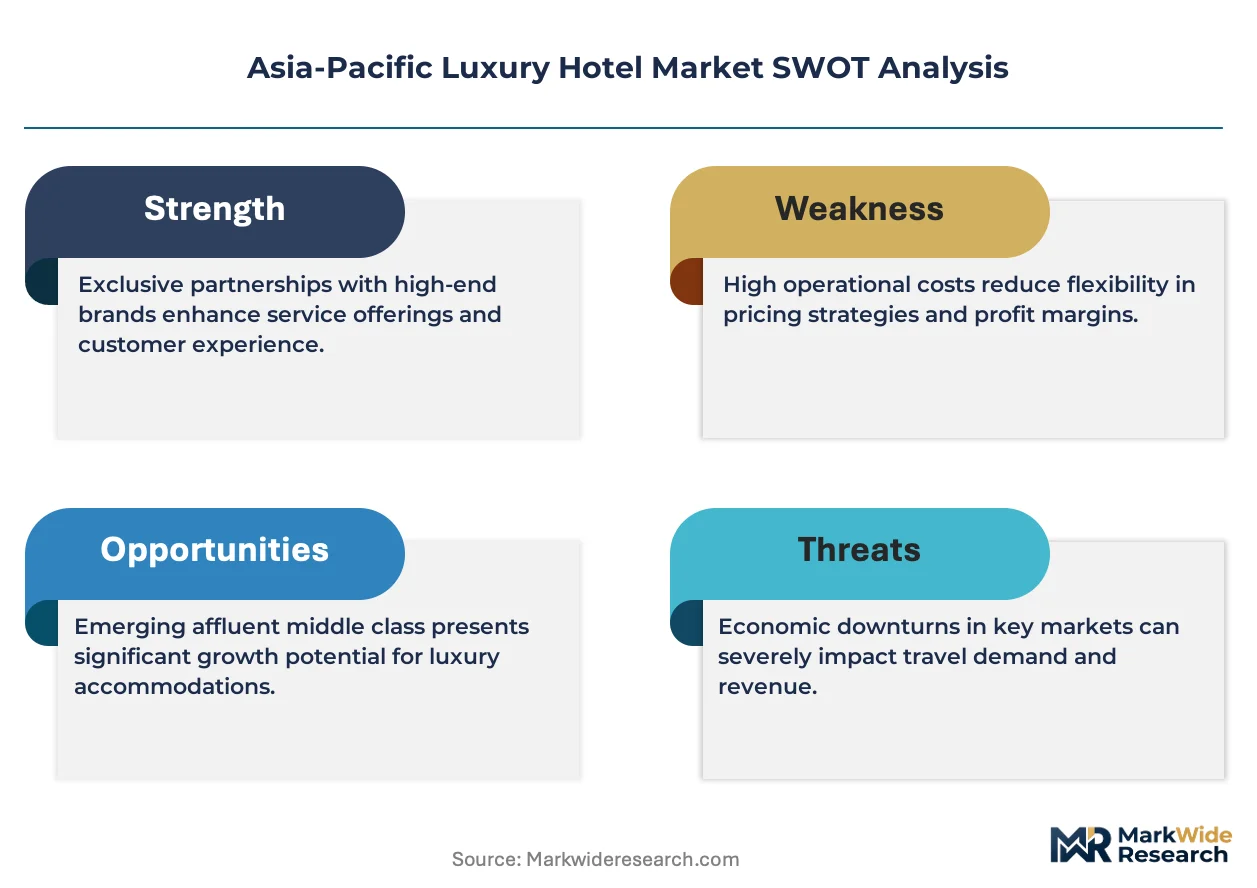
Thailand's Ministry of Tourism and Sports coordinates with local environmental regulators to enforce coastal construction setbacks that constrain beachfront supply in Phuket and Krabi. Australia's Therapeutic Goods Administration and state-level liquor licensing boards shape wellness and F&B amenity standards for properties targeting health-conscious travelers. Japan's METI energy efficiency directives influence refurbishment cycles across Tokyo and Osaka legacy assets. Stakeholders must weigh capital deployment between established gateway cities and emerging secondary destinations where infrastructure gaps present both risk and first-mover positioning.
Market Dynamics
Ultra-high-net-worth leisure travelers from mainland China are compressing booking windows and demanding hyper-personalized service configurations, forcing properties to restructure revenue management and staffing models around unpredictable arrival patterns.
Growth Catalysts
- Visa Liberalization:Japan's easing of visa requirements for Southeast Asian nationals is unlocking new inbound corridors from Indonesia, Philippines, and Vietnam.
- Integrated Resort Pipeline:Bali's Nusa Dua and Uluwatu corridors are absorbing premium room inventory through mixed-use developments combining hospitality, retail, and entertainment.
- Wealth Concentration:Family office travel spend across Singapore, Hong Kong, and Sydney is sustaining extended-stay demand in ultra-luxury tier properties.
Market Restraints
- Labor Supply Compression:A severe shortage of multilingual hospitality management graduates is unwinding development timelines across Thailand, Vietnam, and Indonesia.
- Coastal Construction Limits:Thailand's Ministry of Tourism and Sports enforces mandatory setbacks that constrain beachfront supply in Phuket and Krabi.
- Energy Efficiency Mandates:Japan's METI directives are accelerating refurbishment cycles for legacy assets in Tokyo and Osaka, diverting capital from new development.
Strategic Opportunities
- Secondary Destination Entry:Infrastructure gaps in Vietnam's Da Nang and Nha Trang corridors present first-mover positioning for integrated resort operators.
- Wellness Amenity Expansion:Australia's Therapeutic Goods Administration standards for therapeutic claims are creating differentiation pathways for health-conscious property programming.
- Loyalty Ecosystem Leverage:Points-based redemption models are capturing repeat visitation in Maldives and Phuket through experiential rather than transactional engagement.
Industry Challenges
- Specialized Talent Acquisition:Chef-led concept development requires culinary professionals capable of executing regionally authentic yet internationally calibrated menus.
- Rate Integrity Maintenance:Ultra-luxury properties must defend positioning against dilution from overbuilt full-service supply in gateway cities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Luxury Hotel Market |
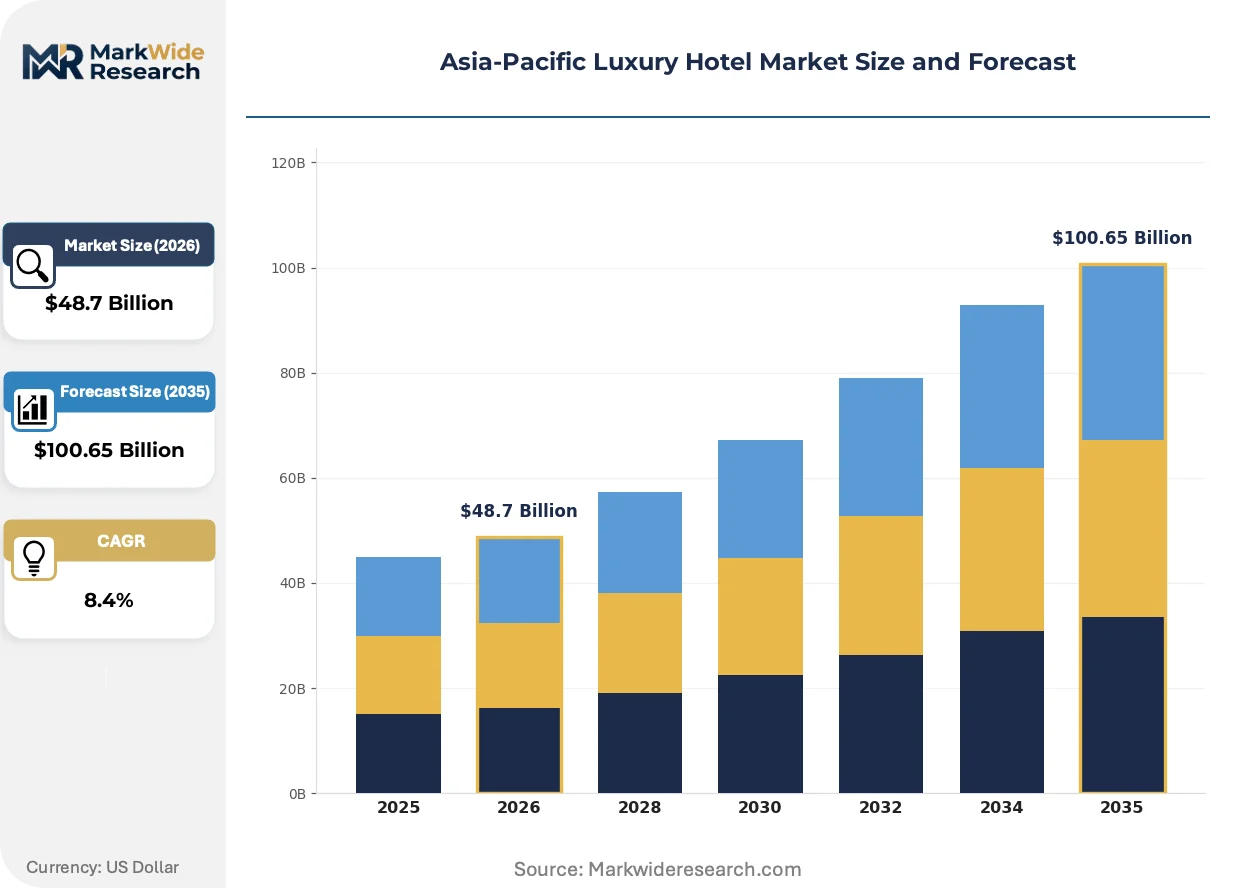
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $100.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Hotel Type: Resort, Boutique, Business, Chain Size: Small, Medium, Large, Ultra-Luxury Service Type: Full-Service, Limited-Service, Extended Stay, All-Inclusive Target Audience: Business Travelers, Tourists, Families, VIP Guests |
| Companies Covered | Hyatt Hotels Corp., Four Seasons Hotels Ltd., Hilton Worldwide Holdings Inc., Aman Group S.a.r.l., Mandarin Oriental International Ltd, Marriott International, InterContinental Hotels Group PLC, Hotel Okura Co. Ltd., Accor SA, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Luxury Hotel Market Strategic Shifts
Digital guest journey orchestration is collapsing traditional service hierarchies, with mobile-first check-in, keyless entry, and AI-curated experience recommendations becoming baseline expectations rather than premium differentiators.
Contactless service architecture is supplanting high-touch lobby and concierge staffing models across upscale urban properties. Business travelers and millennial leisure segments are adopting these interfaces fastest, with adoption curves compressing from five-year horizons to eighteen-month implementation cycles. This shift is enabling smaller footprint lobby designs and reallocating square meterage toward revenue-generating F&B and wellness zones.
Thailand's coastal construction setbacks represent a tightening regulatory envelope that is redirecting developer capital toward inland and hillside sites with elevated rather than beachfront positioning. Properties in Phuket and Krabi are responding through vertical design solutions that preserve ocean views while complying with environmental buffers. The constraint is most acute for mid-scale full-service brands dependent on sand-access marketing.
Direct booking preference is disrupting Online Travel Agency channel dominance among ultra-high-net-worth segments. These travelers are prioritizing property-specific loyalty programs and exclusive member rates over aggregator convenience, particularly in Maldives and Bali resort markets. The shift is most pronounced among mainland Chinese guests with established relationships through prior stays or credit card partnerships.
Asia-Pacific Luxury Hotel Market Segmentation
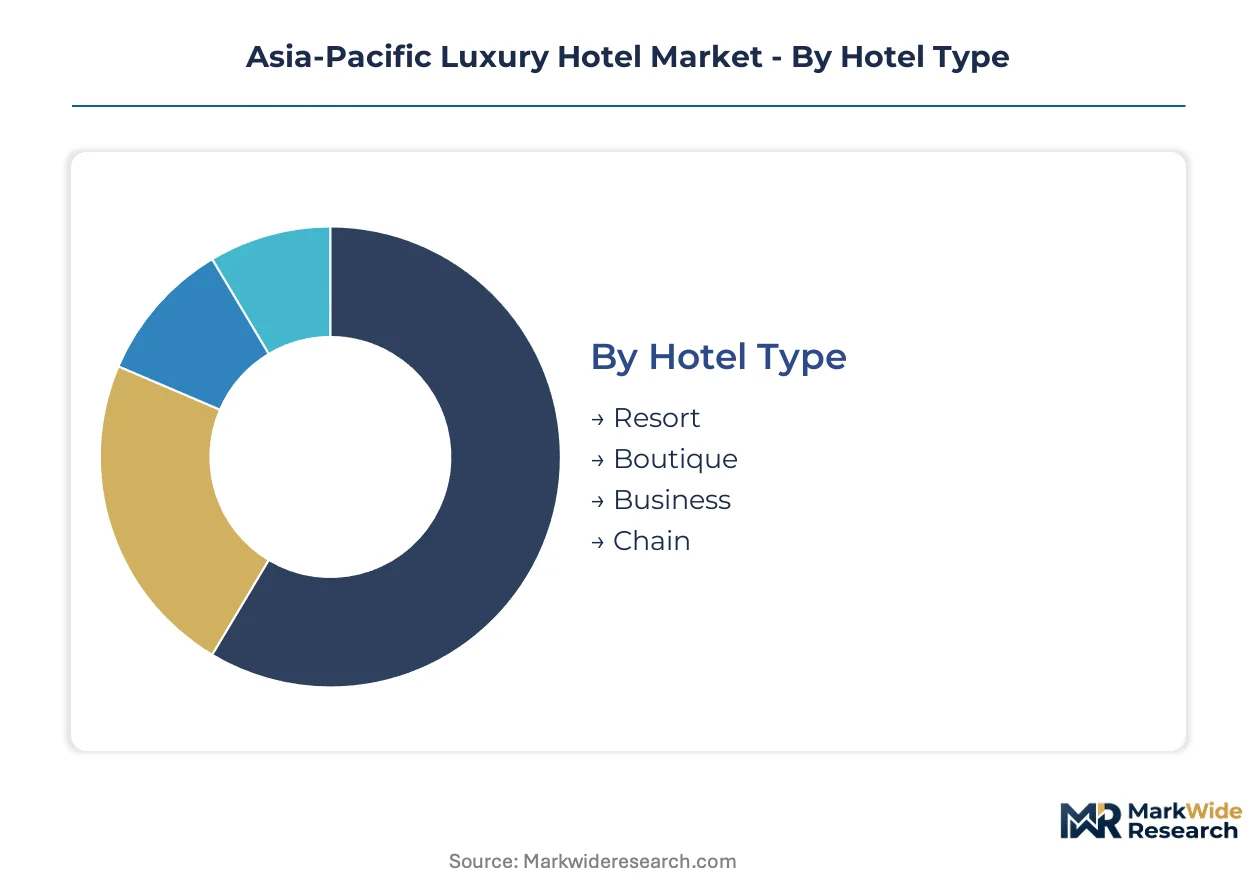
Segmentation in Asia-Pacific luxury hospitality reveals how capital allocation, labor intensity, and distribution channel economics vary dramatically across property configurations. Understanding these divides enables operators to match service models against guest willingness-to-pay and local regulatory constraints.
Hotel Type:
Resort properties flow predominantly through direct booking channels and luxury travel advisors, while urban boutique inventory splits between OTAs and proprietary loyalty platforms.
- Resort:These properties command the deepest rate pools across Indian Ocean and South Pacific island destinations where land scarcity limits competitive supply. Demand concentrates in Maldives and Bali's Nusa Dua corridor, driven by ultra-high-net-worth leisure travelers from mainland China compressing booking windows.
- Boutique:Design-forward properties typically under 100 keys emphasizing localized aesthetic programming and chef-led F&B concepts. Bangkok and Singapore clusters absorb premium positioning here, with Mandarin Oriental International Ltd anchoring differentiation through food and beverage execution.
- Business:Urban properties targeting corporate travel recovery with streamlined service models and proximity to financial districts.
- Chain:Branded portfolios leveraging standardized operating procedures and global distribution systems for volume capture.
Resort dominates installed base across the region's leisure corridors. Boutique is where expansion concentrates as developers seek rate premiums through scarcity positioning.
Size:
Cost tier stratification separates labor-intensive full-service operations from automated limited-service formats, with capital deployment thresholds varying fourfold between tiers.
- Small:Properties under 75 keys emphasizing intimate service ratios and hyper-personalized guest recognition. Phuket and Krabi hillside developments are absorbing this inventory as Thailand's coastal construction setbacks redirect capital inland.
- Medium:Mid-scale formats balancing operational efficiency against amenity breadth, prevalent in Tokyo and Osaka refurbishment cycles driven by Japan's METI energy efficiency directives.
- Large:Integrated resort developments combining hospitality, retail, and entertainment across Bali's Uluwatu corridor.
- Ultra-Luxury:Deliberately constrained room counts with exclusive site control, capturing disproportionate margin contribution per available room. Aman Group S.a.r.l. anchors this tier through rate integrity maintenance against dilution from overbuilt gateway supply.
Large properties dominate installed base in established destinations. Ultra-Luxury is where expansion concentrates as family office travel spend sustains extended-stay demand.
Service Type:
Application context determines staffing models, with corporate travel recovery favoring streamlined formats while leisure destinations absorb labor-intensive configurations.
- Full-Service:Labor-intensive operating models with personalized concierge functions and signature dining venues. These properties face pressure to rationalize against rising wage floors across Thailand, Vietnam, and Indonesia.
- Limited-Service:Automated formats with mobile-first check-in and keyless entry collapsing traditional service hierarchies. Australia's Therapeutic Goods Administration standards for therapeutic claims are creating differentiation pathways here through wellness programming.
- Extended Stay:Apartment-style configurations targeting family office travel spend across Singapore, Hong Kong, and Sydney.
- All-Inclusive:Bundled pricing models capturing predictable revenue per guest, prevalent in Maldives and Phuket where points-based redemption models drive repeat visitation.
Full-Service dominates installed base across metropolitan corridors. Limited-Service is where expansion concentrates as contactless service architecture compresses adoption curves.
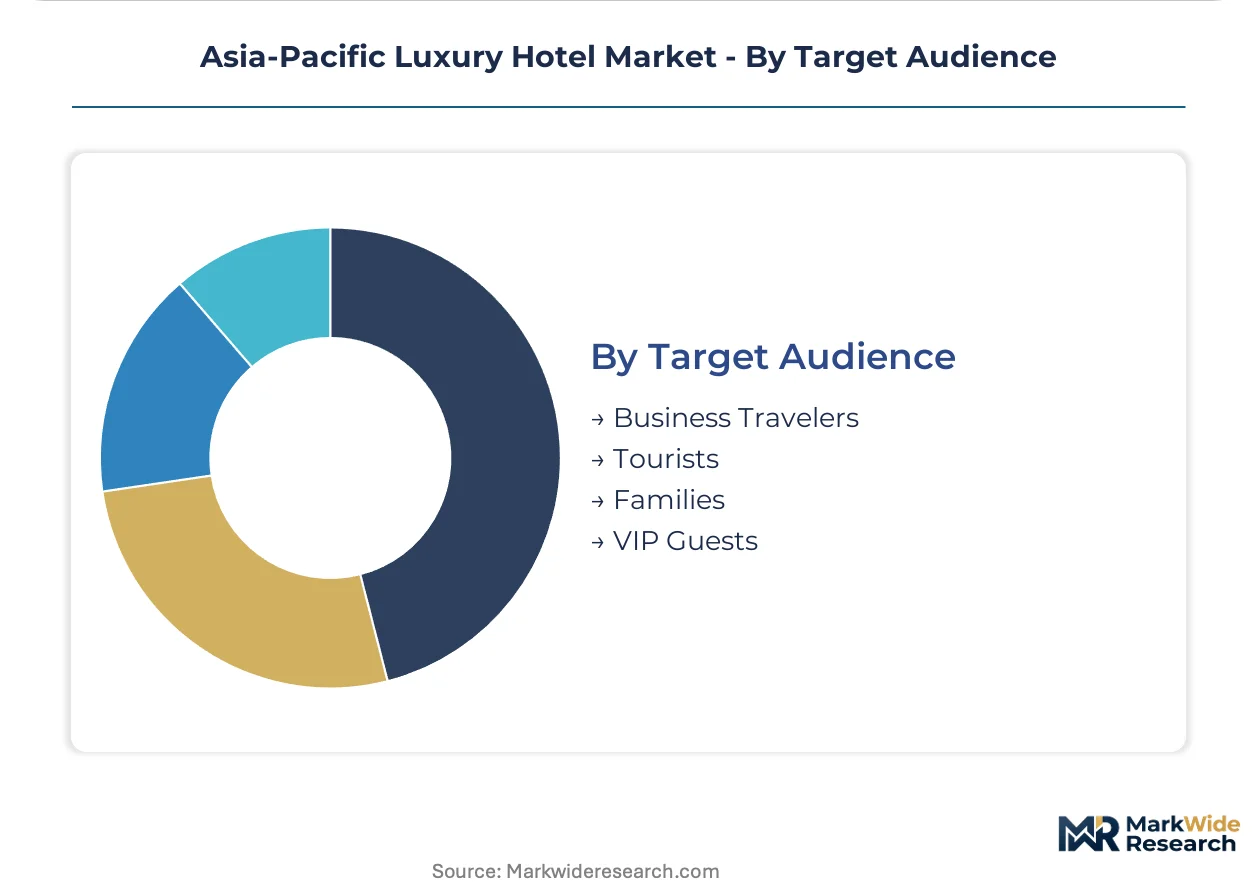
Target Audience:
Customer type segmentation governs distribution strategy, with VIP segments prioritizing direct relationships while family and tourist segments flow through intermediaries.
- Business Travelers:Corporate accounts and negotiated rate structures driving weekday occupancy in Tokyo, Osaka, and Sydney financial districts. Marriott International leverages Bonvoy loyalty ecosystems to sustain this segment.
- Tourists:Leisure demand concentrated in destination corridors with seasonal volatility requiring dynamic revenue management.
- Families:Multi-generational travel segments favoring connecting room configurations and activity programming, expanding most quickly in Vietnam's Da Nang and Nha Trang corridors.
- VIP Guests:Ultra-high-net-worth individuals demanding hyper-personalized service configurations and exclusive member rates over aggregator convenience, particularly in Maldives and Bali resort markets.
Business Travelers dominate installed base in gateway cities. Families represent the steepest expansion trajectory as secondary destinations present first-mover positioning opportunities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's METI energy efficiency directives anchor refurbishment cycles across legacy assets in Tokyo and Osaka, diverting capital from new development. The region's luxury hospitality footprint clusters around visa liberalization corridors, integrated resort pipelines, and family office travel spend concentration.
Japan
Ultra-high-net-worth leisure travelers from mainland China compress booking windows in Tokyo's financial district properties. METI directives accelerate refurbishment timelines for legacy assets in Osaka. Kansai corridor developments absorb premium inventory through mixed-use hospitality and entertainment integration.
Thailand
Phuket and Krabi hillside developments redirect capital inland as coastal construction setbacks constrain beachfront supply. The Ministry of Tourism and Sports enforces mandatory environmental buffers. Integrated resort operators target Nusa Dua corridor positioning through vertical design solutions preserving ocean views.
Indonesia
Bali's Uluwatu corridor absorbs premium room inventory through mixed-use developments combining hospitality, retail, and entertainment. Visa liberalization from Japan unlocks inbound demand from Southeast Asian nationals. Nusa Dua developments concentrate family office travel spend from Singapore and Hong Kong.
Australia
Sydney anchors extended-stay demand in ultra-luxury tier properties driven by family office travel spend. The Therapeutic Goods Administration shapes wellness amenity standards for health-conscious traveler programming. New South Wales and Victoria clusters differentiate through therapeutic claims compliance and chef-led F&B concepts.
Vietnam
Da Nang and Nha Trang corridors present first-mover positioning for integrated resort operators addressing infrastructure gaps. Multilingual hospitality management graduate shortages unwind development timelines. Secondary destination entry captures multi-generational family travel segments favoring connecting room configurations.
Asia-Pacific Luxury Hotel Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in Asia-Pacific luxury hospitality. Consolidation concentrates around loyalty ecosystem scale and exclusive site control. Three archetypes dominate: global portfolio operators leveraging standardized procedures, ultra-luxury specialists maintaining rate integrity through scarcity positioning, and design-forward boutique houses emphasizing localized aesthetic programming. Competitive moves center on loyalty ecosystem leverage and deliberate room count constraints defending margin per available room.
Within the ultra-luxury tier, Aman Group S.a.r.l. and Mandarin Oriental International Ltd exemplify scarcity-driven positioning. Aman anchors rate integrity through deliberately limited room counts and exclusive site control. Mandarin Oriental occupies premium positioning in Bangkok and Singapore through food and beverage programming differentiation. Marriott International represents the integrated leader archetype, leveraging Bonvoy loyalty ecosystems to sustain repeat visitation in Maldives and Phuket markets.
| Leading Market Players |
|---|
| Hyatt Hotels Corp. |
| Four Seasons Hotels Ltd. |
| Hilton Worldwide Holdings Inc. |
| Aman Group S.a.r.l. |
| Mandarin Oriental International Ltd |
| Marriott International |
| InterContinental Hotels Group PLC |
| Hotel Okura Co. Ltd. |
| Accor SA |
| Others |
Value Chain & Pricing Dynamics
Capacity utilization disparities between established gateway cities and emerging secondary corridors concentrate pricing power among operators with exclusive site control in Bali's Uluwatu and Maldives atolls. Scale economies in integrated resort development compress per-unit land costs while vertical design solutions preserve rate premiums against Thailand's coastal construction setbacks.
Pricing Analysis
Rate spreads between Tokyo's financial district properties and Vietnam's Da Nang corridor exceed threefold, with ultra-luxury tiers commanding premiums through deliberate room count constraints. Three-tier pricing structure across ultra-luxury, full-service, and limited-service levels differentiates on concierge depth and chef-led F&B programming. Cost compression in full-service tiers intensifies as multilingual labor shortages in Thailand and Indonesia force wage escalation. Corporate travel segments exhibit highest price sensitivity, while family office travelers from Singapore and Hong Kong prioritize exclusive member rates over aggregator convenience.
Supply Chain Analysis
Inventory lead times for imported marble, specialty timber, and bespoke furnishings extend development cycles across Southeast Asia's luxury pipeline. Supply concentrates in Italy, Indonesia, and India for finishes and millwork, with Japanese fixtures commanding premium positioning in Tokyo and Osaka refurbishment projects. Single-source vulnerability runs through artisanal craft networks for regionally authentic interiors. Distribution runs through direct procurement relationships with property developers, bypassing wholesale intermediaries for ultra-luxury specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The severe shortage of multilingual hospitality management graduates across Thailand, Vietnam, and Indonesia has compressed development timelines and elevated labor costs, creating competitive advantage for operators with established training pipelines and retention architectures.
For Market Incumbents: Secure exclusive site control in Bali's Nusa Dua corridor and Maldives atolls before coastal construction limits tighten further. Anchor rate integrity through deliberate room count constraints against dilution from overbuilt full-service supply in gateway cities. Deepen backward integration into chef-led culinary programming to defend margin contribution per available room. For New Entrants and Emerging Players: Anchor in Vietnam's Da Nang and Nha Trang corridors where infrastructure gaps present first-mover positioning for integrated resort operators. Target multi-generational family travel segments favoring connecting room configurations and activity programming. Pursue direct booking channel development through property-specific loyalty ecosystems rather than OTA dependency. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors operators with mobile-first service architecture and AI-curated experience recommendations. Long-term viability hinges on wellness amenity expansion compliant with Australia's Therapeutic Goods Administration standards. Watch for inflection signals in Japan's METI directive enforcement accelerating legacy asset refurbishment demand.| Strategic Initiative | Industry Significance |
|---|---|
| Exclusive Site Acquisition | Thailand's coastal setbacks redirect capital toward compliant hillside developments in Phuket and Krabi. |
| Chef-Led F&B Programming | Mandarin Oriental's Bangkok differentiation demonstrates margin capture through culinary destination positioning. |
| Loyalty Ecosystem Expansion | Marriott's Bonvoy redemption models sustain repeat visitation in Maldives and Phuket resort markets. |
| Wellness Amenity Certification | Australia's TGA compliance creates differentiation pathways for health-conscious property programming. |
| Multilingual Talent Pipeline | Development timeline compression in Vietnam and Indonesia rewards established hospitality training investments. |
Study Parameters
A spread of perspectives from resort development executives, revenue management directors, culinary concept leads, and environmental compliance officers converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation through tourism ministry filings, customs records for imported finishes, and METI energy efficiency directive documentation. Bottom-up property-level data triangulated against top-down regional demand modeling across the analysis window.
Segmentation dimensions modeled include hotel type, property size tier, service configuration, and target audience archetype throughout the forecast period. CAGRs derived from demand elasticity analysis against visa liberalization corridors and family office travel spend concentration. Forecast inputs incorporated refurbishment cycle timing from Japan's regulatory framework and coastal construction setback enforcement patterns across Thailand's resort zones.
Decision-makers should treat outputs as directional under assumptions of sustained wealth concentration in Singapore, Hong Kong, and Sydney; material deviation in mainland Chinese outbound travel recovery would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hotels and Resorts
Spa Resorts Market
Hotels and Resorts
Philippines Tourism and Hotel Market
Hotels and Resorts
Spain HRI Market
Hotels and Resorts
Europe Luxury Hotel Market
Hotels and Resorts
Hotels, Resorts, and Cruise Lines Market
Hotels and Resorts
India Luxury Hotel Market
Hotels and Resorts
Hotel Armchair Market
Hotels and Resorts
Germany HRI Market
Hotels and Resorts
Hotel Furniture and Furnishing Market
Hotels and Resorts
Morocco Tourism and Hotel Market
Hotels and Resorts
Global Floating Hotels Market
Hotels and Resorts
Global Beach Hotels Market
Hotels and Resorts
Morocco Tourism Market
Hotels and Resorts
Cuba Tourism and Hotel Market
Hotels and Resorts
Morocco Hospitality Market
Hotels and Resorts
Boutique Hotels Market