
 Europe Luxury Hotel Market | 2026-2036
Europe Luxury Hotel Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Luxury Hotel Market Foresight
The capital-intensity divergence between asset-heavy owners and light operators is rotating competitive advantage toward brands with proprietary development pipelines. Marriott International leverages its Bonvoy ecosystem to sustain direct booking share across European gateway cities. Accor anchors its position through the Orient Express and Raffles portfolios, competing on heritage narrative rather than room count alone.
Europe luxury hotels constitute premium lodging assets delivering personalized service, distinctive architecture, and curated experiential programming at price points exceeding four hundred euros per night. Properties typically integrate fine dining venues, spa facilities, and concierge services within buildings averaging fifty to two hundred keys. Boutique and heritage categories command the deepest rate premiums due to supply constraints in protected historic centers. Wellness programs within the service offering dimension represent the fastest-expanding margin pool as guest stays lengthen for health-focused retreats.
The EU Green Deal and national building codes under EMAS oversight are mandating carbon disclosure and energy performance upgrades across pre-1945 building stock. GDPR compliance shapes guest data handling for personalized marketing, while CE marking requirements affect imported furnishings and fixtures. Stakeholders must weigh retrofit timelines against rate recovery mechanics as regulatory thresholds tighten without grandfathering existing assets.
Market Dynamics
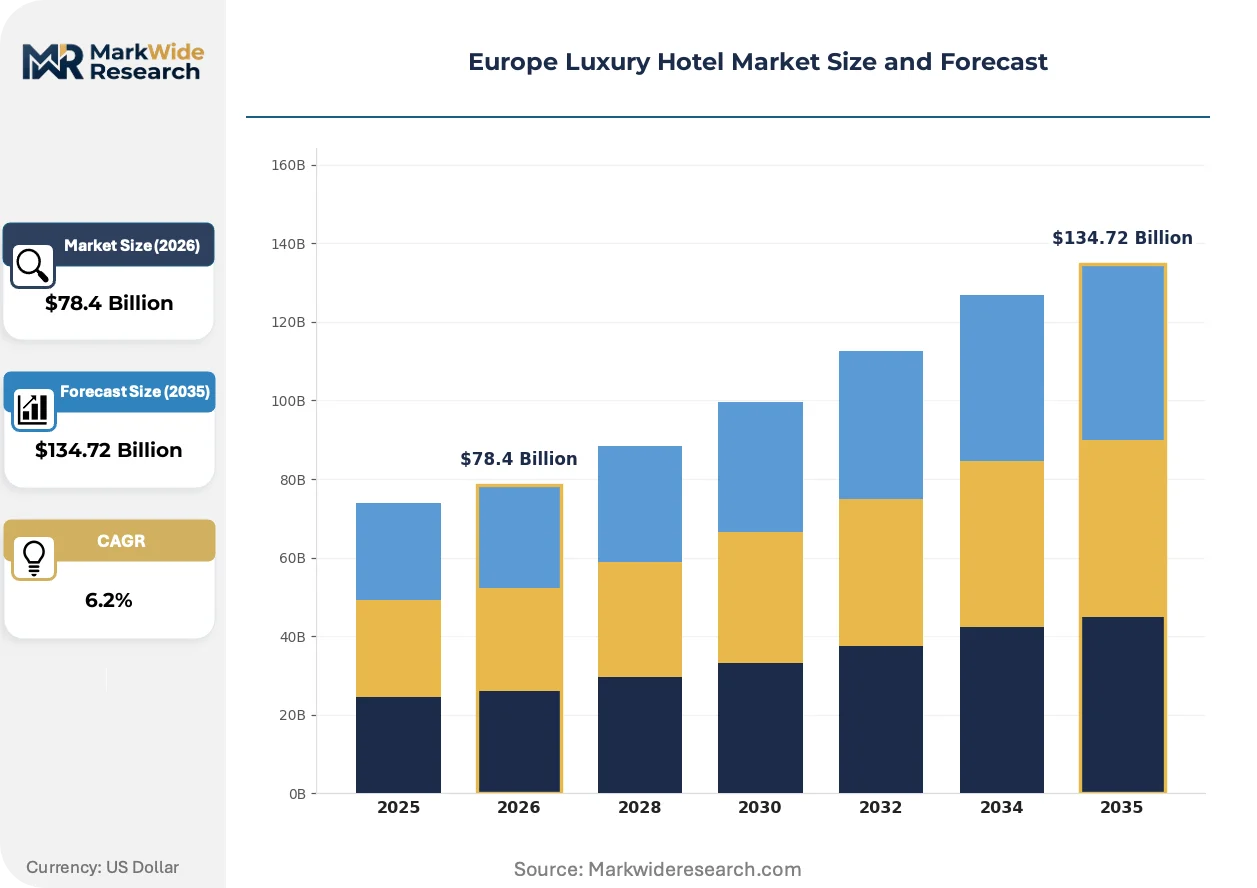
The EU Green Deal's building renovation mandates are forcing capital reallocation across Europe's historic palace hotel stock, compressing renovation timelines while elevating compliance costs for pre-1945 assets. Owners must now sequence energy retrofits against rate recovery mechanics without grandfathering protections.
Growth Catalysts
- EU Green Deal retrofit mandates:The regulation accelerates capital deployment into energy-efficient building systems across protected historic centers, creating first-mover advantages for compliant properties.
- Gulf state leisure travel extension:Affluent travelers from Saudi Arabia and the UAE are lengthening average stays at Mediterranean coastal properties, deepening ancillary revenue pools.
- Wellness programming integration:Health-focused retreat offerings expand margin contribution as guest stays lengthen for specialized spa and medical wellness experiences.
Market Restraints
- Labor cost escalation:Specialized hospitality talent shortages in Paris, Milan, and Zurich compress operating margins for personalized service delivery.
- Heritage building supply constraints:Protected historic center zoning limits new construction permits in Rome, Venice, and Vienna, capping inventory expansion.
- GDPR compliance friction:The regulation complicates guest data utilization for personalized marketing, increasing operational overhead.
Strategic Opportunities
- CEE underpenetration:Prague, Budapest, and Warsaw offer white-space positioning for heritage conversion projects at lower entry multiples than Western capitals.
- CSRD disclosure alignment:The directive rewards early ESG metric transparency with preferential capital access from EU institutional investors.
- Direct booking channel expansion:Proprietary loyalty ecosystems reduce OTA commission exposure across gateway city properties.
Industry Challenges
- Skilled artisan scarcity:Restoration specialists for Baroque and Belle Époque architectural elements command premium wages, extending renovation timelines.
- EMAS certification complexity:The framework's site-specific environmental audit requirements strain operational bandwidth for multi-property portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Luxury Hotel Market |
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $134.72 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Hotel Type: Boutique, Resort, Casino, Heritage, Spa, Palazzo Guest Demographic: Affluent Leisure, Business Executives, Celebrity Travelers, VIP Guests, Honeymooners, Diplomats Service Offering: Personalized Concierge, Gourmet Dining, Wellness Programs, Private Transfers, Cultural Experiences, Exclusive Events Booking Channel: Direct Website, Luxury Travel Agencies, Global Distribution Systems, Corporate Travel Planners, Upscale Tour Operators, Mobile Apps |
| Companies Covered | IHG Hotels & Resorts, Hyatt Hotels Corporation, Marriott International, Mandarin Oriental Hotel Group, Corinthia, Hilton Worldwide, Wyndham Hotels & Resorts, Zannier Hotels, Accor, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Luxury Hotel Market Shifts & Advancements
Technology deployment and regulatory disclosure requirements are restructuring competitive advantage across Europe's luxury hospitality sector. Three forces merit particular attention.
Artificial intelligence-powered revenue management systems are fragmenting traditional rate-setting hierarchies across European palace properties. Independent boutique operators in Lisbon and Porto adopt cloud-native pricing algorithms faster than legacy groups, compressing the yield management capability gap between asset-light and asset-heavy competitors.
CSRD corporate sustainability reporting obligations now mandate granular carbon disclosure from hospitality groups with EU listings. The regulation forces standardized ESG metric collection across scattered property portfolios, with French and Italian heritage assets facing the steepest data infrastructure buildout requirements.
Guest booking behavior is rotating toward extended-stay wellness retreats over traditional short leisure breaks. Alpine corridor properties in Switzerland and Austria capture this shift through multi-night medical spa packages, displacing conventional weekend city-break positioning in revenue mix priorities.
Europe Luxury Hotel Market Segmentation
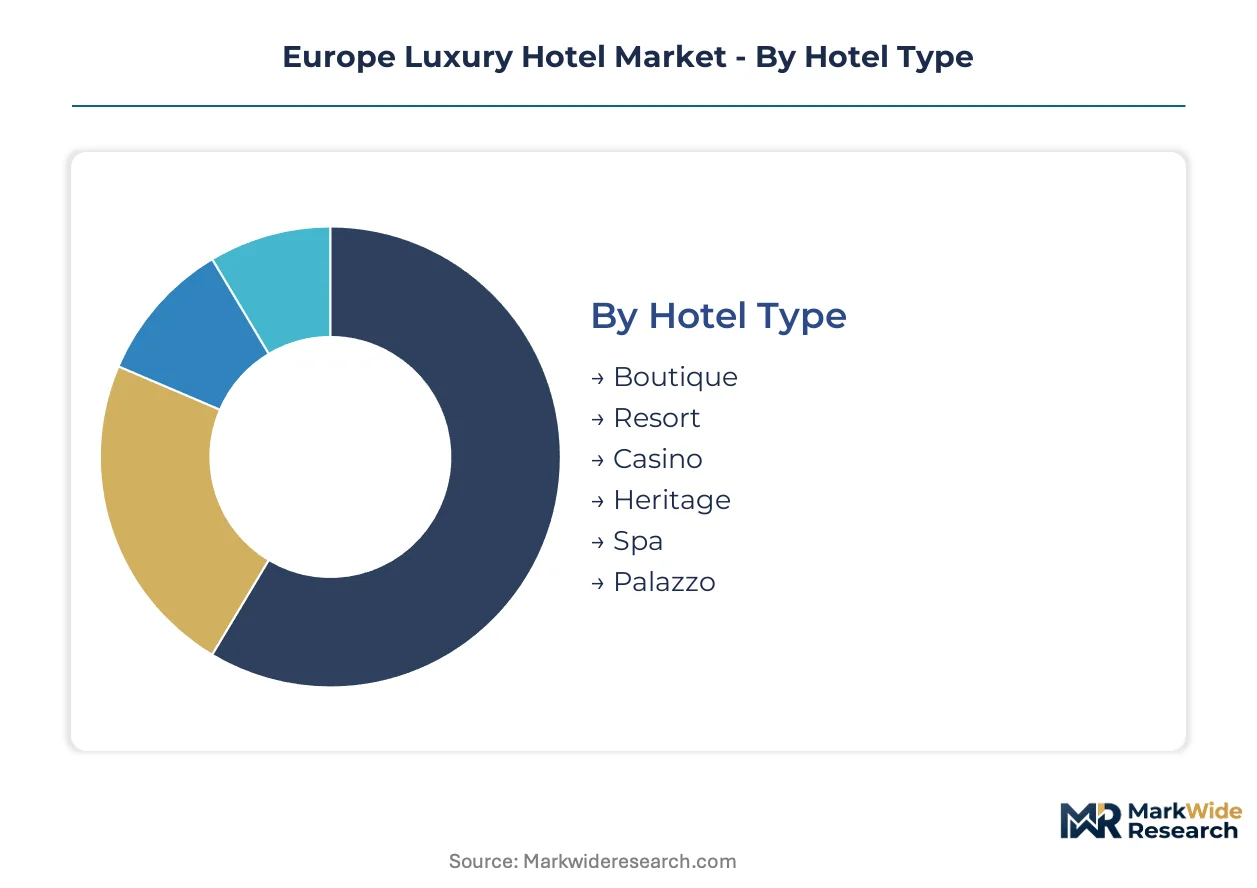
Segmentation in Europe's luxury hotel market reveals how regulatory frameworks and guest expectations fragment revenue streams across distinct operational models. Understanding these divisions clarifies where capital deployment yields compliance advantages alongside rate premiums.
Hotel Type:
EU Green Deal energy performance mandates and heritage preservation codes create divergent compliance burdens across property categories, reshaping investment attractiveness.
- Boutique:Intimate properties with fifty keys or fewer emphasize design-forward aesthetics and hyper-localized service protocols. Demand concentrates in Lisbon and Porto's historic districts where protected zoning limits competitive supply expansion.
- Resort:Coastal and Alpine properties integrating extensive recreational facilities command extended-stay premiums. Mediterranean coastal assets in France and Italy capture lengthening Gulf state leisure itineraries, deepening ancillary spend per guest.
- Casino:Gaming-integrated hospitality complexes operate under national gambling authority oversight with specialized licensing requirements.
- Heritage:Converted palaces and monasteries in protected historic centers face EMAS audit complexity alongside renovation timeline pressures.
- Spa:Medical wellness-focused properties in Switzerland and Austria are climbing the fastest as health retreat demand displaces traditional city-break positioning.
- Palazzo:Aristocratic residences transformed into hospitality assets carry Baroque restoration specialist scarcity and extended artisan procurement cycles.
Established volume favors Heritage; emerging adoption favors Spa.
Guest Demographic:
Rate recovery mechanics and service intensity requirements vary sharply by guest origin and trip purpose, determining staffing models and amenity investment.
- Affluent Leisure:High-net-worth individuals from Saudi Arabia and the UAE pursuing extended Mediterranean stays generate the deepest ancillary revenue pools through yacht charter arrangements and private villa bookings.
- Business Executives:Corporate travelers demand seamless connectivity and expedited check-in protocols at Paris and Zurich gateway properties.
- Celebrity Travelers:Discretion-focused guests requiring private entrances and security coordination command bespoke operational overhead.
- VIP Guests:State-visit level protocol demands specialized staff training and diplomatic liaison capabilities.
- Honeymooners:Amalfi Coast and Lake Como properties capture multi-night celebration itineraries with curated romantic experience packaging.
- Diplomats:Government protocol compliance and secure communications infrastructure differentiate this segment's facility requirements.
Revenue concentration sits with Affluent Leisure; service complexity peaks with Diplomats.
Service Offering:
Margin expansion potential and labor cost structures diverge materially across experiential programming categories, with regulatory touchpoints affecting data-enabled personalization.
- Personalized Concierge:GDPR compliance friction complicates guest preference tracking for predictive service anticipation, increasing operational overhead at multi-property portfolios.
- Gourmet Dining:Michelin-level kitchen operations in heritage buildings face CE marking requirements for imported equipment alongside strict fire safety codes.
- Wellness Programs:Medical spa and longevity retreat offerings in Swiss Alpine corridors represent the steepest expansion trajectory as guest stays lengthen for health-focused programming.
- Private Transfers:Chauffeur and aviation coordination services require transport licensing alignment across Schengen and non-Schengen jurisdictions.
- Cultural Experiences:Curated access to restricted heritage sites and private collections differentiates Mediterranean coastal positioning.
- Exclusive Events:Wedding and celebration hosting demands specialized insurance and noise ordinance navigation in protected historic centers.
Labor intensity peaks with Personalized Concierge; margin contribution climbs fastest through Wellness Programs.
Booking Channel:
Commission structures and guest data ownership rights fragment distribution economics, with direct channel investment reducing OTA dependency.
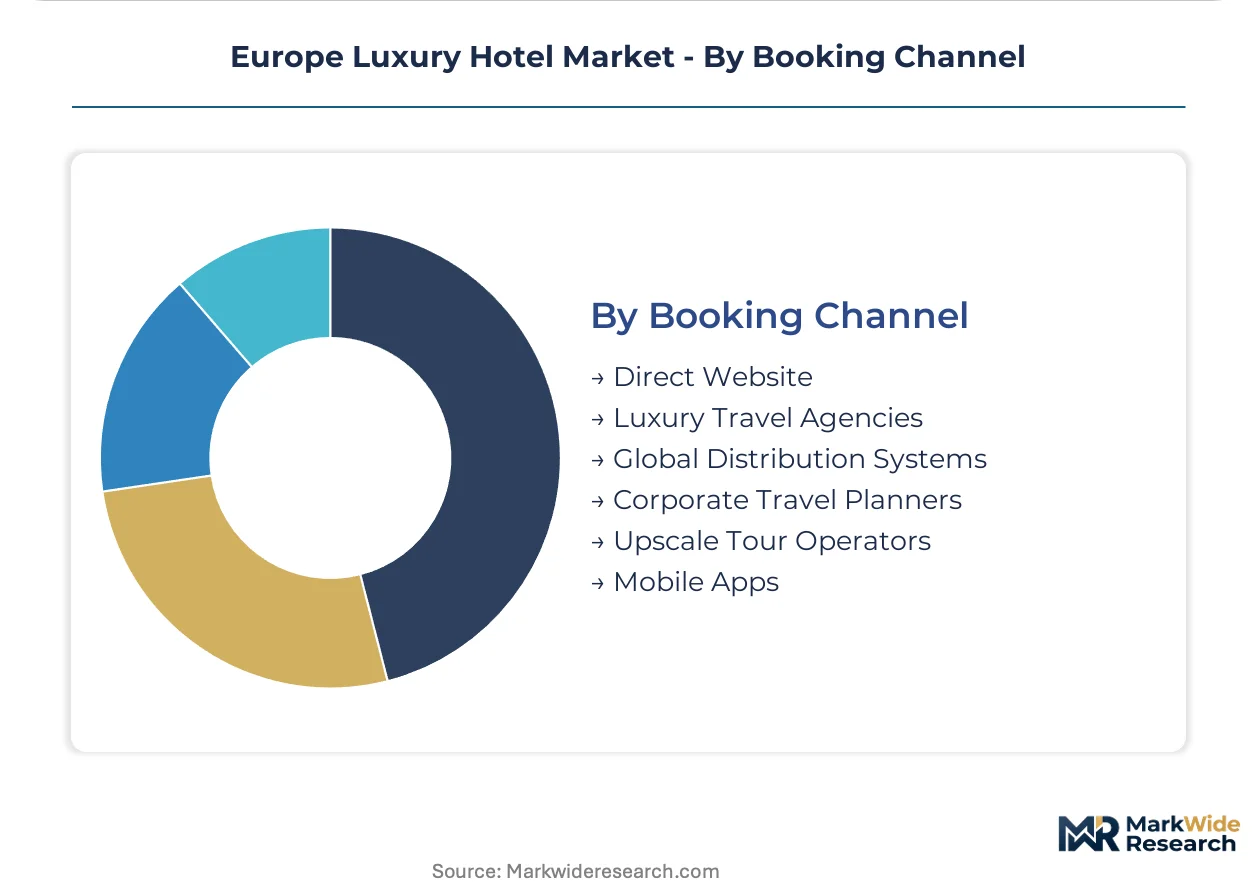
- Direct Website:Proprietary loyalty ecosystems at Marriott and Accor properties reduce third-party commission exposure while capturing full guest data for GDPR-compliant personalization.
- Luxury Travel Agencies:High-touch advisors specializing in ultra-high-net-worth itineraries command substantial commission premiums but deliver extended-stay bookings.
- Global Distribution Systems:Sabre and Amadeus connectivity remains essential for corporate travel manager procurement workflows.
- Corporate Travel Planners:Negotiated rate agreements with multinational headquarters drive volume at Frankfurt and London financial district properties.
- Upscale Tour Operators:Packaged itinerary providers concentrate demand in CEE heritage conversion projects at Prague and Budapest.
- Mobile Apps:Proprietary booking applications face App Store compliance requirements and data localization rules under GDPR.
Commission efficiency favors Direct Website; booking value concentration sits with Luxury Travel Agencies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across European luxury corridors. Gulf state leisure travelers demonstrate low sensitivity at Mediterranean coastal properties, while corporate segments in Frankfurt and London show moderate elasticity during economic uncertainty. Heritage conversion premiums in protected historic centers sustain inelastic demand regardless of macro conditions.
France
Affluent leisure demand concentrates along the Côte d'Azur and Paris, with Gulf state travelers extending average stays at coastal palace properties. The EU Green Deal's building renovation mandates accelerate capital deployment into energy-efficient retrofits across pre-1945 assets in the capital. Parisian heritage properties face compressed renovation timelines without grandfathering protections as EMAS audit requirements tighten.
Italy
Lake Como and Amalfi Coast properties capture lengthening honeymoon and celebration itineraries from North American and Middle Eastern source markets. GDPR compliance friction complicates guest data utilization for personalized concierge services at multi-property portfolios. Milanese and Venetian heritage assets confront skilled artisan scarcity for Baroque restoration elements, extending procurement cycles.
Switzerland
Alpine corridor medical wellness retreats displace traditional weekend city-break positioning as guest stays lengthen for health-focused programming. Swissmedic oversight shapes facility licensing for spa and longevity treatment offerings. Zurich and Geneva gateway properties sustain direct booking share through proprietary loyalty ecosystems reducing OTA commission exposure.
United Kingdom
Corporate travel demand at London financial district properties fluctuates with multinational headquarters procurement cycles. CSRD disclosure obligations mandate granular carbon reporting from hospitality groups with EU listings. Scottish and English countryside heritage conversions attract extended-stay wellness programming investment at lower entry multiples than capital assets.
Spain
Mediterranean coastal properties in Barcelona and the Balearics capture Gulf state leisure extension trends deepening ancillary revenue pools. CE marking requirements affect imported furnishings and fixtures for heritage building renovations. Andalusian palace conversions face EMAS certification complexity alongside labor cost escalation for personalized service delivery.
Europe Luxury Hotel Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across Europe's luxury hospitality sector. Asset-heavy owners with proprietary development pipelines compete against asset-light operators leveraging cloud-native revenue management systems. Three archetypes dominate: heritage narrative specialists, scale-driven loyalty ecosystem operators, and boutique design-forward independents. Competitive moves concentrate on direct booking channel expansion and ESG disclosure alignment for preferential capital access.
Within the heritage narrative tier, Mandarin Oriental Hotel Group and Corinthia exemplify properties competing on distinctive architecture and curated experiential programming rather than room count alone. Zannier Hotels occupies a position among design-forward boutique operators emphasizing hyper-localized service protocols. These three entities represent divergent strategic positioning across the boutique-resort-heritage segmentation, each anchoring distinct guest demographic and service offering combinations without overlapping footprint concentration.
| Leading Market Players |
|---|
| IHG Hotels & Resorts |
| Hyatt Hotels Corporation |
| Marriott International |
| Mandarin Oriental Hotel Group |
| Corinthia |
| Hilton Worldwide |
| Wyndham Hotels & Resorts |
| Zannier Hotels |
| Accor |
| Others |
Supply & Pricing Matrix
Long-term offtake agreements between heritage palace owners and specialized artisan workshops lock in restoration capacity while fixing labor cost visibility across multi-year renovation cycles. These contracts insulate EMAS-compliant properties from wage escalation for Baroque specialists in Italy and France, embedding supply security directly into capital planning.
Pricing Analysis
Ancillary revenue from extended-stay wellness programming drives lifetime value per guest beyond room-rate capture. Three-tier pricing structure across palace, heritage, and boutique tiers separates rate premiums based on EMAS certification status and protected historic center location. Cost compression in standard-tier properties intensifies as OTA commission burdens rise, while Gulf state leisure travelers at Mediterranean coastal assets demonstrate lowest price sensitivity. Corporate travel managers at Frankfurt and London gateway properties negotiate hardest on negotiated rate agreements.
Supply Chain Analysis
Italy and France anchor specialized artisan production for Baroque and Belle Époque restoration elements, while Switzerland concentrates medical wellness equipment manufacturing. Historic palace renovations draw from scarce marble quarries in Carrara, hand-blown glass from Murano, and bespoke textile ateliers in Lyon. Single-source vulnerability sits with master artisan retirement pipelines lacking apprentice succession. Distribution runs through white-glove logistics specialists coordinating just-in-time delivery to protected historic centers with restricted vehicle access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is rotating toward asset-light operators with cloud-native revenue management capabilities as direct booking channel investment fragments OTA dependency. Consolidation among independent boutique properties in Lisbon and Porto accelerates this shift.
For Market Incumbents: Consolidate proprietary loyalty ecosystem depth to reduce third-party commission exposure across gateway city properties. Acquire specialized wellness programming capabilities in Swiss Alpine corridors before independent medical spa operators scale. Vertical integration into artisan workshop partnerships secures restoration capacity against skilled labor scarcity.
For New Entrants and Emerging Players: Differentiate on hyper-localized heritage narrative rather than room count, targeting CEE white-space in Prague and Budapest where entry multiples sit below Western capitals. Position within spa and wellness segments where guest stay lengthening deepens ancillary revenue pools. Pursue EMAS pre-certification to accelerate capital access from EU institutional investors prioritizing CSRD alignment.
For Investors and Strategic Acquirers: Heritage conversion specialists with established EMAS compliance infrastructure and protected historic center positioning offer longest-horizon viability as regulatory thresholds tighten without grandfathering. Monitor Gulf state leisure travel booking patterns as early inflection signal for Mediterranean coastal rate recovery mechanics. Recalibration cycles align with EU Green Deal enforcement milestones and CSRD disclosure deadlines.
| Strategic Initiative | Industry Significance |
|---|---|
| Direct Booking Channel Expansion | Marriott's Bonvoy ecosystem reduces OTA commission exposure across Paris and Zurich properties. |
| EMAS Pre-Certification Investment | Early compliance secures preferential capital access from EU institutional investors ahead of CSRD deadlines. |
| Wellness Programming Integration | Swiss Alpine medical spa packages capture guest stay lengthening trends displacing city-break positioning. |
| Heritage Artisan Partnership | Long-term workshop contracts lock in Baroque restoration capacity against specialist wage escalation in Milan. |
| CEE Geographic Expansion | Prague and Budapest conversions exploit lower entry multiples than Côte d'Azur or Lake Como assets. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EU building registry databases, EMAS certification records, and hospitality group ESG disclosures. Primary interviews engaged asset managers at heritage palace portfolios, revenue directors at gateway city properties, and procurement leads for restoration specialists. Secondary sources encompassed CE marking documentation, GDPR compliance frameworks, and EU Green Deal implementation timelines. Bottom-up property-level analysis triangulated against top-down regional demand modeling.
Segmentation dimensions modeled include hotel type, guest demographic origin, service offering intensity, and booking channel across the analysis window. CAGRs derived from property pipeline tracking, renovation timeline assumptions, and rate recovery mechanics under regulatory compliance burdens. Forecast inputs incorporated Gulf state travel extension patterns and EMAS audit complexity scores for pre-1945 building stock.
Material uncertainties — EU Green Deal enforcement acceleration, artisan labor strike actions, Gulf state travel policy shifts — sit outside the modeled envelope. Forecasts reflect assumptions on renovation timeline compression and rate pass-through elasticity. Recalibration cycles align with material shifts in EMAS certification thresholds and CSRD disclosure granularity requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hotels and Resorts
United Kingdom HRI Market
Hotels and Resorts
Morocco Hospitality Market
Hotels and Resorts
Morocco Tourism and Hotel Market
Hotels and Resorts
Germany HRI Market
Hotels and Resorts
Five Star Hotel Market
Hotels and Resorts
North America Luxury Hotel Market
Hotels and Resorts
Cuba Tourism and Hotel Market
Hotels and Resorts
Global Floating Hotels Market
Hotels and Resorts
Boutique Hotels Market
Hotels and Resorts
United States Luxury Hotel Market
Hotels and Resorts
Morocco Tourism Market
Hotels and Resorts
Philippines Tourism and Hotel Market
Hotels and Resorts
Hotels, Resorts, and Cruise Lines Market
Hotels and Resorts
Hotel Armchair Market
Hotels and Resorts
Mountain and Ski Resorts Market
Hotels and Resorts
Global Beach Hotels Market