
 Spa Resorts Market | 2026-2036
Spa Resorts Market Size, Share, and Industry Trends Forecast 2026-2036
Spa Resorts Market Analytics
The EU Green Deal is expanding requirements for carbon-neutral thermal operations across European spa destinations, compelling property-level retrofits of geothermal and solar water systems. Lanserhof Lans leverages its Austrian alpine location to sustain year-round thermal therapy demand through integrated medical programming. Six Senses anchors its competitive position through controlled supply chains for organic treatment products across Asian and Mediterranean properties. Palace Merano differentiates via specialized longevity diagnostics that occupy a narrow premium tier in Northern Italy.
Spa resorts are hospitality properties delivering therapeutic water-based treatments, wellness programming, and beauty services through purpose-built thermal, mineral, or seawater facilities operating at controlled temperatures and mineral compositions. These properties serve medical tourism, preventive health, and leisure recovery functions for paying guests across multi-day stays. Luxury spas command the deepest margin pools due to extended average lengths of stay and high ancillary capture rates on wellness programs. Health retreats represent the fastest-growing facility type as post-pandemic travelers prioritize immunity-focused, residential-format programming over traditional relaxation sessions.
EMA guidelines on wellness claims and EU Green Deal carbon benchmarks shape permissible service marketing and facility energy standards across European properties, while FDA oversight of medical device classifications in the United States determines which diagnostic and treatment modalities qualify for insurance-adjacent reimbursement. Thailand's Ministry of Public Health coordinates with tourism authorities to license integrative wellness operators under national quality standards. Stakeholders must monitor how regulatory divergence between medical-grade and leisure-grade spa classifications reshapes capital allocation across treatment portfolios.
Market Dynamics
Medical tourism from North American corporate clients is redirecting capital toward destination wellness properties with integrated diagnostic capabilities, while EU Green Deal carbon benchmarks force simultaneous facility retrofits. This dual pressure compresses operator margins even as top-line demand expands.
Growth Catalysts
- EMA wellness claim guidelines:Clarified marketing boundaries for preventive health programming enable European properties to bundle medical-adjacent services with leisure stays.
- Thailand's integrative wellness licensing:Ministry of Public Health quality standards attract premium international bookings to Koh Samui island clusters.
- Geothermal retrofitting:Alpine properties leverage natural thermal resources to meet decarbonization mandates without operational disruption.
Market Restraints
- Energy input volatility:Thermal water heating systems face cost pressure from natural gas price swings, directly impacting operating margins at mineral spring properties.
- Supply concentration in organic treatment inputs:Controlled supply chains for certified botanical ingredients limit formulation flexibility across Asian and Mediterranean properties.
- FDA medical device classification friction:Diagnostic modality restrictions in the United States block insurance-adjacent reimbursement for longevity assessment tools.
Strategic Opportunities
- CSRD reporting mandates:European operators capturing verified carbon data from thermal retrofits can access sustainability-linked financing instruments.
- Residential-format immunity programming:Health retreats offering multi-day residential stays address post-pandemic preference shifts away from session-based relaxation.
- AI-driven personalization:Convergence of biometric monitoring and treatment customization enables premium tier differentiation at Northern Italian diagnostic facilities.
Industry Challenges
- Specialized hydrotherapy technician scarcity:Mineral composition analysis and thermal pool management require certified skills with limited training pipeline capacity.
- Legacy booking system integration:Property management platforms struggle to coordinate medical programming schedules with traditional hospitality reservations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spa Resorts Market |
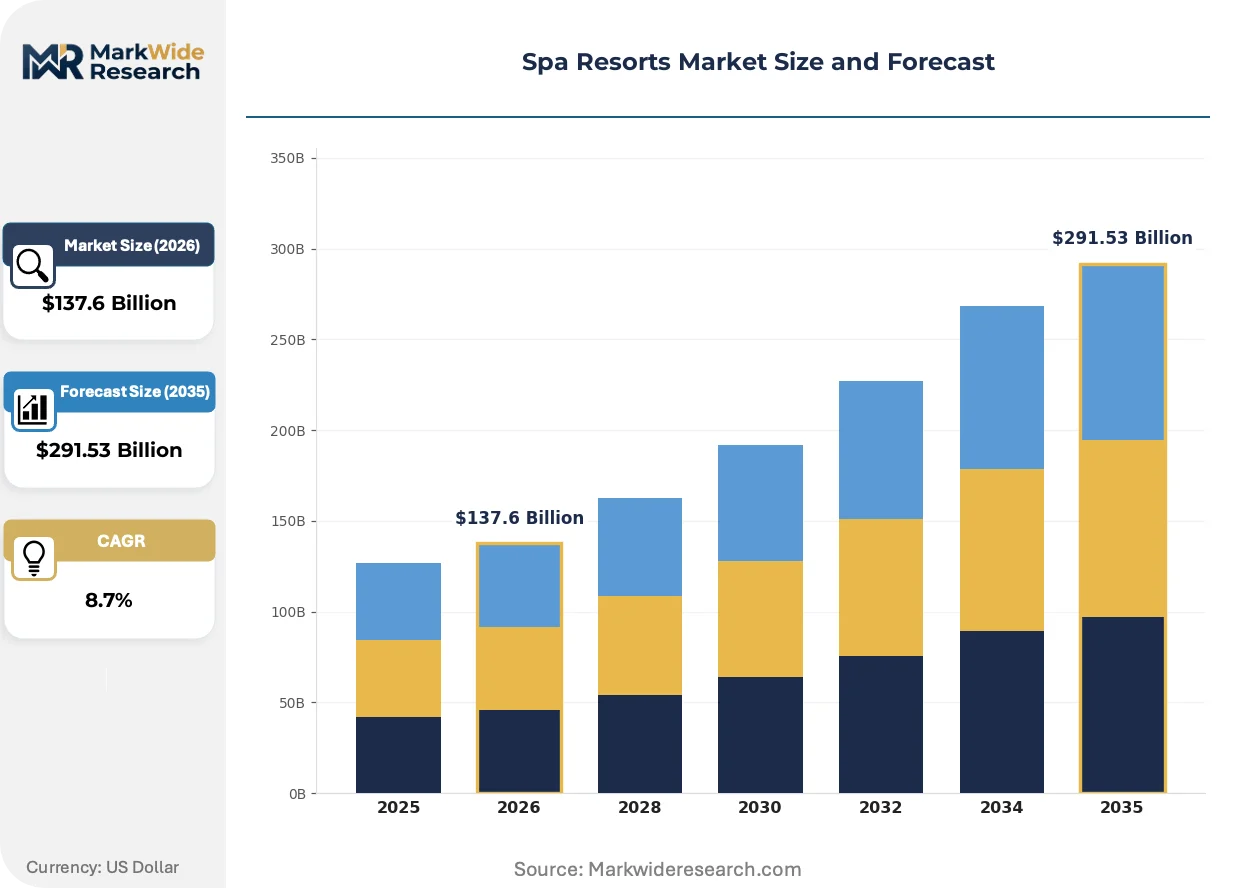
| Market Size in 2026 | $137.6 Billion |
| Market Size in 2035 | $291.53 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Therapeutic Treatments, Relaxation Sessions, Beauty Services, Wellness Programs Facility Type: Luxury Spas, Boutique Resorts, Health Retreats, Day Spas Target Audience: Corporate Clients, Couples, Wellness Seekers, Tourists Pricing Tier: Premium, Mid-Range, Budget, Luxury |
| Companies Covered | Lanserhof Lans, Six Senses, Kamalaya Koh Samui, Palace Merano, Minos Palace, RAKxa Integrative Wellness, Clinique La Prairie, Abano Grand Hotel, Villa Eden The Private Retreat, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spa Resorts Market Evolving Landscape
Properties are reconfiguring around residential-format programming and carbon-verified operations, displacing traditional session-based service models. This structural pivot favors operators with captive thermal resources and integrated medical licensing.
Biometric monitoring systems are absorbing guest data streams from wearable devices to customize treatment protocols in real time. Luxury properties in Austria and Switzerland deploy these tools to extend average lengths of stay through personalized programming. The technology is absorbing guest expectations for measurable wellness outcomes, compressing demand for generic relaxation packages.
EU Green Deal carbon benchmarks are mandating facility-level energy audits and verified decarbonization roadmaps for thermal operations. European spa destinations must retrofit geothermal and solar water heating systems or face marketing restrictions. Alpine properties with natural thermal access are responding fastest, while urban thermal spas face capital-intensive equipment replacement cycles.
Corporate wellness procurement now specifies residential-format immunity and recovery programming over traditional relaxation sessions. Human resources departments at North American technology and financial services firms are contracting directly with destination properties for executive retreat packages. Thailand's licensed integrative wellness operators capture disproportionate share of this contracted demand through Ministry of Public Health quality certification.
Spa Resorts Market Segmentation
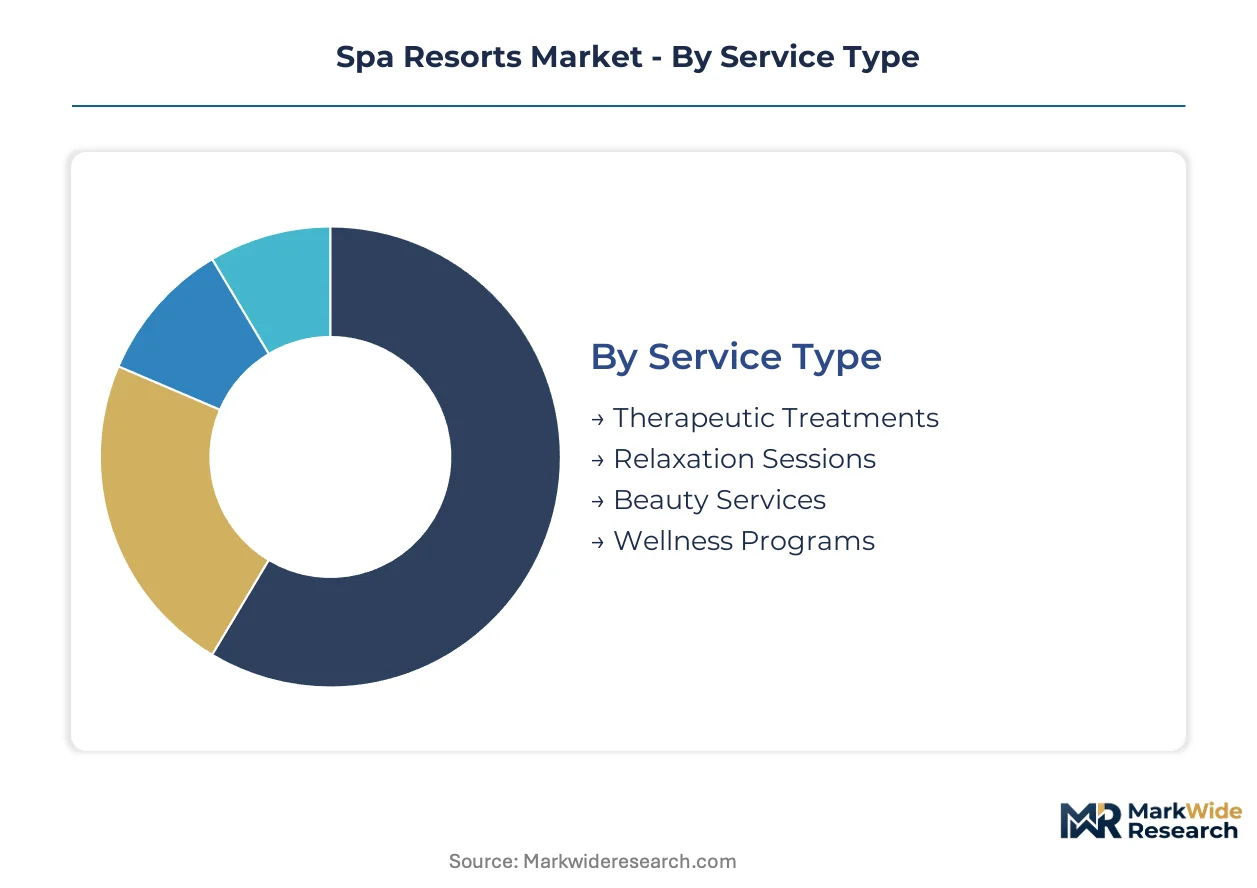
Service configuration and facility positioning determine margin capture in spa resorts. Operators must align thermal infrastructure investments with specific guest profiles to optimize occupancy rates and ancillary revenue per stay.
Service Type:
Guest selection hinges on outcome specificity—whether seeking clinical results, stress relief, aesthetic enhancement, or lifestyle transformation.
- Wellness Programs:Multi-day residential programming combines nutrition, movement, and diagnostic assessments into structured protocols. Demand concentrates at Thai integrative properties serving North American corporate retreat contracts, where Ministry of Public Health licensing validates quality claims and extends average length of stay.
- Therapeutic Treatments:Water-based interventions using controlled mineral compositions and temperatures address specific musculoskeletal or dermatological conditions. Alpine properties in Austria and Switzerland leverage natural geothermal access to sustain year-round demand from medical tourism segments seeking insurance-adjacent outcomes.
- Relaxation Sessions:Single-appointment services targeting stress reduction through massage and hydrotherapy.
- Beauty Services:Aesthetic treatments including skincare, body contouring, and anti-aging procedures.
Volume sits with Therapeutic Treatments; growth tilts toward Wellness Programs.
Facility Type:
Capital intensity and regulatory compliance requirements separate scalable operations from niche positioning.
- Health Retreats:Residential-format properties offering immersive programming across multiple days with integrated accommodation and clinical oversight. Post-pandemic traveler preference shifts favor immunity-focused stays over session-based alternatives, driving fastest expansion trajectory among facility categories.
- Luxury Spas:High-investment properties commanding extended stays through personalized service and premium amenities. EU Green Deal carbon benchmarks force simultaneous geothermal retrofits at European locations, compressing margins despite strong top-line performance.
- Boutique Resorts:Smaller-scale operations emphasizing localized treatment traditions and intimate service.
- Day Spas:Non-residential facilities providing single-visit services without accommodation integration.
Revenue concentrates at Luxury Spas; expansion accelerates most quickly at Health Retreats.
Target Audience:
Procurement channel and booking pattern distinguish commercial sustainability across guest segments.
- Corporate Clients:Contracted wellness procurement from North American technology and financial services firms specifies destination properties with diagnostic capabilities. Human resources departments negotiate direct executive retreat packages, favoring Thai licensed operators with Ministry of Public Health quality certification.
- Wellness Seekers:Individual travelers prioritizing preventive health outcomes and measurable biometric improvements. Biometric monitoring integration at Austrian and Swiss properties absorbs guest expectations for personalized programming, displacing generic relaxation demand.
- Couples:Paired travelers seeking shared relaxation and relationship-focused programming.
- Tourists:Leisure travelers incorporating spa services as ancillary vacation components.
Booking volume clusters with Tourists; value per reservation climbs fastest among Corporate Clients.
Pricing Tier:
Thermal infrastructure access and certification grade stratify attainable rate structures.
- Premium:Properties combining medical-adjacent programming with controlled supply chains for organic treatment inputs. Six Senses properties across Asian and Mediterranean locations sustain positioning through verified ingredient sourcing and extended-stay incentives.
- Luxury:Ultra-high-rate segment anchored by specialized longevity diagnostics and personalized protocol design. Palace Merano occupies narrow Northern Italian tier through AI-driven personalization and biometric customization capabilities.
- Mid-Range:Accessible properties balancing quality assurance with moderate pricing.
- Budget:Entry-level operations minimizing capital investment and service scope.
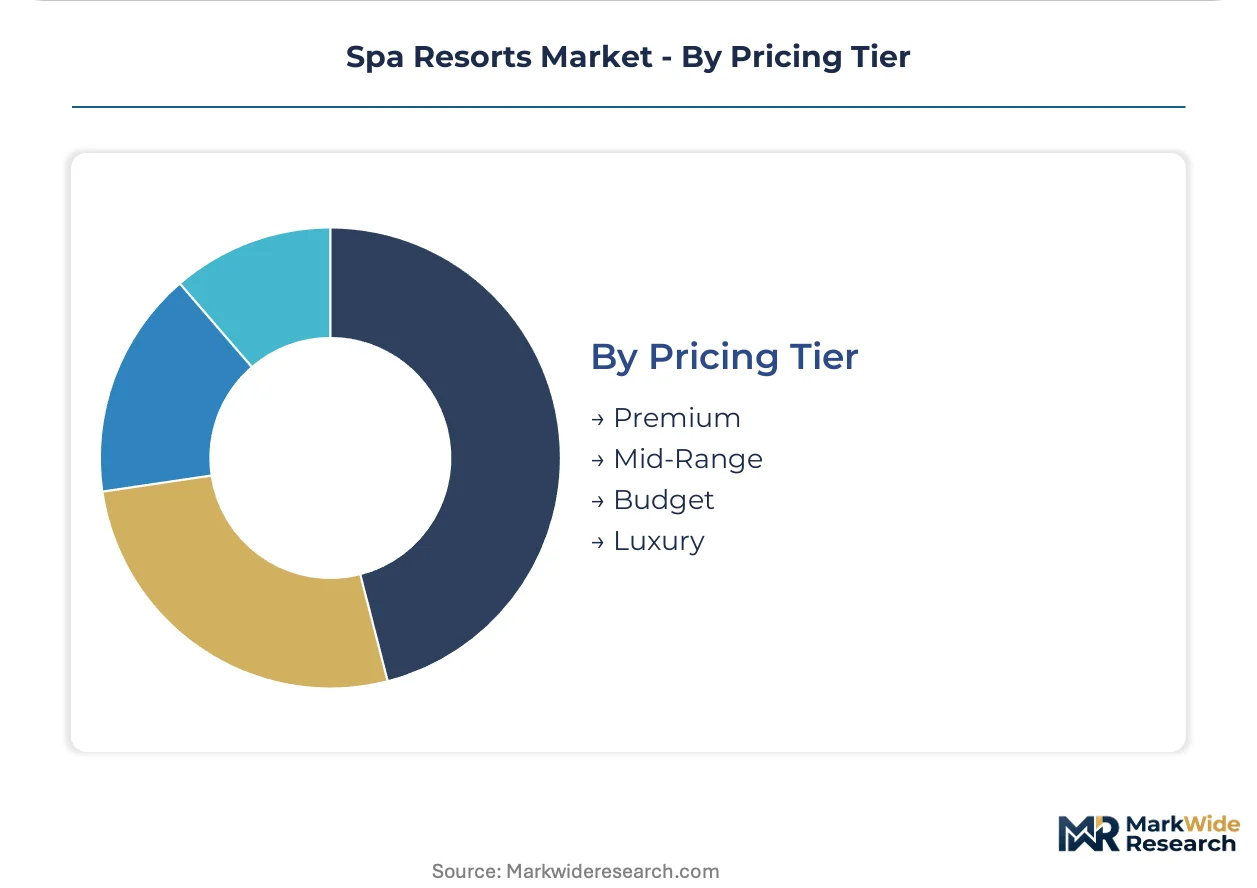
Margin depth peaks at Luxury; volume distribution favors Mid-Range.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Koh Samui's integrative wellness cluster anchors Southeast Asian demand, while European alpine thermal destinations and North American corporate retreat corridors complete the geographic spread across this hospitality segment.
Thailand
Ministry of Public Health licensing standards attract premium international bookings to Koh Samui island properties. Corporate wellness procurement from North American technology firms concentrates contracted demand at certified integrative operators. Thai regulators coordinate quality benchmarks with tourism authorities to validate medical-adjacent service claims.
Austria
Alpine thermal resources sustain year-round medical tourism demand through natural geothermal access. EU Green Deal carbon benchmarks mandate facility-level energy audits for thermal water heating systems. Lanserhof Lans leverages its Tyrol location to anchor premium-tier positioning through integrated medical programming.
Italy
Specialized longevity diagnostics occupy narrow premium positioning in Northern Italian thermal destinations. EMA wellness claim guidelines clarify marketing boundaries for preventive health bundling with leisure stays. Palace Merano exemplifies AI-driven personalization capabilities in the South Tyrol cluster.
Switzerland
Biometric monitoring integration extends average lengths of stay through personalized protocol design. Clinique La Prairie represents medical-grade positioning within the Swiss wellness corridor. Lake Geneva properties capture corporate retreat demand through diagnostic capability certification.
United States
FDA medical device classification friction blocks insurance-adjacent reimbursement for longevity assessment tools. Corporate human resources departments contract directly with destination properties for executive wellness packages. Domestic operators face diagnostic modality restrictions that compress service bundling flexibility compared to Asian and European competitors.
Spa Resorts Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification grade and thermal infrastructure access, creating a tiered structure where medical licensing and captive resource control determine rate attainment. The vendor base concentrates around destination properties with integrated diagnostic capabilities rather than session-based relaxation operators. Three archetypes dominate: alpine thermal medical resorts, Asian integrative wellness islands, and European longevity diagnostic clinics. Competitive moves center on geothermal retrofitting compliance and corporate wellness contract procurement.
Within the alpine medical resort archetype, Lanserhof Lans and Clinique La Prairie exemplify properties leveraging natural thermal access to sustain year-round demand. Six Senses anchors the Asian integrative tier through controlled supply chains across Mediterranean and Southeast Asian locations. Palace Merano occupies the narrow Northern Italian premium segment through specialized diagnostic positioning.
| Leading Market Players |
|---|
| Lanserhof Lans |
| Six Senses |
| Kamalaya Koh Samui |
| Palace Merano |
| Minos Palace |
| RAKxa Integrative Wellness |
| Clinique La Prairie |
| Abano Grand Hotel |
| Villa Eden The Private Retreat |
| Others |
Value Network & Pricing Analysis
Certified hydrotherapy technician scarcity in Austria and Switzerland widens pricing-tier spreads as labor-cost differentials between alpine medical resorts and urban day spas compress margin structures at mineral spring properties. EU Green Deal retrofit mandates amplify this divergence by concentrating compliant thermal capacity at premium-tier operators.
Pricing Analysis
Outcome-based pricing anchors rate structures at destination wellness properties, where biometric-verified programming commands premium positioning against session-based alternatives. Certification grade under EU Green Deal benchmarks and Ministry of Public Health licensing in Thailand stratify attainable rates, with carbon-verified thermal operations sustaining rate premiums. Cost compression in mid-range urban thermal spas intensifies due to natural gas price volatility in heating systems. Corporate procurement departments at North American technology firms exhibit lowest price sensitivity, while individual leisure tourists drive volume at budget tiers.
Supply Chain Analysis
Certification gating through EU Green Deal carbon benchmarks and Thailand's integrative wellness licensing restricts supplier qualification to properties with verified thermal retrofits or medical-adjacent service credentials. Organic botanical inputs draw from controlled cultivation networks in Thailand, India, and Mediterranean coastal zones. Mineral composition testing equipment and geothermal infrastructure components hinge on specialized manufacturing in Germany, Switzerland, and Japan. Single-source vulnerability concentrates in certified organic treatment formulations. Distribution runs through direct contracting between destination properties and corporate human resources departments, bypassing traditional hospitality aggregators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The spa resorts market functions as a cost-of-compliance story where EU Green Deal carbon benchmarks erect barrier-to-entry moats favoring operators with captive geothermal resources and verified decarbonization roadmaps.
For Market Incumbents: Cement defensive positioning through backward integration into organic botanical cultivation and geothermal infrastructure ownership. Alpine operators with natural thermal access should expand capacity in Tyrol and South Tyrol clusters before regulatory saturation. Threat of FDA diagnostic modality restrictions in North American markets compresses service bundling flexibility versus Asian and European competitors.
For New Entrants and Emerging Players: AI-driven personalization technology offers a technology-first wedge into the premium diagnostic tier where Palace Merano currently anchors narrow positioning. White-space targets include residential-format immunity programming for post-pandemic corporate retreat demand and biometric monitoring integration at mid-scale health retreats. Go-to-market through direct human resources procurement channels bypasses hospitality aggregator commission structures.
For Investors and Strategic Acquirers: Re-rating potential sits with EU Green Deal-compliant alpine thermal operators given sustainability-linked financing access and carbon-verified rate premiums. Long-term viability favors properties combining medical licensing with captive geothermal resources over session-based urban day spas. Signal to watch is corporate wellness procurement contract volume migrating from relaxation packages to diagnostic-integrated residential programming.
| Strategic Initiative | Industry Significance |
|---|---|
| Geothermal Retrofit Certification | EU Green Deal compliance unlocks sustainability-linked financing instruments for alpine thermal properties. |
| Biometric Monitoring Integration | Wearable data absorption extends average length of stay at Austrian and Swiss diagnostic facilities. |
| Corporate Wellness Direct Contracting | Human resources procurement bypasses aggregator commissions and anchors predictable occupancy. |
| Organic Supply Chain Captivity | Controlled botanical cultivation secures formulation flexibility against certified ingredient scarcity. |
| Integrative Wellness Licensing | Thailand's Ministry of Public Health certification validates medical-adjacent claims for premium positioning. |
Research Methodology
Document review covered regulatory filings from EMA and FDA, EU Green Deal implementation guidance, and Thailand Ministry of Public Health licensing standards, complemented by interviews with spa resort operations directors, corporate wellness procurement managers at North American technology firms, geothermal infrastructure engineers, and organic botanical supply chain coordinators. Secondary validation drew from hospitality industry association reports, thermal spring facility energy audits, and corporate human resources benefit expenditure disclosures. Bottom-up property-level capacity assessments and top-down segment demand modeling enabled triangulation.
Historical booking patterns at destination wellness properties were cross-referenced against panel input from corporate procurement departments and thermal facility operators. Segmentation dimensions modeled include service type, facility format, target audience procurement channel, and pricing tier certification grade. CAGRs were derived from demand elasticity analysis across medical tourism and corporate retreat segments. Forecast inputs incorporated EU Green Deal compliance timelines and biometric technology adoption curves at alpine diagnostic properties.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt natural gas price spikes or accelerated FDA diagnostic reclassification. Model assumptions reflect thermal infrastructure replacement cycles and corporate wellness budget allocation shifts. A model refresh is warranted upon material change in EU carbon benchmark enforcement or Thailand licensing standard revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hotels and Resorts
Hotel Armchair Market
Hotels and Resorts
Five Star Hotel Market
Hotels and Resorts
Morocco Hospitality Market
Hotels and Resorts
Hotels, Resorts, and Cruise Lines Market
Hotels and Resorts
Morocco Tourism and Hotel Market
Hotels and Resorts
Germany HRI Market
Hotels and Resorts
Europe Luxury Hotel Market
Hotels and Resorts
Philippines Tourism and Hotel Market
Hotels and Resorts
Hotel Furniture and Furnishing Market
Hotels and Resorts
Global Floating Hotels Market
Hotels and Resorts
Boutique Hotels Market
Hotels and Resorts
India Luxury Hotel Market
Hotels and Resorts
Morocco Tourism Market
Hotels and Resorts
North America Luxury Hotel Market
Hotels and Resorts
Mountain and Ski Resorts Market
Hotels and Resorts
Global Beach Hotels Market