
 Morocco Tourism Market | 2026-2036
Morocco Tourism Market Size, Share, and Industry Trends Forecast 2026-2036
Morocco Tourism Market Insights
Cultural enthusiasts is rotating toward premium guided experiences across Morocco's imperial cities and Sahara corridors. Royal Air Maroc anchors long-haul connectivity from North America and Europe into Casablanca's hub. Accor SA dominates the upscale hotel landscape with properties spanning Riads and beach resorts. Booking Holdings competes through platform aggregation of local tour inventory.
Morocco tourism encompasses destination services including accommodation, ground transportation, curated excursions, and dining experiences delivered across diverse physical and cultural landscapes spanning Atlantic coastline, Atlas Mountains, and desert ecosystems. The sector functions as an export-oriented services industry generating foreign exchange through visitor expenditure on lodging, activities, and domestic transport. Hotel accommodation captures the largest revenue pool among service types, while online platforms represent the fastest-growing booking channel as mobile penetration deepens. Cultural sites maintain the strongest visitor pull among attraction types, though natural wonders in the Anti-Atlas and coastal wetlands attract emerging adventure segments.
Morocco's Ministry of Tourism, Air Transport, Handicrafts, and Social Economy sets licensing standards for accommodation and guide services, while the National Office of Airports (ONDA) regulates aviation infrastructure capacity that gates visitor volumes. Environmental impact assessments under the Department of Water and Forests constrain development near protected argan forests and coastal zones. Stakeholders must weigh capacity investments against water scarcity constraints and seasonal demand spikes.
Market Dynamics
European leisure travelers now dominate booking velocity across Morocco's tourism infrastructure, while Royal Air Maroc's hub expansion and new airport capacity from ONDA reshape visitor throughput economics.
Growth Catalysts
- Visa liberalization frameworks:Morocco's streamlined entry protocols for European Union nationals reduce friction for repeat visitors from France, Spain, and Germany.
- Coastal resort zone development:Atlantic beach municipalities attract concentrated foreign direct investment into integrated hospitality complexes.
- Mobile booking penetration:Smartphone-enabled reservation platforms expand last-minute inventory access for independent travelers.
Market Restraints
- Water scarcity constraints:Golf course and pool-dependent resort operations face supply limitations from the Department of Water and Forests licensing.
- Seasonal demand compression:Peak visitor months concentrate infrastructure wear and pricing volatility across Marrakech and Agadir corridors.
- Ground transport fragmentation:Intercity rail gaps between imperial cities force reliance on dispersed private operators.
Strategic Opportunities
- Anti-Atlas adventure circuits:Undeveloped trekking corridors south of the High Atlas attract specialized outfitter investment.
- Argan cooperative tourism:UNESCO-recognized biosphere reserve experiences near Essaouira create certified heritage product lines.
- Direct long-haul expansion:Casablanca hub positioning enables North American origin market development beyond existing European dominance.
Industry Challenges
- Multilingual guide certification:Licensed interpreter shortages constrain premium experience scaling across Fez and Meknes cultural sites.
- Riad renovation compliance:Historic medina property upgrades face extended approval timelines from municipal heritage authorities.
- Payment system integration:International card network compatibility gaps persist in remote Sahara access points.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Morocco Tourism Market |
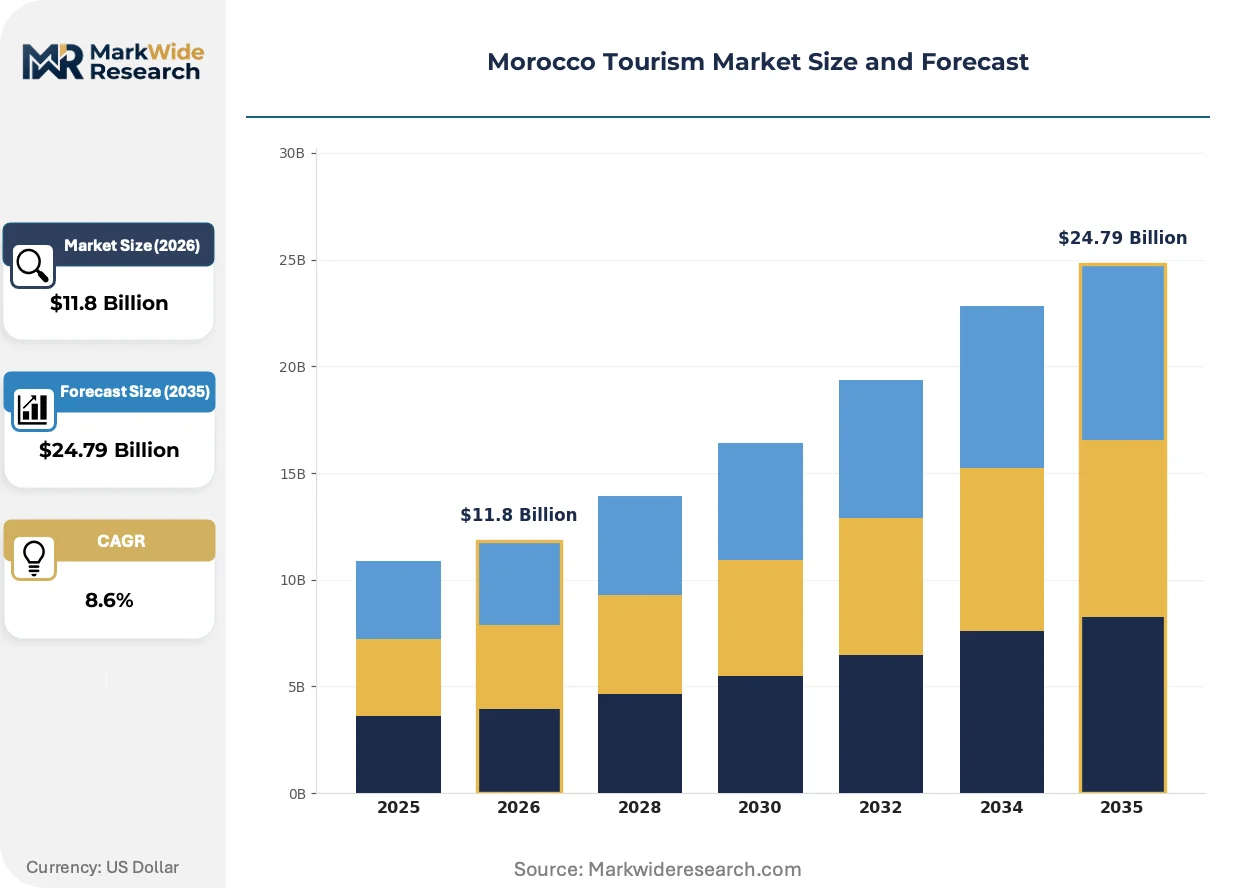
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $24.79 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Guided Tours, Hotel Accommodation, Transportation Services, Culinary Experiences Customer Type: Leisure Travelers, Business Professionals, Cultural Enthusiasts, Adventure Seekers Attraction Type: Cultural Sites, Natural Wonders, Historic Landmarks, Urban Experiences Booking Channel: Travel Agencies, Online Platforms, Direct Booking, Tour Operators |
| Companies Covered | Intrepid Travel, Hilton Worldwide Holdings, Royal Air Maroc, G Adventures, Booking Holdings, Accor SA, TUI Group, Iberostar Group, Marriott International, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Morocco Tourism Market Trends and Innovations
Digital infrastructure is reconfiguring how visitors discover and purchase Moroccan experiences, compressing traditional intermediary roles while elevating direct supplier relationships.
Artificial intelligence-powered itinerary builders are supplanting static travel brochures and fixed-package tour catalogs. Independent European travelers now assemble multi-stop desert-to-coast journeys through algorithmic recommendations. This compression is fragmenting commission structures that historically sustained ground operator networks.
Morocco's Ministry of Tourism licensing standards for sustainable accommodation certification now mandate water recycling thresholds for new coastal developments. Properties in Agadir and Taghazout must demonstrate closed-loop irrigation to obtain operating permits. Desert camp operators face parallel constraints on generator noise and waste management.
Experience-based purchasing now dominates accommodation selection over star-rating systems alone. Cultural travelers prioritize cooking class access, hammam rituals, and artisan workshop visits as booking determinants. This pattern concentrates revenue in Marrakech medina properties with integrated activity programming.
Morocco Tourism Market Segmentation
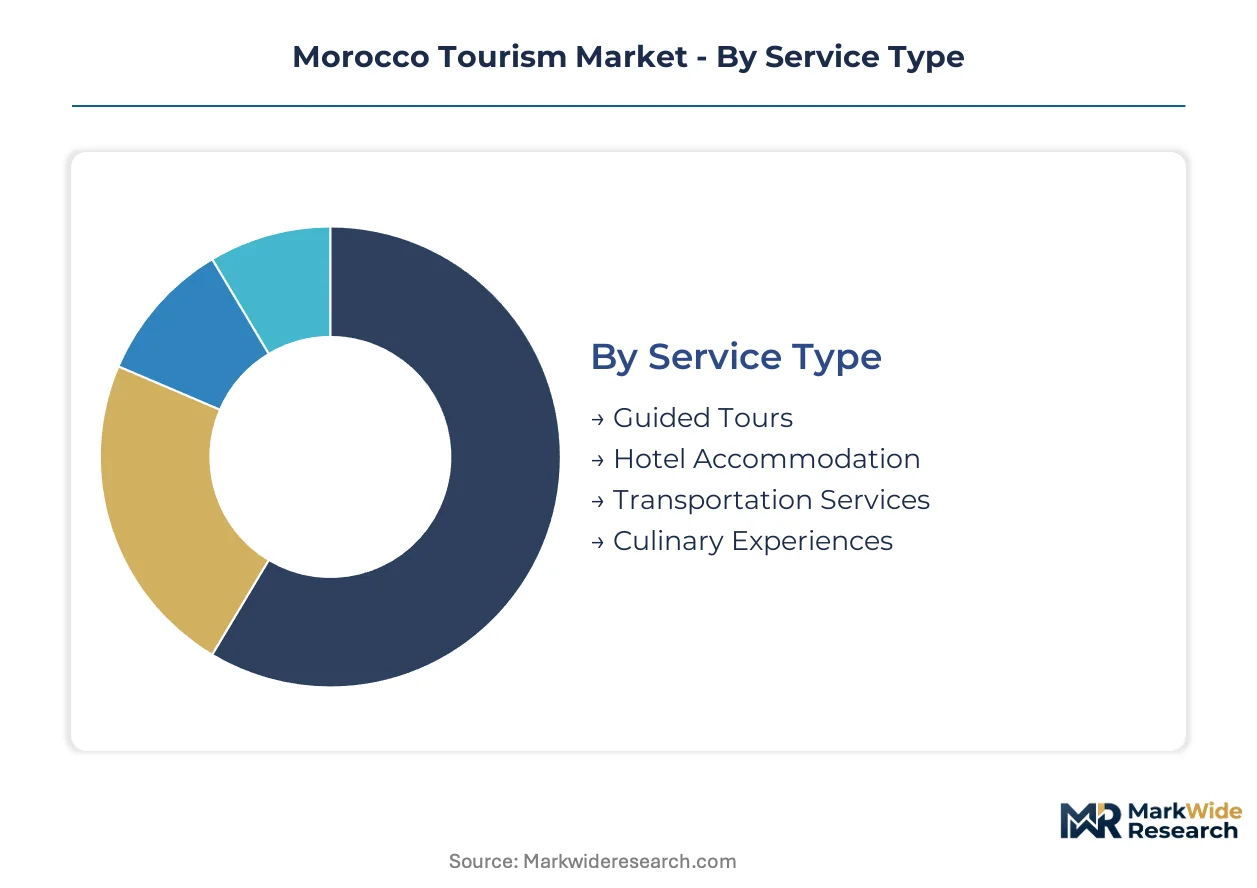
Morocco's tourism segmentation reveals distinct demand patterns across service delivery modes and traveler psychographics. Channel preferences vary sharply between European package tourists and independent mobile bookers. Understanding these splits enables targeted capacity investments across Marrakech medinas and Atlantic resort zones.
Service Type:
Channel-mix dynamics channel premium experiences through direct supplier relationships while commodity services aggregate on platforms.
- Hotel Accommodation:Riads and beach resorts command the largest revenue pool, with Marrakech medina properties integrating hammam and cooking class programming. Coastal developments in Agadir face water recycling mandates from the Department of Water and Forests.
- Guided Tours:Premium certified interpreters lead imperial city circuits through Fez and Meknes, though multilingual guide shortages constrain scaling. Sahara corridor operators battle payment system gaps at remote access points.
- Transportation Services:Intercity rail gaps force reliance on dispersed private operators between imperial cities.
- Culinary Experiences:Argan cooperative tourism near Essaouira creates certified heritage product lines.
Hotel accommodation dominates installed base. Guided tours are where expansion concentrates.
Customer Type:
Cost tier stratification separates high-yield cultural enthusiasts from price-sensitive leisure segments.
- Leisure Travelers:European origin markets drive fastest booking velocity through streamlined EU entry protocols. Atlantic beach municipalities attract concentrated foreign direct investment for this segment.
- Cultural Enthusiasts:Premium guided experience demand concentrates across Morocco's imperial cities and Sahara corridors. Royal Air Maroc's Casablanca hub anchors long-haul connectivity for this high-yield cohort.
- Business Professionals:Casablanca's financial district generates concentrated MICE demand.
- Adventure Seekers:Anti-Atlas trekking corridors south of the High Atlas attract specialized outfitter investment.
Leisure travelers dominate installed base. Cultural enthusiasts represent the fastest-growing trajectory.
Attraction Type:
Volume distribution favors accessible cultural assets over dispersed natural sites requiring specialized infrastructure.
- Cultural Sites:UNESCO-recognized medinas and imperial palaces maintain the strongest visitor pull. Municipal heritage authorities extend Riad renovation approval timelines, constraining accommodation supply.
- Natural Wonders:Anti-Atlas ranges and coastal wetlands attract emerging adventure segments. Generator noise and waste management constraints apply to desert camp operators.
- Historic Landmarks:Roman ruins and kasbahs anchor secondary city itineraries.
- Urban Experiences:Marrakech and Casablanca concentrate nightlife and retail tourism.
Cultural sites dominate installed base. Natural wonders are where expansion concentrates.
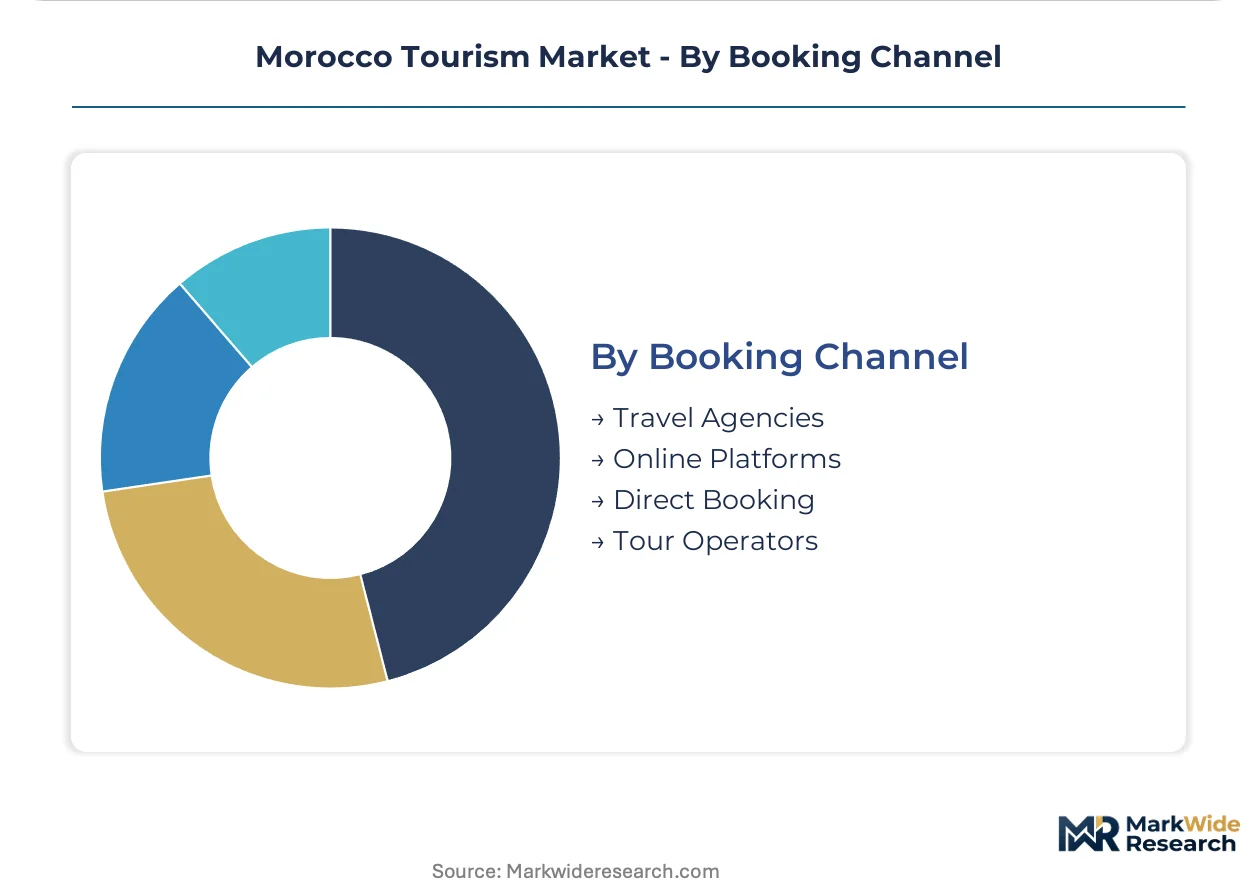
Booking Channel:
Margin structure fragments as mobile penetration compresses traditional intermediary commissions.
- Online Platforms:Smartphone-enabled reservation platforms expand last-minute inventory access for independent European travelers. Algorithmic itinerary builders now supplant fixed-package tour catalogs.
- Tour Operators:Ground operator networks sustain commission structures for packaged European leisure segments. Royal Air Maroc hub expansion enables integrated air-land product bundling.
- Direct Booking:Riad properties with integrated activity programming capture experience-based purchasing preferences.
- Travel Agencies:Traditional storefronts retain package tourist segments from mature European markets.
Online platforms dominate installed base. Direct booking is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France exports the highest volume of leisure travelers to Morocco, followed by Spain and Germany as secondary feeder markets. Royal Air Maroc's Casablanca hub funnels North American visitors through transatlantic connections. European Union visa liberalization protocols sustain repeat visitation cycles across these corridors.
France
French leisure travelers dominate Marrakech medina bookings and Atlantic coastal resort demand. The country's national tourism promotion agency maintains bilateral marketing agreements with Morocco's Ministry of Tourism. Paris and Lyon generate concentrated outbound charter traffic to Agadir and Essaouira.
Spain
Spanish visitors drive short-haul weekend tourism across the Strait of Gibraltar corridor. The country's port authority regulates ferry capacity that gates vehicle-based family travel volumes. Andalusia's Málaga and Algeciras serve as primary embarkation points for Tangier-bound routes.
Germany
German cultural enthusiasts sustain premium guided tour demand through Fez and Meknes imperial circuits. The country's federal tourism board certifies Moroccan destination management companies under quality assurance frameworks. Berlin and Munich source markets concentrate high-yield adventure segment bookings.
United Kingdom
British travelers generate strong demand for Sahara desert camp experiences and Anti-Atlas trekking circuits. The country's foreign office travel advisory system influences seasonal booking velocity through safety perception management. London and Manchester airports anchor direct Royal Air Maroc connections to Casablanca.
United States
American cultural tourists represent the fastest-growing long-haul origin market for Morocco's heritage experiences. The country's transportation security administration reciprocity enables streamlined entry protocols for pre-cleared travelers. New York and Washington metropolitan areas concentrate outbound demand for curated riad accommodations.
Morocco Tourism Market Competitive Landscape
Player mix skews toward integrated hospitality conglomerates with property portfolios spanning multiple Moroccan sub-regions. Market structure concentrates around three strategic tiers: global hotel chains with riad conversions, international tour operators with ground handling networks, and aviation-led destination packaging platforms. Dominant competitive moves include medina property acquisitions and direct-to-consumer digital channel expansion.
Within the hospitality conglomerate tier, Accor SA and Marriott International exemplify scale-driven positioning through mixed-brand portfolios. Royal Air Maroc anchors the aviation-platform archetype with hub-controlled inventory distribution. Booking Holdings occupies the aggregation-platform position, compressing traditional intermediary margins through algorithmic matching. G Adventures and Intrepid Travel represent the specialized adventure-outfitter segment with concentrated Sahara and Atlas trekking products.
| Leading Market Players |
|---|
| Intrepid Travel |
| Hilton Worldwide Holdings |
| Royal Air Maroc |
| G Adventures |
| Booking Holdings |
| Accor SA |
| TUI Group |
| Iberostar Group |
| Marriott International |
| Others |
Pricing and Supply Chain Analysis
Department of Water and Forests licensing thresholds gate both accommodation supply qualification and price differentiation simultaneously, mandating closed-loop irrigation for coastal resort permits while segmenting Marrakech medina properties by heritage certification tiers.
Pricing Analysis
Legacy riad inventory versus newly certified sustainable properties versus speculative luxury developments creates a three-tier pricing structure across premium, standard, and economy levels. Price differentiation hinges on UNESCO heritage certification status and integrated experience programming density. Pricing pressure stems from seasonal demand compression forcing off-peak discounting. Independent mobile bookers exhibit highest price sensitivity while cultural enthusiasts accepting certified guide premiums show lowest.
Supply Chain Analysis
Just-in-time inventory preferences dominate European tour operator relationships while strategic stockpiling of certified guide capacity secures peak-season fulfillment. Supply concentrates in France, Spain, and Germany as origin markets. Ground transport services draw from dispersed private operator networks, accommodation from heritage-constrained medina stock, and aviation from Royal Air Maroc's hub. Single-source vulnerability persists in multilingual interpreter certification pipelines. Distribution runs through platform aggregators compressing traditional ground operator margins.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in experience-based purchasing shifts elevating direct supplier relationships over packaged intermediaries, creating niche entry points for specialized outfitters and certified heritage operators.
For Market Incumbents: Secure medina property portfolios ahead of municipal heritage authority approval timeline extensions constraining new supply. Anchor backward integration into argan cooperative networks near Essaouira to lock certified heritage product lines against emerging competitor access. Prioritize direct-to-consumer channel control as Booking Holdings aggregation threatens commission structures. For New Entrants and Emerging Players: Sustainable accommodation certification fast-tracks from Morocco's Ministry of Tourism offer lowest barrier entry for Agadir and Taghazout coastal developments facing water recycling mandates. Anti-Atlas adventure circuits south of the High Atlas represent the most penetrable geography with undeveloped trekking infrastructure. Go-to-market through algorithmic itinerary builder partnerships targets independent European mobile bookers. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across riad renovation and heritage certification compliance as municipal approval timelines extend. Long-term viability favors operators controlling integrated experience programming beyond pure accommodation. Acquisition targets should exhibit direct booking channel share above platform dependency. Signal to watch: Department of Water and Forests licensing backlog as inflection indicator for constrained supply premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Heritage Certification Fast-Track | Ministry of Tourism licensing accelerates market entry for compliant coastal resort developers. |
| Direct Booking Channel Expansion | Riad properties bypass Booking Holdings commission compression through proprietary reservation platforms. |
| Argan Cooperative Integration | UNESCO biosphere reserve access locks certified heritage product differentiation near Essaouira. |
| Anti-Atlas Circuit Development | Specialized trekking infrastructure captures emerging adventure segment demand from German origin markets. |
| Casablanca Hub Connectivity | Royal Air Maroc long-haul expansion enables North American cultural enthusiast market development. |
Research Methodology
Operator-level perspectives from riad proprietors, certified heritage guides, coastal resort developers, and Royal Air Maroc network planners anchored the qualitative base. Primary interviews combined with secondary validation from ONDA airport capacity disclosures, Department of Water and Forests licensing records, and Ministry of Tourism certification databases. Bottom-up accommodation inventory counts triangulated against top-down visitor expenditure estimates.
Sensitivity analysis tested forecast robustness across visa policy liberalization scenarios and seasonal demand compression assumptions. Segmentation dimensions modeled include service type, customer psychographic, attraction category, and booking channel preference. CAGRs derived from historical trajectory fitting and elasticity-adjusted projection. Forecast inputs incorporated ONDA infrastructure expansion timelines and EU entry protocol stability assumptions.
Decision-makers should treat outputs as directional under stable regulatory enforcement and sustained European origin market connectivity; material deviation in heritage authority approval timelines or water scarcity licensing severity would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hotels and Resorts
Global Beach Hotels Market
Hotels and Resorts
Spain HRI Market
Hotels and Resorts
Philippines Tourism and Hotel Market
Hotels and Resorts
Hotel Armchair Market
Hotels and Resorts
Spa Resorts Market
Hotels and Resorts
Morocco Hospitality Market
Hotels and Resorts
Hotels, Resorts, and Cruise Lines Market
Hotels and Resorts
India Luxury Hotel Market
Hotels and Resorts
North America Luxury Hotel Market
Hotels and Resorts
United Kingdom HRI Market
Hotels and Resorts
Cuba Tourism and Hotel Market
Hotels and Resorts
United States Luxury Hotel Market
Hotels and Resorts
Europe Luxury Hotel Market
Hotels and Resorts
Global Floating Hotels Market
Hotels and Resorts
Asia-Pacific Luxury Hotel Market
Hotels and Resorts
Morocco Tourism and Hotel Market