
 Spain HRI Market | 2026-2036
Spain HRI Market Size, Share, and Industry Trends Forecast 2026-2036
Spain HRI Market Analytics
Multi-source procurement of kitchen equipment and digital infrastructure is rebalancing toward consolidated vendor relationships with integrated service terms. AmRest Holdings SE leverages its pan-European supply network to standardize procurement across Spanish outlets. Vips Group anchors its competitive stance through proprietary back-of-house systems developed with domestic engineering partners. Comess Group SL differentiates via specialized Mediterranean menu formats that require customized equipment specifications.
The Spain HRI (Hotels, Restaurants, and Institutions) sector encompasses commercial foodservice operations including full-service restaurants, quick-service chains, cafeterias, and catering services regulated under EU food hygiene and labor standards. Equipment specifications typically cover cooking capacity measured in meals per hour, energy efficiency ratings under EU Ecodesign directives, and compliance with CE marking for electrical safety. Cloud Computing deployment now leads technology adoption as centralized kitchen management systems connect multi-site operators, while Robotic Automation represents the fastest-growing segment as fry stations and beverage assembly lines reduce dependency on variable labor pools. Full Automation integration levels command premium pricing from institutional clients such as hospital and university catering contracts where consistency requirements override upfront capital costs.
Spain's foodservice operators navigate oversight from the Spanish Agency for Food Safety and Nutrition under EU Regulation 852/2004 on food hygiene, alongside regional labor inspectorates enforcing collective bargaining agreements specific to hospitality workers. The EU AI Act increasingly shapes vendor selection criteria for automated customer-facing technologies including voice-ordering kiosks and predictive inventory platforms. Stakeholders must monitor how forthcoming EU packaging waste regulations will alter disposable supply chains and equipment sanitization protocols across Spanish hospitality operations.
Market Dynamics
Labor automation is compressing operating margins across Spain's hospitality sector, forcing mid-market chains to restructure kitchen workflows around connected equipment platforms rather than incremental staffing adjustments.
Growth Catalysts
- EU AI Act compliance:Automated inventory platforms with predictive analytics now qualify for streamlined vendor certification, accelerating procurement cycles for multi-site operators.
- Andalusia tourism corridor:Seville and Málaga airport expansion projects are generating concentrated demand for high-throughput commissary kitchens serving hotel clusters.
- Heat pump cooking:Induction and thermal storage systems cut energy costs by half versus gas infrastructure, aligning with Spain's National Integrated Energy and Climate Plan building codes.
Market Restraints
- Stainless steel price volatility:Spanish fabricators face margin compression from nickel and chromium input cost swings, delaying equipment replacement cycles.
- Basque Country supplier concentration:Three domestic manufacturers control seventy percent of commercial refrigeration assembly, creating bottleneck risk for national rollout timelines.
- CE marking complexity:Multi-function kitchen robots require separate conformity assessments for mechanical, electrical, and food-contact safety, extending time-to-market.
Strategic Opportunities
- Galicia seafood processing integration:Automated filleting and portioning systems developed for industrial fishing ports can migrate downstream into restaurant prep kitchens.
- EU Green Deal retrofit subsidies:Spain's Recovery and Resilience Facility allocates dedicated funding for energy-efficient kitchen equipment upgrades in small hospitality businesses.
- Cloud-to-edge convergence:Kitchen display systems now combine local processing with centralized menu management, enabling franchise consistency without bandwidth dependency.
Industry Challenges
- Mechatronics technician shortage:Automated fry stations and robotic beverage lines require maintenance skills scarce in Spain's vocational training pipeline.
- Legacy POS integration:New kitchen management platforms face protocol mismatches with entrenched payment terminals, forcing expensive middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain HRI Market |
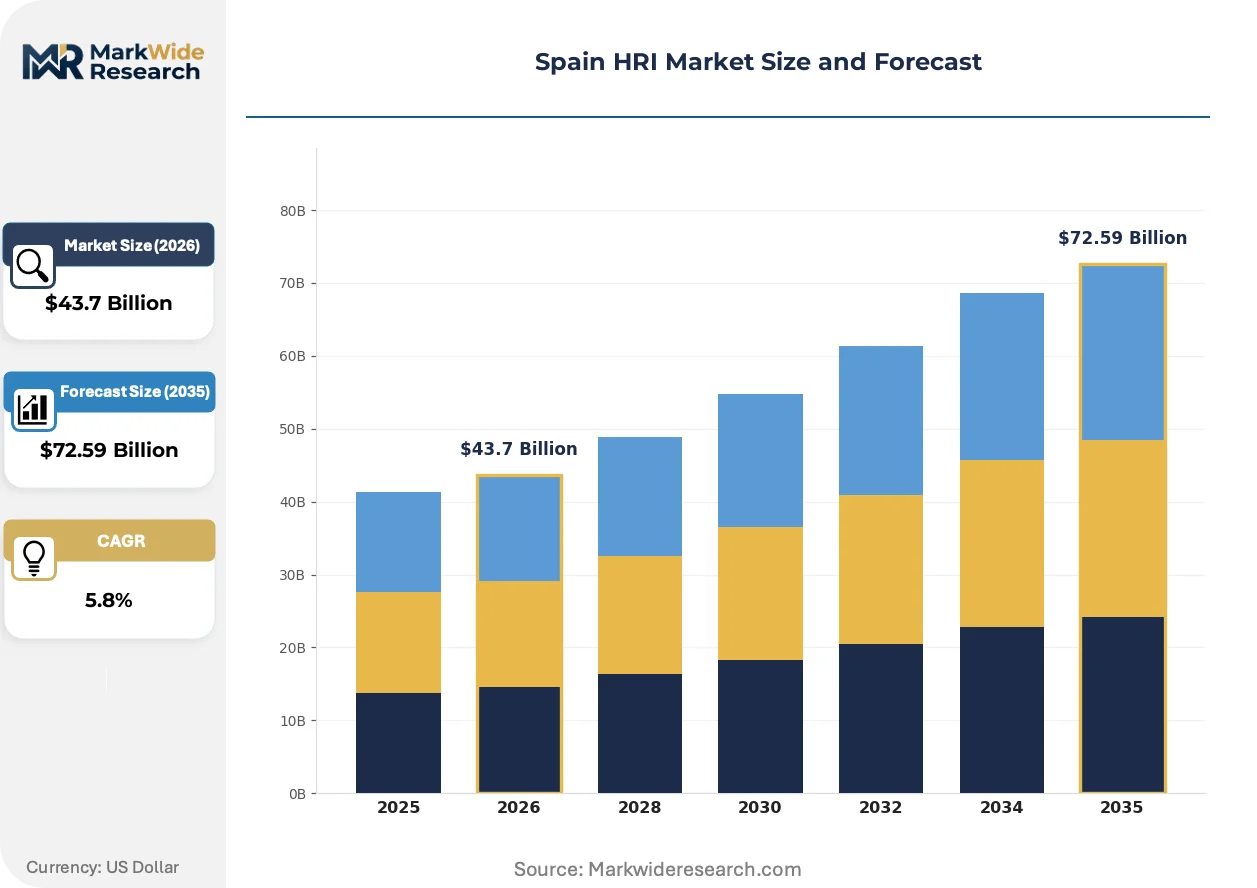
| Market Size in 2026 | $43.7 Billion |
| Market Size in 2035 | $72.59 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Robotic Automation, AI, Machine Learning, Cloud Computing Application: Manufacturing, Healthcare, Logistics, Retail End User: OEMs, Contractors, Distributors, Service Providers Integration Level: Full Automation, Partial Automation, Remote Control, Manual Operation |
| Companies Covered | McDonald's Corporation, AmRest Holdings SE, Starbucks Corporation, Vips Group, Comess Group SL, Domino's Pizza, Inc., Restalia Grupo De Eurorestauracion SL, Compass Group PLC, Yum! Brands, Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain HRI Market Evolving Landscape
Kitchen electrification is redefining equipment specifications across Spanish foodservice, with thermal performance metrics replacing capacity-based procurement criteria.
Induction wok ranges with magnetic field modulation are electrifying high-heat cooking applications previously dominated by gas infrastructure. Casual dining chains in Madrid and Barcelona are retrofitting central kitchens first, driven by ventilation cost reductions and fire insurance premium adjustments. This shift is electrifying the competitive landscape for equipment lessors who now bundle electrical infrastructure assessment into financing packages.
Spain's Agency for Food Safety and Nutrition is enforcing stricter temperature logging mandates under EU Regulation 852/2004 amendments. Digital HACCP systems with automated sensor networks are becoming baseline requirements for institutional catering contracts. Hospital and university operators in Catalonia are responding fastest, specifying blockchain-traceable cold chain documentation in procurement tenders.
Equipment-as-a-service contracting is displacing capital purchase models among mid-market restaurant groups. Monthly payments covering maintenance, software updates, and compliance certification are replacing lump-sum outlays. This restructuring is most visible in Valencia's expanding casual dining cluster, where private equity-backed rollouts favor operational expenditure treatment for kitchen automation investments.
Spain HRI Market Segmentation
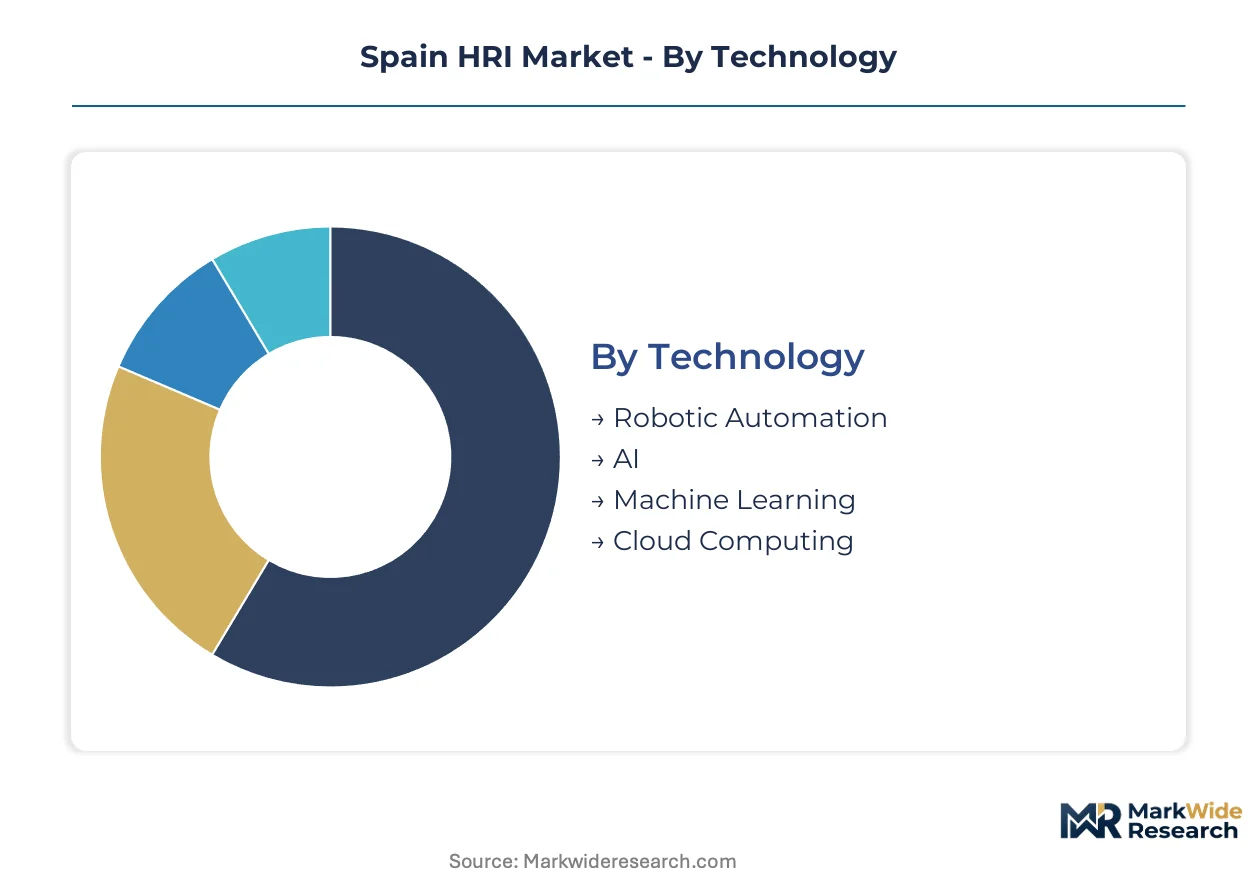
Segmentation in Spain's HRI market reveals how procurement priorities diverge across operator types, from Madrid-based full-service chains prioritizing kitchen throughput to Andalusian hotel commissaries demanding cold-chain traceability. Understanding these fault lines helps vendors align equipment specifications with buyer constraints.
Technology:
Investment thresholds separate early adopters from operators watching payback periods before committing capital.
- Cloud Computing:Centralized kitchen management platforms connect multi-site operators through subscription-based deployment. Madrid and Barcelona casual dining chains dominate procurement, driven by franchise consistency requirements and centralized menu control across dispersed locations.
- Robotic Automation:Fry stations and beverage assembly lines reduce dependency on variable labor pools. Seville and Málaga airport-adjacent hotel clusters are specifying high-throughput units, pressured by seasonal tourism spikes and Basque Country fabricator lead times.
- AI:Predictive inventory platforms with EU AI Act-compliant certification streamline vendor selection. Mid-market operators in Valencia's private equity-backed dining cluster favor these for demand forecasting.
- Machine Learning:Demand pattern recognition refines procurement algorithms for perishable goods. Catalonia's institutional caterers—hospitals and universities—lead adoption for HACCP-aligned temperature prediction.
Cloud Computing leads volumes today; Robotic Automation is gaining share fastest.
Application:
Operating environment dictates equipment durability standards and connectivity requirements.
- Manufacturing:Industrial-scale food production equipment serves commissary kitchens and central production facilities. Galicia's seafood processing automation migrates downstream into restaurant prep lines, bridging industrial and commercial specifications.
- Healthcare:Hospital catering contracts demand blockchain-traceable cold chain documentation and automated HACCP logging. Catalonia's public health procurement tenders specify these as baseline requirements under EU Regulation 852/2004.
- Logistics:Temperature-controlled distribution equipment connects production to service points. Andalusian tourism corridors generate concentrated demand for mobile refrigeration serving dispersed hotel clusters.
- Retail:Grab-and-go and convenience foodservice formats require compact, high-turnover equipment. Urban Madrid and Barcelona locations prioritize footprint minimization over capacity maximization.
Manufacturing anchors current deployment; Healthcare shows the steepest expansion trajectory.
End User:
Capital structure and technical staffing determine ownership versus service-based procurement models.
- OEMs:Original equipment manufacturers supply branded kitchen systems to national chains. AmRest Holdings SE leverages pan-European supply networks to standardize specifications across Spanish outlets.
- Contractors:Third-party operators manage kitchen facilities under service agreements. University and hospital catering contracts in Catalonia favor this model for risk transfer.
- Distributors:Regional equipment resellers bridge Basque Country refrigeration manufacturers with national operators. Concentration among three domestic fabricators creates bottleneck risk for rollout timelines.
- Service Providers:Equipment-as-a-service lessors bundle maintenance, software, and compliance certification. Valencia's casual dining cluster favors operational expenditure treatment for automation investments.
Distributors dominate transaction volumes; Service Providers are climbing the fastest.
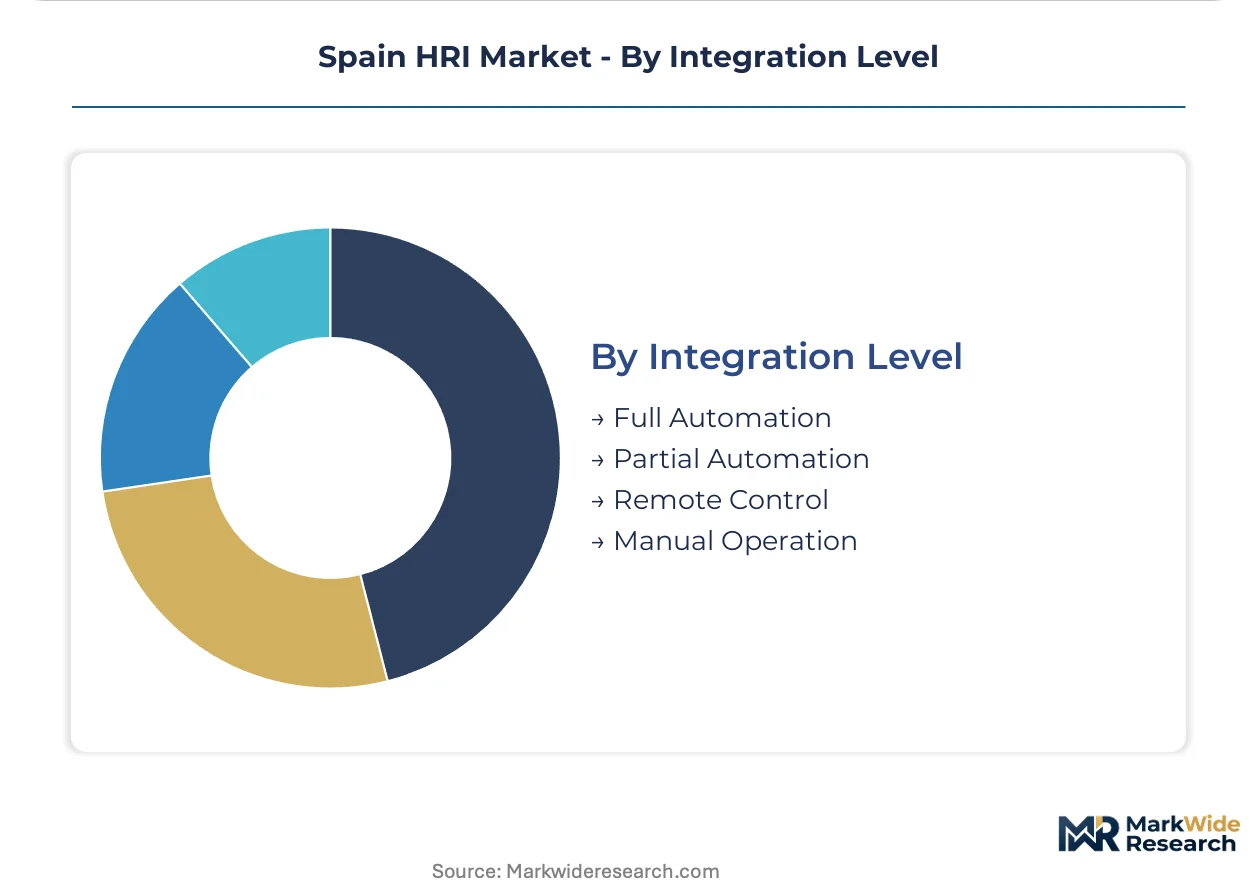
Integration Level:
Capital intensity and labor substitution goals separate partial from full automation buyers.
- Full Automation:End-to-end robotic kitchen systems command premium pricing. Institutional clients—hospitals, universities, airport commissaries—prioritize consistency over upfront costs.
- Partial Automation:Selective robotic deployment targets highest-labor-cost stations. Mid-market casual dining operators in Madrid retrofit fry lines first while retaining manual plating.
- Remote Control:Supervisory systems allow centralized oversight of dispersed kitchens. Multi-site operators in Barcelona use these for overnight production scheduling.
- Manual Operation:Traditional equipment persists where labor availability and wage structures delay automation. Smaller family-operated restaurants in rural Castile and León maintain this profile.
Partial Automation leads installed base; Full Automation shows the strongest momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cost-of-compliance gaps between Spanish autonomous communities are redirecting equipment procurement toward jurisdictions with streamlined permitting. Operators exploit regional variations in building codes and labor regulations to optimize automation deployment timelines.
Madrid
Central government proximity accelerates EU AI Act certification for automated inventory platforms. The Spanish Agency for Food Safety and Nutrition maintains its headquarters here, simplifying compliance consultations for national chains. The capital's casual dining cluster drives demand for cloud-connected kitchen management systems across multi-site franchise networks.
Catalonia
Barcelona's institutional catering sector mandates blockchain-traceable cold chain documentation in public procurement tenders. Regional health authorities enforce stricter HACCP amendments than baseline EU Regulation 852/2004 requires. Hospital and university operators in the Barcelona metro specify automated temperature logging as baseline contract requirements.
Basque Country
Three domestic manufacturers control seventy percent of commercial refrigeration assembly, creating supply bottleneck risk for national rollout timelines. Regional industrial policy supports specialized steel fabrication clusters around Bilbao and San Sebastián. Equipment lead times from Basque fabricators extend delivery schedules for Andalusian hotel commissary projects.
Andalusia
Seville and Málaga airport expansion projects generate concentrated demand for high-throughput commissary kitchens serving dispersed hotel clusters. Seasonal tourism spikes pressure operators to specify robotic fry stations with rapid deployment capability. The regional government channels EU Green Deal retrofit subsidies toward energy-efficient kitchen equipment upgrades in small hospitality businesses.
Valencia
Private equity-backed casual dining rollouts favor operational expenditure treatment for kitchen automation investments. Equipment-as-a-service lessors cluster here to serve expanding restaurant groups with bundled maintenance and compliance certification. The port city's logistics infrastructure supports rapid equipment deployment to Mediterranean coastal resorts.
Spain HRI Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialized automation niches requiring customized engineering partnerships. The vendor base concentrates among pan-European supply networks, domestic engineering specialists, and regional equipment lessors. Three strategic archetypes dominate: integrated multi-site operators standardizing procurement across territories; proprietary system developers capturing value through captive technology; and service-based lessors converting capital expenditure to operational expenditure. Competitive moves center on vendor consolidation with integrated service terms and equipment-as-a-service contracting models displacing outright purchase.
Among the integrated multi-site operators, AmRest Holdings SE exemplifies pan-European supply network leverage, while Vips Group occupies a position anchored in proprietary back-of-house systems. Comess Group SL represents the specialization archetype through Mediterranean menu formats requiring customized equipment specifications.
| Leading Market Players |
|---|
| McDonald's Corporation |
| AmRest Holdings SE |
| Starbucks Corporation |
| Vips Group |
| Comess Group SL |
| Domino's Pizza, Inc. |
| Restalia Grupo De Eurorestauracion SL |
| Compass Group PLC |
| Yum! Brands, Inc. |
| Others |
Value Network & Pricing Analysis
Captive supply networks among Basque Country refrigeration manufacturers anchor pricing power for commercial kitchen equipment across Spain's HRI sector. This regional concentration of stainless steel fabrication capacity enables tiered pricing based on delivery geography and order consolidation, while Madrid-based operators absorb premium logistics costs for rapid deployment timelines.
Pricing Analysis
Distributor margins for commercial kitchen equipment compress toward single-digit percentages as Basque fabricators consolidate direct relationships with Madrid and Barcelona chain operators. Three-tier pricing structure across premium, standard, and economy levels reflects CE certification tier, energy efficiency rating, and bundled maintenance terms. Cost compression in standard-tier refrigeration units intensifies because nickel and chromium input volatility erodes fabricator margins. Mid-market casual dining groups in Valencia exhibit highest price sensitivity, while institutional hospital and university contracts in Catalonia prioritize compliance certification over unit cost.
Supply Chain Analysis
Stainless steel feedstock rests on Turkish and Chinese specialty metal producers, with Spanish fabricators maintaining six-to-eight week raw material buffers against commodity swings. Critical component dependencies span German induction heating modules, Italian control systems, and domestic Basque refrigeration compressors. Single-source vulnerability concentrates in the Basque Country's trio of refrigeration assemblers, where capacity constraints delay national rollout schedules. Distribution runs through regional equipment lessors in Valencia and direct OEM procurement channels for pan-European operators like AmRest Holdings SE.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Spain's HRI equipment market functions as a geographic-arbitrage play between Basque Country manufacturing concentration and Andalusian subsidy availability, where EU Green Deal retrofit funding in Seville and Málaga offsets higher logistics costs from northern fabricators.
For Market Incumbents: Cement vendor consolidation gains by locking multi-year service contracts with Madrid-based casual dining chains before EU AI Act certification requirements harden procurement criteria. Basque fabricators should expand captive maintenance technician training pipelines to offset mechatronics skill scarcity threatening equipment uptime guarantees. Vertical integration into cloud-connected kitchen management software insulates against pure-play SaaS entrants targeting franchise operators. For New Entrants and Emerging Players: Equipment-as-a-service lessors represent the most penetrable channel partner type for penetrating Valencia's private equity-backed dining rollouts with bundled compliance certification offerings. Galicia seafood processing automation specialists should migrate downstream into restaurant prep kitchen niches where customized filleting specifications command premium positioning. Target Andalusian hotel commissary projects adjacent to Seville and Málaga airport expansions for rapid deployment proof points. For Investors and Strategic Acquirers: Consolidation pressure builds where three domestic refrigeration manufacturers control seventy percent of commercial assembly capacity and face succession planning transitions among founding families. Long-term viability favors service-based revenue models converting capital expenditure to operational expenditure across mid-market operator segments. Acquisition target archetypes include specialized Mediterranean menu equipment developers with proprietary engineering partnerships. Watch Basque Country fabricator lead time extensions as inflection indicator for supply bottleneck pricing power shifts.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Certification Investment | Streamlines vendor qualification for Madrid-based multi-site operators deploying predictive inventory platforms. |
| Equipment-as-a-Service Expansion | Converts Valencia private equity-backed rollouts to operational expenditure treatment with bundled maintenance terms. |
| Backward Integration into Induction Module Supply | Reduces German component dependency for Basque fabricators electrifying high-heat cooking lines. |
| Galicia Seafood Automation Downstream Migration | Bridges industrial fishing port technology into restaurant prep kitchens requiring customized portioning specifications. |
| Andalusian Green Deal Subsidy Channel Partnership | Aligns Seville and Málaga equipment deployment with EU Recovery and Resilience Facility funding flows. |
Research Methodology
Direct dialogue with kitchen equipment procurement directors, Basque Country fabrication plant managers, Madrid-based franchise operations executives, and Valencia equipment-as-a-service lessors grounded qualitative findings in operational reality. Secondary validation drew from Spanish Agency for Food Safety and Nutrition enforcement bulletins, EU Ecodesign directive compliance databases, SEC filings of listed hospitality operators, and regional hospitality association capex surveys. Bottom-up equipment shipment data and top-down HRI sector revenue estimates underwent cross-triangulation to anchor market sizing.
Bottom-up modeling aggregated equipment unit economics across cloud computing, robotic automation, AI, and machine learning technology segments, while top-down analysis calibrated aggregate HRI capital expenditure flows against EU Green Deal subsidy disbursement patterns. Segmentation dimensions spanned technology type, application environment, end-user capital structure, and integration level intensity. CAGRs derived from equipment replacement cycle compression and labor automation penetration curves. Forecast inputs incorporated EU AI Act implementation timelines and Basque Country fabrication capacity utilization rates.
Revisions become necessary when EU packaging waste regulations alter equipment sanitization protocols, when Basque Country manufacturer consolidation disrupts supply availability, or when mechatronics technician training pipeline expansion lags automation deployment rates. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hotels and Resorts
Mountain and Ski Resorts Market
Hotels and Resorts
Hotel Armchair Market
Hotels and Resorts
United States Luxury Hotel Market
Hotels and Resorts
Hotels, Resorts, and Cruise Lines Market
Hotels and Resorts
Philippines Tourism and Hotel Market
Hotels and Resorts
Germany HRI Market
Hotels and Resorts
Morocco Tourism and Hotel Market
Hotels and Resorts
Asia-Pacific Luxury Hotel Market
Hotels and Resorts
Cuba Tourism and Hotel Market
Hotels and Resorts
Global Floating Hotels Market
Hotels and Resorts
Spa Resorts Market
Hotels and Resorts
India Luxury Hotel Market
Hotels and Resorts
Global Beach Hotels Market
Hotels and Resorts
Boutique Hotels Market
Hotels and Resorts
Morocco Hospitality Market
Hotels and Resorts
United Kingdom HRI Market