
 Cuba Tourism and Hotel Market | 2026-2036
Cuba Tourism and Hotel Market Size, Share, and Industry Trends Forecast 2026-2036
Cuba Tourism and Hotel Market Outlook
ASTA membership and Cuba-specific tour operator licensing is bifurcating the competitive field between accredited full-service providers and informal booking channels. Meliá Hotels International leverages its Spanish-Cuban joint venture footprint to dominate beachfront resort operations. Iberostar sustains operational scale across multiple Cuban provinces through centralized supply chains. InsightCuba differentiates on curated people-to-people educational itineraries that comply with U.S. travel category requirements.
Cuba tourism and hotel services encompass lodging, guided experiences, ground transportation, and ancillary hospitality operations delivered within a state-regulated framework where foreign operators partner with Cuban state entities. The sector functions through a dual-currency operational structure with foreign-exchange earnings prioritized for infrastructure reinvestment. Luxury hotels and all-inclusive resorts capture the dominant share of foreign currency revenue due to higher per-visitor spending and longer average stays. Boutique hotels represent the fastest-expanding accommodation category, driven by independent European travelers and heritage tourism demand in Old Havana.
Cuba's Ministry of Tourism (MINTUR) and the Cuban Central Bank jointly govern foreign investment structures, while OFAC and BIS regulations from the United States determine market access for American travelers and dollar-denominated transactions. These layered regulatory frameworks shape capital deployment timelines, staffing protocols, and payment channel architectures for all operators. Stakeholders must monitor administrative policy shifts in Washington and corresponding Cuban regulatory responses to calibrate market entry and expansion sequencing.
Market Dynamics
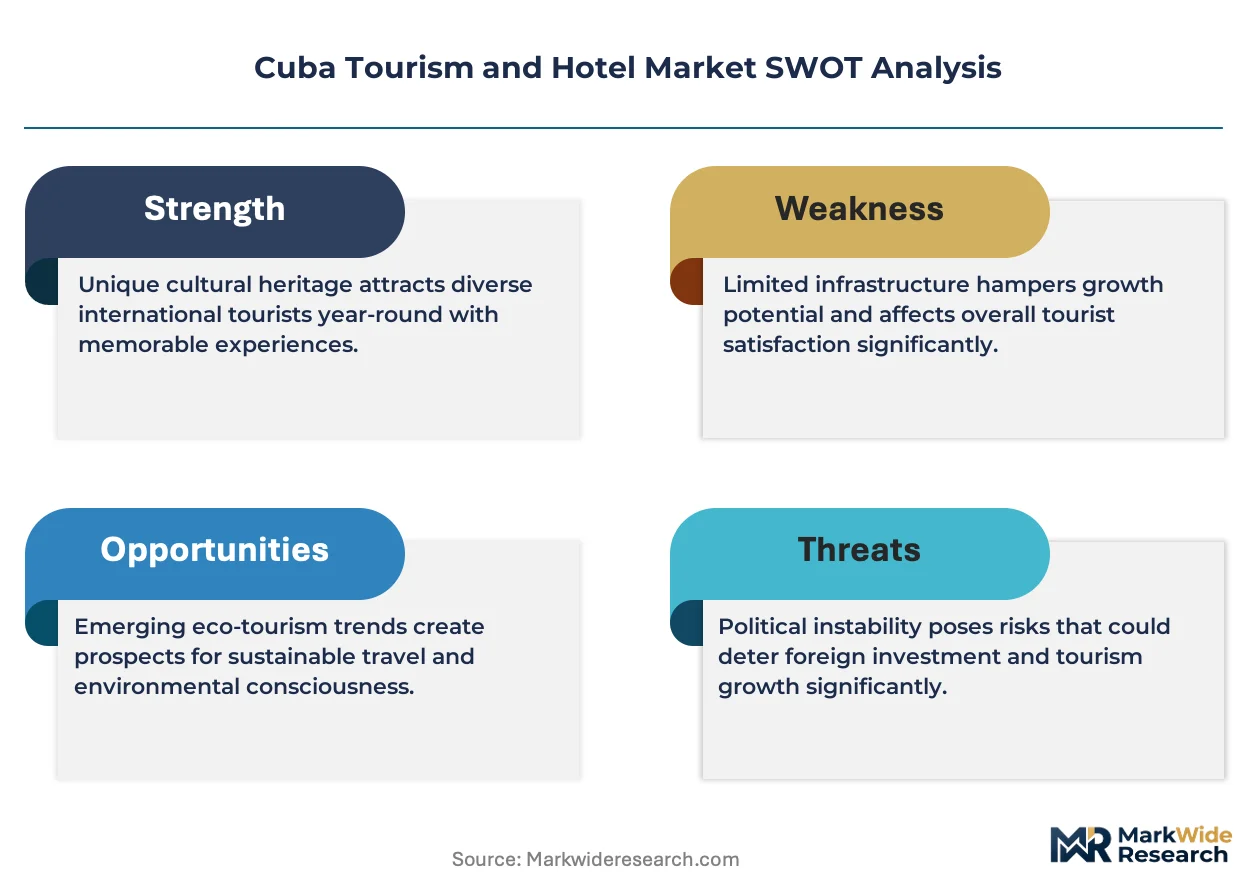
OFAC licensing volatility under successive U.S. administrations creates stop-start investment cycles that compress capital deployment timelines for Cuba-facing operators. Tour operators and hotel developers must sequence expansion around electoral calendars and corresponding Treasury Department rulemaking windows.
Growth Catalysts
- Canadian leisure demand:Air Canada and Sunwing maintain year-round capacity to Varadero and Holguín, feeding all-inclusive resort occupancy during low-season months when European arrivals taper.
- People-to-people educational travel:U.S. Treasury general licenses under 31 CFR 515.565 permit structured cultural exchange programs, creating a compliant booking channel for American visitors.
- Heritage tourism infrastructure:UNESCO World Heritage designation for Old Havana drives boutique hotel conversions in colonial-era structures, attracting independent European travelers with extended stay patterns.
Market Restraints
- Dual-currency operational friction:The Cuban peso (CUP) and freely convertible currency (MLC) create accounting complexity for foreign joint ventures repatriating earnings through Cuban state banks.
- Supply chain import dependency:Food and beverage operations rely on third-country sourcing through Panama and Mexico due to U.S. trade embargo restrictions on direct shipping.
- State employment protocols:MINTUR staffing regulations require foreign hotel operators to hire through state employment agencies, constraining direct workforce management.
Strategic Opportunities
- Viñales Valley ecotourism:Tobacco farm stays and cave system exploration remain underdeveloped relative to coastal resort concentration, offering differentiation for adventure travel specialists.
- Trinidad colonial inventory expansion:The central Cuban city's preserved 19th-century architecture supports additional boutique lodging capacity beyond current limited supply.
- Marina infrastructure development:Cuban state plans for nautical tourism at Varadero and Cienfuegos create berthing and service opportunities for Caribbean yacht charter operators.
Industry Challenges
- Hospitality technology integration:Property management systems and global distribution system connectivity require workaround architectures due to U.S. sanctions on software licensing and payment processing.
- Revenue repatriation timelines:Cuban Central Bank foreign exchange allocation procedures delay hard currency transfers to foreign partners, compressing working capital efficiency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cuba Tourism and Hotel Market |
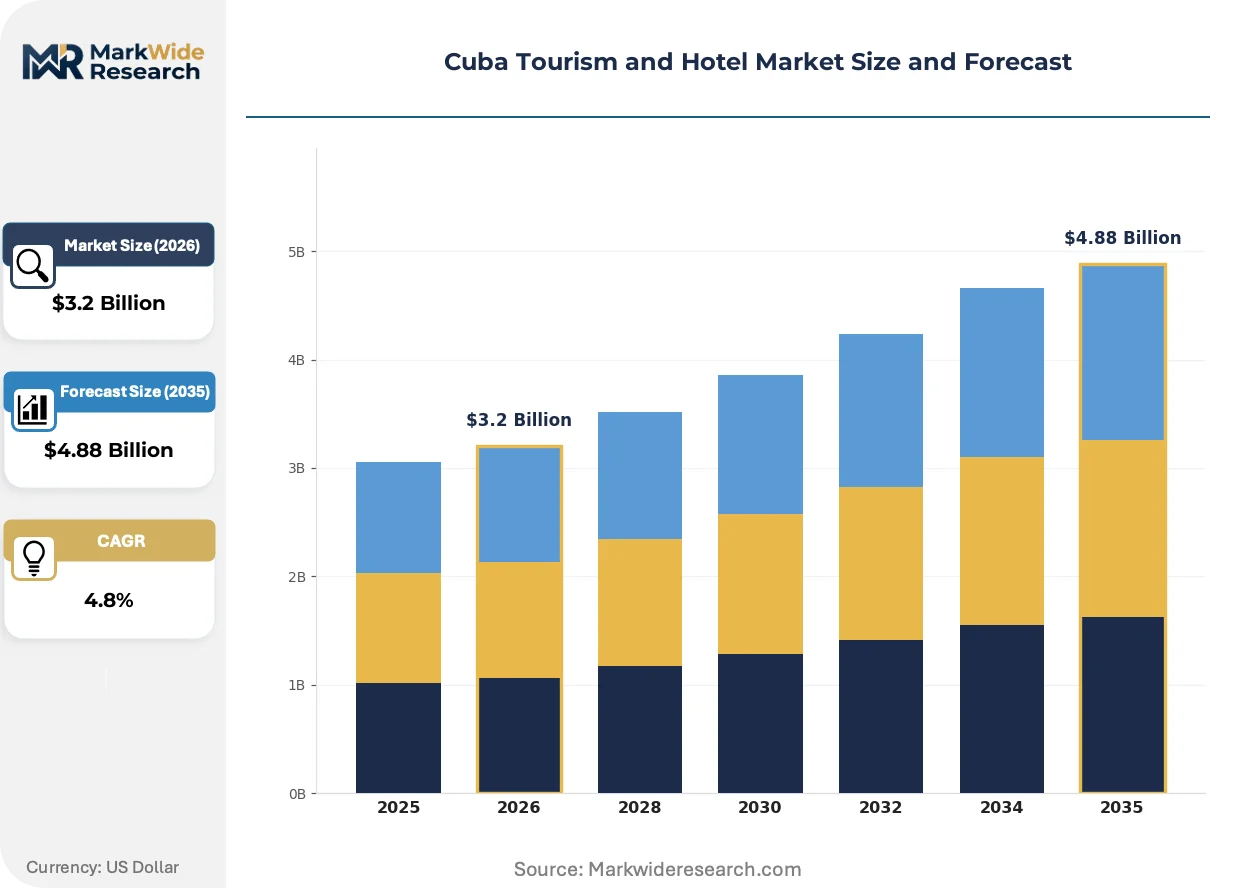
| Market Size in 2026 | $3.2 Billion |
| Market Size in 2035 | $4.88 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Accommodation Type: Luxury Hotels, Boutique Hotels, All-Inclusive Resorts, Hostels Tourism Segment: Leisure, Business, Medical, Educational Customer Type: Domestic Travelers, International Tourists, Student Groups, Family Vacations Service Model: Full-Service, Self-Catering, Shared Accommodation, Bed & Breakfast |
| Companies Covered | Intrepid Travel, InsightCuba, Meliá Hotels International, Cuba Private Travel, Cultural Cuba, Iberostar, Abercrombie & Kent, Exodus Adventure Travels, G Adventures, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cuba Tourism and Hotel Market Strategic Shifts
Digital booking infrastructure is fragmenting traditional tour operator control over Cuba itineraries, with direct-to-consumer platforms capturing independent traveler segments previously served by package providers.
Contactless payment systems using European and Canadian card networks are displacing cash-dependent transaction models that dominated Cuban tourism for decades. Independent travelers from Germany and the United Kingdom now expect tap-to-pay functionality at restaurants and retail in Havana. This shift is compressing the informal currency exchange economy that historically captured significant visitor spending.
U.S. Treasury 31 CFR 515.569 regulations governing remittances and banking transactions continue tightening compliance requirements for entities processing Cuba-related payments. Financial institutions in Canada and Europe face enhanced due diligence obligations when clearing transactions for Cuban tourism services. Canadian banks with Caribbean operations are responding by segmenting Cuba-facing accounts into specialized compliance units.
Curated experiential itineraries are replacing standardized beach-resort packages among high-yield European segments. German and Dutch travelers now prioritize tobacco farm visits, salsa instruction, and private chef engagements over traditional all-inclusive stays. This pattern concentrates in Havana and Trinidad, where supply of authentic cultural intermediaries remains constrained relative to demand growth.
Cuba Tourism and Hotel Market Segmentation
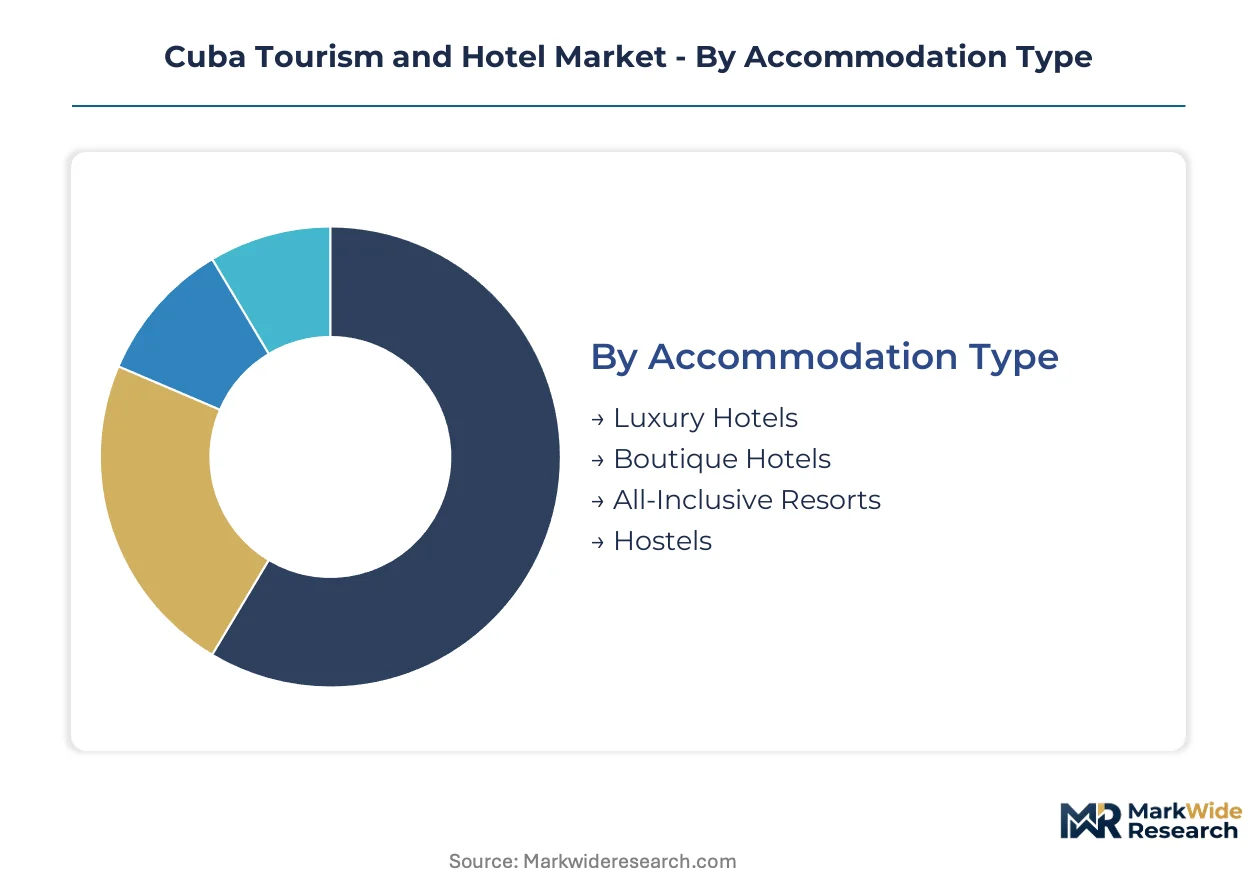
Segmentation in Cuba's tourism market reveals how regulatory constraints and currency dualities create divergent operational models across accommodation and service categories. Understanding these divisions helps operators align capital deployment with the specific compliance and infrastructure requirements of each segment.
Accommodation Type:
Geographic concentration varies sharply: luxury and all-inclusive properties cluster in Varadero and beach corridors serving international markets, while boutique hotels and hostels concentrate in Havana and colonial cities capturing independent travelers.
- Luxury Hotels:High-specification properties with full concierge, spa, and fine dining facilities. Demand concentrates in Varadero and Havana's Miramar district, driven by Canadian and European high-yield leisure segments seeking premium beachfront and urban positioning.
- Boutique Hotels:Small-format conversions of colonial-era structures with curated design and localized service. Heritage tourism demand in Old Havana and Trinidad fuels expansion, with independent European travelers booking extended stays through direct channels.
- All-Inclusive Resorts:Self-contained beachfront compounds with bundled meals, beverages, and activities. Sunwing and Air Canada charter contracts sustain year-round occupancy in Varadero and Holguín.
- Hostels:Budget dormitory and shared-room formats targeting backpacker and student segments. European independent travelers drive demand in Havana Centro and Santiago de Cuba.
All-inclusive resorts command the established base. The steepest expansion runs through boutique hotels.
Tourism Segment:
Cost tier stratification separates capital-intensive infrastructure from lighter-touch programming: leisure and medical tourism require dedicated physical assets, while business and educational segments run on itinerary design and compliance expertise.
- Leisure:Beach, cultural, and recreational travel with discretionary spending on dining, excursions, and retail. Canadian snowbird demand sustains Varadero occupancy through winter months.
- Business:Corporate meetings, incentive travel, and professional conferences. Limited convention infrastructure in Havana constrains scale relative to Caribbean competitors.
- Medical:Healthcare-seeking travel for specialized treatments and wellness programs. Cuban state health institutions partner with foreign facilitators for cardiology and rehabilitation packages.
- Educational:People-to-people cultural exchange under U.S. Treasury general license frameworks. InsightCuba and accredited operators structure compliant itineraries for American university and alumni groups.
Leisure travel commands the established base. Educational programming shows the steepest expansion trajectory as U.S. policy windows open.
Customer Type:
Volume distribution tilts heavily toward international inbound, with domestic Cuban travel constrained by peso purchasing power and MLC access limitations.
- Domestic Travelers:Cuban nationals traveling within the country, primarily for family visits and domestic holidays. Peso-denominated pricing at state-run properties serves this segment at lower margins.
- International Tourists:Foreign visitors from Canada, Europe, and licensed U.S. programs. Hard currency earnings prioritize this segment for joint venture operators.
- Student Groups:Organized educational travel from European universities and U.S. accredited institutions. Semester-length programs in Havana concentrate demand in designated academic housing.
- Family Vacations:Multi-generational leisure bookings with extended stays and excursion add-ons. Canadian market all-inclusive packages dominate this category.
International tourists command the established base. Student groups are climbing the fastest as educational partnerships multiply.
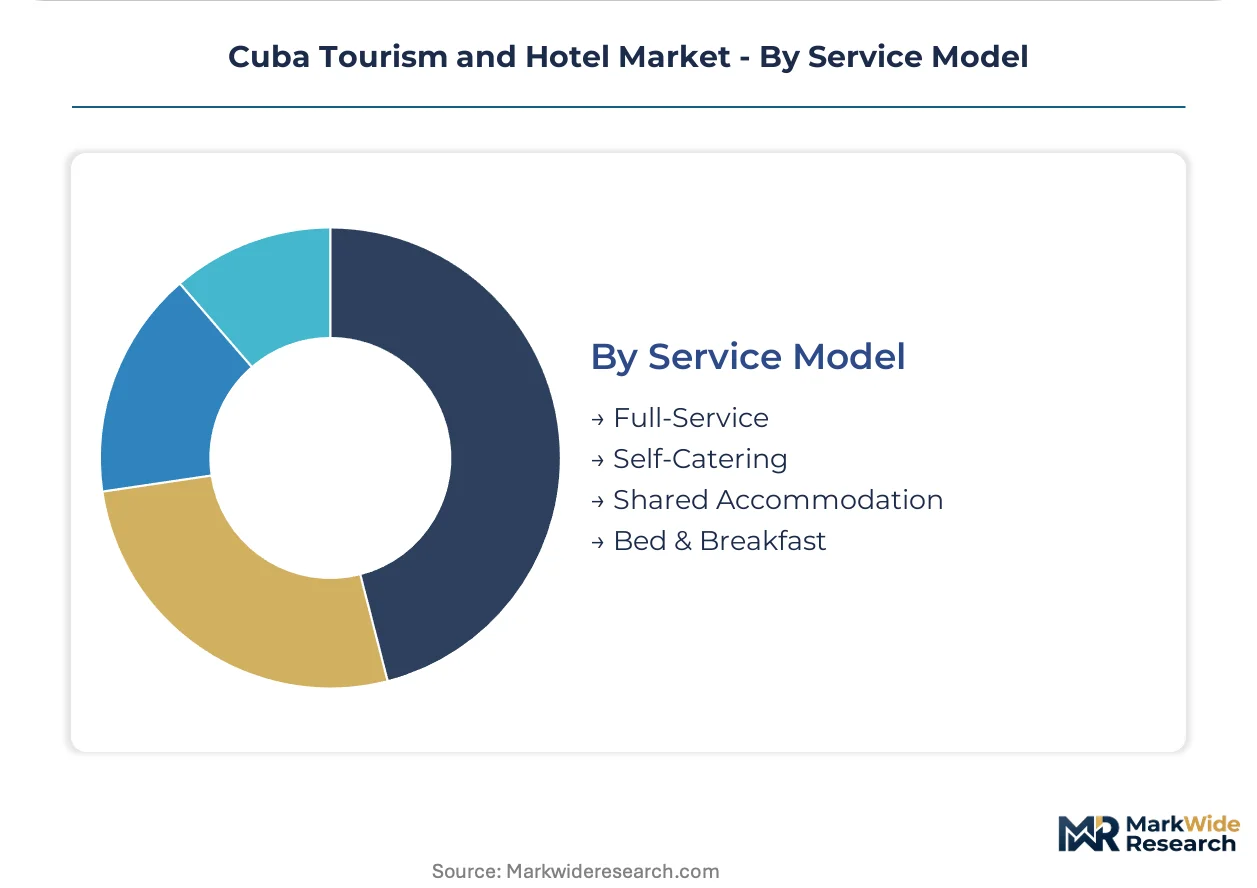
Service Model:
Margin structure differentiates capital-heavy full-service operations from asset-light shared formats, with regulatory compliance burden varying across the spectrum.
- Full-Service:Comprehensive hospitality with on-site dining, housekeeping, and concierge. Meliá and Iberostar joint ventures operate at scale under MINTUR oversight.
- Self-Catering:Apartment and villa formats with kitchen facilities and minimal staff interaction. European independent travelers in Havana Vedado and Miramar drive demand.
- Shared Accommodation:Platform-mediated private room rentals in residential properties. Regulatory ambiguity around casa particular licensing creates operational friction.
- Bed & Breakfast:Small-scale owner-operated lodging with breakfast inclusion. Colonial city centers in Trinidad and Camagüey support this format.
Full-service properties command the established base. Self-catering units gain share fastest as direct booking platforms fragment traditional package control.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
OFAC licensing shifts under successive U.S. administrations create stop-start investment cycles that compress capital deployment timelines for Cuba-facing operators across Caribbean tourism corridors.
Canada
Air Canada and Sunwing maintain year-round charter capacity to Varadero and Holguín, feeding all-inclusive resort occupancy during low-season months when European arrivals taper. Transport Canada safety regulations govern bilateral air service agreements that sustain this route density. Toronto-based tour operators cluster package offerings around winter sunbird demand.
Spain
Meliá Hotels International leverages Spanish-Cuban joint venture structures to dominate beachfront resort operations across multiple provinces. Spain's Ministry of Industry, Trade and Tourism oversees outward investment frameworks that facilitate these hospitality partnerships. Madrid-headquartered operators concentrate management expertise in Varadero and Cayo Coco corridors.
Germany
German independent travelers drive demand for curated experiential itineraries including tobacco farm visits and private chef engagements in Havana and Trinidad. The Federal Foreign Office travel advisory system influences booking confidence for Caribbean destinations. Berlin and Munich-based tour specialists structure people-to-people compliant programs for educational segments.
United Kingdom
British travelers now expect contactless payment functionality at Havana restaurants and retail, displacing cash-dependent transaction models. The Financial Conduct Authority oversees compliance obligations for banks clearing Cuba-related tourism payments. London-based booking platforms fragment traditional package control through direct-to-consumer channels.
France
French heritage tourism demand concentrates in Old Havana boutique hotel conversions, with travelers booking extended stays through direct channels. The French Development Agency participates in cultural preservation financing that supports colonial-era structure rehabilitation. Paris-based operators specialize in high-yield experiential programming for independent European segments.
Cuba Tourism and Hotel Market Competitive Environment
Listed leaders compete with private specialists across accreditation and licensing dimensions, creating a bifurcated field between full-service providers and informal booking channels. The vendor base stratifies across three tiers: multinational hotel chains with state joint ventures, licensed tour operators with ASTA membership, and unaccredited platform-mediated services. Strategic moves center on M&A to secure operational scale and partnerships to navigate OFAC compliance windows.
Within the multinational hotel tier, Meliá Hotels International and Iberostar occupy positions as Spanish-based joint venture anchors with centralized supply chains across Cuban provinces. Among licensed tour operators, InsightCuba exemplifies the educational travel archetype through curated people-to-people itineraries. These three companies represent distinct competitive positions: resort-scale operations, multi-province hospitality networks, and compliance-focused programming specialists.
| Leading Market Players |
|---|
| Intrepid Travel |
| InsightCuba |
| Meliá Hotels International |
| Cuba Private Travel |
| Cultural Cuba |
| Iberostar |
| Abercrombie & Kent |
| Exodus Adventure Travels |
| G Adventures |
| Others |
Value Chain & Pricing Dynamics
Charter-contract pricing between Canadian tour operators and Varadero all-inclusive resorts locks in occupancy floors and foreign-exchange revenue visibility across seasonal demand cycles. These bilateral agreements tether room-rate predictability to guaranteed airlift capacity, compressing pricing volatility even as spot-market boutique rates in Havana fluctuate with European booking patterns.
Pricing Analysis
Certification level through ASTA membership and Cuba-specific OFAC licensing creates the primary spread between accredited full-service providers and informal booking channels. Three-tier pricing structure across luxury beachfront, heritage boutique, and hostel dormitory levels stratifies by service bundling and compliance overhead. Pricing pressure stems from contactless payment infrastructure investments required to capture European independent travelers. Hostel operators in Havana Centro exhibit highest price sensitivity due to platform-mediated rate transparency, while Meliá and Iberostar joint ventures maintain lowest sensitivity through charter-contract anchoring.
Supply Chain Analysis
Inventory lead times for food and beverage operations stretch 45-60 days due to third-country sourcing through Panama and Mexico. Supply concentration in Spanish joint-venture hoteliers and Canadian charter carriers feeds from agricultural imports via Mexican distributors and European payment processing through Canadian bank compliance units. Single-source vulnerability sits with Cuban state employment agencies for hospitality staffing. Distribution runs through MINTUR-licensed tour operators and direct-to-consumer platforms fragmenting traditional package control.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cuba's tourism market represents early-cycle expansion as boutique hotel conversions in colonial-era structures accelerate heritage tourism penetration beyond established beach-resort concentration.
For Market Incumbents: Secure charter-contract renewals with Air Canada and Sunwing ahead of electoral-cycle OFAC volatility, while deepening direct-booking platform integration to capture independent European travelers bypassing traditional package channels. State employment protocol constraints threaten workforce flexibility; vertical integration into proprietary training academies mitigates MINTUR staffing friction. For New Entrants and Emerging Players: Anchor in Viñales Valley ecotourism and Trinidad colonial inventory expansion, the most penetrable white-space segments relative to oversaturated Varadero beach corridors. Partner with Cuban state entities on marina infrastructure development at Cienfuegos to capture Caribbean yacht charter demand. Position through curated experiential itineraries emphasizing tobacco farm stays and private chef engagements for German and Dutch independent travelers. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among ASTA-accredited tour operators with OFAC-compliant people-to-people programming, offering visibility through policy windows. Long-term viability across the 5-10 year horizon rests on diversification beyond U.S. traveler dependency toward Canadian and European source markets. Monitor OFAC general license rulemaking timelines as the primary inflection signal for capital deployment sequencing.| Strategic Initiative | Industry Significance |
|---|---|
| Heritage Boutique Conversion | UNESCO preservation financing unlocks colonial-era inventory expansion in Old Havana and Trinidad. |
| Marina Infrastructure Partnership | Cuban state nautical tourism plans at Varadero and Cienfuegos create berthing capacity for yacht charter operators. |
| Contactless Payment Integration | European and Canadian card network adoption displaces cash-dependent transaction models in Havana retail. |
| People-to-People Licensing | OFAC 31 CFR 515.565 compliance expertise differentiates educational itinerary providers for American university groups. |
| Ecotourism Product Development | Tobacco farm stays and cave system exploration in Viñales Valley remain underdeveloped relative to coastal resort concentration. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with MINTUR licensing officers, ASTA-accredited tour operator executives, Cuban state bank foreign-exchange specialists, and Canadian charter airline route planners. Secondary validation drew from OFAC Federal Register rulemaking archives, Cuban Central Bank regulatory circulars, Transport Canada bilateral air service agreements, and UNESCO World Heritage preservation financing disclosures. Bottom-up property inventory counts triangulated against top-down inbound arrival statistics from the Caribbean Tourism Organization.
Across the analysis window, the forecasting framework modeled accommodation type segmentation by operational structure and foreign-exchange earnings priority, tourism segment by physical asset intensity versus compliance expertise requirements, and customer type by hard currency access and booking channel preferences. CAGRs were derived from trend extrapolation of Canadian charter capacity commitments, European independent traveler growth patterns, and boutique hotel conversion pipelines in designated heritage zones. Inputs incorporated OFAC administrative policy shift probabilities and Cuban state employment protocol evolution.
Material uncertainties — electoral-cycle Treasury Department rulemaking, Cuban peso convertibility reforms, and hurricane-season infrastructure disruption — sit outside the modeled envelope. Forecasts reflect assumptions around sustained Canadian leisure demand and gradual European payment system integration. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hotels and Resorts
Hotel Furniture and Furnishing Market
Hotels and Resorts
Philippines Tourism and Hotel Market
Hotels and Resorts
Global Floating Hotels Market
Hotels and Resorts
Morocco Tourism and Hotel Market
Hotels and Resorts
Morocco Hospitality Market
Hotels and Resorts
India Luxury Hotel Market
Hotels and Resorts
Morocco Tourism Market
Hotels and Resorts
Global Beach Hotels Market
Hotels and Resorts
Spa Resorts Market
Hotels and Resorts
Hotels, Resorts, and Cruise Lines Market
Hotels and Resorts
Europe Luxury Hotel Market
Hotels and Resorts
Asia-Pacific Luxury Hotel Market
Hotels and Resorts
Hotel Armchair Market
Hotels and Resorts
Germany HRI Market
Hotels and Resorts
Five Star Hotel Market
Hotels and Resorts
United States Luxury Hotel Market