
 Personal Luxury Goods Market | 2026-2036
Personal Luxury Goods Market Size, Share, and Industry Trends Forecast 2026-2036
Personal Luxury Goods Market Analysis
Ultra-premium craftsmanship is bifurcating the competitive landscape between artisan-grade ateliers and scaled heritage houses. LVMH Moët Hennessy - Louis Vuitton, SE leverages vertical integration across tanneries and ateliers to control raw material quality. Hermès International SCA anchors its position through deliberate scarcity of hand-stitched leather goods. Richemont S.A. dominates the high-complication watch segment with proprietary movements manufactured in Switzerland.
Personal luxury goods encompass wearable and portable items distinguished by superior materials, artisanal construction, and brand heritage, typically incorporating precious metals, exotic leathers, or hand-finished mechanical components to signal social status and enduring value. Jewelry and watches command the deepest margin pools due to inelastic pricing and gem certification premiums. Handbags sustain the fastest volume trajectory among product types, driven by entry-luxury aspirational buyers. Online retail is displacing department stores as the primary growth channel, though showrooms retain importance for bespoke and exclusive-tier transactions.
REACH and RoHS in Europe restrict chemical use in tanning and metal plating, while China's SAMR enforces stricter labeling and anti-counterfeiting standards for imported luxury goods. The EU Green Deal's due diligence requirements are forcing supply chain transparency from raw material extraction through finished goods. Stakeholders must monitor how carbon border adjustments and evolving digital product passports reshape cost structures and consumer authentication expectations.
Market Dynamics
Ultra-premium craftsmanship is bifurcating the competitive landscape between artisan-grade ateliers and scaled heritage houses, while REACH compliance and evolving customs valuation rules reshape sourcing strategies across leather goods and precious metals.
Growth Catalysts
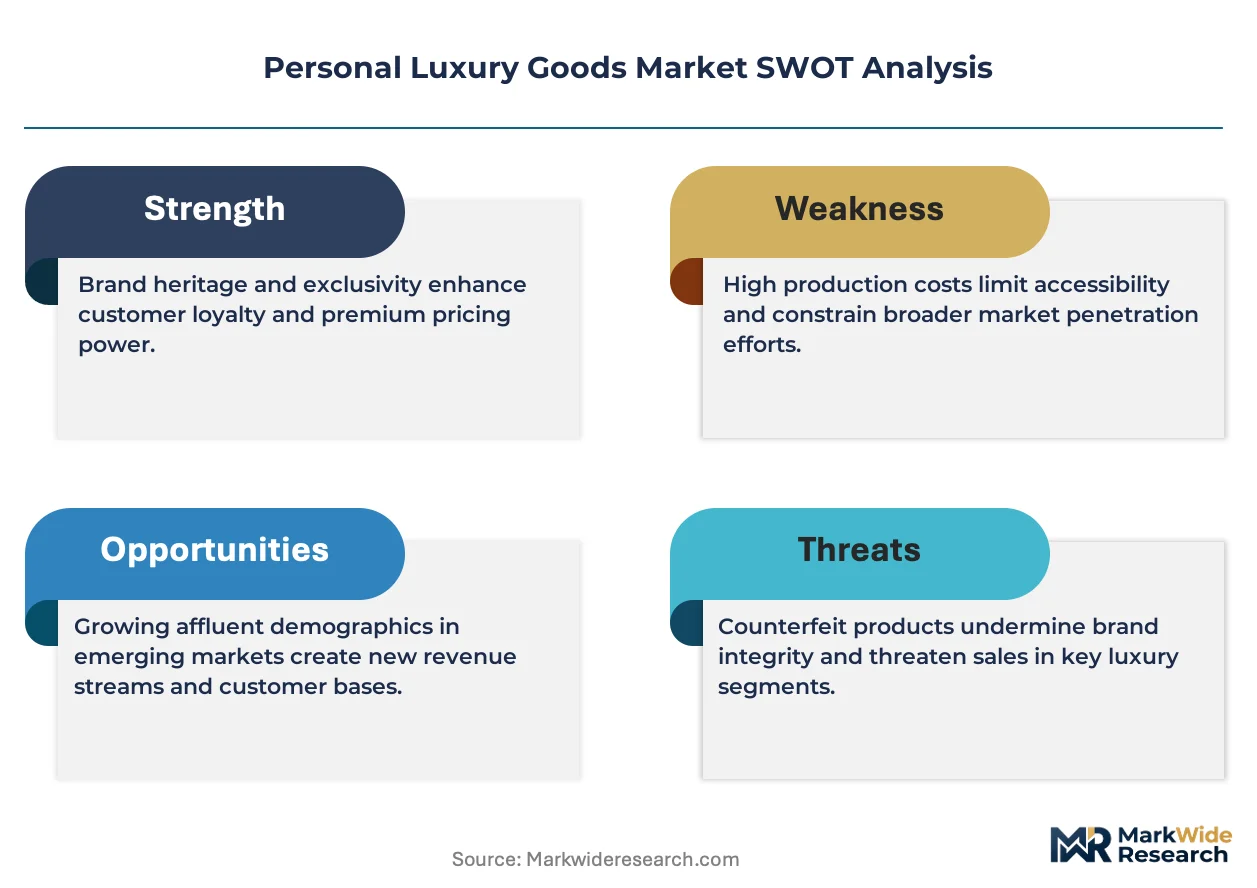
- Affluent consumer expansion:Emerging economy wealth creation, particularly in China's tier-one cities, channels discretionary spending toward heritage-positioned accessories with proven resale value.
- REACH chemical restrictions:European ECHA mandates on tanning and metal plating accelerate investment in compliant supply chains, creating certification premiums for early adopters.
- Domestic consumption pivot:China's SAMR enforcement of stricter labeling and anti-counterfeiting standards redirects cross-border purchasing toward authorized domestic retail channels.
Market Restraints
- Raw material concentration:Exotic leather sourcing concentrates among limited tanneries in France and Italy, exposing margins to supply disruptions and quota limitations.
- Carbon border adjustments:EU Green Deal due diligence requirements impose traceability costs from raw material extraction through finished goods, compressing mid-tier profitability.
- Mechanical watch substitution:Smartwatch adoption among aspirational buyers under 35 erodes entry-luxury timepiece volume in price-sensitive segments.
Strategic Opportunities
- Digital product passports:EU-mandated blockchain-based authentication creates service revenue streams and secondary market control for heritage houses with integrated IT infrastructure.
- Bespoke atelier networks:Ultra-high-net-worth demand for made-to-order leather goods supports geographic expansion of appointment-only showrooms in Dubai, Singapore, and Miami.
- Recycled precious metals:Circular sourcing requirements under EU Green Deal open certified-recycled supply lines as a differentiated positioning axis for jewelry collections.
Industry Challenges
- Artisan talent scarcity:Hand-stitching and high-complication watchmaking skills face generational attrition, extending training pipelines and constraining production scalability.
- Legacy system integration:ERP modernization for supply chain transparency conflicts with decades-old inventory management architectures at established maisons.
- Customs valuation disputes:China's evolving transfer pricing scrutiny on related-party leather imports creates audit exposure and working capital delays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Personal Luxury Goods Market |
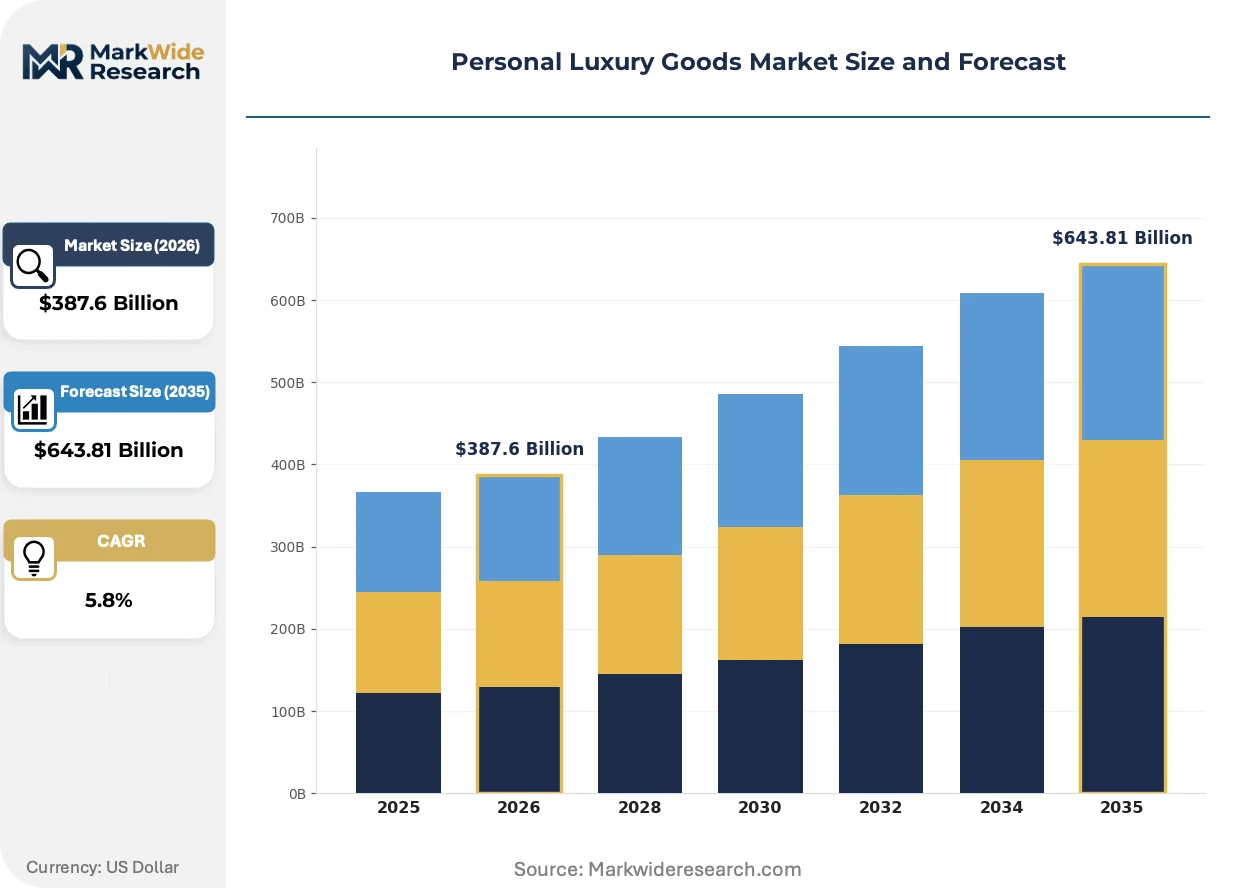
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $643.81 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Jewelry, Watches, Handbags, Clothing Customer Type: Affluent Consumers, Celebrities, Influencers, Corporates Distribution Channel: Online Retail, Specialty Stores, Department Stores, Showrooms Brand Positioning: Premium, Exclusive, Artisan, Heritage |
| Companies Covered | Kering SA, Richemont S.A., LVMH Moët Hennessy - Louis Vuitton, SE, Prada S.p.A., Tapestry, Inc., Hermès International SCA, Chanel Ltd., Burberry Group plc, Christian Dior SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Personal Luxury Goods Market Emerging Trajectories
Technology convergence and regulatory digitization are reconfiguring how authenticity is verified, how supply chains are monitored, and how consumers discover and transact across price tiers.
NFC-enabled authentication chips embedded in leather goods and watch cases enable instant verification through smartphone applications. Entry-luxury buyers in Asia-Pacific adopt this capability fastest, with digital-native generations expecting seamless ownership documentation. Physical certificates and paper warranties is supplanting cloud-based provenance records that transfer across resale transactions.
EU Green Deal due diligence requirements now mandate supply chain mapping from raw material extraction through retail. Leather goods manufacturers face expanded documentation burdens for exotic skins and precious metals. Small ateliers without captive tannery relationships encounter compliance cost barriers that favor scaled houses with in-house legal and sustainability functions.
Discovery and purchase behavior concentrates in brand-controlled digital channels, displacing department store foot traffic as the primary trial mechanism. China's tier-one city consumers complete research through social commerce platforms before booking showroom appointments for tactile validation. Cross-border daigou purchasing collapses as domestic price parity and SAMR enforcement reduce arbitrage incentives.
Personal Luxury Goods Market Segmentation
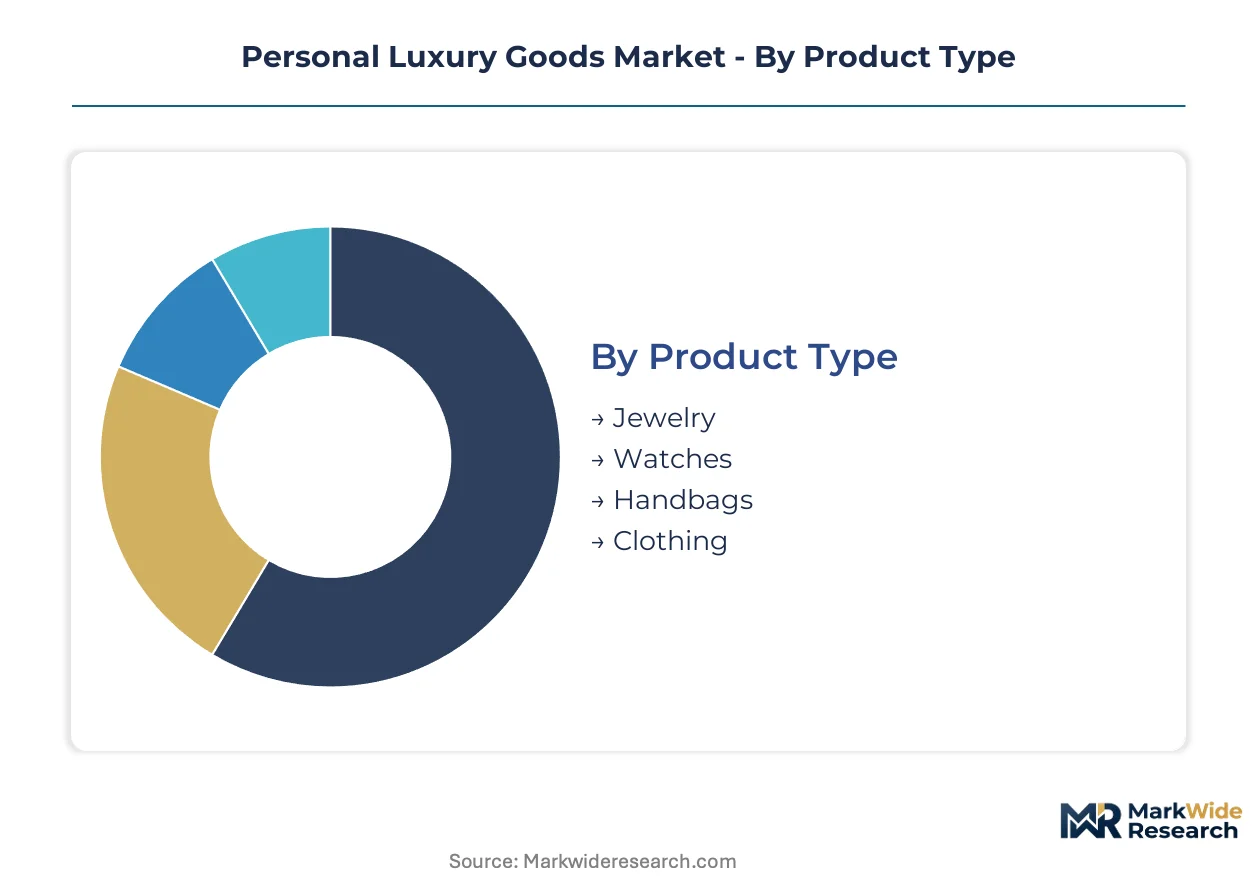
Personal luxury goods segmentation reveals how margin pools concentrate in gem-intensive categories while volume growth shifts toward accessible leather accessories. Understanding these divergent profit mechanics enables targeted resource allocation across product development and channel deployment.
Product Type:
Margin concentration sits deepest in categories where material certification and perpetual scarcity sustain pricing power across economic cycles.
- Jewelry:Pieces incorporating certified gemstones and recycled precious metals command the highest unit economics. Demand clusters in China's tier-one cities where domestic consumption now exceeds cross-border purchasing, reinforced by SAMR anti-counterfeiting enforcement that channels buyers toward authorized retail.
- Watches:Mechanical timepieces with proprietary Swiss movements anchor the ultra-premium tier. Entry-luxury volume faces substitution pressure from smartwatch adoption among buyers under 35, while high-complication pieces sustain artisan scarcity premiums.
- Handbags:Leather goods with exotic skins and hand-stitched construction represent the fastest volume trajectory. REACH-compliant tanneries in France and Italy concentrate supply, creating certification barriers for non-integrated competitors.
- Clothing:Ready-to-wear collections with atelier-grade finishing occupy the most fragmented competitive position. Made-to-measure services in Dubai and Singapore showrooms differentiate ultra-high-net-worth propositions.
Jewelry holds installed capacity. Handbags are rotating up the share rankings.
Customer Type:
Volume distribution skews toward digitally native purchasers whose discovery patterns reshape channel investment priorities.
- Affluent Consumers:Emerging economy wealth creation in China's tier-one cities and Gulf Cooperation Council states drives heritage-positioned accessory demand. These buyers research through social commerce platforms before showroom validation.
- Celebrities:Red carpet and editorial placement generates aspirational pull for entry-luxury segments. Procurement concentrates through stylist relationships and direct maison gifting programs.
- Influencers:Digital-native content creators accelerate discovery among under-35 demographics. Authenticity verification through NFC-enabled chips matches their expectation of seamless ownership documentation.
- Corporates:Executive gifting and client entertainment sustain stable demand for emblematic pieces with proven resale value. Bulk procurement favors houses with established B2B account infrastructure.
Affluent Consumers anchor current volume. Influencers are climbing the fastest as a demand segment.
Distribution Channel:
Channel economics bifurcate between scalable digital reach and high-touch experiential validation for bespoke transactions.
- Online Retail:Brand-controlled e-commerce and social commerce platforms displace department stores as the primary growth channel. China's tier-one city consumers complete majority of research digitally before purchase commitment.
- Specialty Stores:Flagship locations in Paris, Milan, and Tokyo concentrate ultra-premium conversion. These assets require sustained capital deployment for renovation cycles and experiential technology integration.
- Department Stores:Legacy wholesale relationships face margin compression as direct-to-consumer channels capture share. Reduced foot traffic limits their role to clearance and entry-luxury trial.
- Showrooms:Appointment-only spaces in Dubai, Singapore, and Miami support made-to-order leather goods and high-jewelry consultations. EU Green Deal due diligence requirements favor houses with integrated supply chain transparency for these high-value interactions.
Specialty Stores hold installed capacity. Online Retail is gaining share fastest.
Brand Positioning:
Positioning tiers reflect divergent investment requirements in artisan talent cultivation versus scaled marketing efficiency.
- Premium:Accessible luxury tier targeting aspirational buyers with entry-level leather goods and diffusion jewelry lines. Volume scalability depends on compliant sourcing from REACH-certified tanneries.
- Exclusive:Limited-production pieces with controlled distribution through flagship and showroom channels. Scarcity engineering sustains resale market premiums and collector community engagement.
- Artisan:Hand-crafted atelier output with generational skill transmission requirements. Training pipeline constraints limit production scalability regardless of demand absorption.
- Heritage:Centuries-old maisons leveraging vertical integration into tanneries and proprietary movement manufacture. EU-mandated digital product passports reinforce authentication control and secondary market participation.
Heritage holds installed capacity. Artisan is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances diverge sharply across major luxury economies. France and Italy maintain structural surpluses in finished leather goods and timepieces. China absorbs the largest import volume while building domestic production capacity. Switzerland exports high-value watch movements to assembly points worldwide.
China
Domestic consumption in Shanghai, Beijing, and Shenzhen now exceeds cross-border purchasing as SAMR enforcement tightens labeling requirements. The country's anti-counterfeiting standards redirect demand toward authorized retail channels. Hainan duty-free zones concentrate inbound tourism spending with streamlined customs procedures.
France
Paris and Lyon anchor global supply for heritage-positioned leather goods with REACH-compliant tanneries clustered in the Rhône-Alpes region. ECHA chemical restrictions on tanning processes accelerate investment in compliant supply chains. The country's export surplus in finished accessories widened as Italian competitors faced raw material constraints.
Italy
Florence and Milan concentrate artisan-grade production for exotic leather goods with generational skill transmission in Tuscan ateliers. EU Green Deal due diligence requirements impose traceability documentation from raw material extraction through retail. The domestic industry faces margin pressure from carbon border adjustment mechanisms affecting energy-intensive tanning operations.
Switzerland
Geneva and the Jura Arc dominate high-complication watch manufacturing with proprietary movement production subject to Swissmade certification standards. The country's export value per unit exceeds all competing origins due to inelastic pricing for mechanical timepieces. METI-equivalent federal oversight maintains strict geographic origin requirements for precious metal finishing.
United States
New York and Los Angeles serve as primary entry points for European-imported luxury goods with domestic consumption concentrated among ultra-high-net-worth households. Customs valuation scrutiny from CBP creates audit exposure for related-party leather imports. Miami's showroom expansion targets Latin American buyers seeking appointment-only atelier access.
Personal Luxury Goods Market Vendor Landscape
Concentration sits with heritage houses possessing captive tannery and movement manufacture capabilities. The competitive landscape bifurcates between scaled conglomerates with portfolio diversification and artisan-grade ateliers with deliberate production constraints. Three archetypes dominate: vertically integrated luxury groups, family-controlled scarcity engineers, and accessible-premium consolidators. Strategic moves center on supply chain certification investments and digital product passport deployment for secondary market control.
Among French heritage houses, LVMH Moët Hennessy - Louis Vuitton, SE and Hermès International SCA exemplify divergent scarcity architectures. Richemont S.A. anchors the Swiss watch segment with Geneva-based manufacturing heritage. Kering SA occupies a position between pure luxury positioning and accessible contemporary segments.
| Leading Market Players |
|---|
| Kering SA |
| Richemont S.A. |
| LVMH Moët Hennessy - Louis Vuitton, SE |
| Prada S.p.A. |
| Tapestry, Inc. |
| Hermès International SCA |
| Chanel Ltd. |
| Burberry Group plc |
| Christian Dior SE |
| Others |
Supply Flow & Price Mechanics
Recycled precious metals substitution for virgin-mined gold and platinum simultaneously redraws European tannery geography and compresses margin premiums for mid-tier jewelry houses unable to certify circular sourcing under EU Green Deal due diligence rules.
Pricing Analysis
Ultra-high-net-worth collectors anchor pricing power through inelastic demand for artisan-grade atelier output with generational skill transmission. Pricing stratifies across heritage houses with captive tanneries, exclusive-tier scarcity engineers, and accessible-premium diffusion lines. Cost compression in entry-luxury leather goods intensifies as REACH-compliant tanning certification premiums favor scaled conglomerates over independent ateliers. Aspirational buyers under 35 exhibit highest price sensitivity, while established collectors demonstrate near-zero elasticity for high-complication mechanical timepieces.
Supply Chain Analysis
France and Italy anchor global supply for heritage-positioned leather goods with exotic skin tanning concentrated in Rhône-Alpes and Tuscan clusters. Raw material dependencies draw from crocodile farms in Southeast Asia, precious metal refineries in Switzerland, and gemstone cutting centers in India. Single-source vulnerability concentrates in hand-stitching artisan pools facing generational attrition. Distribution runs through brand-controlled flagship networks in Paris, Milan, and Tokyo, with appointment-only showrooms in Dubai and Singapore handling bespoke transactions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ultra-premium craftsmanship bifurcation fragments competitive white space between scaled heritage houses and artisan-grade ateliers, creating entry niches for specialists targeting recycled-material certification and digital-native authentication infrastructure.
For Market Incumbents: Compound scarcity premiums through deliberate production constraints in hand-stitched leather goods while accelerating EU-mandated digital product passport deployment. Backward integration into REACH-certified tanneries defends margin position against mid-tier competitors facing compliance cost barriers. Prioritize artisan talent pipeline investments to offset generational skill attrition threatening production scalability. For New Entrants and Emerging Players: Anchor in recycled precious metals certification as a differentiated positioning axis under EU Green Deal circular sourcing requirements. Target China's tier-one cities where domestic consumption pivot and SAMR enforcement redirect demand toward authorized channels with transparent supply chain documentation. Pursue social commerce-native discovery models matching digital-native buyer research patterns before showroom validation. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated heritage houses with captive tannery relationships and proprietary movement manufacture capabilities over asset-light brand licensors. Long-term viability hinges on supply chain transparency infrastructure enabling secondary market participation and authentication control. Watch for inflection signals in carbon border adjustment implementation affecting energy-intensive Italian tanning operations.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Product Passport Deployment | EU-mandated blockchain authentication creates service revenue streams and secondary market control for integrated maisons. |
| Recycled Precious Metals Certification | Circular sourcing requirements under EU Green Deal open differentiated supply lines for jewelry collections with transparent provenance. |
| Bespoke Atelier Network Expansion | Appointment-only showrooms in Dubai, Singapore, and Miami capture ultra-high-net-worth demand for made-to-order leather goods. |
| Artisan Talent Pipeline Investment | Extended training programs offset generational attrition in hand-stitching and high-complication watchmaking skills constraining scalability. |
| Social Commerce Platform Integration | Brand-controlled digital channels in China's tier-one cities displace department stores as primary discovery mechanism for entry-luxury buyers. |
Methodological Framework
Operator-level perspectives from brand executives, atelier directors, tannery procurement leads, and luxury retail channel managers anchored the qualitative base for this analysis. Primary fieldwork combined structured interviews across heritage houses, independent artisans, and component suppliers with secondary validation from customs trade records, SEC filings of listed luxury groups, and ECHA regulatory documentation. Bottom-up demand modeling across product categories triangulated against top-down macroeconomic consumption indicators.
Sensitivity analysis tested forecast robustness across alternative scenarios for Chinese domestic consumption growth, REACH compliance cost trajectories, and artisan labor supply constraints. Segmentation modeling incorporated product type, customer archetype, distribution channel, and brand positioning tier with regional regulatory cluster differentiation. CAGRs derived from volume-price elasticity functions calibrated to historical margin structure and substitution dynamics between mechanical and smart timepieces.
Decision-makers should treat outputs as directional under assumptions of sustained emerging economy wealth creation and stable EU regulatory enforcement; material deviation in carbon border adjustment timing or Chinese consumption patterns would warrant model refresh. Recalibration cycles align with material shifts in REACH chemical restriction scope and SAMR anti-counterfeiting implementation intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Luxury Goods
Mexico Luxury Goods Market
Luxury Goods
GCC Secondhand Luxury Goods Market
Luxury Goods
Luxury Products for Kids Market
Luxury Goods
Brazil Luxury Goods Market
Luxury Goods
Designer Bags and Luxury Handbags Market
Luxury Goods
India Watch Market
Luxury Goods
Luxury Appraisal Service Market
Luxury Goods
Malaysia Luxury Goods Market
Luxury Goods
Europe Secondhand Luxury Goods Market
Luxury Goods
Italy Luxury Goods Market
Luxury Goods
Spain Luxury Goods Market
Luxury Goods
Luxury Handbag Market
Luxury Goods
Accessible Luxury Goods Market
Luxury Goods
Pre-Owned Luxury Watches Market
Luxury Goods
Global Gold and Diamond Jewellery Market
Luxury Goods
Used Luxury Bags Trading Service Market