
 Landscaping Services Market | 2026-2036
Landscaping Services Market Size, Share, and Industry Trends Forecast 2026-2036
Landscaping Services Market Analysis
Synthetic turf is broadening its addressable footprint across sports facilities and municipal grounds as water restrictions intensify in drought-prone states. BrightView Holdings leverages its national maintenance network to capture recurring revenue from commercial property managers. TruGreen sustains brand recognition in residential lawn care through proprietary treatment protocols. The Davey Tree Expert Company anchors its position in tree preservation services for utility and municipal contracts.
Landscaping services encompass the planning, installation, and ongoing maintenance of vegetated and hardscaped outdoor environments, typically involving soil preparation, plant selection, irrigation system design, and seasonal care schedules calibrated to local climate zones. The primary commercial purpose is to enhance property aesthetics, support ecological function, and ensure regulatory compliance with stormwater and green space ordinances. Lawn Care and Landscape Design together command the largest share of service revenue as property owners prioritize curb appeal and water-efficient layouts. Residential and Commercial customer segments generate the steadiest maintenance contract volumes, while Municipal applications face procurement cycles that compress margins but secure multi-year commitments.
EPA water-use regulations and local stormwater management codes in the United States shape equipment specifications and irrigation system designs across the industry. OSHA landscaping safety standards and state-level pesticide application licensing requirements further determine workforce training investments and operational compliance costs. Stakeholders must monitor evolving drought declarations and building code updates that redefine permissible plant palettes and irrigation technologies.
Market Dynamics
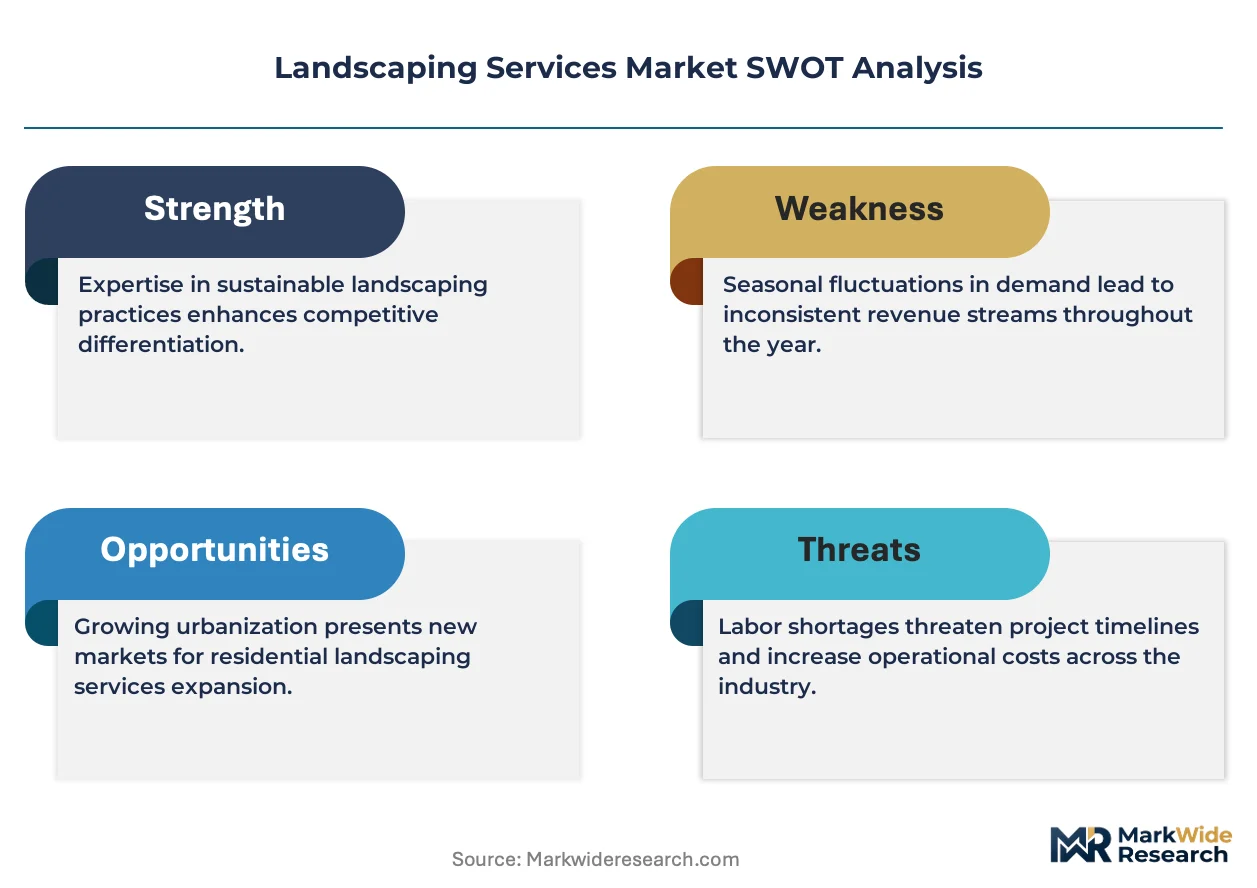
Commercial property managers face escalating compliance burdens as ESG disclosure mandates tighten across multiple jurisdictions, forcing landscaping budgets upward while standardizing service specifications. This regulatory compression is concentrating contract volumes with national maintenance networks capable of delivering auditable sustainability metrics.
Growth Catalysts
- EPA stormwater regulations:Municipalities in drought-prone states mandate permeable hardscapes and bioswales, expanding engineered landscape installation contracts.
- Green building certification pipelines:LEED and BREEAM point systems for commercial assets require native plant palettes and smart irrigation, pulling specialized design services.
- Water scarcity in the southwestern United States:Xeriscaping mandates and turf removal rebates accelerate conversion projects across municipal and residential segments.
Market Restraints
- Diesel equipment cost volatility:Commercial mowing fleets face margin compression from fuel price swings, constraining small-operator expansion.
- Seasonal labor supply concentration:H-2B visa caps limit workforce scaling in peak maintenance months across the northern United States.
- Synthetic turf substitution:Artificial surface durability threatens recurring maintenance revenue from sports field and municipal lawn contracts.
Strategic Opportunities
- Carbon credit eligibility for urban tree planting:Municipalities in California and New York qualify canopy expansion for offset markets, opening public-sector design-build contracts.
- Drone-based irrigation auditing:Thermal imaging convergence with GIS mapping enables precision water-use reports for commercial property ESG filings.
- Electrification incentive stacks:The Inflation Reduction Act equipment credits accelerate battery-powered fleet transitions for maintenance contractors.
Industry Challenges
- Arborist certification bottlenecks:ISA credential timelines lag demand for utility vegetation management contracts, throttling revenue capture.
- Legacy irrigation controller integration:Smart system retrofits require proprietary protocol bridging, complicating upgrade sales for commercial portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Landscaping Services Market |
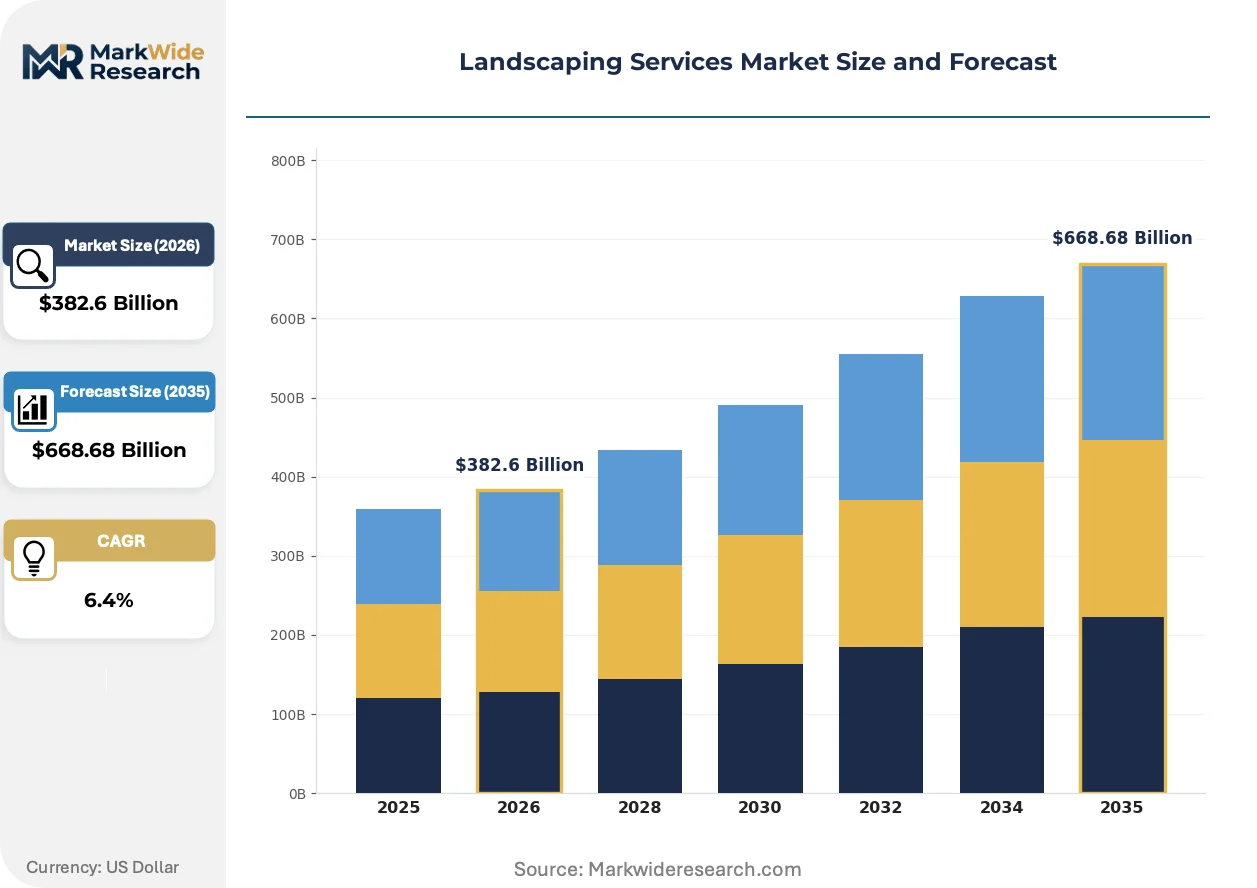
| Market Size in 2026 | $382.6 Billion |
| Market Size in 2035 | $668.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Lawn Care, Landscape Design, Tree Trimming, Irrigation Systems Customer Type: Residential, Commercial, Municipal, Educational Maintenance Type: Regular Maintenance, One-Time Cleanup, Seasonal Planting, Pest Control Application: Public Parks, Private Gardens, Golf Courses, Sports Facilities |
| Companies Covered | The F.A. Bartlett Tree Expert Company, SavATree, BrightView Holdings, LandCare USA, Ruppert Landscape, The Davey Tree Expert Company, Yellowstone Landscape, U.S. Lawns, TruGreen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Landscaping Services Market Emerging Trajectories
Service delivery models are pivoting from reactive maintenance schedules toward predictive, data-driven interventions. Equipment electrification, remote sensing deployment, and outcome-based contracting structures are compressing traditional labor intensity while raising technical barriers to market entry.
Autonomous mowing platforms are automating repetitive turf maintenance across golf courses and corporate campuses. Large commercial property managers in Texas and Florida pilot robotic fleets for overnight cutting cycles. Labor cost arbitrage is compressing as capital expenditure shifts from wage bills to machine depreciation and telemetry subscriptions.
The EU Green Deal biodiversity targets are mandating pollinator corridors and pesticide reduction zones in commercial landscaping specifications. German and French municipal tenders now require integrated pest management certification and native species quotas. Contractors without ecological design capabilities face exclusion from public procurement frameworks.
Subscription-based lawn care packages are displacing per-visit billing in residential channels. TruGreen and regional operators bundle fertilization, aeration, and disease treatment into annual contracts with automated renewal. This pricing consolidation is most advanced in suburban markets across the southeastern United States where homeowner association standards standardize service expectations.
Landscaping Services Market Segmentation
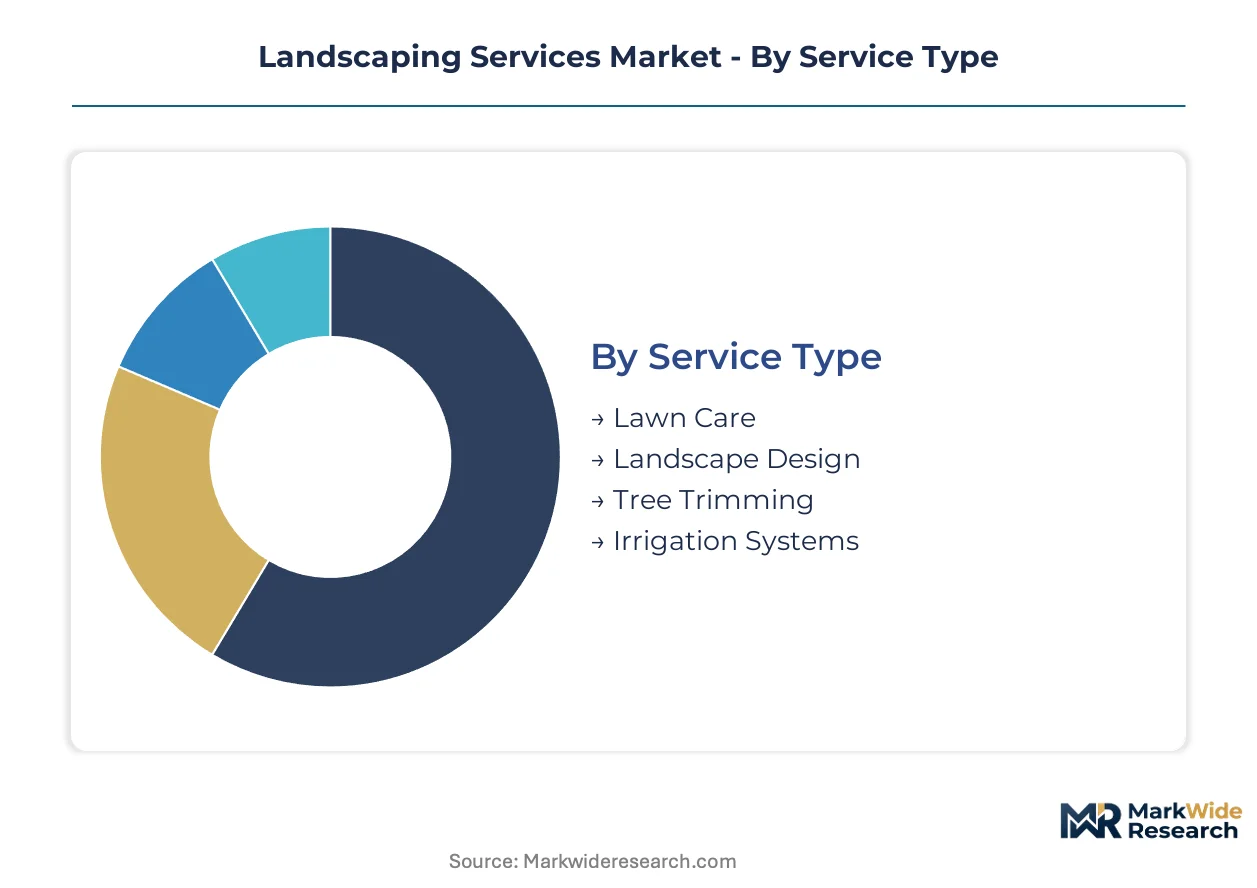
Service specialization determines contractor capability requirements and pricing power in landscaping markets. Customer concentration shapes contract duration, payment terms, and regulatory exposure across operational segments.
Service Type:
Technical complexity separates commodity maintenance from premium design services requiring licensed expertise and specialized equipment.
- Lawn Care:Recurring turf maintenance including mowing, fertilization, and aeration protocols calibrated to USDA hardiness zones. Demand clusters in suburban residential developments across Florida and Texas where HOA covenants mandate weekly service schedules and seasonal treatment regimens.
- Landscape Design:Site planning, plant selection, and hardscape integration requiring CAD visualization and horticultural expertise. Commercial property managers in drought-prone California jurisdictions drive specification toward xeriscape layouts and smart irrigation integration to satisfy municipal water-use ordinances.
- Tree Trimming:Canopy management and hazard mitigation for utility clearance and storm resilience, governed by ISA certification standards and local arborist licensing.
- Irrigation Systems:Design, installation, and retrofit of sprinkler and drip networks, with EPA WaterSense specifications increasingly mandatory for municipal rebate eligibility.
Volume sits with Lawn Care; growth tilts toward Landscape Design.
Customer Type:
Procurement sophistication ranges from individual homeowner discretion to multi-year municipal RFP cycles with bonded performance requirements.
- Residential:Single-family homeowners and multi-unit associations purchasing discretionary aesthetic services with seasonal demand spikes. Subscription bundling is displacing per-visit billing in southeastern markets where automated renewal contracts reduce customer acquisition costs.
- Commercial:Property managers for office, retail, and industrial portfolios requiring auditable sustainability metrics for ESG disclosure. National maintenance networks capture recurring revenue from institutional investors prioritizing LEED certification maintenance across Sun Belt office assets.
- Municipal:City and county contracts for parks, median maintenance, and stormwater infrastructure, subject to prevailing wage requirements and multi-year procurement cycles that compress margins.
- Educational:K-12 districts and university campuses with specialized safety protocols and pesticide-free mandates near student activity zones.
Commercial commands the largest contract values; Educational is expanding most quickly as campus sustainability commitments harden.
Maintenance Type:
Service frequency determines fleet utilization rates and labor scheduling efficiency across the calendar year.
- Regular Maintenance:Scheduled weekly or bi-weekly visits for turf, bed, and hardscape upkeep, generating predictable recurring revenue streams.
- One-Time Cleanup:Post-construction, storm debris, or estate clearance projects with acute labor spikes and equipment mobilization costs.
- Seasonal Planting:Annual flower rotation and perennial installation tied to frost calendars and color scheme specifications.
- Pest Control:Integrated management protocols for turf disease, invasive insects, and weed suppression requiring state applicator licensing.
Regular Maintenance anchors fleet deployment; Pest Control shows the steepest expansion trajectory as regulatory restrictions on chemical applications tighten.
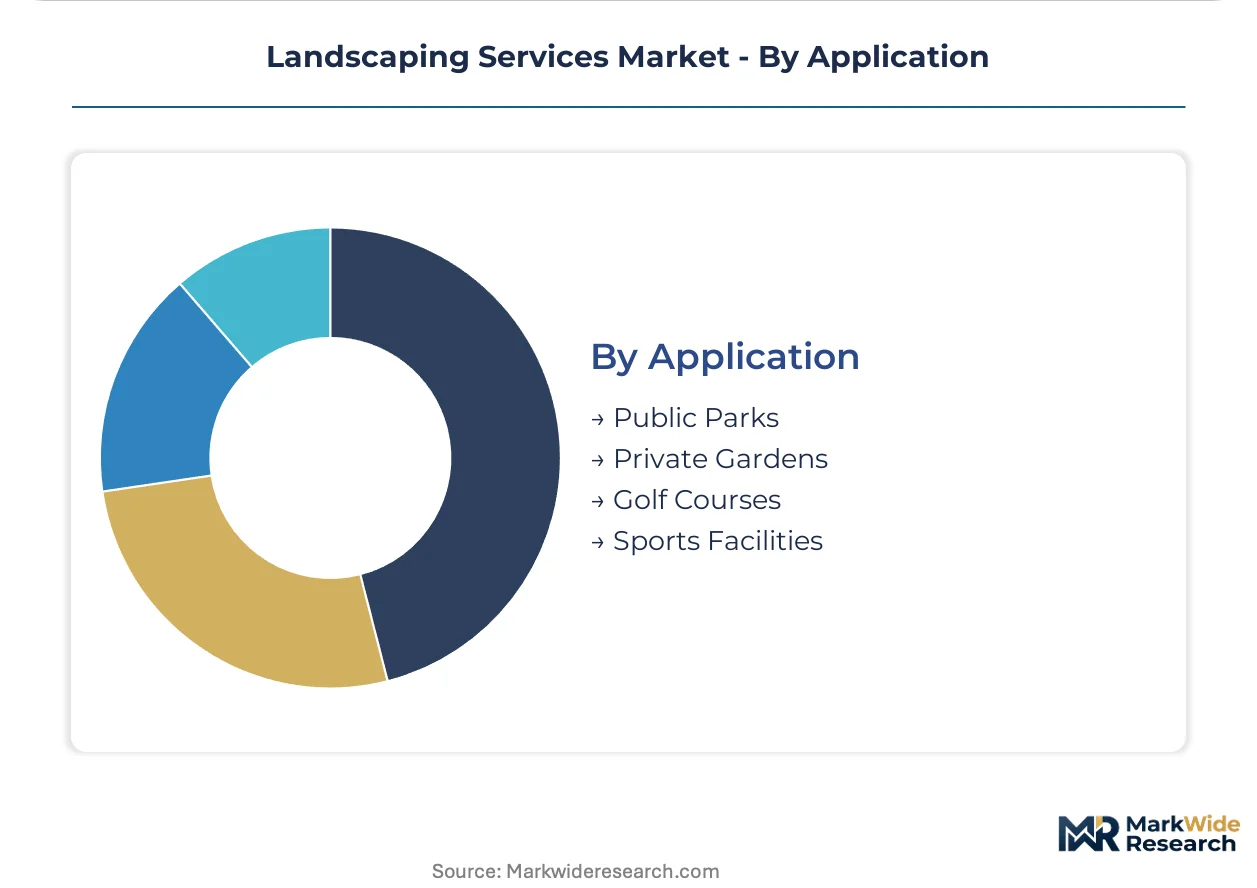
Application:
End-use environment dictates equipment scale, plant palette constraints, and liability exposure for contractors.
- Public Parks:Municipal grounds with high foot traffic, ADA accessibility requirements, and native species mandates for pollinator habitat.
- Private Gardens:Residential estates and corporate courtyards emphasizing aesthetic distinction and water-efficient design.
- Golf Courses:Turf-intensive facilities requiring specialized mowing equipment and agronomic expertise for bentgrass and bermudagrass management.
- Sports Facilities:School and municipal fields facing synthetic turf substitution pressure that threatens recurring natural grass maintenance contracts.
Public Parks generate the steadiest municipal volumes; Private Gardens gain share fastest as residential outdoor living investment climbs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial property managers in the United States drive the largest share of contract value as ESG disclosure mandates tighten. Institutional investors across Sun Belt office markets prioritize green building certification maintenance. Water scarcity regulations in drought-prone states reshape service specifications toward xeriscaping and smart irrigation.
United States
HOA-mandated weekly service schedules in Florida and Texas suburbs generate recurring residential volumes. EPA stormwater regulations and state-level pesticide licensing determine workforce training investments. Dallas-Fort Worth and Phoenix metropolitan clusters concentrate national maintenance network operations for commercial portfolio coverage.
Canada
Municipal park maintenance contracts in Ontario and British Columbia face compressed margins from prevailing wage requirements. Health Canada PMRA standards govern pesticide application protocols near urban waterways. Greater Toronto Area contractors specialize in salt-tolerant plant palettes for winter-hardy commercial installations.
Germany
EU Green Deal biodiversity targets mandate pollinator corridors and pesticide reduction zones in municipal tenders. ECHA REACH compliance shapes equipment specifications for landscape maintenance fleets. Rhine-Ruhr metropolitan contractors integrate integrated pest management certification into public procurement bids.
France
Commercial landscaping specifications in Île-de-France require native species quotas for public space contracts. ANSM and CNIL frameworks influence data collection practices for drone-based irrigation auditing. Lyon and Marseille clusters develop ecological design capabilities for biodiversity-compliant urban greening projects.
Australia
Water restrictions in New South Wales and Queensland accelerate synthetic turf adoption across sports facilities and municipal grounds. State-level stormwater management codes dictate permeable hardscape installation requirements. Sydney and Melbourne metropolitan areas concentrate design-build contractors for drought-adapted landscape conversions.
Landscaping Services Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with national maintenance networks capturing institutional commercial portfolios while regional operators retain residential loyalty. The vendor base organizes around three strategic archetypes: scale-driven national networks, specialized tree care and preservation experts, and technology-integrated precision service providers. Competitive moves concentrate on geographic rollup acquisitions and fleet electrification transitions.
Among national-scale maintenance networks, BrightView Holdings and TruGreen exemplify the branded service model, while The Davey Tree Expert Company anchors the specialized preservation tier. These three occupy positions that reflect divergent capability investments—network density versus technical certification depth versus residential subscription automation.
| Leading Market Players |
|---|
| The F.A. Bartlett Tree Expert Company |
| SavATree |
| BrightView Holdings |
| LandCare USA |
| Ruppert Landscape |
| The Davey Tree Expert Company |
| Yellowstone Landscape |
| U.S. Lawns |
| TruGreen |
| Others |
Supply Flow & Price Mechanics
Certification-tier divergence between ISA-credentialed arborist crews and unlicensed maintenance labor splits pricing power and procurement access across commercial and municipal channels. Premium-tier contractors commanding utility vegetation management contracts leverage credential scarcity for 40-60% rate premiums over commodity mowing services, while supply chain configurations concentrate equipment procurement and workforce training investments around EPA-compliant pesticide applicators and OSHA-certified safety programs.
Pricing Analysis
Volume-massacre splits the market: residential subscription bundles capture scale through automated renewal contracts in southeastern HOA markets, while commercial ESG-auditable services extract margin from LEED certification maintenance mandates. Price differentiation hinges on ISA arborist certification density and smart irrigation EPA WaterSense compliance, with diesel equipment cost volatility compressing margins for fleet-dependent operators. Pricing pressure stems from synthetic turf substitution threats in sports facilities, eroding recurring natural grass maintenance revenue. Municipal procurement faces acute price sensitivity from prevailing wage requirements and multi-year bonded contracts, whereas institutional commercial portfolios absorb premium pricing for auditable sustainability metrics.
Supply Chain Analysis
Workforce availability constraints in Mexico and Central American source markets tighten H-2B visa-dependent labor pipelines for peak-season maintenance scaling across the northern United States. Equipment manufacturing concentrates in China and domestic Midwest production hubs for commercial mowing fleets and irrigation controllers, with supply chains drawing from steel, lithium-ion battery cells, and EPA-compliant small-engine components. Single-source vulnerability sits with proprietary smart irrigation protocol bridging for legacy controller retrofits, complicating upgrade sales. Distribution runs through national maintenance network hubs in Dallas-Fort Worth and Phoenix, with regional operators relying on direct-to-property-manager relationships and municipal procurement portals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Landscaping Services Market functions as a vertical-integration race where fleet electrification and in-house arborist training programs determine cost structure control and credential access. Players pursuing backward integration into battery-powered equipment supply and captive workforce development capture margin compression defense unavailable to subcontractor-dependent operators.
For Market Incumbents: Extend geographic density through rollup acquisitions of regional design-build specialists in drought-prone California and Texas markets, consolidating xeriscape conversion capabilities before municipal rebate programs peak. Deepen backward integration into battery-powered fleet maintenance and telemetry subscription services to offset diesel cost volatility and synthetic turf substitution threats. Prioritize ISA certification pipeline investments to unlock utility vegetation management contracts throttled by arborist credential bottlenecks. For New Entrants and Emerging Players: Drone-based irrigation auditing platforms offer white-space penetration into commercial property ESG filing compliance, with thermal imaging-GIS convergence creating defensible data-service moats. Target mid-market commercial portfolios in Sun Belt office assets underserved by national network coverage, positioning precision water-use reporting against BrightView's maintenance bundling. Deploy direct digital sales channels to bypass incumbent branch infrastructure and capture subscription-based residential lawn care displacement in southeastern markets. For Investors and Strategic Acquirers: Re-rating potential sits with technology-integrated precision service providers given carbon credit eligibility expansion for urban tree planting in California and New York offset markets. Long-term viability across the analysis window favors contractors with ecological design capabilities qualifying for EU Green Deal biodiversity-compliant procurement frameworks. Acquisition target archetype: regional operators with integrated pest management certification and native species quotas positioning for German and French municipal tender exclusion avoidance. Signal to watch: Inflation Reduction Act equipment credit utilization rates as electrification transition velocity indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Fleet Electrification Transition | IRA equipment credits accelerate battery-powered mower adoption, reducing diesel cost exposure and ESG audit compliance burden. |
| Arborist Certification Pipeline Investment | ISA credential capacity expansion unlocks utility vegetation management contracts constrained by qualification bottlenecks. |
| Drone-Based Irrigation Auditing Capability | Thermal imaging-GIS integration enables precision water-use reporting for commercial property ESG disclosure mandates. |
| Regional Design-Build Specialist Acquisition | Xeriscape conversion expertise consolidation captures California and Texas municipal rebate program acceleration. |
| Subscription Billing Platform Deployment | Automated renewal contracts reduce customer acquisition costs in southeastern residential HOA markets. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, combining primary interviews with commercial property managers, municipal procurement officers, landscape contractor operations directors, and ISA-certified arborists with validation against EPA stormwater compliance databases, OSHA landscaping safety standards, and state-level pesticide licensing registries. Bottom-up service-type segmentation triangulated against top-down regional demand modeling ensures cross-verification of contract value estimates and fleet deployment assumptions.
Data-stream reconciliation across the analysis window integrated historical maintenance contract volumes with forward-looking green building certification pipelines and water scarcity regulatory trajectories. Segmentation dimensions modeled include service type specialization, customer procurement sophistication, maintenance frequency scheduling, and end-use environmental constraints, with CAGRs derived from ESG disclosure mandate diffusion rates and drought declaration frequency patterns. Industry-specific forecast inputs incorporated H-2B visa cap volatility and synthetic turf substitution elasticity estimates.
The model holds under stable EPA water-use regulatory enforcement and continued ESG disclosure mandate tightening; deviation in federal immigration policy affecting seasonal labor availability or accelerated synthetic turf technology cost reduction would shift volume and value trajectories. Forecasts reflect documented assumptions regarding green building certification adoption curves and electrification incentive program continuity. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home & Garden
Lawn and Garden Consumables Market
Home & Garden
Artificial Flowers Market
Home & Garden
Hedge Trimmer Market
Home & Garden
Artificial Plants and Flowers Market
Home & Garden
Preserved Flowers Market
Home & Garden
Residential Snow Blower Market
Home & Garden
Lawn and Garden Water Equipment Market
Home & Garden
North America Flower Pots and Planters Market
Home & Garden
US Garden Planter Market
Home & Garden
Automated Blinds and Shades Market
Home & Garden
Asia-Pacific Bonsai Market
Home & Garden
Bird House Market
Home & Garden
Incense Market
Home & Garden
Garage Organization and Storage Market
Home & Garden
Electric Lawn Mower Market
Home & Garden
North America Floral Gifting Market