
 China Pet Food Market | 2026-2036
China Pet Food Market Size, Share, and Industry Trends Forecast 2026-2036
China Pet Food Market Analysis
China's dual carbon goals is pivoting domestic pet food manufacturers toward cleaner production footprints and biodegradable packaging materials. Mars Incorporated leverages its global R&D network to localize formulations for Chinese companion animal preferences. Nestlé Purina anchors its position through specialized nutrition lines targeting aging pet demographics. General Mills Inc. competes via grain-free and functional ingredient portfolios aligned with health-conscious urban buyers.
Pet food comprises nutritionally formulated products manufactured through extrusion, canning, or freeze-drying processes, with protein content, moisture ratios, and micronutrient profiles calibrated to species-specific dietary requirements. Dry food dominates volume due to shelf stability and cost efficiency in mass retail channels. Wet food captures premium margin pools as pet humanization deepens among affluent households. Functional ingredients represent the fastest-growing ingredient type as owners prioritize digestive health, joint support, and coat conditioning in purchasing decisions.
China's national feed regulator and the Ministry of Agriculture and Rural Affairs enforce safety standards for pet food production, while GB standards govern labeling and contaminant thresholds. SAMR oversees market access compliance and anti-counterfeiting measures that protect legitimate manufacturers. Stakeholders must monitor evolving ingredient approval pathways and traceability mandates that will determine which suppliers retain shelf space in domestic retail and e-commerce channels.
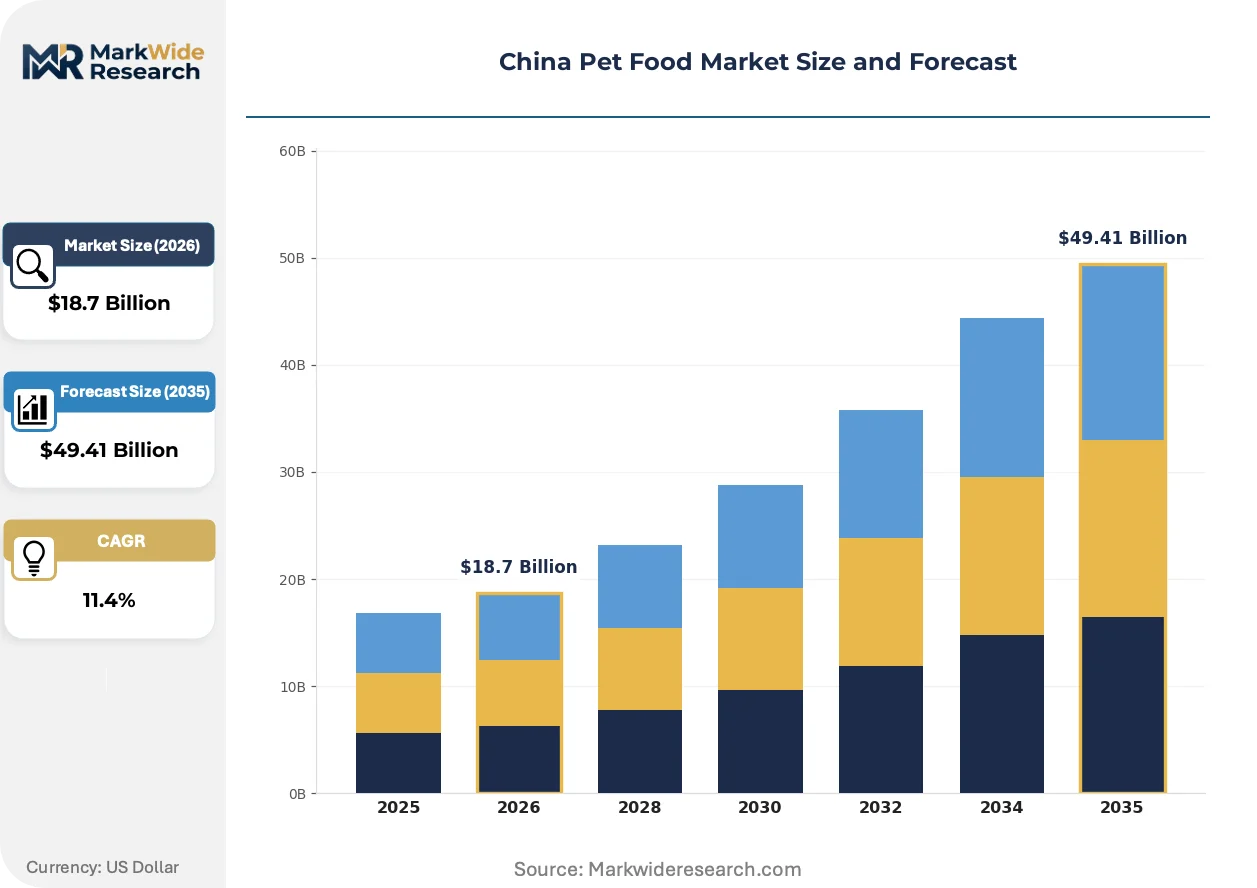
Market Dynamics
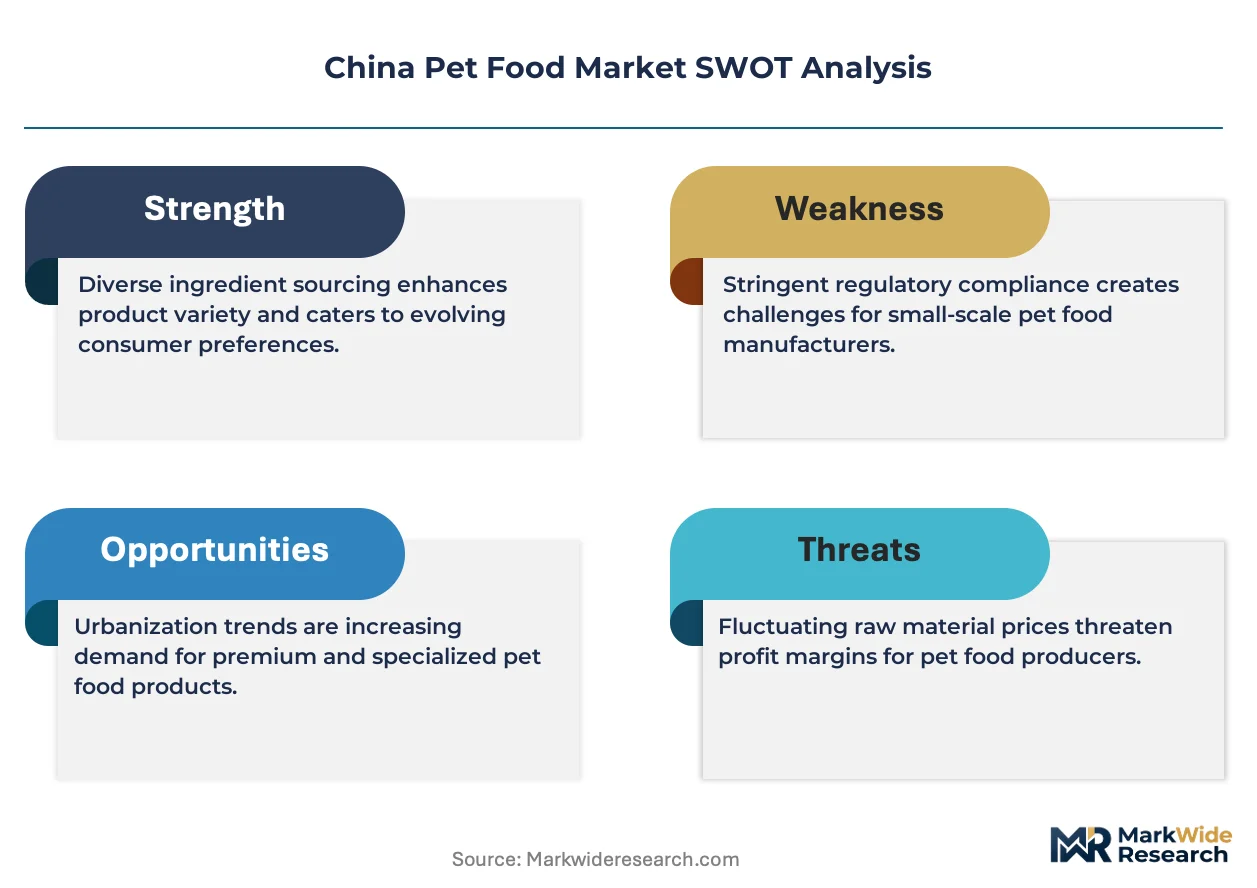
China's dual carbon goals are forcing domestic pet food manufacturers to reconfigure production footprints and packaging supply chains, creating competitive separation between compliant operators and legacy facilities.
Growth Catalysts
- Urban Pet Humanization:Young professionals in Shanghai, Beijing, and Guangzhou treat companion animals as family members, driving nutritionally sophisticated purchasing decisions and premium formulation demand.
- GB Standards Harmonization:The Ministry of Agriculture and Rural Affairs has consolidated feed safety protocols, reducing regulatory fragmentation and accelerating market access for qualified domestic producers.
- Cold Chain Infrastructure:Wet food distribution networks have expanded through refrigerated logistics investments in tier-one metropolitan corridors, unlocking previously inaccessible margin pools.
Market Restraints
- Animal Protein Input Volatility:Pork and poultry meal prices fluctuate with livestock epidemic cycles, compressing gross margins for mid-tier manufacturers without backward integration into rendering operations.
- Import Dependency Concentration:Premium vitamin premixes and specialty amino acids remain concentrated among European and North American suppliers, exposing domestic formulators to currency and shipping cost shocks.
- SAMR Registration Friction:Novel ingredient approval pathways require extensive toxicological dossiers, delaying product launches by manufacturers seeking functional positioning.
Strategic Opportunities
- Biodegradable Packaging Mandates:MEE enforcement of plastic reduction targets creates first-mover advantage for manufacturers investing in compostable film and fiber-based container technologies.
- Aging Pet Nutrition:Geriatric companion animal populations in tier-one cities remain underserved by specialized renal, joint, and cognitive support formulations.
- Veterinary Channel Integration:Prescription diet authorization through licensed clinics represents an underdeveloped route-to-market with higher switching costs than mass retail.
Industry Challenges
- Formulation Talent Scarcity:Veterinary nutritionists and food safety specialists command premium compensation in a labor market with limited accredited training programs.
- Traceability System Integration:Legacy ERP platforms at regional manufacturers require substantial retrofitting to meet blockchain-enabled ingredient sourcing mandates under evolving SAMR guidelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Pet Food Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dry Food, Wet Food, Treats, Supplements Customer Type: Pet Owners, Retailers, Veterinarians, E-commerce Platforms Distribution Channel: Supermarkets, Pet Stores, Online Retail, Specialty Shops Ingredient Type: Meat-Based, Grain-Free, Organic, Functional Ingredients |
| Companies Covered | Mars Incorporated, Nestlé Purina, General Mills Inc., ADM, WellPet LLC, The J.M. Smucker Company, Hill’s Pet Nutrition, Inc., China Mengniu Dairy Company Limited, Yili Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Pet Food Market Emerging Trajectories
Automation and regulatory precision are compressing production cycles while reshaping how Chinese manufacturers compete on formulation transparency and carbon accountability.
Extrusion process control systems are automating temperature and moisture calibration across continuous production lines. Domestic manufacturers in Shandong and Jiangsu provinces are retrofitting facilities with sensor arrays that reduce batch-to-batch variation. This compression of quality deviation is automating the elimination of manual oversight roles while enabling real-time GB compliance documentation.
SAMR has intensified labeling enforcement for functional ingredient claims, requiring substantiated health benefit disclosures on packaging. Manufacturers must now maintain clinical trial records or literature reviews supporting digestive, immune, or coat health assertions. Wet food and treat categories face the steepest compliance costs as claim density concentrates in premium positioning segments.
Subscription-based replenishment models are displacing traditional supermarket stocking cycles among urban millennial pet owners. Direct-to-consumer platforms and veterinary clinic auto-ship programs capture recurring revenue with higher lifetime value than intermittent retail purchases. This behavioral shift is most pronounced in Shanghai and Beijing, where delivery infrastructure density supports chilled product reliability.
China Pet Food Market Segmentation
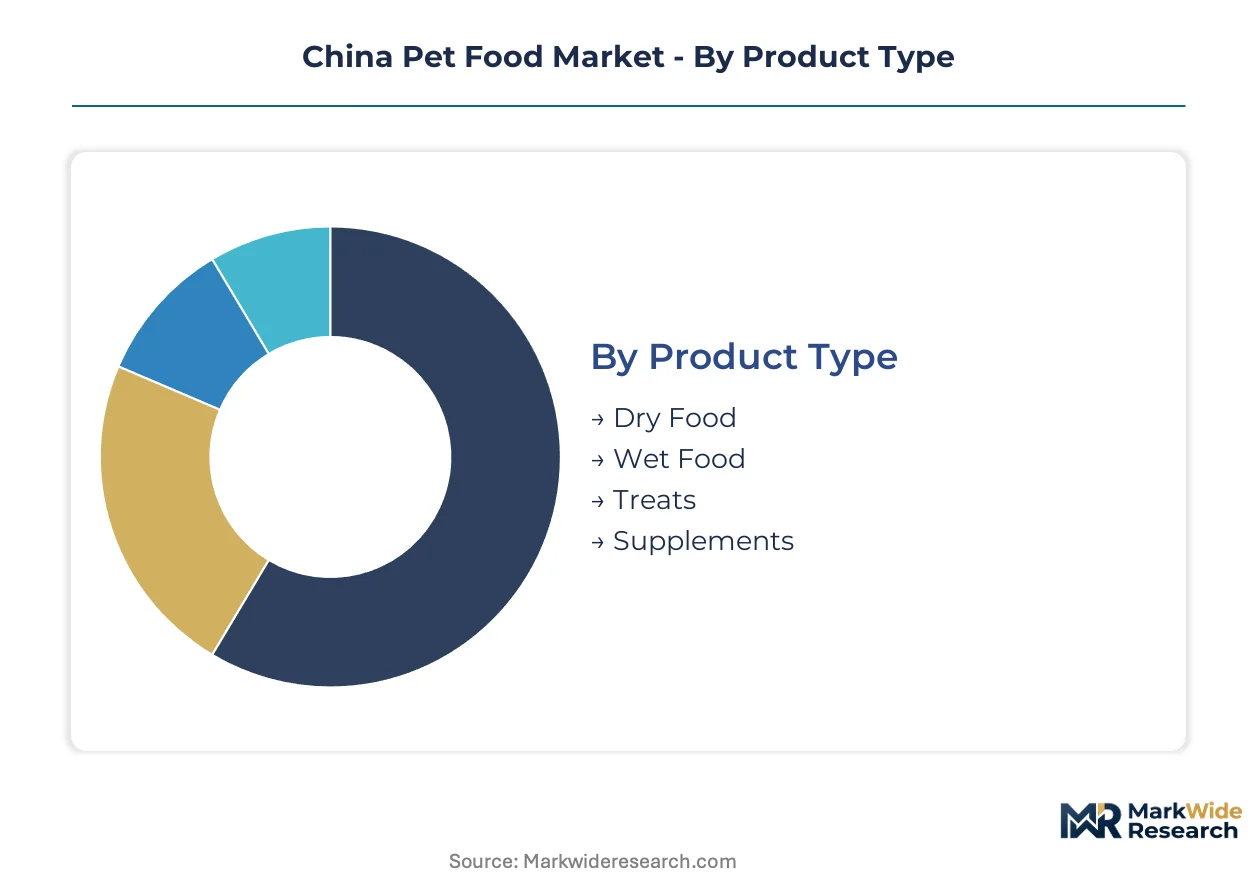
Product architecture, customer purchasing patterns, and distribution infrastructure each create distinct competitive arenas within China's pet food sector. Understanding how segments intersect reveals where margin pools concentrate and where regulatory compliance creates entry barriers.
Product Type:
Moisture content and shelf stability specifications determine manufacturing capital requirements and distribution economics across the four product formats.
- Dry Food:Extruded kibble with 6-10% moisture content achieves shelf stability without refrigeration. Mass retail channels in Shanghai and Beijing metropolitan corridors absorb volume as cost-conscious households prioritize feeding economy over formulation sophistication.
- Wet Food:Canned or pouch formats with 75-85% moisture content command premium positioning through palatability advantages. Cold chain infrastructure investments in tier-one cities have expanded addressable market for chilled distribution-dependent formats.
- Treats:Freeze-dried and baked formats with intermediate moisture profiles serve training and bonding occasions.
- Supplements:Concentrated micronutrient and botanical formulations target specific health conditions with veterinary channel authorization requirements.
Dry food leads on scale; wet food leads on momentum as pet humanization deepens among affluent urban households.
Customer Type:
Purchasing authority and decision criteria vary sharply between end-consumers and institutional intermediaries.
- Pet Owners:Individual households make formulation choices based on humanization intensity, with Shanghai and Beijing professionals driving premium adoption through treatise-level ingredient scrutiny.
- Veterinarians:Licensed clinics prescribe therapeutic diets with higher switching costs and recurring revenue profiles than mass retail channels.
- Retailers:Supermarket and pet store buyers optimize shelf turnover and margin mix with limited formulation expertise.
- E-commerce Platforms:Tmall and JD.com algorithms prioritize review velocity and subscription conversion over traditional brand equity metrics.
Pet owners dominate transaction volume; veterinarians concentrate margin capture through prescription authorization.
Distribution Channel:
Physical versus digital route-to-market selection shapes working capital intensity and customer data access.
- Online Retail:Direct-to-consumer platforms capture subscription revenue with auto-replenishment algorithms. Delivery infrastructure density in tier-one cities enables chilled product reliability for wet food categories.
- Supermarkets:Mass retail chains optimize shelf space for dry food volume with limited SKU depth for specialized formulations.
- Pet Stores:Specialty retailers provide tactile evaluation and staff consultation for premium positioning.
- Specialty Shops:Boutique formats curate import-dependent assortments for discerning households in Guangzhou and Beijing.
Online retail expands most quickly; supermarkets retain volume concentration in lower-tier cities.
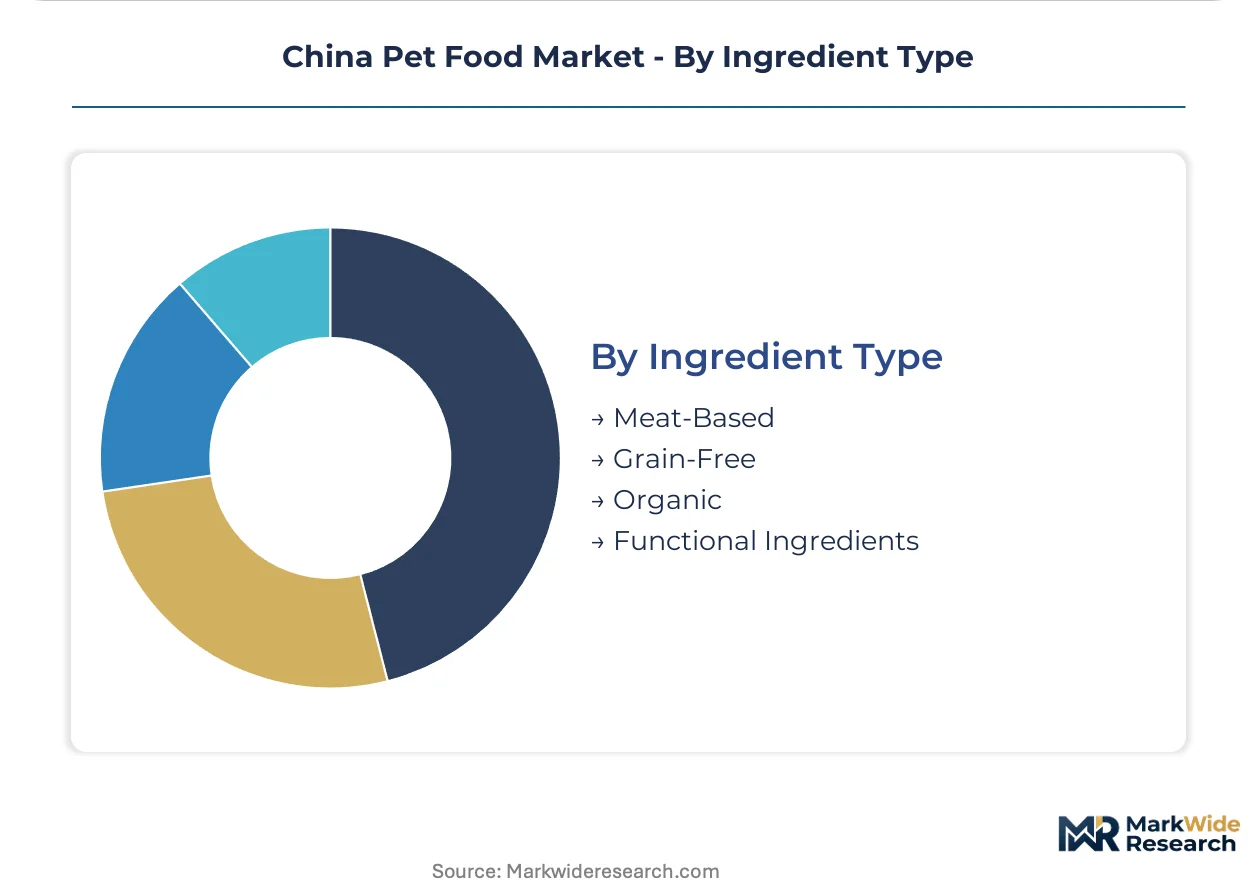
Ingredient Type:
Protein sourcing and functional positioning create tiered pricing architecture aligned with health-conscious purchasing.
- Functional Ingredients:Probiotics, glucosamine, and omega fatty acids target digestive, joint, and coat health with SAMR-mandated substantiation requirements for label claims.
- Meat-Based:Pork, poultry, and fish meals provide species-appropriate protein with input cost volatility tied to livestock epidemic cycles.
- Grain-Free:Potato and legume carbohydrate substitutes serve allergy-sensitive companion animals with formulation complexity premiums.
- Organic:Certified ingredient sourcing with traceability documentation appeals to sustainability-motivated urban professionals.
Meat-based formulations lead on volume; functional ingredients gain share fastest as aging pet populations drive condition-specific nutrition demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shandong and Jiangsu provinces anchor China's pet food manufacturing workforce, with extrusion specialists and food safety technicians clustering around Qingdao and Nanjing industrial corridors. These talent pools supply technical expertise to domestic brands scaling production capacity.
Yangtze River Delta
Shanghai's young professional households drive premium wet food adoption through subscription replenishment models. SAMR labeling enforcement requires clinical substantiation for functional ingredient claims on packaging. Nanjing hosts cold chain logistics hubs enabling chilled distribution reliability for high-moisture formulations.
Pearl River Delta
Guangzhou pet owners demonstrate highest treat and supplement penetration rates among Chinese metropolitan markets. MEE plastic reduction mandates accelerate biodegradable packaging adoption across Shenzhen manufacturing zones. Dongguan specialty retailers curate import-dependent assortments for discerning households.
Beijing-Tianjin-Hebei
Capital region veterinarians concentrate prescription diet authorization through licensed clinic networks. GB standards harmonization by the Ministry of Agriculture and Rural Affairs reduces regulatory fragmentation for qualified producers. Tianjin port infrastructure handles bulk commodity imports for northern manufacturing facilities.
Sichuan-Chongqing
Western China's expanding middle class generates volume demand for economy dry food segments. Provincial environmental bureaus enforce dual carbon compliance timelines on regional production facilities. Chengdu e-commerce fulfillment centers support direct-to-consumer platform growth for domestic brands.
Shandong Peninsula
Qingdao and Yantai host China's densest concentration of extrusion equipment manufacturers and rendering operations. Local SAMR offices coordinate feed safety protocol inspections with national regulators. Weifang agricultural processing clusters supply pork and poultry meal inputs to adjacent pet food plants.
China Pet Food Market Vendor Landscape
Capital-heavy producers compete with asset-light designers as multinational manufacturers operate integrated rendering-to-retail networks while domestic brands outsource formulation to third-party laboratories. Market structure consolidates around three tiers: global conglomerates with R&D subsidiaries, mid-scale regional manufacturers with backward integration into protein rendering, and emerging direct-to-consumer brands leveraging e-commerce algorithms. Strategic archetypes include veterinary channel specialists, subscription-platform native brands, and commodity dry food volume producers. Competitive dynamics center on M&A activity targeting rendering capacity and strategic partnerships with cold chain logistics providers.
Among global conglomerates operating in China, Mars Incorporated and Nestlé Purina occupy positions representing veterinary channel penetration and aging pet nutrition specialization respectively. General Mills Inc. exemplifies the grain-free functional ingredient archetype targeting health-conscious urban buyers. These three entities anchor the premium-tier competitive vector through distinct formulation positioning rather than overlapping segment contention.
| Leading Market Players |
|---|
| Mars Incorporated |
| Nestlé Purina |
| General Mills Inc. |
| ADM |
| WellPet LLC |
| The J.M. Smucker Company |
| Hill's Pet Nutrition, Inc. |
| China Mengniu Dairy Company Limited |
| Yili Group |
| Others |
Supply Flow & Price Mechanics
MEE plastic reduction mandates gate qualified supply access and premium-tier pricing power by disqualifying manufacturers unable to source compostable films or fiber-based containers. Buyers in Shanghai and Beijing metropolitan corridors now treat biodegradable packaging compliance as a threshold condition for shelf placement, compressing margins for legacy operators while rewarding first-movers with pricing authority in wet food and treat categories.
Pricing Analysis
Subscription bundling against transactional unbundling separates recurring-revenue platforms from intermittent retail purchases. Three-tier pricing structure across premium, standard, and economy levels stratifies by formulation sophistication and cold chain reliability. Cost compression in mid-tier dry food is intensifying because pork and poultry meal input volatility squeezes manufacturers without backward integration into rendering. Mass retail buyers in lower-tier cities exhibit highest price sensitivity; veterinary channel purchasers show least sensitivity due to prescription authorization lock-in.
Supply Chain Analysis
Dual-sourcing requirements for vitamin premixes and specialty amino acids now dominate procurement protocols among qualified domestic formulators. Protein inputs draw from Shandong and Jiangsu rendering clusters; functional additives rest on European and North American suppliers. Single-source vulnerability concentrates in premium micronutrient streams exposed to currency and shipping cost shocks. Distribution runs through refrigerated logistics hubs in Nanjing and Chengdu supporting direct-to-consumer platform growth.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's pet food sector functions as a geographic-arbitrage play where MEE enforcement timelines in coastal provinces outpace western regional compliance deadlines, creating cost and access differentials for manufacturers with multi-location footprints.
For Market Incumbents: Deploy cold chain infrastructure expansion as the primary lever. Secure refrigerated logistics partnerships in tier-one metropolitan corridors before capacity constraints harden. Acquire rendering operations in Shandong Peninsula to insulate against pork and poultry meal price volatility from livestock epidemic cycles.
For New Entrants and Emerging Players: Veterinary clinic networks represent the most penetrable channel for prescription diet authorization. Target geriatric companion animal formulations in Beijing-Tianjin-Hebei where specialized renal and joint support products remain underserved. Launch through direct-to-consumer platforms with auto-replenishment algorithms to bypass supermarket shelf space competition.
For Investors and Strategic Acquirers: Roll-up economics work for mid-scale regional manufacturers with backward integration into protein rendering because SAMR registration friction creates barriers to rapid organic scaling. Monitor blockchain-enabled ingredient sourcing mandate implementation as the signal indicating which legacy ERP platforms require costly retrofitting.
| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Packaging Transition | MEE enforcement timelines determine which manufacturers retain tier-one city shelf access. |
| Veterinary Channel Integration | Prescription diet authorization through licensed clinics locks in recurring revenue with higher switching costs. |
| Rendering Capacity Acquisition | Backward integration into Shandong protein processing insulates margins from livestock epidemic cycles. |
| Cold Chain Logistics Partnership | Refrigerated distribution density in Nanjing and Chengdu enables wet food category expansion. |
| Functional Ingredient Substantiation | SAMR-mandated clinical trial records protect label claims against enforcement actions. |
Methodological Framework
Direct dialogue with veterinary nutritionists, cold chain logistics operators, SAMR compliance officers, and e-commerce platform category managers grounded qualitative findings. Secondary validation drew from GB standards documentation, Ministry of Agriculture and Rural Affairs feed safety protocols, customs trade data for protein meal imports, and Tmall/JD.com subscription conversion metrics. Bottom-up manufacturing capacity assessments and top-down metropolitan consumption patterns underwent cross-triangulation.
Segment-level projections across product type, customer category, distribution channel, and ingredient positioning fed into analytical framework outputs over the projection horizon. CAGRs derived from historical trajectory analysis adjusted for regulatory inflection points and infrastructure buildout schedules. Modeled inputs included cold chain penetration rates in tier-one cities, SAMR novel ingredient approval queue lengths, and MEE plastic reduction compliance timelines.
Revisions become necessary when livestock epidemic cycles deepen protein input volatility, SAMR accelerates blockchain traceability mandates, or MEE enforcement timelines compress beyond current facility retrofitting schedules. Deviation in dual carbon compliance deadlines across provincial environmental bureaus would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Dog Biscuit Market
Pet Care Products
Pet Daycare Market
Pet Care Products
Dog Clothes Market
Pet Care Products
Pet Molar Bite Toy Market
Pet Care Products
GPS Dog Collar Market
Pet Care Products
UK Pet Boarding Market
Pet Care Products
Weight Management Dog Food Market
Pet Care Products
Smart Pet Kennel Market
Pet Care Products
Germany Pet Clothing Market
Pet Care Products
Canada Pet Training Services Market
Pet Care Products
Pet Hair Brush Market
Pet Care Products
Pet Odor Absorber Market
Pet Care Products
GCC Cat Food Market
Pet Care Products
Pet GPS Tracker Market
Pet Care Products
Europe Organic Pet Food for Cats and Dogs Market
Pet Care Products
Pet Furniture Market