
 Global Mobile and Wireless Backhaul Equipment Market | 2026-2036
Global Mobile and Wireless Backhaul Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Mobile and Wireless Backhaul Equipment Market Intelligence
The shift towards network-as-a-service (NaaS) and leasing models for backhaul equipment is narrowing the field of competitors to those with strong financing arms. Ericsson sustains its market position by offering integrated 5G-ready solutions directly to major telecom operators. Cisco leverages its deep enterprise channel to capture private network deployments. NEC Corporation differentiates through its specialization in advanced microwave radio systems, particularly in the Japanese market.
Mobile and wireless backhaul equipment comprises the hardware connecting cell sites to the core network, including microwave radios operating up to 80 GHz. Its purpose is to aggregate and transport high-capacity data traffic from the radio access network. Fiber optic solutions dominate deployments in dense urban networks due to their superior bandwidth capacity. Microwave radio remains essential for connecting rural coverage areas and for rapid deployment scenarios where trenching fiber is not feasible.
Spectrum allocation policies from regulators like the US FCC for millimeter wave bands directly influence technology choices. National industrial strategies set by bodies such as China's MIIT and India's TRAI shape the pace of 5G infrastructure build-out. Vendor selection will increasingly hinge on the ability to support network slicing and low-latency applications for enterprise clients.
Market Dynamics
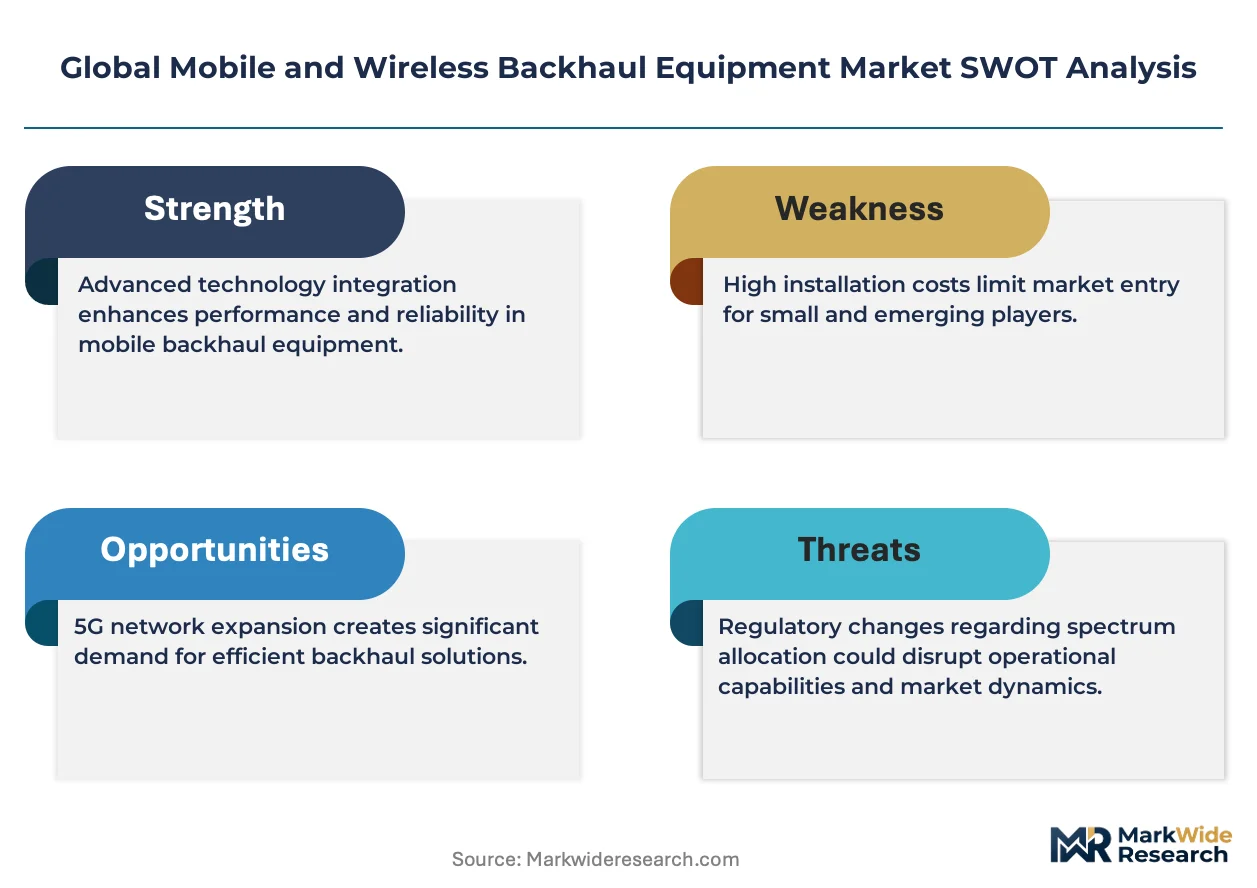
The global rollout of 5G networks is the central force compelling a fundamental redesign of backhaul infrastructure. This transition necessitates higher capacity, lower latency, and more flexible transport solutions to connect the vast number of new cell sites required for expanded coverage and service delivery.
Growth Catalysts
- Private 5G Networks:Deployment in manufacturing and logistics sectors creates dedicated demand for high-performance, low-latency backhaul separate from public networks.
- Rapid Urbanization:Concentrated population growth in cities across India and Vietnam requires massive upgrades to network density and capacity, driving investment in both fiber and microwave backhaul.
- 5G Infrastructure Rollout:The ongoing global deployment of 5G technology, governed by national timelines, inherently requires backhaul networks with significantly higher throughput and reliability than previous generations.
Market Restraints
- Fiber Deployment Costs:The high capital expenditure and lengthy permitting processes associated with trenching for fiber optic cable installations limit its feasibility, especially in suburban and rural areas.
- Spectrum Scarcity:Competition for and the high cost of suitable microwave frequency bands, managed by regulators like the US FCC, act as a significant barrier to entry and expansion for operators.
- Component Dependencies:The supply chain for critical high-frequency radio components, such as monolithic microwave integrated circuits, is concentrated among a few specialized semiconductor foundries, creating potential bottlenecks.
Strategic Opportunities
- Rural and Remote Connectivity:Microwave and emerging satellite backhaul solutions present a significant opportunity to provide broadband connectivity in underserved regions where fiber is economically unviable.
- Network Slicing for Enterprise:The ability to offer guaranteed service levels for specific enterprise applications via network slicing opens new revenue streams for operators beyond simple connectivity.
- Open RAN Architectures:The move towards Open Radio Access Networks creates opportunities for new vendors to provide disaggregated backhaul hardware and software that interoperates with equipment from multiple suppliers.
Industry Challenges
- Legacy System Integration:Operators face significant technical challenges and costs in ensuring that new 5G backhaul equipment can seamlessly interoperate with existing 3G and 4G network infrastructure during phased upgrades.
- Navigating Regulatory Divergence:Equipment vendors must design and certify products to meet a wide array of differing national spectrum allocation rules and power limits set by bodies like India's TRAI and China's MIIT.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Mobile and Wireless Backhaul Equipment Market |
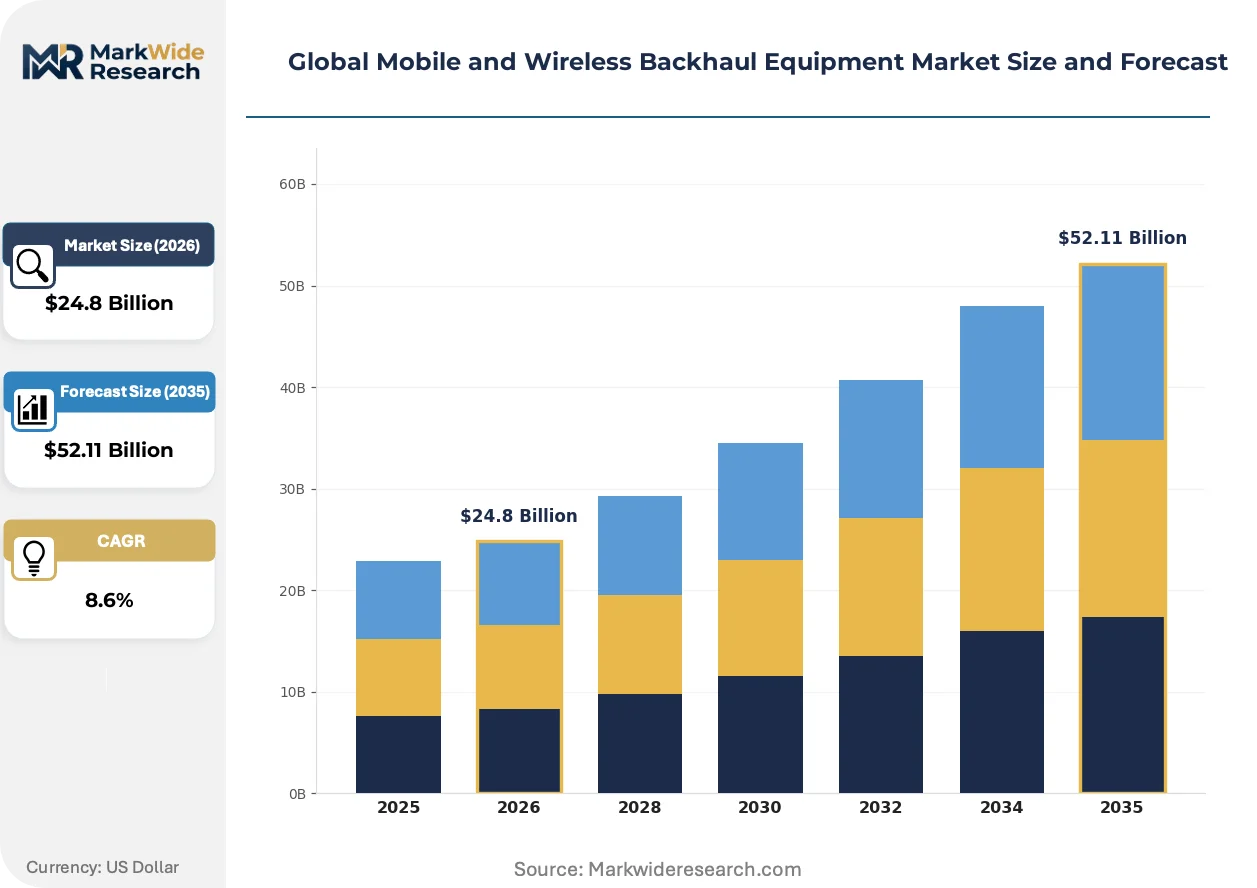
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $52.11 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microwave Radio, Fiber Optic, Millimeter Wave, Satellite Communication, Copper Wire, Free Space Optics Technology: TDMA, CDMA, IP/MPLS, Ethernet, WDM, SDH Application: Urban Networks, Rural Coverage, Private Networks, Public Safety Communication, IoT Connectivity, Emergency Services End User: Telecom Operators, Network Service Providers, Government Agencies, Enterprises, Infrastructure Vendors, Managed Service Providers |
| Companies Covered | Huawei Technologies, Ericsson, Nokia, Cisco System Inc., ZTE Corporation, Juniper Networks, NEC Corporation, Ciena, Infinera, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Mobile and Wireless Backhaul Equipment Market Strategic Shifts & Innovations
Software-defined networking principles are transforming mobile backhaul from a static, hardware-centric function into a dynamic, programmable resource. This evolution allows operators to manage transport network capacity and traffic routing in real time, responding to fluctuating demand patterns.
Integrated Access and Backhaul technology provides wireless backhauling using the same 5G spectrum and hardware that serves end-user devices. Mobile network operators are adopting this for faster, more cost-effective deployment of dense urban and millimeter-wave 5G networks. This technology is hybridizing the traditionally distinct network segments, allowing for more flexible cell site connectivity without requiring new fiber drops.
Spectrum allocation policy from regulators like the US FCC, which has opened millimeter-wave bands such as the E-band for licensed use, directly impacts equipment design. This action creates a clear pathway for deploying high-capacity, short-range microwave links in dense urban environments. Consequently, equipment manufacturers are focusing R&D on systems optimized for these specific frequencies to capture demand from operators building out 5G networks.
A transition from one-time capital equipment purchases toward network-as-a-service and leasing models is altering procurement patterns. This shift away from traditional capex-heavy models is particularly pronounced for private network deployments. Enterprise customers in sectors like manufacturing and logistics favor the financial flexibility of opex-based consumption for their dedicated backhaul needs.
Global Mobile and Wireless Backhaul Equipment Market Segmentation
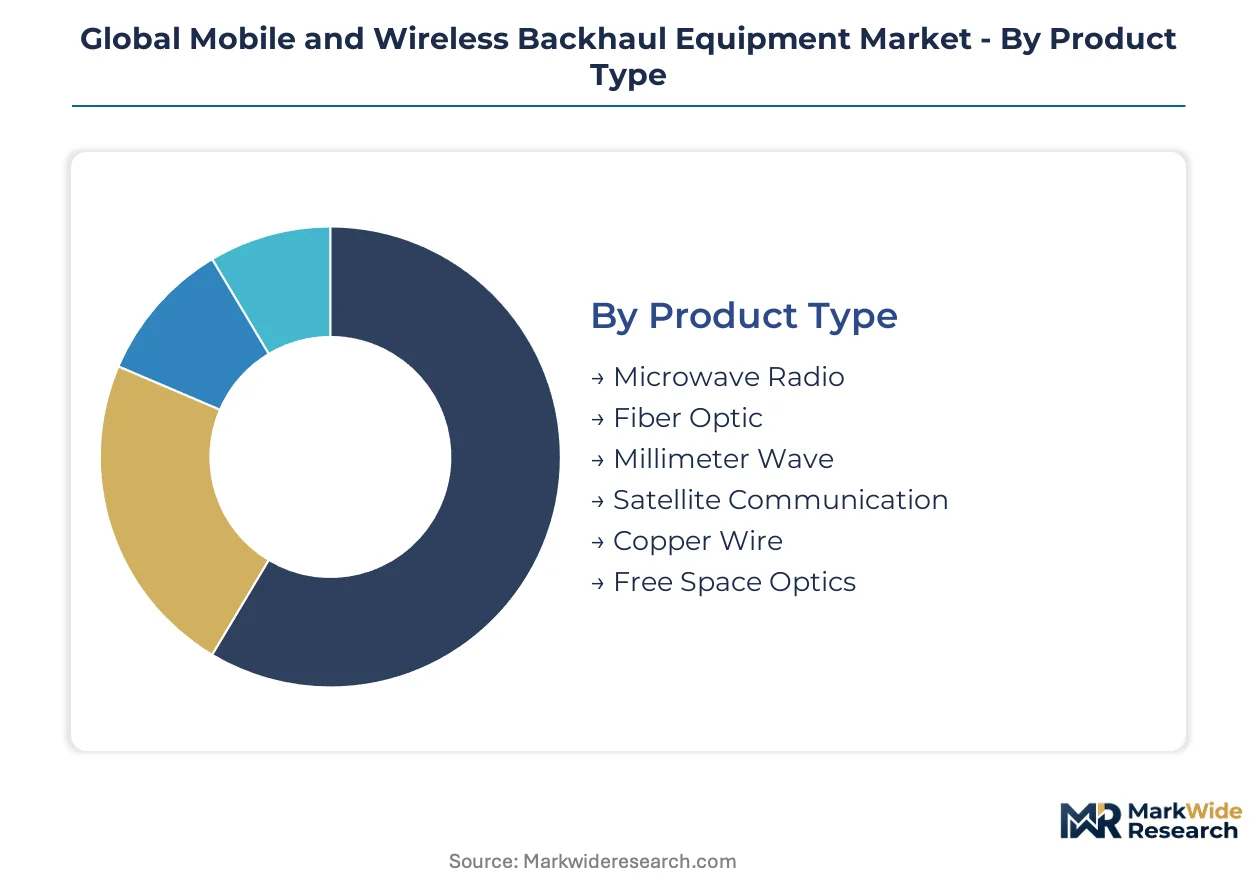
The global mobile and wireless backhaul equipment market segments across diverse product types, underlying technologies, specific applications, and distinct end-user categories. Understanding these distinctions is critical for vendors to align product development with evolving network requirements and for operators to optimize infrastructure investments for 5G deployments and private networks.
Product Type:
The equipment types defining backhaul infrastructure vary by deployment scenario and capacity needs, influencing network architecture choices.
- Fiber Optic:These solutions provide unparalleled bandwidth and low latency, making them indispensable for dense urban networks and high-capacity core connections. Deployments in rapidly urbanizing areas like India and Vietnam heavily rely on fiber for network upgrades.
- Microwave Radio:This equipment utilizes radio frequencies up to 80 GHz for line-of-sight communication, offering rapid deployment and cost-effectiveness in rural coverage areas. Its flexibility supports quick infrastructure build-out where fiber trenching is not feasible.
- Millimeter Wave:Operating in higher frequency bands like E-band, millimeter wave systems deliver multi-gigabit capacities over short distances, primarily for urban small cell backhaul. Regulatory allocations from bodies like the US FCC enable these high-capacity links.
- Satellite Communication:Satellite backhaul provides connectivity to remote and underserved regions, offering global coverage where terrestrial options are unavailable. This technology ensures essential communication links for isolated communities.
- Copper Wire:Primarily used for legacy systems and short-distance connections, copper wire solutions offer lower bandwidth but remain cost-effective for specific last-mile applications. Some existing infrastructure still leverages copper for backhaul.
- Free Space Optics:This technology transmits data through the air using laser beams, offering high bandwidth without spectrum licensing. It finds niche applications in urban environments for short-range, high-capacity links.
Microwave Radio holds installed capacity for rural connectivity. Fiber Optic is rotating up the share rankings, especially in urban centers.
Technology:
Backhaul technology choices reflect evolving network demands and protocol efficiencies, driving the shift towards packet-based solutions.
- IP/MPLS:Internet Protocol/Multi-Protocol Label Switching provides a scalable, flexible, and efficient packet-based transport solution for modern backhaul networks. This technology is fundamental for supporting network slicing and low-latency applications.
- Ethernet:Widely adopted for its simplicity and cost-effectiveness, Ethernet forms the backbone of many backhaul networks, offering high-speed data transmission. Its ubiquity supports diverse network topologies, from metro to access.
- WDM:Wavelength Division Multiplexing increases fiber capacity by transmitting multiple data streams over a single optical fiber using different light wavelengths. This technology maximizes the utility of existing fiber infrastructure.
- SDH:Synchronous Digital Hierarchy is a legacy time-division multiplexing technology for digital data transmission over optical fiber, still present in some older network infrastructures. It provides reliable, circuit-switched connectivity.
- TDMA:Time Division Multiple Access is a channel access method for shared-medium networks, allowing multiple users to share the same frequency channel by dividing the signal into different time slots. It is common in some wireless backhaul systems.
- CDMA:Code Division Multiple Access is another channel access method, allowing multiple users to share the same frequency band simultaneously by assigning unique codes to each user. This technology is less common in modern backhaul but exists in some legacy systems.
Packet-based technologies like IP/MPLS are gaining prominence for 5G backhaul. Legacy systems like SDH maintain a presence for specific network functions during phased upgrades.
Application:
Specific deployment contexts dictate the required backhaul characteristics and performance envelopes, influencing equipment selection.
- Urban Networks:These applications demand high-capacity, low-latency backhaul solutions to support dense populations and a high concentration of cell sites. Fiber optic deployments dominate in urban centers due to superior bandwidth.
- Private Networks:Dedicated backhaul for enterprises in manufacturing and logistics sectors requires high reliability, security, and guaranteed service levels. These networks often utilize tailored solutions for specific operational needs.
- Rural Coverage:Connecting remote areas necessitates cost-effective and rapidly deployable backhaul, often relying on microwave radio or satellite communication. Economic viability is a primary concern for these deployments.
- Public Safety Communication:Backhaul for emergency services requires highly resilient and secure networks with guaranteed uptime, often involving dedicated spectrum and robust equipment. Regulatory bodies like the US FCC ensure spectrum availability for these critical services.
- IoT Connectivity:Backhaul for Internet of Things devices supports a massive number of low-bandwidth connections, requiring efficient and scalable solutions. The architecture must accommodate diverse device types and data volumes.
- Emergency Services:Similar to public safety, this application focuses on providing robust communication infrastructure during disasters or critical events. Equipment must withstand harsh conditions and maintain connectivity.
High-density urban deployments drive significant investment in fiber. Niche applications like public safety communication require specialized, highly reliable solutions.
End User:
The ultimate consumers of backhaul equipment shape procurement patterns and service level expectations across the industry.
- Telecom Operators:These entities are the largest consumers, deploying backhaul for their extensive mobile networks and driving demand for 5G infrastructure. National industrial strategies from bodies like China's MIIT influence their investment cycles.
- Enterprises:Manufacturing, logistics, and other industries deploy backhaul for their private 5G networks, seeking dedicated, high-performance connectivity. This segment increasingly favors NaaS and leasing models.
- Network Service Providers:These companies offer backhaul as a service to other operators or enterprises, requiring flexible and scalable equipment. They often manage complex multi-vendor environments.
- Government Agencies:Public safety, defense, and other government bodies utilize backhaul for secure and reliable communication networks. Their procurement often involves stringent security and performance standards.
- Infrastructure Vendors:Companies specializing in network infrastructure provide backhaul solutions as part of broader network deployment projects. They often work with telecom operators and enterprises to build out complete systems.
- Managed Service Providers:These providers offer end-to-end management of backhaul networks for clients, requiring equipment that supports remote monitoring and efficient operation. They focus on service level agreements and operational efficiency.
Telecom operators remain primary consumers for global 5G rollouts. Enterprise demand for dedicated private networks is expanding rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global mobile and wireless backhaul equipment market exhibits a dynamic interplay between regions with advanced infrastructure and those undergoing rapid expansion. Countries with established telecom ecosystems often focus on technology exports and high-value component manufacturing. Conversely, nations with burgeoning digital economies drive substantial import demand for backhaul solutions.
India
India's rapid urbanization and extensive 5G infrastructure rollout drive significant demand for backhaul equipment. The Telecom Regulatory Authority of India (TRAI) actively shapes spectrum allocation and network expansion policies. Major urban centers like Mumbai and Delhi are undergoing massive network density upgrades to support rising data traffic.
United States
The United States market sees substantial investment in private 5G networks and millimeter wave deployments. The US FCC's clear spectrum allocation for high-frequency bands facilitates short-range, high-capacity links. Tech hubs such as Silicon Valley and Seattle prioritize low-latency backhaul for enterprise applications.
China
China's vast 5G infrastructure build-out and industrial IoT initiatives generate immense backhaul demand. The Ministry of Industry and Information Technology (MIIT) guides national strategies for network development and indigenous technology. Manufacturing zones in Shenzhen and Shanghai are rapidly integrating dedicated private backhaul solutions.
Germany
Germany focuses on Industry 4.0 applications and the deployment of private campus networks. European Union directives, including the EU Green Deal, influence sustainable network infrastructure choices. Automotive and industrial clusters in Bavaria and North Rhine-Westphalia require highly reliable, low-latency backhaul.
Vietnam
Vietnam experiences significant demand from rapid urbanization and digital transformation initiatives. The government's digital economy development plans prioritize widespread broadband access. Ho Chi Minh City and Hanoi are undergoing substantial network upgrades, particularly for fiber optic and microwave backhaul.
Global Mobile and Wireless Backhaul Equipment Market Key Industry Players
On the supply side, the industry is structured across a tiered landscape, featuring large, integrated telecommunications equipment providers alongside specialized technology firms. This market configuration includes global infrastructure giants offering end-to-end solutions and agile innovators focusing on specific backhaul technologies. Strategic partnerships are common, enabling vendors to combine expertise for complex 5G rollouts and private network deployments. Portfolio diversification into software-defined solutions also helps secure long-term contracts.
Specialists in integrated solutions and core network components include Ericsson, a Swedish multinational networking and telecommunications company, and Cisco System Inc., a US-based technology conglomerate. NEC Corporation, a Japanese multinational information technology and electronics company, exemplifies a player with deep expertise in advanced microwave radio systems. These entities represent distinct approaches to capturing demand across varying network architectures and operator requirements. Their market positioning often reflects long-standing relationships with major telecom operators and enterprise clients.
| Leading Market Players |
|---|
| Huawei Technologies |
| Ericsson |
| Nokia |
| Cisco System Inc. |
| ZTE Corporation |
| Juniper Networks |
| NEC Corporation |
| Ciena |
| Infinera |
| Others |
Cost & Logistics Intelligence
Single-source dependency on specialized semiconductor foundries for monolithic microwave integrated circuits (MMICs) dictates the premium pricing for high-frequency backhaul equipment and concentrates critical component manufacturing within a few key regions. This dependency directly shapes the supply chain's resilience and cost structure.
Pricing Analysis
Industrial OEM buyers anchor a hybrid pricing structure, combining project-based contracts for large-scale telecom operator deployments with Network-as-a-Service (NaaS) and leasing models for enterprise private networks. Price differentiation stems from customization levels for network slicing, comprehensive after-sales service, and established brand premium. Pricing softness affects standard microwave radio systems due to increased competition from new entrants. Enterprise clients, favoring opex models, demonstrate sensitivity to upfront capital expenditure but prioritize value-based outcomes.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities are crucial for managing cash flow for equipment vendors, particularly for large infrastructure projects. Supply concentration for advanced components centers on specialized foundries in Taiwan and South Korea, with final assembly occurring in China, Japan, and the United States. Critical dependencies include monolithic microwave integrated circuits and high-purity optical fiber, where single-source vulnerability presents a structural risk. Distribution runs through direct channels to major telecom operators and via enterprise channel partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The mobile and wireless backhaul market is experiencing a buyer-power shift, driven by the fragmentation of enterprise demand for specialized private network solutions. This shift necessitates tailored offerings beyond traditional telecom operator requirements.
For Market Incumbents: Build integrated solution ecosystems that span hardware, software, and services to counter emerging Open RAN threats. Major players must deepen R&D into network slicing and low-latency applications to maintain competitive advantage. Consolidate market share by offering comprehensive 5G-ready solutions directly to large telecom operators. Leverage existing enterprise channels for private network deployments, bundling specialized support and financing.
For New Entrants and Emerging Players: Establish a beachhead in underserved rural and remote connectivity markets using cost-effective microwave and satellite backhaul solutions. Target enterprise private networks requiring highly specialized, low-latency applications where incumbent solutions may be over-engineered. Provide disaggregated backhaul hardware and software compatible with Open RAN architectures to gain traction. Offer flexible Network-as-a-Service models to attract enterprises seeking opex-based consumption.
For Investors and Strategic Acquirers: US FCC's millimeter wave spectrum allocations reshapes the acquisition landscape, favoring companies with advanced high-frequency radio expertise. The market offers long-term viability, driven by sustained 5G infrastructure build-out and enterprise digital transformation across the next decade. Target specialized firms in network slicing software, millimeter wave systems, or satellite backhaul for strategic acquisitions. Increased M&A activity in Open RAN-compatible backhaul solutions will signal market consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Millimeter Wave R&D | Optimizes high-capacity, short-range urban deployments for 5G networks. |
| Develop Network Slicing Software | Enables guaranteed service levels for diverse enterprise applications. |
| Expand NaaS and Leasing Models | Attracts enterprise clients seeking opex-based financial flexibility. |
| Pursue Open RAN Interoperability | Broadens market access by integrating with disaggregated network components. |
| Acquire Satellite Backhaul Specialists | Extends reach to remote and underserved regions economically. |
Research Approach
Findings reconcile primary fieldwork against secondary review of national spectrum allocation reports, telecom industry association publications, and major equipment vendor financial filings. Primary interviews engaged telecom operator CTOs, enterprise IT directors, backhaul equipment engineers, and regulatory affairs specialists. This approach integrated bottom-up market sizing from component data and top-down validation against operator capital expenditure trends. Data triangulation ensured robust market estimates.
Forecast inputs considered projected 5G infrastructure build-out rates, national spectrum allocation policies, and enterprise private network investment trends across the analysis window. Segmentation modeled product type, technology, application, end-user, and regional 5G rollout phases. CAGRs derived from historical growth patterns, planned 5G deployment schedules, and anticipated enterprise digital transformation. 5G cell site density targets and national broadband penetration goals drove forecasts.
Stress conditions across geopolitical trade policies, global semiconductor supply, and national 5G rollout timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions regarding stable regulatory environments and sustained capital expenditure. Significant supply chain disruptions or unforeseen technological shifts could revise projections, with macroeconomic, regulatory, or technological deviation prompting revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications Infrastructure
Slovenia Telecom Market
Telecommunications Infrastructure
Global Telecom Towers Market
Telecommunications Infrastructure
NLD and ILD Telecom Service Market
Telecommunications Infrastructure
South Korea Telecom Tower Market
Telecommunications Infrastructure
Latin America Telecom Tower Market
Telecommunications Infrastructure
Japan Telecom Towers Market
Telecommunications Infrastructure
United States Telecom Towers Market
Telecommunications Infrastructure
Bangladesh Telecom Towers Market
Telecommunications Infrastructure
Microwave Backhaul System Market
Telecommunications Infrastructure
Spain Telecom Towers Market
Telecommunications Infrastructure
United Kingdom Telecom Towers Market
Telecommunications Infrastructure
China Telecom Equipment Market
Telecommunications Infrastructure
Kenya Telecom Tower Market
Telecommunications Infrastructure
Fixed Telephony Service Market
Telecommunications Infrastructure
Peru Telecom Tower Market
Telecommunications Infrastructure
Session Initiation Protocol (SIP) Trunk Market