
 UAE Health Insurance Third Party Administrators (TPA) Market | 2026-2036
UAE Health Insurance Third Party Administrators (TPA) Market Size, Share, and Industry Trends Forecast 2026-2036
UAE Health Insurance Third Party Administrators (TPA) Market Insights
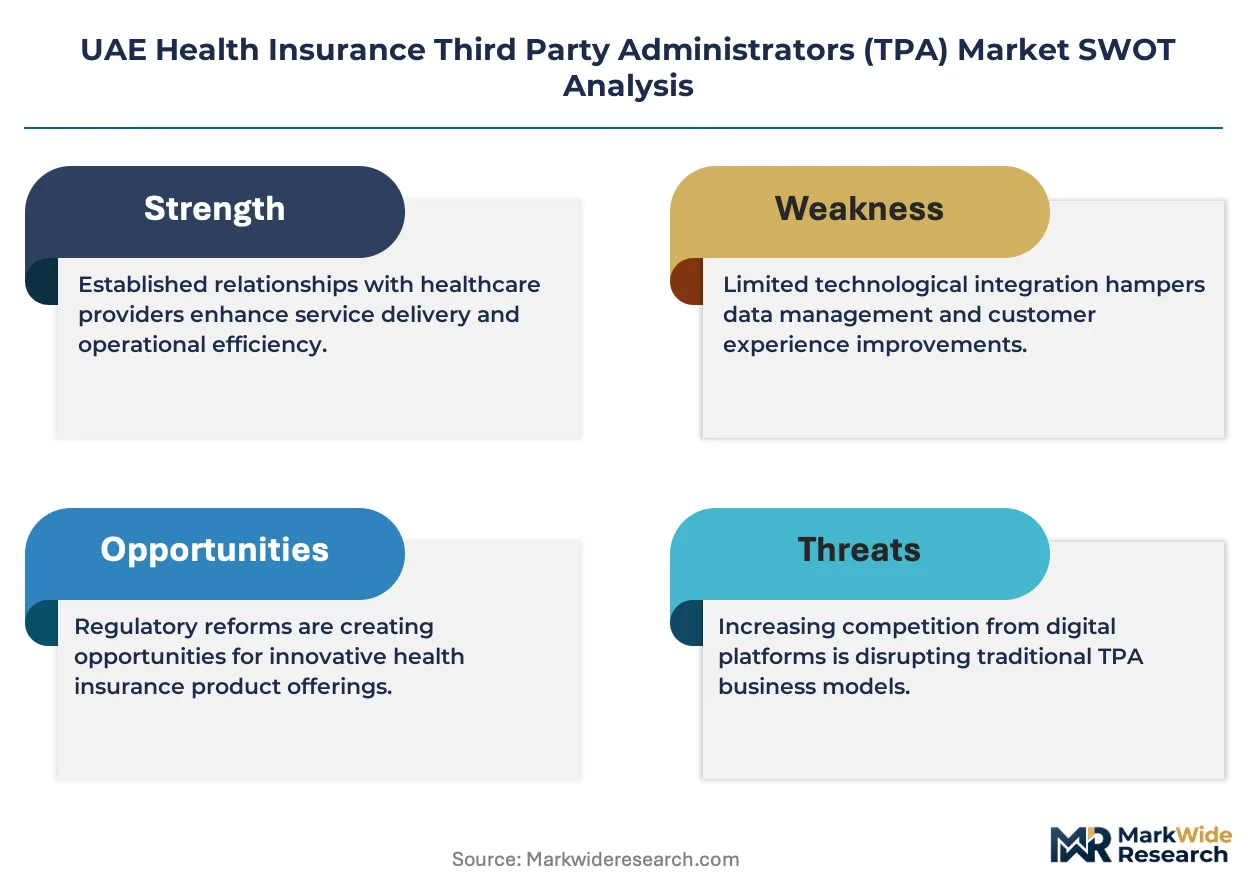
The premium-corporate TPA tier is shifting toward integrated digital health platforms while basic individual coverage remains transaction-heavy. Aetna International leverages its multinational provider network to sustain cross-border claims capabilities. GlobeMed Gulf anchors its position through proprietary payer-provider connectivity infrastructure. Nextcare differentiates via specialized chronic disease management programs for employer groups.
Third Party Administrators in UAE health insurance function as intermediaries processing claims, managing provider networks, and administering policy benefits between insurers and healthcare providers. Core operations require ISO 27001-certified data infrastructure, real-time eligibility verification systems, and automated pre-authorization workflows to comply with emirate-level health information exchange standards. Claims Management services occupy the largest revenue pool due to mandatory DHA and DOH electronic submission requirements, while AI-driven Platforms represent the fastest-expanding technology segment as TPAs deploy machine learning for fraud detection and predictive cost modeling. Provider Network Management commands premium margins where TPAs maintain exclusive hospital contracts in concentrated urban zones.
MOHAP, DHA, and DOH enforce escalating interoperability mandates that compel TPAs to upgrade legacy claims engines or exit licensed operation. ADGM and DIFC regulatory frameworks additionally govern TPA data residency and cross-border reinsurance arrangements for internationally portable policies. Stakeholders must monitor evolving emirate-specific accreditation thresholds that will determine which administrators retain preferred network status with dominant domestic insurers.
Market Dynamics
MOHAP, DHA, and DOH interoperability mandates are forcing wholesale replacement of legacy claims engines with ISO 27001-certified infrastructure, compressing the operational window for administrators unable to fund digital upgrades.
Growth Catalysts
- Electronic submission protocols:DHA-mandated digital claims workflows compel employer groups to engage TPAs with real-time eligibility systems, expanding addressable corporate accounts.
- Chronic disease management specialization:Employer demand for integrated diabetes and cardiovascular programs drives TPA investment in care coordination platforms.
- Abu Dhabi-Dubai corridor concentration:Hospital network density in these emirates enables TPAs to capture premium margins through exclusive provider contracts.
Market Restraints
- Data infrastructure capex intensity:ISO 27001 certification and HIE-compliant systems require capital outlays that exclude sub-scale administrators from licensed operation.
- Emirate-level regulatory fragmentation:Divergent MOHAP, DHA, and DOH technical standards force TPAs to maintain three parallel compliance architectures.
- AI fraud detection talent scarcity:Machine learning engineering expertise for predictive cost modeling concentrates in Dubai and Abu Dhabi, inflating compensation costs.
Strategic Opportunities
- Sharjah tertiary corridor emergence:Expanding hospital networks in this emirate create first-mover advantages for TPAs establishing provider relationships ahead of competitor entry.
- AI-platform convergence with claims engines:Integration of machine learning fraud detection with automated pre-authorization workflows differentiates premium-tier administrators.
- ADGM regulatory framework for portable policies:Cross-border reinsurance arrangements under this framework enable TPAs to serve internationally mobile corporate workforces.
Industry Challenges
- Legacy system integration complexity:TPAs must bridge decades-old payer databases with real-time HIE protocols without disrupting claims processing continuity.
- Interoperability certification timelines:Sequential MOHAP, DHA, and DOH accreditation processes delay market entry for new entrants by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UAE Health Insurance Third Party Administrators (TPA) Market |
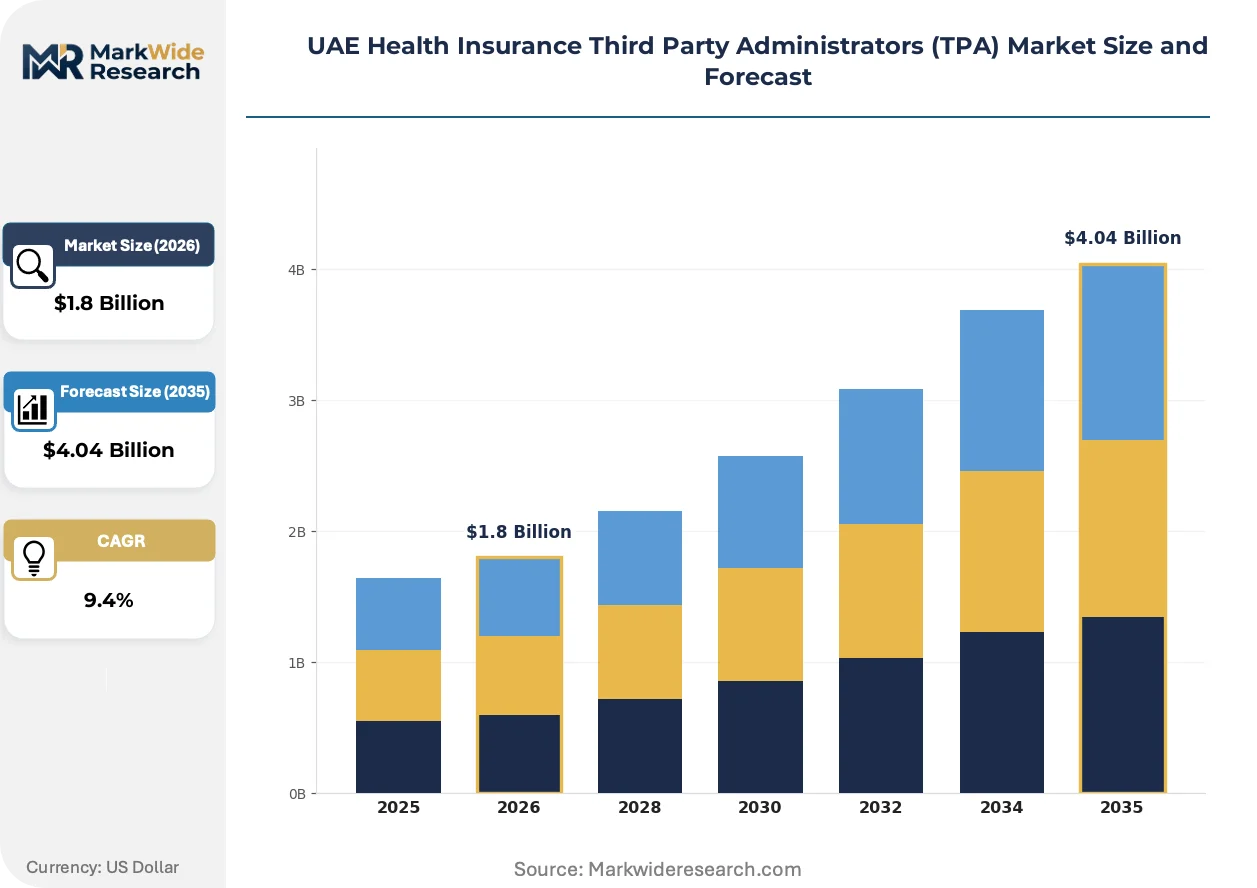
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Claims Management, Provider Network Management, Customer Service, Risk Management End User: Employers, Individual Policyholders, Insurance Companies, Healthcare Providers Technology: Cloud-based Solutions, AI-driven Platforms, Mobile Applications, Data Analytics Tools Coverage Type: In-patient, Out-patient, Dental, Maternity |
| Companies Covered | Aetna International, Aafiya Medical Billing Services, Nextcare, Inayah TPA, E Care International Medical Billing Services, NAS Neuron, Sehteq, GlobeMed Gulf, MedNet UAE, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UAE Health Insurance Third Party Administrators (TPA) Market Trends and Innovations
Machine learning infrastructure is consolidating operational advantages around administrators with capital reserves to deploy predictive analytics at scale, compressing the competitive set toward digitally mature players.
AI-driven fraud detection platforms are consolidating TPA competitive positioning by automating claims pattern recognition and flagging anomalous provider billing before payment authorization. Large employer groups in Dubai now mandate such capabilities in RFP evaluations, excluding administrators with rules-based legacy systems. The technology is consolidating market share among capitalized players capable of continuous model retraining on emirate-specific claims datasets.
DHA electronic submission mandates are eliminating paper-based claims workflows and compelling TPAs to deploy API-first architectures connecting directly to hospital information systems. Administrators without real-time eligibility verification face network exclusion by dominant domestic insurers. Dubai-based employer groups are responding by consolidating TPA relationships toward vendors with certified HIE connectivity.
Corporate procurement of TPA services is compressing contract renewal cycles from three-year to annual terms, with performance guarantees tied to claims turnaround time and pre-authorization automation rates. Employer benefits managers in Abu Dhabi now unbundle network management from claims administration, selecting specialized vendors for each function. This pattern is most visible among multinational corporate headquarters relocating to DIFC and ADGM free zones.
UAE Health Insurance Third Party Administrators (TPA) Market Segmentation
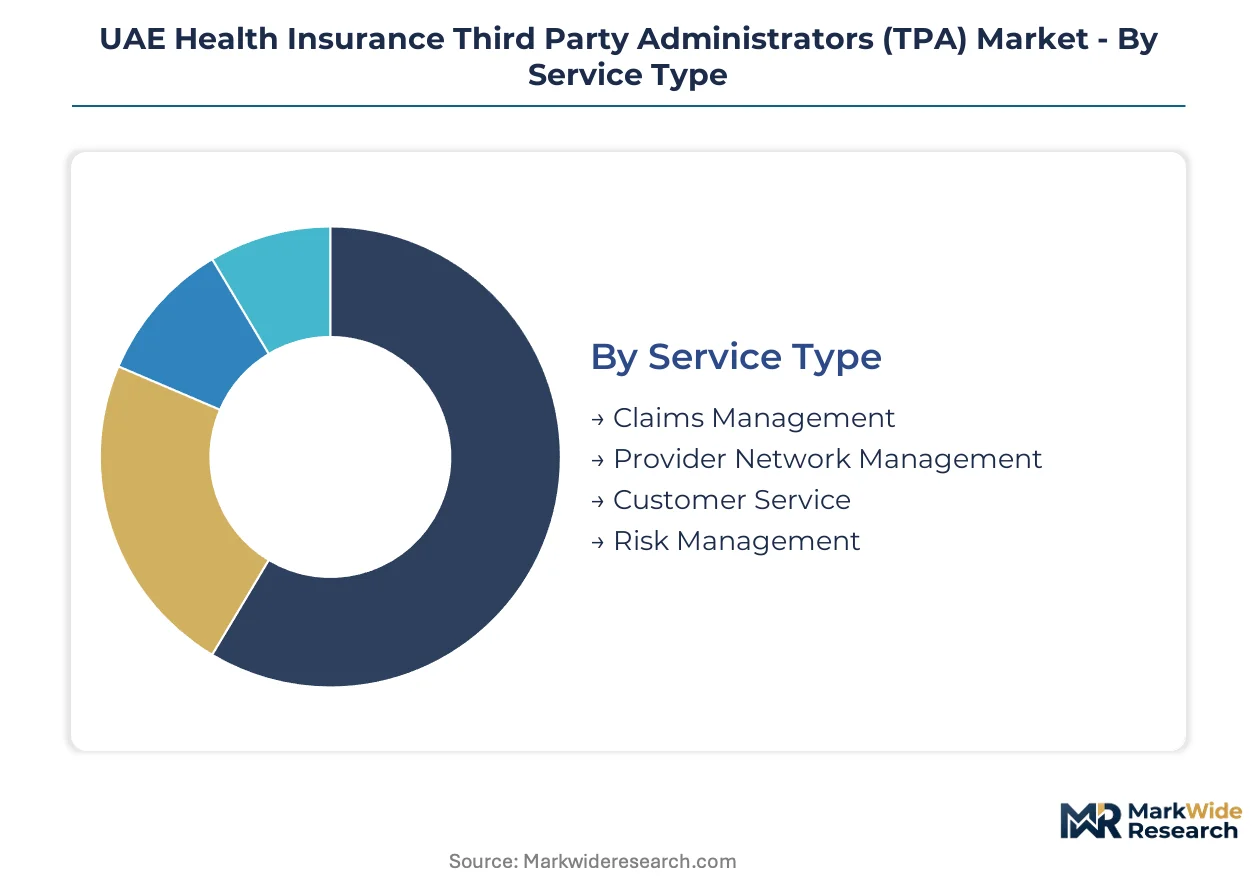
TPA service portfolios in the UAE fragment across operational functions, beneficiary categories, and technology architectures. Each segmentation dimension carries distinct margin profiles and regulatory compliance burdens that shape vendor selection criteria for insurers and employer groups.
Service Type:
Volume concentration sits with high-transaction processing functions, while premium margins attach to relationship-intensive network management capabilities.
- Claims Management:Core revenue engine processing electronic submissions through DHA-mandated workflows. Dubai employer groups now require sub-48-hour turnaround times as table stakes, compressing margins for administrators without automated adjudication infrastructure.
- Provider Network Management:Exclusive hospital contracts in Abu Dhabi and Dubai corridor command premium positioning. TPAs maintaining direct API connectivity to dominant private hospital groups capture preferred vendor status with domestic insurers.
- Customer Service:Multilingual call center operations serving Arabic-English-Tagalog speaking policyholder bases. Labor cost arbitrage drives some administrators toward Sharjah-based service centers.
- Risk Management:Actuarial support and stop-loss administration for self-insured employer plans. Concentrated demand among multinational corporations with DIFC and ADGM free zone headquarters.
Today's leader: Claims Management. Tomorrow's challenger: Provider Network Management.
End User:
Corporate procurement patterns diverge sharply from individual retail engagement, with intermediated channels dominating volume flows.
- Employers:Mandatory health insurance obligations under DHA and DOH frameworks generate recurring TPA contracts. Large corporate accounts in Dubai increasingly unbundle network management from claims administration.
- Individual Policyholders:Direct-to-consumer TPA engagement remains limited, with most individuals accessing services through insurer intermediation. Growth potential exists in high-net-worth expatriate segments seeking concierge medical coordination.
- Insurance Companies:Domestic carriers outsource operational functions to TPAs with certified HIE infrastructure. Accreditation thresholds determine preferred partnership status.
- Healthcare Providers:Hospitals and clinic networks engage TPAs for revenue cycle management and claims dispute resolution. Concentrated in Abu Dhabi-Dubai corridor where provider density enables scale economies.
Employer groups anchor current revenue. Insurance companies represent the structural expansion path.
Technology:
Capital deployment intensity separates scalable platforms from transaction-heavy legacy operations.
- Cloud-based Solutions:ISO 27001-certified infrastructure enables real-time eligibility verification across emirate-level health information exchanges. DHA electronic submission mandates effectively require cloud-native architectures for new market entrants.
- AI-driven Platforms:Machine learning fraud detection and predictive cost modeling differentiate premium-tier administrators. Talent scarcity in Dubai and Abu Dhabi inflates development costs for continuous model retraining.
- Mobile Applications:Policyholder-facing interfaces for claims submission and provider directory access. Adoption concentrated among younger expatriate demographics in Dubai corporate workforce segments.
- Data Analytics Tools:Employer-facing dashboards reporting utilization patterns and cost drivers. Demand rising among multinational headquarters with centralized benefits management functions.
Cloud infrastructure dominates deployment volume. AI platforms are climbing the fastest as competitive differentiators.
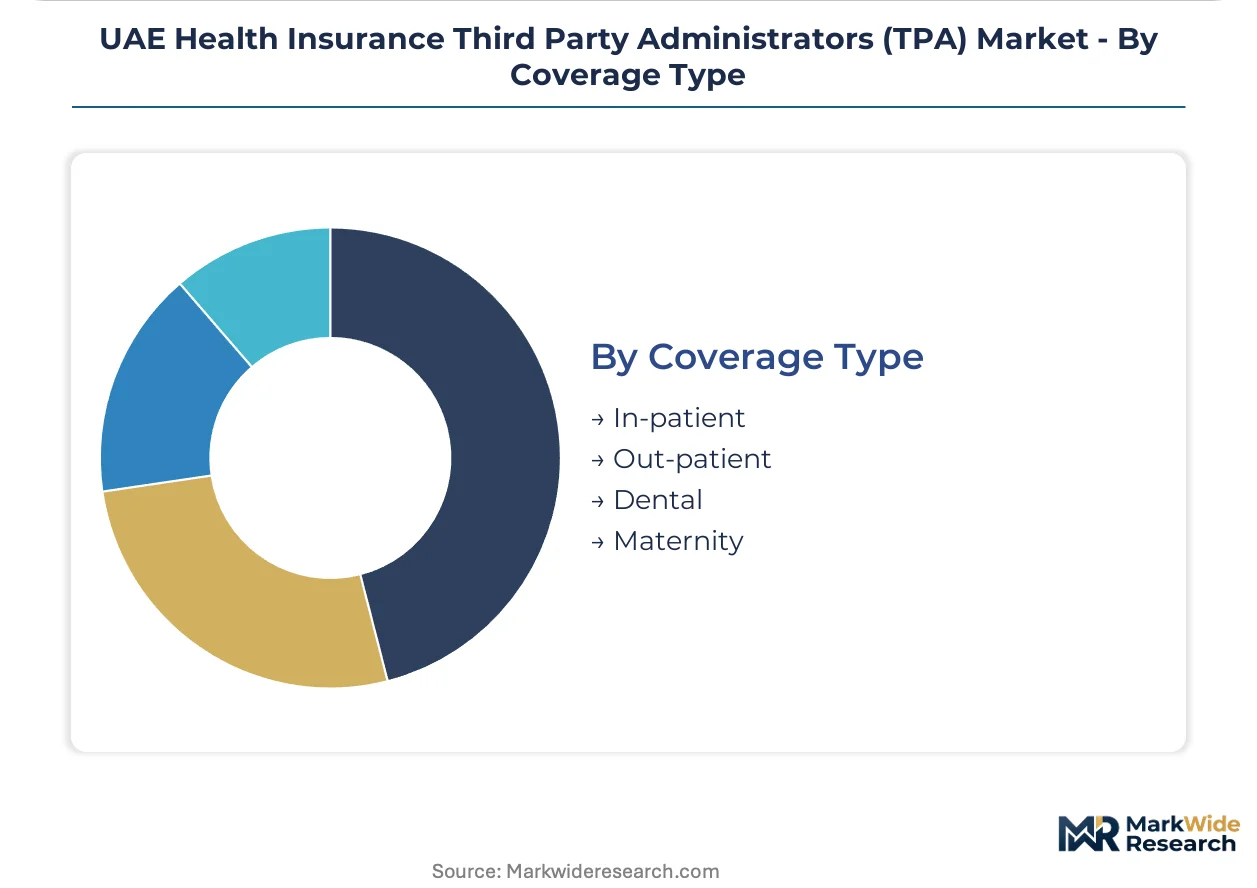
Coverage Type:
Benefit category complexity determines TPA operational specialization and pricing power.
- In-patient:High-value claims requiring intensive pre-authorization and utilization review. Abu Dhabi hospital networks generate concentrated transaction volumes.
- Out-patient:High-frequency, low-value transactions demanding automated processing. Dubai employer groups prioritize turnaround time metrics in vendor selection.
- Dental:Specialized provider network requirements with limited coverage penetration in basic employer plans. Niche positioning for administrators with orthodontic and cosmetic procedure expertise.
- Maternity:Predictable high-cost episodes with defined clinical pathways. Sharjah corridor expansion creates network development opportunities for maternity-focused TPA capabilities.
In-patient services command premium positioning. Out-patient volumes scale fastest with employer mandate expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Expatriate healthcare professionals cluster in Dubai and Abu Dhabi, anchoring TPA operational scale across the emirates. This talent concentration shapes regional service delivery patterns and technology deployment priorities.
Dubai
Corporate headquarters relocation to DIFC drives demand for internationally portable health policies. DHA mandates electronic claims submission protocols that exclude administrators without real-time HIE connectivity. Dubai Healthcare City clusters specialist hospitals where TPAs maintain exclusive network contracts.
Abu Dhabi
DOH interoperability standards compel legacy system replacement across licensed administrators. Mandatory health insurance under the Thiqa and Enhanced schemes generates recurring TPA contracts for employer groups. Al Maryah Island and Yas Island medical districts concentrate premium hospital capacity.
Sharjah
Expanding hospital networks in this emirate create first-mover opportunities for provider relationship development. MOHAP technical standards apply alongside federal baseline requirements. University City and Sharjah Healthcare City emerging as tertiary care destinations.
Northern Emirates
Ras Al Khaimah and Fujairah employer groups rely on Dubai-based TPAs with extended network reach. Federal MOHAP standards govern where emirate-specific regulators lack jurisdiction. Healthcare infrastructure gaps sustain dependence on Abu Dhabi-Dubai corridor providers.
UAE Health Insurance Third Party Administrators (TPA) Market Competitive Landscape
Top-tier vendors anchor premium service tiers, while mid-scale administrators compete on transaction processing efficiency. The vendor base separates into three distinct tiers: multinational networks with cross-border capabilities, regional specialists with emirate-specific accreditation depth, and transaction processors serving cost-sensitive employer segments. Consolidation pressure intensifies as DHA and DOH interoperability mandates raise capital barriers. M&A activity concentrates among administrators seeking ISO 27001-certified infrastructure through acquisition rather than organic development.
Within the multinational network tier, Aetna International and GlobeMed Gulf exemplify archetypes leveraging cross-border provider relationships and proprietary payer connectivity infrastructure. Nextcare occupies a position among regional specialists investing in chronic disease management differentiation. These three anchors demonstrate how competitive positioning increasingly depends on technology certification depth rather than network size alone.
| Leading Market Players |
|---|
| Aetna International |
| Aafiya Medical Billing Services |
| Nextcare |
| Inayah TPA |
| E Care International Medical Billing Services |
| NAS Neuron |
| Sehteq |
| GlobeMed Gulf |
| MedNet UAE |
| Others |
Pricing and Supply Chain Analysis
Machine learning engineering talent clustering in Dubai and Abu Dhabi widens labor-cost differentials between premium-tier TPAs and transaction-heavy administrators, compressing margins at the economy end while sustaining pricing power for certified digital platforms.
Pricing Analysis
The bundled-versus-unbundled service split now defines TPA pricing architecture across the UAE. Three-tier pricing structure across premium, standard, and economy levels separates AI-enabled administrators with real-time HIE connectivity from rules-based legacy processors. Price differentiation rests on ISO 27001 certification grade and exclusive provider contract density. Pricing pressure stems from corporate procurement teams unbundling network management from claims administration. Small employer groups in Sharjah and the Northern Emirates exhibit highest price sensitivity, while DIFC-headquartered multinationals prioritize performance guarantees over unit cost.
Supply Chain Analysis
Logistics and freight cost exposure remains minimal for TPA services given digital delivery, yet physical infrastructure dependencies concentrate in the UAE, India, and the Philippines. Cloud infrastructure provisioning draws from hyperscaler data centers in Dubai and Abu Dhabi, while multilingual call center operations source from Sharjah and offshore facilities in South Asia. Supply chain risk centers on single-source vulnerability for ISO 27001-certified hosting providers. Distribution runs through direct enterprise sales teams for corporate accounts and insurer partnership channels for embedded TPA services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UAE Health Insurance TPA market functions as a stable compounder underpinned by mandatory employer health insurance obligations that generate recurring revenue streams regardless of economic cycles.
For Market Incumbents: Acquire ISO 27001-certified infrastructure assets to compress compliance timelines for new emirate accreditations. Defensive consolidation should target administrators with established DOH or MOHAP interoperability credentials ahead of tightening DHA mandates. Threats from AI-native entrants with superior fraud detection capabilities necessitate continuous model retraining investments. Backward integration into proprietary payer-provider API connectivity secures preferred vendor status with dominant domestic insurers. For New Entrants and Emerging Players: The mid-market price-point gap between premium AI-enabled TPAs and economy transaction processors offers white-space opportunity. Sharjah's emerging hospital networks represent the most penetrable geography for first-mover provider relationship development. Unbundled risk management services for self-insured DIFC and ADGM corporations present a specialized entry vector. Go-to-market positioning should emphasize rapid accreditation completion through cloud-native architecture deployment. For Investors and Strategic Acquirers: Valuations sit cheapest among sub-scale administrators with legacy systems facing DHA-mandated replacement costs. Long-term viability over a five-to-ten-year horizon favors TPAs with demonstrated cross-emirate accreditation depth and exclusive hospital network contracts. Acquisition target archetype: regional specialists with MOHAP certification and underutilized chronic disease management capabilities. The signal to watch is corporate procurement RFP language shifting from network size metrics to AI fraud detection and pre-authorization automation rate guarantees.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 27001 Certification Investment | Enables real-time HIE connectivity required by DHA electronic submission mandates. |
| AI Fraud Detection Platform Deployment | Differentiates premium-tier administrators in corporate RFP evaluations across Dubai. |
| Sharjah Provider Network Expansion | Captures first-mover advantage in tertiary corridor before competitor entry accelerates. |
| Chronic Disease Management Specialization | Addresses employer demand for integrated diabetes and cardiovascular care coordination. |
| Cross-Border Reinsurance Arrangement | Unlocks ADGM framework opportunities for internationally mobile corporate workforces. |
Research Methodology
Coverage spans Dubai, Abu Dhabi, Sharjah, and the Northern Emirates, with primary inputs from each emirate's regulatory environment and stakeholder base. Primary interviews engaged TPA operations executives, health insurance procurement managers at multinational employers, DHA and DOH regulatory affairs specialists, and hospital network contracting officers. Secondary validation drew from MOHAP interoperability standards documentation, DHA electronic submission protocol releases, DOH accreditation guidelines, and UAE health insurance regulatory circulars. Bottom-up service line revenue modeling triangulated against top-down employer mandate penetration estimates.
Rate-of-change decomposition across the analysis window isolated volume expansion from price-mix effects and technology substitution patterns. Segmentation dimensions modeled include service type, end user category, technology architecture, coverage type, and emirate-level regulatory cluster. CAGRs were derived from fitted trend extrapolation adjusted for regulatory mandate implementation schedules. Forecast inputs incorporated DHA electronic submission deadline enforcement patterns and corporate procurement cycle compression trends.
Caveats apply where MOHAP, DHA, or DOH interoperability mandate delays could materially shift the outlook for technology upgrade investment timelines. Forecasts reflect assumptions regarding employer mandate enforcement consistency and hospital network expansion plans in Sharjah. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Health Insurance
Germany Health Insurance Market
Health Insurance
US Group Health Insurance Market
Health Insurance
Healthcare Reimbursement Market
Health Insurance
UAE Health Insurance Market
Health Insurance
Health Insurance Market
Health Insurance
Healthcare Payer Services Market
Health Insurance
North America Group Health Insurance Market
Health Insurance
Indonesia Health and Medical Insurance Market
Health Insurance
US Healthcare Discount Plan Market
Health Insurance
Healthcare Payer Solution Market
Health Insurance
Healthcare Insurance Market
Health Insurance
UAE Health and Medical Insurance Market
Health Insurance
United States Health and Medical Insurance Market