
 Indonesia Health and Medical Insurance Market | 2026-2036
Indonesia Health and Medical Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Indonesia Health and Medical Insurance Market Foresight
The gap between premium comprehensive plans and basic BPJS-supplement products is hardening. Prudential Indonesia leverages its bancassurance network to dominate high-margin individual policies. Manulife Indonesia anchors corporate group schemes through direct employer relationships. Allianz Life Indonesia differentiates via specialized inpatient riders tied to private hospital chains.
Health and medical insurance constitutes risk-pooling financial instruments designed to cover hospitalization, outpatient treatment, and preventive care costs through premium contributions and actuarial reserve management. Products incorporate waiting periods, co-payment ratios, and annual benefit limits calibrated to morbidity tables and provider network tariffs. Corporate group policies represent the deepest margin pool due to employer-sponsored premium structures and low acquisition costs. Individual policies exhibit faster expansion as self-employed professionals and affluent families seek BPJS gap coverage beyond state ceilings. Inpatient coverage commands the largest premium share, though outpatient riders gain traction through digital-first distribution.
BPJS Kesehatan, Otoritas Jasa Keuangan (OJK), and the Ministry of Health collectively shape product standards, pricing transparency rules, and mandatory participation thresholds. OJK's digital licensing framework accelerates insurtech entry, while BPJS integration requirements force private insurers to design complementary rather than competing coverage. Stakeholders must monitor regulatory shifts around premium adjustment mechanisms and the potential elevation of minimum benefit standards.
Market Dynamics
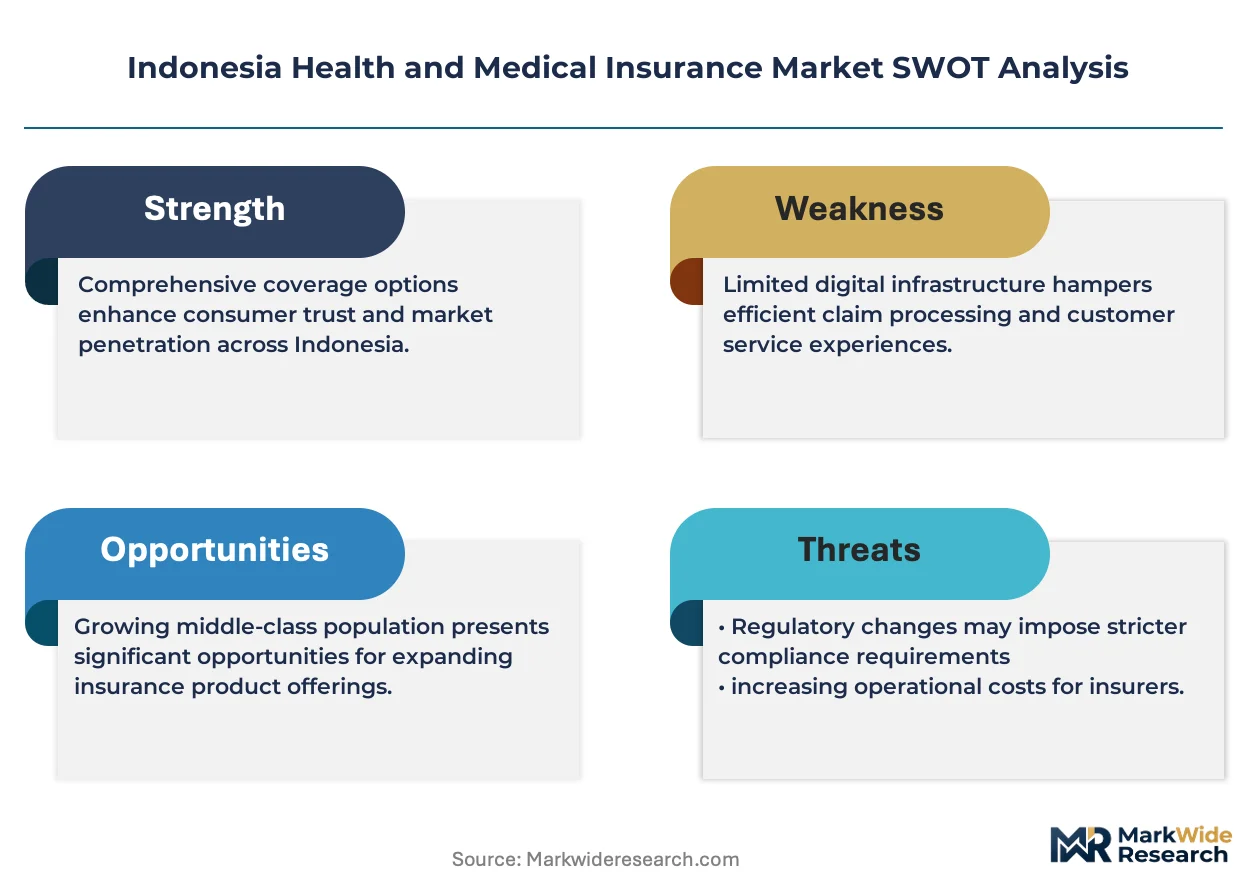
BPJS Kesehatan's universal mandate has bifurcated Indonesia's insurance landscape into state-mandated basic coverage and premium private gap products, forcing insurers to recalibrate distribution networks and actuarial models around complementary positioning rather than direct competition.
Growth Catalysts
- OJK Digital Licensing:The financial services authority's streamlined insurtech approval process accelerates platform-based distribution models and reduces capital barriers for technology-enabled entrants.
- Employer-Sponsored Schemes:Multinational corporations operating in Jakarta and Surabaya expand corporate group policies as talent retention instruments, creating stable premium pools with low customer acquisition costs.
- Private Hospital Network Expansion:Concentrated growth of premium inpatient facilities in Greater Java drives demand for specialized riders tied to specific provider chains.
Market Restraints
- Morbidity Table Uncertainty:Limited longitudinal health data across Indonesia's archipelago geography complicates actuarial pricing precision and reserve adequacy calculations.
- BPJS Ceiling Compression:State-mandated benefit maximums suppress private insurer pricing power for basic coverage tiers and limit addressable market expansion.
- Claims Adjudication Infrastructure:Fragmented electronic health record systems between public and private providers delay claims processing and elevate administrative cost ratios.
Strategic Opportunities
- Outpatient Rider Penetration:Digital-first distribution platforms enable scalable attachment of preventive care and telemedicine modules to core inpatient policies.
- Surabaya Corporate Hub:Indonesia's second-largest city exhibits underpenetrated group policy density relative to Jakarta, presenting whitespace for direct employer relationship models.
- Ministry of Health Integration Mandates:Regulatory pressure for interoperability between private insurers and public health information exchanges creates first-mover advantages for compliant platforms.
Industry Challenges
- Actuarial Talent Scarcity:Indonesia's domestic supply of health insurance specialists with archipelago-specific morbidity modeling experience remains insufficient for market expansion pace.
- Legacy System Integration:Established insurers face technical debt burdens when connecting proprietary policy administration systems to emerging digital health platforms and BPJS data interfaces.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indonesia Health and Medical Insurance Market |
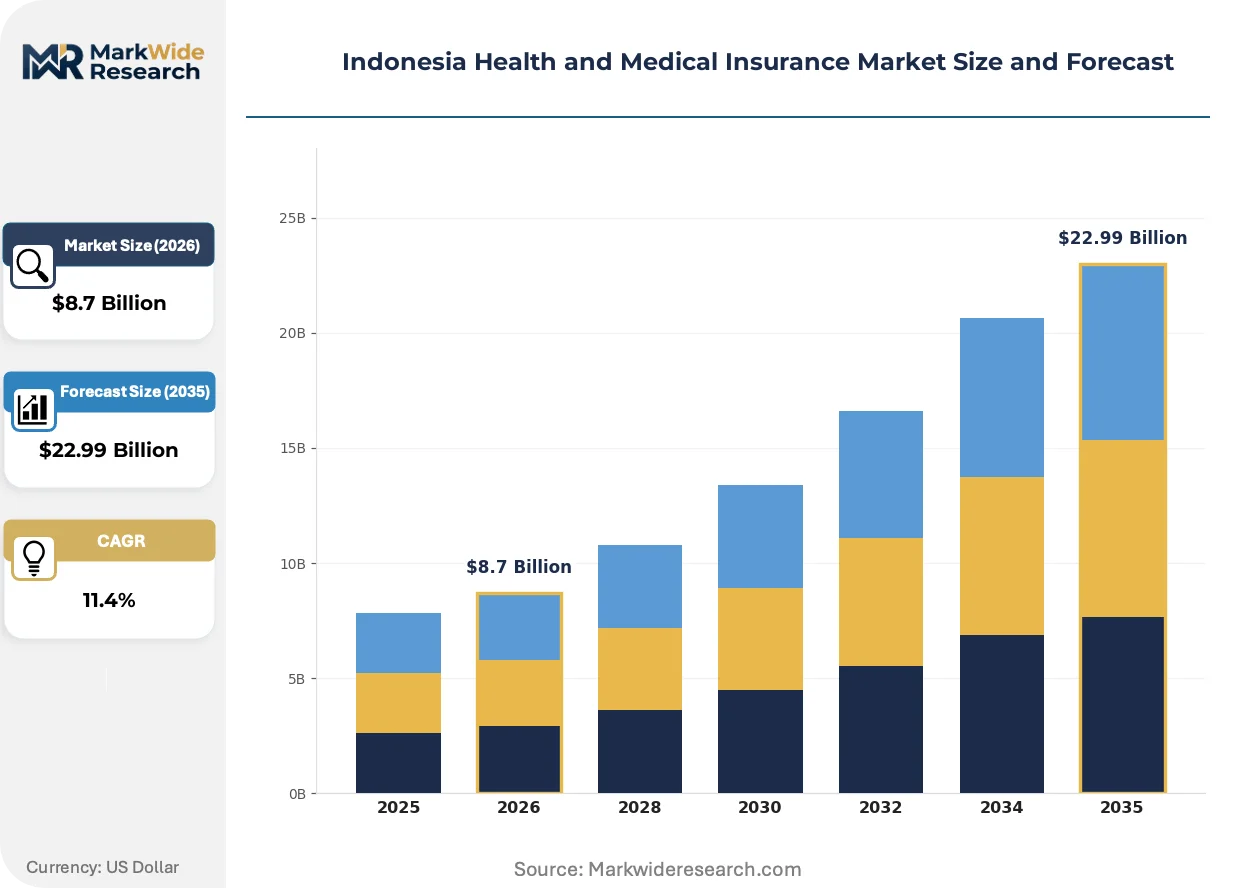
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Policy Type: Individual, Family, Group, Corporate Coverage Type: Inpatient, Outpatient, Dental, Maternity Payment Model: Fee-for-Service, Capitation, Pay-per-Event, Comprehensive End User: Employees, Self-Employed, Families, Retirees |
| Companies Covered | AXA Mandiri Financial Services, Manulife Indonesia, Prudential Indonesia, Panin Dai-ichi Life, BCA Life, Allianz Life Indonesia, Astra Aviva Life, Cigna Insurance, AIA Financial Indonesia, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indonesia Health and Medical Insurance Market Shifts & Advancements
Digital health platform integration is compressing traditional distribution timelines and enabling real-time risk assessment models that reshape how insurers interact with both policyholders and provider networks across Indonesia's fragmented geography.
Telemedicine infrastructure is decentralizing primary care access across Indonesia's outer islands. Rural and semi-urban policyholders in Sumatra and Sulawesi now access specialist consultations through mobile-enabled platforms. This technology is decentralizing the historical Jakarta-centric concentration of diagnostic and treatment decisions, forcing insurers to restructure provider network contracts and reimbursement protocols.
OJK's digital licensing framework mandates API-first architecture standards for new market entrants. This regulatory requirement compresses time-to-market for insurtech platforms while elevating compliance costs for legacy carriers. Direct-to-consumer distribution channels and embedded insurance products are most affected, with established players accelerating technology partnerships to meet interoperability deadlines.
Self-employed professionals in Bali and Yogyakarta are abandoning traditional agent-mediated policy purchases in favor of comparison-platform transactions. Digital aggregators capture this behavioral shift through instant premium quoting and automated underwriting. This pattern concentrates most visibly among freelance technology workers and creative industry contractors seeking BPJS gap coverage with minimal friction.
Indonesia Health and Medical Insurance Market Segmentation
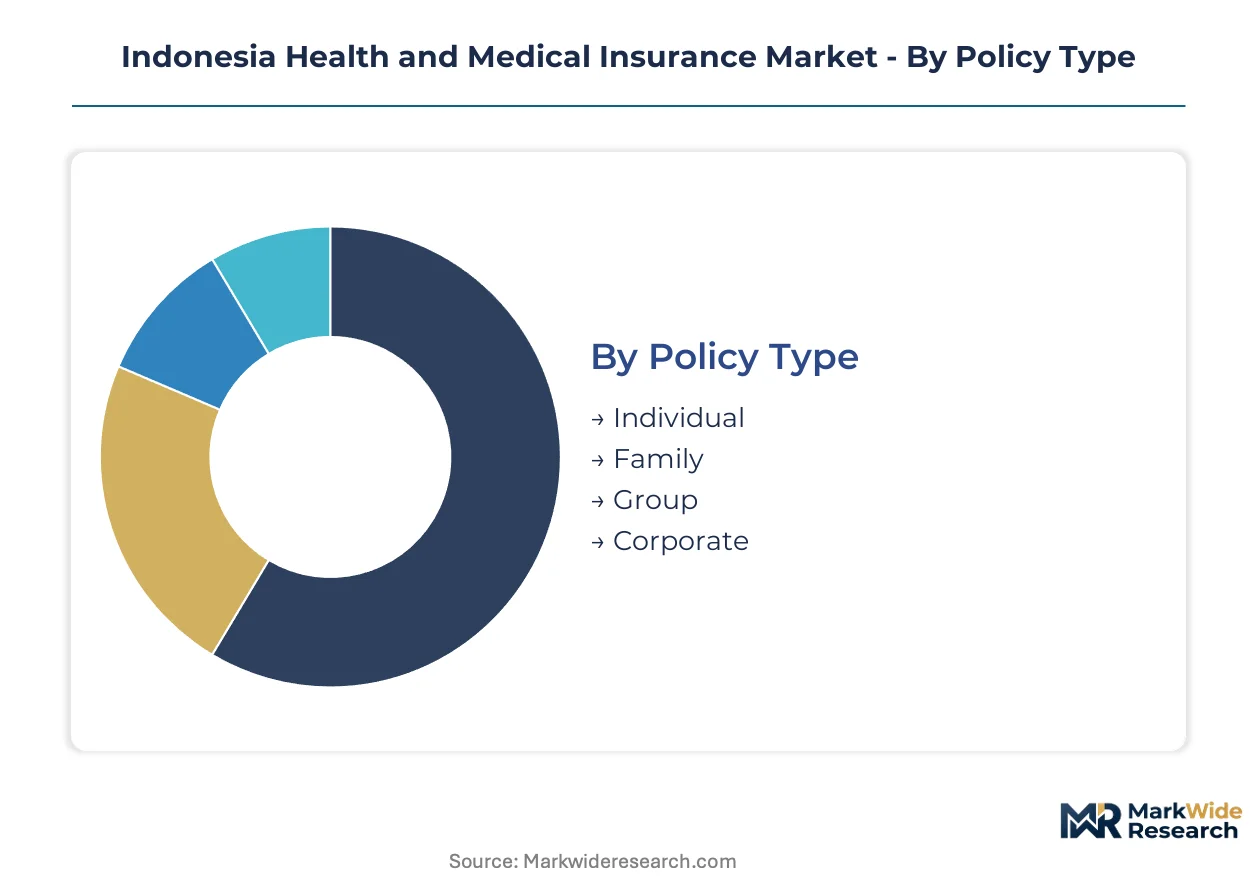
Segmentation in Indonesia's health insurance market reflects the structural divide between BPJS-mandated basic coverage and premium private gap products. Insurers calibrate distribution networks, pricing models, and actuarial reserves differently across each segment cluster.
Policy Type:
Volume concentrates in employer-sponsored schemes while premium yields favor individual policies with specialized riders.
- Individual:Self-employed professionals and affluent families purchase these policies to bridge BPJS coverage ceilings, particularly in Greater Jakarta where private hospital density supports high-margin rider attachments. Digital aggregators accelerate transaction velocity among freelance technology workers in Bali and Yogyakarta.
- Family:Multi-life policies bundle dependent coverage under single premium structures, with demand clustering among middle-income households in Surabaya seeking coordinated outpatient and maternity benefits. OJK's digital licensing framework enables instant underwriting for nuclear family configurations.
- Group:Small and medium enterprises outside Jakarta's corporate core utilize these schemes for standardized benefit tiers with simplified enrollment.
- Corporate:Multinational employers leverage these policies as talent retention instruments, creating stable premium pools with low acquisition costs through direct broker relationships.
Mature deployment sits with Corporate policies. Newer deployment is concentrated in Individual policies.
Coverage Type:
Cost tier differentiation separates basic inpatient mandates from premium outpatient and specialized care modules.
- Inpatient:Hospitalization coverage commands the largest premium share across all policy types, with benefits calibrated to private room tariffs and surgical procedure costs at Jakarta's premium hospital networks. Actuarial reserves for this segment draw on archipelago-specific morbidity tables with limited longitudinal data.
- Outpatient:Preventive care and specialist consultation riders gain traction through telemedicine platforms, particularly in Sumatra and Sulawesi where geographic fragmentation drives mobile-enabled primary care access. Digital-first distribution compresses attachment timelines for these modules.
- Dental:Elective coverage remains a niche attachment with concentrated uptake among expatriate communities and corporate expatriate benefit schemes.
- Maternity:Specialized riders attach predominantly to family policies in urban Java where private maternity hospital networks have expanded capacity.
Established revenue concentration sits with Inpatient coverage. Steepest expansion trajectory belongs to Outpatient riders.
Payment Model:
Customer type and risk tolerance determine selection across reimbursement structures, with corporate schemes favoring predictability and individual policyholders accepting variable exposure.
- Fee-for-Service:Traditional reimbursement dominates legacy policy administration systems, though claims adjudication delays from fragmented electronic health records elevate administrative cost ratios.
- Capitation:Fixed per-member-per-month payments to provider networks concentrate in corporate group schemes where employers prioritize budget certainty over utilization flexibility.
- Pay-per-Event:Episodic reimbursement structures appeal to self-employed professionals with irregular income patterns seeking premium flexibility.
- Comprehensive:All-inclusive coverage bundles command premium pricing and attach most frequently to high-net-worth individual policies with concierge service expectations.
Legacy infrastructure supports Fee-for-Service dominance. Capitation models are gaining share fastest among new corporate schemes.
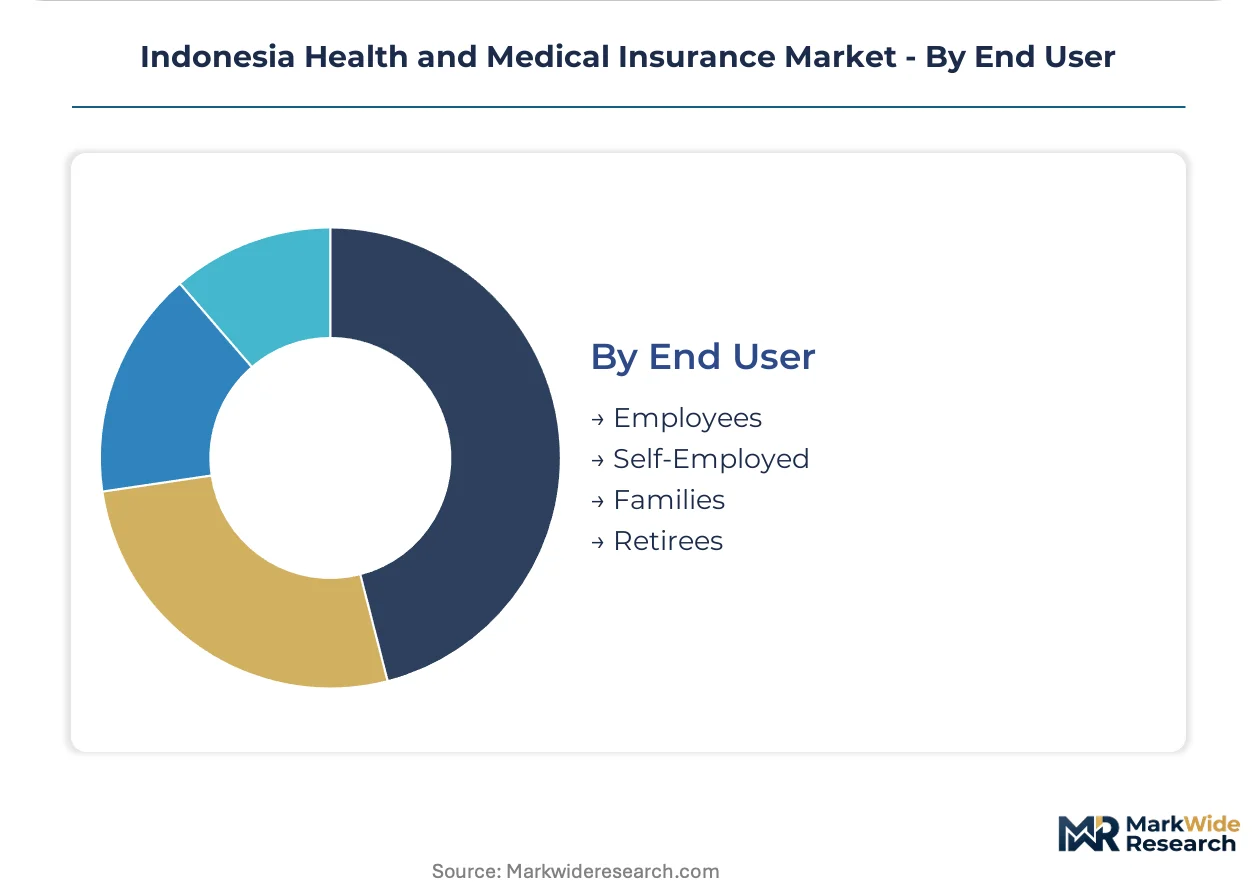
End User:
Geography and employment status segment addressable demand, with Java-based formal employment contrasting outer island informal coverage gaps.
- Employees:Formal sector workers access coverage primarily through employer-sponsored schemes, with density highest in Jakarta and Surabaya multinational corporate hubs. BPJS integration requirements force complementary private coverage design.
- Self-Employed:Freelance professionals and small business owners drive individual policy expansion, abandoning agent-mediated purchases for digital comparison platforms. This segment exhibits the sharpest behavioral shift toward embedded insurance products.
- Families:Multi-generational coverage decisions concentrate household purchasing power, with policy selection influenced by pediatric and maternity benefit adequacy.
- Retirees:Post-employment coverage represents underpenetrated whitespace, with limited product development addressing longevity risk and chronic condition management in Indonesia's aging demographic.
Current premium concentration sits with Employees. Self-Employed users are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Greater Jakarta concentrates Indonesia's health insurance demand through overlapping private hospital networks and multinational employer schemes. Surabaya anchors corporate group policy expansion as Indonesia's second metropolitan hub. Provincial capitals in Sumatra and Sulawesi exhibit emerging outpatient rider traction via telemedicine platforms.
Java
Corporate group policies cluster densely in Jakarta and Surabaya where multinational employers compete for talent through comprehensive coverage. BPJS Kesehatan integration mandates from the Ministry of Health force private insurers to design complementary gap products rather than competing coverage. Bandung's growing technology workforce drives individual policy adoption through digital aggregator platforms.
Sumatra
Medan's private hospital network expansion creates demand for specialized inpatient riders tied to specific provider chains. OJK's digital licensing framework enables insurtech platforms to penetrate previously underserved semi-urban areas. Palembang's manufacturing corridor exhibits rising employer-sponsored scheme density among industrial employers.
Sulawesi
Geographic fragmentation across Indonesia's fourth-largest island accelerates telemedicine-enabled outpatient rider attachment. Makassar's port economy supports corporate group policy growth among logistics and shipping employers. Localized morbidity data scarcity complicates actuarial pricing precision for regional underwriters.
Bali
Self-employed professionals in the creative and technology sectors abandon traditional agent-mediated purchases for comparison-platform transactions. Digital-first distribution compresses underwriting timelines for freelance workers seeking BPJS gap coverage. Denpasar's hospitality industry drives demand for portable individual policies among transient professional populations.
Kalimantan
Resource extraction employers in Balikpapan and Samarinda utilize corporate group schemes as retention instruments in competitive labor markets. Limited private hospital infrastructure constrains premium inpatient rider penetration outside major cities. Mining sector occupational health requirements intersect with private insurance product design.
Indonesia Health and Medical Insurance Market Competitive Landscape
Premium-margin players sit above commodity-margin players across distribution sophistication and rider specialization. The market exhibits tiered consolidation with bancassurance networks, direct employer relationships, and digital platforms representing distinct competitive vectors. Three archetypes dominate: integrated financial conglomerates with captive banking channels, specialist life insurers with corporate group expertise, and technology-enabled entrants leveraging OJK's streamlined licensing. Dominant competitive moves include bancassurance network deepening and outpatient rider portfolio expansion.
Among integrated financial conglomerates, AXA Mandiri Financial Services and BCA Life anchor the bancassurance tier through captive banking relationships. Manulife Indonesia and Prudential Indonesia exemplify scale-driven specialists with differentiated corporate group and individual policy positioning. Allianz Life Indonesia occupies a position within the specialized rider segment tied to private hospital network partnerships.
| Leading Market Players |
|---|
| AXA Mandiri Financial Services |
| Manulife Indonesia |
| Prudential Indonesia |
| Panin Dai-ichi Life |
| BCA Life |
| Allianz Life Indonesia |
| Astra Aviva Life |
| Cigna Insurance |
| AIA Financial Indonesia |
| Others |
Supply & Pricing Matrix
Premium-to-basic coverage bifurcation between BPJS-complementary gap products and state-mandated floors creates divergent pricing architectures across Indonesia's health insurance value chain. This tier divergence manifests in actuarial reserve requirements, provider network contracting terms, and distribution cost structures that reshape how insurers source underwriting capacity and medical provider access.
Pricing Analysis
Value-based pricing anchored to inpatient throughput at named private hospital chains dominates premium tier structures, with riders calibrated to surgical procedure volumes and private room utilization rates. Three-tier pricing structure across premium, standard, and economy levels differentiates by provider network breadth and annual benefit ceilings. Cost compression in economy tiers intensifies because BPJS ceiling compression limits pricing power for basic coverage. Self-employed professionals purchasing through digital aggregators exhibit highest price sensitivity, while multinational corporate schemes show lowest sensitivity due to employer-sponsored premium structures.
Supply Chain Analysis
Dual-sourcing requirements for actuarial talent and medical provider networks force insurers to qualify multiple underwriting partners and hospital chains simultaneously. Domestic supply concentrates in Jakarta and Surabaya for corporate policy administration, with secondary capacity in Bandung and Denpasar for individual policy processing. Raw material dependencies include proprietary morbidity data, electronic health record infrastructure, and licensed medical provider directories. Single-source vulnerability in archipelago-specific morbidity modeling creates concentration risk for regional pricing precision. Distribution runs through bancassurance networks, direct employer relationships, and digital aggregator platforms in descending volume share.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Indonesia's health insurance market operates as a supply-constrained environment where actuarial talent scarcity props pricing power for specialist underwriters with archipelago-specific morbidity modeling capabilities.
For Market Incumbents: Hedge against insurtech platform disruption by deepening bancassurance network exclusivity and accelerating outpatient rider portfolio expansion. Acquire specialist actuarial capabilities in outer island morbidity modeling before talent scarcity intensifies. Vertical integration into telemedicine provider networks secures preferred reimbursement protocols for emerging digital-first distribution channels. For New Entrants and Emerging Players: Enter via Surabaya's underpenetrated corporate group policy density relative to Jakarta saturation. Target self-employed professionals in Bali and Yogyakarta through embedded insurance products on freelance platform marketplaces. White-space concentration sits with outpatient rider attachment to existing BPJS coverage through API-first distribution partnerships. For Investors and Strategic Acquirers: Re-rating potential sits with insurtech platforms possessing OJK digital licensing compliance and hospital network API integration given Ministry of Health interoperability mandates. Long-term viability over a multi-year horizon favors acquirers of archipelago-specific morbidity data assets. Monitor BPJS premium adjustment mechanism announcements as the critical inflection signal for private insurer pricing power expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Outpatient Rider Portfolio Expansion | Telemedicine platform partnerships in Sumatra and Sulawesi capture geographic fragmentation value. |
| API-First Architecture Compliance | OJK digital licensing mandates create first-mover advantage for interoperable policy administration systems. |
| Surabaya Corporate Hub Development | Direct employer relationships in Indonesia's second metropolis exploit whitespace in group policy density. |
| Actuarial Talent Acquisition | Specialist health insurance expertise with archipelago morbidity modeling experience addresses critical supply constraint. |
| BPJS Integration Partnership | Ministry of Health data interoperability requirements force complementary product design alignment. |
Research Methodology
Regulatory filings from Otoritas Jasa Keuangan, BPJS Kesehatan annual reports, and Ministry of Health policy circulars formed the secondary backbone of this analysis. Primary interviews with health insurance product managers, actuarial directors, hospital procurement officers, and digital platform executives combined with secondary validation across these sources. Bottom-up and top-down triangulation anchored market sizing to policy issuance data and premium pool estimates.
Analytical lenses alternated between bottom-up policy enumeration and top-down healthcare expenditure allocation across the projection horizon. Segmentation dimensions modeled include policy type, coverage tier, payment structure, and geographic demand cluster. CAGRs derived from actuarial reserve growth trajectories and premium pool expansion rates. Forecast inputs incorporated morbidity table evolution assumptions and digital platform penetration curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under BPJS benefit ceiling adjustments and OJK regulatory acceleration scenarios. Deviation in actuarial talent supply or outer island morbidity data availability would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Health Insurance
Germany Health Insurance Market
Health Insurance
UAE Health and Medical Insurance Market
Health Insurance
US Healthcare Discount Plan Market
Health Insurance
Healthcare Reimbursement Market
Health Insurance
United States Health and Medical Insurance Market
Health Insurance
Healthcare Insurance Market
Health Insurance
North America Group Health Insurance Market
Health Insurance
US Group Health Insurance Market
Health Insurance
Health Insurance Market
Health Insurance
Healthcare Payer Services Market
Health Insurance
Healthcare Payer Solution Market
Health Insurance
UAE Health Insurance Market
Health Insurance
UAE Health Insurance Third Party Administrators (TPA) Market