
 US Group Health Insurance Market | 2026-2036
US Group Health Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
US Group Health Insurance Market Insights
Cloud-native claims processing is tilting operational economics toward platforms with real-time adjudication capabilities. UnitedHealth Group leverages its Optum analytics layer to sustain medical loss ratio advantages across self-funded accounts. Elevance Health anchors regional dominance through Blue Cross Blue Shield network density in the Southeast and Midwest. CVS Health competes on integrated pharmacy-benefit leverage, controlling formulary costs that determine employer renewal rates.
US group health insurance constitutes employer-sponsored medical coverage pooling risk across employee populations, typically administered through fully insured or self-funded arrangements with annual deductibles, coinsurance tiers, and negotiated provider networks. PPO plans retain structural dominance due to employer preference for broad network flexibility, though high-deductible payment structures are capturing enrollment growth as firms shift cost exposure to workers. HMO segments command tighter margins but attract public-sector and unionized employers seeking predictable per-member-per-month expenditures.
ERISA preemption shapes interstate plan administration, while state insurance commissioners regulate fully insured products, creating a dual compliance architecture that elevates administrative complexity. The No Surprises Act, enforced through HHS and DOL coordination, mandates arbitration for out-of-network billing disputes, directly pressuring payment structure design. CMS innovation center pilots for employer direct contracting will test whether stakeholders can bypass traditional carrier intermediaries without sacrificing network adequacy guarantees.
Market Dynamics
Employer cost-shifting to workers through high-deductible health plans is compressing traditional PPO economics while accelerating demand for price transparency tools and alternative funding vehicles.
Growth Catalysts
- IRA Prescription Drug Provisions:Medicare price negotiation benchmarks are cascading into commercial formularies, reducing employer pharmacy spend and expanding coverage generosity for specialty medications.
- Texas Manufacturing Expansion:Petrochemical and semiconductor facility construction is adding insured lives faster than national enrollment baselines, concentrating new premium volume in Gulf Coast metropolitan areas.
- Cloud-Native Claims Engines:Real-time adjudication platforms are cutting administrative expense ratios and enabling self-funded employers to assume risk previously ceded to carriers.
Market Restraints
- Hospital Consolidation:System-level pricing power in concentrated metropolitan markets is offsetting payer negotiation leverage and preserving elevated unit costs.
- Specialty Drug Inflation:GLP-1 therapies and cell-and-gene treatments are expanding per-member-per-month drug spend at rates exceeding general medical trend.
- ERISA Preemption Complexity:The dual federal-state regulatory architecture elevates compliance costs for multi-state employers and discourages plan standardization.
Strategic Opportunities
- Direct Primary Care Integration:Employer-sponsored DPC memberships are reducing emergency department utilization and enabling capitation-like predictability outside traditional HMO structures.
- Florida Small-Group Underpenetration:Service-sector employers with 50-100 lives represent a coverage gap where level-funded products can displace fully insured arrangements.
- No Surprises Act Arbitration:The federal independent dispute resolution process is creating transparency datasets that enable reference-based pricing strategies for self-funded plans.
Industry Challenges
- Actuarial Talent Scarcity:Pricing and reserving functions face recruitment gaps as experienced professionals retire and predictive modeling demands expand.
- Legacy Core System Modernization:Policy administration platforms built on 1990s architectures require costly replacement to support real-time member engagement and regulatory reporting.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Group Health Insurance Market |
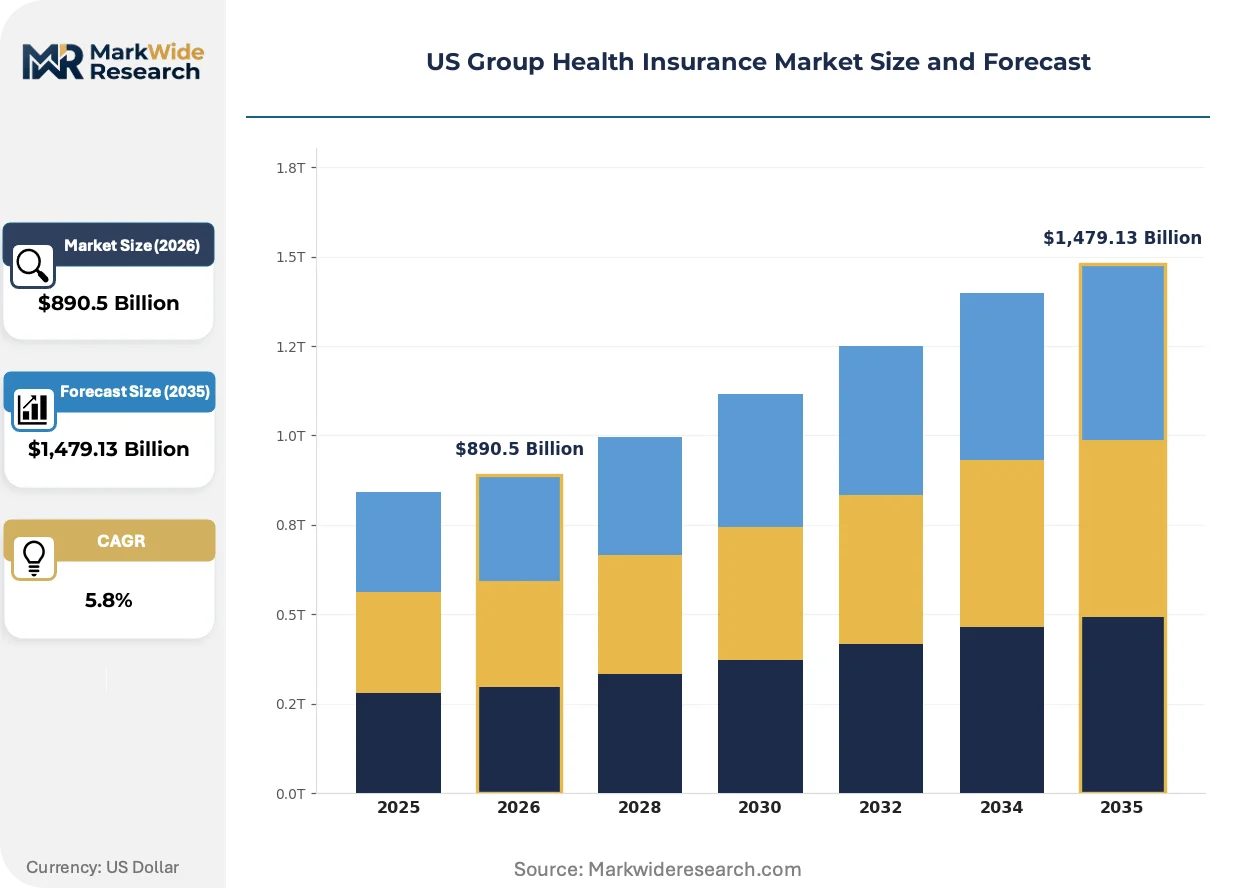
| Market Size in 2026 | $890.5 Billion |
| Market Size in 2035 | $1,479.13 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Plan Type: HMO, PPO, EPO, POS Coverage Level: Individual, Family, Employee Plus One, Group Premium Range: Low, Medium, High, Ultra-High Payment Structure: Traditional, High Deductible, Copay, Coinsurance |
| Companies Covered | UnitedHealth Group, Elevance Health, CVS Health, Kaiser Permanente, Centene Corporation, Humana, Health Care Service Corporation, Cigna Healthcare, Molina Healthcare, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Group Health Insurance Market Trends and Innovations
Artificial intelligence is penetrating prior authorization and fraud detection workflows, compressing decision cycles from days to hours while raising new compliance questions under HIPAA and state algorithmic accountability laws.
Machine learning models trained on historical claims patterns are rendering obsolete manual nurse review processes for routine prior authorizations. Large self-funded employers in manufacturing and logistics are deploying these tools aggressively. The compression is eliminating administrative cost layers that previously justified carrier administrative fees.
The No Surprises Act arbitration mandate is forcing carriers to restructure out-of-network payment methodologies and build dispute resolution infrastructure. Self-funded plans face particular exposure as they retain ultimate liability for arbitrated awards. California and Texas employers are experiencing the highest arbitration volumes and are accelerating network adequacy investments.
Hourly workers in distribution and warehousing are demanding portable benefit structures as job mobility rises. Employers are responding with individual coverage HRA designs and defined contribution frameworks that decouple coverage from employment tenure. This shift is most visible in Florida and Georgia logistics corridors where seasonal employment patterns dominate.
US Group Health Insurance Market Segmentation
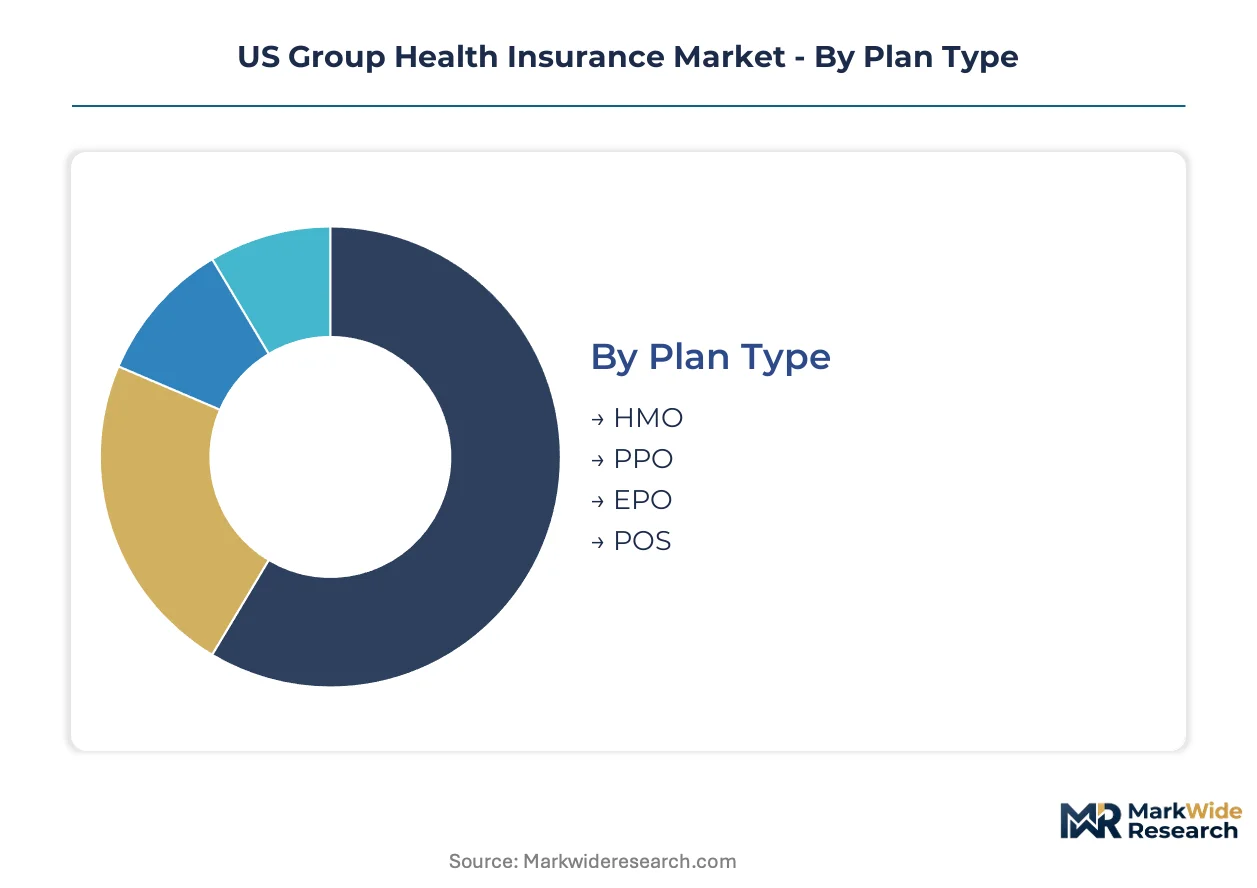
Plan design segmentation determines carrier profitability and employer renewal rates across the US group health insurance market. Each dimension shapes risk pooling, administrative complexity, and member cost exposure in distinct ways.
Plan Type:
Mature network models dominate employer procurement while emerging configurations test new cost-control architectures.
- PPO:Preferred provider organization plans maintain broad network access with tiered cost-sharing for out-of-network utilization. Manufacturing and logistics employers in Texas and Florida favor PPO flexibility for hourly workforces with unpredictable care-seeking patterns.
- HMO:Health maintenance organization structures require primary care gatekeeping and restrict coverage to contracted provider panels. Public-sector employers in California and unionized workforces across the Midwest select HMOs for predictable per-member-per-month expenditures.
- EPO:Exclusive provider organization plans blend HMO-like network restrictions with PPO-style member cost-sharing, omitting out-of-network coverage entirely except for emergencies.
- POS:Point-of-service designs layer HMO gatekeeping onto PPO network breadth, requiring referrals for specialist access while preserving out-of-network options at elevated member cost.
PPO handles the majority of throughput; EPO is expanding most quickly on share as employers seek middle-ground flexibility without out-of-network liability.
Coverage Level:
Enrollment unit size drives pricing granularity and risk stratification across employer-sponsored pools.
- Individual:Single-employee coverage represents the baseline unit for premium rating and claims experience analysis. Technology and professional services firms in California concentrate individual enrollment growth as remote work fragments household benefit coordination.
- Family:Employee-plus-dependent coverage carries the highest per-unit premium and drives employer contribution strategy. Family enrollment dominates in suburban Texas and Florida markets where dual-income households prioritize comprehensive pediatric and maternity benefits.
- Employee Plus One:Two-person coverage units attract empty-nest demographics and dual-income couples without children, offering mid-tier pricing between individual and family tiers.
- Group:Collective enrollment structures aggregate small employer lives for experience rating and administrative efficiency, common among 50-100 life employers in Georgia and North Carolina logistics corridors.
Family coverage generates the premium volume base; Individual is climbing the fastest as gig-economy and remote-work arrangements proliferate.
Premium Range:
Cost tier positioning aligns with employer industry, workforce tenure, and competitive labor market pressures.
- Medium:Mid-market premium tiers balance network breadth with manageable employer contribution burdens. Mid-sized professional services employers in Illinois and Ohio anchor procurement in this band.
- High:Elevated premium tiers fund low-deductible designs and rich pharmacy formularies. Financial services and biotechnology employers in Massachusetts and New Jersey concentrate here to support recruitment.
- Low:Entry-premium tiers feature narrow networks and substantial member cost-sharing. Retail and hospitality employers in Florida and Arizona leverage low tiers for part-time and seasonal workforces.
- Ultra-High:Top-tier premiums support concierge access, out-of-network flexibility, and minimal member cost exposure. Executive carve-outs and professional partnerships in New York and California dominate this segment.
Medium premium tiers carry the enrollment weight; Ultra-High is gaining share fastest as specialty drug coverage and direct primary care integration expand.
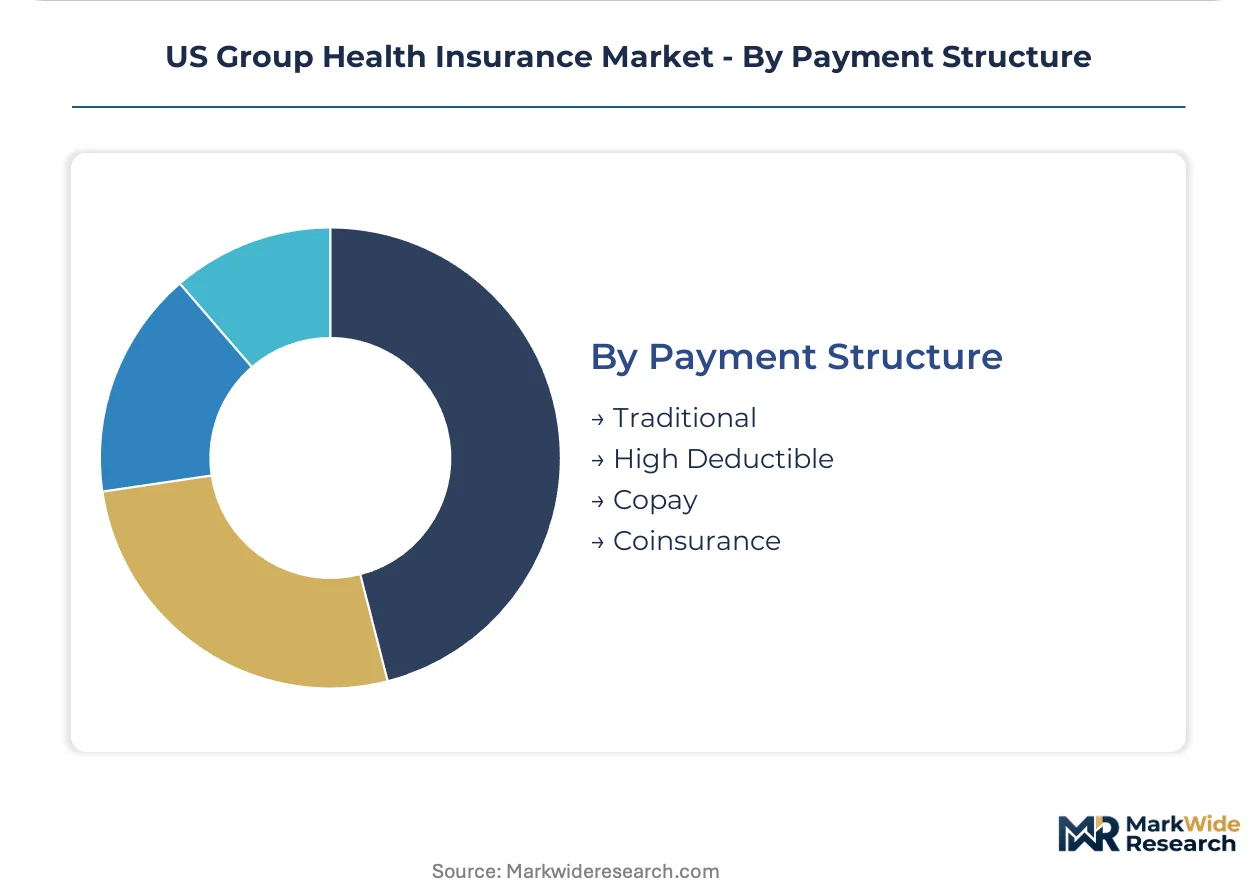
Payment Structure:
Member cost exposure design determines utilization patterns and carrier medical loss ratio outcomes.
- High Deductible:HDHP designs pair tax-advantaged health savings account eligibility with substantial upfront member cost exposure. Large self-funded employers in manufacturing and distribution sectors accelerate HDHP adoption to shift cost consciousness to workers.
- Traditional:Conventional low-deductible designs with fixed copayments for routine services retain preference among unionized employers and public-sector plans seeking predictable member cost experience.
- Copay:Fixed-dollar point-of-service payments for physician visits and prescriptions simplify member cost exposure but reduce price sensitivity for marginal utilization decisions.
- Coinsurance:Percentage-based cost-sharing after deductible satisfaction exposes members to price variation and steers utilization toward lower-cost providers within tiered networks.
Traditional structures still process the most claims volume; High Deductible shows the steepest expansion trajectory as employer cost-shifting accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Large employers in manufacturing, logistics, and technology sectors concentrate premium volume in specific metropolitan corridors where labor competition drives benefit expansion. State regulatory variation and local hospital market concentration shape plan design economics across sub-regional markets.
Texas
Petrochemical and semiconductor facility construction in Houston, Austin, and Dallas-Fort Worth is accelerating employer-sponsored enrollment growth beyond national benchmarks. The Texas Department of Insurance regulates fully insured products while ERISA preemption governs self-funded arrangements prevalent among energy sector employers. Gulf Coast metropolitan areas concentrate new premium volume as manufacturing employers expand coverage for hourly workforces.
California
Technology and professional services firms in Silicon Valley and Los Angeles are fragmenting household benefit coordination through remote work arrangements, driving individual coverage tier expansion. The California Department of Managed Health Care enforces stringent network adequacy standards that elevate carrier compliance costs. San Francisco Bay Area employers anchor high-premium tier procurement to support recruitment in competitive labor markets.
Florida
Service-sector employers with 50-100 lives represent a coverage gap where level-funded products are displacing fully insured arrangements, particularly in Miami, Tampa, and Orlando logistics corridors. The Florida Office of Insurance Regulation oversees fully insured markets while seasonal employment patterns drive demand for portable benefit structures. Southeast Florida metropolitan areas concentrate small-group underpenetration where defined contribution frameworks are gaining traction.
Illinois
Mid-sized professional services employers in Chicago and suburban markets anchor procurement in mid-market premium tiers balancing network breadth with contribution burdens. The Illinois Department of Insurance regulates state-mandated benefit requirements that shape plan design for multi-state employers. Chicago metropolitan area employers are accelerating high-deductible health plan adoption to shift cost consciousness to workers.
Massachusetts
Financial services and biotechnology employers concentrate in Boston and Cambridge, driving demand for elevated premium tiers funding low-deductible designs and rich pharmacy formularies. The Massachusetts Health Connector and state insurance regulations create a dual compliance architecture for employers offering coverage. Greater Boston's concentration of knowledge-economy employers sustains ultra-high premium tier growth as specialty drug coverage expands.
US Group Health Insurance Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a consolidated market structure where national carriers dominate premium volume and regional Blue Cross Blue Shield plans anchor local network density. The vendor base concentrates among integrated health systems, diversified managed care organizations, and pharmacy-benefit managers extending into insurance. Two strategic archetypes predominate: vertically integrated platforms combining medical and pharmacy benefits, and regional specialists leveraging provider network exclusivity. Competitive moves center on cloud-native claims infrastructure investment and direct primary care network expansion.
Within the integrated platform tier, UnitedHealth Group and CVS Health represent archetypal combinations of medical benefit administration with pharmacy and analytics capabilities. Elevance Health occupies a position exemplifying regional Blue Cross Blue Shield network density strategies in the Southeast and Midwest. These three entities anchor the competitive structure through differentiated leverage over medical loss ratio economics and employer renewal rate determination.
| Leading Market Players |
|---|
| UnitedHealth Group |
| Elevance Health |
| CVS Health |
| Kaiser Permanente |
| Centene Corporation |
| Humana |
| Health Care Service Corporation |
| Cigna Healthcare |
| Molina Healthcare |
| Others |
Pricing and Supply Chain Analysis
The I-35 logistics corridor stretching from Laredo through Dallas-Fort Worth shapes cost dynamics for employer-sponsored health plan administration, concentrating third-party administrator capacity in Texas metropolitan hubs while downstream price differentiation reflects network density investments in Gulf Coast manufacturing zones.
Pricing Analysis
Cost-plus contracts with medical trend indexation anchor pricing between self-funded employers and administrative services only carriers. Three-tier pricing structure across premium, standard, and economy levels reflects network breadth, pharmacy formulary generosity, and member cost-sharing exposure. Cost compression in standard tiers intensifies because cloud-native claims platforms are eliminating administrative fee justifications. Small-group employers in Florida and Georgia exhibit highest price sensitivity; large self-funded manufacturers in Texas demonstrate lowest sensitivity due to risk retention capacity.
Supply Chain Analysis
Contract-manufacturing concentration for health plan administration rests with Cognizant, Conduent, and EXL Service for claims processing infrastructure. Geographic supply concentration centers on India for back-office adjudication, the Philippines for member services, and domestic U.S. locations for regulatory compliance functions. Raw material dependencies include cloud compute capacity from AWS and Azure, proprietary analytics software licenses, and licensed clinical reviewer labor pools. Single-source vulnerability in cloud infrastructure poses structural risk. Distribution runs through broker-consultant intermediaries who control employer procurement decisions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in level-funded products for mid-size employers, as remote work arrangements and gig-economy expansion create coverage gaps outside traditional fully insured structures.
For Market Incumbents: Harden network adequacy guarantees in Texas and Florida metropolitan corridors against reference-based pricing entrants. Consolidate direct primary care partnerships to reduce emergency department leakage. Acquire cloud-native claims platforms to defend administrative fee revenue from self-funded employer insourcing. For New Entrants and Emerging Players: Establish a beachhead in Florida small-group level-funded products for 50-100 life employers currently trapped in fully insured arrangements. Target Georgia logistics corridors with portable benefit designs for seasonal hourly workforces. Deploy defined contribution HRA frameworks as the primary go-to-market angle. For Investors and Strategic Acquirers: Carve-out targets emerge from regional Blue Cross Blue Shield plans seeking to monetize administrative services only capabilities. Long-term viability favors platforms with integrated pharmacy benefit leverage and real-time adjudication infrastructure. Monitor arbitration volume under the No Surprises Act as the inflection signal for network adequacy investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Claims Migration | Real-time adjudication platforms cut administrative expense ratios for self-funded employers. |
| Direct Primary Care Network Expansion | Employer-sponsored DPC memberships reduce emergency department utilization in manufacturing corridors. |
| Pharmacy Benefit Integration | Formulary cost control determines renewal rates for large self-funded accounts. |
| Level-Funded Product Development | Mid-size employers in Florida and Georgia seek alternatives to fully insured arrangements. |
| No Surprises Act Compliance Infrastructure | Arbitration process mandates new payment methodology investments from carriers. |
Research Methodology
A spread of perspectives from benefits consultants, employer HR executives, carrier product managers, and TPA operations directors converged on the working assumptions underlying this analysis. Primary interviews with these stakeholders combined with secondary validation against CMS Medicare data, state insurance commissioner filings, GPO contracts, and hospital procurement databases. Bottom-up enrollment modeling and top-down premium volume estimates were triangulated to constrain forecast variance.
Demand-supply balance framing anchored the projection framework across the analysis window. Segmentation dimensions modeled include plan type, coverage level, premium tier, payment structure, and employer industry vertical. CAGRs were derived from enrollment trend extrapolation and per-member-per-month pricing trajectory analysis. Forecast inputs incorporated medical loss ratio regulatory floors and cloud-native platform adoption curves.
Stress conditions across medical trend volatility, regulatory enforcement intensity, and cloud infrastructure cost inflation were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about employer mandate stability and IRA prescription drug provision implementation. Quarterly review of arbitration volume trends and level-funded product penetration rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Health Insurance
UAE Health Insurance Third Party Administrators (TPA) Market
Health Insurance
Indonesia Health and Medical Insurance Market
Health Insurance
UAE Health Insurance Market
Health Insurance
Germany Health Insurance Market
Health Insurance
North America Group Health Insurance Market
Health Insurance
Healthcare Payer Services Market
Health Insurance
Healthcare Insurance Market
Health Insurance
Healthcare Reimbursement Market
Health Insurance
UAE Health and Medical Insurance Market
Health Insurance
United States Health and Medical Insurance Market
Health Insurance
Health Insurance Market
Health Insurance
US Healthcare Discount Plan Market
Health Insurance
Healthcare Payer Solution Market