
 Healthcare Reimbursement Market | 2026-2036
Healthcare Reimbursement Market Size, Share, and Industry Trends Forecast 2026-2036
Healthcare Reimbursement Market Intelligence
India's national expansion of digital health infrastructure and insurance coverage is reshaping the landscape for payment processing. UnitedHealth Group leverages its vast data analytics capabilities to manage costs under new payment models. Cigna Healthcare specializes in managing complex employer-sponsored plans across multiple geographies. Allianz operates a significant private insurance portfolio in Europe, navigating diverse national reimbursement policies.
Healthcare reimbursement refers to the financial process where providers receive payment from payers like insurance companies for services rendered to patients. This system relies on standardized coding and claim adjudication to determine compensation amounts. Pay-for-performance and bundled payment models are gaining traction over traditional fee-for-service structures. While inpatient care represents a mature value segment, telehealth services are seeing the most rapid expansion in reimbursement coverage.
Regulations like the US Health Insurance Portability and Accountability Act (HIPAA) and Europe's GDPR dictate strict data privacy standards for claims processing. Government bodies, including the Centers for Medicare & Medicaid Services in the United States, set benchmarks for payment rates and model adoption. Payers and providers must now decide how to invest in technology that ensures compliance while adapting to new payment structures.
Market Dynamics
The fundamental transition from fee-for-service reimbursement to value-based care, specifically pay-for-performance and bundled payment models, is the central force reconfiguring financial relationships between healthcare providers and payers across developed and emerging economies.
Growth Catalysts
- Telehealth Expansion:The rapid integration of telehealth services into standard care delivery creates new revenue streams and necessitates the development of specific reimbursement codes and policies, accelerating market growth.
- National Health Initiatives:Government-led expansions of digital health infrastructure and insurance coverage, such as in India, increase the volume of claims processed and demand for efficient management systems.
- Demographic Shifts:Aging populations in countries like Germany and Japan increase utilization of inpatient and chronic care services, driving payer focus on cost-containment through advanced reimbursement models.
Market Restraints
- Regulatory Fragmentation:Diverse and often conflicting national reimbursement regulations, particularly within Europe, create significant compliance burdens and increase operational costs for multi-country payers.
- High Implementation Costs:The substantial capital investment required for providers to adopt sophisticated IT systems for reimbursement management and data analytics acts as a significant barrier to entry. *
- Interoperability Deficits:A lack of standardization between disparate electronic health record and billing platforms hinders seamless data exchange, leading to claim denials and payment delays.
Strategic Opportunities
- AI in Fraud Detection:The application of artificial intelligence and machine learning algorithms presents a major opportunity to automate the detection of fraudulent claims, reducing financial losses for payers.
- Emerging Market Penetration:Expanding private and public insurance schemes in developing nations offer significant growth potential for vendors of claims processing software and services.
- Value-Based Care Consulting:A growing need exists for specialized advisory services that guide healthcare providers through the complex transition from fee-for-service to pay-for-performance models.
Industry Challenges
- Data Security Compliance:Adhering to stringent data privacy regulations like the US HIPAA and Europe's GDPR during claims processing poses a constant operational challenge, with severe penalties for non-compliance.
- Specialized Talent Scarcity:A shortage of professionals skilled in both medical coding and advanced data analytics complicates the effective management of new, complex payment models.
- Legacy System Integration:Integrating modern reimbursement platforms with outdated hospital IT infrastructure is a complex and resource-intensive challenge that can delay technology adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Healthcare Reimbursement Market |
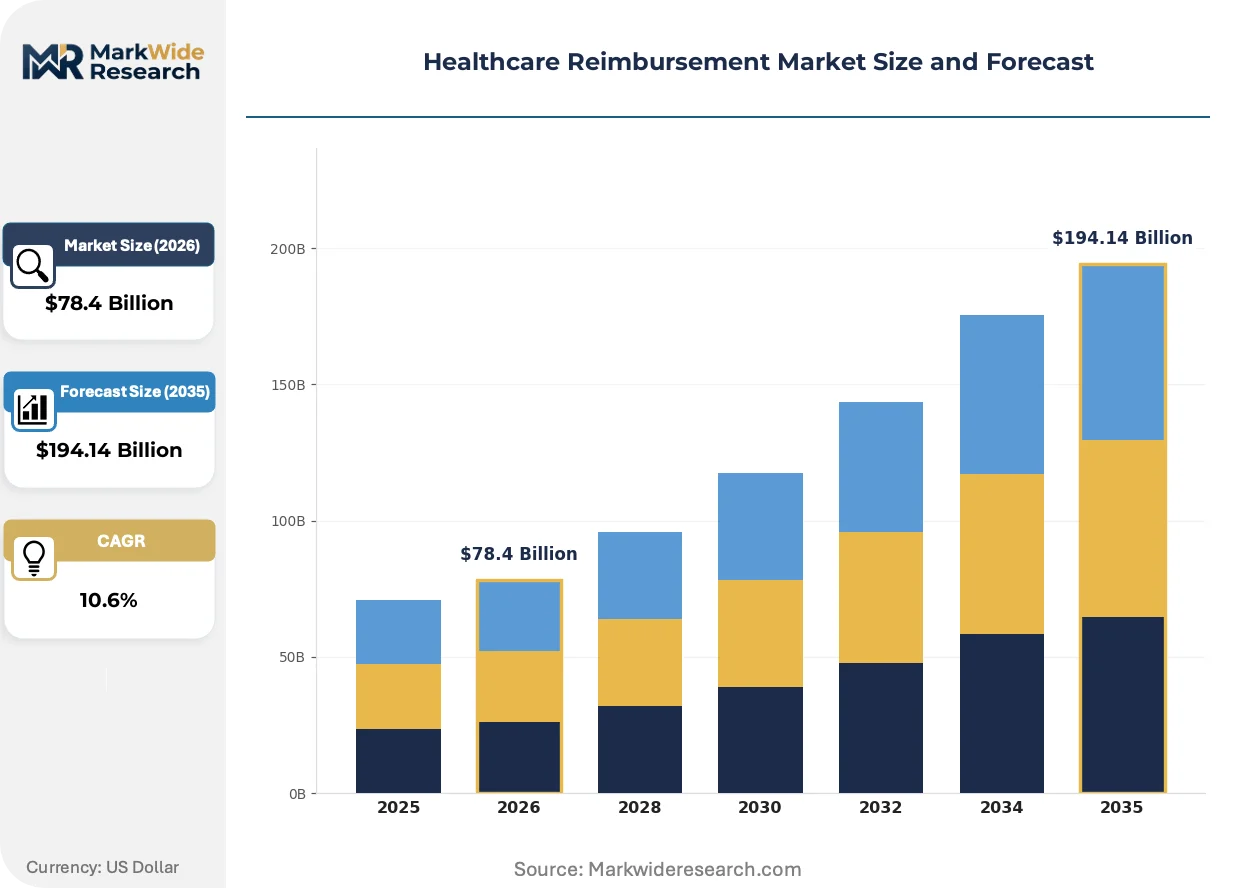
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $194.14 Billion |
| CAGR (2026 – 2036) | 10.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Reimbursement Model: Fee-for-Service, Pay-for-Performance, Capitation, Bundled Payment, Accountable Care Service Type: Inpatient Care, Outpatient Care, Diagnostic Services, Preventive Care, Telehealth Provider Type: Hospitals, Ambulatory Surgical Centers, Primary Care Clinics, Specialty Clinics, Rehabilitation Facilities Payment Source: Private Insurance, Medicare, Medicaid, Self-Pay, Employer-Sponsored Plans |
| Companies Covered | UnitedHealth Group, Blue Cross Blue Shield Association, CVS Health, Cigna Healthcare, Aetna, Allianz, Aviva, WellCare Health Plans, Humana, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Healthcare Reimbursement Market Strategic Shifts & Innovations
The convergence of advanced data analytics and evolving payment structures is compelling both payers and providers to reassess their technology stacks. This shift prioritizes systems that support cost management under value-based care arrangements and ensure regulatory compliance.
Artificial intelligence-powered claims adjudication software automates the verification of medical claims against complex payer rules and contracts. Large insurance carriers and hospital networks are the primary adopters, seeking to improve accuracy and efficiency. This technology is digitizing the entire claims management workflow, significantly reducing manual review cycles and payment turnaround times.
Regulatory bodies like the US Centers for Medicare & Medicaid Services (CMS) continue to champion alternative payment models, including bundled payments for specific medical episodes. This policy shifts financial risk to providers, rewarding them for cost-effective, high-quality care across a patient's entire treatment journey. Orthopedic and cardiac service lines are most affected, requiring investment in integrated care coordination platforms.
A notable behavioral shift involves large employers moving away from traditional, fully-insured health plans. They are increasingly adopting self-funded insurance models that provide greater transparency and control over healthcare expenditures. This trend is most pronounced in the United States, where corporations use third-party administrators to analyze claims data and manage costs.
Healthcare Reimbursement Market Segmentation
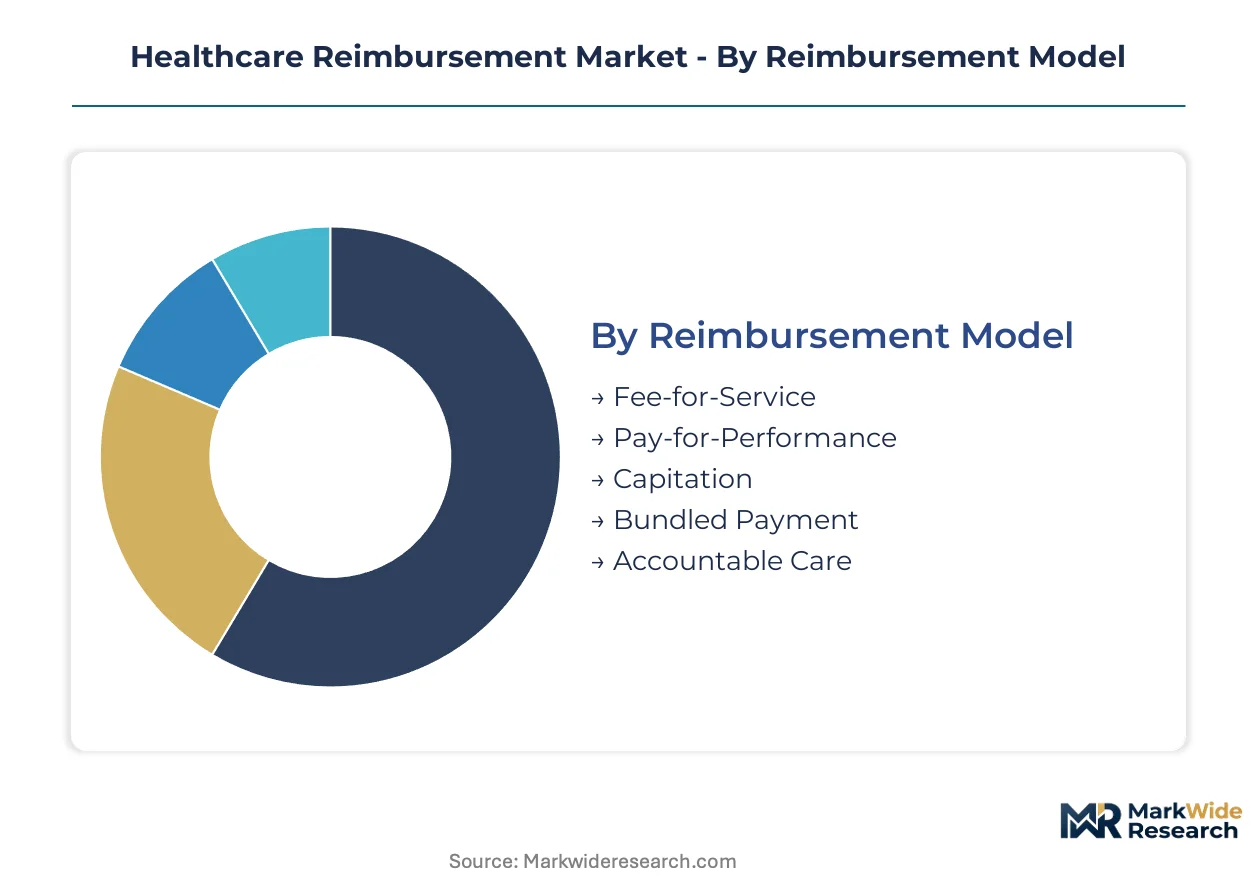
The Healthcare Reimbursement Market structures around distinct payment mechanisms and service delivery models, reflecting the complex financial relationships between providers and payers. Understanding these segments is crucial for stakeholders to identify growth areas and adapt to evolving regulatory and technological landscapes. This market analysis delineates the various components that define reimbursement streams and operational focus.
Reimbursement Model:
The intensity of after-sales service and ongoing patient engagement directly influences the viability and design of different reimbursement models within healthcare.
- Pay-for-Performance:This model links provider compensation to quality metrics and patient outcomes, incentivizing efficient, high-value care. Demand concentrates in developed economies like the United States as government bodies, such as CMS, champion value-based care initiatives.
- Bundled Payment:Providers receive a single, fixed payment for all services related to a specific medical episode or condition, promoting coordinated care and cost control. Orthopedic and cardiac service lines in North America are primary adopters, driven by policies that shift financial risk to providers.
- Fee-for-Service:Providers receive payment for each individual service rendered, such as an office visit or a specific medical procedure.
- Capitation:A fixed payment is made to a provider per patient for a defined period, regardless of the services provided.
- Accountable Care:Groups of providers manage the health of a defined patient population, aiming to improve health outcomes and reduce costs.
By volume, Fee-for-Service leads. By growth pace, Pay-for-Performance is ahead.
Service Type:
The application of different healthcare services dictates varying reimbursement complexities and technological requirements.
- Telehealth:Remote delivery of healthcare services, including virtual consultations and remote monitoring, has seen rapid expansion in reimbursement coverage. This segment's growth is accelerating due to digital health infrastructure expansion and increased patient access in regions like India.
- Inpatient Care:Services provided during an overnight stay in a hospital or other medical facility, typically for acute conditions or complex procedures. This represents a mature value segment, with aging populations in countries like Germany driving consistent utilization.
- Outpatient Care:Medical services received without an overnight stay, such as doctor's office visits, diagnostic tests, and minor surgeries.
- Diagnostic Services:Procedures and tests used to identify diseases or conditions, including imaging, laboratory tests, and pathology services.
- Preventive Care:Services focused on maintaining health and preventing illness, such as vaccinations, screenings, and wellness exams.
The segment driving the most significant shifts in care delivery and reimbursement innovation is Telehealth.
Provider Type:
The volume of services delivered by various healthcare provider types influences the scale and specialization of reimbursement management systems.
- Hospitals:Large medical institutions offering a comprehensive range of inpatient and outpatient services, including emergency care, surgeries, and specialized treatments. Hospitals generate the largest volume of claims, necessitating robust IT systems for compliance with regulations like HIPAA.
- Ambulatory Surgical Centers:Facilities where surgical procedures that do not require an overnight hospital stay are performed, often focusing on specific specialties. These centers are gaining prominence due to their cost-effectiveness and efficiency in developed economies.
- Primary Care Clinics:Facilities providing initial and ongoing healthcare services, focusing on general health and preventive care.
- Specialty Clinics:Healthcare centers dedicated to specific medical fields, such as cardiology, oncology, or orthopedics.
- Rehabilitation Facilities:Institutions providing therapeutic services to help patients recover from injury, illness, or surgery.
Hospitals maintain the largest market share in terms of processed claims, while Ambulatory Surgical Centers demonstrate notable expansion.
Payment Source:
The customer type initiating payment significantly impacts billing processes, regulatory adherence, and claim adjudication protocols.
- Private Insurance:Coverage provided by commercial insurance companies to individuals or groups, often through employer-sponsored plans or direct purchase. Allianz operates a significant private insurance portfolio in Europe, navigating diverse national reimbursement policies.
- Employer-Sponsored Plans:Health insurance benefits provided by employers to their employees, increasingly moving towards self-funded models for greater cost control. This trend is pronounced in the United States, where corporations utilize third-party administrators for claims data analysis.
- Medicare:A federal health insurance program in the United States primarily for individuals aged 65 or older, and younger people with certain disabilities.
- Medicaid:A joint federal and state program in the United States that provides health coverage to low-income individuals and families.
- Self-Pay:Patients directly pay for their medical services without involvement from an insurance company or government program.
Government bodies like the Centers for Medicare & Medicaid Services set benchmarks for payment rates, influencing the entire market.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's established national health programs, including its robust social health insurance system, underpin its significant role in the healthcare reimbursement market. This infrastructure drives demand for advanced reimbursement management solutions and influences policy adoption across Europe. The country's focus on value-based care models further shapes regional dynamics.
United States
The United States market sees high demand for complex reimbursement management due to its fragmented payer landscape. Regulations like HIPAA dictate strict data privacy standards for all claims processing. Major technology hubs such as Silicon Valley and Boston are centers for health tech innovation, driving software development for payers.
Germany
Germany's aging population drives consistent utilization of inpatient and chronic care services, increasing reimbursement complexity. The country's national health insurance system integrates diverse private and public schemes. Berlin and Munich serve as key innovation hubs for health IT, developing solutions for navigating national reimbursement policies.
India
India's expansion of digital health infrastructure and insurance coverage rapidly reshapes its payment processing landscape. Government initiatives, including the PLI scheme for medical devices, boost local healthcare manufacturing. Bangalore and Hyderabad are emerging as significant centers for health tech startups, focusing on efficient claims management.
Japan
Japan's rapidly aging demographic intensifies the focus on cost-containment through advanced reimbursement models for chronic diseases. The Ministry of Health, Labour and Welfare (MHLW) continuously refines payment schedules to balance access and affordability. Tokyo and Osaka remain central to healthcare innovation, with companies developing AI-powered claims adjudication systems.
United Kingdom
The United Kingdom's National Health Service (NHS) drives significant demand for efficiency in claims and payment processing. The NHS Long Term Plan emphasizes digital transformation and value-based care. London's vibrant tech ecosystem supports numerous health informatics firms, specializing in optimizing public sector healthcare finances.
Healthcare Reimbursement Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream providing core technologies. The market exhibits a tiered structure, with large insurance carriers and health systems dominating the payer and provider sides respectively. Several strategic archetypes emerge, including integrated health services providers and specialized reimbursement technology vendors. Dominant competitive moves include strategic partnerships to enhance service offerings and M&A activity to consolidate market share.
Within the integrated payer-provider archetype, UnitedHealth Group and Cigna Healthcare exemplify large, diversified entities leveraging vast data analytics capabilities to manage costs under new payment models. Allianz, a Europe-based financial services giant, anchors the private insurance portfolio segment, navigating diverse national reimbursement policies across multiple geographies. These organizations consistently invest in technology to ensure compliance while adapting to evolving payment structures.
| Leading Market Players |
|---|
| UnitedHealth Group |
| Blue Cross Blue Shield Association |
| CVS Health |
| Cigna Healthcare |
| Aetna |
| Allianz |
| Aviva |
| WellCare Health Plans |
| Humana |
| Others |
Cost & Logistics Intelligence
Specialized health IT vendors in developed economies, particularly the United States, concentrate the upstream technology supply, directly influencing margin pools for sophisticated claims processing and reimbursement management systems. This concentration shapes the pricing power for compliance-driven software solutions.
Pricing Analysis
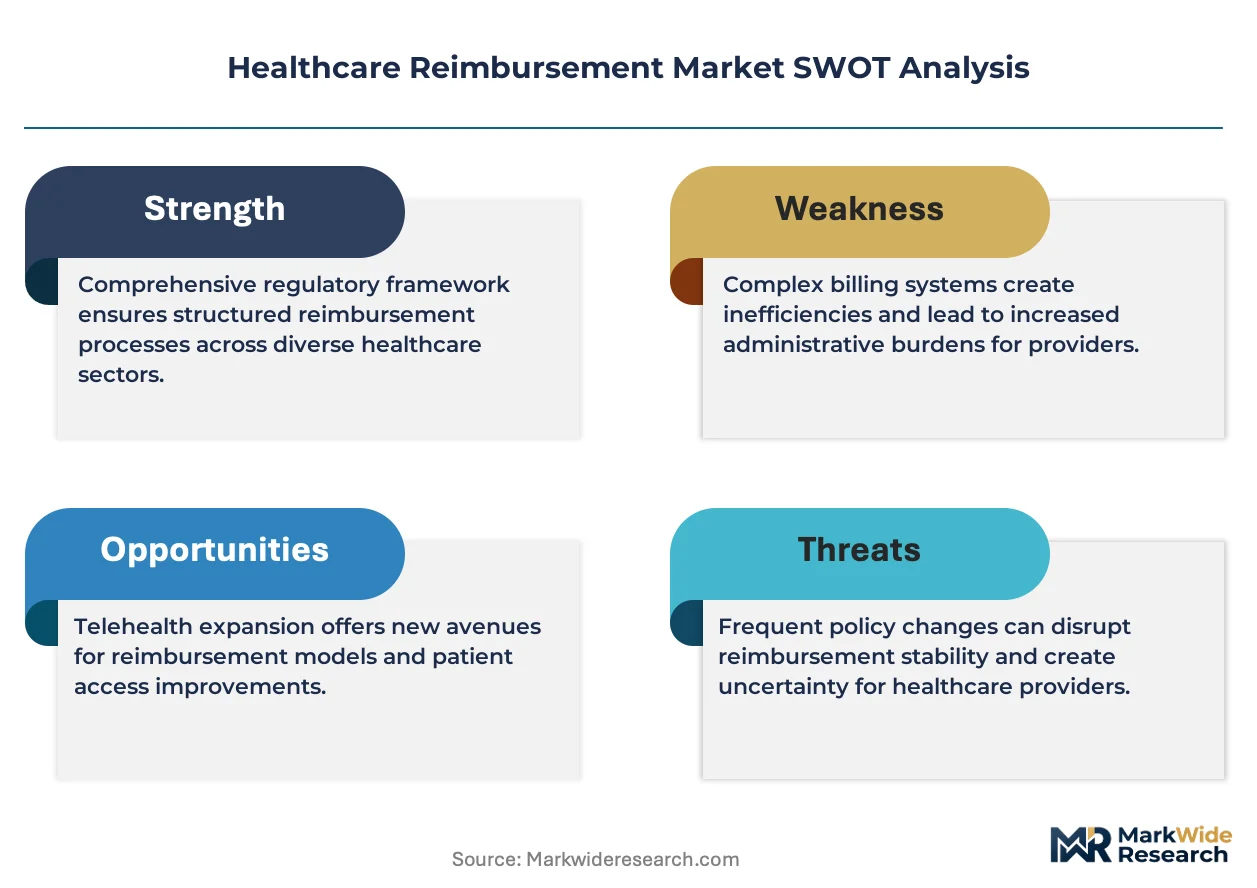
HIPAA and GDPR dictate the pricing tier structure for healthcare reimbursement software, emphasizing compliance-driven features. The dominant pricing model for advanced reimbursement management systems is SaaS-tiered, often with additional project-based fees for implementation and customization. Price differentiation stems from the level of integration required with existing IT infrastructure and the depth of data analytics capabilities offered. Pricing softness reflects increasing competition among technology vendors, with smaller primary care clinics exhibiting the highest price sensitivity compared to large hospital networks.
Supply Chain Analysis
Specialized talent scarcity in medical coding and data analytics dominates the supply chain risk for advanced reimbursement management solutions. The development and support for these systems draw from concentrated talent pools in the United States, India, and Germany. Key dependencies include cloud infrastructure services and highly skilled software engineers. Distribution runs through direct sales channels to large insurance carriers and hospital networks, complemented by partnerships with health IT integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Navigating the complex healthcare reimbursement market requires specialized expertise, particularly in advanced data analytics and regulatory compliance. This market is fundamentally shaped by a scarcity of professionals skilled in both medical coding and sophisticated payment model management.
For Market Incumbents: Insulate core revenue streams by deepening strategic partnerships with AI-powered claims adjudication software providers, especially against the threat of new specialized tech entrants. Consolidate market share through targeted acquisitions of smaller firms excelling in value-based care consulting or interoperability solutions. Investment in advanced data security certifications like ISO 27001 can reinforce trust and compliance, a critical lever in this highly regulated environment.
For New Entrants and Emerging Players: Untapped potential within emerging markets like India, driven by national digital health infrastructure expansion, represents a penetrable entry point for claims processing software. Specialized niches such as behavioral health telehealth reimbursement in fragmented US state markets also offer white-space opportunities. Offering modular, cloud-native platforms for small to mid-sized provider groups transitioning to bundled payment models provides a strong go-to-market angle.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed health tech firms specializing in revenue cycle management or value-based care consulting. The long-term viability of this market is secured by increasing regulatory complexity and the essential need for efficient payment processing. Acquisition targets should focus on mid-sized reimbursement technology vendors possessing robust intellectual property in AI-powered claims adjudication or seamless EHR integration. Watch for increasing M&A activity among large insurance carriers acquiring niche software providers as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop AI-powered Claims Adjudication Software | Automates verification processes, significantly reducing manual review cycles and payment turnaround times for payers. |
| Expand Telehealth Reimbursement Coverage | Capitalizes on the rapid integration of remote services into standard care delivery, creating new revenue streams for providers. |
| Offer Value-Based Care Consulting Services | Guides healthcare providers through the complex transition from fee-for-service to pay-for-performance models, ensuring compliance. |
| Invest in Interoperability Solutions | Addresses data exchange deficits between disparate electronic health record and billing platforms, minimizing claim denials. |
| Penetrate Emerging Healthcare Markets | Leverages expanding private and public insurance schemes in developing nations, offering significant growth potential for vendors. |
Research Approach
The analysis maps reimbursement models, service types, provider types, and payment sources, each validated through primary interviews with payer executives and health tech developers. This involved extensive secondary research across CMS reports, national health ministry publications, and insurance carrier annual reports. The research incorporated both bottom-up market sizing from specific segments and top-down validation against overall industry expenditure.
Forecasts were developed by holding macroeconomic conditions fixed while varying regulatory policy shifts and technological adoption rates across the analysis window. The quantitative model segmented the market by reimbursement model, service type, provider type, payment source, and regional regulatory landscapes. Compound annual growth rates were derived from historical data trends and projected impacts of evolving payment reforms. Key forecast inputs included telehealth service utilization and the pace of value-based care model mandates.
Practitioners should monitor unforeseen regulatory changes, particularly in data privacy and payment model mandates, for early signals that could revise market forecasts. The projections reflect a defined set of assumptions regarding market evolution and technological integration. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Health Insurance
US Healthcare Discount Plan Market
Health Insurance
Healthcare Payer Services Market
Health Insurance
Healthcare Payer Solution Market
Health Insurance
US Group Health Insurance Market
Health Insurance
Germany Health Insurance Market
Health Insurance
Health Insurance Market
Health Insurance
Indonesia Health and Medical Insurance Market
Health Insurance
North America Group Health Insurance Market
Health Insurance
UAE Health Insurance Market
Health Insurance
UAE Health and Medical Insurance Market
Health Insurance
Healthcare Insurance Market
Health Insurance
UAE Health Insurance Third Party Administrators (TPA) Market
Health Insurance
United States Health and Medical Insurance Market