
 UAE Health and Medical Insurance Market | 2026-2036
UAE Health and Medical Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
UAE Health and Medical Insurance Market Analytics
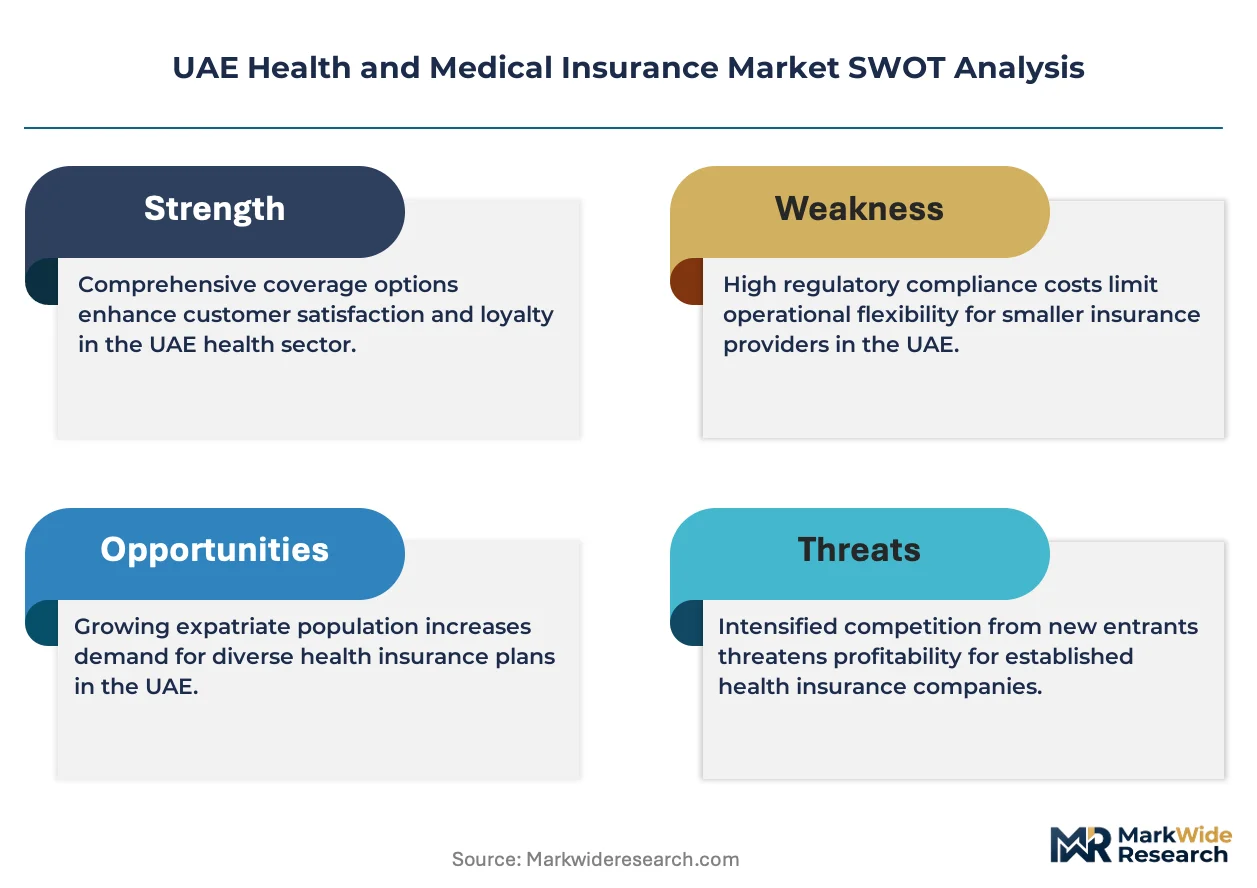
Dubai's mandatory health insurance framework is reshaping how insurers structure coverage and compete for resident populations. Daman anchors the northern emirates with its government-linked position and extensive provider networks. GIG Gulf leverages digital underwriting platforms to accelerate policy issuance for mid-size employers. Cigna competes through specialized expatriate plans that extend into cross-border telemedicine services.
Health and medical insurance constitutes a risk-pooling financial instrument where policyholders pay premiums in exchange for coverage of specified medical treatments, hospitalization, and preventive services, typically governed by annual policy terms, deductible thresholds, and network-based provider agreements. Its primary commercial purpose lies in transferring individual healthcare cost volatility to institutional risk bearers while ensuring regulated access to care. Corporate group plans dominate premium volume by capturing mandatory employer obligations across the UAE's private workforce, while managed care payment models are gaining structural share as insurers seek to cap exposure through pre-negotiated provider rates and utilization controls. Family plans occupy a distinct margin pool by combining dependent coverage with maternity benefits that command higher per-policy yields.
The Dubai Health Authority and Department of Health Abu Dhabi enforce divergent mandatory coverage standards that shape product design, minimum benefit thresholds, and pricing floors across their respective jurisdictions. MOHAP's federal oversight adds a coordination layer for inter-emirate portability and national provider registry standards. Stakeholders must monitor how Takaful-compliant structures evolve against conventional insurance frameworks as Shariah-aligned products claim greater share of policyholder preference.
Market Dynamics
Mandatory employer obligations under Dubai Health Authority and Department of Health Abu Dhabi regulations are compressing policy issuance timelines and forcing insurers to restructure underwriting workflows around real-time eligibility verification systems.
Growth Catalysts
- Expatriate Workforce Expansion:Construction, hospitality, and logistics sectors in Dubai and Abu Dhabi are absorbing labor from South Asia and Southeast Asia, creating concentrated demand pools for group medical coverage.
- MOHAP Federal Coordination:Inter-emirate portability standards are reducing administrative friction for policyholders relocating between Dubai, Abu Dhabi, and the northern emirates, expanding addressable premium pools.
- Telemedicine Infrastructure:Cross-border virtual consultation platforms are extending policy value propositions beyond UAE territorial limits, differentiating expatriate-focused products.
Market Restraints
- Medical Cost Inflation:Hospital service tariffs in Dubai's private provider market are rising faster than premium adjustment schedules, compressing loss ratios for conventional indemnity products.
- Provider Network Concentration:Three hospital groups control majority bed capacity in Abu Dhabi, limiting insurer negotiating leverage on reimbursement rates.
- Takaful Capital Requirements:Shariah-compliant structures demand segregated policyholder funds and modified reserve calculations, raising operational complexity versus conventional frameworks.
Strategic Opportunities
- Northern Emirates Penetration:Ras Al Khaimah, Fujairah, and Umm Al Quwain exhibit lower insurance density than Dubai and Abu Dhabi, offering white-space growth for digitally-enabled distributors.
- Chronic Disease Management Bundles:Diabetes and cardiovascular prevention programs aligned with DHA preventive care mandates are creating differentiated product tiers above minimum benefit floors.
- API-Enabled Embedded Distribution:Payroll and HR platforms are becoming policy origination channels, bypassing traditional broker intermediation for SME employer segments.
Industry Challenges
- Actuarial Talent Scarcity:Shortage of professionals experienced in both Takaful mathematics and Gulf-specific morbidity patterns is delaying product development cycles.
- Legacy Core System Integration:Incumbent insurers face friction connecting 1990s-era policy administration platforms to real-time provider eligibility verification networks mandated by health authorities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UAE Health and Medical Insurance Market |
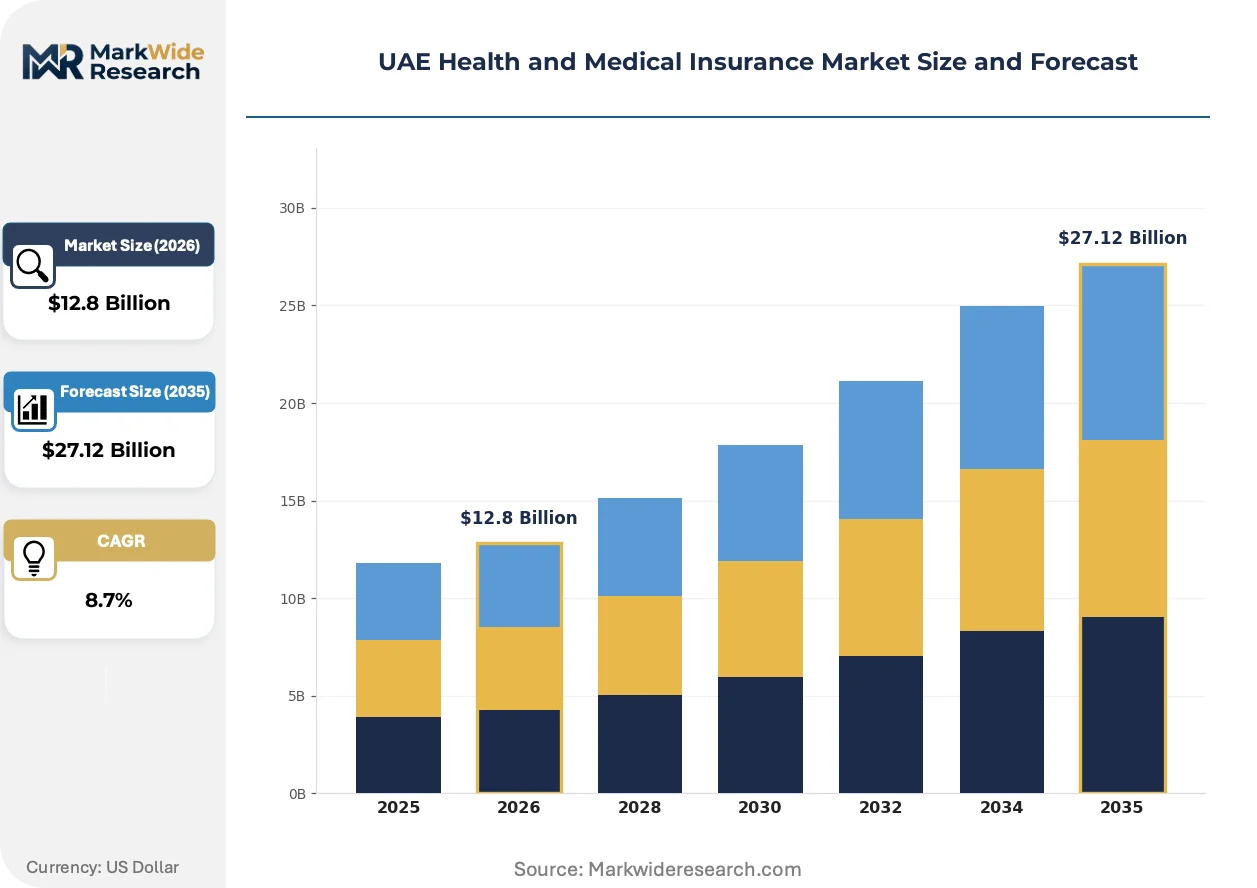
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $27.12 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Individual Plans, Family Plans, Group Plans, Corporate Plans Coverage Type: Inpatient Coverage, Outpatient Coverage, Dental Coverage, Maternity Coverage Payment Model: Fee-for-Service, Capitation, Pay-as-You-Go, Managed Care Policyholder Type: Employed Individuals, Self-Employed Individuals, Dependents, Retirees |
| Companies Covered | GIG Gulf, MetLife, Daman, Orient Insurance, Salama Takaful, Sukoon Insurance, Cigna, Medgulf, Abu Dhabi National Insurance Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UAE Health and Medical Insurance Market Evolving Landscape
Digital underwriting platforms and AI-powered claims adjudication are compressing operational cost structures while regulatory mandates around data interoperability are forcing technology stack modernization across the sector.
Blockchain-enabled smart contracts are digitizing policy issuance and claims settlement workflows for group employers. Mid-size construction and logistics firms are adopting these platforms to automate dependent eligibility verification. This architecture is digitizing the previously paper-intensive onboarding processes that delayed coverage activation for rotating project workforces.
The Department of Health Abu Dhabi's mandatory health insurance law amendments are tightening minimum benefit thresholds for outpatient mental health services. Insurers must reprice group policies and renegotiate provider contracts to accommodate expanded coverage obligations. SME employers in Abu Dhabi are responding by consolidating broker relationships to access actuarial expertise for compliance restructuring.
Subscription-based primary care attachments are displacing traditional fee-for-service outpatient reimbursement among younger expatriate professionals. Digital health platforms are capturing these policyholders through mobile-first enrollment interfaces. This behavioral shift is most visible in Dubai's technology and financial services employment clusters, where employers compete for talent through wellness-centric benefit differentiation.
UAE Health and Medical Insurance Market Segmentation
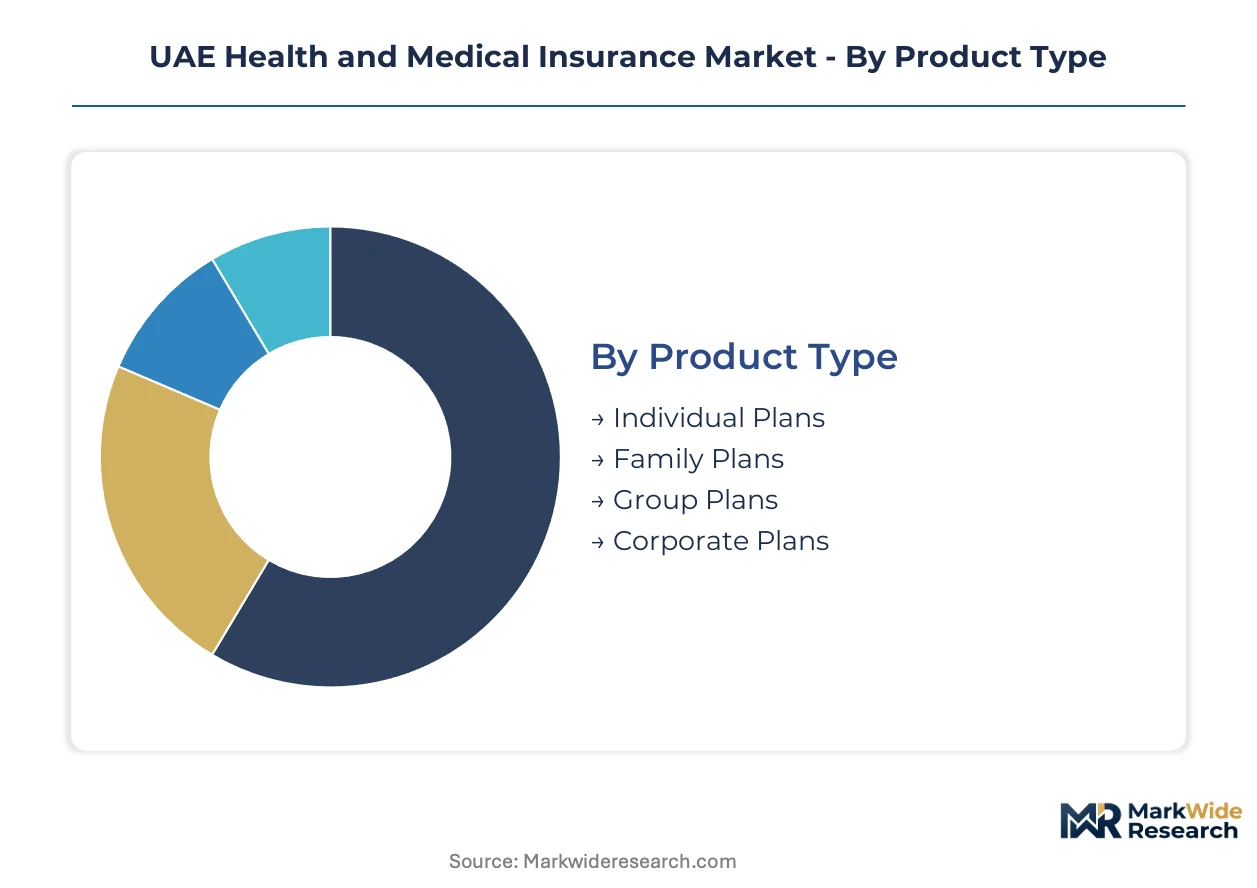
Segmentation in the UAE health insurance market reveals distinct risk pools and margin profiles. Policy lifecycle velocity varies dramatically across product types, with annual group renewals compressing pricing cycles while family plans lock in multi-year relationships.
Product Type:
Group plans turn over fastest with annual employer renewal cycles, while family plans exhibit the slowest velocity with multi-year tenures. Individual plans sit between these extremes with policyholders switching on employment transitions.
- Individual Plans:Single-life coverage structured around portable benefits for professionals changing employers within Dubai and Abu Dhabi's fluid labor markets. Demand concentrates among mid-senior expatriates in financial services and technology sectors where employer portability is valued over group stability.
- Family Plans:Multi-life policies bundling spousal and dependent coverage with maternity benefits commanding premium yields above individual equivalents. Dubai's technology corridor employers leverage these plans for talent retention, with dependent eligibility verification driving administrative complexity.
- Group Plans:Employer-sponsored coverage for SME workforces across construction and logistics verticals.
- Corporate Plans:Large-employer schemes with customized benefit tiers and captive provider networks.
Group plans dominate installed base. Family plans are where expansion concentrates.
Coverage Type:
Cost tier stratification separates essential inpatient from premium outpatient and maternity riders. Minimum benefit mandates from Dubai Health Authority and Department of Health Abu Dhabi establish pricing floors that compress variance at the base tier.
- Inpatient Coverage:Hospitalization benefits covering surgical procedures, emergency admissions, and intensive care stays. Mandatory across all UAE policies, this tier absorbs catastrophic risk transfer and anchors actuarial pricing for employer group schemes in construction and hospitality sectors.
- Outpatient Coverage:Clinic consultations, diagnostic imaging, and specialist referrals outside hospital admission. Abu Dhabi's amended mental health mandates are expanding this tier's cost base, forcing repricing among SME employers consolidating broker relationships.
- Dental Coverage:Preventive and restorative oral health benefits typically ridered to base policies.
- Maternity Coverage:Prenatal, delivery, and postnatal benefits concentrated in family plan structures.
Inpatient coverage dominates installed base. Outpatient coverage is gaining share fastest as preventive care mandates expand.
Payment Model:
Volume concentration in managed care models reflects insurer efforts to cap exposure through pre-negotiated provider rates. Fee-for-service retains share in high-turnover construction workforce segments where provider flexibility outweighs cost control.
- Managed Care:Network-restricted coverage with utilization controls and capitated provider payments. Dubai Health Authority's real-time eligibility verification mandates favor this model's administrative infrastructure, with GIG Gulf and Daman deploying digital platforms to capture mid-size employer volume.
- Fee-for-Service:Indemnity-style reimbursement allowing policyholder choice across uncontracted providers. Rotating project workforces in northern emirates construction sites prefer this flexibility despite premium loadings, with blockchain-enabled verification reducing onboarding friction.
- Capitation:Fixed per-member-per-month payments to provider networks.
- Pay-as-You-Go:Retrospective reimbursement without pre-negotiated rate schedules.
Managed care dominates installed base. Fee-for-service retains niche expansion in project-based employment clusters.
Policyholder Type:
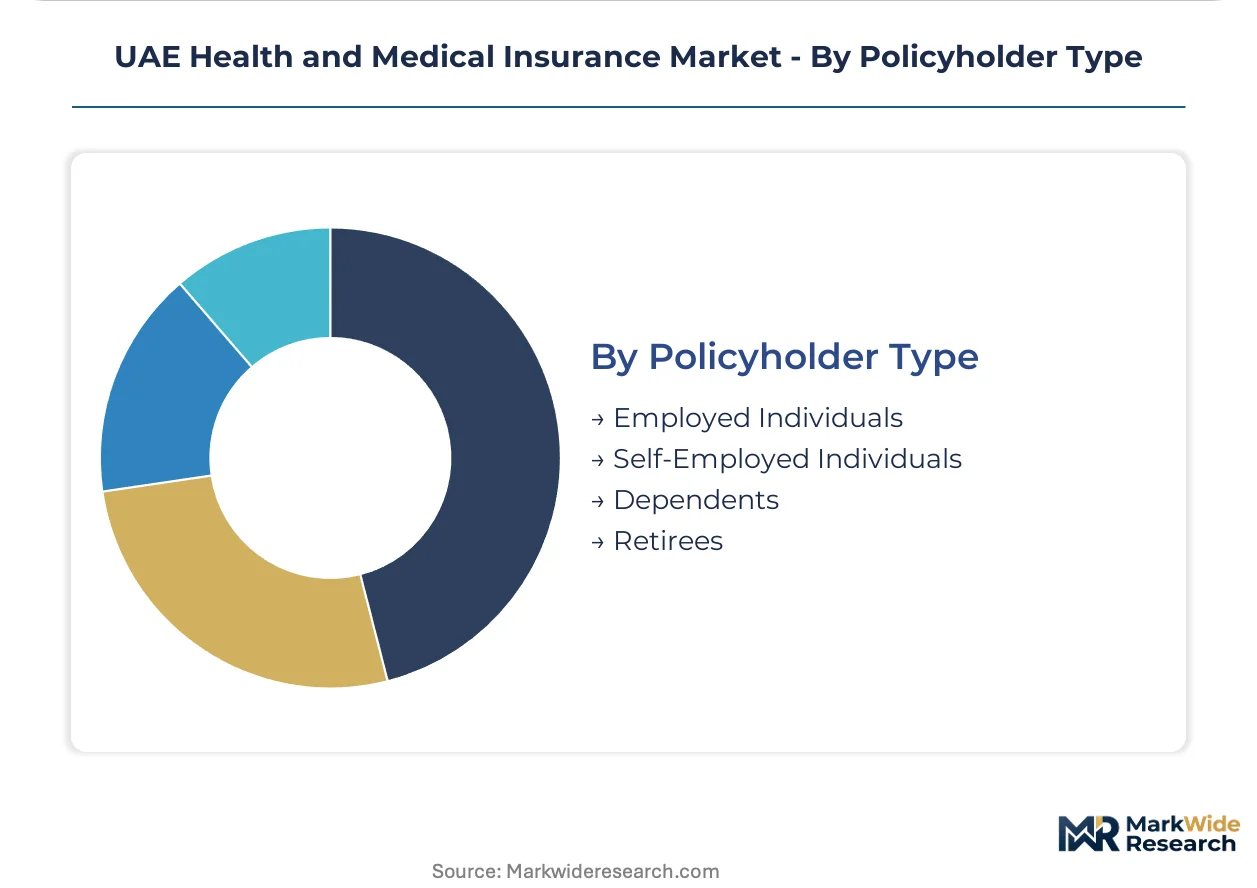
Customer type segmentation maps directly to regulatory obligation flows. Employed individuals trigger mandatory employer coverage, while self-employed and dependent categories expose coverage gaps that Takaful products target.
- Employed Individuals:Private-sector workers covered through employer obligations under Dubai Health Authority and Department of Health Abu Dhabi regulations. Expatriate-dense construction, hospitality, and logistics sectors generate concentrated premium volume with annual renewal cycles.
- Dependents:Spouses and children attached to primary policyholder coverage. Maternity benefits and pediatric care drive per-policy yields higher than individual equivalents, with eligibility verification complexity rising as blockchain platforms automate previously paper-intensive processes.
- Self-Employed Individuals:Freelancers and entrepreneurs purchasing coverage without employer sponsorship.
- Retirees:Post-employment coverage for long-term UAE residents.
Employed individuals dominate installed base. Dependents represent the steepest expansion trajectory as family plan penetration deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Insurer headquarters and provider network density concentrate in Dubai and Abu Dhabi, with northern emirates presenting white-space expansion corridors for digitally-enabled distributors.
Dubai
Construction, hospitality, and logistics sectors absorb South Asian and Southeast Asian labor at scale, generating concentrated demand pools for employer-sponsored group coverage. Dubai Health Authority mandates real-time eligibility verification systems that compress policy issuance timelines. Dubai South and Jebel Ali industrial zones host rotating project workforces where blockchain-enabled onboarding platforms reduce coverage activation delays.
Abu Dhabi
Three hospital groups control majority bed capacity, limiting insurer negotiating leverage on reimbursement rates for conventional indemnity products. Department of Health Abu Dhabi amended minimum benefit thresholds for outpatient mental health services, forcing SME employers to consolidate broker relationships for compliance restructuring. Khalifa Industrial Zone and Musaffah manufacturing corridors anchor corporate plan volume for large employers with captive provider networks.
Sharjah
Mid-size manufacturing and trading enterprises generate steady group policy demand with annual renewal cycles. MOHAP federal coordination enables inter-emirate portability for policyholders relocating from Dubai, expanding addressable premium pools. Sharjah's industrial areas and Port Khalifa logistics clusters serve as secondary distribution nodes for insurers extending reach beyond primary emirates.
Northern Emirates
Ras Al Khaimah, Fujairah, and Umm Al Quwain exhibit lower insurance density than Dubai and Abu Dhabi, creating expansion opportunities for API-enabled embedded distribution through payroll platforms. Takaful-compliant structures claim growing policyholder preference in these markets. RAK Economic Zone and Fujairah's port and mining corridors host project-based employment segments where fee-for-service flexibility outweighs managed care cost controls.
UAE Health and Medical Insurance Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with narrower network configurations. The market structures around government-linked incumbents with extensive provider relationships, digitally-enabled challengers with accelerated underwriting workflows, and international carriers with cross-border service extensions. Strategic archetypes include network aggregators, Takaful operators, and expatriate-focused specialists. Competitive moves center on API-enabled embedded distribution partnerships and chronic disease management bundle differentiation.
Within the government-linked tier, Daman anchors the northern emirates with extensive provider networks. GIG Gulf and Cigna occupy positions among internationally-oriented carriers; GIG Gulf exemplifies digital underwriting platform deployment for mid-size employer segments, while Cigna represents expatriate-focused specialists extending into cross-border telemedicine services.
| Leading Market Players |
|---|
| GIG Gulf |
| MetLife |
| Daman |
| Orient Insurance |
| Salama Takaful |
| Sukoon Insurance |
| Cigna |
| Medgulf |
| Abu Dhabi National Insurance Company |
| Others |
Value Network & Pricing Analysis
Regulatory chokepoints at the Dubai Health Authority and Department of Health Abu Dhabi determine both pricing tier spreads and supply chain shape, with mandatory minimum benefit thresholds compressing variance at the base tier while premium outpatient riders command wider spreads.
Pricing Analysis
Dubai Health Authority and Department of Health Abu Dhabi regulations dictate the pricing tier structure across the UAE health insurance market. Three-tier pricing separates premium plans with cross-border telemedicine and chronic disease bundles from standard employer-mandated coverage and economy tiers serving basic inpatient obligations. Price differentiation hinges on network breadth and utilization control intensity, with managed care models commanding premium positioning over fee-for-service flexibility. Pricing pressure stems from medical cost inflation outpacing premium adjustment schedules in Dubai's private hospital market. SME employers in construction and logistics exhibit highest price sensitivity, while technology and financial services employers prioritize wellness-centric benefit differentiation over cost minimization.
Supply Chain Analysis
Extended payment terms from hospital groups to insurers are reshaping working capital requirements across the provider network. Healthcare service delivery concentrates in the UAE's private hospital infrastructure, with three Abu Dhabi-based groups controlling majority bed capacity and limiting insurer negotiating leverage. Medical technology and pharmaceutical inputs draw from Germany, the United States, and Switzerland for high-end diagnostic equipment and specialty therapeutics. Single-source vulnerability sits with concentrated hospital group dominance in Abu Dhabi, creating reimbursement rate rigidity. Distribution runs through broker intermediaries for large employers and API-enabled payroll platforms for SME segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mandatory real-time eligibility verification systems represent a technological inflection that is compressing policy issuance timelines and rewarding digitally-enabled underwriting platforms across the UAE health insurance market.
For Market Incumbents: Pre-empt margin erosion in conventional indemnity products by accelerating managed care network densification in Dubai's technology corridor. Invest in chronic disease management bundle certification to capture premium positioning above DHA preventive care mandates. Counter GIG Gulf's digital underwriting advantage through API-enabled embedded distribution partnerships with payroll platforms serving mid-size employers. For New Entrants and Emerging Players: Northern Emirates white-space in Ras Al Khaimah and Fujairah represents the most penetrable entry point, with lower insurance density and Takaful-compliant product preference creating differentiated positioning. Target project-based construction workforces through fee-for-service flexibility and blockchain-enabled eligibility verification that reduces onboarding friction. Pursue go-to-market partnerships with HR software vendors serving SME manufacturing clusters in Sharjah's industrial zones. For Investors and Strategic Acquirers: Abu Dhabi's amended mental health benefit mandates reshape the acquisition landscape by forcing SME employers to consolidate broker relationships and seek actuarial expertise. Long-term viability favors platforms with real-time eligibility infrastructure and Takaful operational capabilities over legacy indemnity specialists. Monitor Dubai Health Authority interoperability mandate timelines as the signal for technology stack modernization urgency.| Strategic Initiative | Industry Significance |
|---|---|
| Chronic Disease Management Bundle Development | Aligns with DHA preventive care mandates to create premium tier differentiation above minimum benefit floors. |
| API-Enabled Embedded Distribution Partnership | Captures SME employer volume through payroll platform integration, bypassing traditional broker intermediation. |
| Takaful Operational Capability Investment | Addresses Shariah-aligned product preference growth in northern emirates and self-employed segments. |
| Real-Time Eligibility Verification Infrastructure | Satisfies Dubai Health Authority mandates while compressing policy issuance timelines for rotating workforces. |
| Cross-Border Telemedicine Platform Extension | Differentiates expatriate-focused products beyond UAE territorial limits for technology and financial services employers. |
Research Methodology
The analysis maps group plans, family plans, individual coverage, and Takaful-compliant structures, each validated through underwriters, actuarial consultants, broker network heads, and health authority compliance officers. Primary interviews with DHA-licensed insurers and DOH Abu Dhabi-registered providers combined with secondary validation from regulatory filings, hospital procurement databases, and GPO contracts. Bottom-up premium volume estimates triangulated against top-down addressable workforce calculations across construction, hospitality, logistics, technology, and financial services verticals.
Assumptions around mandatory employer obligation enforcement and medical cost inflation trajectories were held fixed across scenarios, while Takaful penetration rates and telemedicine adoption curves were varied. The analytical framework segmented by product type, coverage tier, payment model, and policyholder category across the projection horizon. CAGRs derived from policy issuance velocity trends and premium yield trajectories by segment. Forecast inputs incorporated hospital bed capacity expansion timelines and inter-emirate portability utilization patterns.
Macroeconomic conditions sit as an overlay; deviation in expatriate workforce flows, oil-price-correlated government spending, or dirham-dollar peg stability would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement continuity and provider network consolidation pace. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Health Insurance
UAE Health Insurance Market
Health Insurance
Health Insurance Market
Health Insurance
UAE Health Insurance Third Party Administrators (TPA) Market
Health Insurance
US Healthcare Discount Plan Market
Health Insurance
Healthcare Insurance Market
Health Insurance
US Group Health Insurance Market
Health Insurance
Healthcare Payer Services Market
Health Insurance
Indonesia Health and Medical Insurance Market
Health Insurance
United States Health and Medical Insurance Market
Health Insurance
North America Group Health Insurance Market
Health Insurance
Healthcare Payer Solution Market
Health Insurance
Healthcare Reimbursement Market
Health Insurance
Germany Health Insurance Market