
 Health Insurance Market | 2026-2036
Health Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Health Insurance Market Analysis
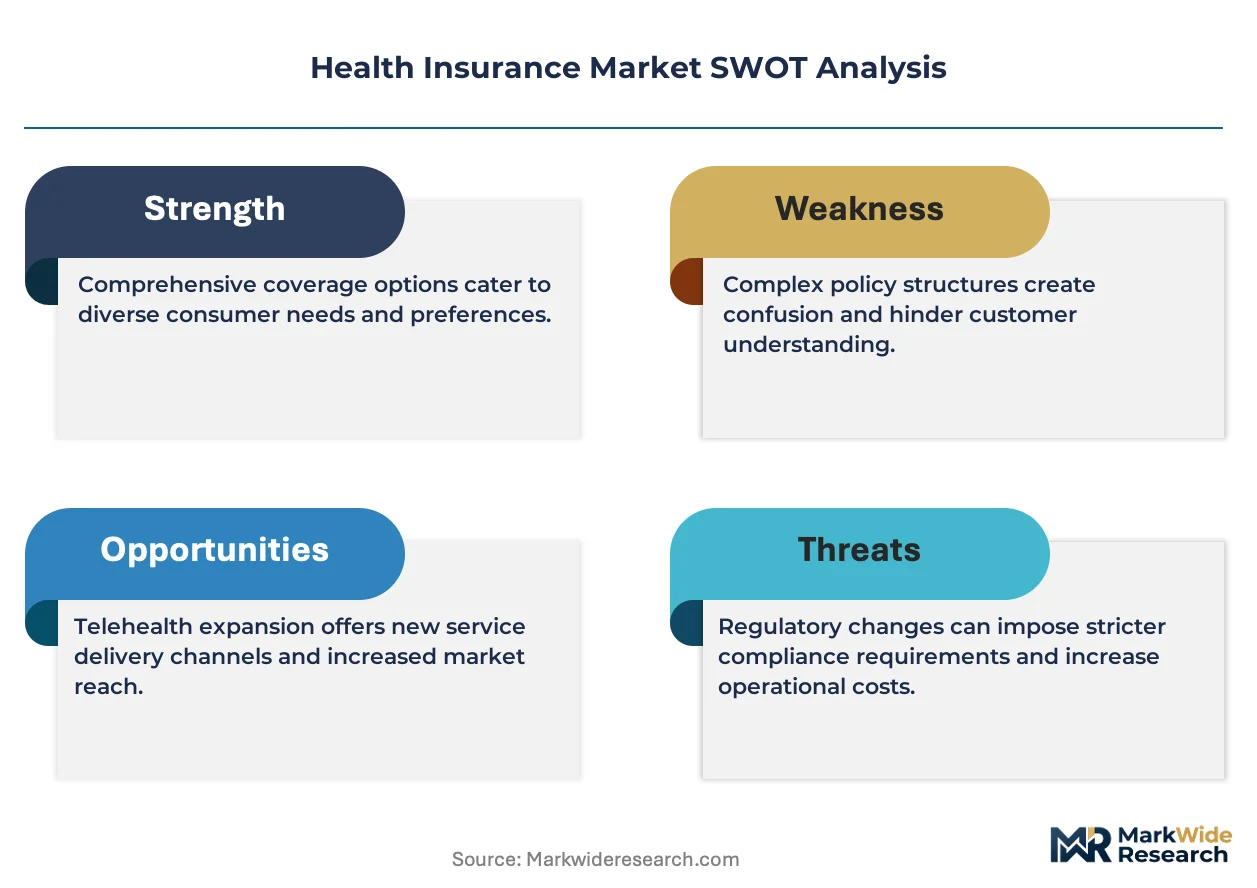
The Affordable Care Act is restructuring the cost-of-entry calculus for regional carriers seeking to compete in state-based exchanges. UnitedHealth Group leverages its Optum care delivery arm to sustain integrated cost advantages across 50 states. Elevance Health anchors its position through Medicaid managed care dominance in the Southeast and Midwest. Kaiser Permanente differentiates via captive provider networks that control utilization patterns in California and Hawaii.
Health insurance constitutes a risk-pooling financial contract that transfers the economic burden of medical expenses from individuals or groups to an underwriter in exchange for premium payments, with actuarial reserves maintained per state solvency requirements and NAIC risk-based capital standards. Its primary commercial purpose is to reduce catastrophic health expenditure exposure while enabling predictable budgeting for employers and households. Group Plans generate the largest premium volume due to employer mandate provisions and tax-advantaged status, while Individual Plans exhibit the fastest policy growth as gig-economy workers exit traditional employment arrangements. Distribution through Online channels is capturing margin pools previously allocated to agent commissions, though Brokers retain structural importance in the small-business segment where plan complexity demands advisory intervention.
The Department of Health and Human Services, state insurance commissioners, and the NAIC collectively determine reserve requirements, network adequacy standards, and rate review protocols that constrain pricing flexibility and product design. CMS innovation center pilot programs reshape demand by conditioning reimbursement on quality metrics rather than fee-for-service volume. Stakeholders must monitor whether Medicare Advantage rate adjustments and state Medicaid expansion waivers alter the relative attractiveness of public versus commercial book composition.
Market Dynamics
Artificial intelligence is automating claims adjudication across the health insurance value chain, compressing administrative overhead while reshaping workforce composition and carrier operating models.
Growth Catalysts
- Employer Mandate Provisions:The Affordable Care Act's minimum benefit requirements are expanding group coverage enrollment among mid-sized enterprises, particularly in professional services and manufacturing sectors.
- Medicaid Expansion Waivers:State-level program expansions in the Southeast and Midwest are accelerating managed care penetration among previously uninsured populations.
- Telehealth Infrastructure:CMS reimbursement parity for virtual care visits is embedding remote delivery into standard benefit design, reducing per-encounter costs for routine consultations.
Market Restraints
- Actuarial Reserve Requirements:NAIC risk-based capital standards and state solvency mandates tie up substantial premium dollars in low-yield instruments, constraining carrier investment flexibility.
- Provider Network Concentration:Hospital system consolidation in metropolitan markets limits payer negotiating leverage, compressing commercial margin pools in California and Texas.
- Legacy Core System Architecture:Mainframe-dependent policy administration platforms impose integration friction with modern data analytics stacks, delaying real-time risk scoring deployment.
Strategic Opportunities
- Medicare Advantage Penetration:The aging demographic cohort in Florida and Arizona presents white space for supplemental benefit packaging beyond traditional fee-for-service coverage.
- Individual Exchange Channel:Gig-economy worker migration from employer-sponsored plans is accelerating direct-to-consumer platform adoption, particularly among technology and creative sector independents.
- Value-Based Care Incentives:CMS innovation center pilot programs conditioning reimbursement on quality metrics rather than service volume are opening capitated arrangement opportunities for integrated delivery systems.
Industry Challenges
- Actuarial Talent Scarcity:Competition for predictive modeling specialists with machine learning expertise is intensifying compensation pressure in pricing and underwriting functions.
- Interoperability Standards:HL7 FHIR implementation timelines vary across state Medicaid programs and commercial exchanges, fragmenting member data portability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Health Insurance Market |
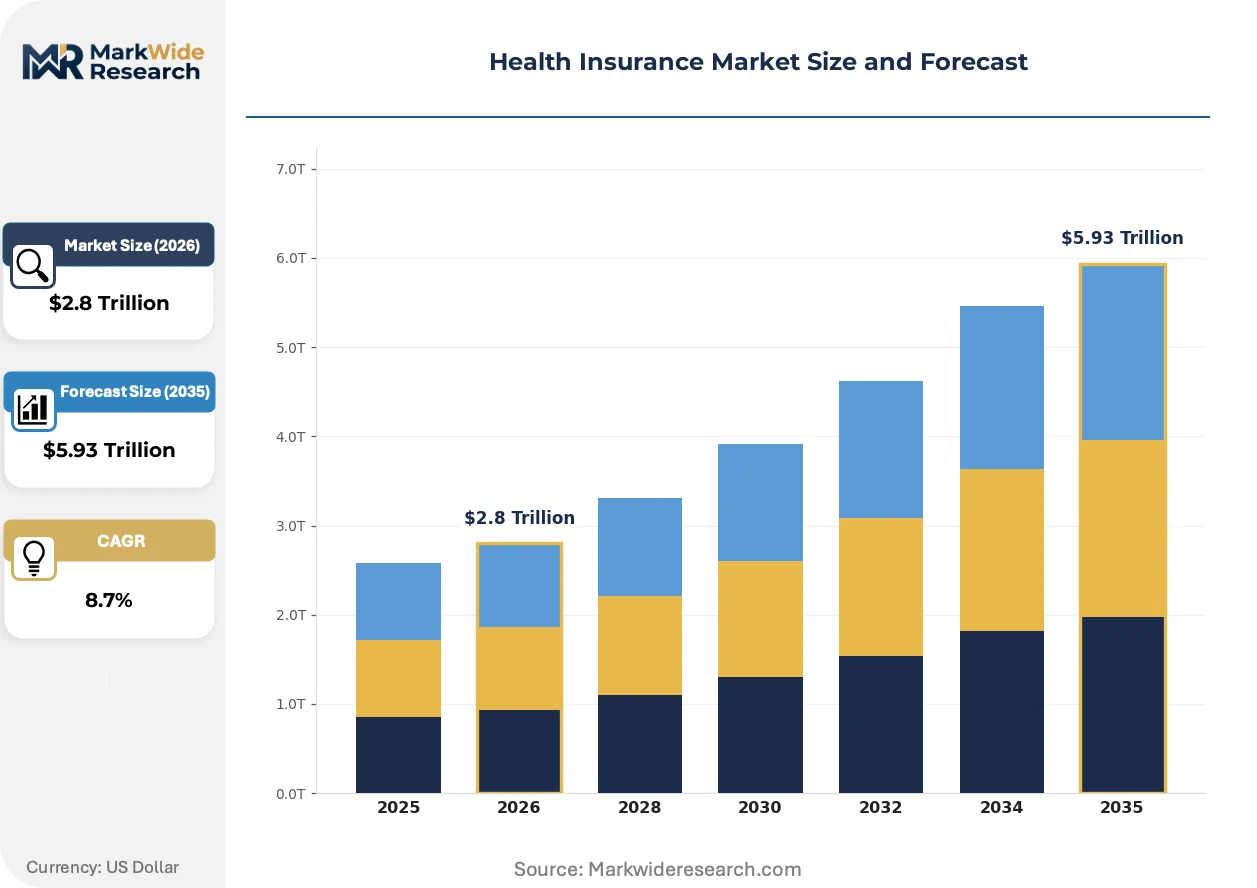
| Market Size in 2026 | $2.8 Trillion |
| Market Size in 2035 | $5.93 Trillion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Individual Plans, Family Plans, Group Plans, Short-Term Insurance Coverage Type: Comprehensive, Basic, Catastrophic, Supplemental Distribution Channel: Online, Brokers, Agents, Direct Sales End User: Individuals, Small Businesses, Corporations, Nonprofits |
| Companies Covered | UnitedHealth Group, Elevance Health, Kaiser Permanente, Centene Corporation, CVS Health, Humana, Health Care Service Corporation, Cigna, Molina Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Health Insurance Market Emerging Trajectories
Machine learning is penetrating core insurance operations from underwriting to fraud detection, while regulatory pressure on pricing transparency and network adequacy is forcing product redesign across state markets.
Natural language processing is automating prior authorization reviews and clinical documentation analysis, reducing manual touchpoints in utilization management. Large national carriers are deploying these tools across commercial and Medicare Advantage books, compressing decision timelines from days to hours. This capability is automating administrative cost structures that previously consumed fifteen to twenty percent of premium dollars.
CMS rate review protocols and state insurance commissioner oversight of network adequacy are tightening product design constraints, particularly in rural service areas where provider supply is limited. Carriers must now document travel time standards and specialty access metrics before plan approval. Small-group segments in sparsely populated counties face the tightest network construction requirements.
Direct enrollment through carrier websites and state-based exchanges is displacing broker-mediated small-group placements, though advisory relationships persist among businesses with complex multi-state footprints. Employers with fifty to two hundred lives are increasingly self-serving plan comparisons through digital tools. This channel migration is most pronounced in Colorado and Nevada, where exchange infrastructure investment has lowered enrollment friction.
Health Insurance Market Segmentation
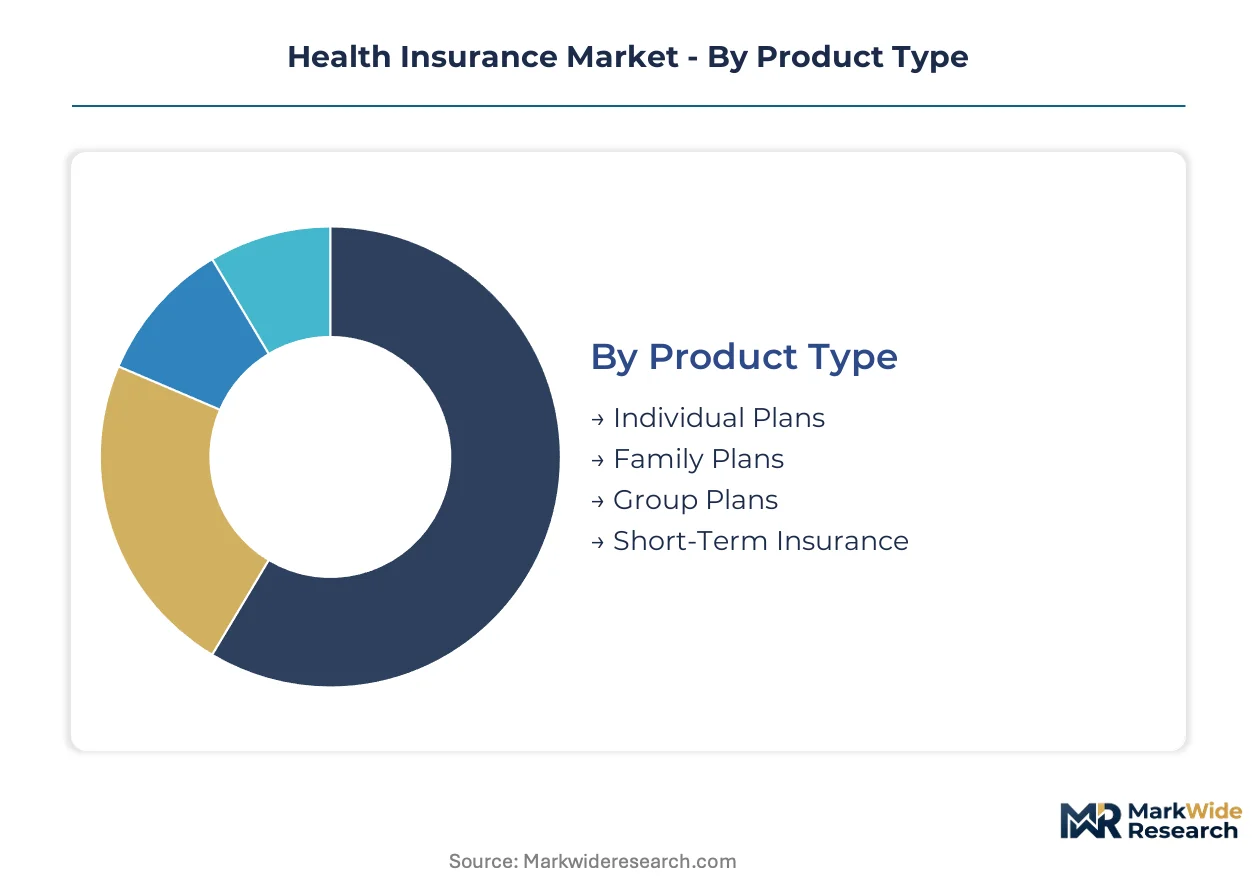
Segmentation in health insurance determines capital allocation, pricing precision, and regulatory compliance pathways. Carriers optimize product portfolios by matching risk pools to distribution economics and employer scale.
Product Type:
Upgrade cycles in employer-sponsored coverage are accelerating as mid-sized enterprises respond to Affordable Care Act threshold adjustments and competitive labor market pressures.
- Individual Plans:Single-policy contracts purchased through exchanges or direct carrier channels, typically bearing higher per-member administrative load. Demand concentrates among gig-economy workers in California and New York as traditional employment relationships fragment.
- Family Plans:Multi-dependent coverage structures with tiered premium calculations based on household composition. Volume placements dominate in suburban markets across Texas and Florida where household size and employer subsidy eligibility intersect favorably.
- Group Plans:Employer-sponsored risk pools leveraging tax-advantaged premium structures and mandate compliance. Faster expansion belongs to professional services and manufacturing sectors navigating ACA minimum benefit requirements.
- Short-Term Insurance:Limited-duration coverage bridging employment gaps or waiting periods, subject to state-level duration caps and benefit limitations.
Volume placements concentrate in Group Plans; the faster expansion belongs to Individual Plans.
Coverage Type:
Cost tier differentiation shapes carrier profitability, with comprehensive products commanding premium pricing while catastrophic offerings serve price-sensitive segments with minimal claims exposure.
- Comprehensive:Full-spectrum coverage spanning preventive, acute, and chronic care with low member cost-sharing. Demand concentrates in employer-sponsored books where recruitment competition drives benefit richness in technology and financial services sectors.
- Basic:Essential health benefits meeting minimum ACA standards with moderate deductibles and copayment structures. Volume placements dominate Medicaid managed care and entry-level exchange tiers across Midwestern states.
- Catastrophic:High-deductible protection against major medical expenses, restricted to enrollees under thirty or hardship exemptions. Faster expansion tracks young adult migration into gig employment in Colorado and Washington.
- Supplemental:Gap coverage for dental, vision, or critical illness layered atop primary medical policies.
Comprehensive coverage captures the largest premium pool; catastrophic products are climbing the fastest among age-restricted eligible populations.
Distribution Channel:
Channel economics are restructuring as commission compression and digital enrollment infrastructure reshape customer acquisition costs across market tiers.
- Online:Direct-to-consumer platforms and state-based exchange portals enabling self-service plan comparison and enrollment. Demand concentrates among technology sector independents and metropolitan millennials in Nevada and Colorado where exchange investment has reduced friction.
- Brokers:Independent advisors serving small-group complexity with multi-state regulatory navigation and plan design consultation. Volume placements persist among fifty-to-two-hundred-life employers with fragmented geographic footprints.
- Agents:Captive or affiliated representatives with exclusive carrier relationships and quota-driven compensation structures.
- Direct Sales:Carrier-employed field forces targeting large-group self-insured accounts with customized administrative service arrangements.
Broker-mediated placements retain structural importance in small-group segments; online channels are gaining share fastest where exchange infrastructure investment has matured.
End User:
Customer scale determines pricing flexibility, with large corporations extracting volume discounts while small businesses absorb administrative cost inefficiencies and risk-rating limitations.
- Corporations:Large employers with self-insured or fully-insured arrangements leveraging thousand-plus life pools for administrative rate concessions. Demand concentrates in Fortune 500 manufacturing and technology headquarters across California, Texas, and Illinois.
- Small Businesses:Firms with fewer than fifty full-time equivalents navigating SHOP exchange options and tax credit eligibility. Faster expansion tracks professional services firm formation in Arizona and North Carolina.
- Individuals:Non-group purchasers through exchanges or direct enrollment without employer subsidy.
- Nonprofits:Mission-driven organizations with constrained compensation budgets seeking value-oriented benefit structures and grant-funded coverage expansions.
Corporate accounts generate the deepest premium volume; small business segments show the steepest expansion trajectory as services sector entrepreneurship accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for health insurance concentrates in the United States, where private payers dominate commercial risk pools and employer-sponsored coverage generates the deepest premium volume. Regional variations in Medicaid expansion, network adequacy standards, and demographic composition reshape competitive positioning across state markets.
United States
Employer mandate provisions under the Affordable Care Act are expanding group coverage enrollment among mid-sized enterprises in professional services and manufacturing sectors. The Department of Health and Human Services and state insurance commissioners jointly determine reserve requirements and rate review protocols that constrain pricing flexibility. UnitedHealth Group leverages its Optum care delivery arm across all 50 states to sustain integrated cost advantages.
Germany
Statutory health insurance funds face enrollment pressure as higher-income earners opt for private coverage, fragmenting risk pools. The Federal Joint Committee and Federal Ministry of Health regulate benefit catalogues and reimbursement rates through the Social Code Book V. Munich and Hamburg host concentration of private health insurers managing supplementary coverage portfolios.
United Kingdom
NHS waiting list pressures are accelerating demand for private medical insurance among employer-sponsored segments and affluent individuals. The Prudential Regulation Authority and Financial Conduct Authority oversee solvency standards and consumer protection frameworks. London anchors the market with concentration of large-group self-insured arrangements in financial services headquarters.
Japan
Aging demographics and medical cost inflation are straining the statutory health insurance system, creating openings for supplemental cancer and nursing care products. The Ministry of Health, Labour and Welfare and the Financial Services Agency coordinate on insurer solvency and product approval. Tokyo and Osaka metropolitan areas concentrate demand for premium-tier private coverage among corporate executives.
India
Rising out-of-pocket health expenditure and government push for universal coverage are accelerating commercial and government-sponsored insurance penetration. The Insurance Regulatory and Development Authority of India mandates minimum capital requirements and product standardization under the Insurance Act. Mumbai and Bangalore concentrate health insurer headquarters and third-party administrator operations serving corporate group policies.
Health Insurance Market Vendor Landscape
United States carriers anchor the premium tier; European mutual specialists hold position in statutory-complementary segments. The market structure consolidates around national-scale integrated delivery systems, regional Medicaid managed care organizations, and pharmacy-benefit-manager-affiliated payers. Three archetypes dominate: vertically integrated care-delivery-insurer hybrids, government-program-focused managed care specialists, and pharmacy-retail-backed benefit administrators. Competitive moves center on Medicare Advantage geographic expansion and value-based care contract restructuring.
Among United States-based national carriers, UnitedHealth Group, Elevance Health, and Kaiser Permanente exemplify the integrated delivery archetype. UnitedHealth Group occupies a position spanning commercial, Medicare Advantage, and Medicaid lines through its Optum care delivery and pharmacy services arms. Elevance Health sits within the government-program specialist tier with concentration in Medicaid managed care across the Southeast and Midwest. Kaiser Permanente represents the captive provider network model with closed-system operations in California and Hawaii.
| Leading Market Players |
|---|
| UnitedHealth Group |
| Elevance Health |
| Kaiser Permanente |
| Centene Corporation |
| CVS Health |
| Humana |
| Health Care Service Corporation |
| Cigna |
| Molina Healthcare |
| Others |
Supply Flow & Price Mechanics
Artificial intelligence deployment in claims adjudication is compressing administrative cost structures while concentrating technology procurement power among carriers with capital reserves for enterprise-scale implementations. This shift simultaneously reshapes pricing flexibility and supplier dependence across the health insurance value chain.
Pricing Analysis
Volume placements concentrate in group-sponsored comprehensive coverage where employer scale extracts administrative rate concessions; catastrophic individual products face steeper margin compression due to adverse selection risk and exchange commission compression. Price differentiation hinges on network breadth and actuarial risk tier classification, with narrow-network HMO structures commanding fifteen to twenty percent discounts against PPO equivalents. Pricing pressure stems from CMS Medicare Advantage rate adjustments and state Medicaid expansion waivers altering public program competitiveness. Small-group employers with fifty to two hundred lives exhibit highest price sensitivity, while Fortune 500 self-insured accounts prioritize network adequacy over premium minimization.
Supply Chain Analysis
Single-source vulnerability sits with cloud infrastructure providers Amazon Web Services, Microsoft Azure, and Google Cloud Platform hosting carrier core systems and member data platforms. Raw material dependencies center on specialized actuarial talent pools, proprietary claims scoring algorithms, and pharmacy benefit manager rebate contracting. Supply chain risk concentrates in regulatory restriction exposure as HIPAA and state privacy laws fragment data portability standards. Distribution runs through broker-mediated small-group placements, direct-to-consumer exchange portals, and carrier-employed field forces targeting large-group administrative service arrangements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over care delivery assets determines cost advantage sustainability. Players are pursuing captive provider network expansion as the decisive downstream lever.
For Market Incumbents: To counter pharmacy benefit manager rebate compression and specialty drug cost inflation, deepen backward integration into primary care delivery through clinic network acquisition or joint venture structures. Prioritize Medicare Advantage geographic white space in Florida and Arizona where demographic tailwinds support supplemental benefit packaging.
For New Entrants and Emerging Players: Begin with direct-to-consumer exchange channel penetration targeting gig-economy independents in Colorado and Nevada where exchange infrastructure investment has reduced enrollment friction. Pursue narrow-network HMO designs with fifteen to twenty percent premium discounts against incumbent PPO offerings.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by national carriers seeking regional Medicaid managed care footprint or pharmacy-benefit-manager-affiliated payers expanding care delivery control. Target Medicaid-centric specialists with Southeast and Midwest state contract concentration. Watch CMS innovation center pilot program expansion as signal for value-based care contract restructuring inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Provider Network Expansion | Kaiser Permanente's California closed-system model demonstrates utilization control advantages through in-house specialist employment. |
| Medicare Advantage Geographic Entry | Humana's Florida and Arizona footprint captures aging demographic migration with supplemental benefit differentiation. |
| Pharmacy Benefit Integration | CVS Health's Caremark-CVS Pharmacy linkage extracts rebate leverage unavailable to standalone carriers. |
| Medicaid Managed Care Contract Concentration | Elevance Health's Southeast state portfolio generates stable premium volume through multi-year procurement awards. |
| Artificial Intelligence Claims Automation | UnitedHealth Group's Optum deployment compresses administrative cost ratios below legacy mainframe-dependent competitors. |
Methodological Framework
SEC 10-K filings, CMS Medicare Advantage enrollment data, and state insurance commissioner rate review filings formed the secondary backbone, cross-referenced with primary interviews involving actuarial directors, health plan product officers, and employer benefits consultants. Bottom-up policy volume estimates triangulated against top-down premium pool calculations derived from NAIC statutory filings and employer-sponsored coverage survey data.
Historical trendline analysis across employer mandate implementation phases and Medicaid expansion waiver cycles established baseline growth patterns. Segmentation modeling incorporated product type, coverage tier, distribution channel, and end-user scale dimensions. CAGRs were derived from regression analysis of premium volume trajectories, calibrated against demographic shift projections and regulatory change scenarios including Medicare Advantage rate adjustment schedules and state exchange infrastructure investment levels.
Medicaid expansion waiver reversals, Medicare Advantage rate cut implementations, and artificial intelligence regulatory intervention are the dominant revision risks to projection assumptions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Health Insurance
United States Health and Medical Insurance Market
Health Insurance
US Healthcare Discount Plan Market
Health Insurance
Healthcare Payer Services Market
Health Insurance
UAE Health Insurance Third Party Administrators (TPA) Market
Health Insurance
Healthcare Insurance Market
Health Insurance
US Group Health Insurance Market
Health Insurance
North America Group Health Insurance Market
Health Insurance
UAE Health and Medical Insurance Market
Health Insurance
Healthcare Payer Solution Market
Health Insurance
Indonesia Health and Medical Insurance Market
Health Insurance
Germany Health Insurance Market
Health Insurance
UAE Health Insurance Market
Health Insurance
Healthcare Reimbursement Market