
 UAE Health Insurance Market | 2026-2036
UAE Health Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
UAE Health Insurance Market Intelligence
Market Context
Telemedicine integration is narrowing the gap between policy distribution and point-of-care delivery across the Emirates. Daman Health leverages its government-linked position to dominate group coverage for public sector employees. GIG Gulf sustains competitive intensity through specialized corporate wellness bundles tailored to multinational workforces. Cigna anchors its presence by controlling direct-billing networks with premium hospital chains in Dubai and Abu Dhabi.
Technical Definition and Structural Segments
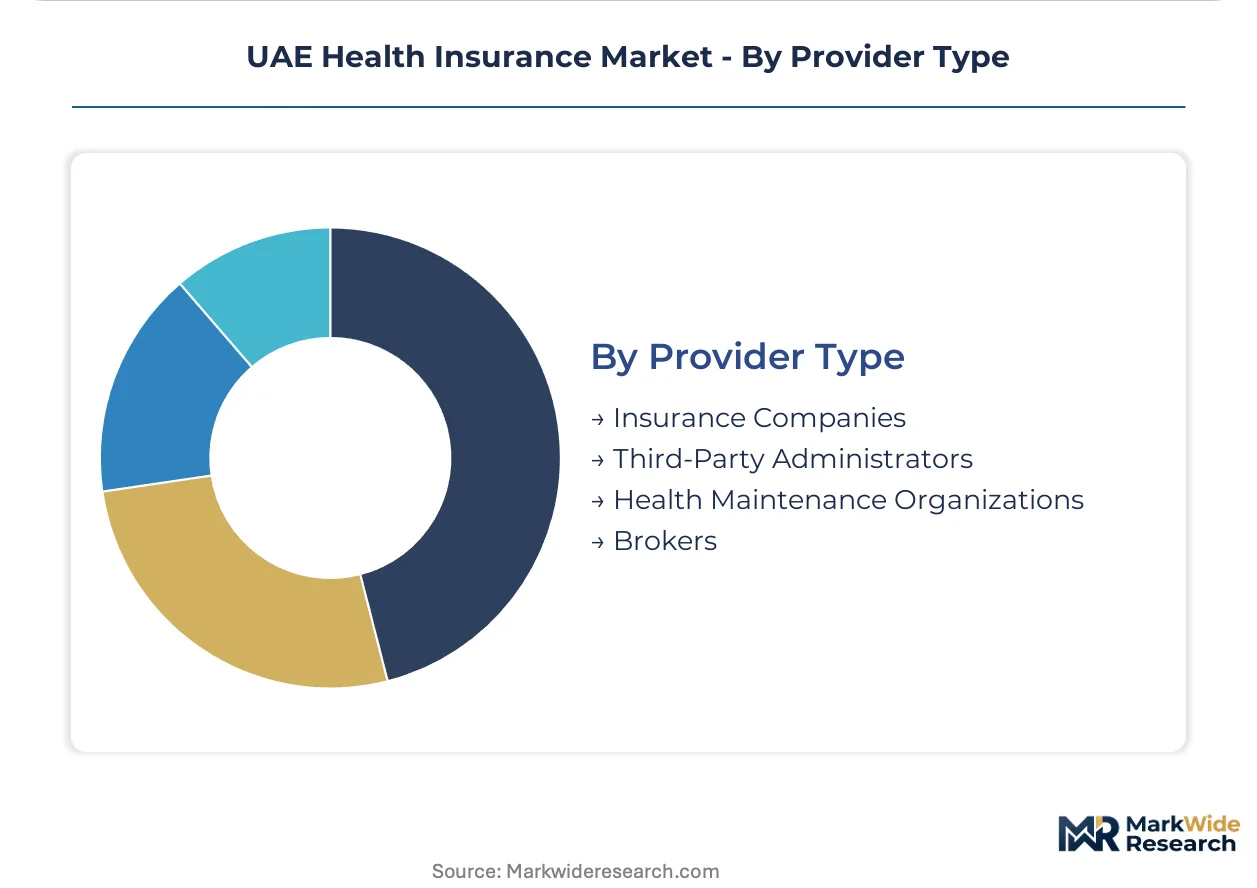
UAE health insurance constitutes risk-pooling financial instruments that reimburse medical expenditures across inpatient, outpatient, dental, and vision services, governed by emirate-level mandates with minimum benefit floors. These instruments transfer financial risk from individuals and employers to underwriters, with premiums calibrated to age-banded risk profiles and network access tiers. Group Plans command the largest premium pool due to employer mandate density, while Critical Illness Plans represent the fastest-growing product line as expatriates seek catastrophic protection beyond basic coverage. The Provider Type dimension reveals Third-Party Administrators capturing margin pools through claims management outsourcing, while Insurance Companies retain underwriting risk and capital reserves.
Regulatory Frame and Outlook
The Dubai Health Authority and the Department of Health Abu Dhabi jointly enforce mandatory coverage laws, with MOHAP extending federal coordination across northern emirates. These regulators shape demand by setting minimum benefit standards, penalizing non-compliant employers, and licensing network providers. Stakeholders must monitor evolving mandatory benefit expansions and emirate-specific network adequacy rules to align product design with compliance thresholds.
Market Dynamics
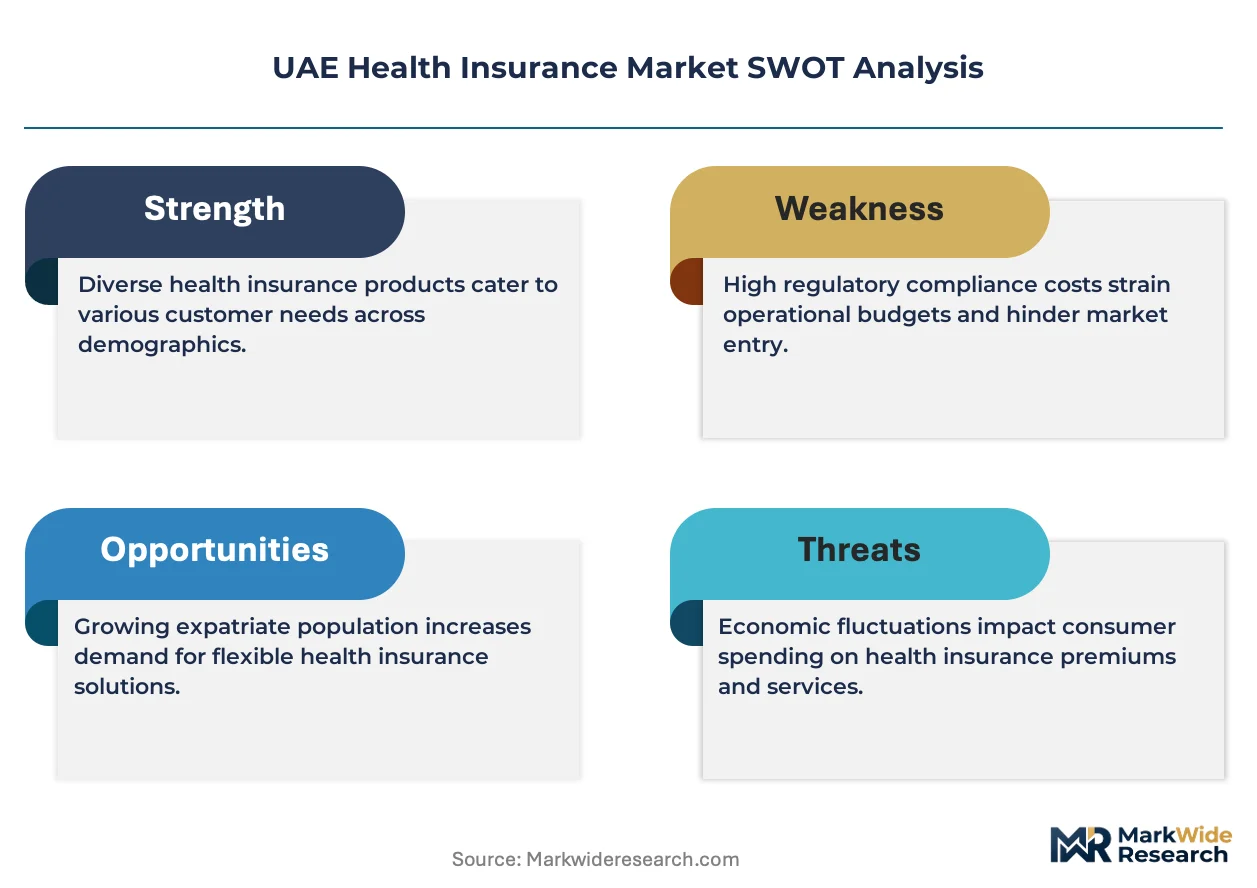
The Dubai Health Authority's tightening enforcement of mandatory coverage laws is compressing the competitive set while elevating compliance costs for smaller underwriters. This regulatory pressure is accelerating consolidation among regional carriers and forcing product standardization across emirate-level jurisdictions.
Growth Catalysts
- Employer Mandate Density:Private sector firms across Dubai and Abu Dhabi face escalating penalties for non-compliance, driving automatic enrollment expansion.
- Telemedicine Infrastructure:Virtual care platforms are integrating with policy administration systems, collapsing the distance between enrollment and service delivery.
- Critical Illness Product Innovation:Expatriate workforce demographics are pulling catastrophic coverage designs beyond basic inpatient floors.
Market Restraints
- Medical Cost Inflation:Hospital service charges in Dubai and Abu Dhabi outpace premium adjustment cycles, squeezing underwriting margins.
- Network Concentration Risk:Premium hospital chains in the two emirates control direct-billing negotiations, limiting insurer pricing power.
- Regulatory Fragmentation:Divergent minimum benefit standards between the Dubai Health Authority and Department of Health Abu Dhabi complicate multi-emirate product design.
Strategic Opportunities
- Northern Emirates Penetration:Sharjah, Ajman, and Ras Al Khaimah hold underpenetrated employer groups outside mandate-heavy Dubai-Abu Dhabi corridors.
- Third-Party Administrator Outsourcing:Claims management delegation is opening margin pools for specialized service vendors.
- MOHAP Federal Coordination:Unified licensing frameworks across northern emirates are streamlining cross-border network expansion.
Industry Challenges
- Actuarial Talent Scarcity:UAE-based underwriters face acute shortages of professionals versed in emirate-specific risk pooling and Sharia-compliant product structures.
- Legacy System Integration:Incumbent carriers struggle to merge decades-old policy administration platforms with real-time telemedicine billing interfaces.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UAE Health Insurance Market |
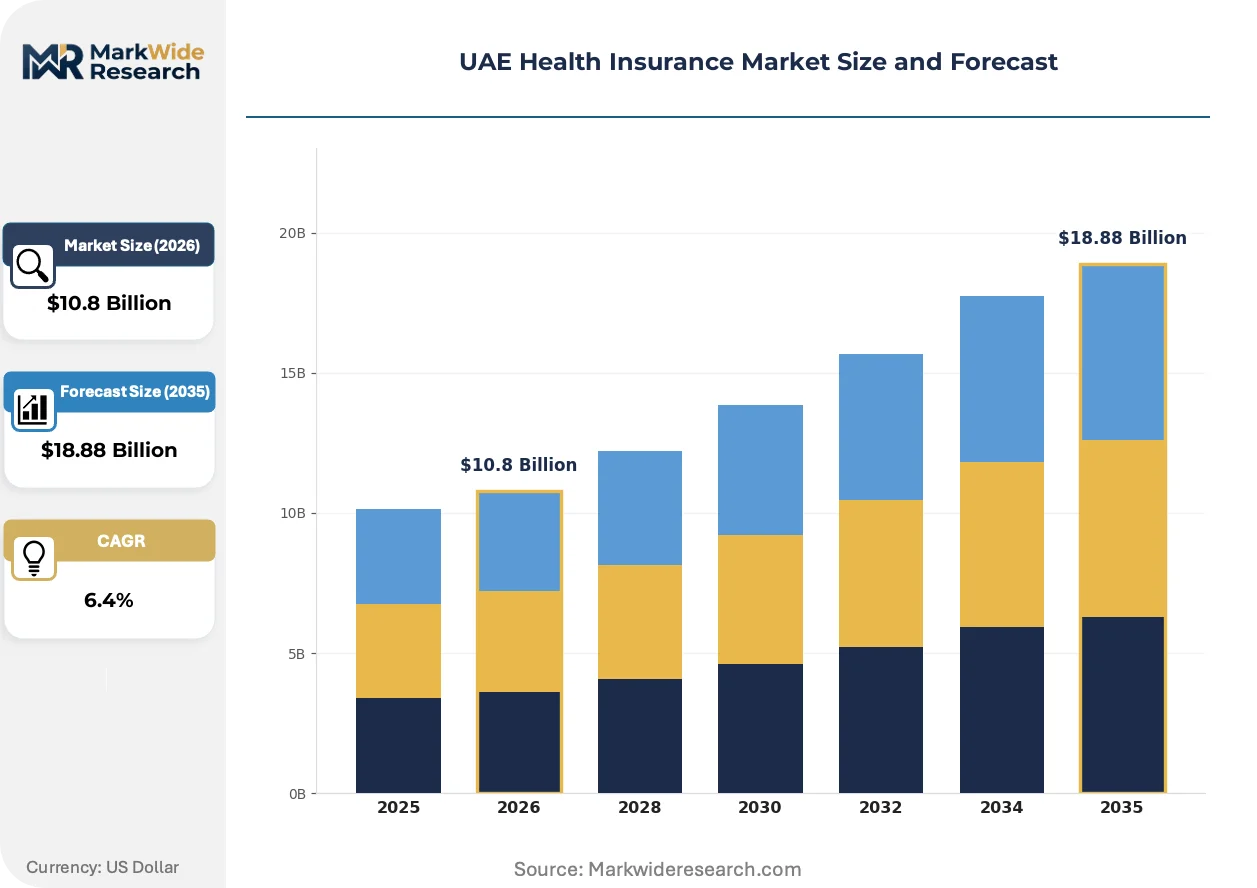
| Market Size in 2026 | $10.8 Billion |
| Market Size in 2035 | $18.88 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Individual Plans, Group Plans, Family Floater, Critical Illness Plans Coverage Type: Inpatient, Outpatient, Dental, Vision Customer Type: Individuals, Corporates, Government Employees, Expatriates Provider Type: Insurance Companies, Third-Party Administrators, Health Maintenance Organizations, Brokers |
| Companies Covered | GIG Gulf, Cigna, Daman Health, Al Buhaira National Insurance, Orient Insurance PJSC, Abu Dhabi National Insurance Company (ADNIC), MetLife, Al Ain Ahlia Insurance Company, Sukoon Insurance, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UAE Health Insurance Market Strategic Shifts & Innovations
Digital health infrastructure is compressing traditional value chains while regulatory mandates force product convergence. Three distinct movements are restructuring how coverage is designed, distributed, and consumed across the Emirates.
Artificial intelligence-driven claims adjudication is collapsing processing timelines from weeks to hours. Large employer groups in Dubai's financial services sector are demanding real-time pre-authorization for specialist referrals. This compression is eliminating traditional Third-Party Administrator bottlenecks and reallocating margin pools toward technology-enabled underwriters.
MOHAP's federal coordination mandate is harmonizing licensing standards across northern emirates. The policy removes duplicative provider credentialing requirements that previously fragmented network adequacy compliance. Multi-emirate employers are consolidating coverage under single policies as regulatory friction diminishes between Dubai-Abu Dhabi and peripheral markets.
Direct-to-consumer digital enrollment is displacing broker-mediated group sales among small and medium enterprises. Younger expatriate professionals in technology and consulting sectors are purchasing individual supplemental coverage outside employer channels. This channel shift is most visible in Dubai's free zone clusters where workforce turnover accelerates policy switching cycles.
UAE Health Insurance Market Segmentation
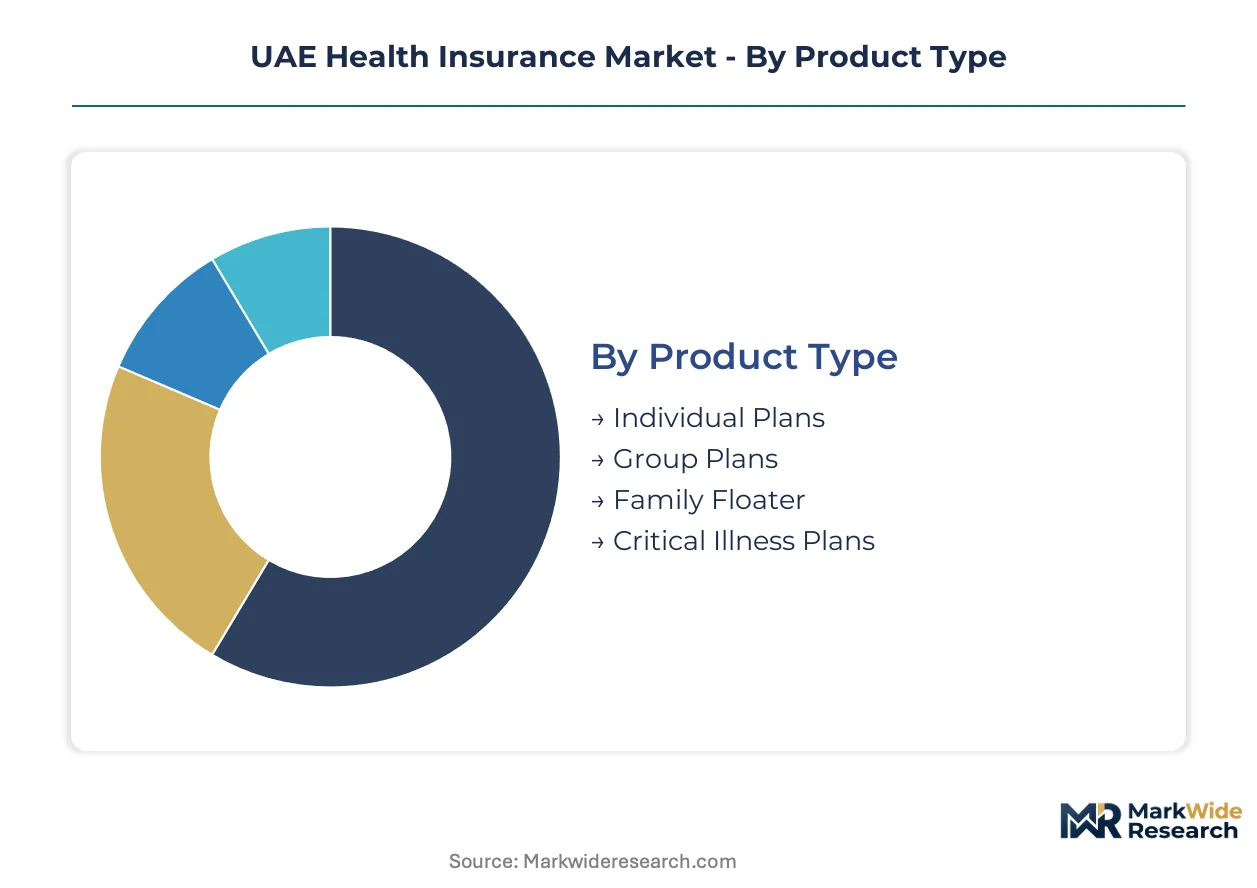
UAE health insurance segmentation reflects the interplay between emirate-level mandates and employer compliance structures. Product design varies sharply across customer types, with government-linked coverage demanding different service intensity than private corporate accounts.
Product Type:
After-sales service intensity diverges dramatically across product categories, with group plans requiring dedicated account management teams while individual plans demand self-service digital portals.
- Group Plans:Employer-sponsored risk pools covering employee cohorts under single master policies. Dubai and Abu Dhabi corporate sectors concentrate demand here, driven by DHA and DOH mandate enforcement with escalating non-compliance penalties.
- Critical Illness Plans:Catastrophic coverage products providing lump-sum payouts upon diagnosis of specified conditions. Expatriate professionals in technology and consulting sectors are pulling this segment fastest, seeking protection beyond basic inpatient floors.
- Individual Plans:Single-life policies purchased outside employer channels. Younger expatriates in Dubai free zones are switching policies more frequently as workforce turnover accelerates.
- Family Floater:Shared sum-insured structures covering multiple family members under one premium. Demand clusters among mid-tier expatriate households seeking dependent coverage compliance.
By volume, Group Plans lead. By growth pace, Critical Illness Plans are climbing the fastest.
Coverage Type:
Cost tier differentiation separates inpatient from outpatient offerings, with premium hospital chains in Dubai and Abu Dhabi commanding higher reimbursement rates for complex procedures.
- Inpatient:Hospitalization coverage including surgery, room charges, and intensive care. Mandatory benefit floors set by DHA and DOH ensure universal inclusion, though network tier access varies by premium level.
- Outpatient:Consultation, diagnostic, and minor procedure coverage outside admission. Telemedicine platforms are collapsing the distance between policy enrollment and service delivery for this segment.
- Dental:Preventive and restorative oral health services. Employer groups increasingly bundle this as a retention tool in competitive sectors.
- Vision:Eye examination and corrective lens coverage. Often positioned as a supplemental add-on rather than core benefit.
By volume, Inpatient dominates premium allocation. By growth pace, Outpatient is expanding most quickly through virtual care integration.
Customer Type:
Application focus varies across customer categories, with corporates demanding real-time pre-authorization systems while individual purchasers prioritize price transparency.
- Corporates:Private sector employer groups spanning multinational, local, and SME segments. Dubai financial services firms are demanding real-time specialist referral approvals, compressing traditional TPA processing timelines.
- Expatriates:Non-citizen residents requiring mandatory coverage compliance. This segment spans both employer-sponsored and individually purchased policies across all emirates.
- Government Employees:Public sector cohorts covered through state-linked arrangements. Daman Health dominates this segment through its government-affiliated position.
- Individuals:Self-purchased coverage outside employer channels. Direct-to-consumer digital enrollment is displacing broker-mediated sales among younger professionals.
By volume, Corporates lead policy issuance. By growth pace, Individual purchasers are gaining share fastest through digital channel displacement.
Provider Type:
Margin concentration favors entities controlling claims processing infrastructure, with technology-enabled underwriters capturing pools previously held by legacy intermediaries.
- Insurance Companies:Licensed underwriters retaining risk and capital reserves. Incumbents struggle to merge decades-old policy administration platforms with real-time telemedicine billing interfaces.
- Third-Party Administrators:Claims management specialists operating on outsourcing contracts. AI-driven adjudication is collapsing their processing timelines from weeks to hours, reallocating margin pools toward technology-enabled competitors.
- Brokers:Distribution intermediaries facilitating policy placement. Channel share is eroding among SMEs as direct digital enrollment rises.
- Health Maintenance Organizations:Integrated delivery systems combining insurance with captive provider networks. Limited penetration in UAE compared to other Gulf markets.
By volume, Insurance Companies retain the largest premium pool. By growth pace, Third-Party Administrators face the steepest competitive pressure from technology disruption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
UAE health insurance flows concentrate through Dubai and Abu Dhabi as primary demand centers, with northern emirates emerging as secondary corridors. Regulatory enforcement tightens compliance requirements across all jurisdictions. Premium collection clusters where employer mandate density reaches maximum penetration.
Dubai
Financial services and technology sectors drive group plan enrollment through escalating DHA penalties for non-compliance. The Dubai Health Authority mandates minimum benefit floors that compress product differentiation. Dubai Healthcare City anchors specialist network concentration, forcing real-time pre-authorization demands from corporate purchasers.
Abu Dhabi
Government employee coverage dominates through state-linked arrangements with Daman Health. The Department of Health Abu Dhabi enforces network adequacy rules that exceed Dubai standards. Al Ain industrial zones generate secondary demand from manufacturing employer groups seeking compliant coverage.
Sharjah
Logistics and education sectors form the core employer base outside mandate-heavy southern corridors. MOHAP federal coordination extends minimum benefit standards without equivalent penalty enforcement. University City clusters academic institutions with international faculty requiring dependent coverage compliance.
Ras Al Khaimah
Tourism and manufacturing investments pull new employer group formation with underpenetrated coverage rates. Northern emirate regulatory frameworks lag Dubai-Abu Dhabi compliance intensity. Al Hamra and Mina Al Arab developments concentrate hospitality workforce demand.
Ajman and Umm Al Quwain
Small and medium enterprise density creates fragmented policy switching cycles. Free zone establishments in Ajman generate expatriate professional demand outside traditional corporate channels. Fujairah's port and logistics corridor extends northern emirate coverage requirements eastward.
UAE Health Insurance Market Key Industry Players
On the supply side, the industry is bifurcated between government-affiliated underwriters and multinational commercial carriers. Daman Health occupies a protected position through public sector linkages. Cigna and GIG Gulf anchor the competitive tier through direct-billing network control. Strategic moves concentrate on telemedicine platform integration and TPA outsourcing partnerships to collapse claims processing timelines.
Within the government-linked tier, Daman Health exemplifies captive market positioning through its Department of Health Abu Dhabi affiliation. Among multinational commercial carriers, Cigna and GIG Gulf represent contrasting network strategies—Cigna through premium hospital chain direct-billing control, GIG Gulf through specialized corporate wellness bundling. These three anchors illustrate the structural divide between protected public sector coverage and contested private corporate accounts.
| Leading Market Players |
|---|
| GIG Gulf |
| Cigna |
| Daman Health |
| Al Buhaira National Insurance |
| Orient Insurance PJSC |
| Abu Dhabi National Insurance Company (ADNIC) |
| MetLife |
| Al Ain Ahlia Insurance Company |
| Sukoon Insurance |
| Others |
Cost & Logistics Intelligence
Jebel Ali Port freight corridors shape cost dynamics across the UAE health insurance value chain, with logistics expenses feeding into premium differentials between network tiers while supply concentration in Dubai Healthcare City and Abu Dhabi's Corniche district reinforces pricing power for premium hospital chains.
Pricing Analysis
Legacy policy administration platform pricing diverges sharply from next-generation telemedicine-integrated offerings, with AI-enabled underwriters commanding premium positioning over incumbent carriers. Three-tier pricing structure across premium, standard, and economy levels separates direct-billing network access, specialist referral speed, and annual claim limits. Pricing pressure stems from medical cost inflation outpacing premium adjustment cycles in Dubai and Abu Dhabi. Small and medium enterprises exhibit highest price sensitivity, while multinational corporate purchasers prioritize network adequacy over premium minimization.
Supply Chain Analysis
Single-source vulnerability in third-party administrator networks concentrates risk among legacy claims processors unable to merge with real-time telemedicine billing interfaces. Geographic supply concentration centers on Dubai and Abu Dhabi for policy issuance, with Sharjah and Ras Al Khaimah emerging as secondary service delivery nodes. Raw material dependencies include medical practitioner licensing pools, hospital bed capacity, and pharmaceutical distribution networks. Distribution runs through employer-sponsored group channels dominating premium collection, with direct-to-consumer digital enrollment gaining share among younger expatriate professionals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UAE health insurance market sits at a platform-economics inflection where telemedicine integration collapses traditional value chains, with interoperability between policy administration and point-of-care delivery determining competitive survival.
For Market Incumbents: Build switching-cost moats through embedded telemedicine platform integration that locks employer groups into integrated service ecosystems. Consolidate claims processing capabilities through strategic third-party administrator partnerships to compress adjudication timelines from weeks to hours. Defend against digital-native entrants by controlling direct-billing relationships with premium hospital chains in Dubai and Abu Dhabi. For New Entrants and Emerging Players: Establish a beachhead in northern emirates employer groups outside mandate-heavy Dubai-Abu Dhabi corridors, where compliance intensity lags and switching costs remain low. Target small and medium enterprises in Sharjah logistics and education sectors with modular, self-service digital enrollment products. Pursue white-label telemedicine platform partnerships to bypass legacy system integration barriers. For Investors and Strategic Acquirers: Technology-enabled third-party administrators with AI-driven adjudication capabilities represent the highest-conviction acquisition archetype for margin pool capture. Long-term viability hinges on regulatory harmonization progress across emirate-level jurisdictions. Monitor MOHAP federal coordination implementation as the critical inflection signal for cross-border network scalability.| Strategic Initiative | Industry Significance |
|---|---|
| Telemedicine Platform Integration | Collapses distance between DHA-mandated enrollment and virtual care delivery for outpatient services. |
| Third-Party Administrator Acquisition | Captures margin pools from claims processing outsourcing as AI adjudication displaces legacy processors. |
| Northern Emirates Network Expansion | Exploits underpenetrated employer groups in Sharjah and Ras Al Khaimah before mandate intensification. |
| Direct-Billing Hospital Partnership | Secures pricing power with premium chains in Dubai Healthcare City and Abu Dhabi Corniche district. |
| Digital Enrollment Channel Buildout | Displaces broker-mediated SME sales through self-service portals targeting free zone professionals. |
Research Approach
Operator-level perspectives from health insurance underwriting executives, DHA compliance officers, hospital network contracting managers, and third-party administrator operations directors anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation against Dubai Health Authority regulatory filings, Department of Health Abu Dhabi mandate documentation, MOHAP federal coordination circulars, and employer group procurement databases. Bottom-up policy issuance tracking and top-down premium pool estimation triangulated market sizing across the analysis window.
Scenario-bracketing framed the analytical approach with sensitivity testing around regulatory enforcement intensity, medical cost inflation trajectories, and telemedicine adoption curves. Segmentation dimensions modeled include product type, coverage tier, customer category, provider archetype, and emirate-level regulatory jurisdiction. CAGRs derived from policy volume growth rates and average premium per life adjustments. Forecast inputs incorporated employer mandate penalty escalation schedules and network adequacy rule evolution.
Sensitivities concentrate around DHA and DOH mandate enforcement variability, northern emirates regulatory harmonization pace, and hospital chain consolidation effects on direct-billing negotiations. Forecasts reflect assumptions regarding expatriate workforce demographics and technology platform adoption thresholds. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Health Insurance
US Healthcare Discount Plan Market
Health Insurance
UAE Health and Medical Insurance Market
Health Insurance
US Group Health Insurance Market
Health Insurance
United States Health and Medical Insurance Market
Health Insurance
Healthcare Reimbursement Market
Health Insurance
Healthcare Payer Services Market
Health Insurance
North America Group Health Insurance Market
Health Insurance
Indonesia Health and Medical Insurance Market
Health Insurance
Healthcare Insurance Market
Health Insurance
Health Insurance Market
Health Insurance
Germany Health Insurance Market
Health Insurance
Healthcare Payer Solution Market
Health Insurance
UAE Health Insurance Third Party Administrators (TPA) Market