
 Healthcare Insurance Market | 2026-2036
Healthcare Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Healthcare Insurance Market Intelligence
Small and mid-sized employers is bifurcating from large enterprise contracts as the dominant growth archetype in healthcare insurance purchasing. UnitedHealth Group leverages its Optum care delivery arm to sustain integrated cost advantages across employer and Medicare segments. Elevance Health anchors its expansion in Medicaid managed care and commercial risk plans across diverse state-level markets.
Healthcare insurance constitutes a risk-pooling financial instrument underwritten through actuarial assessment of population health probabilities, with policies specifying benefit triggers, cost-sharing tiers, and network adequacy requirements designed to fund medical expenditure and indemnify against catastrophic health loss. Employer-sponsored coverage dominates premium volume, while Medicare Advantage represents the fastest-expanding payer type as demographic shifts enlarge the eligible population. Comprehensive coverage scope captures the deepest margin pools, though catastrophic plans attract price-sensitive individual buyers through lower premium structures.
The Centers for Medicare & Medicaid Services shapes product design through star-rating quality thresholds and value-based payment mandates, while state insurance commissioners enforce reserve adequacy and network adequacy standards that govern market access. HIPAA portability rules and Affordable Care Act essential health benefit requirements constrain underwriting flexibility and standardize coverage minimums across individual and small-group markets. Stakeholders must monitor evolving prior authorization restrictions and pharmacy benefit cost controls as these regulatory levers determine competitive positioning and profitability trajectories.
Market Dynamics
Value-based care mandates from CMS are forcing carriers to restructure provider networks around quality metrics rather than fee-for-service volume, fundamentally altering how actuarial risk gets priced and managed across employer and government segments.
Growth Catalysts
- Medicare Advantage expansion:CMS star-rating bonuses reward plans achieving quality thresholds, pulling enrollment toward managed care models that integrate medical and pharmacy benefits under unified risk contracts.
- Employer-sponsored group plan adaptation:Mid-sized enterprises are redesigning coverage around hybrid workforce models, expanding eligibility for part-time employees and remote workers across state lines.
- Telehealth reimbursement permanence:Post-pandemic parity laws in multiple states now mandate equivalent payment for virtual visits, enabling carriers to build narrow networks with geographic flexibility.
Market Restraints
- Medical cost inflation:Specialty drug pricing from gene and cell therapies is compressing margins in commercial risk pools, forcing carriers to tighten prior authorization protocols.
- Network adequacy enforcement:State insurance commissioners in California and New York are rejecting narrow-network designs that fail time-and-distance standards for specialty care access.
- Actuarial uncertainty:Long COVID prevalence and post-acute sequelae lack sufficient claims history for accurate reserving, elevating capital requirements.
Strategic Opportunities
- Medicaid managed care expansion:States including Texas and Georgia are transitioning fee-for-service populations to managed care, creating procurement windows for carriers with existing infrastructure.
- Behavioral health integration:Collaborative care models that embed psychiatric consultation in primary care are attracting employer purchasers seeking total cost-of-care reduction.
- Direct primary care alignment:Subscription-based primary care practices are partnering with high-deductible plans to create hybrid products that reduce emergency department utilization.
Industry Challenges
- Interoperability implementation:CMS mandates for prior authorization automation require carriers to rebuild legacy claims systems around FHIR standards by specified deadlines.
- Actuarial talent scarcity:Pricing teams with expertise in both Medicare risk adjustment and commercial underwriting are concentrated among established carriers, constraining new market entry.
- Pharmacy benefit complexity:Rebate contracting with pharmacy benefit managers involves opaque pricing structures that complicate transparent reporting to employer sponsors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Healthcare Insurance Market |
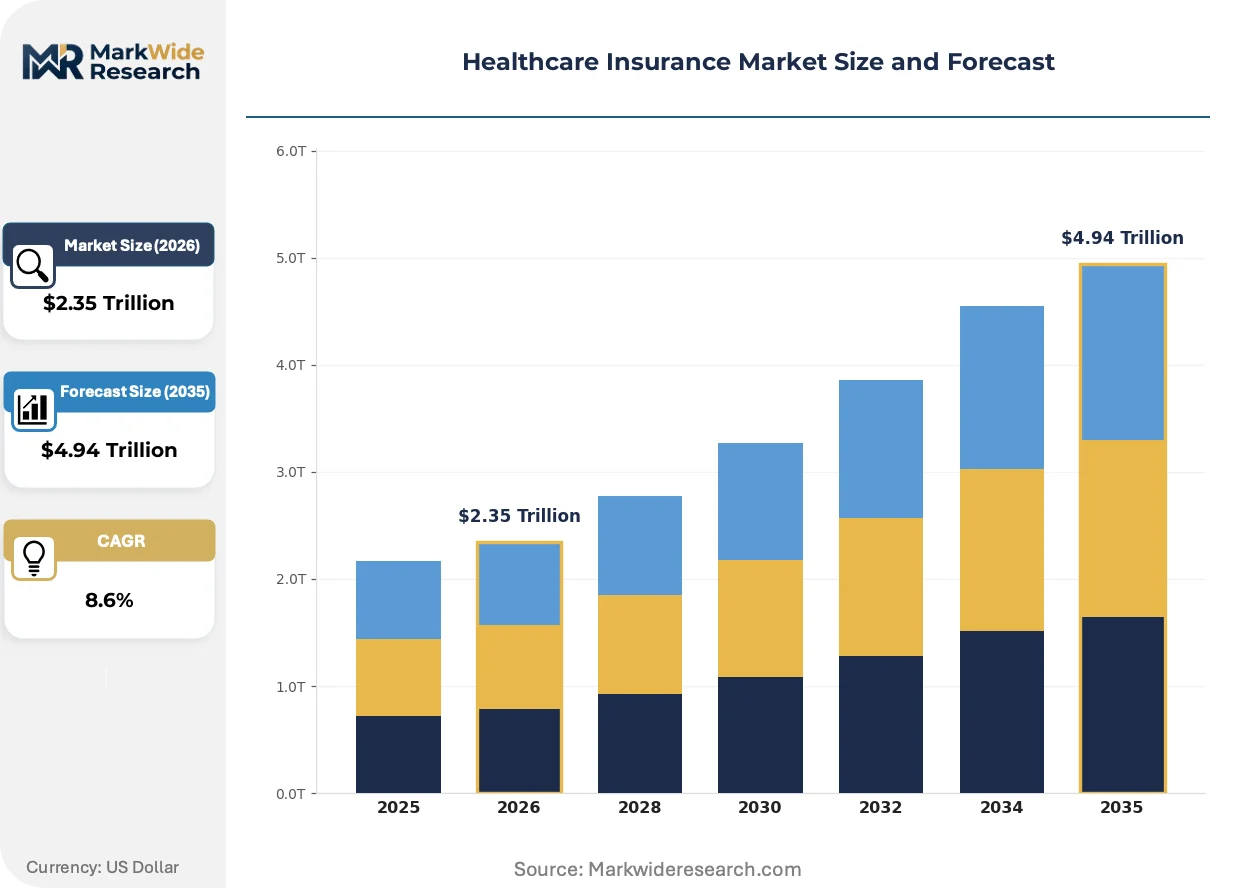
| Market Size in 2026 | $2.35 Trillion |
| Market Size in 2035 | $4.94 Trillion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Policy Type: Individual, Family, Group, Short-Term Payer Type: Private, Public, Employer-Sponsored, Medicare Coverage Scope: Basic, Comprehensive, Catastrophic, Preventive Premium Range: Lower, Middle, Upper, High-Net-Worth |
| Companies Covered | UnitedHealth Group, Elevance Health, Kaiser Permanente, Centene Corporation, CVS Health, Humana, Health Care Service Corporation, Cigna, Molina Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Healthcare Insurance Market Strategic Shifts & Innovations
Artificial intelligence deployment is fragmenting traditional underwriting workflows while regulatory pressure on algorithmic bias intensifies scrutiny of automated claims decisions.
Machine learning models trained on electronic health record data are fragmenting risk stratification capabilities, enabling carriers to identify high-cost episodes before they occur. Medicare Advantage plans with advanced analytics infrastructure are deploying these tools to reduce preventable hospitalizations. The technology is fragmenting competitive advantage toward carriers with proprietary data assets and in-house data science capacity.
CMS interoperability rules under the 21st Century Cures Act are mandating real-time claims data exchange between payers and providers. This regulatory pressure is compressing administrative lag times in prior authorization and accelerating shift toward instant eligibility verification. Commercial carriers serving self-insured employers are most affected, with large group administrators racing to build API infrastructure.
Employer purchasers are unbundling pharmacy benefits from medical contracts to secure direct contracts with specialty pharmacies and rebate transparency. This procurement evolution is disrupting traditional PBM-carrier bundled offerings and elevating standalone pharmacy administrators. The pattern is most visible among Fortune 500 employers in manufacturing and technology sectors seeking pass-through pricing models.
Healthcare Insurance Market Segmentation
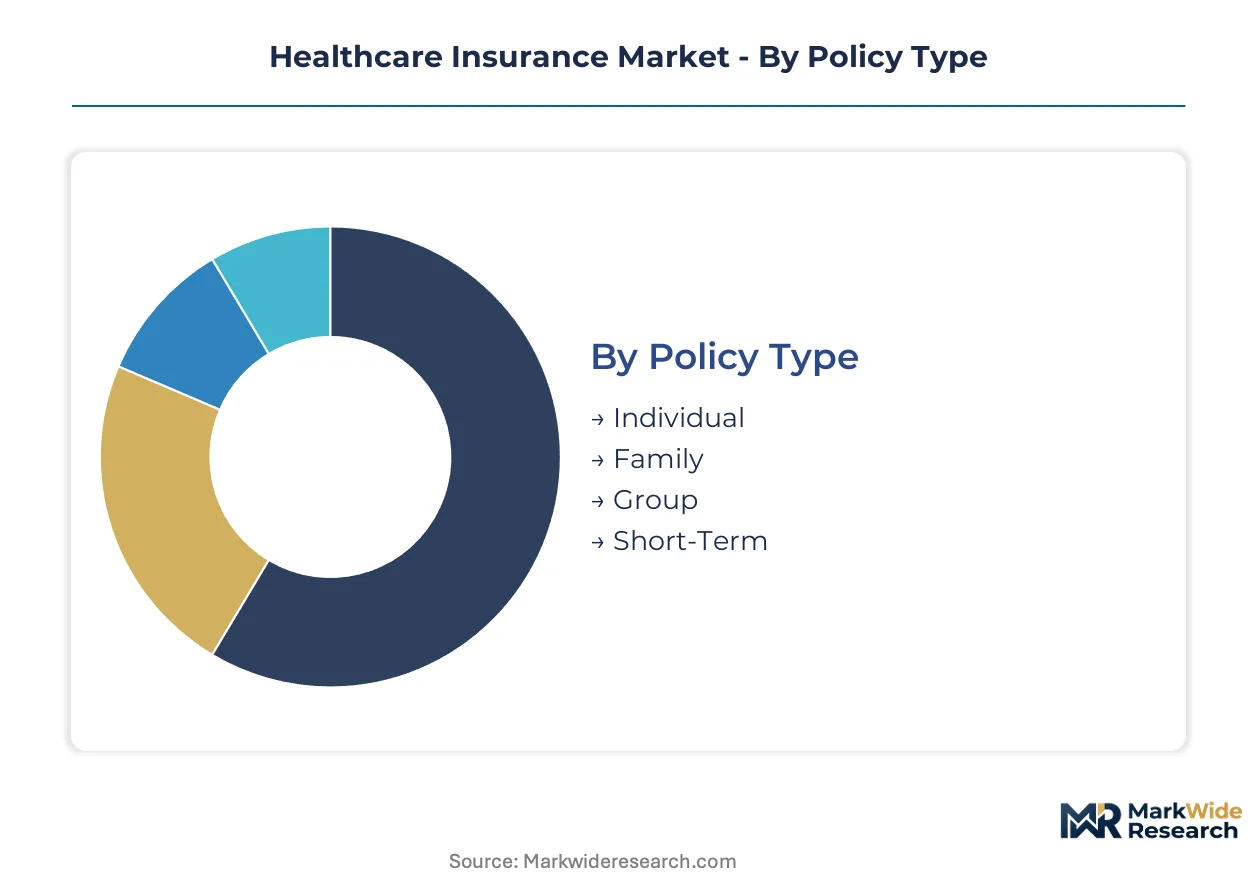
Healthcare insurance segmentation governs how carriers allocate capital across risk pools, price products for distinct buyer economics, and comply with jurisdiction-specific benefit mandates. Understanding these divisions reveals where margin concentrates and which structural shifts reshape competitive positioning.
Policy Type:
Distribution channels diverge sharply across policy structures, with group contracts flowing through employer benefit consultants while individual and family plans route through state exchanges and direct-to-consumer platforms.
- Individual:Single-subscriber policies purchased through Affordable Care Act marketplaces or off-exchange. Demand concentrates in states with limited employer coverage availability, where premium subsidies from CMS determine affordability thresholds and enrollment velocity.
- Family:Multi-dependent coverage units with tiered cost-sharing structures. Growth pace is accelerating among gig-economy households in Texas and Florida seeking alternatives to employer-sponsored plans.
- Group:Employer-aggregated risk pools with guaranteed issue requirements. By volume, this segment leads. By growth pace, individual coverage is ahead.
- Short-Term:Limited-duration products exempt from essential health benefit mandates. These plans attract healthy buyers in transitional employment gaps, particularly in states with relaxed duration limits.
Group policies generate the deepest premium volumes, yet individual and short-term segments are expanding most quickly as workforce mobility fractures traditional employment relationships.
Payer Type:
Cost tier stratification determines which payer categories absorb the highest per-member medical expenditures and where administrative complexity escalates.
- Private:Commercial carriers underwriting risk through fully insured or self-funded arrangements. These entities dominate employer-sponsored purchasing in the United States, where UnitedHealth Group and Elevance Health compete for national accounts.
- Public:State and federal programs including Medicaid fee-for-service and CHIP. Procurement is shifting toward managed care carve-outs in states like Texas and Georgia, creating contract migration.
- Employer-Sponsored:Group risk pools where employers assume partial or full financial responsibility. Mid-sized enterprises in manufacturing and technology sectors are redesigning eligibility around remote workforce dispersion.
- Medicare:Federal entitlement program with expanding managed care penetration through Medicare Advantage. CMS star-rating thresholds determine bonus eligibility and plan positioning in this segment.
Employer-sponsored coverage retains the largest enrolled base, though Medicare Advantage is climbing the fastest as demographic aging enlarges the eligible population.
Coverage Scope:
Application intensity varies across coverage tiers, with comprehensive plans dominating hospital network negotiations and catastrophic products requiring minimal administrative infrastructure.
- Basic:Essential health benefit coverage with high deductibles and limited provider choice. These products attract price-sensitive buyers in states with narrow-network regulatory flexibility.
- Comprehensive:Broad benefit designs with low cost-sharing and expansive network access. Demand concentrates among large employers seeking total cost-of-care predictability and employee retention.
- Catastrophic:High-deductible structures protecting against ruinous medical expenses. Young adult enrollment in ACA-compliant catastrophic plans is expanding most quickly as premium affordability constrains purchase decisions.
- Preventive:Wellness-focused designs with first-dollar coverage for screenings and primary care. These products are gaining traction among self-insured employers targeting chronic disease reduction.
Comprehensive coverage captures the deepest margin pools, while catastrophic and preventive tiers are gaining share fastest as cost-conscious purchasing reshapes buyer behavior.
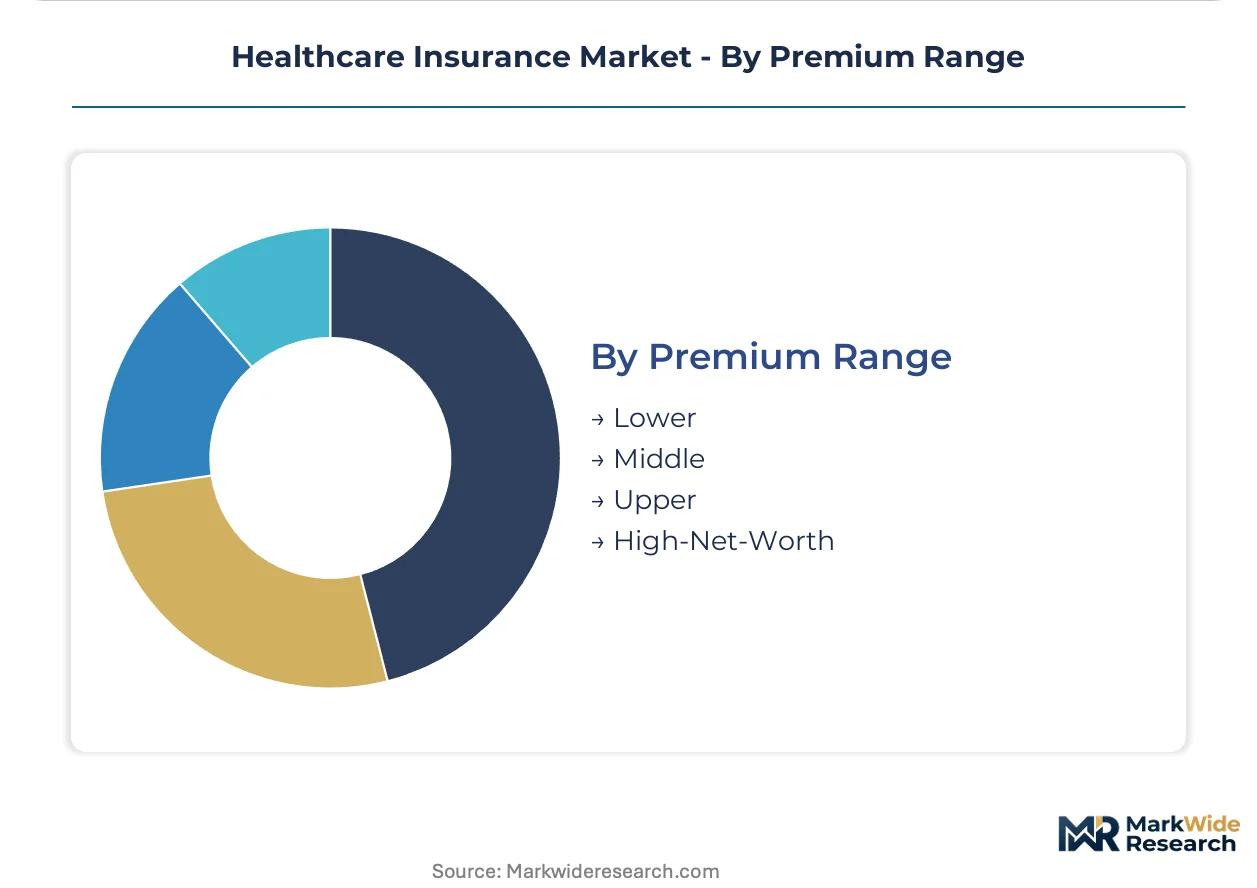
Premium Range:
Customer type and purchasing power segment the market into distinct pricing strata, with commission structures and service intensity scaling accordingly.
- Lower:Subsidized individual market products with narrow networks and high member cost-sharing. Enrollment concentrates in states with expanded Medicaid thresholds and robust exchange outreach.
- Middle:Standard commercial group and individual products with moderate deductibles. This tier dominates mid-sized employer purchasing and represents the largest covered lives volume.
- Upper:Low-deductible plans with broad network access and enhanced benefits. Fortune 500 employers in financial services and technology sectors anchor demand here.
- High-Net-Worth:Concierge-integrated products with direct primary care alignment and international coverage options. These policies command the steepest premium multiples and require specialized distribution through wealth advisors.
Middle-tier products enroll the most lives, yet high-net-worth and lower-tier segments are expanding most quickly as polarization concentrates purchasing at the extremes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States maintains its position through employer-sponsored group infrastructure and Medicare Advantage distribution networks. Germany leverages its statutory health insurance framework and social health insurance mandates. Japan's universal coverage system and aging demographic profile create distinct payer dynamics.
United States
Employer-sponsored coverage dominates premium volume through mid-sized enterprise adaptation to hybrid workforce models. CMS star-rating thresholds and value-based payment mandates from the Centers for Medicare & Medicaid Services reshape product design. Medicare Advantage enrollment concentrates in Florida and Arizona retirement corridors.
Germany
Statutory health insurance funds face consolidation pressure as social health insurance mandates expand coverage obligations. The Federal Joint Committee regulates benefit catalog updates and reimbursement structures. Berlin and Munich anchor competing statutory insurer headquarters clusters.
Japan
Universal health coverage sustains enrollment through employer-based society-managed plans and community-based National Health Insurance. The Ministry of Health, Labour and Welfare adjusts reimbursement rates biennially. Tokyo and Osaka metropolitan areas concentrate private supplementary insurance purchasing.
United Kingdom
Private medical insurance supplements National Health Service access through employer-sponsored group contracts. Care Quality Commission standards influence network adequacy requirements. London's financial services sector drives corporate health benefit expenditure.
Canada
Provincial single-payer systems dominate while private supplementary insurance covers prescription drugs and dental benefits. Health Canada regulates medical device and drug approval timelines affecting benefit design. Ontario and British Columbia concentrate private insurer operational infrastructure.
Healthcare Insurance Market Key Industry Players
Concentration sits with vertically integrated national carriers commanding Medicare Advantage and employer-sponsored segments. The market structure tiers between diversified health services conglomerates, Medicaid-focused regional specialists, and pharmacy-benefit-integrated platforms. Strategic archetypes include care-delivery-integrated underwriters, state-level Medicaid contractors, and PBM-affiliated carriers. Competitive moves center on Medicare Advantage geographic expansion and employer group account consolidation.
Within the integrated health services tier, UnitedHealth Group exemplifies care-delivery convergence through its Optum infrastructure. Elevance Health occupies a position bridging Medicaid managed care and commercial risk diversification. CVS Health represents pharmacy-benefit-manager-carrier integration, anchoring the PBM-affiliated archetype.
| Leading Market Players |
|---|
| UnitedHealth Group |
| Elevance Health |
| Kaiser Permanente |
| Centene Corporation |
| CVS Health |
| Humana |
| Health Care Service Corporation |
| Cigna |
| Molina Healthcare |
| Others |
Cost & Logistics Intelligence
Capitated risk contracts with multi-year rate guarantees lock in both provider network access and premium predictability for employer sponsors navigating medical cost inflation. These arrangements tether pricing visibility to care-delivery infrastructure commitments across United States markets.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates comprehensive employer-sponsored plans from narrow-network commercial products and high-deductible catastrophic coverage. Price differentiation hinges on network breadth and CMS star-rating attainment. Pricing pressure stems from gene therapy cost compression in commercial risk pools. Individual marketplace buyers exhibit highest price sensitivity; Fortune 500 employers show lowest.
Supply Chain Analysis
Inbound logistics costs for pharmaceutical distribution through Port of Long Beach and Port of New York and New Jersey fluctuate with container availability across transpacific trade lanes. Claims processing infrastructure concentrates in the United States, India, and Ireland. Carrier operations draw from cloud computing services, specialized actuarial software, and PBM rebate administration platforms. Single-source vulnerability sits with concentrated pharmacy benefit manager relationships. Distribution runs through employer benefit consultants, state exchange platforms, and direct-to-consumer digital channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
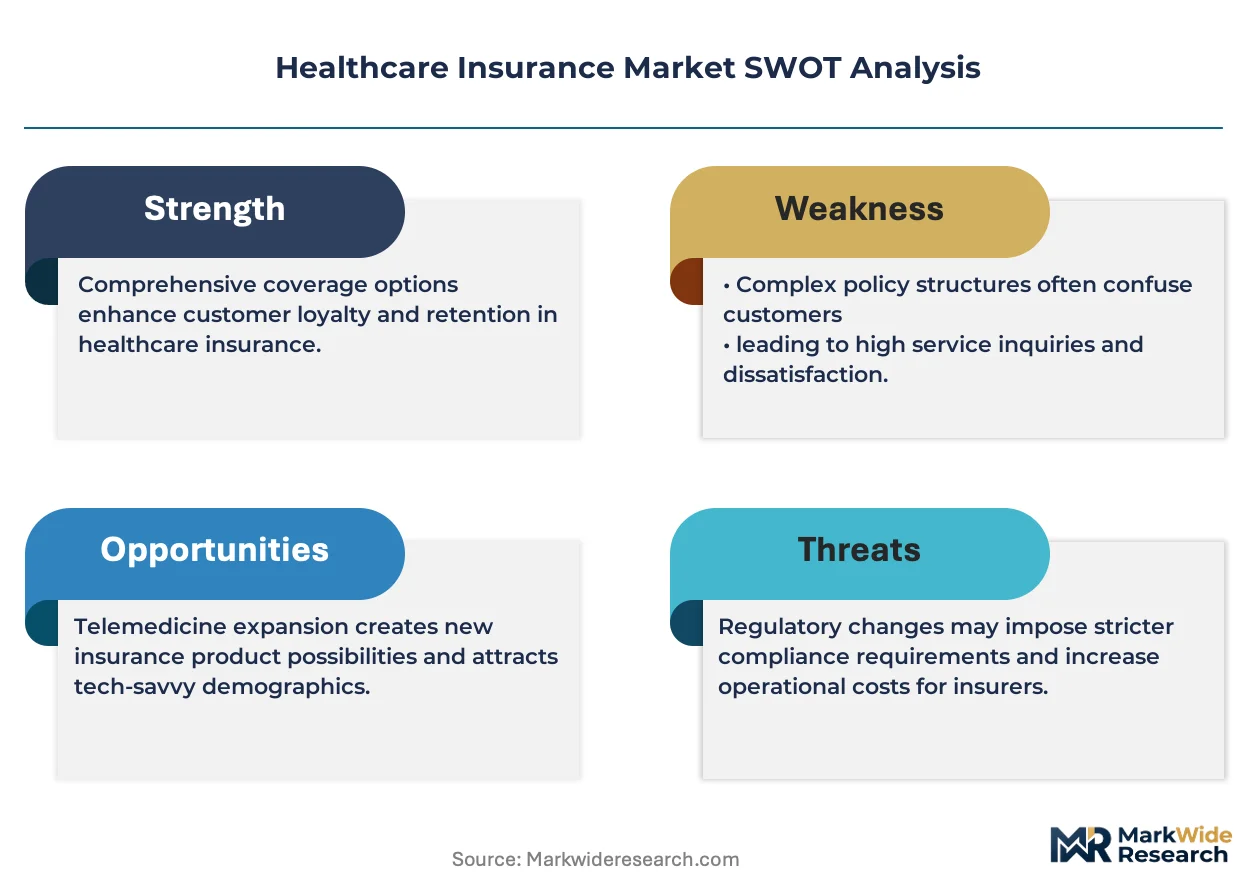
Analyst Recommendations
Healthcare insurance fragmentation creates entry niches as workforce mobility fractures traditional employer-aggregated risk pools and individual marketplace demand accelerates.
For Market Incumbents: Consolidate Medicare Advantage geographic footprints in Florida and Arizona retirement corridors to capture demographic-driven enrollment expansion. Deepen backward integration into primary care delivery through direct employment of physician networks, countering narrow-network adequacy enforcement from state insurance commissioners. For New Entrants and Emerging Players: Anchor in Medicaid managed care procurement windows opening in Texas and Georgia as these states transition fee-for-service populations to managed care. Target behavioral health integration partnerships with employer purchasers seeking total cost-of-care reduction through collaborative care models. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors care-delivery-integrated underwriters with proprietary data assets. Long-term viability over the next decade rests on analytics infrastructure and Medicare risk adjustment expertise. Watch CMS prior authorization automation mandates as the inflection signal for legacy system replacement demand.| Strategic Initiative | Industry Significance |
|---|---|
| Medicare Advantage Geographic Expansion | Captures demographic-driven enrollment growth in retirement-heavy states with CMS bonus eligibility. |
| Provider Network Vertical Integration | Locks in cost advantages through Optum-style care delivery arms and employed physician models. |
| Pharmacy Benefit Unbundling | Responds to employer demand for rebate transparency and direct specialty pharmacy contracting. |
| Behavioral Health Platform Acquisition | Addresses employer purchaser priorities for psychiatric consultation embedded in primary care. |
| Medicaid Managed Care Procurement | Secures state contracts in Texas and Georgia fee-for-service transition windows. |
Research Approach
A spread of perspectives from chief actuaries, employer benefit consultants, state insurance commissioners, and CMS policy leads converged on the working assumptions shaping this analysis. Primary interviews with carrier network contracting officers and hospital system reimbursement directors combined with secondary validation from CMS Medicare Advantage enrollment files, state insurance commissioner rate filings, and GPO contract databases. Bottom-up policy enrollment modeling and top-down premium volume triangulation anchored the quantitative framework.
Segmentation dimensions modeled across the projection horizon include policy type, payer category, coverage scope, and premium tier alongside geographic regulatory cluster. CAGRs derived from historical enrollment velocity and medical cost trend extrapolation incorporate Medicare risk adjustment factor evolution and employer-sponsored coverage elasticity assumptions.
Decision-makers should treat outputs as directional under stable regulatory implementation timelines; material deviation in CMS star-rating methodology or state Medicaid expansion decisions would warrant model refresh. Practitioners should keep alternative scenarios live as prior authorization automation deadlines and gene therapy cost containment policies evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Health Insurance
UAE Health Insurance Market
Health Insurance
Healthcare Reimbursement Market
Health Insurance
Health Insurance Market
Health Insurance
US Healthcare Discount Plan Market
Health Insurance
Healthcare Payer Services Market
Health Insurance
UAE Health and Medical Insurance Market
Health Insurance
Healthcare Payer Solution Market
Health Insurance
Indonesia Health and Medical Insurance Market
Health Insurance
Germany Health Insurance Market
Health Insurance
North America Group Health Insurance Market
Health Insurance
US Group Health Insurance Market
Health Insurance
United States Health and Medical Insurance Market
Health Insurance
UAE Health Insurance Third Party Administrators (TPA) Market