
 Healthcare Payer Solution Market | 2026-2036
Healthcare Payer Solution Market Size, Share, and Industry Trends Forecast 2026-2036
Healthcare Payer Solution Market Outlook
The capability gap between cloud-native platforms and legacy mainframe-dependent operations is reorganizing competitive dynamics across the Healthcare Payer Solution landscape. UnitedHealth Group Inc. leverages its vertically integrated Optum technology stack to control both payer and provider data flows. Cognizant Technology Solutions anchors its position through deep R&D partnerships with regional Blue Cross plans seeking modular modernization paths. Tata Consultancy Services Limited dominates offshore delivery centers that sustain cost advantages for mid-market payers.
Healthcare payer solutions encompass software platforms and services that automate eligibility verification, claims adjudication, risk stratification, and provider network management for insurance entities. These systems typically process batch claims cycles within 24-48 hours while maintaining HIPAA-compliant audit trails across member and transaction records. Claims management platforms retain the largest installed base among product type segments, though fraud detection modules are capturing disproportionate investment as synthetic identity schemes multiply. Cloud-based technology deployments are displacing on-premise infrastructure fastest among Medicare Advantage entrants lacking legacy technical debt.
FDA oversight of clinical decision support algorithms and CMS interoperability mandates under the 21st Century Cures Act are tightening compliance requirements for payer data exchange architectures. State insurance commissioners in California, New York, and Texas are layering prior authorization reform rules that force workflow redesigns across existing platforms. Stakeholders must weigh whether to build proprietary AI-driven utilization management engines or embed third-party analytics tools that shift regulatory liability to vendors.
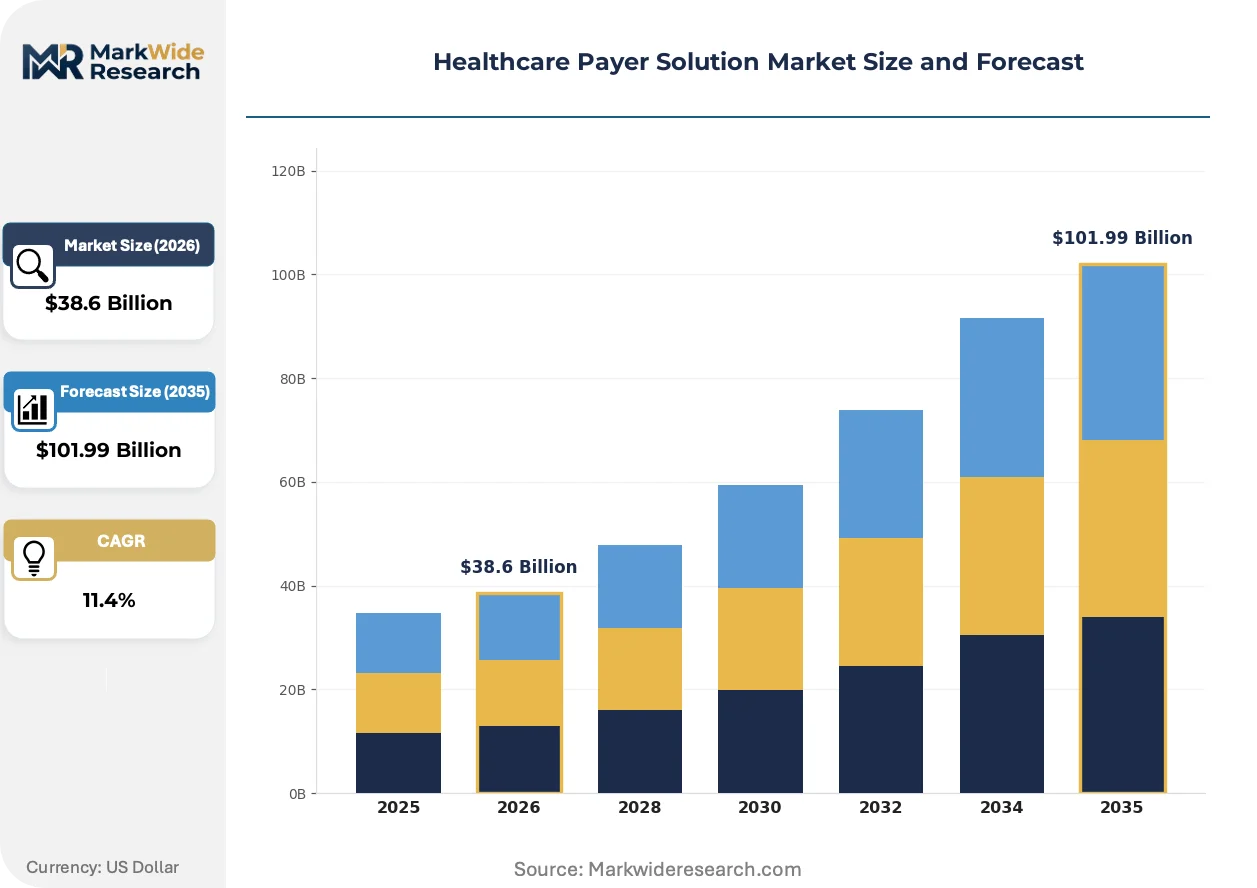
Market Dynamics
The migration from mainframe-dependent claims infrastructure to cloud-native architectures is forcing wholesale replatforming decisions across Medicare Advantage and commercial payer segments. Technical debt accumulated over three decades now collides with CMS interoperability mandates and real-time adjudication requirements.
Growth Catalysts
- CMS Interoperability Mandates:The 21st Century Cures Act final rules compel standardized API-driven data exchange between payers, providers, and patients. Payers must replace batch-oriented EDI transactions with FHIR-based real-time interfaces by mandated deadlines.
- Medicare Advantage Surge:Enrollment expansion among aging populations creates demand for modern eligibility engines and risk adjustment platforms. New market entrants lack legacy infrastructure and adopt cloud-first stacks without migration burden.
- Value-Based Reimbursement:CMS alternative payment models tie reimbursement to quality metrics and total cost of care. Payers invest in analytics layers that stratify member risk and predict utilization patterns.
Market Restraints
- Mainframe Technical Debt:COBOL-dependent core administration systems require specialized talent pools that shrink annually. Migration costs for large national plans often exceed nine-figure thresholds.
- State Regulatory Fragmentation:Prior authorization reform rules in California, New York, and Texas impose conflicting workflow requirements. Multi-state payers face compliance multiplication rather than harmonization.
- Synthetic Identity Fraud:Fabricated member identities exploit gaps between payer eligibility systems and federal verification databases. Fraud detection module investments divert capital from platform modernization.
Strategic Opportunities
- AI-Driven Utilization Management:Machine learning models trained on historical claims data automate prior authorization decisions. Payers must choose between proprietary engine development and third-party vendor embedding.
- Medicaid Expansion States:States adopting Medicaid expansion under ACA provisions require eligibility and enrollment platforms. Regional health plans compete for new managed care contracts with modernized administrative capabilities.
- Social Determinant Integration:CMS innovation center pilots reward payers for addressing housing instability and food insecurity. Platform vendors add non-clinical data ingestion layers to capture these metrics.
Industry Challenges
- HIPAA Compliance Architecture:Cloud migration requires re-engineering audit trails and access controls that were designed for on-premise perimeter security. Encryption key management across hybrid environments introduces operational complexity.
- Interoperability Talent Scarcity:FHIR implementation expertise and API security engineering command premium compensation. Payers compete with technology vendors and provider systems for limited specialist pools.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Healthcare Payer Solution Market |
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $101.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Claims Management, Revenue Cycle Management, Fraud Detection, Analytics Tools Technology: Cloud-Based, On-Premise, Artificial Intelligence, Blockchain Deployment: Hybrid, Public Cloud, Private Cloud, Mobile Application End User: Insurance Providers, Third-Party Administrators, Self-Insured Employers, Healthcare Networks |
| Companies Covered | Accenture plc, Cognizant Technology Solutions, Tata Consultancy Services Limited, Infosys Limited, UnitedHealth Group Inc., Xerox Corporation, HCL Technologies Ltd., Wipro Limited, Change Healthcare Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Healthcare Payer Solution Market Strategic Shifts
Real-time data exchange requirements and algorithmic decision-making are compressing development cycles across payer technology stacks. Vendors race to embed predictive capabilities before regulatory frameworks solidify.
Containerized microservices architectures are displacing monolithic claims administration suites. Medicare Advantage entrants without COBOL legacy adopt Kubernetes-orchestrated eligibility engines that deploy updates in hours rather than months. This technical foundation enables continuous compliance adaptation as state prior authorization rules evolve.
FDA oversight of clinical decision support algorithms is tightening validation requirements for AI-driven prior authorization tools. Payers deploying machine learning for utilization management must document training data provenance and algorithmic fairness metrics. The affected segment spans national carriers with automated denial workflows that now require human-in-the-loop redesigns.
Consolidated vendor relationships are replacing best-of-breed procurement patterns among mid-market Blues plans. Single-platform contracts with modular analytics add-ons displace point solutions for fraud detection and network management. This concentration is most visible in southeastern states where regional plans seek operational simplicity over functional depth.
Healthcare Payer Solution Market Segmentation
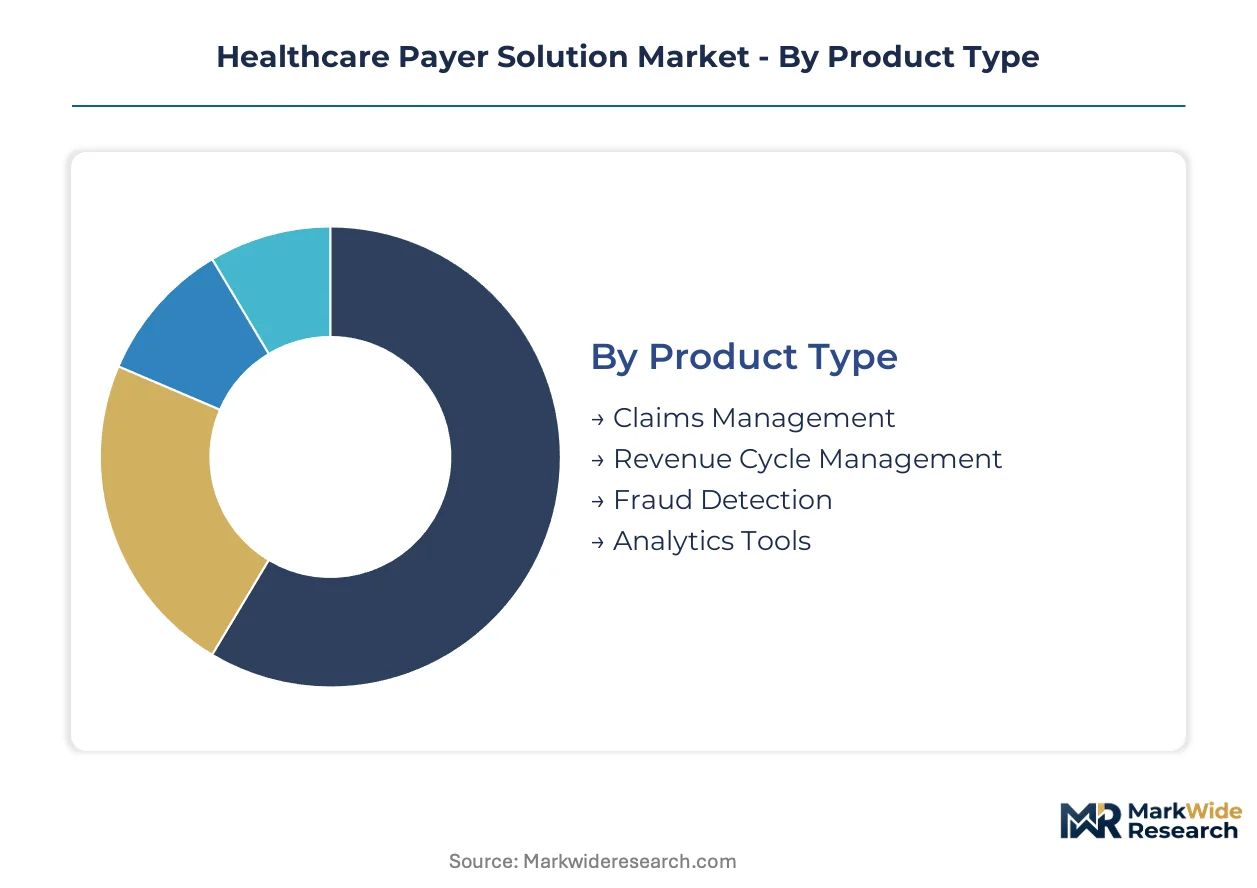
Segmentation reveals how technology maturity and regulatory pressure split demand across payer archetypes. Cloud-native entrants pursue fundamentally different procurement patterns than legacy carriers managing mainframe migration.
Product Type:
Domestic demand concentrates in platforms serving Medicare Advantage and Medicaid managed care contracts, while export opportunity sits with modular fraud detection tools licensed to international insurers.
- Claims Management:Core platforms process eligibility verification and adjudication cycles within 24-48 hour windows. United States commercial payers and Medicare Advantage plans anchor installed base expansion as batch-to-real-time conversion accelerates under CMS interoperability mandates.
- Fraud Detection:Machine learning modules identify synthetic identity schemes and phantom provider billing patterns. United States payers divert disproportionate capital here as fraud losses compound, though this diverts resources from core modernization.
- Revenue Cycle Management:Integrates member billing, premium collection, and accounts receivable workflows for insurance providers.
- Analytics Tools:Risk stratification and predictive utilization engines support value-based reimbursement models.
Claims Management holds the largest share; momentum sits with Fraud Detection.
Technology:
Cost tier separation is pronounced: cloud-native stacks command premium pricing for speed-to-deploy, while on-premise retention reflects compliance-driven risk aversion among national carriers.
- Cloud-Based:Kubernetes-orchestrated microservices enable continuous deployment of eligibility engines and API gateways. Medicare Advantage entrants without COBOL legacy adopt these stacks fastest, bypassing nine-figure migration burdens that plague established payers.
- Artificial Intelligence:Clinical decision support algorithms automate prior authorization decisions. FDA oversight tightens validation requirements, forcing human-in-the-loop redesigns for carriers with automated denial workflows.
- On-Premise:COBOL-dependent core systems persist among large national plans facing specialized talent scarcity.
- Blockchain:Distributed ledger pilots target provider credentialing and cross-payer identity verification.
Cloud-Based platforms dominate new procurement; Artificial Intelligence is expanding most quickly as utilization management automation matures.
Deployment:
Application criticality drives architecture choice: claims adjudication demands private cloud or hybrid for HIPAA audit trail control, while member-facing tools migrate to public cloud for elasticity.
- Hybrid:Split architectures segregate sensitive member data in private environments while exposing FHIR APIs through public cloud gateways. United States regional Blues plans favor this model to satisfy state insurance commissioners while containing capital expenditure.
- Private Cloud:Dedicated infrastructure hosts core administration systems for payers with strict data residency requirements.
- Public Cloud:Elastic compute supports analytics workloads and development environments.
- Mobile Application:Member-facing portals deliver real-time claims status and digital ID cards.
Hybrid deployments capture the largest share; Public Cloud is climbing the fastest among insurtech entrants.
End User:
Customer type determines platform complexity: national carriers need enterprise-scale integration, while self-insured employers prioritize plug-and-play modules with minimal IT overhead.
- Insurance Providers:Commercial carriers and Medicare Advantage plans operate the most complex technology stacks. These entities face simultaneous pressure from CMS interoperability deadlines, state prior authorization reforms, and synthetic identity fraud proliferation.
- Third-Party Administrators:TPAs serving self-insured employers aggregate multiple client configurations on shared infrastructure. Demand concentrates in southeastern United States where regional plans seek operational simplicity through consolidated vendor relationships.
- Self-Insured Employers:Large corporations administer benefits directly, procuring modular solutions for eligibility and claims oversight.
- Healthcare Networks:Integrated delivery systems with captive insurance functions require payer-provider interoperability.
Insurance Providers command the largest share; Third-Party Administrators are gaining share fastest as employer-sponsored plan administration outsources.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply between the United States, where Medicare Advantage modernization drives cloud-first procurement, and offshore delivery hubs in India that sustain cost-competitive service layers for mid-market payers. European markets favor hybrid architectures under GDPR constraints, while Asia-Pacific adoption clusters around modular fraud detection licensing.
United States
Commercial carriers and Medicare Advantage plans anchor demand for real-time adjudication platforms and FHIR-compliant API gateways. CMS interoperability mandates under the 21st Century Cures Act force batch-to-real-time conversion deadlines that concentrate investment in California, New York, and Texas health plan technology stacks.
India
Offshore delivery centers in Bangalore and Hyderabad sustain cost advantages for claims processing and eligibility verification outsourcing. The country's IT services sector captures multi-year modernization contracts from mid-market Blues plans seeking to bypass mainframe migration burdens through remote managed services.
United Kingdom
NHS Digital interoperability frameworks and GDPR-compliant data residency requirements shape procurement for private health insurers. London-based insurtech entrants adopt cloud-native member engagement platforms that bypass the technical debt accumulated by legacy mutual insurers.
Germany
Statutory health insurance funds (Gesetzliche Krankenversicherung) modernize core administration under EU AI Act compliance pressures. Munich and Berlin clusters host regional technology partnerships that embed predictive analytics into utilization management workflows.
Canada
Provincial health authority procurement favors hybrid cloud deployments that satisfy Health Canada data sovereignty requirements. Ontario and British Columbia health plans invest in fraud detection modules as synthetic identity schemes exploit gaps between provincial eligibility systems.
Healthcare Payer Solution Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier that serves discrete functional domains. The upper tier combines payer operations with captive technology development, while specialists concentrate on modular claims administration or offshore delivery scale. Three archetypes dominate: vertically integrated health plan technology stacks, IT services vendors with healthcare vertical specialization, and standalone health information technology platforms. Competitive moves center on consolidated vendor relationships replacing best-of-breed procurement, and strategic partnerships between regional Blues plans and modular modernization providers.
Within the integrated tier, UnitedHealth Group Inc. exemplifies vertical control over both payer operations and technology infrastructure. Cognizant Technology Solutions and Tata Consultancy Services Limited occupy positions as anchor IT services providers, with the former representing deep R&D partnership models and the latter exemplifying offshore delivery scale for cost-sensitive payers.
| Leading Market Players |
|---|
| Accenture plc |
| Cognizant Technology Solutions |
| Tata Consultancy Services Limited |
| Infosys Limited |
| UnitedHealth Group Inc. |
| Xerox Corporation |
| HCL Technologies Ltd. |
| Wipro Limited |
| Change Healthcare Inc. |
| Others |
Value Chain & Pricing Dynamics
Cloud-native microservices replacing COBOL-dependent mainframe stacks simultaneously redraws supply geography toward India and Eastern European delivery centers while compressing pricing premiums for real-time adjudication platforms. This substitution dynamic forces legacy-dependent national carriers to absorb nine-figure migration costs while Medicare Advantage entrants capture first-mover pricing advantages through SaaS procurement models.
Pricing Analysis
Implementation services and multi-year managed support contracts drive lifetime value beyond initial software licensing. Subscription-based SaaS tiers dominate new procurement, with pricing differentiation hinging on FHIR compliance certification levels and customization depth for state-specific prior authorization workflows. Cost compression in implementation services is intensifying because offshore delivery centers compete aggressively for mid-market Blues modernization contracts. Third-party administrators exhibit highest price sensitivity due to thin margins on employer-sponsored plan administration, while vertically integrated national carriers prioritize compliance-grade solutions over cost minimization.
Supply Chain Analysis
India and Poland anchor offshore software development and claims processing operations for North American and European payers respectively. The supply chain draws from specialized FHIR implementation expertise, Kubernetes orchestration talent, and HIPAA-compliant cloud infrastructure. Single-source vulnerability concentrates in legacy COBOL maintenance talent pools that shrink annually as specialized practitioners retire. Distribution runs through direct enterprise sales for national carriers and channel partnerships with systems integrators for mid-market regional plans.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as regional Blues plans consolidate vendor relationships and abandon best-of-breed procurement patterns. This consolidation among mid-market payers shifts negotiation leverage toward integrated platform providers capable of delivering modular modernization paths.
For Market Incumbents: Fortify proprietary AI-driven utilization management engines through FDA-aligned validation investments that preempt regulatory liability shifts to third-party vendors. Deepen captive cloud infrastructure capabilities to reduce dependency on hyperscaler pricing volatility. Anchor position through exclusive R&D partnerships with Medicare Advantage entrants lacking legacy technical debt. For New Entrants and Emerging Players: Lead with containerized microservices architectures targeting Medicaid expansion states requiring rapid eligibility platform deployment without mainframe migration burden. Capture share in southeastern United States where regional plans prioritize operational simplicity over functional depth. Establish go-to-market presence through TPA channel partnerships rather than direct national carrier sales cycles. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed claims administration specialists holding sticky installed bases among commercial payers facing CMS interoperability deadlines. Long-term viability hinges on successful batch-to-real-time platform conversion without client attrition. Watch FHIR implementation talent acquisition rates as inflection indicator for execution capability gaps.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Consolidated vendor relationships displace point solutions across regional Blues plans seeking workflow simplicity. |
| Strategic Partnership | Deep R&D collaborations with Medicare Advantage entrants accelerate cloud-first stack adoption without legacy burden. |
| Acquisition of Specialist Firm | AI-driven utilization management engines address FDA oversight tightening on clinical decision support algorithms. |
| Geographic Expansion | Medicaid expansion states require modern eligibility platforms as new managed care contracts come to market. |
| Product Launch | FHIR-compliant API gateways satisfy CMS interoperability mandates under 21st Century Cures Act deadlines. |
Study Parameters
Two parallel data streams informed the analysis: primary interviews with payer technology executives, CMS policy specialists, and health plan procurement directors; and secondary validation through hospital procurement databases, GPO contracts, and CMS Medicare Advantage enrollment filings. Bottom-up triangulation across payer segment technology budgets and top-down reconciliation against vendor revenue disclosures anchored market sizing.
Across the projection horizon, the analytical framework modeled deployment architecture, payer archetype, and regulatory compliance tier as core segmentation dimensions. CAGRs were derived from technology investment trajectories mapped against CMS mandate deadlines and Medicare Advantage enrollment curves. Forecast inputs incorporated state prior authorization reform timelines and synthetic identity fraud loss rates.
Forecasts assume regulatory continuity in CMS interoperability rulemaking and FDA AI oversight frameworks; material policy shifts would require re-modeling. Specific risk factors include mainframe talent pool collapse accelerating migration cost inflation and state regulatory fragmentation multiplying compliance overhead. Recalibration cycles align with material shifts in Medicare Advantage enrollment velocity and CMS deadline enforcement patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Health Insurance
UAE Health Insurance Market
Health Insurance
Healthcare Insurance Market
Health Insurance
Health Insurance Market
Health Insurance
United States Health and Medical Insurance Market
Health Insurance
UAE Health Insurance Third Party Administrators (TPA) Market
Health Insurance
Healthcare Payer Services Market
Health Insurance
US Group Health Insurance Market
Health Insurance
Healthcare Reimbursement Market
Health Insurance
UAE Health and Medical Insurance Market
Health Insurance
North America Group Health Insurance Market
Health Insurance
Indonesia Health and Medical Insurance Market
Health Insurance
US Healthcare Discount Plan Market
Health Insurance
Germany Health Insurance Market