
 North America Group Health Insurance Market | 2026-2036
North America Group Health Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
North America Group Health Insurance Market Analytics
Employer consolidation in the mid-market segment is realigning purchasing power toward larger broker networks and administrative platforms. UnitedHealth Group leverages its Optum care delivery arm to anchor integrated medical and pharmacy benefit designs. Elevance Health competes through regional Blue Cross Blue Association partnerships that sustain state-level provider network density. CVS Health controls retail clinic access points that differentiate its Aetna book with proximity-based primary care.
North America group health insurance constitutes employer-sponsored medical coverage pooled across employee populations, typically underwritten through experience-rated or community-rated methodologies with actuarial reserves held against incurred but not reported claims. Its commercial purpose centers on risk-pooling efficiency that reduces per-capita premium volatility while satisfying IRS Section 105 and ERISA fiduciary standards for tax-advantaged benefits. PPO plans retain dominant enrollment share due to out-of-network flexibility that commands premium tolerance from large corporations, while self-funded arrangements are expanding fastest among employers with over one thousand lives as they capture direct savings from claims data transparency. HMO products occupy mature growth corridors where Kaiser Permanente's closed-system model limits competitor network replication.
The Affordable Care Act, ERISA, and state insurance department reserving requirements shape product design, rate filing timelines, and stop-loss attachment points across US jurisdictions. Canada's provincial health frameworks and US state-level benchmark plan standards create divergent compliance burdens for carriers operating cross-border employer contracts. Stakeholders must monitor Medicare buy-in proposals and state public option legislation that could redirect large employer migration patterns toward government-sponsored alternatives.
Market Dynamics
Self-funded plan administration is concentrating purchasing power among large employers seeking direct claims data transparency, while mid-sized employers face escalating compliance burdens under Affordable Care Act employer mandates that reshape broker network dependencies.
Growth Catalysts
- Affordable Care Act employer provisions:Mid-sized manufacturing and professional services employers across Texas, California, and Illinois are expanding coverage mandates, pooling risk across larger employee populations and stabilizing premium volatility.
- Experience-rated underwriting methodologies:Large corporations with over one thousand covered lives are capturing direct savings through claims data transparency, accelerating migration from fully-insured arrangements.
- Retail clinic access point expansion:Proximity-based primary care integration is differentiating plan designs through geographic density of convenient care locations in urban corridors.
Market Restraints
- Stop-loss attachment point volatility:State insurance department reserving requirements create unpredictable capital thresholds for self-funded arrangements, compressing margin predictability for smaller plan sponsors.
- Provider network replication barriers:Closed-system HMO models in mature growth corridors limit competitor network density, constraining plan design flexibility outside dominant regional systems.
- Cross-border compliance fragmentation:Divergent US state-level benchmark plan standards and Canadian provincial health frameworks create administrative friction for carriers operating multi-jurisdictional employer contracts.
Strategic Opportunities
- Medicare buy-in proposal monitoring:Large employer migration patterns toward government-sponsored alternatives represent white-space positioning for hybrid public-private plan architectures.
- State public option legislation:Emerging regulatory tailwinds in progressive jurisdictions are creating new competitive entry points for carriers with Medicaid administrative infrastructure.
- Telehealth-mental health convergence:Virtual care platform integration with employee assistance programs is opening underserved behavioral health access corridors in rural and exurban geographies.
Industry Challenges
- ERISA fiduciary litigation exposure:Plan sponsors face escalating class-action risk over pharmacy benefit manager fee transparency and formulary design governance.
- Legacy claims platform modernization:Core administrative system replacement timelines stretch 18-36 months, delaying real-time analytics deployment and member engagement tool integration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Group Health Insurance Market |
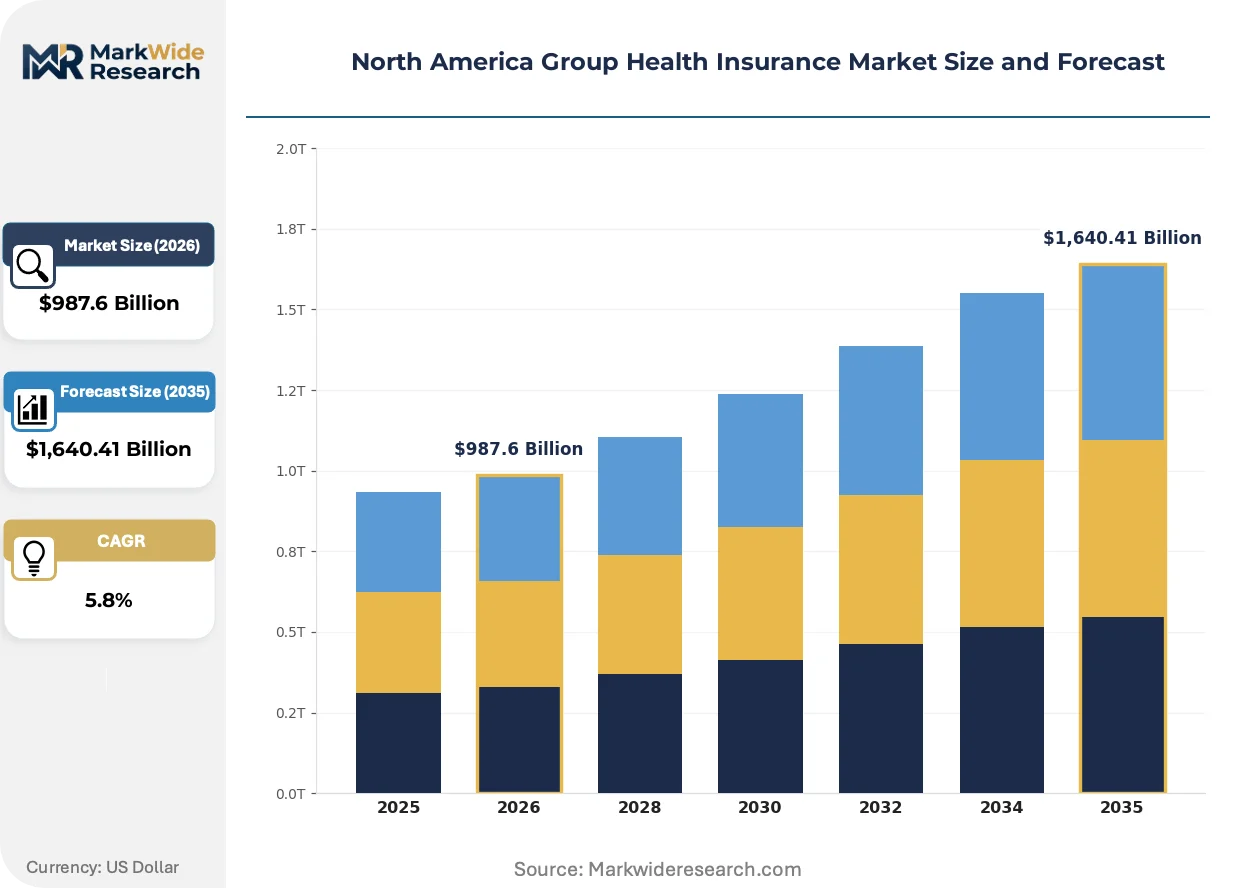
| Market Size in 2026 | $987.6 Billion |
| Market Size in 2035 | $1,640.41 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Plan Type: HMO, PPO, EPO, POS Coverage Type: Comprehensive, Catastrophic, Short-term, Supplemental Employer Size: Small Business, Medium Enterprise, Large Corporation, Startups Service Model: Fully Funded, Self-Funded, ASO, Union |
| Companies Covered | UnitedHealth Group, Elevance Health, CVS Health, Kaiser Permanente, Centene Corporation, Humana, Health Care Service Corporation, Cigna, Molina Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Group Health Insurance Market Evolving Landscape
Digital health infrastructure is actively redistributing care delivery away from traditional facility-based models, while regulatory pressure on price transparency and data interoperability forces architectural redesign of benefit administration platforms.
Virtual primary care platforms are decentralizing traditional payer-provider relationships by embedding asynchronous messaging and remote patient monitoring directly into employer-sponsored benefit designs. Mid-market employers with 500-2,000 covered lives are adopting these tools fastest, compressing traditional primary care visit volumes and redirecting utilization toward lower-acuity digital touchpoints.
IRS Section 105 and ERISA fiduciary standards are tightening documentation requirements for tax-advantaged health benefit arrangements, forcing plan sponsors to upgrade governance frameworks. Self-funded employers in California and New York are responding with dedicated compliance officer roles and third-party fiduciary insurance products.
Broker consolidation is compressing distribution channel diversity as mid-sized employers consolidate purchasing through larger advisory networks. Traditional independent agents in the Midwest and Southeast are losing share to national platforms that bundle benefits administration with HR technology, shifting commission structures toward per-employee-per-month fees rather than percentage-of-premium arrangements.
North America Group Health Insurance Market Segmentation
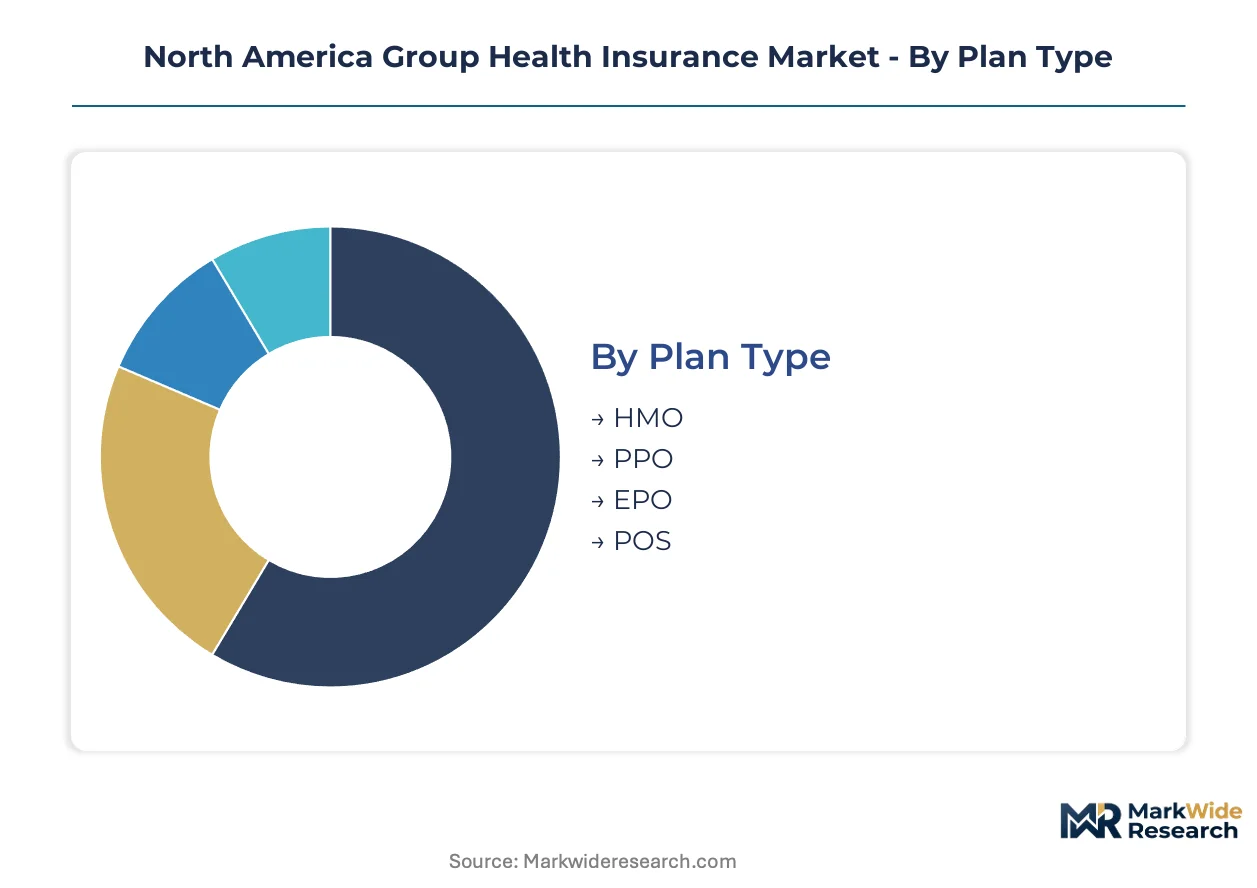
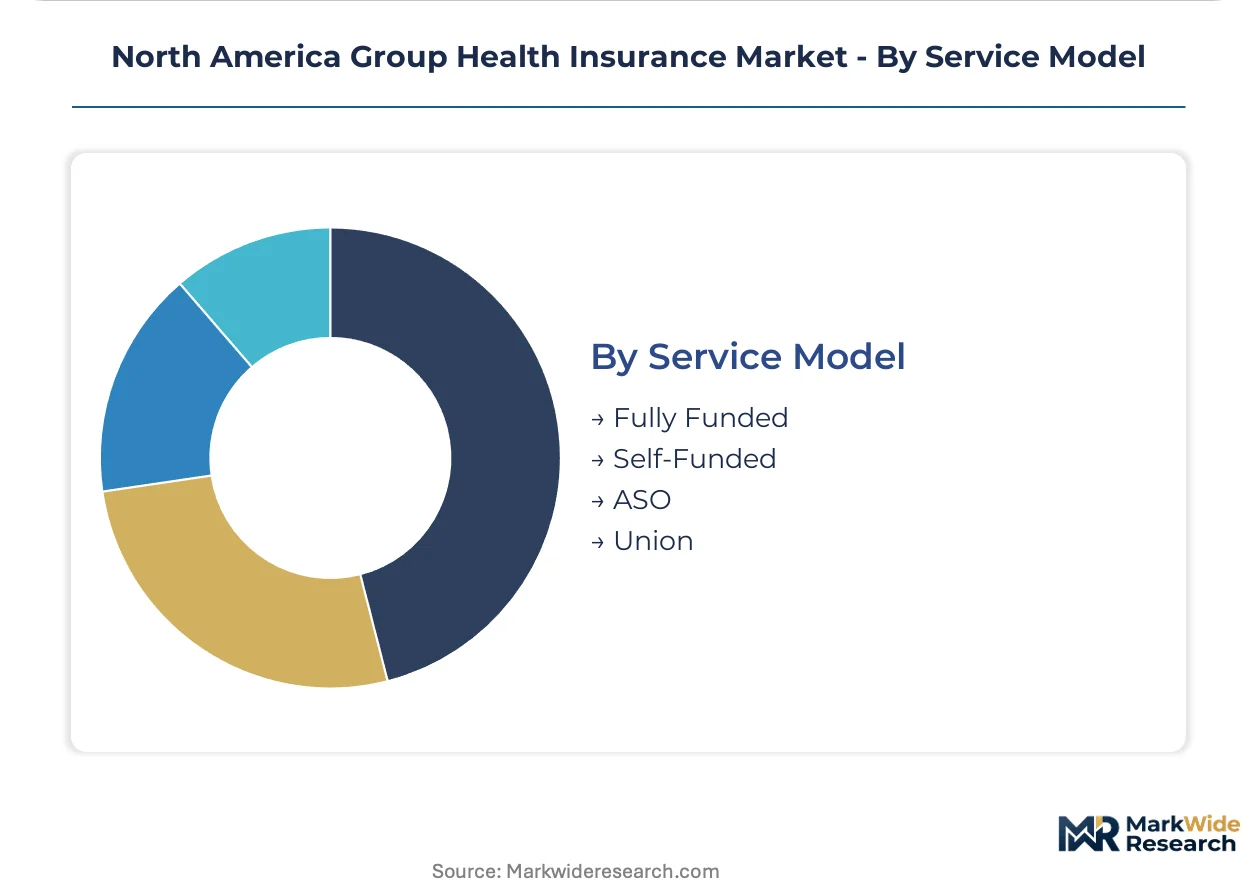
Group health insurance product architecture fragments across four structural dimensions that determine underwriting methodology, regulatory jurisdiction, and administrative cost allocation. Each segmentation axis carries distinct margin profiles and carrier capability requirements that shape competitive positioning.
Plan Type:
Customization intensity varies from closed-system gatekeeping to open-access flexibility, with network density and member cost-sharing calibrated to each model's administrative complexity.
- PPO:Preferred provider organization designs combine in-network discounts with out-of-network reimbursement rights, requiring broad provider contracting infrastructure. Demand concentrates among large corporations in Texas and California where employee populations value specialist choice without referral requirements, though premium tolerance is narrowing as cost-sharing escalates.
- HMO:Health maintenance organization products gate specialist access through primary care physician assignment, lowering per-member administrative costs through capitated reimbursement structures. Kaiser Permanente's closed-system model dominates California and Pacific Northwest corridors where integrated delivery infrastructure limits competitor network replication.
- EPO:Exclusive provider organization plans blend HMO-style network restrictions with PPO-like direct specialist access, eliminating out-of-network coverage entirely.
- POS:Point of service products layer HMO gatekeeping with optional out-of-network benefits at elevated cost-sharing tiers, appealing to mid-sized employers seeking hybrid flexibility.
Most installed capacity flows through PPO arrangements. Expansion is steepest in EPO configurations as employers seek premium relief without full HMO conversion.
Coverage Type:
Risk retention levels stratify from first-dollar coverage to catastrophic-only designs, with employer cost-sharing philosophy and IRS affordability standards driving selection patterns.
- Comprehensive:Broad benefit packages spanning preventive, acute, and chronic care with prescription drug integration and behavioral health parity compliance. Small business demand clusters in Illinois and New York where state benchmark plan standards mandate minimum essential coverage thresholds, though premium compression is forcing deductible escalation.
- Catastrophic:High-deductible designs paired with health savings account eligibility, covering essential health benefits only after substantial out-of-pocket spending. Startups and gig-economy employers in Florida and Texas are adopting these fastest to satisfy ACA employer mandates while capping premium exposure.
- Short-term:Limited-duration coverage bridging employment gaps or waiting periods, exempt from ACA market reforms and essential health benefit requirements.
- Supplemental:Ancillary products covering dental, vision, accident, or critical illness through voluntary payroll deduction or employer contribution.
Comprehensive coverage retains dominant enrollment share. Supplemental products are climbing the fastest as employers unbundle core medical to manage rate shock.
Employer Size:
Purchasing sophistication and regulatory exposure scale with covered life count, determining whether experience-rated underwriting or community-rated pooling applies.
- Large Corporation:Employers with over one thousand covered lives command direct claims data access and custom network carve-outs, accelerating self-funded migration. Manufacturing concentrations in Michigan and Ohio leverage scale to negotiate hospital system discounts and pharmacy benefit manager pass-through pricing.
- Medium Enterprise:Mid-sized employers with 100-999 lives face the steepest ACA compliance burden, balancing affordability safe harbor requirements against workforce retention needs.
- Small Business:Firms with under 50 full-time equivalents access SHOP exchange subsidies and community-rated pooling in most states, though broker dependency is high.
- Startups:Early-stage companies with volatile headcount leverage professional employer organizations or level-funded products to outsource benefits administration and compliance.
Large corporations command disproportionate carrier attention. Startups represent the most volatile expansion corridor as venture funding cycles dictate benefit generosity.
Service Model:
Financial risk transfer arrangements range from full carrier assumption to complete employer retention, with stop-loss markets and administrative service only platforms occupying intermediate positions.
- Self-Funded:Employers retain claim liability directly, purchasing stop-loss coverage for catastrophic individual and aggregate exposure. Concentration is heaviest in California, Texas, and Illinois where large corporations capture pharmacy rebate transparency and claims data analytics unavailable under fully-insured arrangements.
- Fully Funded:Traditional insurance transfers all claim risk to carriers in exchange for fixed premium, appealing to risk-averse small and mid-sized employers.
- ASO:Administrative services only contracts allow self-funded employers to license carrier networks and claims platforms without risk transfer, common among union trusts and municipal plans.
- Union:Taft-Hartley multiemployer plans pool contributions across participating employers in construction, trucking, and hospitality industries, governed by joint labor-management committees.
Most premium volume still flows through fully-funded arrangements. Self-funded penetration is gaining share fastest as stop-loss markets deepen and pharmacy cost transparency pressures mount.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canada's provincial health frameworks diverge sharply from US employer-sponsored models, creating distinct compliance architectures for cross-border carriers. Mexico's nascent private insurance segment offers expansion corridors as manufacturing foreign direct investment deepens.
United States
Self-funded plan administration concentrates in Texas, California, and Illinois where large corporations capture pharmacy rebate transparency. ERISA fiduciary standards and IRS Section 105 requirements shape tax-advantaged benefit governance. Michigan and Ohio manufacturing clusters leverage scale to negotiate hospital system discounts and pass-through pharmacy benefit manager pricing.
Canada
Provincial health frameworks create divergent compliance burdens for carriers operating cross-border employer contracts. Health Canada regulates supplementary private coverage while provincial authorities administer primary care. Ontario and Quebec employer groups drive demand for extended health benefits that bridge public system gaps.
Mexico
Manufacturing foreign direct investment in Nuevo León and Jalisco is expanding expatriate and local executive coverage mandates. The country's national insurance regulator supervises solvency requirements for private health carriers. Mexico City Metro anchors administrative infrastructure for multinational employer contracts.
North America Group Health Insurance Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Consolidation patterns favor integrated medical-pharmacy platforms and closed-system delivery models. Three archetypes dominate: vertically integrated care delivery organizations, regional Blue Cross Blue Association affiliates, and retail clinic network operators. M&A activity targets administrative service platforms and specialty pharmacy capabilities.
Within the integrated delivery tier, UnitedHealth Group and Kaiser Permanente exemplify distinct risk-bearing models. UnitedHealth leverages its Optum care delivery arm for medical-pharmacy benefit integration. Kaiser Permanente occupies a closed-system position in California and Pacific Northwest corridors where network replication barriers limit competitor entry.
| Leading Market Players |
|---|
| UnitedHealth Group |
| Elevance Health |
| CVS Health |
| Kaiser Permanente |
| Centene Corporation |
| Humana |
| Health Care Service Corporation |
| Cigna |
| Molina Healthcare |
| Others |
Value Network & Pricing Analysis
Medical cost inflation indices published by CMS cascade through employer-sponsored benefit structures, compressing premium tolerance at the mid-market tier while amplifying price differentiation between self-funded and fully-insured arrangements. Carrier pricing power concentrates in states with limited provider network competition, where hospital system consolidation amplifies negotiated rate disparities.
Pricing Analysis
Capacity additions in Texas and California among alternative primary care networks are reshaping price floors for comprehensive PPO designs, forcing legacy carriers to unbundle administrative fees from medical trend assumptions. Three-tier pricing structure across premium, standard, and economy levels reflects employer size stratification and stop-loss attachment point selection, with quality grade differentiation tied to provider network density and care coordination intensity. Pricing pressure stems from pharmacy benefit manager rebate transparency mandates, compressing margin predictability for smaller plan sponsors. Startups and gig-economy employers exhibit highest price sensitivity, while large manufacturing clusters in Michigan demonstrate lowest sensitivity due to scale-negotiated hospital system discounts.
Supply Chain Analysis
Direct-to-employer channels handle hyperscale buyer demand from corporations with over one thousand covered lives, while broker-consolidated distribution manages mid-market access. Geographic supply concentration clusters in California, Texas, and Illinois where large self-funded employers capture claims data transparency unavailable elsewhere. Raw material dependencies center on pharmaceutical formularies, specialty physician networks, and stop-loss reinsurance capacity. Supply chain risk hinges on single-source vulnerability among dominant hospital systems in closed-market geographies. Distribution runs through national administrative service platforms that bundle benefits technology with compliance outsourcing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Employer migration toward self-funded arrangements creates geographic-arbitrage opportunities across state regulatory regimes, with Texas and Florida offering lower stop-loss capital requirements than California and New York.
For Market Incumbents: To counter pharmacy benefit manager fee transparency litigation, UnitedHealth Group and Elevance Health should deepen backward integration into specialty pharmacy fulfillment and deploy dedicated fiduciary compliance infrastructure in California and New York. Carrier investment in real-time claims analytics platforms represents the critical capability gap separating market leaders from regional affiliates. For New Entrants and Emerging Players: Begin with level-funded product architectures targeting mid-sized employers with 100-500 covered lives in Illinois and Ohio manufacturing corridors, where ACA compliance burden exceeds broker advisory capacity. White-space concentration sits in telehealth-mental health convergence products for rural and exurban geographies underserved by traditional EAP vendors. Go-to-market execution should anchor in professional employer organization partnerships that outsource administrative complexity. For Investors and Strategic Acquirers: Asymmetric upside sits with administrative service platforms possessing Medicaid infrastructure adaptable to state public option legislation. Long-term viability favors targets with stop-loss underwriting licenses and proprietary provider network density in single-state markets. Monitor Medicare buy-in proposal advancement in progressive jurisdictions as the signal indicating large employer migration timing toward hybrid public-private architectures.| Strategic Initiative | Industry Significance |
|---|---|
| Self-Funded Platform Expansion | Captures pharmacy rebate transparency unavailable under fully-insured arrangements in Texas and California. |
| Telehealth-Mental Health Integration | Opens behavioral health access corridors in rural geographies beyond traditional EAP network reach. |
| State Public Option Infrastructure | Leverages Medicaid administrative capabilities for emerging progressive jurisdiction legislation. |
| Specialty Pharmacy Backward Integration | Controls formulary design governance against escalating ERISA fiduciary litigation exposure. |
| Real-Time Claims Analytics Deployment | Compresses legacy platform replacement timelines for mid-market employer competitive positioning. |
Research Methodology
Bottom-up employer size modeling reconciled against top-down carrier premium tracking forms the analytical core of this study. Primary interviews with benefits consultants, self-funded plan administrators, pharmacy benefit manager contract negotiators, and ERISA compliance officers combined with secondary validation from CMS Medicare cost reports, state insurance department rate filings, and hospital system chargemaster disclosures. Triangulation across these sources anchors segmentation-specific growth assumptions.
Input-output matrices map employer premium expenditure to carrier administrative cost allocation across the projection horizon, with segmentation dimensions spanning plan type, coverage intensity, employer size tier, and service model architecture. CAGRs derive from experience-rated underwriting migration patterns and stop-loss market depth trajectories. Forecast inputs incorporate ACA employer mandate enforcement variability and state-level benchmark plan standard evolution.
Several conditions sit outside the modeled scope, including federal Medicare buy-in legislation passage and Canadian provincial health framework harmonization. Forecasts reflect base-case assumptions regarding medical cost trend stability and stop-loss reinsurance capacity availability. Periodic stress-testing of base assumptions is recommended given regulatory and litigation environment volatility.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Health Insurance
United States Health and Medical Insurance Market
Health Insurance
Health Insurance Market
Health Insurance
US Healthcare Discount Plan Market
Health Insurance
UAE Health Insurance Third Party Administrators (TPA) Market
Health Insurance
Healthcare Payer Solution Market
Health Insurance
UAE Health Insurance Market
Health Insurance
Healthcare Reimbursement Market
Health Insurance
US Group Health Insurance Market
Health Insurance
Germany Health Insurance Market
Health Insurance
Healthcare Payer Services Market
Health Insurance
UAE Health and Medical Insurance Market
Health Insurance
Healthcare Insurance Market
Health Insurance
Indonesia Health and Medical Insurance Market