
 River Cruises Market | 2026-2036
River Cruises Market Size, Share, and Industry Trends Forecast 2026-2036
River Cruises Market Analytics
European shipyard orderbooks for shallow-draft river vessels is hardening as operators replace aging tonnage ahead of stricter environmental rules. Viking River Cruises dominates Northern European route networks with one of the largest purpose-built fleets on the Rhine and Main. AmaWaterways differentiates through culinary-focused programming that anchors its premium positioning in the Douro and Mekong basins. Tauck sustains brand loyalty via all-inclusive pricing and dedicated tour director staffing on every departure.
River cruises entail shallow-draft passenger vessels purpose-built for inland waterways, typically measuring 110-135 meters in length with drafts under 1.8 meters to clear locks and bridges, designed for multi-day itineraries combining transportation, accommodation, and destination immersion. The primary commercial purpose centers on converting ocean-cruise-averse travelers into repeat purchasers through intimate scale and port-proximate docking. Luxury cruise type commands the deepest margin pools due to bundled shore excursions and balcony-heavy cabin mixes. Solo traveler demand is expanding fastest as operators reduce or waive single supplements to fill shoulder-season capacity. Cultural itinerary focus occupies the largest share as heritage-rich routes through the Rhine Gorge and Wachau Valley attract repeat visitation.
The EU Green Deal and its F-Gas Regulation are forcing engine retrofits and shore-power compatibility investments that reshape fleet economics and deployment decisions. The International Maritime Organization's greenhouse gas strategy for domestic vessels adds compliance layers for operators running cross-border itineraries. National regulators along the Danube, including Germany's Federal Maritime and Hydrographic Agency and Austria's waterway administration, coordinate lock scheduling and emissions enforcement. Stakeholders must monitor which operators secure priority berthing in Amsterdam and Budapest as port capacity tightens and overnight mooring limits proliferate.
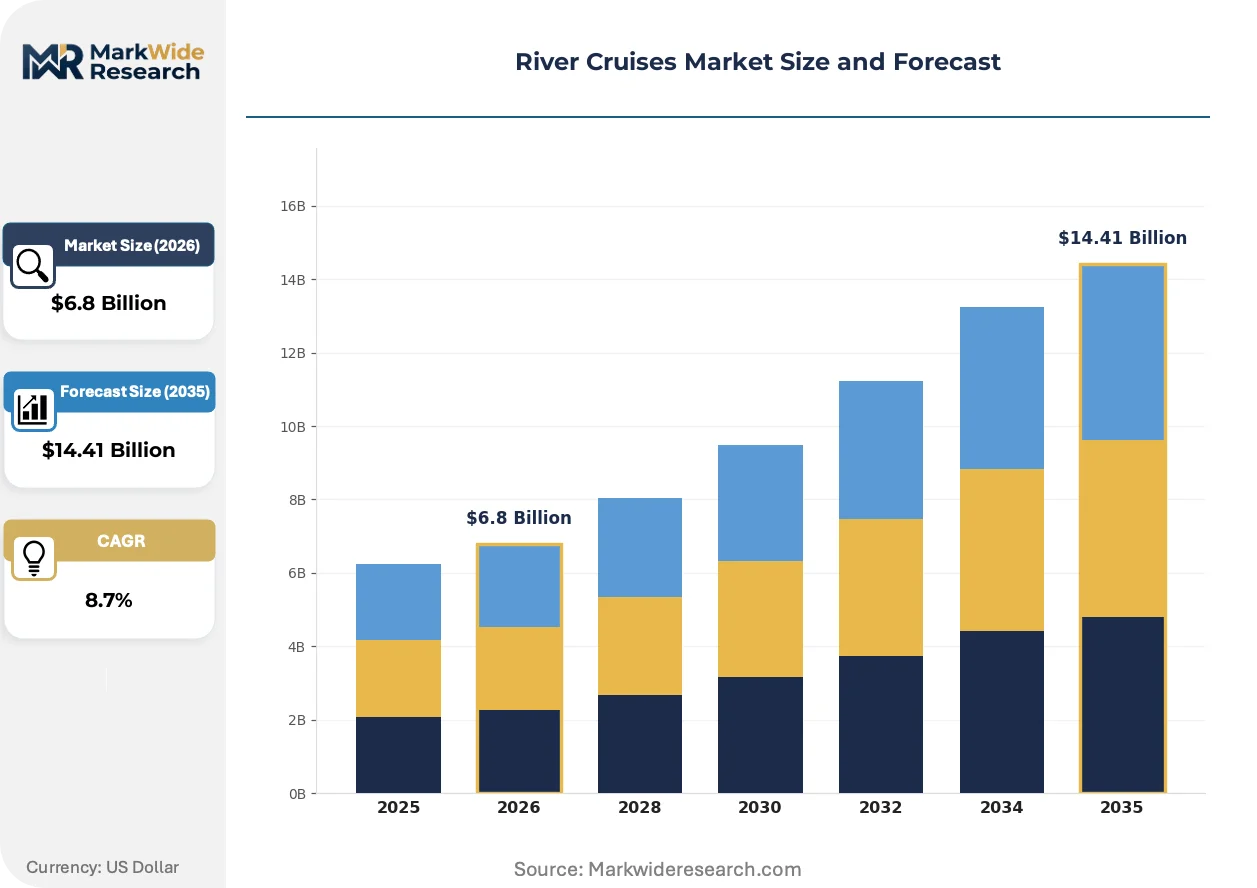
Market Dynamics
The EU Green Deal's F-Gas Regulation is compressing fleet economics as operators face mandatory engine retrofits and shore-power compatibility investments before the next renewal cycle. This regulatory pressure is accelerating capital deployment decisions and reshaping deployment patterns along Europe's inland waterways.
Growth Catalysts
- Hybrid Propulsion Mandates:The EU Green Deal's emissions standards are pulling investment into battery-electric and hydrogen-ready vessel designs. German and Austrian yards report hardening orderbooks as operators replace aging tonnage.
- Affluent Retiree Demographics:Extended European itineraries are capturing repeat purchasers from ocean-cruise-averse travelers seeking intimate scale and port-proximate docking experiences.
- Single Supplement Waivers:Solo traveler demand is expanding fastest as operators reduce or waive single supplements to fill shoulder-season capacity, converting previously uneconomic berths.
Market Restraints
- Lock and Bridge Clearances:Vessel dimensions remain physically constrained by 110-135 meter length limits and sub-1.8 meter draft requirements along the Rhine-Main-Danube corridor.
- Shipyard Capacity Bottlenecks:European yards specializing in shallow-draft river vessels face extended lead times as environmental compliance deadlines concentrate replacement demand.
- Port Berthing Scarcity:Amsterdam and Budapest are tightening overnight mooring limits, forcing operators into costly repositioning or truncated itineraries.
Strategic Opportunities
- Mekong Basin Expansion:Vietnam and Cambodia river segments remain underpenetrated relative to European saturation, offering first-mover positioning for culinary-focused programming.
- Shore Power Infrastructure:EU funding mechanisms for port electrification create regulatory tailwinds for early adopters securing priority berthing at electrified terminals.
- Solo-Optimized Cabins:Purpose-built single-occupancy staterooms without supplement penalties represent untapped cabin-mix innovation for shoulder-season yield management.
Industry Challenges
- Marine Engineering Talent Scarcity:Dual-fuel and battery-hybrid propulsion systems require specialized technicians that European inland waterway labor pools currently lack.
- Cross-Border Certification Complexity:Operators running Germany-Austria-Hungary itineraries face fragmented approval timelines from Germany's Federal Maritime and Hydrographic Agency, Austria's waterway administration, and Hungarian regulators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | River Cruises Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Cruise Type: Luxury, Budget, Expedition, Charter Customer Type: Families, Couples, Seniors, Solo Travelers Onboard Experience: Culinary, Wellness, Entertainment, Culture Itinerary Focus: Cultural, Scenic, Adventure, Historical |
| Companies Covered | Scenic, Tauck, Viking River Cruises, Riverside Luxury Cruises, Emerald Cruises, AmaWaterways, Avalon Waterways, Riviera Travel, Uniworld Boutique River Cruises, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
River Cruises Market Evolving Landscape
Propulsion technology is overtaking cabin amenities as the primary competitive differentiator, with regulatory compliance costs now exceeding interior refurbishment cycles in capital allocation decisions.
Battery-electric hybrid systems are overtaking diesel-electric configurations as the baseline specification for newbuild orders. Premium operators targeting the Danube corridor are specifying hydrogen-ready dual-fuel engines to future-proof against Phase IV emission standards. This technology compression is lengthening design-to-delivery cycles and concentrating procurement among yards with proven hybrid integration experience.
The EU F-Gas Regulation is forcing refrigerant system replacements across existing fleets, with operators facing simultaneous engine retrofit and HVAC overhaul costs. Germany's Federal Maritime and Hydrographic Agency is coordinating lock scheduling priority for compliant vessels, creating operational advantages for early adopters. Luxury segment operators are absorbing these costs through balcony-heavy cabin mixes and bundled shore excursion pricing.
Direct-to-consumer booking platforms are displacing traditional travel advisor channels for repeat purchasers familiar with specific operators. Viking River Cruises and AmaWaterways have invested in proprietary reservation systems capturing guest preference data for personalized pre-cruise upselling. This channel shift is most advanced in the United States and United Kingdom source markets where brand recognition reduces search friction.
River Cruises Market Segmentation
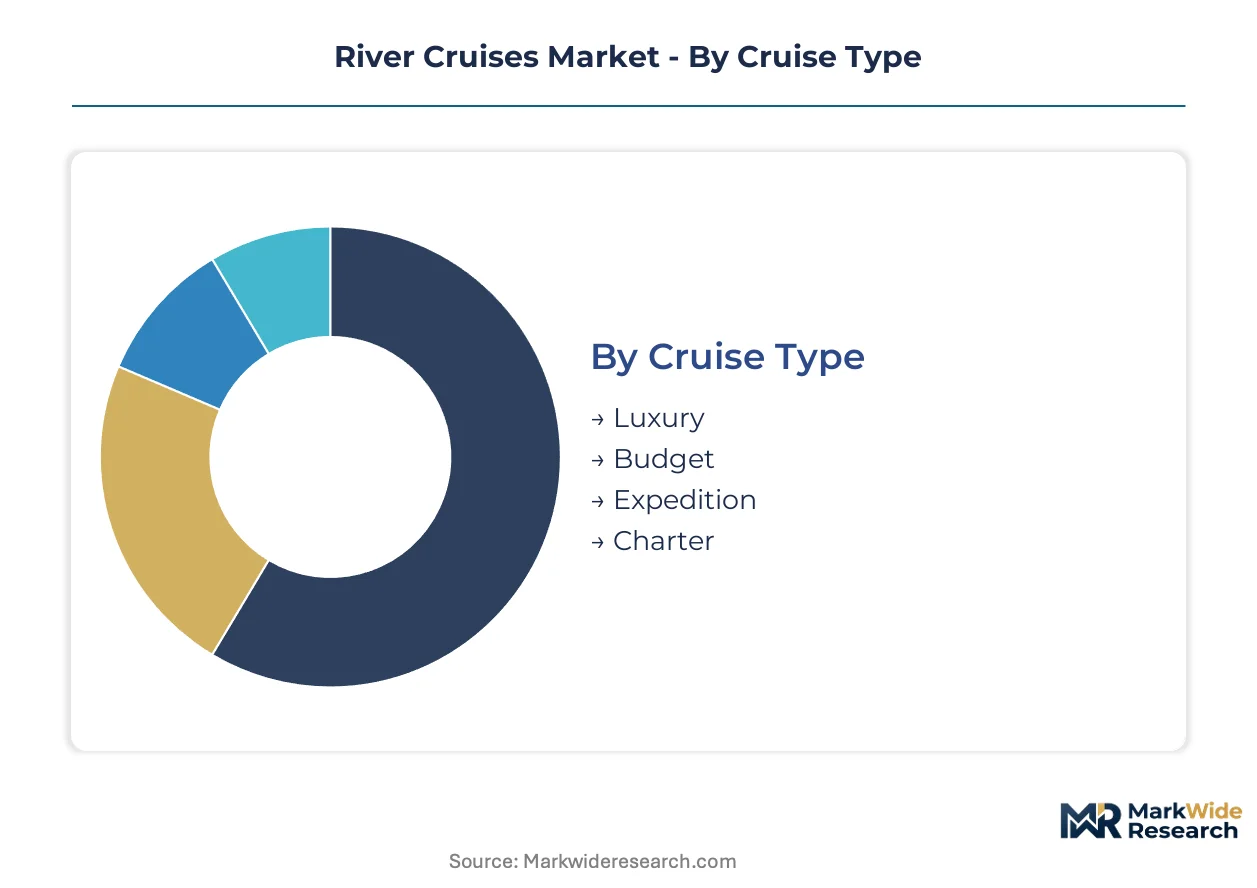
River cruise operators calibrate fleet deployment and cabin mix around four distinct segmentation axes. Each dimension shapes capital allocation decisions, from hull design specifications to shore excursion bundling strategies.
Cruise Type:
Standalone cruise products dominate revenue capture, while embedded charter arrangements serve specialized demand pockets with lower operational overhead.
- Luxury:Vessels feature balcony-heavy cabin mixes exceeding 80% suite ratios with all-inclusive pricing models. Demand concentrates along the Danube corridor through Germany, Austria, and Hungary where affluent retirees seek extended itineraries with bundled shore excursions.
- Budget:Compact staterooms with reduced amenity tiers and à-la-carte pricing structures. This segment absorbs price-sensitive travelers through shorter Rhine-Main rotations and high-berth-density configurations.
- Expedition:Reinforced hulls and Zodiac deployment capabilities for remote waterway access. Demand clusters in Mekong basin segments through Vietnam and Cambodia.
- Charter:Full-vessel bookings for corporate incentives and affinity groups. Operators deploy older tonnage here to preserve premium fleet utilization rates.
Volume placements concentrate in Luxury; the faster expansion belongs to Expedition as operators diversify beyond European saturation.
Customer Type:
Demographic targeting determines shoulder-season yield tactics and single-supplement policies across fleet deployment cycles.
- Families:Multi-generational stateroom configurations with adjoining cabin options and supervised activity programming. School holiday calendars dictate fleet positioning on shorter, port-intensive itineraries.
- Couples:Premium balcony staterooms with intimate dining venues and wine-focused shore excursions. This segment sustains base-load pricing power across Rhine Gorge and Wachau Valley rotations.
- Seniors:Accessible cabin designs with elevator-served decks and slower-paced excursion options. Affluent retirees represent the core repeat-purchaser base for extended European itineraries.
- Solo Travelers:Purpose-built single-occupancy staterooms and waived supplement policies. Demand is climbing the fastest as operators fill shoulder-season capacity through targeted pricing.
Revenue density peaks with Couples; demographic momentum favors Solo Travelers as supplement waivers expand.
Onboard Experience:
Experience differentiation now rivals propulsion technology in competitive positioning as operators seek margin expansion beyond hardware cycles.
- Culinary:Regional kitchen brigades with market-tour shore excursions and wine-pairing programming. AmaWaterways anchors premium positioning through chef-hosted itineraries in the Douro basin.
- Wellness:Spa facilities with thermal suite access and active excursion options including cycling and hiking. This segment gains share fastest among repeat purchasers seeking differentiation from standard ocean cruise offerings.
- Entertainment:Local performer embarkation and destination-focused enrichment lectures. Programming costs scale efficiently across standardized fleet configurations.
- Culture:Curator-led museum access and UNESCO site immersion with dedicated tour director staffing. Tauck sustains brand loyalty through all-inclusive cultural packaging.
Booking concentration sits with Culinary; Wellness is expanding most quickly as post-pandemary health priorities persist.
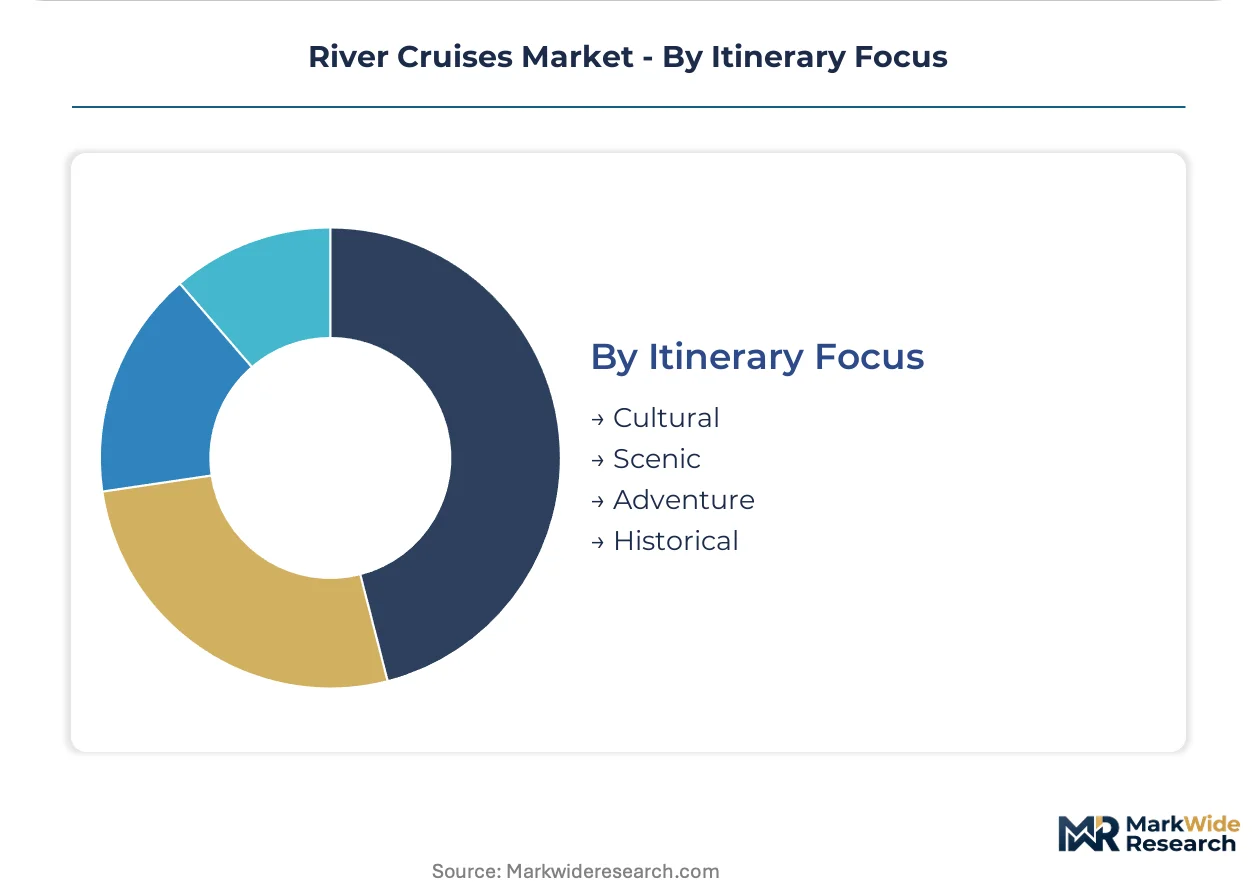
Itinerary Focus:
Route positioning determines port fee structures, berthing priority negotiations, and shore excursion margin capture.
- Cultural:Heritage-rich rotations through cathedral cities and archaeological sites with expert guide staffing. This segment occupies the largest share as Rhine Gorge and Wachau Valley routes attract repeat visitation.
- Scenic:Landscape-focused cruising with extended daylight transit through gorge and valley corridors. Demand concentrates on shoulder-season departures when foliage and lighting conditions peak.
- Adventure:Active excursion portfolios with kayak, cycling, and hiking components. Mekong and Amazon basin deployments favor this positioning.
- Historical:Battlefield and memorial site access with specialized historian guides. Danube corridor itineraries through Germany and Austria leverage this focus for premium pricing.
Fleet deployment tilts toward Cultural; Adventure is gaining share fastest as operators seek underpenetrated basin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Main-Danube corridor anchors European river cruise deployment, with shipyard capacity concentrated along Germany's inland waterway industrial belt and passenger sourcing gravitating toward affluent retiree demographics in German-speaking markets.
Germany
Affluent retirees from North Rhine-Westphalia and Bavaria drive repeat bookings on extended Danube itineraries. The Federal Maritime and Hydrographic Agency coordinates lock scheduling priority for EU Green Deal-compliant vessels. Shipyards in Papenburg and Wismar concentrate hybrid propulsion newbuilds as operators replace aging tonnage.
Austria
Vienna and Salzburg source markets sustain premium pricing for Wachau Valley cultural rotations. The national waterway administration enforces emissions standards aligned with EU F-Gas Regulation timelines. Linz serves as the primary embarkation hub for eastbound Danube deployments into Hungary.
Hungary
Budapest's overnight mooring limits are tightening as port capacity constraints intensify. The national transport authority coordinates cross-border certification with German and Austrian regulators. The city attracts repeat visitation from heritage-focused itineraries through the Danube Bend.
United States
Direct-to-consumer booking platforms capture repeat purchasers in coastal metropolitan markets. No federal regulator governs inland waterway emissions for foreign-flagged vessels. Miami and Fort Lauderdale serve as pre-cruise packaging hubs for European itinerary sales.
France
The Douro basin attracts culinary-focused programming from premium operators seeking differentiation. ANSM and CNIL oversee data protection for passenger reservation systems. Lyon and Strasbourg anchor Rhône and Rhine embarkation clusters with established shore excursion infrastructure.
River Cruises Market Competitive Landscape
Global majors compete with regional champions across itinerary specialization and propulsion technology adoption. The market structure tilts toward consolidated fleet ownership among purpose-built vessel operators, with barriers rising for new entrants lacking shipyard relationships. Three archetypes dominate: vertically integrated fleet owners controlling design-to-deployment value chains, experiential specialists anchoring premium positioning through culinary or cultural programming, and charter-focused operators deploying older tonnage for affinity-group bookings. Competitive moves concentrate on hybrid propulsion fleet renewal and direct-to-consumer channel capture.
Within the vertically integrated tier, Viking River Cruises and AmaWaterways exemplify divergent scale strategies. Tauck occupies a position emphasizing all-inclusive packaging and dedicated tour director staffing. These three anchors illustrate how fleet ownership depth, experiential differentiation, and service-model architecture separate competitive positions.
| Leading Market Players |
|---|
| Scenic |
| Tauck |
| Viking River Cruises |
| Riverside Luxury Cruises |
| Emerald Cruises |
| AmaWaterways |
| Avalon Waterways |
| Riviera Travel |
| Uniworld Boutique River Cruises |
| Others |
Value Network & Pricing Analysis
Battery-electric hybrid propulsion retrofits are compressing vessel economics while concentrating procurement power among German and Austrian yards with proven integration capabilities. This technology transition simultaneously elevates capital requirements for operators and tightens supply-side negotiating leverage for compliant shipyards.
Pricing Analysis
All-inclusive shore excursion bundling separates luxury operators from à-la-carte budget tiers, with balcony-heavy cabin mixes commanding premium positioning. Price differentiation rests on EU Green Deal compliance certification and dedicated tour director staffing ratios. Cost compression in budget tiers is intensifying because single-supplement waivers convert previously uneconomic berths. Solo travelers exhibit highest price sensitivity; affluent retirees on extended Danube itineraries show lowest.
Supply Chain Analysis
Marine engineering talent shortages in German and Austrian shipyard clusters are extending design-to-delivery cycles for hybrid propulsion systems. Hull fabrication and engine integration concentrate in Germany, Austria, and the Netherlands. Battery-electric systems, hydrogen-ready dual-fuel engines, and F-Gas-compliant HVAC components anchor raw material dependencies. Single-source vulnerability sits with specialized hybrid propulsion integrators. Distribution runs through direct-to-consumer platforms displacing traditional travel advisor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
River cruise operators face a fleet renewal phase as battery-electric and hydrogen-ready propulsion systems displace conventional diesel-electric configurations. This technology transition favors early movers with shipyard relationships and regulatory priority access.
For Market Incumbents: Deepen hybrid propulsion fleet renewal ahead of Phase IV emission standards to secure priority berthing at electrified terminals. Lock long-term shipyard capacity at Papenburg and Wismar yards before orderbook hardening intensifies. Absorb compliance costs through balcony-heavy cabin mixes and bundled cultural programming that sustains premium pricing power against ocean-cruise substitutes.
For New Entrants and Emerging Players: The premium-economy pricing gap in Mekong basin expedition cruising offers white-space positioning for culinary-focused programming. Vietnam and Cambodia segments remain underpenetrated relative to European saturation. Target shoulder-season capacity absorption through purpose-built solo-occupancy staterooms without supplement penalties.
For Investors and Strategic Acquirers: Re-rating potential sits with experiential specialists owning chef-hosted itinerary IP and proprietary reservation systems given direct-to-consumer channel capture. Long-term viability favors operators with backward integration into shipyard relationships and regulatory coordination capabilities. Watch EU F-Gas Regulation enforcement timelines as fleet compliance inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Propulsion Fleet Renewal | Battery-electric specifications secure priority lock scheduling from Germany's Federal Maritime and Hydrographic Agency. |
| Direct-to-Consumer Platform Investment | Proprietary reservation systems capture guest preference data for personalized pre-cruise upselling in US and UK source markets. |
| Shore Power Infrastructure Partnership | EU funding mechanisms for port electrification create regulatory tailwinds for priority berthing at Amsterdam and Budapest terminals. |
| Solo-Optimized Cabin Mix Innovation | Purpose-built single-occupancy staterooms convert shoulder-season capacity into yield without supplement penalties. |
| Mekong Basin Culinary Programming | Chef-hosted itineraries in Vietnam and Cambodia segments differentiate beyond saturated European route networks. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across cruise line fleet directors, shipyard procurement managers, port authority planners, and travel advisor network heads. EU Green Deal implementation documents, Germany's Federal Maritime and Hydrographic Agency lock scheduling protocols, and Austria's waterway administration emissions filings provided regulatory calibration. Bottom-up vessel deployment tracking and top-down passenger sourcing analysis enabled triangulation across market sizing estimates.
Data-stream reconciliation across shipyard orderbook disclosures, cruise line fleet deployment schedules, and passenger manifest patterns shaped the analytical framework. Segmentation dimensions modeled include cruise type, customer demographic, onboard experience positioning, and itinerary focus across the projection horizon. CAGRs were derived from vessel capacity expansion trajectories and demographic penetration curves in affluent retiree source markets. Hybrid propulsion adoption timelines and EU F-Gas Regulation compliance deadlines served as industry-specific forecast inputs.
Underlying measurement precision varies by segment; luxury and expedition cruise types carry tighter precision than charter arrangements due to disclosed fleet specifications. Forecasts reflect assumptions regarding regulatory enforcement consistency, shipyard delivery reliability, and port infrastructure electrification schedules. EU Green Deal timeline acceleration, marine engineering labor pool constraints, and cross-border certification fragmentation represent specific risk factors warranting ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cruise and Marine Tourism
US Hotels, Resorts, and Cruise Lines Market
Cruise and Marine Tourism
Cruise Travel Market
Cruise and Marine Tourism
Saudi Arabia Diving Tourism Market
Cruise and Marine Tourism
Fishing Tourism Market
Cruise and Marine Tourism
Cruise Tourism Market
Cruise and Marine Tourism
Luxury Cruise Tourism Market
Cruise and Marine Tourism
Cruise Ship Market
Cruise and Marine Tourism
Coastal and Maritime Tourism Market
Cruise and Marine Tourism
Asia-Pacific Cruise Ship Market
Cruise and Marine Tourism
Asia-Pacific Cruise Tourism Market
Cruise and Marine Tourism
Diving Tourism Market
Cruise and Marine Tourism
Global Cruise Market
Cruise and Marine Tourism
Alaskan Cruises Market