
 Germany Outbound Tourism Market | 2026-2036
Germany Outbound Tourism Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Outbound Tourism Market Analysis
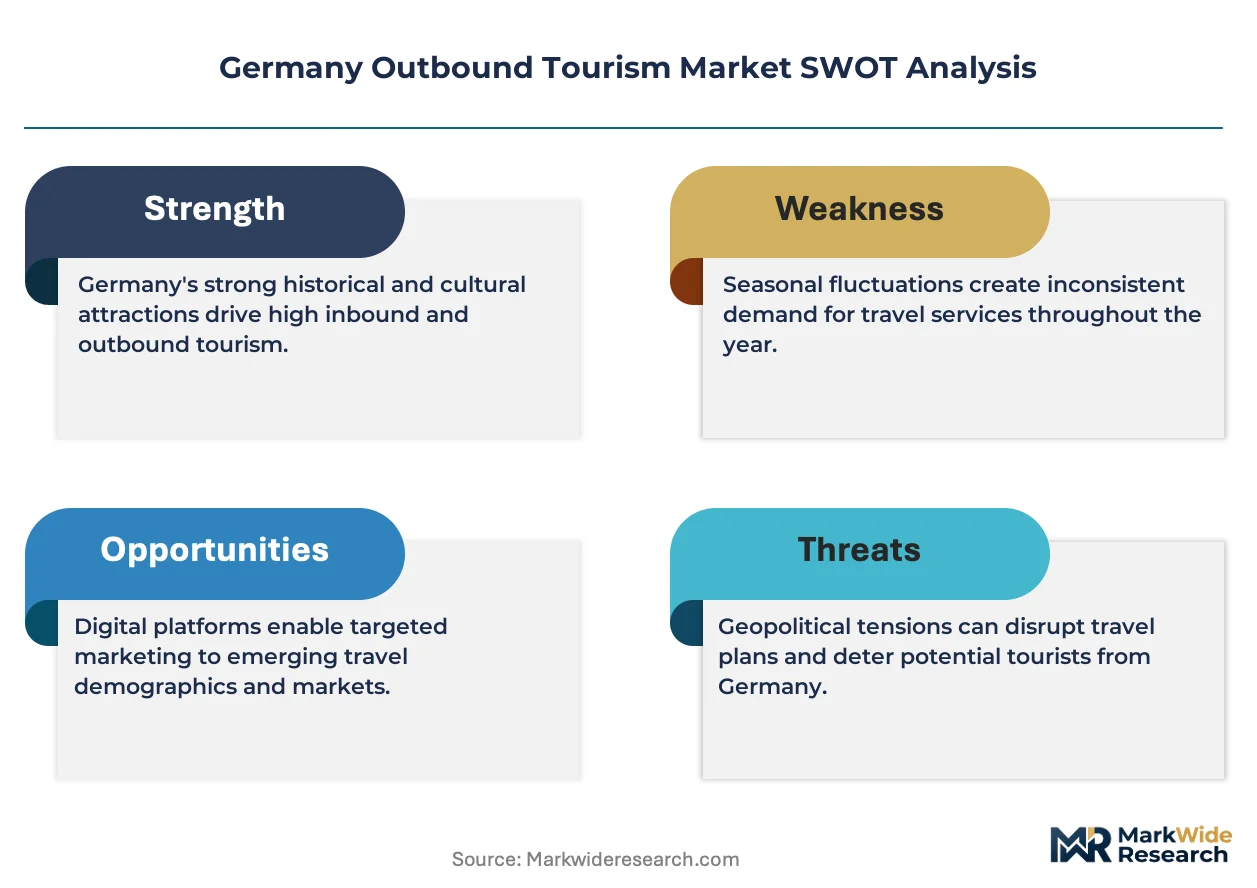
Modular itinerary bundling is shifting how German travelers assemble trips, unbundling traditional package components into bookable segments. TUI Deutschland leverages its integrated airline-hotel platform to sustain margin control across the value chain. DER Touristik competes through specialized long-haul and cruise portfolios. Tourlane differentiates via algorithmic personalization for premium independent travelers.
Germany outbound tourism comprises resident departures for temporary stays abroad, spanning air and surface transport, accommodation procurement, and destination services. Package configuration typically involves dynamic packaging engines that aggregate flights, lodging, and ground services through API-connected inventory systems. Leisure travel dominates volume within the Travel Type dimension, while Online Travel Agencies capture the fastest expansion in Booking Channel due to mobile-first conversion optimization. The Destination Type split shows Cultural and Urban categories concentrating higher per-trip expenditure than Beach segments.
The EU Green Deal and F-Gas Regulation shape aviation fuel and aircraft standards affecting German carrier economics, while GDPR and the EU AI Act govern traveler data processing and algorithmic pricing transparency. KBA vehicle emissions rules influence coach and rail alternatives for surface-bound departures. Stakeholders must monitor regulatory cost pass-through mechanisms and carbon border adjustments affecting route profitability.
Market Dynamics
EU Green Deal carbon pricing and F-Gas Regulation compliance costs are compressing aviation margins while accelerating rail and coach alternatives. German carriers face simultaneous pressure from emissions caps and traveler preference shifts toward lower-carbon surface transport for intra-European departures.
Growth Catalysts
- EU Green Deal aviation fuel mandates:ReFuelEU Aviation requirements are forcing fleet renewal toward more efficient aircraft, reducing per-passenger emissions on long-haul routes to Asia and the Americas.
- Algorithmic personalization engines:Machine learning platforms are matching independent German travelers with modular flight-hotel-ground bundles previously available only through traditional package operators.
- Mediterranean destination infrastructure:Spanish and Italian regional airports have expanded low-cost carrier capacity, lowering access costs for German leisure segments.
Market Restraints
- Jet fuel cost volatility:Kerosene price swings directly compress airline margins on thin-yield European routes, forcing capacity discipline during peak summer periods.
- GDPR data processing constraints:Cross-border traveler data flows face German and EU-level consent and retention limitations, complicating predictive pricing and personalization algorithms.
- Rail infrastructure bottlenecks:Deutsche Bahn network congestion limits reliable overnight sleeper capacity for climate-conscious travelers seeking alternatives to short-haul aviation.
Strategic Opportunities
- Carbon-neutral rail corridors:German federal rail electrification programs and cross-border agreements with Austrian and Swiss operators create zero-emission positioning for surface-bound holiday products.
- Extended-stay remote work packages:Portuguese and Croatian municipalities are attracting German digital nomads through visa facilitation and co-living infrastructure subsidies.
- EU AI Act algorithmic transparency:Early compliance with explainable pricing rules enables trusted direct-booking relationships versus opaque intermediary platforms.
Industry Challenges
- Sustainable aviation fuel procurement:German carriers struggle to secure certified SAF volumes at scale, forcing operational trade-offs between route frequency and emissions targets.
- Legacy reservation system integration:Established tour operators face technical debt migrating from mainframe-based inventory to API-native dynamic packaging architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Outbound Tourism Market |
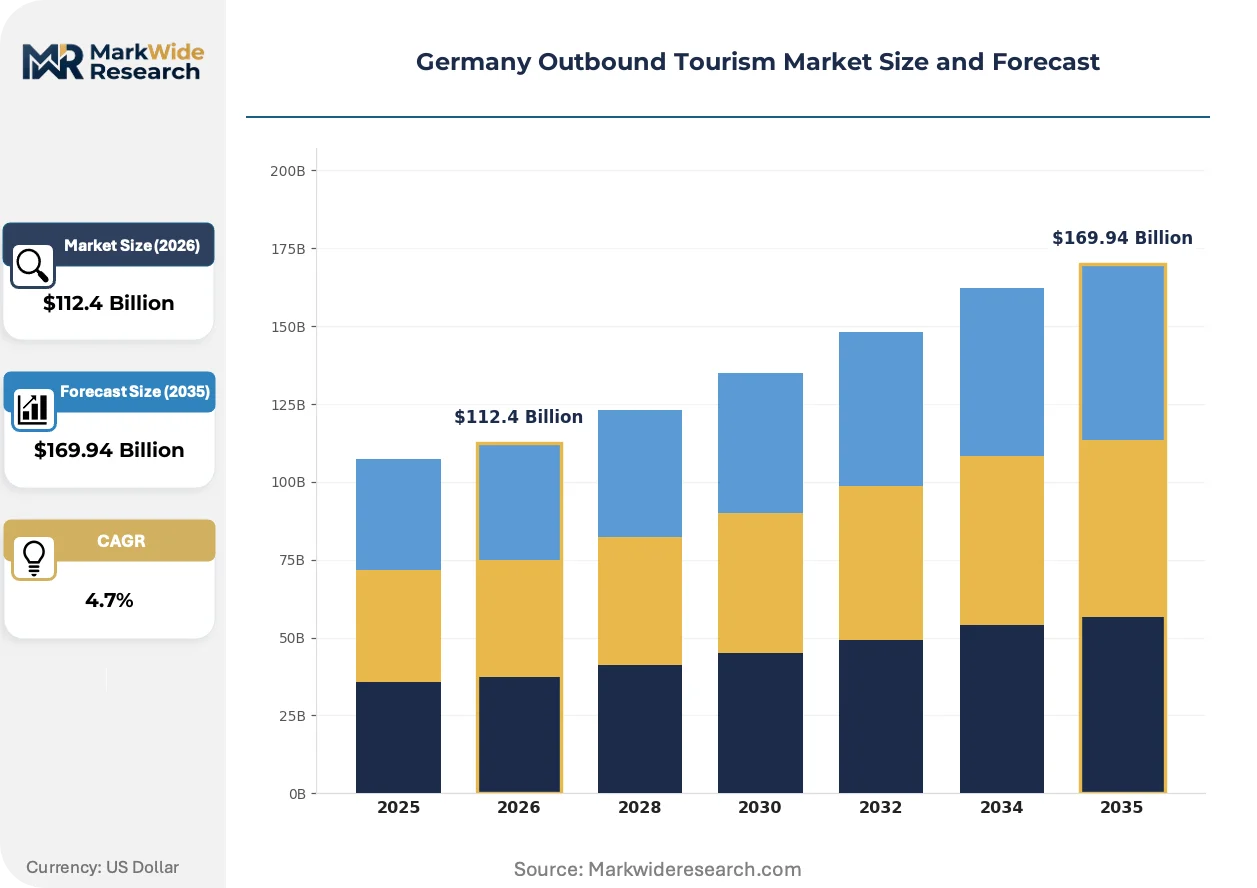
| Market Size in 2026 | $112.4 Billion |
| Market Size in 2035 | $169.94 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Travel Type: Leisure, Business, Health, Educational Demographic Profile: Families, Couples, Solo Travelers, Retirees Destination Type: Cultural, Adventure, Beach, Urban Booking Channel: Online Travel Agencies, Direct Booking, Travel Agents, Mobile Apps |
| Companies Covered | YGO Trips, Intakt-Reisen GmbH & Co. KG, Tourlane, DER Touristik, TUI Deutschland, FlixBus, Limehome, FTI Touristik, Omio, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Outbound Tourism Market Emerging Trajectories
Technology convergence and regulatory pressure are fragmenting traditional package tour economics while enabling new traveler-controlled assembly models. The sector is witnessing simultaneous disintermediation and re-intermediation across booking channels.
Dynamic packaging engines are unifying fragmented flight, accommodation, and ground inventory through real-time API connections. Independent German travelers now assemble bespoke itineraries from component suppliers previously locked behind operator contracts. This unifying architecture compresses the traditional package tour value chain, transferring margin control to travelers and technology platforms.
The EU AI Act transparency requirements are mandating explainable logic for algorithmic pricing and recommendation systems. German Online Travel Agencies must document decision pathways for personalized offers, increasing compliance overhead but building traveler trust. Premium independent segments are responding fastest, demanding auditable fairness in dynamic rate calculations.
Remote work visa programs are extending German traveler stays in Mediterranean and Balkan destinations. Croatian and Portuguese municipalities now compete for extended-stay digital nomads through infrastructure subsidies and tax incentives. This behavioral shift concentrates demand in shoulder seasons, reshaping traditional peak-trough revenue patterns for accommodation providers.
Germany Outbound Tourism Market Segmentation
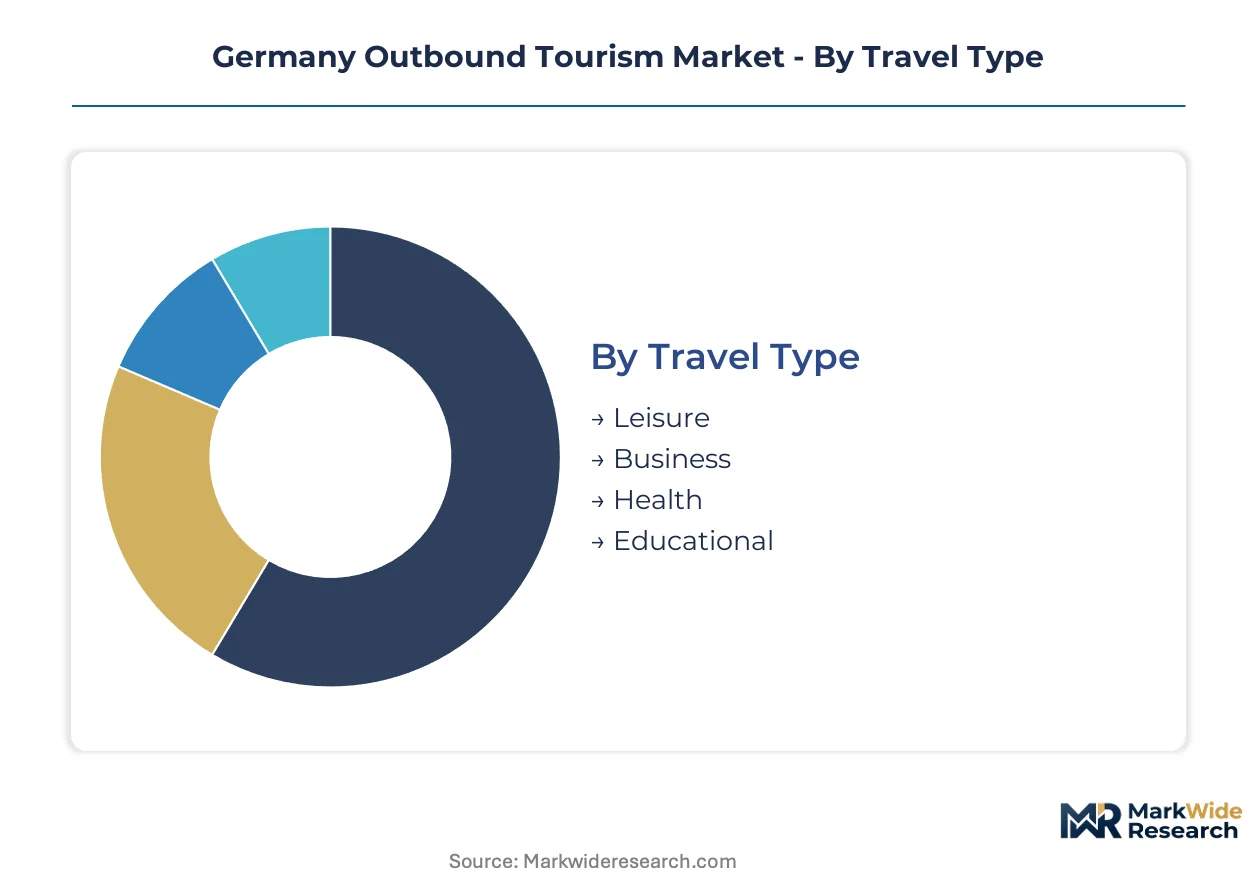
German outbound tourism segments fragment across behavioral, demographic, and channel dimensions. Each category carries distinct margin profiles and capital requirements for operators seeking to capture specific traveler cohorts.
Travel Type:
Capital intensity varies sharply across travel purpose, with long-haul infrastructure and specialized medical partnerships demanding the heaviest upfront investment.
- Leisure:Package tour operators deploy integrated airline-hotel platforms requiring fleet and inventory commitments. German Mediterranean demand concentrates in Spanish and Italian coastal corridors where low-cost carrier capacity expansion has lowered access costs.
- Business:Corporate travel management platforms integrate expense systems and duty-of-care tracking. Frankfurt and Munich corporate hubs generate concentrated intra-European route demand where rail alternatives compete on emissions compliance.
- Health:Medical tourism partnerships with Hungarian and Thai facilities require accreditation investments and patient transfer protocols.
- Educational:University exchange programs and language immersion contracts operate on semester-cycle procurement with institutional billing structures.
Most installed capacity flows through Leisure. Expansion is steepest in Health.
Demographic Profile:
Customer lifetime value and trip frequency diverge substantially across age and household composition, shaping acquisition spend and retention economics.
- Families:Multi-generational bookings command higher per-trip expenditure through accommodation upgrades and activity bundles. All-inclusive resorts in Majorca and Crete capture German family demand through child-care infrastructure and flight timing optimization.
- Couples:Romantic and honeymoon segments prioritize boutique properties and experiential dining. Croatian island destinations and Portuguese wine regions attract German couples through shoulder-season pricing and privacy positioning.
- Solo Travelers:Independent itinerary assembly via dynamic packaging engines dominates. Safety infrastructure and single-supplement waivers drive destination selection.
- Retirees:Extended-stay products and cruise portfolios align with flexible timing and comprehensive insurance requirements.
Volume concentrates in Families. Solo Travelers are climbing the fastest.
Destination Type:
Per-trip expenditure and margin structure correlate with activity intensity and infrastructure specialization rather than distance alone.
- Cultural:Museum passes, guided heritage circuits, and performance ticketing require destination management company partnerships. Italian Renaissance cities and Vienna concentrate German cultural demand through rail connectivity and concentrated inventory.
- Adventure:Equipment logistics, certified guide networks, and activity insurance create operational complexity. Norwegian fjord trekking and Icelandic volcanic terrain attract German adventure segments through sustainability credentials.
- Beach:Sun-and-sand packages compete on yield management and aircraft utilization. Balearic and Canary Islands infrastructure supports high-frequency German charter operations.
- Urban:City-break products leverage short-haul aviation and high-speed rail. Berlin and Hamburg origin markets feed Amsterdam, Prague, and Copenhagen weekend demand.
Beach maintains the largest installed base. Adventure shows the steepest expansion trajectory.
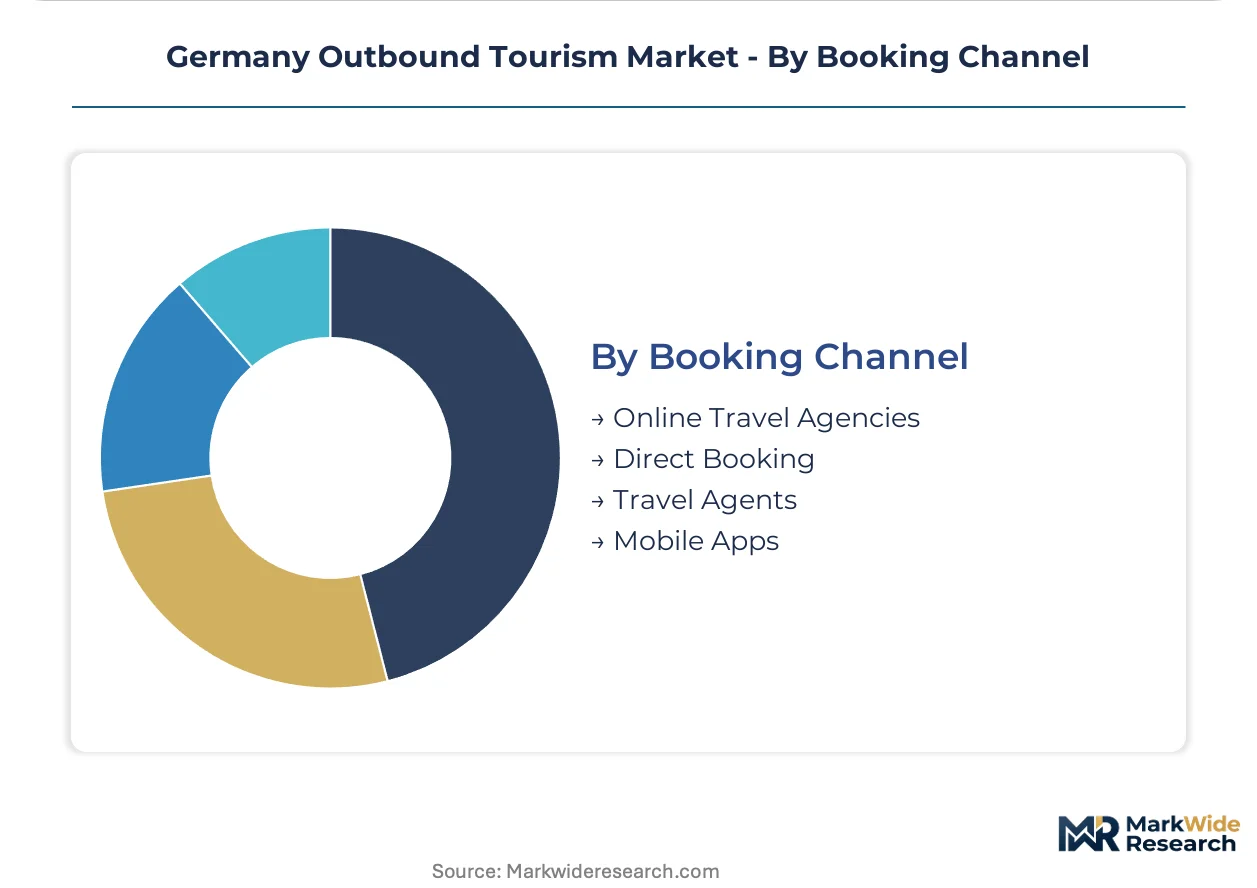
Booking Channel:
Technology stack requirements and customer acquisition costs scale with platform sophistication and personalization depth.
- Online Travel Agencies:API-native architectures aggregate fragmented inventory through real-time pricing engines. GDPR compliance and EU AI Act transparency mandates increase development overhead for German-focused platforms.
- Direct Booking:Hotel and airline proprietary apps bypass intermediary commissions. Loyalty program integration and exclusive rate access drive German traveler registration.
- Travel Agents:High-touch consultation for complex multi-destination and cruise products retains relevance among retiree and affluent family segments.
- Mobile Apps:Last-minute inventory clearance and geolocation-based recommendations capture spontaneous German booking behavior.
Online Travel Agencies channel the most volume. Mobile Apps are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German outbound tourism originated in post-war leisure travel expansion through Mediterranean charter operations. Package tour infrastructure consolidated around Frankfurt and Munich as departure hubs during the 1970s and 1980s. Today, regional demand patterns reflect this heritage while adapting to sustainability mandates and digital booking migration.
Spain
German leisure travelers concentrate in Balearic and Canary Islands resorts, driving year-round demand through all-inclusive contracts. Spanish coastal municipalities receive EU cohesion funds for sustainable tourism infrastructure upgrades. Mallorca maintains the densest German tour operator presence, with charter capacity exceeding any other Mediterranean destination.
Italy
Renaissance city circuits and Alpine ski domains capture German cultural and adventure segments through rail-linked accessibility. Italian regional governments administer tourism promotion budgets under national recovery framework guidelines. Tuscany and South Tyrol host the highest concentration of German-speaking hospitality infrastructure outside German-speaking Europe.
Portugal
Remote work visa programs and co-living subsidies attract extended-stay German digital nomads to Lisbon and Porto metropolitan areas. Portuguese immigration authorities process EU mobility documentation under Schengen coordination protocols. The Algarve region competes for German retiree wintering demand through long-term rental tax incentives.
Austria
Alpine wellness tourism and cross-border rail connectivity sustain German visitor flows to Vorarlberg and Tyrol provinces. Austrian federal rail electrification aligns with EU Green Deal corridor development standards. Salzburg and Innsbruck function as secondary departure points for German travelers accessing Eastern Mediterranean circuits.
Thailand
Long-haul beach and wellness tourism from Germany concentrates in Phuket and Koh Samui resort zones. Thai tourism authorities coordinate with German carriers on seasonal capacity allocation under bilateral air service agreements. Bangkok serves as the primary hub for German travelers continuing to Indochina and Indonesian archipelago destinations.
Germany Outbound Tourism Market Vendor Landscape
The competitive structure tilts toward integrated tour operators with captive airline and hotel inventory. Market concentration remains moderate, with three to five national-scale players commanding significant package tour volume alongside fragmented independent travel platforms. Strategic archetypes divide between vertically integrated leisure conglomerates, algorithmic personalization specialists, and mobility-as-a-service platforms. Dominant competitive moves include dynamic packaging technology deployment and sustainable product line repositioning under EU regulatory pressure.
Within the integrated tour operator tier, TUI Deutschland and DER Touristik exemplify scale-driven market presence through established airline-hotel platforms. Tourlane occupies a position among algorithmic personalization specialists serving premium independent travelers. These three anchors illustrate the sector's bifurcation between traditional package infrastructure and technology-native booking assembly.
| Leading Market Players |
|---|
| YGO Trips |
| Intakt-Reisen GmbH & Co. KG |
| Tourlane |
| DER Touristik |
| TUI Deutschland |
| FlixBus |
| Limehome |
| FTI Touristik |
| Omio |
| Others |
Supply Flow & Price Mechanics
Dynamic packaging engine deployment across German Online Travel Agencies is compressing traditional tour operator margins while fragmenting supply concentration toward API-connected inventory aggregators. This technology shift simultaneously lowers traveler acquisition costs for platforms and erodes price-setting power for legacy operators with captive airline-hotel contracts.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates German outbound tourism, with premium tiers capturing extended-stay digital nomad segments and economy tiers serving high-frequency Mediterranean beach demand. Price differentiation rests on booking channel control and loyalty program depth, with direct-booking platforms commanding rate premiums through exclusive inventory access. Cost compression in standard-tier packages is intensifying because low-cost carrier capacity expansion has commoditized Spanish and Italian route economics. Families exhibit highest price sensitivity due to multi-passenger booking volumes, while solo independent travelers show lowest sensitivity when algorithmic personalization reduces search friction.
Supply Chain Analysis
Jet fuel hedging costs and sustainable aviation fuel procurement premiums are reshaping German carrier network economics, forcing operational trade-offs between route frequency and emissions compliance. Supply concentration centers on Spain, Italy, and Thailand as primary destination infrastructure hubs, with accommodation inventory drawing from regional property management platforms and global hotel chains. Raw material dependencies include aviation turbine fuel, aircraft leasing capacity, and destination ground service labor pools. Single-source vulnerability runs through Deutsche Bahn overnight sleeper capacity constraints for climate-conscious intra-European demand. Distribution runs through API-native Online Travel Agencies capturing fastest channel expansion alongside direct-booking hotel and airline proprietary applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
German outbound tourism offers margin expansion through dynamic packaging technology deployment and premium independent traveler segmentation, with algorithmic personalization reducing customer acquisition costs for platform-native operators.
For Market Incumbents: Acquire API-native dynamic packaging technology to defend against disintermediation by independent booking platforms. Consolidate position through backward integration into sustainable aviation fuel procurement partnerships, securing certified volumes ahead of ReFuelEU Aviation mandate compliance deadlines. Fortify captive airline-hotel inventory control against margin erosion from fragmented supplier-direct relationships. For New Entrants and Emerging Players: Begin with extended-stay remote work package specialization targeting German digital nomad demand in Portuguese and Croatian municipalities, where visa facilitation infrastructure creates first-mover positioning. Capture underserved solo traveler safety infrastructure segments through single-supplement waiver partnerships and destination security certification. Pursue mobile-first conversion optimization as primary go-to-market angle, leveraging last-minute inventory clearance algorithms. For Investors and Strategic Acquirers: Roll-up economics work for algorithmic personalization specialists because fragmented independent traveler demand lacks scaled platform aggregation. Target acquisition archetypes combining dynamic packaging engines with premium traveler loyalty data assets. Monitor EU AI Act transparency compliance costs as inflection indicator for platform profitability divergence versus intermediary-dependent competitors.| Strategic Initiative | Industry Significance |
|---|---|
| Dynamic Packaging Engine Deployment | API-native inventory aggregation transfers margin control from legacy tour operators to technology platforms. |
| Sustainable Aviation Fuel Procurement Partnership | ReFuelEU Aviation compliance secures route operating rights ahead of German carrier fleet renewal cycles. |
| Extended-Stay Remote Work Product Launch | Portuguese and Croatian visa facilitation captures German digital nomad demand in shoulder-season windows. |
| Rail Infrastructure Capacity Expansion | Deutsche Bahn electrification programs unlock zero-emission surface-bound holiday product positioning. |
| EU AI Act Transparency Compliance Investment | Explainable pricing algorithms build direct-booking trust versus opaque intermediary platform competition. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with tour operator revenue managers, airline network planners, Online Travel Agency platform engineers, and destination management company procurement leads with secondary validation. Secondary sources included EU Green Deal regulatory filings, KBA vehicle emissions documentation, airline traffic statistics, and accommodation inventory platform disclosures. Bottom-up traveler departure modeling and top-down market sizing triangulated volume and value estimates.
Comparable historical periods anchored projection assumptions across the analysis window, with segmentation modeling across travel type, demographic profile, destination type, and booking channel dimensions. CAGRs derived from trend extrapolation adjusted for regulatory intervention timing and technology adoption curves. Forecast inputs incorporated ReFuelEU Aviation mandate implementation schedules and GDPR consent framework evolution.
Caveats apply where jet fuel price volatility, rail infrastructure bottlenecks, or EU AI Act compliance cost pass-through could materially shift the outlook. Forecasts reflect documented assumptions about traveler preference stability and regulatory enforcement intensity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Travel and Tourism
Inflight Shopping Market
Travel and Tourism
China Travel Retail Market
Travel and Tourism
France Culinary Tourism Market
Travel and Tourism
USA Sports Tourism Market
Travel and Tourism
Tourism Security Market
Travel and Tourism
Global Enotourism Market
Travel and Tourism
Asia-Pacific MICE Tourism Market
Travel and Tourism
India Sustainable Tourism Market
Travel and Tourism
Surfing Tourism Market
Travel and Tourism
USA Sustainable Tourism Market
Travel and Tourism
Luxury Tourism Market
Travel and Tourism
India Outbound Tourism Market
Travel and Tourism
Latin America Inflight Services Market
Travel and Tourism
France Outbound Tourism Market
Travel and Tourism
Luxury Travel Market
Travel and Tourism
North America Travel Retail Market