
 Vacation Ownership Market | 2026-2036
Vacation Ownership Market Size, Share, and Industry Trends Forecast 2026-2036
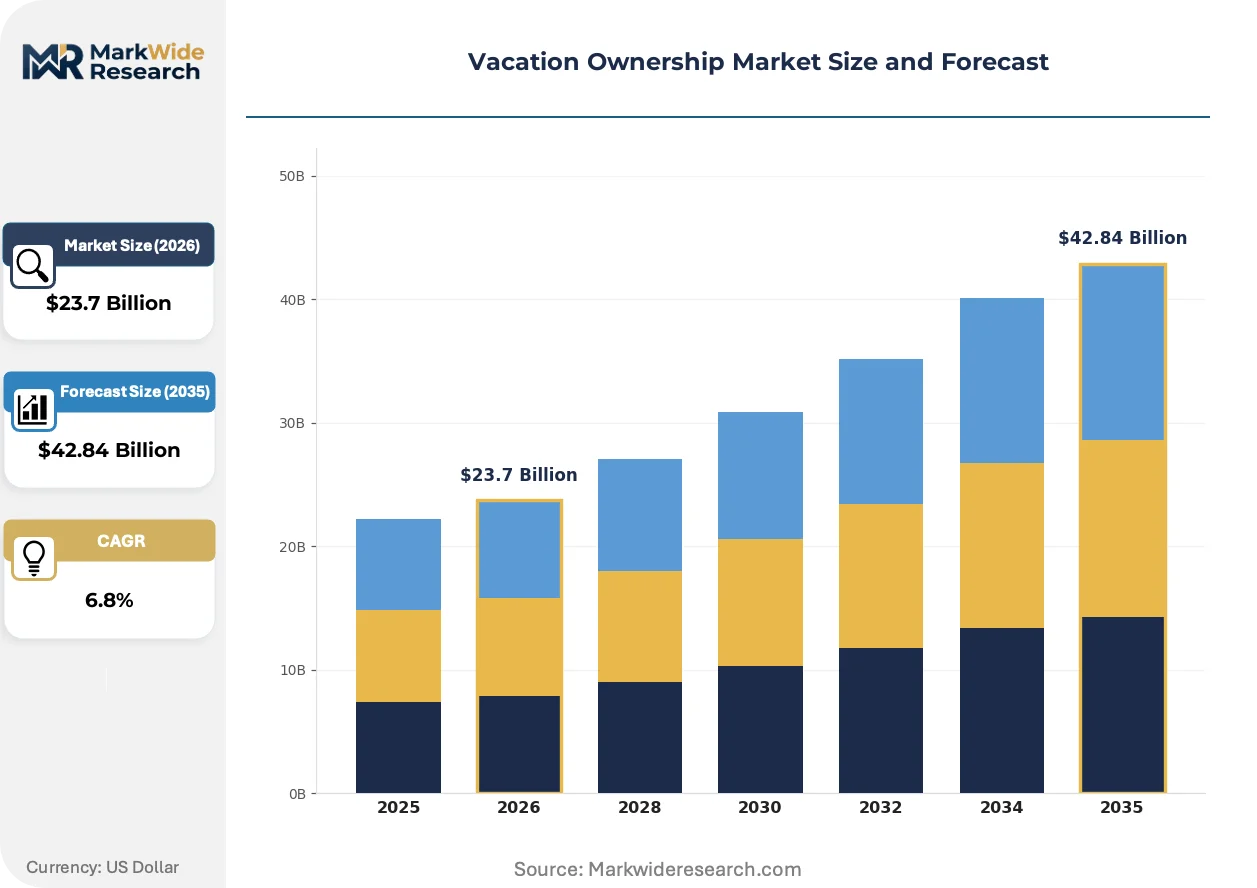
Vacation Ownership Market Outlook
Family travel demand is consolidating as the dominant end-use vertical, displacing traditional retiree-centric positioning across resort portfolios. Marriott Vacations Worldwide leverages its exchange network density to sustain occupancy premiums in Orlando and Caribbean clusters. Hilton Grand Vacations anchors its pipeline in urban leisure destinations, competing directly with Hyatt's boutique resort footprint. Wyndham Destinations differentiates through its mid-market points-based systems, controlling price-sensitive segments with lower entry thresholds.
Vacation ownership denotes a shared real estate structure where purchasers acquire either deeded fractional interests, leasehold rights, or points-based entitlements to resort accommodations, typically structured through fixed-week or floating-week reservation systems with annual maintenance fee obligations. The model functions as a hybrid consumption-financial instrument, blending prepaid leisure accommodation with potential appreciation or exchange liquidity through affiliated networks like Interval International. Points-based ownership models now represent the fastest-growing structural category, as developers prioritize flexibility over fixed-week inventory to capture younger buyer cohorts. Deeded condominiums in beach and mountain destinations retain the deepest margin pools, while exchange programs absorb disproportionate operational complexity without commensurate revenue yield.
The US Federal Trade Commission enforces cooling-off period mandates and advertising disclosure standards that directly shape sales floor scripting and rescission rates. Florida's Department of Business and Professional Regulation imposes escrow requirements and project completion bonding that filter developer market access, while Mexico's PROFECO consumer protection framework governs cross-border timeshare marketing to North American buyers. Stakeholders must monitor evolving state-level lending regulations and exchange network consolidation patterns to calibrate capital deployment between inventory development and platform technology.
Market Dynamics
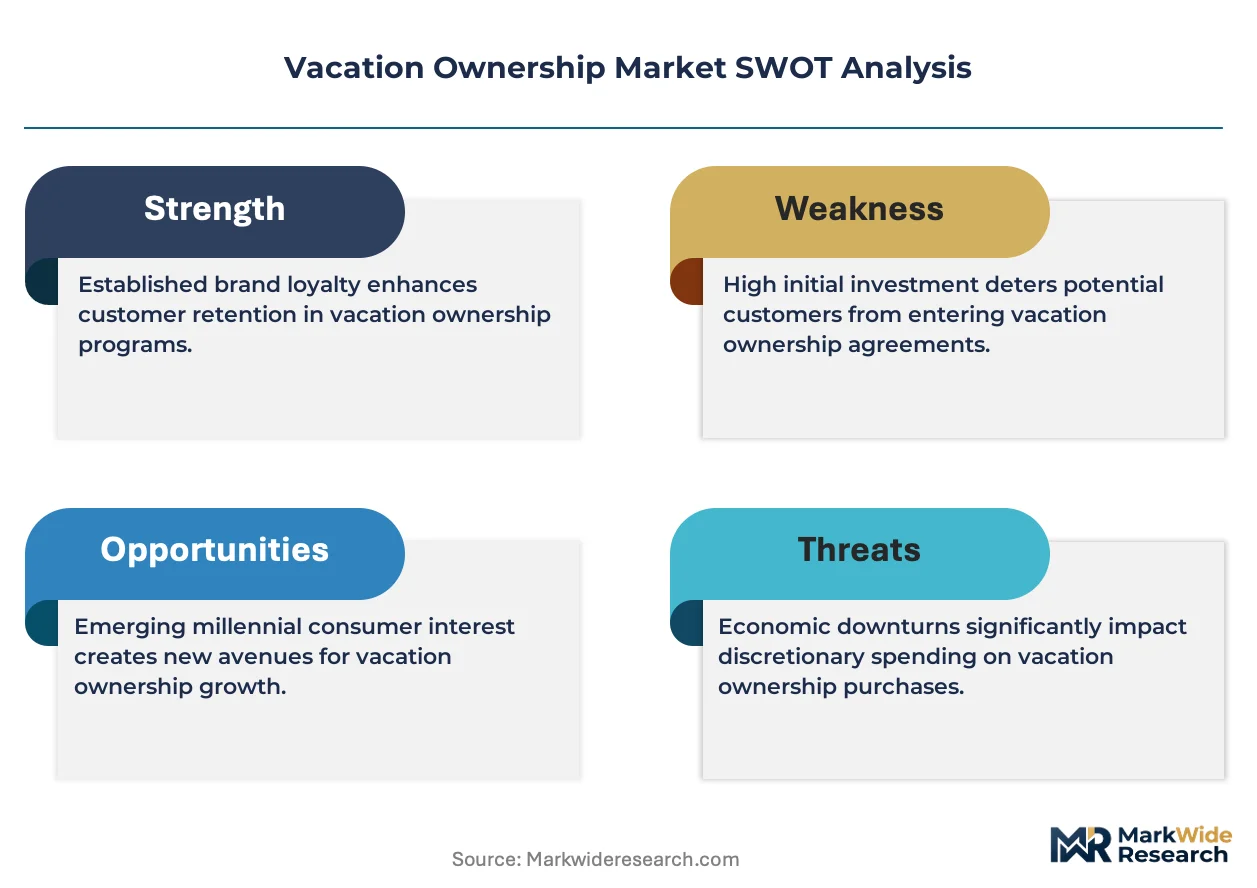
The US Consumer Financial Protection Bureau's intensified scrutiny of timeshare lending practices is forcing developers to restructure sales floor financing protocols and absorb elevated compliance costs across their US operations.
Growth Catalysts
- Millennial Experiential Spending:Buyers entering prime earning years prioritize prepaid leisure accommodation over discretionary goods, expanding the addressable purchaser base for points-based ownership structures.
- Florida Escrow Requirements:The state's Department of Business and Professional Regulation mandates project completion bonding that filters out undercapitalized developers, concentrating market share among established operators with balance sheet depth.
- Exchange Network Density:Interval International and affiliated platforms enable liquidity for fractional owners, reducing perceived purchase risk and accelerating conversion rates on sales floors.
Market Restraints
- Maintenance Fee Escalation:Annual fee obligations on deeded interests compound at rates exceeding inflation, eroding value propositions for price-sensitive buyer cohorts and elevating default risk.
- Inventory Concentration Risk:Development pipelines cluster in Florida and Mexico resort corridors, exposing portfolios to hurricane damage, localized regulatory shifts, and destination-specific demand shocks.
- Resale Market Illiquidity:Secondary channels for fractional interests lack standardized pricing mechanisms, trapping owners in depreciating assets and dampening primary market confidence.
Strategic Opportunities
- Urban Leisure Destinations:Hilton Grand Vacations anchors new inventory in city-center locations, capturing weekend travel demand from business travelers extending stays into leisure segments.
- Mid-Market Points Systems:Lower entry thresholds attract first-time buyers previously excluded from deeded condominium purchases, expanding developer revenue pools without per-unit construction cost inflation.
- Cross-Border Mexican Marketing:PROFECO consumer protection frameworks governing North American buyer outreach create compliant pathways for US and Canadian purchaser acquisition at lower customer acquisition costs.
Industry Challenges
- Sales Floor Talent Scarcity:Licensed timeshare salesperson turnover exceeds hospitality industry averages, degrading conversion consistency and elevating training expenditures.
- Rescission Rate Volatility:Cooling-off period mandates enforced by the US Federal Trade Commission generate inventory reversion spikes that disrupt occupancy forecasting and revenue recognition timing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vacation Ownership Market |
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $42.84 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Ownership Model: Deeded, Right-to-Use, Leasehold, Points-Based Property Type: Condominiums, Villas, Hotels, Townhouses Customer Type: Families, Retirees, Millennials, Corporate Groups Usage Type: Annual Usage, Biennial Usage, Fractional Ownership, Exchange Programs |
| Companies Covered | Marriott Vacations Worldwide, Hilton Grand Vacations, Wyndham Destinations, Travel + Leisure Co., Disney Vacation Club, Bluegreen Vacations, Hyatt, Interval International, Resort Condominiums International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vacation Ownership Market Strategic Shifts
Digital booking platforms and flexible entitlement structures are compressing the traditional fixed-week model, while regulatory pressure on lending practices forces operational redesign across developer sales organizations.
Blockchain-based title verification is rewriting fractional ownership record-keeping by eliminating escrow delays and reducing title insurance costs. Marriott Vacations Worldwide pilots distributed ledger systems for Caribbean and Orlando inventory transfers. The technology is rewriting settlement timelines from weeks to hours, compressing working capital cycles for developers.
The US Federal Trade Commission enforces cooling-off period mandates and advertising disclosure standards that directly shape sales floor scripting and rescission rates. Florida's Department of Business and Professional Regulation imposes escrow requirements and project completion bonding that filter developer market access. Mexico's PROFECO consumer protection framework governs cross-border timeshare marketing to North American buyers, creating compliance complexity for developers operating in both jurisdictions.
Buyer preference for experience flexibility over fixed obligations is fragmenting traditional week-based purchasing patterns. Younger cohorts reject rigid scheduling in favor of points-based systems enabling destination switching and date flexibility. This behavioral pivot concentrates in Orlando and Caribbean clusters where exchange network density supports entitlement liquidity.
Vacation Ownership Market Segmentation
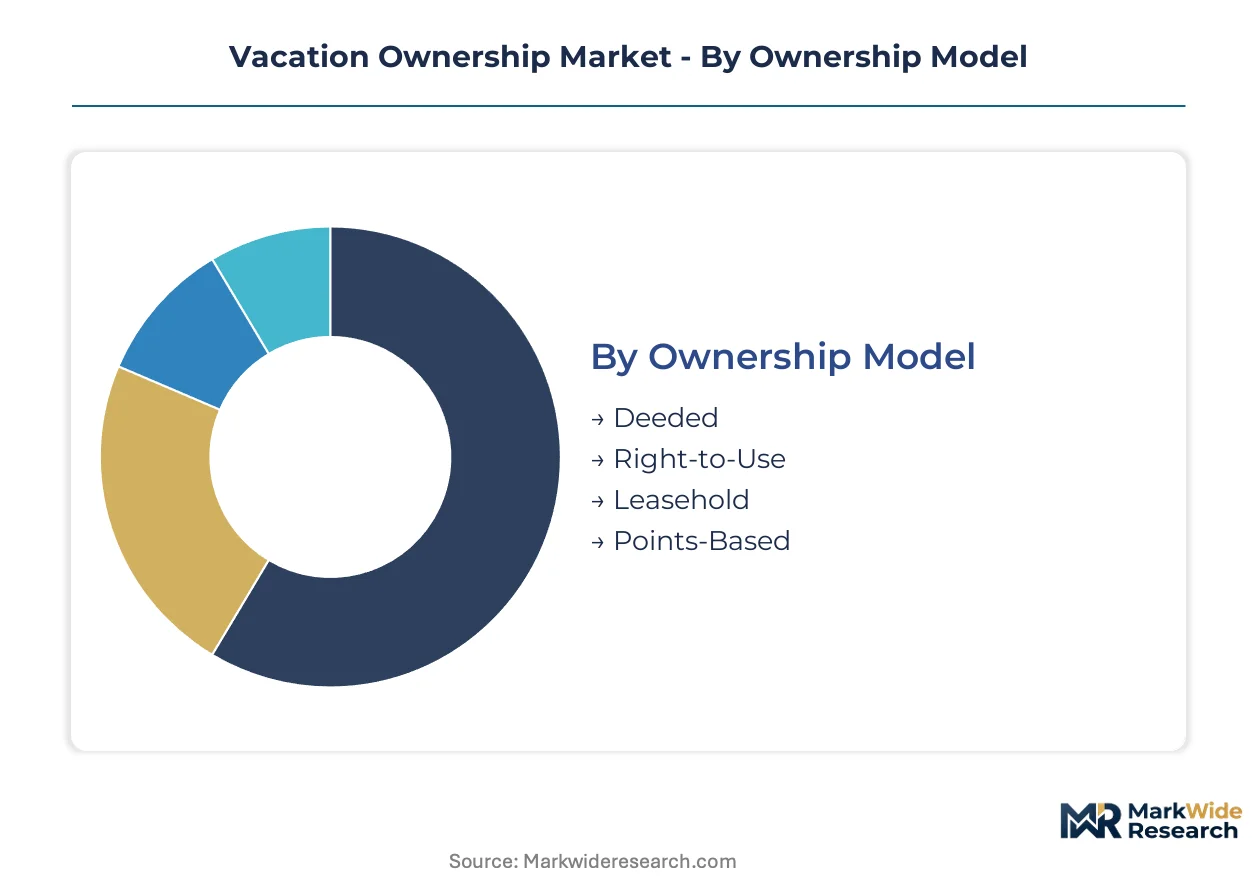
Segmentation in vacation ownership reveals how structural choices in legal entitlement, physical inventory, and customer targeting determine margin architecture and capital efficiency across developer portfolios. Each dimension carries distinct regulatory exposure and resale liquidity profiles that shape portfolio construction decisions.
Ownership Model:
Legal entitlement structures define the balance sheet treatment, consumer financing eligibility, and exchange network compatibility that developers must engineer into product design.
- Points-Based:Entitlements denominated in currency-equivalent credits enable destination switching and date flexibility through centralized reservation systems. Demand concentrates among millennial first-time buyers in Orlando and Caribbean clusters who prioritize experience variety over fixed-location commitment.
- Deeded:Fee-simple fractional interests in specific condominium units carry real property tax obligations and title insurance requirements. Florida beachfront inventory absorbs the deepest capital deployment as developers exploit appreciation narratives and estate planning motivations among high-net-worth purchasers.
- Right-to-Use:Contractual access rights without property interest transfer simplify Mexican and Caribbean cross-border sales by avoiding foreign ownership restrictions.
- Leasehold:Long-term lease structures with developer land retention predominate in Hawaii and coastal California where land scarcity elevates underlying dirt values.
Points-based structures lead on scale; deeded interests lead on momentum in premium coastal markets.
Property Type:
Physical inventory specifications determine construction cost per key, maintenance fee burden, and the demographic addressability of each product tier.
- Condominiums:Multi-unit buildings with shared amenities dominate Florida development pipelines due to economies of scale in construction and property management. Demand clusters among retiree segments seeking low-maintenance winter residences with resort-style service layers.
- Villas:Detached single-family structures with private pools command premium pricing in Mexico's Riviera Maya and Hawaii's Kohala Coast. Family travel segments absorb this inventory as multi-generational gathering venues with kitchen facilities reducing dining costs.
- Hotels:Traditional room inventory converted to fractional use through condo-hotel structures enables urban leisure positioning in Nashville, Las Vegas, and New Orleans where land constraints prohibit greenfield resort development.
- Townhouses:Attached multi-story units bridge the density gap between condominiums and villas, concentrating in Colorado ski markets and Carolina mountain destinations where terrain limits high-rise construction.
Condominiums dominate developer pipelines by volume; villas generate the steepest expansion trajectory in experiential leisure positioning.
Customer Type:
Purchaser demographic targeting calibrates sales floor scripting, financing product design, and exchange network marketing investments.
- Families:Multi-generational travel parties with school-calendar constraints drive demand for fixed-week inventory in Orlando and Anaheim proximity to theme park clusters. This segment absorbs the highest maintenance fee tolerance due to per-person cost spreading across larger household units.
- Millennials:Prime earning-year entrants prioritize points-based flexibility and Instagram-compatible destination variety over legacy fixed-week traditions. Mexico's Pacific coast and urban leisure markets capture disproportionate marketing investment aimed at this cohort.
- Retirees:Traditional snowbird segments with fixed income streams and established vacation patterns sustain fixed-week deeded demand in Florida and Arizona desert markets. FTC cooling-off period utilization rates run highest among this demographic.
- Corporate Groups:Incentive travel and executive retreat purchasers access inventory through bulk points acquisitions and meeting package bundling, concentrating in Las Vegas and Orlando convention corridor properties.
Families anchor current revenue recognition; millennials represent the fastest-growing trajectory as developers retool sales floors for younger conversion economics.
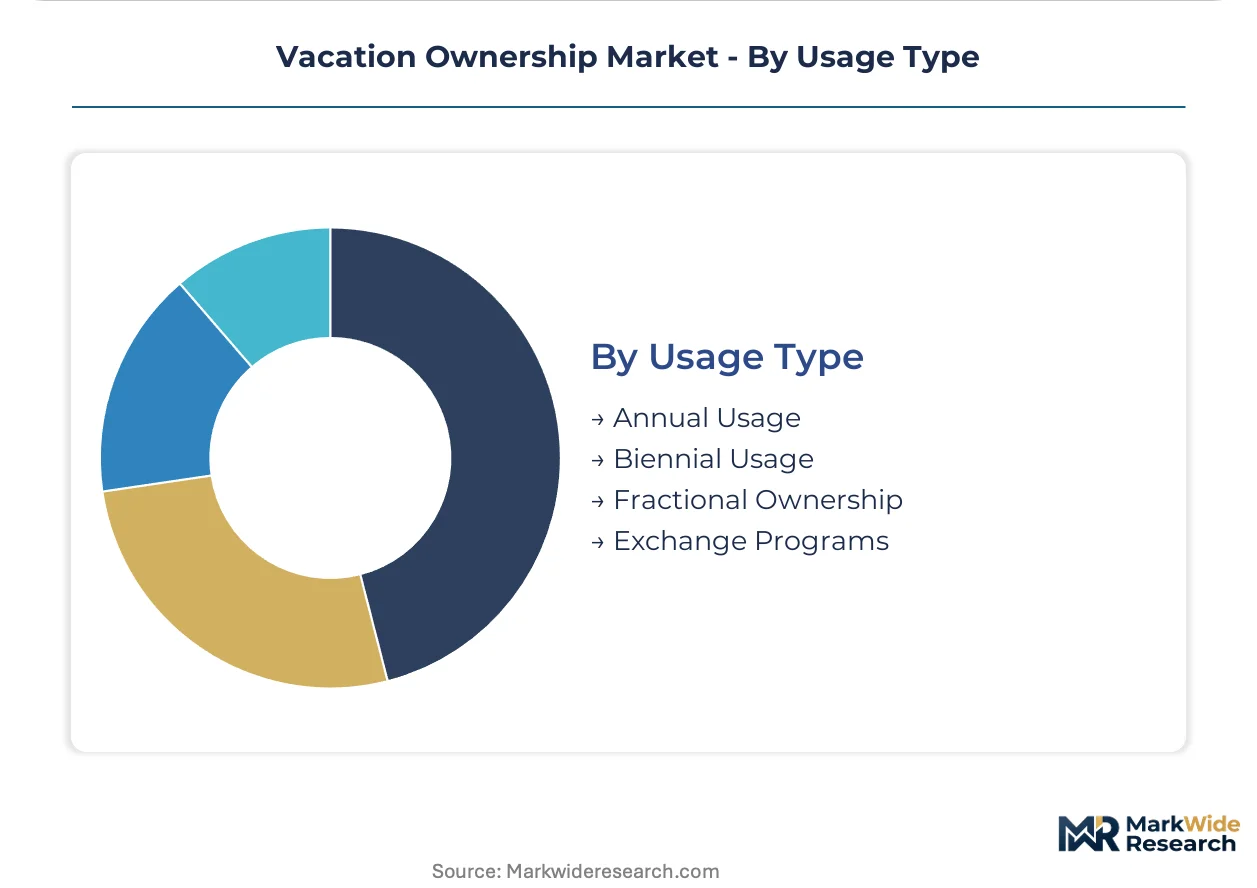
Usage Type:
Temporal access patterns determine inventory utilization rates, maintenance fee collection timing, and exchange network liquidity mechanics.
- Annual Usage:Traditional every-year entitlement structures sustain the highest maintenance fee revenue predictability and developer cash flow stability. Florida and Mexico inventory defaults to this structure as the baseline product configuration.
- Biennial Usage:Alternate-year access rights halve upfront purchase prices and maintenance obligations, expanding addressable markets among price-sensitive first-time buyers in mid-tier point systems.
- Fractional Ownership:Quarter-share and one-eighth interests in ultra-premium residences concentrate in Aspen, Vail, and Hamptons markets where whole-ownership costs exclude mass-market participation.
- Exchange Programs:Interval International and affiliated platform memberships convert fixed entitlements into destination liquidity, reducing purchase risk perception and accelerating sales floor conversion rates across all inventory types.
Annual usage retains the largest installed base; exchange programs are climbing the fastest as developers bundle membership subsidies into closing incentives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Developers arbitrage compliance costs by concentrating inventory in jurisdictions with streamlined escrow requirements and exchange-friendly regulatory frameworks. Mexico's PROFECO consumer protection protocols impose lighter lending disclosure burdens than US Federal Trade Commission mandates, diverting sales floor investment southward. This regulatory gradient concentrates capital deployment across four distinct national markets.
United States
Florida's Department of Business and Professional Regulation enforces project completion bonding that filters undercapitalized developers from Orlando and Miami-Dade corridors. The US Consumer Financial Protection Bureau intensifies scrutiny of timeshare lending practices, forcing Marriott Vacations Worldwide and Hilton Grand Vacations to restructure sales floor financing protocols. Inventory clusters concentrate in Orlando's theme park proximity and Arizona's desert retirement markets.
Mexico
PROFECO consumer protection frameworks govern cross-border marketing to North American buyers with lighter compliance overhead than US equivalents. Riviera Maya and Los Cabos resort corridors absorb the deepest foreign direct investment in vacation ownership inventory. Developers exploit this regulatory arbitrage to capture price-sensitive millennial cohorts at lower customer acquisition costs.
Canada
Ontario and British Columbia snowbird segments sustain fixed-week demand for Florida and Arizona inventory through Interval International exchange memberships. The country's Competition Act disclosure requirements shape cross-border sales floor scripting for Canadian purchasers. Toronto and Vancouver metropolitan areas generate the highest outbound vacation ownership inquiry volumes.
United Kingdom
UK Financial Conduct Authority regulations on consumer credit agreements constrain domestic timeshare financing innovation, pushing developers toward exchange network subscriptions. London and Southeast England concentrate the highest density of outbound leisure travelers accessing Mediterranean and Caribbean inventory through points-based systems. Brexit-related regulatory divergence complicates EU-based resort marketing to British buyers.
Vacation Ownership Market Competitive Environment
Branded specialists and contract developers split share differently across segments, with integrated hospitality conglomerates controlling premium deeded inventory while independent operators capture mid-market points-based volume. The market structure concentrates among five dominant parent entities with exchange network affiliations, creating tiered competitive dynamics. Three strategic archetypes define positioning: exchange-network-anchored developers, urban leisure specialists, and mid-market points system operators. Consolidation through resort portfolio acquisitions and technology platform licensing dominate competitive moves as players defend occupancy premiums.
Within the hospitality-conglomerate tier, Marriott Vacations Worldwide and Hilton Grand Vacations exemplify exchange-network density strategies, anchoring inventory in Orlando and Caribbean clusters where reservation liquidity sustains pricing power. Wyndham Destinations occupies a distinct mid-market position, controlling price-sensitive segments through lower entry thresholds in points-based systems. These three entities collectively represent the competitive spectrum from premium deeded condominiums to flexible entitlement structures.
| Leading Market Players |
|---|
| Marriott Vacations Worldwide |
| Hilton Grand Vacations |
| Wyndham Destinations |
| Travel + Leisure Co. |
| Disney Vacation Club |
| Bluegreen Vacations |
| Hyatt |
| Interval International |
| Resort Condominiums International |
| Others |
Value Chain & Pricing Dynamics
Captive exchange network ownership anchors both supply position and pricing power across developer portfolios, concentrating inventory liquidity control in Orlando and Caribbean clusters where Interval International density sustains reservation premiums. This vertical integration into entitlement platforms shields Marriott Vacations Worldwide and Hilton Grand Vacations from third-party platform fees while compressing working capital cycles for inventory transfers.
Pricing Analysis
Developer direct-to-consumer margins dominate vacation ownership economics, bypassing traditional travel distribution markups through sales floor financing products. Three-tier pricing structure across premium deeded condominiums, standard points-based memberships, and economy biennial access rights segments buyer cohorts by liquidity preference and income trajectory. Cost compression in mid-market points systems intensifies as Wyndham Destinations and Travel + Leisure Co. compete on entry thresholds, eroding per-unit revenue yields. Corporate group purchasers exhibit lowest price sensitivity due to meeting package bundling, while millennial first-time buyers absorb highest financing cost burden through extended payment terms.
Supply Chain Analysis
Florida escrow bonding requirements filter developer market access, concentrating construction pipelines among balance-sheet-deep operators capable of project completion guarantees. Concrete, steel, and interior finish materials draw from domestic US suppliers and Mexican manufacturing clusters across Riviera Maya development corridors. Single-source vulnerability concentrates in specialized resort amenity equipment sourced from European hospitality vendors. Distribution runs through developer-owned sales galleries and tour operator partnerships, with exchange network platforms providing secondary inventory liquidity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vacation ownership functions as a regulatory arbitrage play where Mexico's PROFECO framework imposes lighter lending disclosure burdens than US Federal Trade Commission mandates, diverting sales floor investment toward cross-border purchaser acquisition at lower compliance costs.
For Market Incumbents: Lock in exchange network density advantages by acquiring distressed inventory in Orlando and Caribbean clusters before competitor platform consolidation. Absorb elevated US Consumer Financial Protection Bureau compliance costs through captive finance subsidiary restructuring rather than third-party lending partnerships. Prioritize technology platform licensing to independent resort operators seeking Interval International affiliation without capital-intensive inventory development.
For New Entrants and Emerging Players: The premium-to-economy tier price-point gap in urban leisure destinations offers white-space entry for boutique condo-hotel developers targeting Nashville and New Orleans weekend travel extensions. Mid-market points-based systems in secondary Mexican markets—Puerto Vallarta, Mazatlán—remain penetrable through PROFECO-compliant direct marketing to Canadian snowbird segments. Pursue fractional management contracts with existing hotel owners seeking revenue stabilization without capital deployment.
For Investors and Strategic Acquirers: Consolidation pressure builds where maintenance fee default rates erode developer servicing economics and exchange network liquidity fragments across incompatible reservation systems. Long-term viability hinges on platform technology ownership rather than physical inventory accumulation. Target acquisition archetype: regional points-based operators with established Interval International affiliations and underoptimized sales floor conversion rates. Watch rescission rate volatility as inflection indicator—spikes above historical baselines signal regulatory enforcement intensity or sales floor talent degradation.
| Strategic Initiative | Industry Significance |
|---|---|
| Exchange Network Platform Integration | Interval International density in Orlando sustains reservation liquidity premiums for affiliated developers. |
| Cross-Border Mexican Marketing Expansion | PROFECO compliance pathways enable lower customer acquisition costs for North American buyer outreach. |
| Points-Based System Technology Licensing | Flexible entitlement structures capture millennial demand without per-unit construction cost inflation. |
| Urban Leisure Destination Pipeline Development | City-center inventory in Nashville and New Orleans captures business traveler leisure extension demand. |
| Blockchain Title Verification Implementation | Distributed ledger systems compress Caribbean and Orlando inventory transfer timelines from weeks to hours. |
Study Parameters
Direct dialogue with timeshare sales executives, resort development officers, exchange network platform managers, and consumer protection regulators grounded qualitative findings in operational reality. Secondary validation drew from US Federal Trade Commission enforcement actions, Florida Department of Business and Professional Regulation escrow filings, PROFECO consumer complaint databases, and SEC 10-K disclosures from publicly traded vacation ownership entities. Bottom-up inventory pipeline tracking across Orlando, Riviera Maya, and Caribbean clusters triangulated against top-down exchange network transaction velocity estimates.
Bottom-up modeling aggregated developer-reported unit deliveries, maintenance fee revenue streams, and exchange network membership flows across ownership model, property type, and customer type segmentation dimensions. Top-down validation cross-referenced hospitality industry capital expenditure surveys and resort construction permitting data. CAGRs were derived from regression analysis of historical entitlement sales against macroeconomic leisure spending indicators. Forecast inputs incorporated US Consumer Financial Protection Bureau regulatory intensity scenarios and millennial household formation trajectories.
Caveats apply where Florida escrow requirement modifications or PROFECO framework revisions could materially shift developer capital deployment patterns. Forecasts reflect assumptions regarding exchange network consolidation stability and hurricane damage frequency in inventory-concentrated corridors. A model refresh is warranted upon material change in rescission rate enforcement intensity or points-based system technology interoperability standards.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Short-term Rentals and Vacation Homes
Vacation Rental Website Market
Short-term Rentals and Vacation Homes
Online Home Rental Services Market
Short-term Rentals and Vacation Homes
Short-Term Rental Platform Market
Short-term Rentals and Vacation Homes
Europe Glamping Market
Short-term Rentals and Vacation Homes
Vacation Ownership Timeshare Market
Short-term Rentals and Vacation Homes
RV Rental Market
Short-term Rentals and Vacation Homes
Vacation Rentals Market
Short-term Rentals and Vacation Homes
Australia Glamping Market
Short-term Rentals and Vacation Homes
Treehouse Glamping Market
Short-term Rentals and Vacation Homes
Luxury Vacation Rental Market
Short-term Rentals and Vacation Homes
North America Glamping Market
Short-term Rentals and Vacation Homes
Asia-Pacific Glamping Market
Short-term Rentals and Vacation Homes
Short-Term Vacation Rental Market