
 Asia-Pacific Travel Retail Market | 2026-2036
Asia-Pacific Travel Retail Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Travel Retail Market Outlook
CE marking under the EU Cosmetics Regulation is rotating as the baseline qualification for beauty brands seeking shelf space in Asia-Pacific travel retail. Lotte Duty Free leverages its Incheon Airport dominance to control premium beauty allocations across Northeast Asia. China Duty Free Group anchors the Hainan market through captive retail infrastructure at Sanya and Haikou. Shilla Duty Free specializes in K-beauty curation, differentiating its offering from broader Western portfolios at Singapore Changi and Bangkok Suvarnabhumi.
Asia-Pacific travel retail encompasses duty-free and duty-paid commerce conducted within international transit zones, airport terminals, in-flight environments, and cruise vessels, where goods are sold to passengers holding valid boarding passes for cross-border journeys. Product authentication through serialized tax-stamp systems and real-time customs integration prevents diversion into domestic gray markets. Beauty Products generate the densest margin pools due to high impulse conversion and exclusive SKU strategies, while Airport Duty-Free channels capture the dominant traffic share against emerging Cruise Ships distribution. Leisure Travelers represent the fastest-expanding customer type as post-pandemic vacation itineraries rebound across Southeast Asian beach destinations.
Japan's Consumption Tax Act exemptions and China's Hainan offshore duty-free regulations, administered by the General Administration of Customs China, dictate inventory eligibility and purchase-quota frameworks that operators must embed into POS systems. South Korea's Ministry of Economy and Finance periodically adjusts duty-free licensing terms, directly affecting which consortia secure downtown and airport concessions. Stakeholders must monitor evolving customs-tech integration requirements as digital tax-refund platforms replace paper-based stamping across major Asia-Pacific transit hubs.
Market Dynamics
China's Hainan offshore duty-free quota expansion is redistributing passenger spending from overseas airports toward domestic island retail, forcing incumbent airport operators to restructure concession terms and inventory mix to retain brand partners.
Growth Catalysts
- Consumption Tax Exemptions:Japan's Consumption Tax Act rebates for foreign visitors incentivize downtown duty-paid shopping, extending retail capture beyond airport transit zones into urban commercial districts.
- Serialized Tax-Stamp Integration:Real-time customs data linkage at Seoul Incheon and Singapore Changi prevents inventory diversion, reassuring brand principals and unlocking exclusive SKU allocations for travel retail channels.
- Cruise Ship Terminal Expansion:Southeast Asian beach destination itineraries are rebuilding post-pandemic, creating floating retail environments with captive passenger bases and extended dwell times.
Market Restraints
- Quota Saturation Risk:China's annual offshore duty-free purchase limits constrain per-transaction value capture at Hainan, compressing average basket sizes despite high footfall.
- Concession Concentration:Lotte Duty Free and China Duty Free Group control dominant airport and downtown licenses across Northeast Asia, limiting new entrant access to premium locations.
- Gray Market Diversion:Weak authentication infrastructure at secondary transit hubs enables unauthorized resale of duty-free cosmetics into domestic channels, eroding brand equity.
Strategic Opportunities
- Vietnam and Philippines Airport Privatization:Emerging tier-1 airport expansions at Ho Chi Minh City and Manila offer first-mover concession opportunities outside established Northeast Asian hubs.
- Digital Tax-Refund Platforms:South Korea's Ministry of Economy and Finance mandates paperless VAT rebate processing, enabling seamless mobile integration and post-purchase engagement.
- K-Beauty Curation Specialization:Shilla Duty Free's focused Korean cosmetics portfolios demonstrate how regional brand aggregation can differentiate against Western luxury house saturation.
Industry Challenges
- Customs-Tech Integration Complexity:Operators must embed General Administration of Customs China real-time inventory protocols into legacy POS architectures, requiring substantial middleware investment.
- Staff Multilingual Capability Gaps:Airport retail environments demand Mandarin, Korean, Japanese, and English fluency for Chinese, South Korean, and Japanese passenger segments, constraining talent pools.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Travel Retail Market |
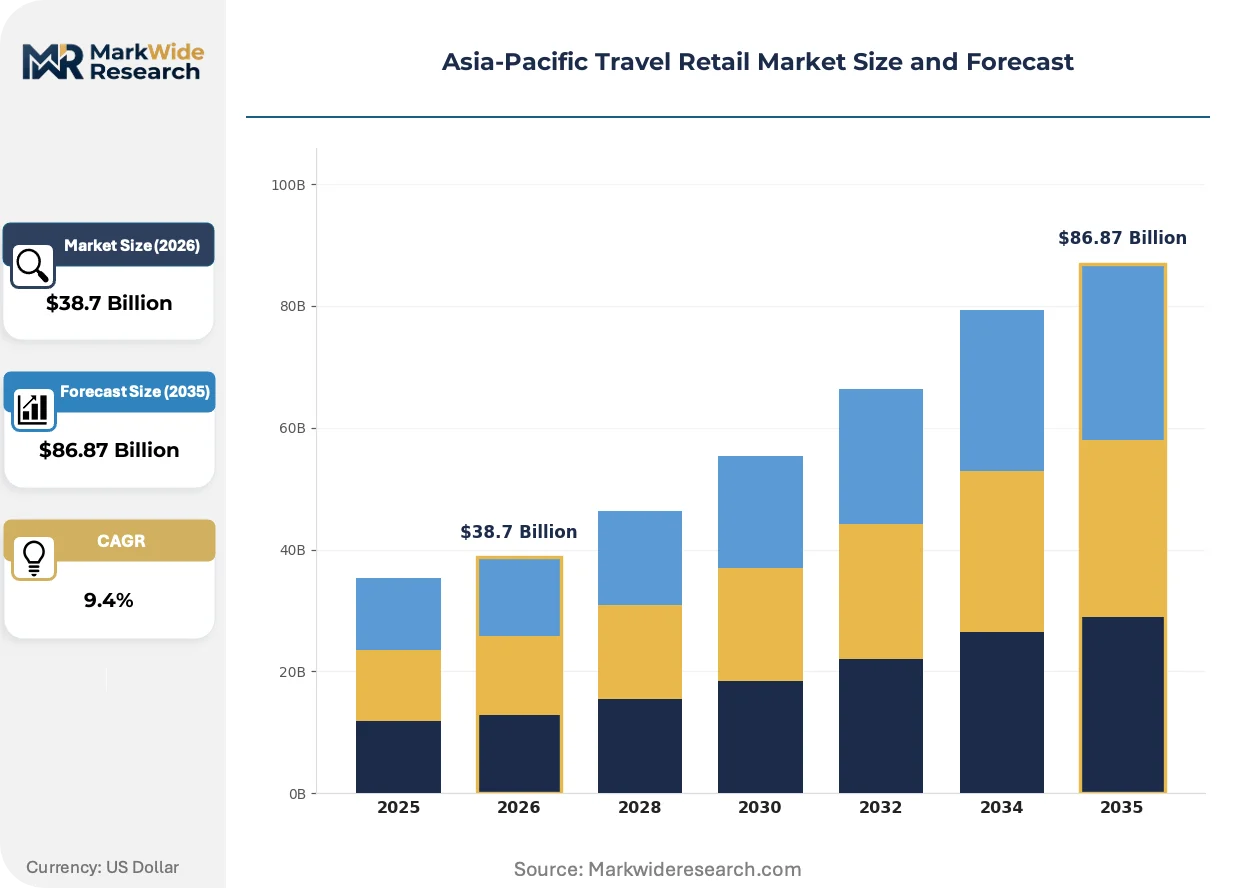
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $86.87 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Beauty Products, Fashion Apparel, Electronics, Confectionery Distribution Channel: Airport Duty-Free, In-Flight Sales, Train Stations, Cruise Ships Customer Type: Leisure Travelers, Business Travelers, Tour Groups, Frequent Flyers Price Tier: Luxury, Mid-Range, Budget, Discount |
| Companies Covered | Lotte Duty Free, Lagardère Travel Retail, China Duty Free Group (CTGDF), Gebr. Heinemann, King Power International Group, Dufry AG, Shilla Duty Free, Avolta, DFS Group, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Travel Retail Market Strategic Shifts
Serialized product authentication and mobile-first passenger engagement are displacing paper-based duty-free processes, compressing transaction friction while expanding post-purchase brand relationship channels beyond the physical retail moment.
Blockchain-enabled provenance verification is fragmenting trust architectures in luxury beauty retail. High-value cosmetics and skincare brands deploy distributed ledger systems to authenticate batch origins and prevent counterfeiting. Chinese and South Korean passengers, representing dominant spend profiles, increasingly demand scan-to-verify functionality before purchase completion. This technology is fragmenting traditional brand-retailer trust relationships into direct consumer-verification pathways that bypass operator intermediaries.
South Korea's Ministry of Economy and Finance licensing term adjustments are restructuring concession competitive dynamics. Periodic duty-free license renewals now incorporate digital sales integration and sustainability metrics as evaluation criteria. Airport and downtown operators must demonstrate technology infrastructure maturity to retain exclusivity. Northeast Asian hub airports face compressed preparation timelines for compliance demonstration ahead of renewal windows.
Pre-order mobile applications are capturing passenger wallet share before physical airport arrival. Chinese travelers utilizing Hainan offshore channels and international outbound routes increasingly complete product selection and payment via smartphone, treating physical collection as fulfillment rather than discovery. Duty-free operators at Seoul Incheon and Singapore Changi respond by reconfiguring floor space toward experience and sampling, reducing inventory-holding square footage. This behavioral pivot is most pronounced among leisure travelers under 35 years of age across Greater China origin markets.
Asia-Pacific Travel Retail Market Segmentation
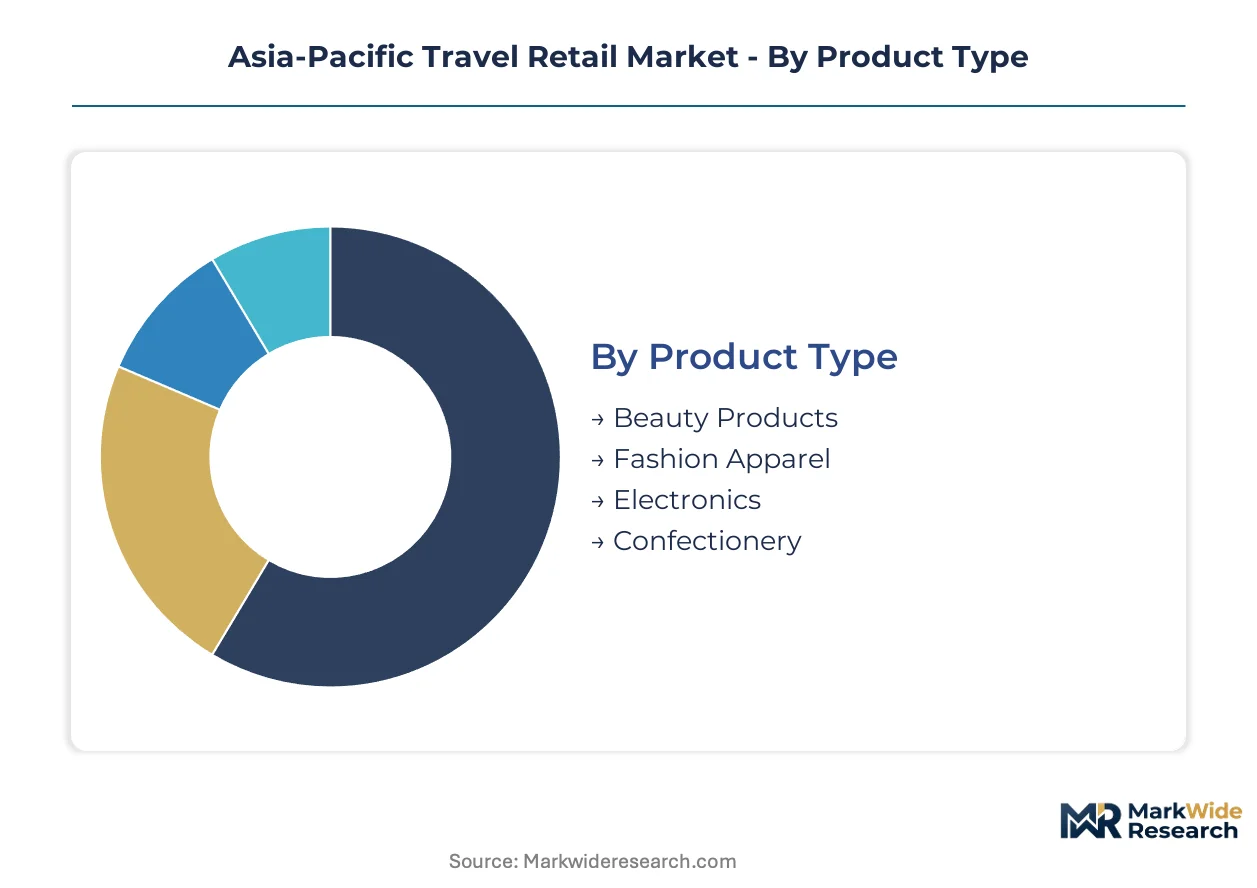
Asia-Pacific travel retail segmentation reflects divergent regulatory treatments across transit zones, with customs protocols and duty-free licensing frameworks determining which product categories and distribution channels achieve operational viability in specific jurisdictions.
Product Type:
CE marking under the EU Cosmetics Regulation functions as the baseline qualification threshold for beauty brands seeking shelf space across Asia-Pacific transit hubs, while electronics face divergent safety certification requirements between Japan's METI standards and China's GB protocols.
- Beauty Products:High-margin cosmetics and skincare lines deploy exclusive SKU strategies to prevent price arbitrage with domestic retail. China's Hainan Free Trade Port offshore quotas concentrate demand for premium fragrance and skincare assortments, though serialized tax-stamp integration requirements complicate inventory management for operators.
- Electronics:Mobile devices and accessories generate transaction velocity through currency arbitrage opportunities for Chinese and South Korean passengers. Japan's Consumption Tax Act exemptions extend electronics capture into downtown duty-paid environments beyond airport transit zones, redistributing passenger spending geographically.
- Fashion Apparel:Luxury house accessories and leather goods leverage limited-edition travel retail exclusives.
- Confectionery:Regional specialty food products target souvenir purchase occasions with compressed dwell-time conversion requirements.
Established volume favors Beauty Products; emerging adoption favors Electronics.
Distribution Channel:
Channel economics hinge on passenger dwell-time differentials and customs-tech integration maturity, with airport environments offering superior authentication infrastructure compared to floating retail platforms.
- Airport Duty-Free:Dominant traffic share at Seoul Incheon and Singapore Changi relies on real-time General Administration of Customs China data linkage to prevent inventory diversion. Operators reconfigure floor space toward experience and sampling as pre-order mobile applications capture wallet share before physical arrival.
- Cruise Ships:Southeast Asian beach destination itineraries generate extended passenger dwell times with captive retail environments. Post-pandemic itinerary rebuilding creates floating retail opportunities, though weaker authentication infrastructure at secondary terminals enables gray market diversion risks.
- In-Flight Sales:Compressed transaction windows favor small-format beauty and confectionery with immediate consumption profiles.
- Train Stations:Cross-border rail corridors between China and Southeast Asia offer emerging duty-paid capture opportunities.
Scale concentration favors Airport Duty-Free; steepest expansion trajectory favors Cruise Ships.
Customer Type:
Passenger segmentation aligns with itinerary purpose and purchase authorization frameworks, with leisure itineraries unlocking extended retail engagement windows compared to business transit patterns.
- Leisure Travelers:Vacation itineraries across Southeast Asian beach destinations generate the densest margin capture through impulse beauty and fashion purchases. Chinese travelers under 35 years of age increasingly complete product selection via smartphone before physical collection, treating airport retail as fulfillment rather than discovery.
- Business Travelers:Compressed transit schedules favor pre-order platforms and expedited collection points. South Korea's Ministry of Economy and Finance digital tax-refund mandates enable seamless mobile integration for time-constrained passenger segments.
- Tour Groups:Aggregated purchasing power secures preferential pricing and dedicated service protocols.
- Frequent Flyers:Loyalty program integration drives repeat purchase behavior across multiple transit occasions.
Revenue density favors Leisure Travelers; program stickiness favors Frequent Flyers.
Price Tier:
Pricing stratification reflects brand portfolio exclusivity agreements and quota-constrained purchase authorization frameworks, with luxury tiers commanding dedicated counter space and staff specialization requirements.
- Luxury:Premium beauty and fashion houses secure dedicated retail counters through exclusive SKU allocations. LVMH and Estée Lauder expansion at Seoul Incheon and Singapore Changi demonstrates how brand principals prioritize transit hubs with robust serialized authentication infrastructure.
- Mid-Range:Accessible premium segments capture quota-saturated passengers seeking value alternatives. China's Hainan offshore duty-free annual purchase limits compress average basket sizes, redirecting demand toward mid-range substitutions.
- Budget:Price-sensitive confectionery and accessories target impulse conversion with minimal staff interaction.
- Discount:Promotional inventory clearance operates through secondary channel partnerships.
Margin concentration favors Luxury; volume accessibility favors Mid-Range.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption tax exemptions and offshore duty-free quotas are redistributing passenger spending across the Asia-Pacific region, reshaping retail infrastructure investments and concession licensing priorities.
China
Hainan Free Trade Port offshore duty-free shopping quotas have transformed the island into a domestic alternative to overseas travel retail. The General Administration of Customs China administers purchase-quota frameworks and real-time inventory protocols that operators embed into POS systems. Sanya and Haikou anchor captive retail infrastructure where China Duty Free Group controls premium allocations.
South Korea
Seoul Incheon International Airport concentrates luxury beauty brand expansion from LVMH and Estée Lauder through dedicated travel retail counters. The Ministry of Economy and Finance periodically adjusts duty-free licensing terms, directly affecting which consortia secure downtown and airport concessions. Lotte Duty Free leverages its Incheon dominance to control premium beauty allocations across Northeast Asia.
Japan
Foreign visitor consumption tax exemptions under the Consumption Tax Act incentivize downtown duty-paid shopping, extending retail capture beyond airport transit zones. METI standards govern electronics safety certification, creating divergent compliance requirements from regional neighbors. Tokyo's commercial districts and Osaka's urban retail clusters absorb significant passenger spending through tax rebate programs.
Singapore
Changi Airport maintains serialized tax-stamp integration and real-time customs data linkage to prevent inventory diversion, reassuring brand principals and unlocking exclusive SKU allocations. The city-state's regulatory framework supports pre-order mobile application adoption among leisure travelers. Premium beauty and electronics concessions dominate terminal reconfigurations toward experience and sampling formats.
Thailand
Bangkok Suvarnabhumi Airport serves as a Southeast Asian hub where Shilla Duty Free specializes in K-beauty curation. Post-pandemic leisure itinerary rebuilding across beach destinations generates extended passenger dwell times. King Power International Group holds dominant concession positions linking airport retail to downtown duty-paid capture.
Asia-Pacific Travel Retail Market Competitive Environment
Listed leaders compete with private specialists across concession licensing and inventory allocation, creating a tiered structure where scale-driven operators face regional curators. The market consolidates around airport dominance and downtown duty-paid extension as dual vectors of competitive positioning. Three archetypes prevail: integrated airport-downtown operators, specialized beauty curators, and diversified global travel retailers. Capacity expansion through terminal reconfiguration and strategic partnerships with luxury houses constitute dominant competitive moves.
Within the integrated operator tier, Lotte Duty Free and China Duty Free Group exemplify scale-driven concession control across multiple transit hubs and urban locations. Shilla Duty Free occupies a specialized position representing K-beauty curation expertise against broader Western portfolios. Gebr. Heinemann anchors European-origin travel retail presence with Asia-Pacific expansion positioning.
| Leading Market Players |
|---|
| Lotte Duty Free |
| Lagardère Travel Retail |
| China Duty Free Group (CTGDF) |
| Gebr. Heinemann |
| King Power International Group |
| Dufry AG |
| Shilla Duty Free |
| Avolta |
| DFS Group |
| Others |
Value Chain & Pricing Dynamics
CE marking under the EU Cosmetics Regulation gates both supplier qualification and price stratification simultaneously, forcing beauty brands to absorb certification costs into landed pricing while operators leverage compliance scarcity to command premium shelf placement fees at Seoul Incheon and Singapore Changi.
Pricing Analysis
Certification level creates the primary spread across Asia-Pacific travel retail, with CE-marked beauty SKUs commanding dedicated counter space and staff specialization while non-certified alternatives compress into mid-range allocations. Luxury tiers deploy exclusive travel retail SKUs to prevent domestic price arbitrage, though China's Hainan offshore quota saturation redirects demand toward accessible premium substitutes. Pricing pressure stems from serialized tax-stamp integration mandates requiring middleware investment that operators pass through concession fees. Tour group buyers exhibit highest price sensitivity due to aggregated purchasing leverage, while individual leisure travelers under 35 years show lowest sensitivity to premium tiers when mobile pre-order platforms reduce transaction friction.
Supply Chain Analysis
Port congestion across the Shanghai-Singapore trade lane elevates inbound logistics costs for European-origin luxury beauty inventory, compressing operator margins before products reach Incheon or Changi terminals. Manufacturing concentration in France, Italy, and South Korea feeds the premium beauty pipeline, while electronics sourcing draws from Japan's METI-certified facilities and China's GB-standard plants. Supply chain risk centers on single-source vulnerability for serialized authentication hardware required by General Administration of Customs China protocols. Distribution runs through captive airport concession infrastructure controlled by Lotte Duty Free and China Duty Free Group, with downtown duty-paid extensions in Tokyo and Seoul adding secondary capture nodes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific travel retail functions as a service-attach opportunity where digital tax-refund platforms and mobile pre-order engagement layers expand faster than physical retail square footage, rewarding operators who capture recurring passenger interaction beyond single transactions.
For Market Incumbents: Secure exclusive SKU allocations through accelerated serialized authentication infrastructure deployment at secondary hubs before regulatory mandates harden compliance windows. Defend concession positions by embedding real-time General Administration of Customs China data protocols into legacy POS architectures, as licensing renewals now weight digital integration maturity. Counter gray market diversion risks through blockchain-enabled provenance verification that fragments traditional brand-retailer trust relationships into direct consumer pathways. For New Entrants and Emerging Players: Differentiate on K-beauty curation specialization following Shilla Duty Free's regional brand aggregation model against Western luxury house saturation. Target Vietnam and Philippines airport privatization windows at Ho Chi Minh City and Manila where first-mover concessions remain unclaimed by Northeast Asian incumbents. Penetrate through digital tax-refund platform partnerships with South Korea's Ministry of Economy and Finance paperless mandate as the regulatory entry wedge. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across customs-tech integration requirements as operators face compressed preparation timelines for compliance demonstration ahead of renewal windows. Long-term viability favors operators with dual airport-downtown footprints that capture both transit zone and urban duty-paid spending. Acquisition targets should demonstrate technology infrastructure maturity and sustainability metrics integration. Monitor South Korea's Ministry of Economy and Finance licensing term adjustments as the signal for concession competitive restructuring across Northeast Asian hubs.| Strategic Initiative | Industry Significance |
|---|---|
| Serialized Authentication Infrastructure Deployment | Unlocks exclusive SKU allocations from LVMH and Estée Lauder at premium transit hubs. |
| Mobile Pre-Order Platform Integration | Captures Chinese leisure traveler wallet share before physical airport arrival at Changi. |
| K-Beauty Curation Specialization | Differentiates offering against Western portfolios through regional brand aggregation expertise. |
| Downtown Duty-Paid Extension | Extends retail capture beyond transit zones into Tokyo's consumption tax rebate corridors. |
| Blockchain Provenance Verification | Prevents gray market diversion while satisfying Chinese passenger scan-to-verify demands. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with duty-free operators, brand principals, airport concession directors, and customs technology vendors; and secondary validation through General Administration of Customs China regulatory filings, South Korea Ministry of Economy and Finance licensing records, and airport authority concession disclosures. Bottom-up passenger spend modeling triangulated against top-down market sizing from trade lane cargo data and transit hub passenger statistics.
Across the analysis window, forecasts applied segmented growth assumptions by product type, distribution channel, customer itinerary purpose, and price tier, with CAGRs derived from elasticity-adjusted spend projections. Modeled inputs incorporated Hainan offshore quota utilization rates, Japan consumption tax exemption claim volumes, and cruise ship itinerary rebuilding patterns across Southeast Asian beach destinations.
Decision-makers should treat outputs as directional under base assumptions of continued customs-tech integration mandates and stable leisure travel recovery; material deviation would warrant model refresh. Specific risk factors include sudden quota contraction in Hainan, accelerated airport privatization timelines disrupting incumbent positioning, or authentication hardware supply disruptions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Travel and Tourism
US Outbound Tourism Market
Travel and Tourism
North America Pet Travel Services Market
Travel and Tourism
Halal Tourism Market
Travel and Tourism
Sustainable Tourism Market
Travel and Tourism
South Africa Sports Tourism Market
Travel and Tourism
Digital Travel Market
Travel and Tourism
Singapore Travel Retail Market
Travel and Tourism
Incentive Travel Market
Travel and Tourism
Wedding Tourism Market
Travel and Tourism
USA Sports Tourism Market
Travel and Tourism
Pet Travel Services Market
Travel and Tourism
Indonesia Sustainable Tourism Market
Travel and Tourism
Japan Outbound Tourism Market
Travel and Tourism
France Luxury Travel Market
Travel and Tourism
Sustainable Traveling Market
Travel and Tourism
UK Outbound Travel Market