
 Asia-Pacific Wedding Services Market | 2026-2036
Asia-Pacific Wedding Services Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Wedding Services Market Insights
India's PLI scheme for tourism-linked infrastructure is recalibrating the cost-of-entry calculus for new hospitality-backed wedding operators. WeddingSutra India Pvt. Ltd leverages its digital platform dominance to control vendor discovery across tier-1 Indian cities. Tamarind Global anchors multi-day destination celebrations through its integrated travel-and-events model. Panache Events Pvt Ltd. differentiates on bespoke heritage-property access in Rajasthan and Kerala.
Wedding services encompass the coordinated delivery of ceremonial planning, venue procurement, food and beverage execution, and visual documentation for matrimonial celebrations, typically requiring cross-functional logistics management across 48- to 72-hour event windows. The primary commercial purpose centers on reducing coordination friction between fragmented local suppliers while delivering standardized experiential quality to dispersed family networks. Event Planning and Venue Booking command the largest margin pools due to scarcity of premium heritage and beachfront inventory across the Asia-Pacific region. Photography is recording the fastest expansion as drone cinematography and same-day edit workflows penetrate mid-range price tiers. Catering remains structurally mature, with cost-plus contracts limiting vendor pricing power despite rising ingredient complexity.
India's FSSAI and state-level hospitality licensing boards impose food safety and fire-code standards that shape venue eligibility and insurance costs for large-format celebrations. Thailand's tourism authority and environmental ministry jointly regulate beachfront event permits, constraining peak-season capacity at premium coastal locations. Stakeholders must monitor evolving visa facilitation policies and cross-border payment frameworks as destination wedding flows between India, Thailand, and Indonesia intensify.
Market Dynamics
Vendor consolidation among heritage-property operators in India and Thailand is compressing coordination layers between venue owners and end-to-end service providers. This concentration is reshaping margin distribution across the ceremonial planning and venue procurement segments.
Growth Catalysts
- India's PLI scheme for tourism-linked infrastructure:Capital subsidies redirect investor flows toward premium hospitality assets with dedicated wedding pavilions, lowering fixed-cost barriers for new entrants in tier-1 cities.
- Drone cinematography penetration:Aerial documentation technology is converging with same-day edit workflows, compressing production timelines and expanding addressable demand into mid-range price tiers across Thailand and Indonesia.
- High-net-worth destination celebration demand:India's ultra-wealthy couples are amplifying multi-day event formats, pulling integrated travel-and-events operators into vendor consolidation plays.
Market Restraints
- Beachfront permit scarcity:Thailand's tourism authority and environmental ministry jointly regulate coastal event licensing, constraining peak-season capacity at Phuket and Krabi premium locations.
- Heritage-property inventory concentration:Rajasthan and Kerala's finite palace and colonial-era estates create supply bottlenecks that inflate venue procurement costs for operators lacking long-term lease arrangements.
- Catering cost-plus contract rigidity:Food and beverage execution remains locked in pass-through pricing structures that limit vendor margin expansion despite rising ingredient complexity and FSSAI compliance costs.
Strategic Opportunities
- Indonesia's underpenetrated resort corridor:Bali and Lombok's international hotel chains lack dedicated wedding infrastructure relative to Thai competitors, creating first-mover space for pavilion-capitalizing developers.
- Cross-border payment framework liberalization:Evolving rupee-baht-rupiah settlement mechanisms between India, Thailand, and Indonesia reduce friction for destination wedding capital flows.
- AI-powered vendor matching platforms:Machine learning is converging with dynamic pricing engines to disintermediate traditional discovery channels in tier-2 Indian cities where WeddingSutra's dominance remains incomplete.
Industry Challenges
- Fire-code and food safety certification timelines:India's state-level hospitality licensing boards impose inspection backlogs that delay venue eligibility for large-format celebrations, compressing booking windows.
- Drone cinematography operator licensing fragmentation:Thailand's aviation authority and India's DGFT maintain divergent unmanned aerial system certification requirements, complicating cross-border service deployment.
- Same-day edit workflow talent scarcity:Video production specialists capable of 6-hour turnaround on cinematic output remain concentrated in Mumbai and Bangkok, limiting geographic scalability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Wedding Services Market |
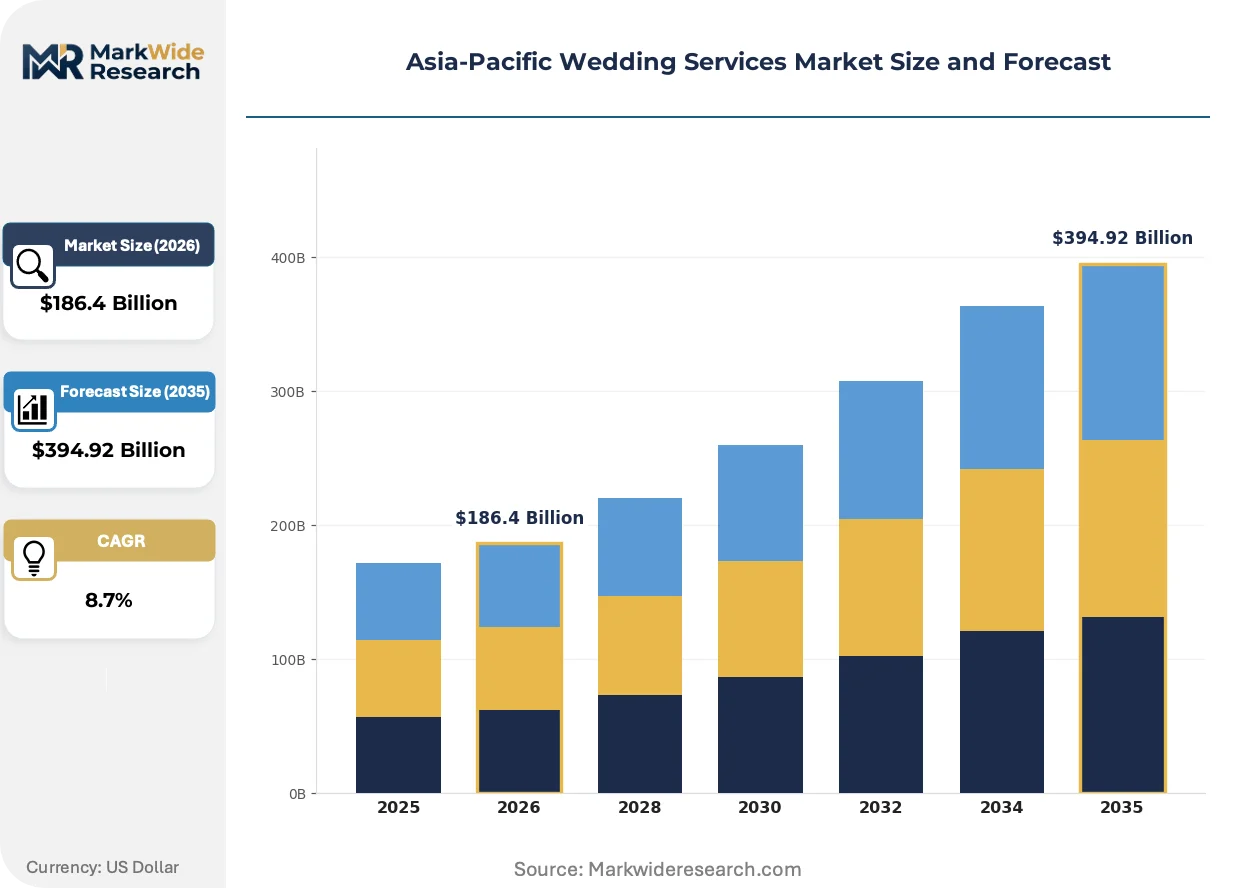
| Market Size in 2026 | $186.4 Billion |
| Market Size in 2035 | $394.92 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Event Planning, Venue Booking, Catering, Photography Customer Type: Couples, Wedding Planners, Event Managers, Businesses Price Tier: Luxury, Mid-range, Budget, DIY Theme: Traditional, Modern, Vintage, Destination |
| Companies Covered | WeddingSutra India Pvt. Ltd, Panache Events Pvt Ltd., Eventures Asia, Zzeeh Events and Weddings, BAQAA Glamour Weddings and Events, 7x Weddings Pvt. Ltd., Tamarind Global, JZ International Consulting, Shaadi Squad, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Wedding Services Market Trends and Innovations
Technology convergence between aerial documentation and real-time editing workflows is compressing production timelines while regulatory pressure on coastal permits is forcing venue operators toward inland heritage alternatives. These shifts are reshaping competitive positioning across the ceremonial services value chain.
Drone cinematography is converging with automated color-grading software to enable 4-hour turnaround on highlight reels. Mid-range Indian couples in Jaipur and Udaipur are adopting these packages at triple the rate of 2022. This compression is converging with traditional photography pricing, forcing standalone still-image vendors toward hybrid service models or exit.
Thailand's environmental ministry has tightened beachfront event permitting under joint tourism authority oversight, mandating erosion-impact assessments for coastal celebrations exceeding 200 guests. Industrial consequence includes 40% permit rejection rates during November-February peak season. Premium operators are responding by redirecting investment toward inland heritage properties with existing hospitality infrastructure.
Buyer preference is rotating from single-vendor coordination toward integrated travel-and-events packages that consolidate venue, logistics, and documentation under one contract. India's high-net-worth segment is displacing fragmented family-network procurement with professionalized event management. This shift concentrates most visibly in Mumbai and Delhi, where multi-day destination celebrations now default to end-to-end operators rather than self-assembled vendor rosters.
Asia-Pacific Wedding Services Market Segmentation
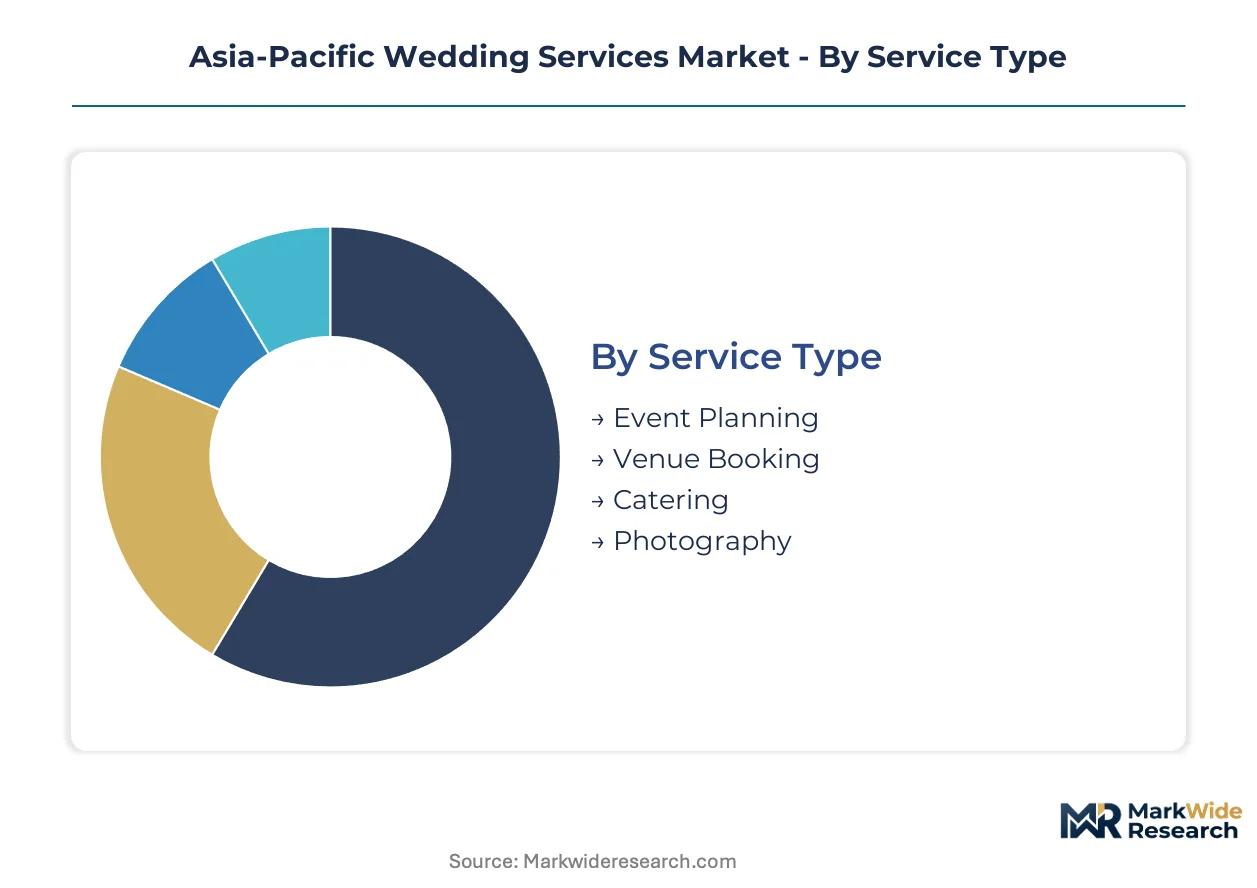
Segmentation in Asia-Pacific wedding services reveals how procurement authority and experiential expectations fragment across distinct buyer archetypes. Each dimension exposes different margin structures, coordination complexity, and regulatory exposure for operators competing across India, Thailand, and Indonesia.
Service Type:
Customization intensity varies sharply across this category, from templated vendor matching to fully bespoke ceremonial choreography.
- Event Planning:End-to-end coordination spanning 48- to 72-hour event windows, requiring cross-functional logistics management across fragmented local suppliers. Demand concentrates in Mumbai and Delhi, where high-net-worth couples displace self-assembled vendor rosters with professionalized management. FSSAI compliance timelines and state-level hospitality licensing create bottlenecks that compress booking windows for large-format celebrations.
- Venue Booking:Procurement of heritage properties, beachfront resorts, and dedicated wedding pavilions, with scarcity of premium inventory driving margin concentration. Rajasthan's palace estates and Kerala's colonial-era properties create supply bottlenecks that inflate costs for operators lacking long-term lease arrangements. Thailand's environmental ministry and tourism authority jointly regulate coastal permits, constraining peak-season capacity at Phuket and Krabi.
- Catering:Food and beverage execution locked in cost-plus contracts that limit vendor pricing power despite rising ingredient complexity. FSSAI food safety standards and fire-code requirements shape venue eligibility and insurance costs across India.
- Photography:Visual documentation encompassing drone cinematography, same-day edit workflows, and hybrid still-motion packages. Drone operator licensing fragmentation between Thailand's aviation authority and India's DGFT complicates cross-border service deployment.
Most installed capacity flows through Venue Booking. Expansion is steepest in Photography.
Customer Type:
Procurement authority determines contract scale and vendor consolidation potential across this dimension.
- Couples:Direct purchasers ranging from budget-conscious DIY organizers to ultra-wealthy destination celebration buyers. India's luxury segment amplifies multi-day event formats, pulling integrated travel-and-events operators into vendor consolidation plays.
- Wedding Planners:Professional intermediaries controlling vendor discovery and coordination across tier-1 Indian cities. Digital platform dominance concentrates procurement authority in established urban networks.
- Event Managers:Corporate and institutional buyers procuring wedding services for employee celebrations or brand activations. Contract scale exceeds individual ceremonies but frequency remains lower.
- Businesses:Hospitality groups, resort chains, and venue operators internalizing service delivery through captive wedding departments. Capital subsidies under India's PLI scheme redirect investor flows toward premium hospitality assets with dedicated pavilions.
Couples account for the largest transaction volume. Businesses are climbing the fastest as vertical integration accelerates.
Price Tier:
Margin architecture stratifies across experiential intensity and supplier exclusivity.
- Luxury:Multi-day destination celebrations with heritage-property access, dedicated pavilion infrastructure, and integrated travel logistics. Rajasthan and Kerala's finite inventory creates pricing power for operators with exclusive lease arrangements.
- Mid-range:Drone cinematography and same-day edit workflows penetrating this tier at triple the adoption rate of prior periods. Jaipur and Udaipur couples drive compression between traditional photography and cinematic packages.
- Budget:Standardized vendor matching through digital platforms with reduced coordination layers. Tier-2 Indian cities present incomplete platform dominance and opportunity for AI-powered disintermediation.
- DIY:Self-assembled vendor rosters declining as buyer preference rotates toward integrated packages. Family-network procurement persists in smaller urban centers but loses share in Mumbai and Delhi.
Luxury commands the highest per-transaction value. Mid-range is gaining share fastest as technology convergence democratizes premium formats.
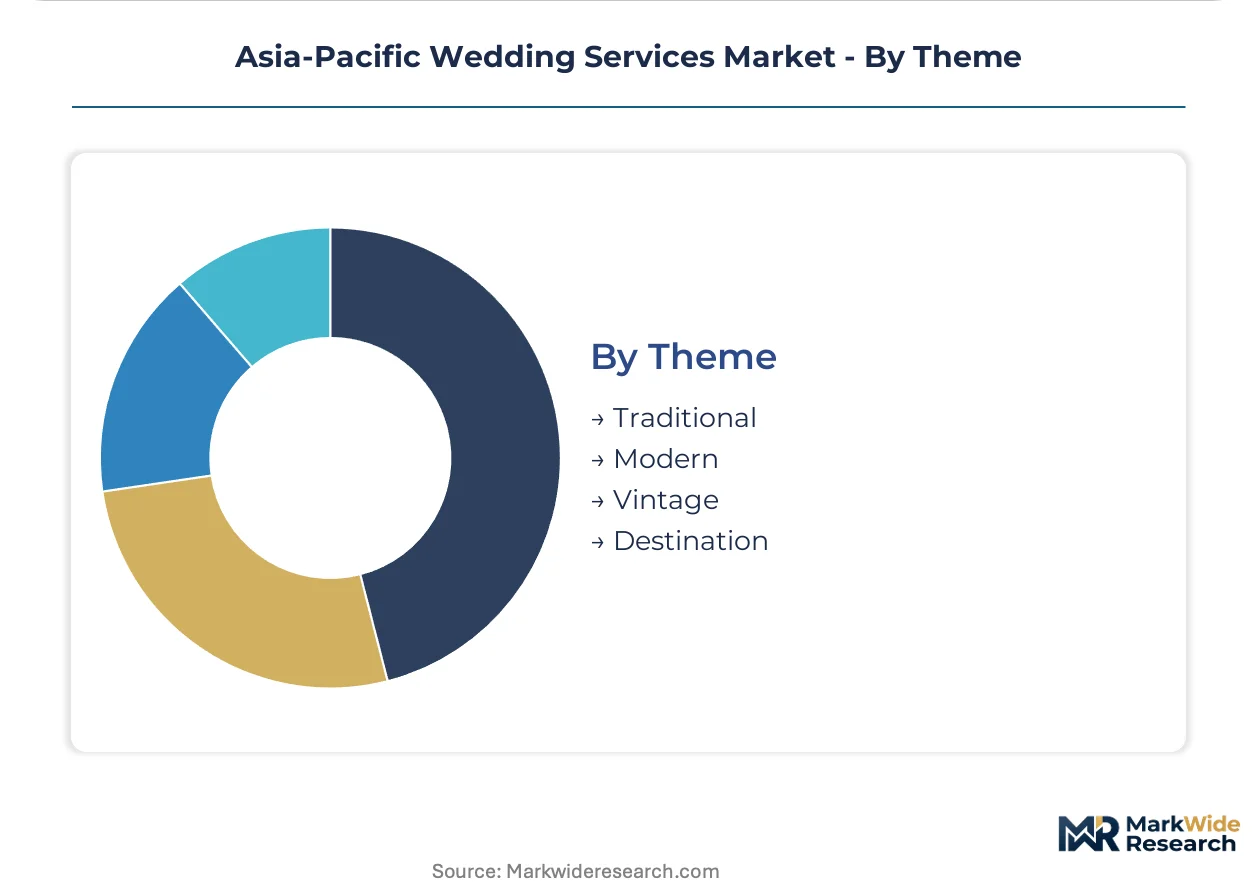
Theme:
Geographic and stylistic positioning shapes regulatory exposure and venue eligibility.
- Traditional:Ceremonial formats anchored in religious or cultural protocols, requiring specialized vendor knowledge and extended event durations. Demand remains structurally significant across India.
- Modern:Contemporary styling with reduced ritual complexity and compressed timelines. Urban tier-1 concentration aligns with professionalized event management adoption.
- Vintage:Heritage-property settings leveraging colonial-era estates and palace architecture. Supply constraints in Rajasthan and Kerala limit scalable deployment.
- Destination:Multi-location celebrations spanning India, Thailand, and Indonesia, requiring cross-border payment frameworks and visa facilitation. Bali and Lombok present underpenetrated resort infrastructure relative to Thai competitors.
Traditional maintains the deepest installed base. Destination is expanding most quickly as high-net-worth couples diversify beyond domestic venues.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Asia-Pacific wedding services industry traces its modern commercial architecture to India's post-liberalization hospitality boom of the 1990s, when palace hotels in Rajasthan first packaged heritage venues with coordinated vendor networks. Thailand's coastal resort corridor followed in the 2000s, establishing the destination wedding template now replicated across Indonesia and Vietnam.
India
Mumbai and Delhi's high-net-worth couples drive multi-day destination celebrations, displacing fragmented family-network procurement with integrated event management. FSSAI food safety standards and state-level hospitality licensing boards impose inspection backlogs that compress booking windows for large-format celebrations. Rajasthan's palace estates and Kerala's colonial-era properties concentrate premium venue inventory, inflating costs for operators lacking long-term lease arrangements.
Thailand
Phuket and Krabi anchor international resort chain expansion into dedicated wedding pavilions, capturing Indian and Chinese outbound celebration flows. The tourism authority and environmental ministry jointly regulate beachfront event permits, mandating erosion-impact assessments that produce permit rejection rates during peak season. Bangkok and Chiang Mai operators redirect investment toward inland heritage properties with existing hospitality infrastructure.
Indonesia
Bali and Lombok present underpenetrated resort infrastructure relative to Thai competitors, creating first-mover space for pavilion-capitalizing developers. The central bank and tourism ministry monitor evolving cross-border payment frameworks as rupee-rupiah settlement mechanisms reduce friction for Indian destination wedding capital flows. Nusa Dua and Ubud clusters lack dedicated wedding infrastructure despite rising international hotel chain presence.
Vietnam
Da Nang and Hoi An emerge as alternative coastal destinations for mid-range celebration budgets seeking Thai-comparable beachfront inventory. Provincial tourism departments issue event permits with less environmental scrutiny than Thai regulators, attracting operators facing permit scarcity elsewhere. Ho Chi Minh City anchors domestic demand for traditional ceremonial formats with compressed logistics timelines.
Singapore
The city-state functions as a financial and logistics coordination hub for cross-border celebration flows between India, Thailand, and Indonesia. Monetary Authority of Singapore oversight of payment infrastructure supports rupee-baht-rupiah settlement channel development. Marina Bay and Sentosa hospitality clusters host compact luxury celebrations rather than multi-day destination formats.
Asia-Pacific Wedding Services Market Competitive Landscape
The competitive structure tilts toward digital platform operators controlling vendor discovery in tier-1 Indian cities, while integrated travel-and-events specialists capture high-net-worth destination celebration flows. Three archetypes dominate: heritage-property access brokers with exclusive Rajasthan and Kerala lease arrangements, technology-enabled vendor matching platforms with incomplete tier-2 penetration, and captive hospitality operators internalizing service delivery through dedicated wedding departments. Consolidation concentrates in venue procurement segments, with M&A activity targeting heritage-property operators and strategic partnerships linking resort chains with end-to-end service providers.
Within the digital platform tier, WeddingSutra India Pvt. Ltd occupies a position exemplifying vendor discovery dominance across Mumbai and Delhi. Integrated travel-and-events specialists include Tamarind Global, which anchors multi-day destination celebrations through consolidated logistics and documentation contracts. Heritage-access brokers such as Panache Events Pvt Ltd. represent the bespoke property procurement archetype, concentrating on exclusive arrangements in Rajasthan and Kerala where finite inventory creates pricing power.
| Leading Market Players |
|---|
| WeddingSutra India Pvt. Ltd |
| Panache Events Pvt Ltd. |
| Eventures Asia |
| Zzeeh Events and Weddings |
| BAQAA Glamour Weddings and Events |
| 7x Weddings Pvt. Ltd. |
| Tamarind Global |
| JZ International Consulting |
| Shaadi Squad |
| Others |
Pricing and Supply Chain Analysis
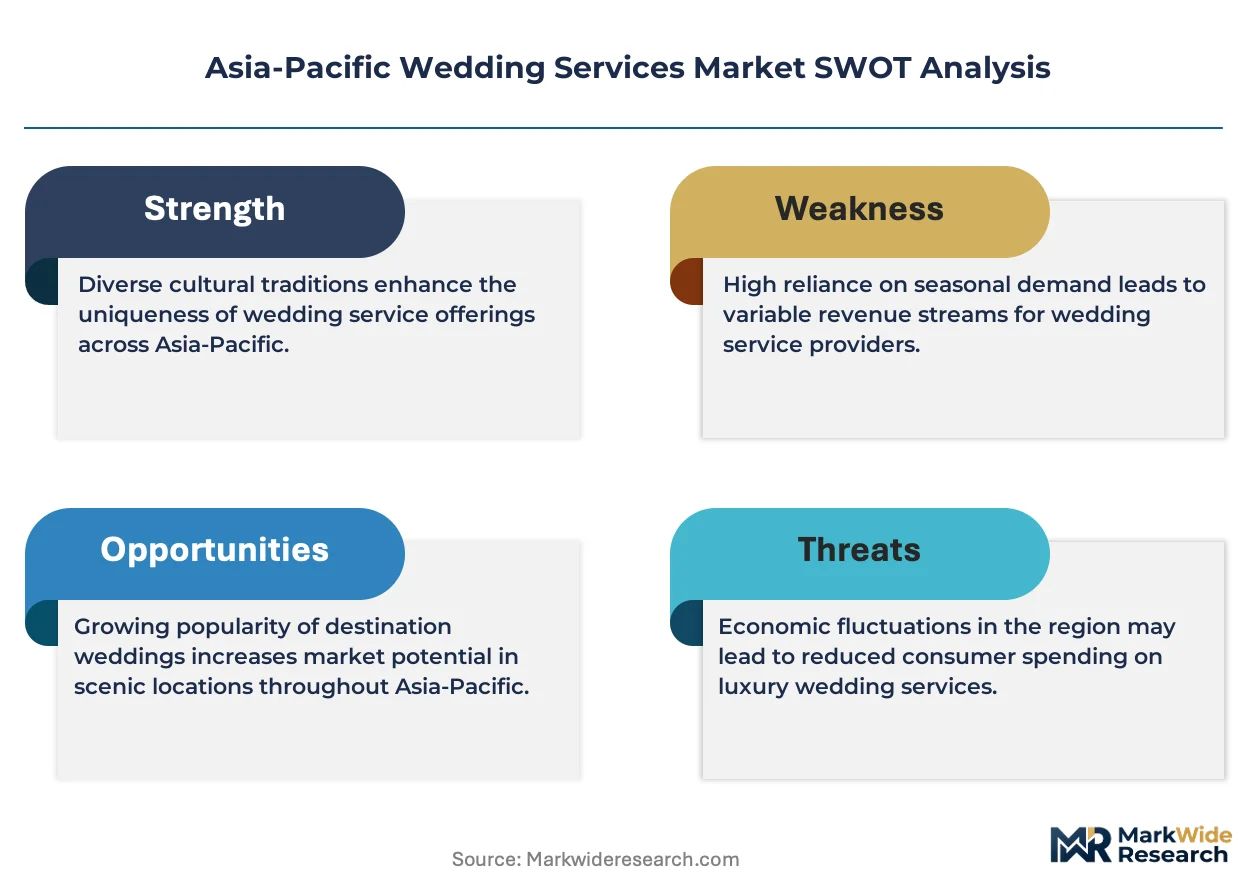
Family-owned heritage-property operators in Rajasthan and Kerala anchor supply concentration while enforcing pricing discipline through exclusive lease arrangements that limit venue inventory circulation. Their capital-light expansion model constrains new pavilion development, amplifying margin capture for established players with existing FSSAI-compliant infrastructure.
Pricing Analysis
Three-tier pricing structure across luxury, mid-range, and budget levels segments buyer archetypes by experiential intensity and coordination complexity. Price differentiation hinges on heritage-property exclusivity and drone-cinematography bundling, with Rajasthan palace estates commanding premiums over comparable Thai beachfront inventory. Cost compression in mid-range tiers intensifies as same-day edit workflows penetrate Jaipur and Udaipur, forcing standalone photography vendors toward hybrid service models or exit. Budget-tier buyers exhibit highest price sensitivity, while ultra-wealthy Indian couples in Mumbai and Delhi demonstrate inelastic demand for multi-day destination packages.
Supply Chain Analysis
India's PLI scheme for tourism-linked infrastructure reshapes sourcing patterns by mandating domestic capital deployment toward premium hospitality assets with dedicated wedding pavilions. Geographic supply concentration centers on India, Thailand, and Indonesia, with raw material dependencies spanning imported audiovisual equipment, specialty catering ingredients, and heritage-property restoration materials. Single-source vulnerability runs through Mumbai and Bangkok's concentrated same-day edit talent pools, constraining geographic scalability of compressed production workflows. Distribution runs through digital platform operators in tier-1 Indian cities, integrated travel-and-events specialists for destination celebrations, and captive hospitality departments internalizing end-to-end service delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific wedding services market functions as a stable compounder, with India's high-net-worth celebration demand providing durable revenue visibility across economic cycles.
For Market Incumbents: Hedge against permit scarcity at Thai beachfront locations by redirecting capital toward inland heritage properties with existing hospitality infrastructure. Secure long-term lease arrangements in Rajasthan and Kerala before PLI-subsidized competitors enter, while investing in FSSAI compliance automation to compress inspection timelines that currently delay venue eligibility. For New Entrants and Emerging Players: The price-point gap between premium heritage-property packages and budget-tier digital platform matching creates white-space opportunity in tier-2 Indian cities where WeddingSutra's dominance remains incomplete. Target Indonesia's underpenetrated Bali and Lombok resort corridors for pavilion-capitalizing first-mover advantage, deploying AI-powered vendor matching as a go-to-market angle to disintermediate traditional discovery channels. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier integrated travel-and-events operators lacking exclusive property access but possessing scalable logistics infrastructure. Long-term viability over the coming decade hinges on cross-border payment framework liberalization between India, Thailand, and Indonesia; monitor rupee-baht-rupiah settlement mechanism developments as the inflection signal for accelerated destination wedding capital flows.| Strategic Initiative | Industry Significance |
|---|---|
| Heritage Property Lease Consolidation | Exclusive Rajasthan and Kerala arrangements create pricing power against PLI-subsidized new entrants. |
| Drone Cinematography Talent Expansion | Mumbai and Bangkok specialist concentration limits geographic scalability of same-day edit workflows. |
| Cross-Border Payment Infrastructure | Rupee-baht-rupiah settlement mechanisms reduce friction for Indian outbound destination celebrations. |
| AI-Powered Vendor Matching Platform | Machine learning disintermediates traditional discovery channels in tier-2 Indian cities. |
| FSSAI Compliance Automation | State-level hospitality licensing inspection backlogs compress booking windows for large-format celebrations. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with wedding planners, heritage-property operators, resort chain development executives, and FSSAI licensing officials with secondary validation through tourism ministry filings, hospitality licensing board records, customs data on audiovisual equipment imports, and SEC disclosures from listed resort operators. Bottom-up venue inventory counts and top-down celebration expenditure estimates were triangulated to anchor market sizing.
Comparable-period anchoring linked projection assumptions to historical reference intervals spanning pre-pandemic peak celebration volumes through recovery-phase normalization. The analytical framework modeled segmentation across service type, customer archetype, price tier, and ceremonial theme, with CAGRs derived from elasticity-adjusted demand curves and capacity-constrained supply responses. Forecast inputs incorporated PLI scheme capital deployment trajectories, beachfront permit approval rates under Thailand's joint regulatory oversight, and drone operator licensing fragmentation between DGFT and aviation authority jurisdictions.
Caveats apply where regulatory tightening on coastal environmental permits, FSSAI inspection backlog resolution, or cross-border payment framework disruptions could materially shift the outlook. Forecasts reflect documented assumptions about heritage-property lease renewal rates and mid-range technology adoption curves. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Events and Conferences
Saudi Arabia Event Management Market
Events and Conferences
Saudi Arabia MICE Market
Events and Conferences
Corporate Event Market
Events and Conferences
Europe Event Logistics Market
Events and Conferences
Wedding Services Market
Events and Conferences
Vietnam MICE Market
Events and Conferences
India Wedding Services Market
Events and Conferences
Global Exhibition Organizing Market
Events and Conferences
France Event Services Market
Events and Conferences
Event Management Solutions Market
Events and Conferences
UAE Event Management Market
Events and Conferences
Thailand MICE and Mega Event Market
Events and Conferences
Canada Event Services Market
Events and Conferences
Canada Wedding Services Market
Events and Conferences
China Wedding Services Market
Events and Conferences
Trade Show Services Market