
 Global Archiving Software Market | 2026-2036
Global Archiving Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Archiving Software Market Foresight
Enterprise software distribution is fragmenting as cloud marketplaces, direct vendor sales, and managed service intermediaries compete for procurement budgets. Microsoft leverages its Azure ecosystem to bundle archiving with productivity suites, while IBM anchors its position through mainframe-integrated governance tools. Commvault differentiates via unified data protection platforms that span backup and archive workflows.
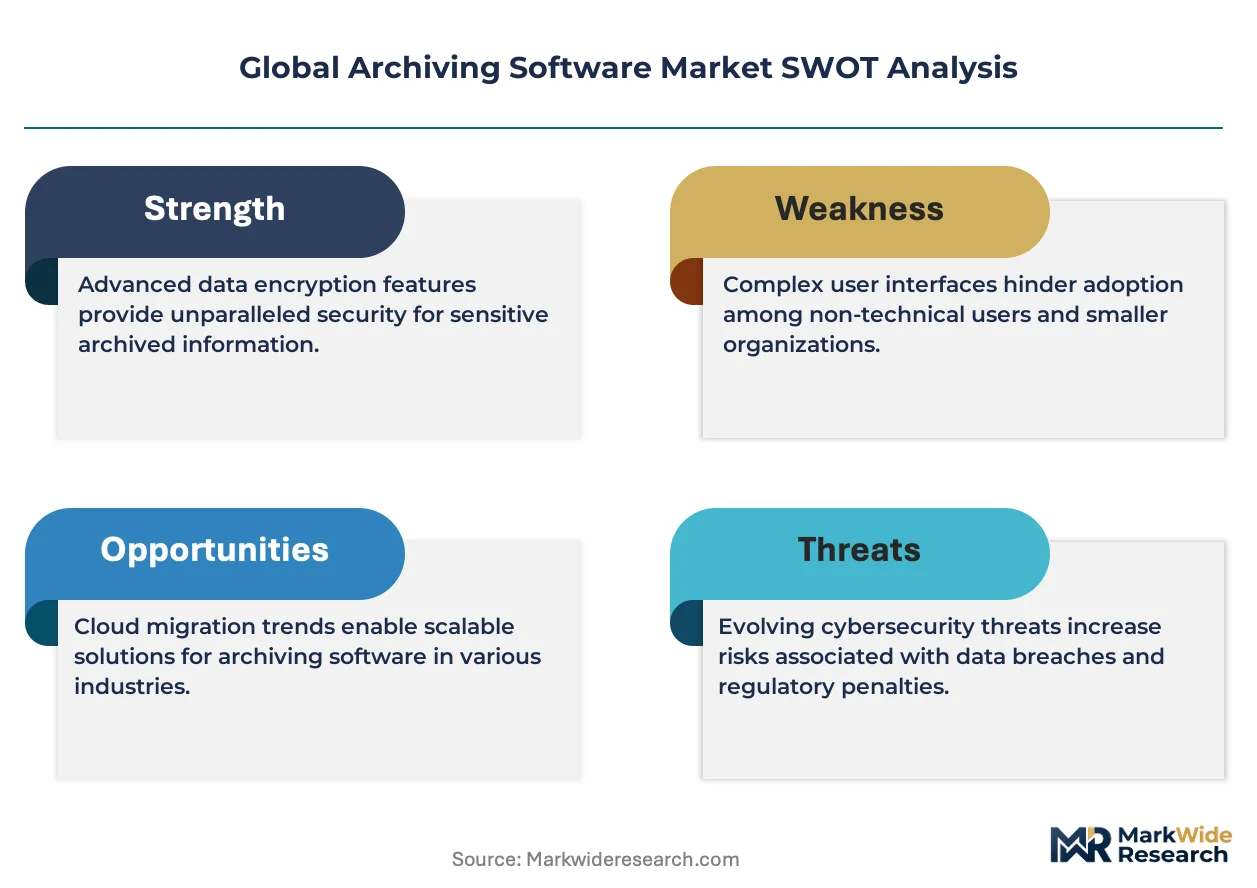
Archiving software comprises systems that capture, index, store, and retrieve structured and unstructured information across retention lifecycles, typically supporting WORM (Write Once Read Many) storage, metadata tagging, and legal-hold capabilities to ensure evidentiary integrity. Enterprise archiving and cloud-based deployment command the largest revenue pools, though compliance archiving and hybrid cloud configurations are expanding fastest as organizations navigate jurisdictional data sovereignty requirements. Email archiving retains maturity in financial services, while digital asset management segments show rising traction among media conglomerates handling high-resolution creative libraries.
The SEC, HIPAA, and EU GDPR collectively enforce retention periods, audit trails, and deletion protocols that dictate product feature roadmaps and customer procurement criteria. France's CNIL and Germany's federal data protection authority impose additional territorial obligations that complicate cross-border archive replication. Stakeholders must monitor evolving eDiscovery standards and AI training data provenance rules that will reshape information lifecycle governance investments.
Market Dynamics
The archiving software sector faces a structural inflection as EU AI Act retention mandates and GDPR deletion protocols force enterprises to rebuild data governance stacks from compliance modules upward.
Growth Catalysts
- Healthcare data explosion:Patient imaging and electronic health record volumes in Germany, France, and the United States are forcing hospital networks to deploy automated tiered storage with legal-hold capabilities.
- EU AI Act Article 50:Training data provenance requirements are compelling AI developers to implement immutable audit trails and WORM-compliant repositories for model lineage documentation.
- SEC 17a-4(f) enforcement:Broker-dealers in the United States face intensified examination schedules for electronic record-keeping, driving replacement of legacy tape-based systems with compliant cloud archives.
Market Restraints
- Cloud egress cost volatility:Hyperscaler retrieval fees for long-term cold storage create unpredictable total cost of ownership that complicates multi-year budgeting for financial services procurement teams.
- Data sovereignty fragmentation:Germany's BSI technical guidelines, France's ANSSI cloud security requirements, and divergent national implementations of GDPR Article 44 are fragmenting vendor certification pathways.
- Legacy mainframe dependency:Large European insurers remain tethered to IBM z/OS environments, constraining migration velocity to modern object-storage architectures despite technical obsolescence.
Strategic Opportunities
- India's digitization push:RBI mandated data localization for payment systems and SEBI's growing eDiscovery expectations are creating first-mover advantages for vendors establishing compliant in-country infrastructure.
- AI training data marketplaces:Provenance-verified archival repositories that cryptographically attest to data origin and processing history are emerging as licensable assets for foundation model developers.
- Blockchain-anchored immutability:Distributed ledger notarization layered atop conventional WORM storage is rendering evidentiary chains tamper-evident for cross-border litigation support.
Industry Challenges
- Forensic metadata engineering:The scarcity of specialists who can design index schemas satisfying simultaneous eDiscovery, privacy, and AI lineage requirements is extending implementation timelines.
- Cross-border replication complexity:Synchronizing deletion schedules across German federal record-keeping laws, French CNIL guidance, and SEC retention mandates demands jurisdictional workflow orchestration that most platforms lack natively.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Archiving Software Market |
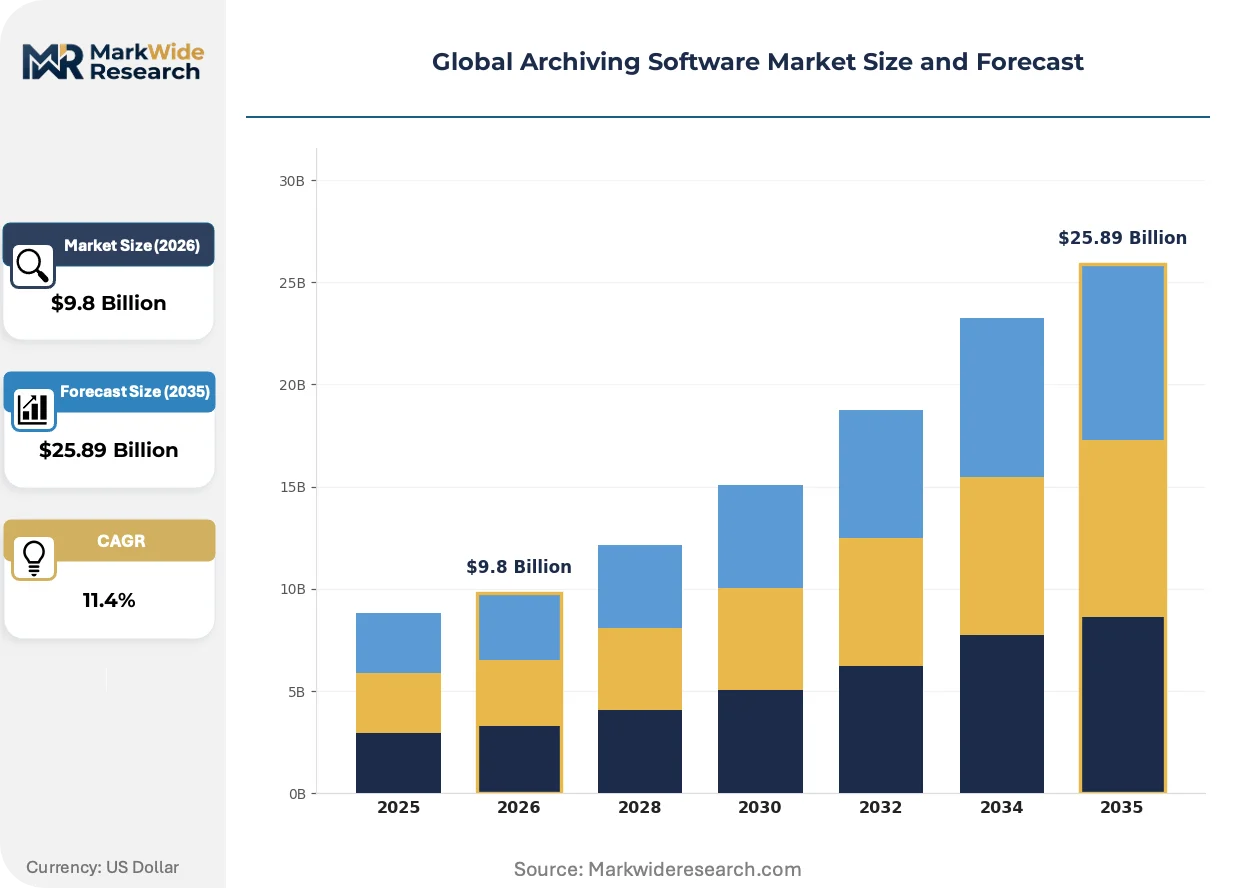
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $25.89 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Enterprise Archiving, Email Archiving, Content Archiving, Compliance Archiving, Digital Asset Management Deployment: On-Premises, Cloud-Based, Hybrid Cloud, Hosted, Managed Services Application: Data Retention, Regulatory Compliance, Litigation Support, Data Backup, eDiscovery, Information Management End User: BFSI, Legal Firms, Government Agencies, IT & Telecom, Media & Entertainment |
| Companies Covered | Veritas Technologies LLC, Microsoft Corporation, IBM Corporation, OpenText Corporation, Commvault Systems Inc., Barracuda Networks, Inc., Mimecast Limited, Google LLC, Proofpoint, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Archiving Software Market Shifts & Advancements
Intelligent classification engines and automated policy enforcement are compressing the archival value chain, collapsing manual triage layers that previously separated ingestion from compliance verification.
Neural content analysis is rendering obsolete keyword-dependent discovery workflows. Financial services litigation teams in London and New York now deploy transformer-based entity extraction that surfaces privileged communications without exhaustive manual review. This capability is compressing eDiscovery timelines from months to days while raising evidentiary admissibility standards.
CSRD sustainability disclosure requirements are mandating decade-long retention of carbon accounting records and supply chain audit trails. Industrial manufacturers in Germany and the Netherlands are retrofitting archival systems with ESG-specific metadata taxonomies. The automotive sector faces particular pressure as KBA type-approval documentation must now link to lifecycle environmental data.
Subscription-based archive-as-a-service models are displacing perpetual license deployments among mid-market enterprises. Channel partners in the United Kingdom and Australia now lead with consumption-priced offerings that bundle ingestion, storage, and legal-hold management. Healthcare providers in Canada are piloting these structures to align cash outflows with patient record growth curves.
Global Archiving Software Market Segmentation
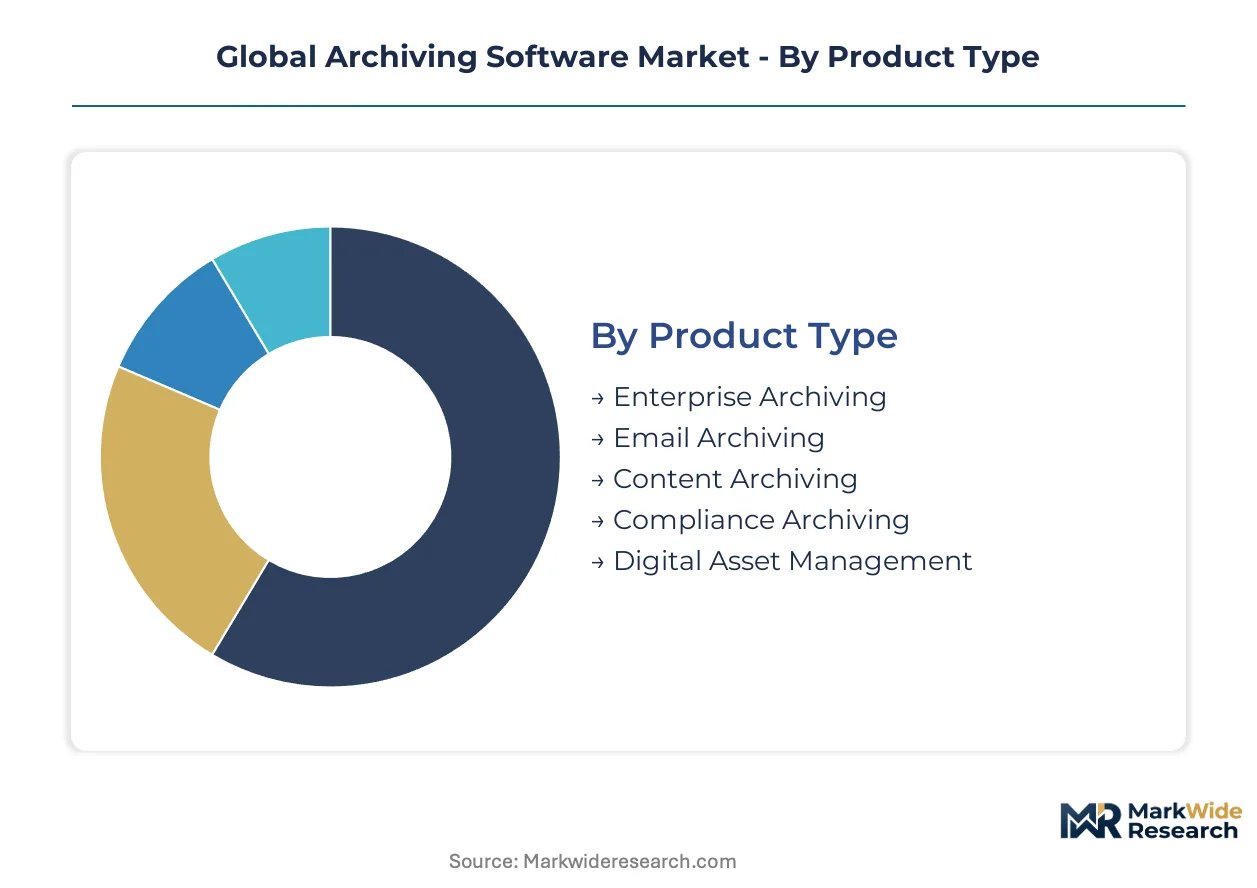
Segmentation in archiving software reveals divergent procurement rhythms across deployment modes, end-user industries, and compliance intensity levels. Understanding these cycle-time differentials enables vendors to calibrate sales motions and product roadmaps against actual customer refresh patterns rather than assumed uniformity.
Product Type:
Enterprise archiving commands the longest replacement cycles at seven to ten years, while compliance archiving refreshes every two to four years as mandates evolve.
- Enterprise Archiving:Comprehensive systems integrating structured and unstructured data repositories with WORM storage and legal-hold capabilities. German automotive manufacturers and French pharmaceutical groups anchor demand as they consolidate decades of engineering documentation and clinical trial records under unified governance frameworks.
- Compliance Archiving:Purpose-built platforms engineered for SEC 17a-4(f), HIPAA, and GDPR Article 44 retention with automated audit trails. United States broker-dealers and EU AI Act-regulated AI developers are driving replacement of legacy tape systems with immutable cloud repositories to satisfy training data provenance requirements.
- Email Archiving:Specialized solutions capturing messaging metadata and content for eDiscovery readiness.
- Content Archiving:Web and document management systems preserving institutional knowledge bases.
- Digital Asset Management:Creative-focused repositories handling high-resolution media libraries with version control.
Enterprise archiving anchors the volume base while compliance archiving gains share at the steepest rate.
Deployment:
Cost tier stratification separates hyperscaler-native consumption models from capital-intensive on-premises infrastructure commitments.
- Cloud-Based:Fully managed object storage with elastic scaling and geographic redundancy. Healthcare networks in Canada and financial services firms in the United Kingdom are migrating patient records and trading communications to consumption-priced archives that align cash outflows with data growth curves.
- Hybrid Cloud:Tiered architectures keeping active litigation holds on-premises while archiving cold data to cloud. German federal contractors and Dutch industrial manufacturers favor this configuration to satisfy BSI technical guidelines and CSRD sustainability disclosure mandates without surrendering jurisdictional control.
- On-Premises:Dedicated hardware installations for air-gapped security requirements.
- Hosted:Single-tenant managed deployments in third-party data centers.
- Managed Services:Outsource operations where vendors assume full lifecycle responsibility.
Cloud-based deployment captures the largest revenue pool while hybrid cloud configurations expand most quickly among regulated European enterprises.
Application:
Volume concentration clusters around defensive compliance workloads, with offensive information management applications showing faster adoption velocity among data-mature organizations.
- Regulatory Compliance:Mandatory retention with audit trail generation for SEC, HIPAA, and GDPR enforcement. United States healthcare systems and EU financial institutions treat this as non-discretionary spend with procurement governed by examination schedules rather than budget cycles.
- eDiscovery:Litigation readiness with predictive coding and privilege detection. London and New York legal departments are deploying transformer-based entity extraction to compress review timelines from months to days.
- Data Retention:Long-term preservation without immediate legal or compliance drivers.
- Litigation Support:Active matter management with legal hold orchestration.
- Data Backup:Operational recovery systems overlapping with disaster recovery planning.
- Information Management:Proactive knowledge organization for business intelligence extraction.
Regulatory compliance anchors the volume base while information management gains share at the steepest rate.
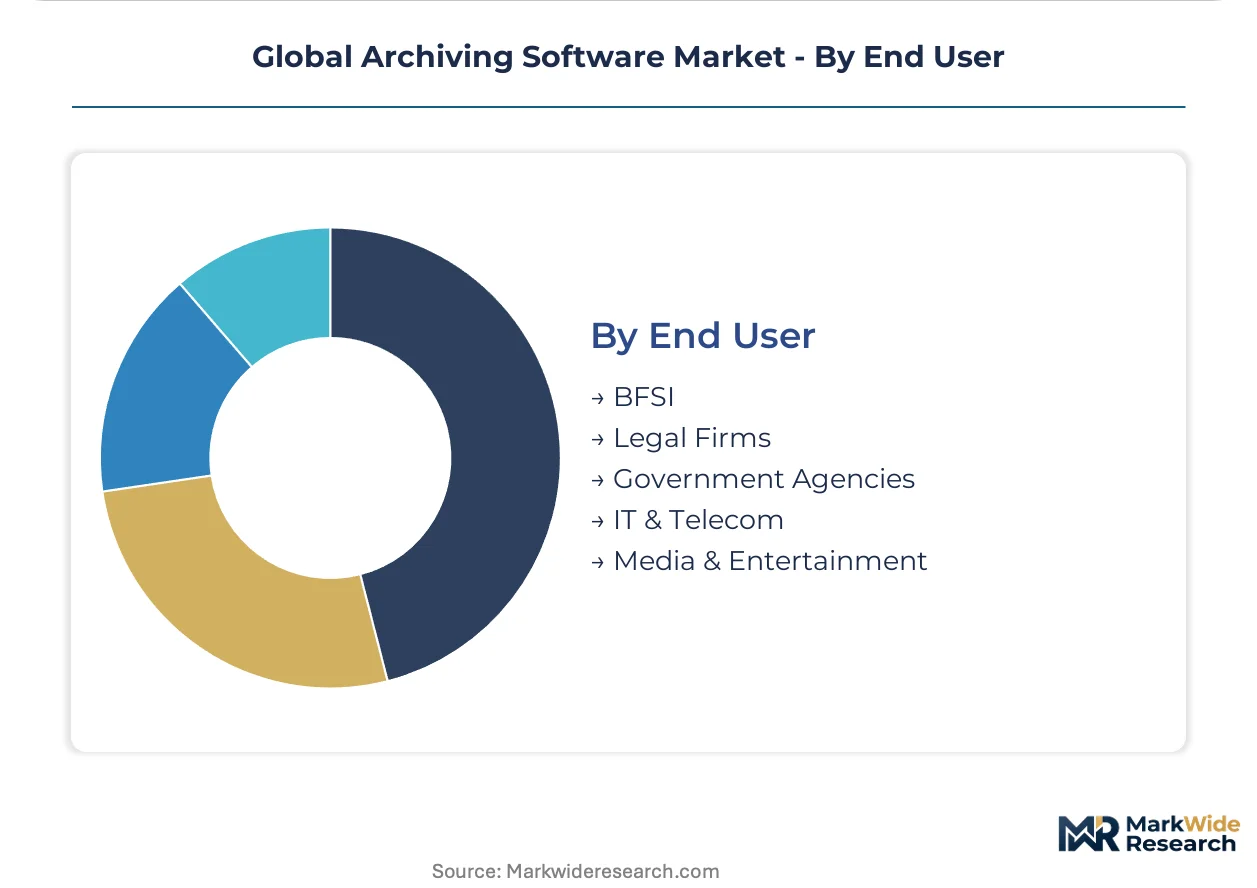
End User:
Customer type determines margin structure, with BFSI and legal firms accepting premium pricing for evidentiary-grade features while media and entertainment segments prioritize storage economics over forensic integrity.
- BFSI:Banking, securities, and insurance with intensifying SEC and RBI data localization mandates. German insurers remain tethered to IBM z/OS mainframes, constraining migration velocity despite technical obsolescence.
- Legal Firms:AmLaw 200 and Magic Circle practices with client-mandated retention protocols. United States and United Kingdom litigation boutiques are consolidating vendor relationships to platforms offering neural content analysis and automated privilege detection.
- Government Agencies:Federal, state, and municipal with classified and unclassified record-keeping requirements.
- IT & Telecom:Service providers with subscriber data and network operations documentation.
- Media & Entertainment:Studios and broadcasters managing high-resolution creative libraries with version lineage.
BFSI anchors the volume base while legal firms gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German healthcare networks command 15-20% pricing premiums over Canadian equivalents for compliant archiving infrastructure, reflecting stricter federal record-keeping mandates and longer procurement qualification cycles. This asymmetry shapes vendor resource allocation and product localization investments across the analysis window.
United States
SEC 17a-4(f) enforcement intensifies among broker-dealers, driving replacement of legacy tape systems with immutable cloud repositories. HIPAA audit trails mandate automated tiered storage for hospital networks. New York and Chicago financial services clusters anchor litigation-ready archive deployments with neural content analysis capabilities.
Germany
BSI technical guidelines and federal record-keeping laws sustain procurement pull from automotive and pharmaceutical manufacturers. KBA type-approval documentation now links to lifecycle environmental data under CSRD mandates. Bavarian industrial digitization hubs in Munich and Nuremberg retrofit archival systems with ESG-specific metadata taxonomies.
United Kingdom
Magic Circle legal practices consolidate vendor relationships around automated privilege detection platforms. Channel partners lead with consumption-priced archive-as-a-service offerings bundling ingestion and legal-hold management. London litigation boutiques deploy transformer-based entity extraction to compress eDiscovery timelines.
India
RBI data localization for payment systems and SEBI eDiscovery expectations create first-mover advantages for compliant in-country infrastructure. Healthcare digitization accelerates in Maharashtra and Karnataka as hospital networks manage exploding patient imaging volumes. Mumbai and Bangalore technology corridors attract vendor establishment of sovereign cloud archive facilities.
Canada
Healthcare providers pilot subscription-based archive structures to align cash outflows with patient record growth curves. Health Canada and PMRA retention protocols govern pharmaceutical trial documentation. Toronto and Vancouver hospital networks migrate electronic health records to consumption-priced cloud archives with geographic redundancy.
Global Archiving Software Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with targeted governance modules. The vendor base organizes around three strategic archetypes: hyperscaler-native platforms bundling productivity and storage, mainframe-anchored incumbents with federal certification depth, and unified data protection vendors spanning backup-archive workflows. Consolidation pressure intensifies through strategic partnerships and geographic expansion rather than horizontal M&A.
Among North American platform providers, Microsoft Corporation and Veritas Technologies LLC occupy positions at opposing ends of the integration spectrum. Microsoft exemplifies the hyperscaler-native archetype with ecosystem-anchored distribution, while Veritas represents the independent governance specialist tier with cross-platform deployment flexibility. Commvault Systems Inc. sits within the unified protection category, bridging operational recovery and long-term retention workflows. IBM Corporation anchors the mainframe-integrated segment, particularly among European insurers with z/OS dependencies.
| Leading Market Players |
|---|
| Veritas Technologies LLC |
| Microsoft Corporation |
| IBM Corporation |
| OpenText Corporation |
| Commvault Systems Inc. |
| Barracuda Networks, Inc. |
| Mimecast Limited |
| Google LLC |
| Proofpoint, Inc. |
| Others |
Supply & Pricing Matrix
EU AI Act data provenance mandates and GDPR Article 44 cross-border transfer restrictions function as regulatory chokepoints that compress pricing tier spreads while forcing vendors to restructure cloud infrastructure geography. German BSI certification requirements and French ANSSI cloud security guidelines create compliance-cost premiums that widen spreads between certified and uncertified deployments, reshaping procurement patterns across European enterprise buyers.
Pricing Analysis
Configured-to-order pricing for hybrid cloud deployments with jurisdictional sovereignty controls commands 40-60% premiums over standard SaaS-tiered subscriptions. Three-tier pricing structure across premium, standard, and economy levels stratifies by compliance certification depth, with GDPR- and SEC 17a-4(f)-validated repositories anchoring the premium band. Cost compression in standard cloud tiers intensifies as hyperscaler consumption models commoditize base storage, though evidentiary-grade features retain pricing power. Mid-market healthcare providers in Canada and the United Kingdom exhibit highest price sensitivity, while German automotive manufacturers and United States broker-dealers accept premium positioning for immutable audit trails.
Supply Chain Analysis
Extended payment terms from large European insurers and federal contractors now stretch to 90-120 days, forcing mid-tier vendors to secure supply-chain finance facilities against recurring revenue streams. Component concentration centers on hyperscaler infrastructure in the United States, Ireland, and Germany, with WORM-compliant storage hardware sourcing from specialized manufacturers in Japan and Taiwan. The supply chain draws from cryptographic security modules, optical disk libraries, and neural processing units for content classification. Single-source vulnerability in EU sovereign cloud certification pathways threatens delivery timelines. Distribution runs through Azure Marketplace, AWS Marketplace, and direct enterprise sales teams with vertical specialization.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Global archiving software demand follows cyclical recovery patterns tied to regulatory examination schedules, with SEC 17a-4(f) enforcement waves and EU AI Act implementation phases driving replacement cycles that lag macroeconomic indicators by 12-18 months.
For Market Incumbents: Entrench position through mainframe-integrated governance tools that capture IBM z/OS-dependent European insurers, while accelerating certification investment for EU AI Act Article 50 training data provenance requirements. Defensive consolidation should prioritize channel control in Germany and the United Kingdom, where Magic Circle legal practices and automotive manufacturers consolidate vendor relationships around neural content analysis capabilities. Cloud-native substitutes threaten tape-replacement revenue pools; counter with hybrid cloud tiering that preserves on-premises legal-hold control. For New Entrants and Emerging Players: Establish a beachhead in India's sovereign cloud archive infrastructure, where RBI data localization and SEBI eDiscovery expectations outpace incumbent footprint. White-space concentration sits with AI training data marketplace provisioning, where provenance-verified repositories with cryptographic attestation remain underserved. Target mid-market Canadian healthcare providers piloting subscription-based archive-as-a-service models. Go-to-market leverage: consumption-priced bundling that aligns cash outflows with patient record growth curves. For Investors and Strategic Acquirers: EU AI Act Article 50 enforcement reshapes the acquisition landscape toward vendors with immutable audit trail capabilities and WORM-compliant repository expertise. Long-term viability favors platforms spanning backup-archive workflows with unified data protection architecture, rather than point solutions. Acquisition target archetype: compliance archiving specialists with GDPR Article 44 cross-border workflow orchestration. Signal to watch: intensified SEC examination schedules for broker-dealer electronic record-keeping.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Microsoft Azure ecosystem bundling captures productivity-suite procurement budgets. |
| Geographic Expansion | India sovereign cloud facilities address RBI data localization mandates. |
| Strategic Partnership | Channel partners in the United Kingdom lead consumption-priced archive-as-a-service offerings. |
| Acquisition of Specialist Firm | Neural content analysis capabilities compress eDiscovery timelines for Magic Circle practices. |
| Product Launch | Blockchain-anchored immutability layers render evidentiary chains tamper-evident for litigation. |
Research Methodology
Initial hypotheses were tested against primary input from CTOs, IT procurement officers, platform engineers, and channel partners, and refined through secondary validation against SEC filings, hyperscaler capex disclosures, GPO contracts, and healthcare procurement databases. Bottom-up segmentation modeling triangulated with top-down macroeconomic anchoring ensured cross-verification of demand estimates. Primary fieldwork concentrated on United States broker-dealers, German automotive manufacturers, United Kingdom legal practices, and Canadian healthcare networks.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with deployment model, organization size, vertical industry, integration complexity, and regional adoption pattern serving as core segmentation dimensions. CAGRs were derived from trend extrapolation against regulatory milestone timing and technology substitution curves. Industry-specific forecast inputs included SEC examination schedule intensity, EU AI Act implementation phase transitions, and healthcare data volume growth trajectories.
Sensitivities concentrate around regulatory enforcement timing, hyperscaler pricing volatility, and sovereign cloud certification pathway fragmentation. Forecasts reflect documented assumptions regarding compliance mandate adherence rates and technology refresh cycle stability. Macroeconomic contraction, accelerated regulatory divergence, or breakthrough AI training data provenance alternatives would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Customer Communications Management (CCM) Software Market
Software & Services
Business Spend Management (BSM) Software Market
Software & Services
Global Idea Management Software Market
Software & Services
Workflow Automation and Optimization Software Market
Software & Services
Global Electronic Lab Notebook (ELN) Market
Software & Services
GCC Human Capital Management Software Market
Software & Services
Global Diagram Software Market
Software & Services
Global Project Software Market
Software & Services
Asia-Pacific Saas-Based SCM Market
Software & Services
Global PPC Software Market
Software & Services
Visitor Identification Software Market
Software & Services
Global Driving School Software Market
Software & Services
Image Analysis Software Market
Software & Services
Global Neural Network Software Market
Software & Services
Sales Performance Management (SPM) Software Market
Software & Services
Software Market